
 Industrial Wastewater Treatment Market | 2026-2036
Industrial Wastewater Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Wastewater Treatment Market Intelligence
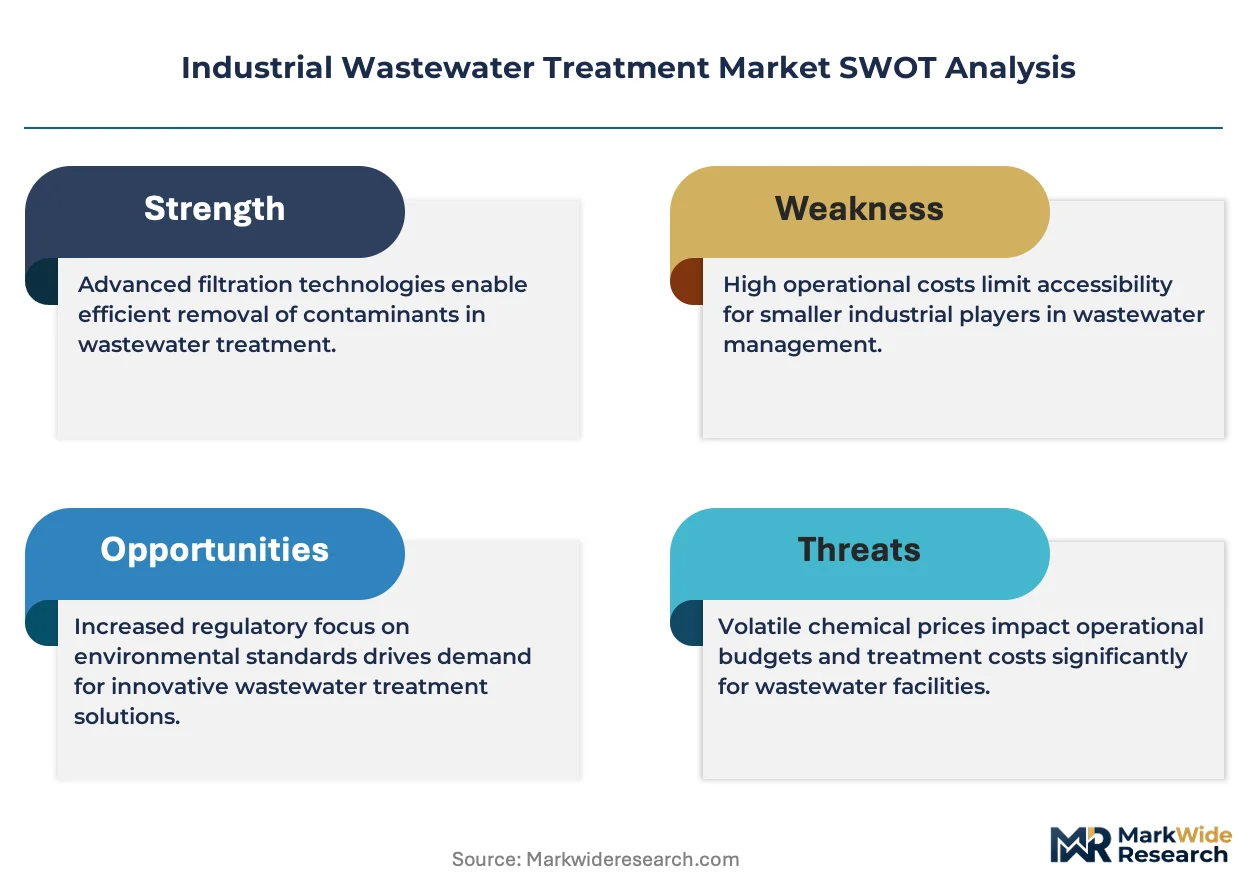
The bundling of advanced monitoring sensors with modular treatment systems is consolidating buyer preference towards integrated solutions. Veolia Environnement leverages its extensive service network and operational expertise to deliver these comprehensive packages. Ecolab specializes in chemical treatment programs and water management services for industrial clients. Xylem differentiates through its intelligent water infrastructure and advanced pumping technologies, positioning itself as a leader in smart water solutions.
Industrial wastewater treatment encompasses the physical, chemical, and biological processes for purifying water contaminated by industrial activities. Systems are engineered to remove specific pollutants, such as heavy metals and organic compounds, to meet stringent discharge limits. Membrane bioreactor technology commands a premium in pharmaceutical manufacturing due to its high removal efficiency. The food and beverage processing application segment is expanding rapidly, driven by high organic loads and the need for water reuse.
Discharge standards, such as the US EPA's Effluent Limitation Guidelines and the EU's Industrial Emissions Directive, establish critical performance benchmarks. China's 'dual carbon goals' further push investment into water-efficient technologies and circular economy models. These regulations directly influence technology choice and operational expenditures. Stakeholders must now decide whether to retrofit existing plants for compliance or invest in new, decentralized systems to gain operational flexibility.
Market Dynamics
Intensifying regulatory pressure for water circularity and stringent effluent quality is the central force shaping the industrial wastewater treatment market. This compels industries to move beyond basic compliance and invest in advanced technologies that enable water reuse, directly influencing capital budgets and technology selection across all sectors.
Growth Catalysts
- Stricter Effluent Standards:Regulations like the EU's Industrial Emissions Directive and the US EPA's Effluent Limitation Guidelines are mandating lower pollutant levels, forcing operators to upgrade or replace legacy treatment systems with more efficient technologies.
- Water Scarcity and Reuse Initiatives:Growing water stress, particularly in industrial clusters in India and China, is pushing food and beverage and textile manufacturers to adopt zero liquid discharge (ZLD) and water recycling systems to ensure operational continuity.
- Expansion in Chemical Manufacturing:The rapid expansion of chemical and petrochemical production in Asia-Pacific economies necessitates sophisticated wastewater treatment solutions capable of handling complex and toxic organic compounds and heavy metals.
Market Restraints
- High Capital and Operational Costs:The significant upfront investment required for advanced treatment technologies, such as membrane bioreactors or advanced oxidation processes, combined with high energy and chemical consumption, can be prohibitive for small and medium-sized enterprises.
- Retrofitting Complexity:Integrating modern, compact treatment systems into existing industrial facilities with space constraints and aging infrastructure presents significant engineering challenges and potential for costly operational downtime.
- Sludge Disposal and Management:The disposal of concentrated sludge, a byproduct of the treatment process, is becoming increasingly regulated and costly, adding a substantial, long-term financial burden on industrial operators.
Strategic Opportunities
- Digitalization and Automation:Integrating IoT sensors and AI-driven analytics into treatment systems offers opportunities for remote monitoring, predictive maintenance, and process optimization, creating value through performance-based service contracts.
- Decentralized Treatment Models:The development of modular, containerized treatment units allows for decentralized, point-of-source treatment, offering greater flexibility and scalability for industrial parks and facilities with variable wastewater loads.
- Resource Recovery from Wastewater:Technologies that enable the recovery of valuable resources such as nutrients, metals, and energy from industrial effluent are creating new revenue streams and supporting corporate circular economy goals.
Industry Challenges
- Skilled Operator Shortage:The increasing complexity of automated and digitally controlled wastewater treatment plants creates a deficit of technicians and engineers with the necessary skills for operation, maintenance, and troubleshooting.
- Handling Emerging Contaminants:The presence of new and unregulated contaminants, such as per- and poly-fluoroalkyl substances (PFAS) and micropollutants from pharmaceutical production, poses a significant technical challenge for conventional treatment processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Wastewater Treatment Market |
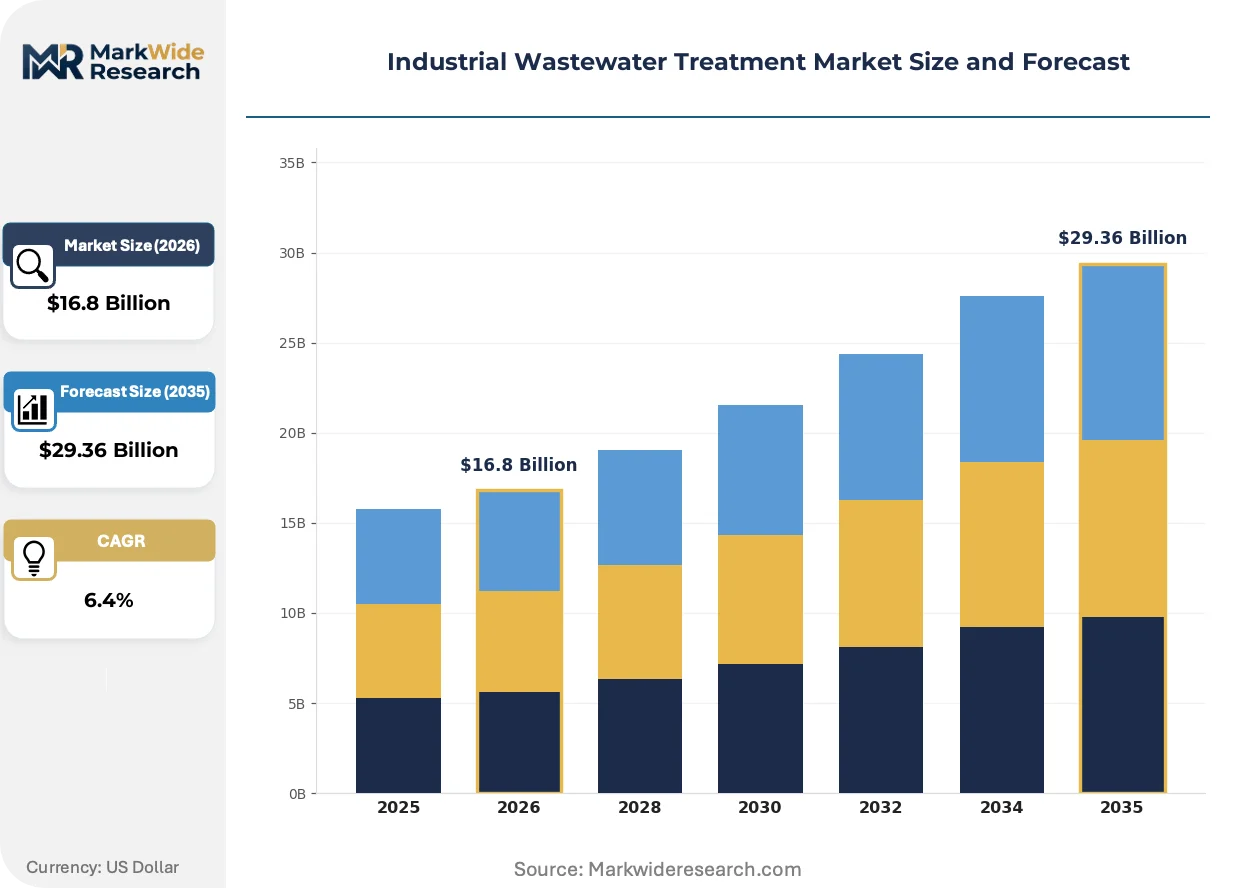
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Membrane Bioreactor, Activated Sludge, Adsorption, Coagulation, Electrochemical Treatment, Ion Exchange Application: Chemical Manufacturing, Food & Beverage Processing, Textile Production, Pulp & Paper, Metal Finishing, Pharmaceutical Manufacturing End User: Refineries, Mining Companies, Power Plants, Electronic Fabricators, Urban Sewage Plants, Shipbuilders Installation Type: Onsite Systems, Centralized Plants, Mobile Units, Modular Installations |
| Companies Covered | Ecolab, Pentair, Veolia Environnement, Kurita Water Industries, Thermax Group, SUEZ, Evoqua Water Technologies, Epic Cleantec, Xylem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Wastewater Treatment Market Strategic Shifts & Innovations
The market is seeing a definitive shift toward intelligent and decentralized water management systems. This evolution is driven by the convergence of advanced sensor technology, modular system design, and stringent regulations demanding greater process control and resource efficiency.
Advanced Membrane Technologies Membrane bioreactor (MBR) technology combines a membrane process like microfiltration with a biological wastewater treatment process. Pharmaceutical and semiconductor manufacturing are rapidly adopting MBR systems due to their superior effluent quality and smaller physical footprint compared to conventional methods. This technology is modularizing plant design, allowing for phased capacity expansions that align with production growth rather than requiring a single, large-scale capital investment.
Regulatory Focus on Water Circularity China's 'dual carbon goals' and associated mandates from the Ministry of Ecology and Environment (MEE) are pushing for greater industrial water efficiency. This directly impacts heavy industries such as coal-to-chemical, power generation, and textiles, which are now under pressure to implement water recycling and ZLD systems. The chemical manufacturing hubs in Jiangsu and Shandong provinces are seeing accelerated investment into advanced evaporation and crystallization technologies to meet these circular economy targets.
Service-Based Model Adoption A transition away from one-time capital equipment sales toward long-term, performance-based service agreements is gaining traction. These Water-as-a-Service (WaaS) models shift the operational and compliance risk from the industrial client to the technology provider, who guarantees water quality and quantity. This trend is most prominent in the food and beverage and electronics sectors in Europe and North America, where water is a critical component of production quality and operational uptime.
Industrial Wastewater Treatment Market Segmentation
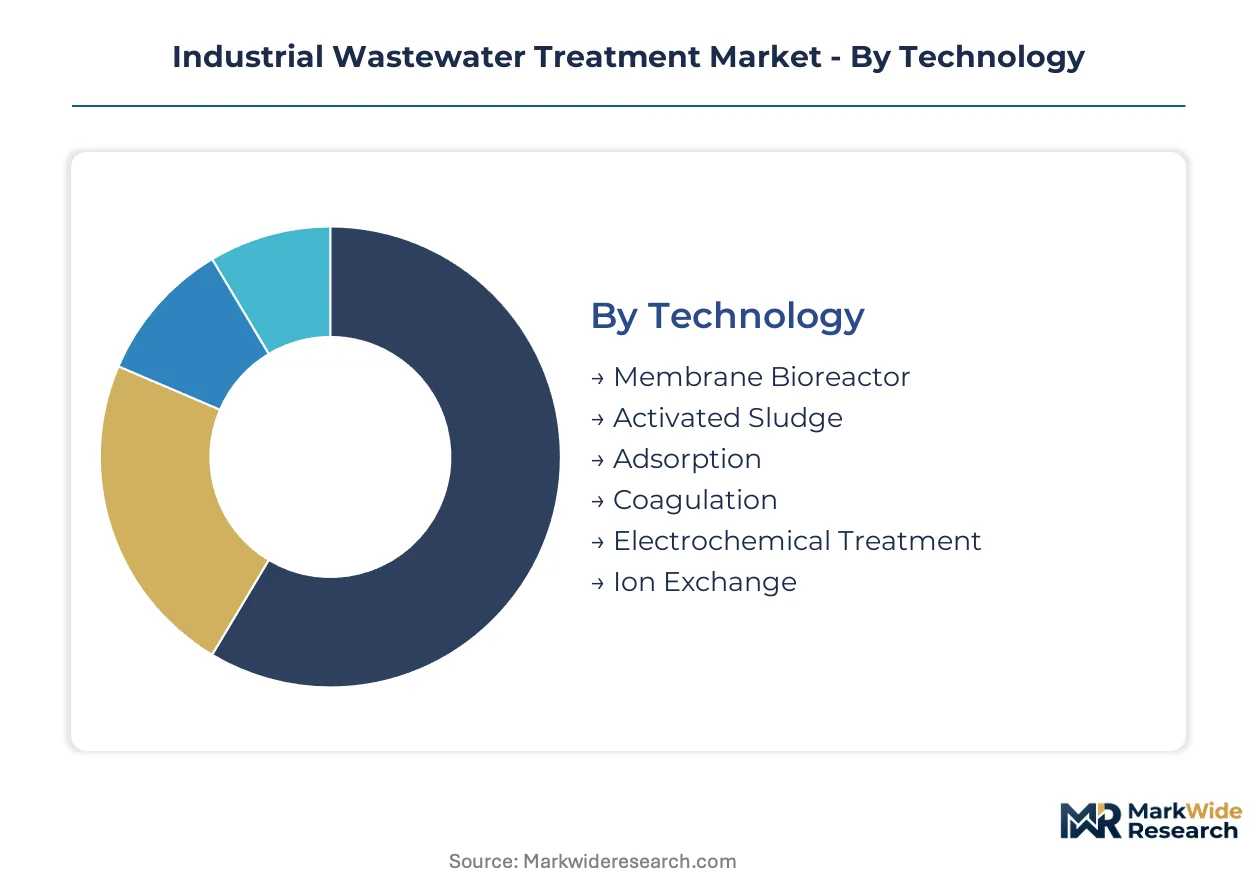
The industrial wastewater treatment market delineates its structure across several critical dimensions, reflecting varied technological approaches, application requirements, end-user specificities, and installation preferences. Understanding these segments reveals where technological innovation is most impactful and where operational efficiencies are paramount for industrial operators.
Technology:
Supply concentration in treatment technologies shifts towards sophisticated solutions capable of meeting evolving discharge standards and water reuse goals.
- Membrane Bioreactor:This advanced technology combines biological treatment with membrane filtration, producing superior effluent quality and occupying a smaller footprint. Pharmaceutical manufacturing and semiconductor fabrication in Germany and Japan increasingly adopt MBR systems for high purity water requirements.
- Activated Sludge:A widely established biological treatment method using microorganisms to break down organic pollutants in wastewater, activated sludge systems remain foundational. Food and beverage processing plants in the United States and Brazil utilize this technology for its cost-effectiveness in handling high organic loads before further polishing.
- Adsorption:Adsorption processes employ solid materials to remove dissolved pollutants from wastewater through surface adhesion.
- Coagulation:Coagulation involves adding chemicals to wastewater to destabilize suspended solids, facilitating their aggregation and removal.
- Electrochemical Treatment:This method uses electrical energy to drive chemical reactions for pollutant removal, offering an alternative for specific industrial effluents.
- Ion Exchange:Ion exchange resins selectively remove ionic contaminants like heavy metals and salts from water.
Today's leader: Activated Sludge. Tomorrow's challenger: Membrane Bioreactor.
Application:
Application drivers determine the specific treatment complexity and required removal efficiencies for industrial wastewater streams.
- Food & Beverage Processing:This segment generates wastewater with high organic content and suspended solids, necessitating robust biological treatment and often advanced filtration for water reuse. Manufacturers in Europe and Southeast Asia are investing in systems that enable closed-loop water cycles to reduce operational costs.
- Chemical Manufacturing:Wastewater from chemical production contains diverse and often toxic organic compounds, heavy metals, and salts, requiring highly specialized physical-chemical and biological processes. Industrial zones in China and India demand advanced oxidation and biological treatment to comply with stringent effluent guidelines.
- Textile Production:Textile wastewater is characterized by high color, organic load, and chemical oxygen demand from dyeing and finishing processes.
- Pulp & Paper:This industry produces large volumes of wastewater containing organic matter, suspended solids, and chlorinated compounds.
- Metal Finishing:Wastewater from metal finishing operations often contains heavy metals, acids, and cyanides, requiring precise chemical precipitation and ion exchange.
- Pharmaceutical Manufacturing:Pharmaceutical wastewater contains complex organic compounds and active pharmaceutical ingredients, demanding high-efficiency removal technologies like MBR.
The segment requiring the most advanced treatment is Chemical Manufacturing, while Food & Beverage Processing focuses on water reuse.
End User:
Regulatory impact significantly influences end-user investment decisions and technology choices for wastewater treatment.
- Power Plants:Thermal and nuclear power plants generate large volumes of cooling water and process wastewater, often requiring advanced treatment for heavy metals and suspended solids before discharge or reuse. Facilities in the United States and South Korea implement zero liquid discharge (ZLD) systems to minimize environmental impact.
- Refineries:Petroleum refineries produce complex wastewater streams containing hydrocarbons, sulfides, and phenols, demanding multi-stage physical, chemical, and biological treatment. Refineries in the Middle East and Russia are upgrading treatment infrastructure to meet stricter environmental regulations.
- Mining Companies:Mining operations generate acidic or alkaline wastewater with high concentrations of heavy metals and suspended solids.
- Electronic Fabricators:Electronic manufacturing requires ultra-pure water and generates wastewater with trace metals and organic solvents.
- Urban Sewage Plants:While primarily municipal, some industrial discharges are routed to urban sewage plants, requiring pre-treatment or specialized co-treatment.
- Shipbuilders:Shipyard operations produce wastewater containing oils, paints, solvents, and heavy metals.
Strict discharge limits drive innovation in Power Plants, whereas Refineries prioritize water reuse.
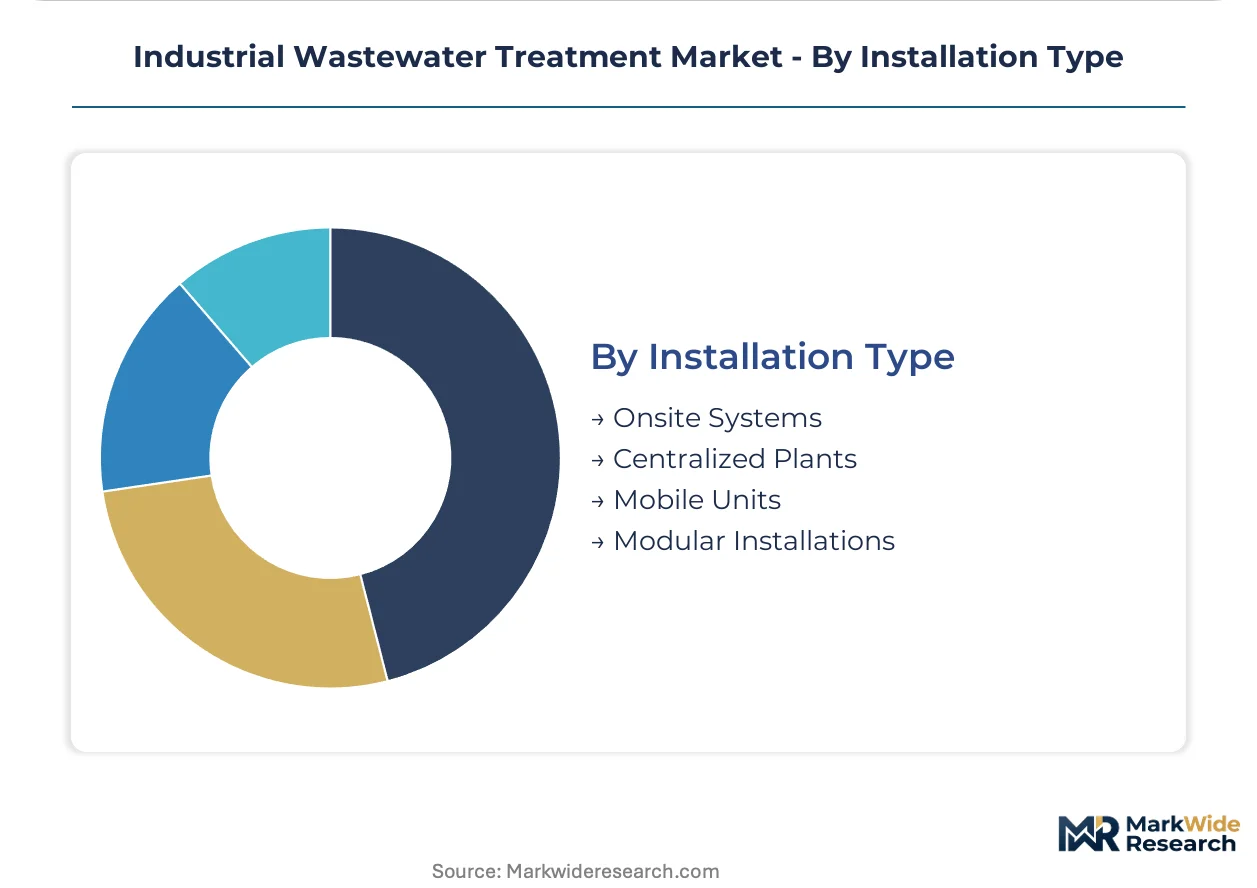
Installation Type:
Flexibility needs and scalability requirements shape the preferred installation types for industrial wastewater treatment systems.
- Modular Installations:These pre-engineered, skid-mounted units offer rapid deployment, scalability, and operational flexibility, allowing industries to expand treatment capacity incrementally. Food and beverage facilities in Europe and chemical manufacturers in India increasingly adopt modular systems for their adaptability.
- Onsite Systems:Dedicated treatment plants located directly at the industrial facility provide tailored solutions for specific wastewater characteristics and discharge requirements. Pharmaceutical companies in Switzerland and electronics manufacturers in Taiwan rely on onsite systems for precise control over effluent quality.
- Centralized Plants:Large-scale facilities collect and treat wastewater from multiple industrial sources within a region or industrial park.
- Mobile Units:Containerized, portable treatment systems provide temporary or emergency wastewater treatment solutions for various industrial applications.
The shift towards operational flexibility favors Modular Installations, while Mobile Units provide rapid deployment solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial wastewater treatment industry scaled significantly with the rise of industrialization across Europe and North America, driven by early environmental concerns. Today, investment in advanced treatment technologies is accelerating across diverse geographies, propelled by increasingly stringent discharge standards and critical water scarcity challenges. Rapidly industrializing economies in Asia-Pacific are now central to market expansion.
United States
Demand for advanced wastewater treatment in the United States is driven by stringent environmental regulations and the need for water reuse in arid regions. The US EPA's Effluent Limitation Guidelines compel industrial facilities to upgrade existing infrastructure. Chemical manufacturing facilities in the Gulf Coast region, particularly Texas, are investing in advanced oxidation processes to manage complex wastewater streams.
Germany
German industrial operators prioritize high-purity water requirements for pharmaceutical and semiconductor manufacturing. The EU's Industrial Emissions Directive mandates lower pollutant levels, driving adoption of advanced membrane bioreactor systems. Companies in Bavaria are increasingly implementing sophisticated treatment solutions to meet both environmental and operational standards.
China
China's rapid industrial expansion and ambitious 'dual carbon goals' are accelerating investment in water-efficient technologies. Mandates from the Ministry of Ecology and Environment (MEE) push heavy industries toward zero liquid discharge systems. Chemical manufacturing hubs in Jiangsu and Shandong provinces are seeing substantial investment in evaporation and crystallization technologies.
India
Indian industrial growth, particularly in chemical and textile manufacturing, creates significant demand for robust wastewater treatment solutions. Water stress in industrial clusters across India is pushing manufacturers to adopt water recycling and reuse systems. Facilities in Gujarat and Maharashtra are upgrading treatment plants to comply with national environmental standards.
Japan
Japanese pharmaceutical and semiconductor manufacturing sectors require superior effluent quality, driving the adoption of membrane bioreactor technology. METI initiatives encourage industrial water efficiency and resource recovery from wastewater. Semiconductor fabrication plants in Kyushu are implementing advanced purification systems for process water reuse.
Industrial Wastewater Treatment Market Key Industry Players
Premium-margin players sit above commodity-margin players across technological sophistication and integrated service offerings. The market structure exhibits a tiered landscape, with specialized technology providers and comprehensive solution integrators. Key strategic archetypes include integrated solution providers, chemical treatment specialists, and smart water technology developers. Dominant competitive moves include strategic partnerships for technology co-development and portfolio diversification into water management services.
Within the integrated solutions archetype, Veolia Environnement exemplifies comprehensive service delivery, leveraging its extensive network and operational expertise. Ecolab represents specialized chemical treatment programs and water management services for diverse industrial clients. Xylem differentiates through its intelligent water infrastructure and advanced pumping technologies, positioning itself as a leader in smart water solutions.
| Leading Market Players |
|---|
| Ecolab |
| Pentair |
| Veolia Environnement |
| Kurita Water Industries |
| Thermax Group |
| SUEZ |
| Evoqua Water Technologies |
| Epic Cleantec |
| Xylem |
| Others |
Cost & Logistics Intelligence
Sodium hydroxide futures, a key chemical commodity, cascade through the industrial wastewater treatment supply chain, influencing pricing tiers for chemical-intensive treatment processes. This directly impacts operational expenditures for end-users and the profitability of service providers.
Pricing Analysis
Project-based contracting dominates the market for large-scale industrial wastewater treatment systems. Price differentiation drivers include the customization level required for specific effluent characteristics and the comprehensive after-sales service bundles offered. Pricing pressure stems from increased competition in standardized modular solutions for smaller facilities. Small and medium-sized enterprises (SMEs) are most price-sensitive, while pharmaceutical manufacturers prioritize stringent performance and compliance over initial cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized component manufacturers, particularly for advanced membrane materials and intelligent sensor technologies. Geographic supply concentration for membrane manufacturing is prevalent in Japan and Germany, while specialized sensor components source from the United States and China. The supply chain relies on polymer resins for membranes and rare earth elements for advanced sensors. Geopolitical tensions impacting critical component availability represent a significant structural risk. Distribution channels leverage direct sales for large, complex projects and channel partners for more standardized modular systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial wastewater treatment market functions as a stable compounder, driven by intensifying global regulatory pressure for water circularity across industrial sectors.
For Market Incumbents: Deploy integrated digital platforms to enhance operational efficiency and remote monitoring capabilities. Consolidate smaller technology providers specializing in emerging contaminant removal to expand portfolio breadth. This defends against margin erosion from agile modular system providers. Expand service contracts in rapidly industrializing regions like Asia-Pacific, leveraging existing extensive networks.
For New Entrants and Emerging Players: Launch via direct-to-customer SaaS models for treatment process optimization and predictive maintenance. Target white-space opportunities such as decentralized treatment solutions for industrial parks or resource recovery from specific waste streams like phosphorus. The most penetrable segment remains small and medium-sized food and beverage facilities seeking cost-effective compliance. A strong go-to-market angle involves performance-based guarantees for water reuse quality.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized technology developers in emerging contaminant removal and advanced water reuse. The long-term viability of this market is assured by sustained demand for water purification over the next decade. Target acquisition archetypes include niche providers of advanced membrane or electrochemical solutions. A key signal to watch as an inflection indicator is increased government funding for industrial water innovation programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Allows rapid deployment for food and beverage facilities and chemical manufacturers in India. |
| Green Manufacturing Transition | Aligns with China's 'dual carbon goals' and reduces operational expenditures for power plants. |
| Strategic Partnership | Enhances remote monitoring capabilities and predictive maintenance for industrial clients. |
| Portfolio Diversification | Creates new revenue streams from nutrient and metal extraction for pharmaceutical manufacturing. |
| Technology Licensing | Accelerates adoption of complex wastewater treatment solutions for chemical manufacturing in the US Gulf Coast. |
Research Approach
Multiple input streams — industry reports, regulatory filings, and primary interviews — were reconciled to construct a comprehensive market view. Primary research involved discussions with plant managers, environmental compliance officers, technology R&D directors, and procurement specialists across various industrial sectors. Secondary validation drew from US EPA effluent guidelines, the EU Industrial Emissions Directive, China MEE mandates, and corporate sustainability reports, ensuring robust data triangulation through both bottom-up and top-down approaches.
Quantitative and qualitative data streams were reconciled to develop the forecast framework. The analytical framework modeled segmentation dimensions including technology, application, end-user, installation type, and regional regulatory stringency across the analysis window. Compound annual growth rates were derived from historical growth patterns and projected technology adoption rates. Key industry-specific forecast inputs included industrial production indices and water scarcity projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid technological disruption or unforeseen regulatory shifts. Forecasts reflect assumptions regarding economic stability and continued regulatory enforcement. Global economic downturns impacting capital expenditure or breakthroughs in waterless industrial processes represent specific risk factors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Water Treatment Chemicals Market
Water & Sludge Treatment
Low-Dosage Hydrate Inhibitors (Ldhis) Market
Water & Sludge Treatment
Wastewater Treatment Chemicals Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
Saudi Arabia Industrial Hazardous Waste Management Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
US Water and Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Hypochlorous Acid Water Generator Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market