
 Medium Carbon Steel Market | 2026-2036
Medium Carbon Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Medium Carbon Steel Market Outlook
AISI 1045-grade specification upgrades is collapsing the gap between commodity and performance-grade material, forcing mills to recalibrate melt shop chemistry controls. ArcelorMittal leverages its European R&D network to sustain premium-positioned flat-rolled output for machinery OEMs. Baowu Group anchors Asia-Pacific supply through integrated coastal mills with direct iron ore port access. Tata Steel Group competes on forged bar specialization for automotive crankshaft and axle applications.
Medium carbon steel contains approximately 0.30% to 0.60% carbon by weight, typically produced through basic oxygen or electric arc furnace routes with controlled manganese alloying to achieve tensile strength between 500 MPa and 800 MPa after heat treatment; this composition balances weldability against hardness, serving as the structural backbone for load-bearing machinery, vehicle chassis, and construction frameworks requiring fatigue resistance without full alloy-steel cost. Hot rolled plates dominate volume throughput for infrastructure girders and heavy equipment bases, while forged bars command margin concentration in automotive drivetrain and power transmission shafts where grain structure uniformity determines component life. Cold rolled sheets occupy a narrower but defensible niche in precision machinery housings and thin-walled structural profiles.
The EPA enforces emissions thresholds at US integrated mills, while REACH governs chemical disclosure across European supply chains, and China's MEE imposes carbon-intensity caps that reshape furnace fuel choices and scrap ratios. These frameworks elevate compliance costs for merchant producers while advantaging mills with captive renewable power or direct reduced iron capacity. Stakeholders must monitor how evolving carbon border mechanisms and green procurement mandates redirect contract flows between domestic and import-sourced supply.
Market Dynamics
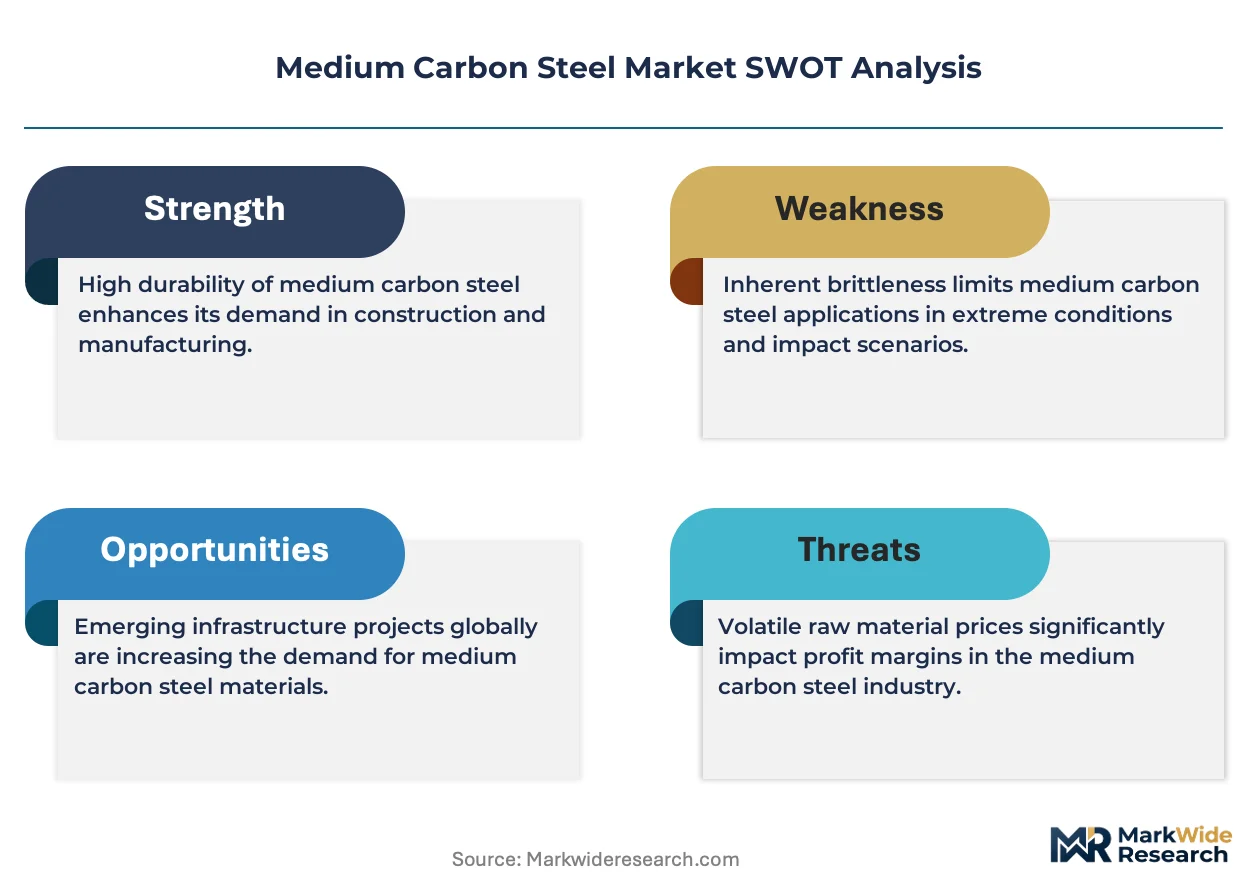
Automotive OEMs are tightening material specifications for drivetrain forgings, forcing mills to upgrade melt shop chemistry controls and traceability systems to meet durability standards without absorbing full alloy-steel costs.
Growth Catalysts
- EU REACH traceability mandates:Chemical disclosure requirements across European supply chains are accelerating investment in certified heat-treatment documentation and digital batch tracking systems.
- India's western industrial corridor:Infrastructure build-out and automotive supplier clustering in Gujarat and Maharashtra are concentrating orders for hot-rolled plates and forged bars.
- Basic oxygen furnace optimization:Controlled manganese alloying advances are expanding the performance envelope of AISI 1045-grade material for machinery OEMs.
Market Restraints
- Iron ore price volatility:Coastal mills with direct port access capture cost advantages that inland electric arc furnace operators cannot match, squeezing merchant producer margins.
- Scrap quality fragmentation:Inconsistent residual element levels in shredded automotive scrap complicate chemistry targeting for medium carbon specifications.
- Aluminum substitution in light-weighting:Automotive chassis designers are specifying aluminum extrusions for non-structural components, compressing addressable volume in passenger vehicle applications.
Strategic Opportunities
- India's PLI scheme for specialty steel:Production-linked incentives for high-grade automotive steel are attracting greenfield forging capacity to the western industrial corridor.
- Direct reduced iron-hybrid furnaces:Convergence of hydrogen-reduction technology with electric arc melting enables carbon-intensity compliance under China's MEE caps.
- Digital mill certification platforms:Blockchain-anchored material passports are opening premium contract channels for machinery OEMs requiring full supply chain transparency.
Industry Challenges
- Metallurgical technician scarcity:Skilled operators capable of precise ladle chemistry adjustments are in short supply across aging European and North American melt shops.
- Heat-treatment furnace retrofit cycles:Legacy continuous furnaces require capital-intensive upgrades to achieve uniform grain structure for automotive crankshaft specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium Carbon Steel Market |
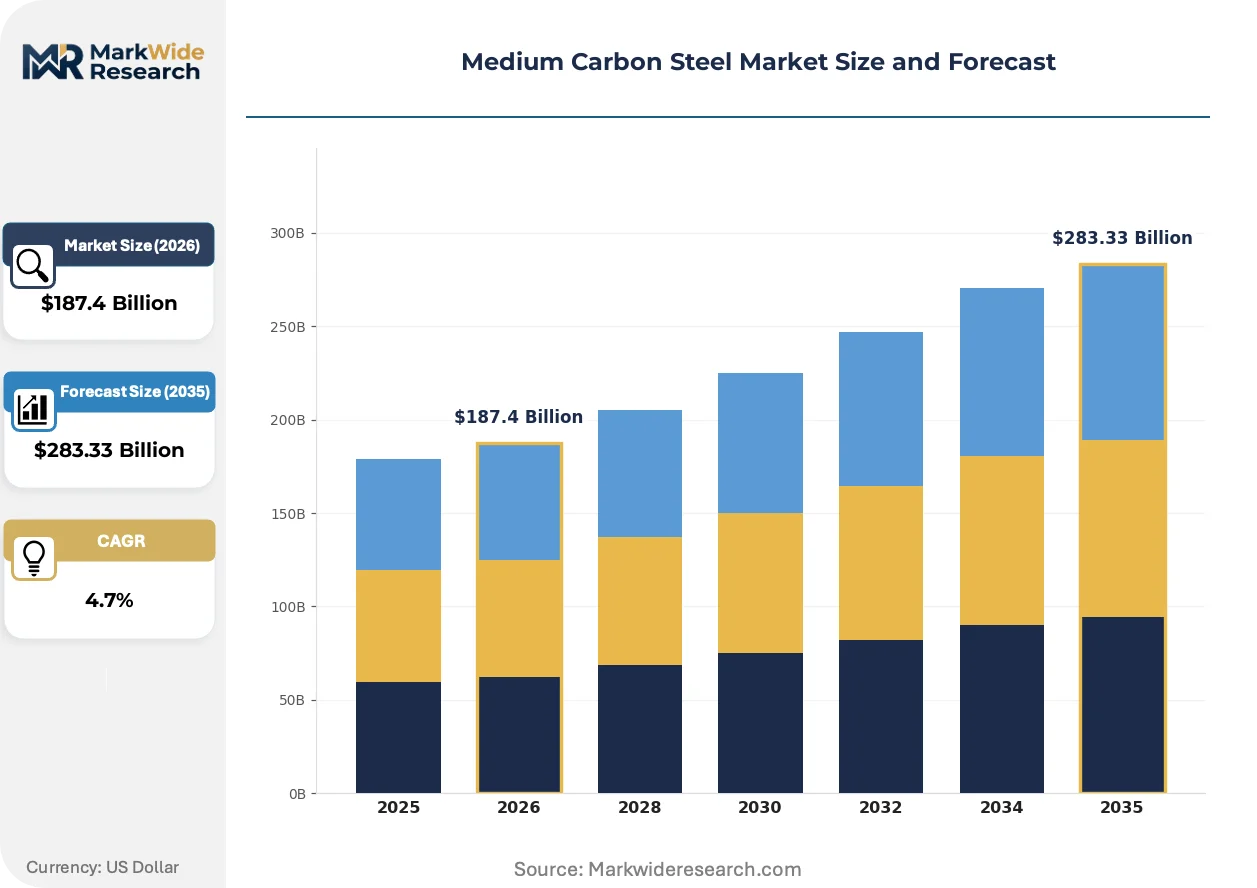
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $283.33 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wires, Bars, Sheets, Plates Application: Automotive Components, Construction Materials, Machinery Parts, Infrastructure Form: Hot Rolled, Cold Rolled, Forged, Annealed End User: Construction Industry, Automotive OEMs, Manufacturing, Transportation |
| Companies Covered | POSCO Holdings, Ansteel Group, Baowu Group, Shagang Group, HBIS Group, ArcelorMittal, Tata Steel Group, Jianlong Group, Nippon Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium Carbon Steel Market Strategic Shifts
Process digitization and low-carbon metallurgy are converging to redefine competitive advantage, with mills racing to align production footprints with tightening emissions frameworks and buyer certification requirements.
Hydrogen-based direct reduced iron is supplanting conventional coke-based blast furnace routes in new capacity investments. European machinery OEMs are specifying DRI-origin material for precision housing applications. This transition is compressing the cost premium between commodity and performance-grade flat-rolled output.
China's MEE carbon-intensity caps are reshaping furnace fuel choices and scrap ratios across integrated coastal mills. The regulation forces operators to rebalance basic oxygen and electric arc furnace throughput to avoid penalties. Forged bar producers serving automotive drivetrain applications are accelerating renewable power offtake agreements to maintain contract eligibility.
Automotive tier-one suppliers are consolidating forging procurement through long-term offtake contracts with certified mills. Direct mill relationships are displacing traditional distributor channels for high-volume crankshaft and axle programs. This concentration is most visible in Germany and Japan, where OEM durability warranties require full batch traceability from melt to finish machining.
Medium Carbon Steel Market Segmentation
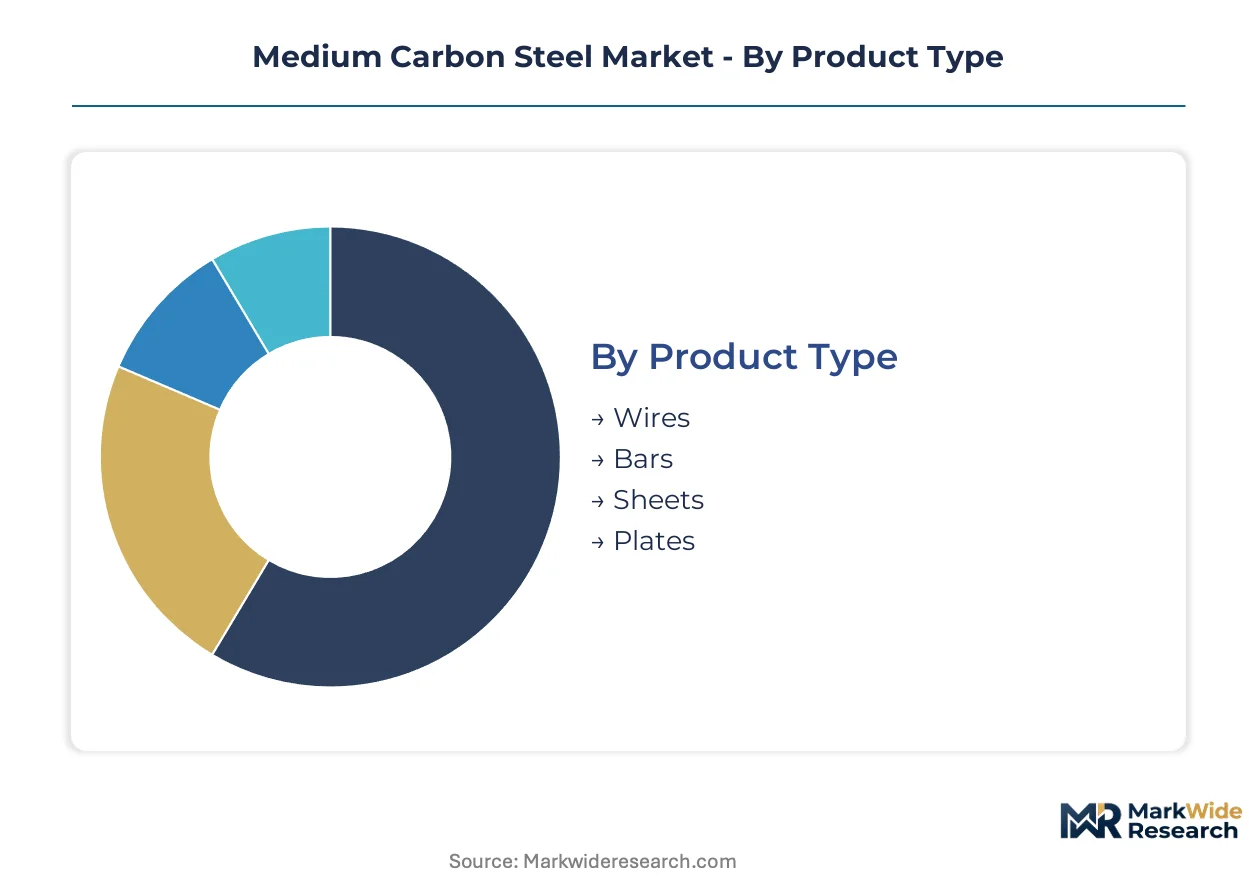
Segmentation in medium carbon steel markets reflects divergent certification requirements and performance thresholds across end-use industries. Procurement specifications for automotive drivetrain forgings demand tighter chemistry controls than construction-grade material, creating distinct pricing tiers and supplier qualification barriers.
Product Type:
REACH traceability mandates and China's GB standards enforce differentiated certification protocols depending on product geometry and surface area exposure.
- Plates:Hot-rolled flat products with thicknesses from 3mm to 150mm serve as the structural backbone for bridge girders and heavy equipment bases. Infrastructure build-out in India's western industrial corridor is concentrating orders for thick-gauge plate as Gujarat and Maharashtra expand port and highway capacity.
- Bars:Long products with circular, square, or hexagonal cross-sections provide feedstock for forged crankshafts and axle shafts. Automotive OEMs in Germany and Japan are consolidating procurement through direct mill relationships that mandate full batch traceability from melt to finish machining.
- Sheets:Cold-rolled thin flat products occupy precision machinery housings where dimensional tolerance and surface finish determine component fit.
- Wires:Drawn rod products supply fastener manufacturers and welding electrode producers with controlled carbon content for consistent mechanical properties.
Plates handle the majority of throughput; bars are expanding most quickly on share as automotive durability standards tighten.
Application:
Cost tier differentiation separates commodity infrastructure material from performance-grade automotive and machinery specifications.
- Infrastructure:Structural frameworks for bridges, buildings, and port facilities utilize standard-grade hot-rolled sections where fatigue resistance requirements stop short of full alloy-steel substitution.
- Automotive Components:Drivetrain forgings including crankshafts, camshafts, and transmission gears demand AISI 1045-grade material with precise manganese alloying and verified grain structure uniformity.
- Machinery Parts:Precision housing applications and power transmission shafts require cold-rolled or forged material with documented heat-treatment certification.
- Construction Materials:Rebar and structural sections for commercial and residential building frames operate under less stringent traceability requirements than automotive specifications.
Infrastructure commands the largest volume base; automotive components show the steepest expansion trajectory as OEMs upgrade material specifications without absorbing full alloy-steel costs.
Form:
Volume concentration favors hot-rolled output while margin capture concentrates in thermomechanically processed forms.
- Hot Rolled:Material formed above recrystallization temperature delivers the foundational output for plates, bars, and structural sections serving construction and heavy equipment markets.
- Forged:Compressively deformed material achieves refined grain structure and directional strength properties essential for automotive crankshaft and axle applications where component life determines warranty exposure.
- Cold Rolled:Room-temperature reduction produces tight dimensional tolerances and smooth surface finishes for precision machinery housings and thin-walled profiles.
- Annealed:Softened material with reduced internal stresses facilitates subsequent machining and forming operations for complex machinery components.
Hot rolled handles the majority of throughput; forged material is gaining share fastest as automotive tier-one suppliers consolidate procurement through certified mill direct contracts.
End User:
Customer type determines certification depth, with automotive OEMs imposing the most stringent documentation requirements.
- Construction Industry:Contractors and fabricators purchasing standard-grade plates and bars for commercial building frames, highway infrastructure, and port facilities.
- Automotive OEMs:Vehicle manufacturers and tier-one suppliers specifying forged bars with verified chemistry, grain structure, and full supply chain traceability for drivetrain components.
- Manufacturing:Machinery OEMs and industrial equipment producers sourcing cold-rolled sheets and precision bars for housings, shafts, and structural frames.
- Transportation:Rail, shipbuilding, and heavy truck manufacturers procuring plate and bar products for load-bearing chassis and hull structures.
Construction industry accounts for the largest volume absorption; automotive OEMs are climbing the fastest on share as durability warranties force material specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across major steel-producing economies, with coastal integrated mills capturing cost advantages through direct iron ore port access while inland operators face margin compression from logistics premiums and scrap quality fragmentation.
China
GB standards enforcement and MEE carbon-intensity caps are reshaping furnace fuel choices across Baowu's coastal integrated mills. The Yangtze River Delta anchors Asia-Pacific supply through direct reduced iron-hybrid investments. Shanghai and Ningbo clusters process the majority of hot-rolled plate exports serving Southeast Asian infrastructure build-out.
India
PLI scheme incentives for specialty steel are accelerating greenfield forging capacity in Gujarat and Maharashtra. BIS certification requirements for automotive-grade material are tightening traceability documentation. The western industrial corridor between Ahmedabad and Pune concentrates demand for forged bars serving tier-one automotive suppliers.
Germany
REACH chemical disclosure mandates are elevating compliance costs for merchant producers while advantaging mills with renewable power offtake agreements. The Ruhr industrial basin maintains forging specialization for automotive crankshaft applications. Cologne and Düsseldorf clusters host machinery OEMs specifying cold-rolled precision sheets with full heat-treatment certification.
United States
EPA emissions thresholds at integrated mills are compressing margins for operators lacking captive scrap or renewable power access. The Great Lakes region concentrates electric arc furnace capacity serving construction-grade plate demand. Detroit automotive OEMs are consolidating procurement through direct mill relationships that mandate batch traceability from melt to finish machining.
Japan
METI industrial standards and JIS certification requirements enforce tighter chemistry controls for automotive drivetrain forgings than construction-grade specifications. The Chubu region around Nagoya anchors forging specialization for transmission gear applications. Osaka-Kobe clusters supply cold-rolled sheets to precision machinery OEMs requiring documented grain structure uniformity.
Medium Carbon Steel Market Competitive Environment
Concentration sits with integrated coastal mills possessing direct iron ore port access and captive renewable power capacity. The vendor base stratifies across three tiers: scale-driven integrated producers, regional forging specialists, and merchant electric arc furnace operators facing scrap quality fragmentation. Strategic moves center on hydrogen-reduction technology licensing and long-term offtake contracting with automotive tier-one suppliers.
Within the integrated producer tier, Baowu Group and ArcelorMittal occupy positions defined by coastal mill networks and European R&D infrastructure. Tata Steel Group exemplifies the forging specialization archetype through its western India capacity. POSCO Holdings anchors the Asia-Pacific premium flat-rolled segment. These three entities represent distinct competitive vectors: Chinese scale, European technology integration, and Indian automotive proximity.
| Leading Market Players |
|---|
| POSCO Holdings |
| Ansteel Group |
| Baowu Group |
| Shagang Group |
| HBIS Group |
| ArcelorMittal |
| Tata Steel Group |
| Jianlong Group |
| Nippon Steel Corporation |
| Others |
Value Chain & Pricing Dynamics
Coastal integrated mills with direct iron ore port access capture structural cost advantages that compress price floors for inland electric arc furnace operators across North America and Europe. China's MEE carbon-intensity caps and the EU's REACH compliance costs further stratify pricing power between renewable-powered coastal producers and merchant operators facing scrap quality fragmentation.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for automotive-grade forged bars, while construction contractors transact on commodity spot markets for hot-rolled plates. Three-tier pricing structure across premium, standard, and economy levels separates full-traceability automotive material from infrastructure-grade output with limited certification. Cost compression in the standard tier is intensifying because coastal mills with DRI-hybrid furnaces exploit carbon-border advantages. Tier-one automotive suppliers show least price sensitivity due to warranty exposure, while commercial construction fabricators remain most responsive to spot volatility.
Supply Chain Analysis
Container availability constraints on the Asia-Europe trade lane and Yangtze River port congestion elevate inbound logistics costs for European machinery OEMs sourcing precision cold-rolled sheets. Supply concentrates in China, India, and Japan, with raw material dependencies on Australian iron ore, high-grade metallurgical coal, and manganese alloying elements. Single-source vulnerability around Chinese DRI-hybrid furnace technology creates supply chain risk for mills seeking MEE compliance. Distribution runs through direct mill relationships displacing traditional steel service centers for high-volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as automotive OEMs consolidate forging procurement through certified mill direct contracts, fragmenting distributor influence across Germany, Japan, and the US Great Lakes region.
For Market Incumbents: Shield premium positioning by deepening backward integration into hydrogen-reduction technology and renewable power offtake agreements. ArcelorMittal's European R&D infrastructure exemplifies defensive R&D leverage against emerging DRI-hybrid entrants. Captive scrap sorting capabilities address residual element fragmentation threatening AISI 1045 chemistry targets. For New Entrants and Emerging Players: BIS certification fast-tracks for India's western industrial corridor offer the most penetrable entry vector for forged bar specialization targeting Gujarat-Maharashtra automotive clusters. Greenfield forging capacity under PLI scheme incentives bypasses legacy furnace retrofit burdens. Direct mill partnerships with tier-one suppliers displace distributor-dependent competitors lacking traceability infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors forging specialists with automotive proximity over commodity plate producers exposed to infrastructure cyclicality. Long-term viability hinges on carbon-intensity compliance architecture rather than scale alone. Monitor hydrogen-reduction licensing velocity as inflection indicator for stranded asset risk in conventional blast furnace capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into DRI-Hybrid Furnaces | China's MEE caps and EU carbon border mechanisms reward early hydrogen-reduction adopters with contract eligibility. |
| Long-term Supply Agreement with Automotive Tier-Ones | German and Japanese OEM durability warranties require full batch traceability from melt to finish machining. |
| Green Manufacturing Transition | Renewable power offtake agreements satisfy REACH chemical disclosure and China's carbon-intensity thresholds simultaneously. |
| Capacity Expansion in India's Western Corridor | PLI scheme incentives for specialty steel concentrate greenfield forging investment in Gujarat and Maharashtra. |
| Joint Venture for Scrap Quality Sorting | Consistent residual element control addresses chemistry targeting challenges in shredded automotive scrap feedstock. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with melt shop metallurgists, automotive tier-one procurement directors, infrastructure project engineers, and steel service center distribution managers. Secondary validation drew from customs trade data, SEC 10-K filings of listed steel producers, EPA emissions disclosures, and BIS certification registries. Bottom-up volume modeling across product types and applications triangulated against top-down macroeconomic steel consumption indicators.
Across the analysis window, the forecast framework modeled product type segmentation by form and grade tier, application segmentation by durability specification intensity, and geographic segmentation by regulatory framework cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating automotive production cycles and infrastructure investment pipelines. Key inputs included iron ore price trajectories, scrap availability indices, and carbon border mechanism implementation schedules.
Decision-makers should treat outputs as directional under base assumptions of sustained automotive durability specification tightening and gradual hydrogen-reduction technology diffusion; material deviation in regulatory enforcement intensity or iron ore supply disruption would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Gold Smelting Market
Metals
Beryllium Market
Metals
Global Electrolytic Copper Foil Market
Metals
North America Aluminium Powder Market
Metals
Global Copper Market
Metals
Brazing Strips Market
Metals
High Carbon Bearing Steel Market
Metals
Powder Metallurgy Market
Metals
Global Aluminium Wire Rod Market
Metals
Medical Metal Tubing Market
Metals
Grain Oriented Electrical Steel Market
Metals
Global Hot Rolled Coil Steel Market
Metals
Lithium Foil Market
Metals
Motor Lamination Material Market
Metals
Steel Drums and Ibcs Market
Metals
Copper and Copper Alloy Powder Market