
 Global Liquid Waste Management Market | 2026-2036
Global Liquid Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquid Waste Management Market Foresight
The gap between premium zero-liquid-discharge systems and commodity hauling services is repositioning how buyers evaluate total cost of ownership. Veolia leverages its integrated treatment network across Europe to capture long-term industrial service contracts. Clean Harbors sustains dominance in North American hazardous liquid waste through specialized incineration and fuel-blending infrastructure. GFL Environmental competes aggressively on collection density in Canadian and US municipal markets.
Liquid waste management encompasses the collection, transportation, treatment, and final disposition of aqueous effluents containing suspended solids, dissolved contaminants, or hazardous constituents, typically requiring pH adjustment, biological degradation, or thermal destruction to meet discharge thresholds. The primary purpose centers on protecting receiving waters, human health, and ecosystem integrity while recovering reusable water, energy, or material byproducts. Treatment services command the largest revenue pool given capital intensity and regulatory compliance burdens, while recycling applications are expanding fastest as manufacturing plants seek to reduce freshwater intake and discharge volumes. Membrane filtration technology leads capital deployment for water reuse projects, whereas anaerobic digestion is displacing conventional activated sludge at food processing units seeking biogas co-generation revenue.
The EPA enforces effluent limitation guidelines under the Clean Water Act, while the EU applies the Industrial Emissions Directive and REACH frameworks to restrict hazardous substance releases. India's Central Pollution Control Board mandates online effluent monitoring for designated polluting industries under the Water Act. Stakeholders must track how tightening nitrogen and phosphorus limits across multiple jurisdictions will force upgrades to biological nutrient removal capacity.
Market Dynamics
Zero-liquid-discharge mandates from industrial clusters in Germany and the US Great Lakes region are compressing discharge permits and forcing capital redeployment toward closed-loop treatment infrastructure.
Growth Catalysts
- EU Circular Economy Directives:Germany's packaging and manufacturing sectors face binding liquid byproduct recycling quotas. Industrial plants upgrade biological nutrient removal capacity to meet phosphorus discharge limits.
- Membrane filtration deployment:Reverse osmosis and nanofiltration systems cut freshwater intake at semiconductor fabrication facilities. Water reuse rates climb as membrane costs decline.
- China's MEE enforcement:The Ministry of Ecology and Environment tightens online effluent monitoring for chemical parks. Non-compliant facilities face production suspensions.
Market Restraints
- Caustic soda price volatility:pH adjustment chemicals swing with chlor-alkali capacity curtailments. Treatment operators absorb margin compression or pass through via fuel-blending surcharges.
- Specialized incineration scarcity:North American hazardous liquid waste disposal concentrates among three thermal treatment networks. Permit scarcity blocks new market entry.
- Anaerobic digestion temperature sensitivity:Mesophilic systems stall in cold climates without supplemental heat. Biogas yields drop below project finance thresholds.
Strategic Opportunities
- India's Central Pollution Control Board mandates:Online effluent monitoring hardware and data platform contracts open for textile clusters in Gujarat and Tamil Nadu.
- Electrocoagulation convergence:Combined electrocoagulation-ultrafiltration units target oilfield produced water in Texas Permian Basin. Brine disposal costs drive adoption.
- Industrial service contract bundling:Integrated water-energy-material recovery packages displace spot hauling. Chemical plants in Belgium and the Netherlands pilot twenty-year performance agreements.
Industry Challenges
- Process control engineering shortage:Biological nutrient removal optimization requires specialized expertise in nitrification-denitrification kinetics. Universities produce fewer environmental engineering graduates than plant retirements.
- Legacy SCADA integration:Municipal utilities operate decades-old distributed control systems. Cybersecurity patches conflict with real-time process monitoring requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquid Waste Management Market |
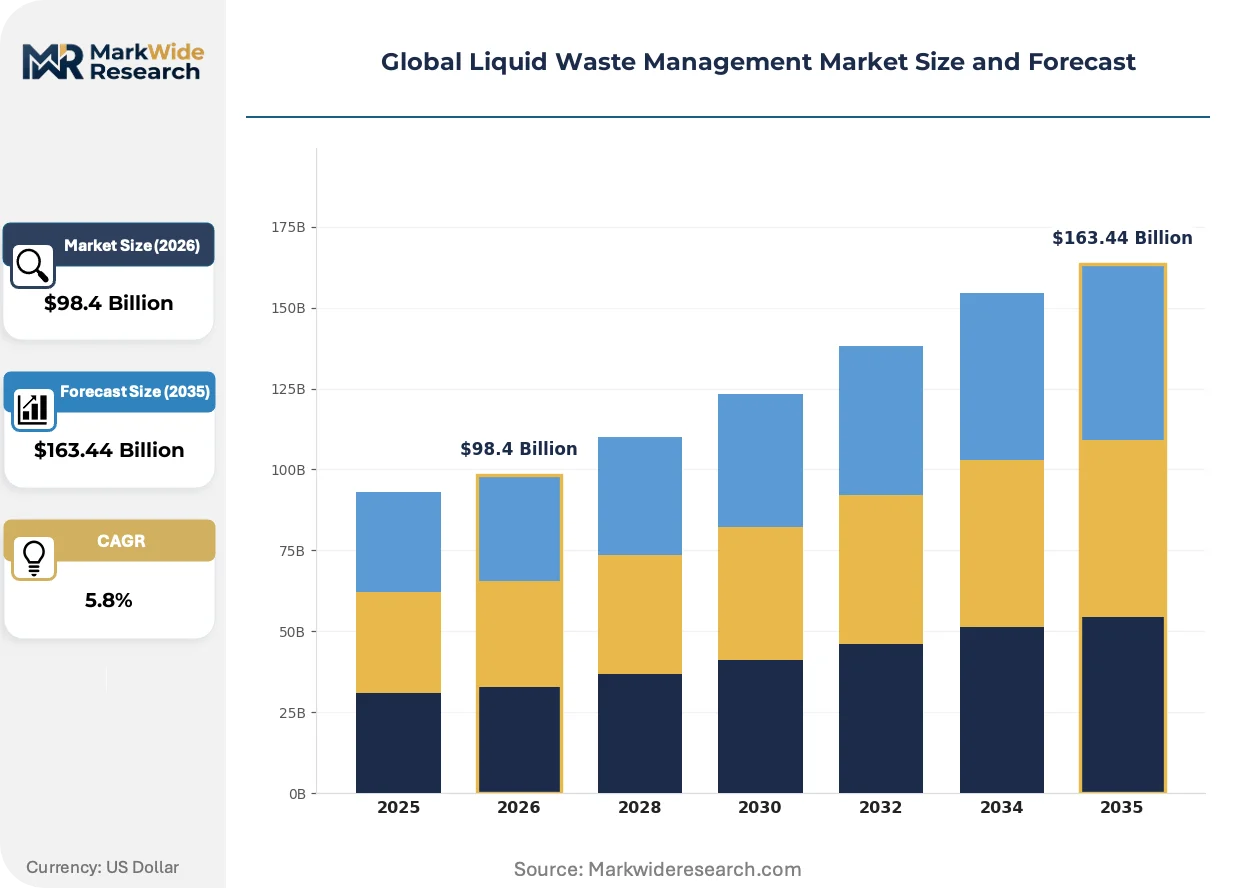
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $163.44 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Treatment, Recycling, Disposal, Transportation Application: Municipal, Industrial Facilities, Agricultural Sites, Construction Projects, Commercial Premises Technology: Membrane Filtration, Aerobic Digestion, Anaerobic Digestion, Chemical Precipitation, Thermal Treatment End User: Water Utilities, Manufacturing Plants, Food Processing Units, Energy Production Facilities, Research Centers |
| Companies Covered | Republic Services, GFL Environmental, Veolia, Covanta, Remondis, Clean Harbors, Suez, Waste Connections, Waste Management, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquid Waste Management Market Shifts & Advancements
Digital twin modeling of treatment trains is compressing commissioning timelines and enabling predictive chemical dosing. Vendors bundle hardware with subscription analytics.
Forward osmosis draw-solute regeneration is absorbing capital allocation from conventional reverse osmosis at high-salinity industrial sites. Food processors in California's Central Valley deploy forward osmosis to concentrate organic waste streams before anaerobic digestion. The technology is absorbing volume that thermal evaporators previously captured, cutting energy intensity by half.
The EPA's forthcoming per- and polyfluoroalkyl substances effluent limitation guidelines will impose nanogram-per-liter detection limits on select industrial categories. Metal finishing and electronics manufacturing facilities face multi-million-dollar activated carbon or ion exchange retrofits. Michigan and Minnesota state regulators are advancing ahead of federal timelines, accelerating capital commitment decisions.
Large industrial buyers now unbundle treatment plant operation from engineering-procurement-construction contracts. Chemical manufacturers in Germany's Ruhr region hire specialist operators under availability-based payments. This procurement split shifts performance risk to vendors while retaining capital ownership with industrial clients.
Global Liquid Waste Management Market Segmentation
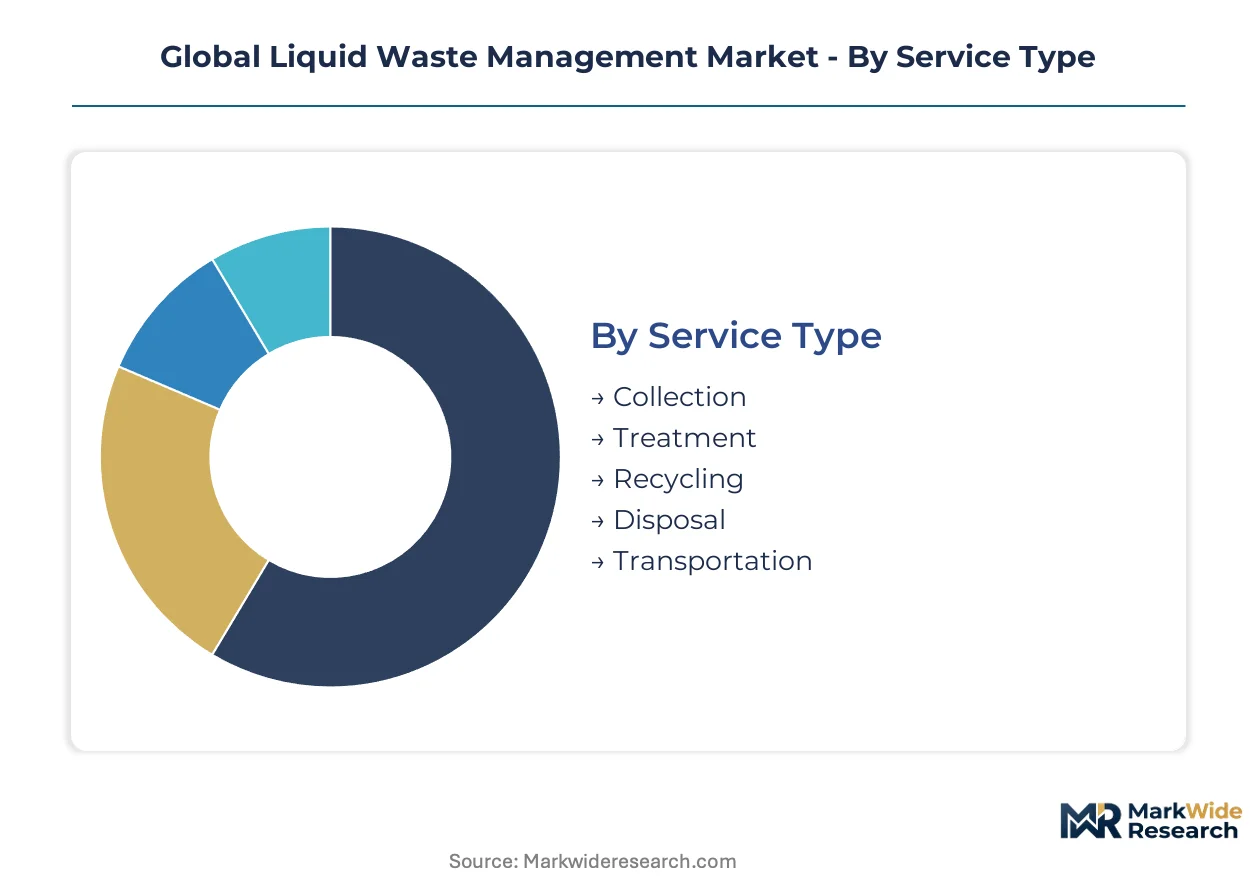
Liquid waste management procurement splits across service modes, regulatory contexts, and technical complexity tiers. Buyers optimize total cost of ownership through bundled contracts or spot purchasing depending on waste stream characteristics and discharge permit stringency.
Service Type:
Capital deployment concentrates in treatment infrastructure while collection and transportation remain fragmented across regional haulers.
- Collection:Vacuum truck fleets and interceptor maintenance services handle non-hazardous effluent from municipal sewers and industrial sumps. Demand clusters in Germany's chemical corridor where pre-treatment sampling precedes centralized processing. The country's packaging sector circular economy mandates require segregated collection of liquid byproduct streams.
- Treatment:Biological, chemical, and physical processing systems neutralize contaminants to meet EPA effluent limitation guidelines or EU Industrial Emissions Directive thresholds. US Great Lakes region industrial clusters drive zero-liquid-discharge upgrades. Capital intensity and regulatory compliance burdens concentrate revenue in this segment.
- Recycling:Water reuse and material recovery systems reduce freshwater intake at semiconductor fabrication and food processing facilities. Membrane filtration deployment is climbing as unit costs decline.
- Disposal:Final disposition through deep-well injection, land application, or thermal destruction handles non-recoverable residues. North American hazardous liquid waste disposal concentrates among three thermal treatment networks.
- Transportation:Bulk tanker and drum logistics bridge collection points with treatment or disposal facilities. Spot hauling competes with integrated service contracts.
Today's leader: Treatment. Tomorrow's challenger: Recycling.
Application:
Cost tier differentiation separates municipal rate-base stability from industrial spot-market volatility.
- Municipal:Publicly owned treatment works serve residential and commercial sewage loads under regulated rate structures. India's Central Pollution Control Board mandates online effluent monitoring for designated municipal systems.
- Industrial Facilities:Manufacturing plants pre-treat process water to meet categorical discharge standards. Michigan and Minnesota state regulators advance per- and polyfluoroalkyl substances limits ahead of federal timelines.
- Agricultural Sites:Livestock operations and food processing units manage nutrient-laden runoff. Anaerobic digestion deployment is expanding fastest here for biogas co-generation revenue.
- Construction Projects:Dewatering and tunneling effluent requires temporary treatment capacity. Mobile membrane units serve this intermittent demand.
- Commercial Premises:Restaurants, hospitals, and retail properties generate grease, medical, and cleaning waste streams. Collection density determines hauler profitability.
Municipal anchors volume stability. Industrial delivers margin expansion.
Technology:
Application specificity drives technology selection across salinity, organic load, and contaminant chemistry.
- Membrane Filtration:Reverse osmosis and nanofiltration systems achieve water reuse at semiconductor fabrication facilities. Forward osmosis draw-solute regeneration is cutting energy intensity at high-salinity sites.
- Aerobic Digestion:Conventional activated sludge remains dominant for municipal carbon removal. Biological nutrient removal upgrades target tightening phosphorus limits.
- Anaerobic Digestion:Mesophilic systems generate biogas from food processing and agricultural waste. Temperature sensitivity in cold climates requires supplemental heat.
- Chemical Precipitation:Coagulation and flocculation remove heavy metals and suspended solids. Caustic soda price volatility swings operating costs.
- Thermal Treatment:Incineration and fuel-blending destroy hazardous constituents. Permit scarcity blocks new market entry in North America.
Membrane filtration captures capital flow. Anaerobic digestion scales fastest.
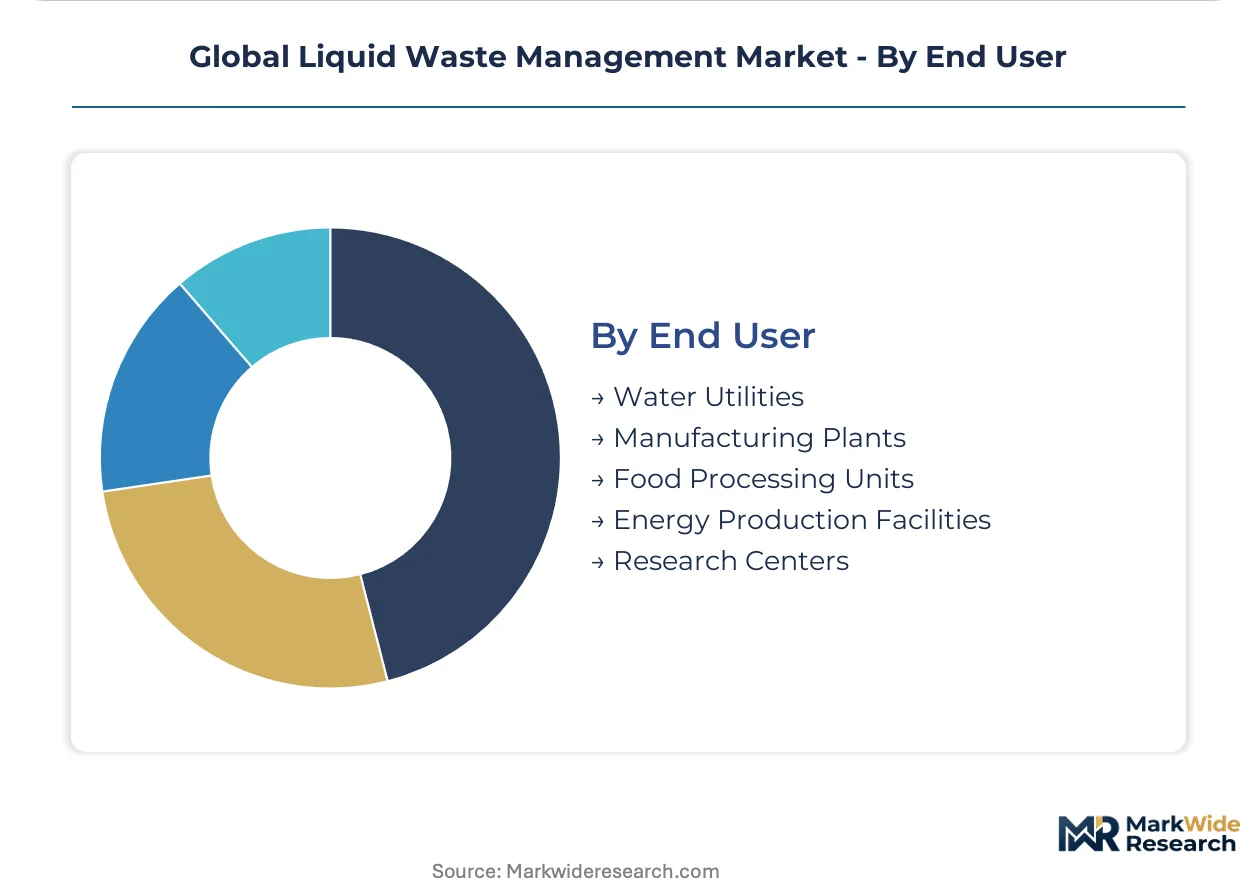
End User:
Customer type determines contract structure from availability-based payments to spot procurement.
- Water Utilities:Municipal and regional authorities operate collection and treatment infrastructure. Legacy SCADA integration challenges cybersecurity upgrades.
- Manufacturing Plants:Chemical, electronics, and metal finishing facilities face multi-million-dollar activated carbon retrofits for per- and polyfluoroalkyl substances compliance.
- Food Processing Units:Dairy, meat, and beverage operations deploy anaerobic digestion for organic waste concentration. California's Central Valley leads forward osmosis adoption.
- Energy Production Facilities:Power plants manage cooling tower blowdown and flue gas desulfurization wastewater. Zero-liquid-discharge mandates compress discharge permits.
- Research Centers:Laboratories generate small-volume hazardous liquid waste requiring specialized handling. Incineration capacity constraints affect disposal economics.
Manufacturing plants drive technology upgrade cycles. Food processing units expand fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Environmental engineering talent clusters in Germany's Ruhr Valley and the US Great Lakes industrial corridor anchor liquid waste management capacity. Regulatory stringency in these regions compresses discharge permits and forces capital deployment toward closed-loop infrastructure. Municipal utilities and industrial clusters compete for scarce process control expertise.
United States
Industrial effluent from semiconductor fabrication and metal finishing drives membrane filtration deployment. The EPA's forthcoming per- and polyfluoroalkyl substances effluent limitation guidelines impose nanogram-per-liter detection limits. Michigan and Minnesota state regulators advance ahead of federal timelines, accelerating activated carbon retrofits in Minneapolis-St. Paul industrial parks.
Germany
Circular economy directives mandate higher recycling rates for liquid industrial byproducts from packaging and manufacturing sectors. The EU Industrial Emissions Directive tightens phosphorus discharge limits, forcing biological nutrient removal upgrades. Chemical plants in North Rhine-Westphalia pilot twenty-year performance agreements with specialist operators.
China
Chemical parks face intensified online effluent monitoring under Ministry of Ecology and Environment enforcement. Non-compliant facilities risk production suspensions. Yangtze River Delta manufacturing clusters deploy zero-liquid-discharge systems to meet tightening discharge standards for heavy metals and organic pollutants.
India
Textile clusters in Gujarat and Tamil Nadu require online effluent monitoring hardware and data platform contracts under Central Pollution Control Board mandates. The Water Act designates polluting industries for continuous discharge oversight. Surat and Tiruppur dyeing operations upgrade biological treatment capacity to meet color and chemical oxygen demand limits.
Canada
Oil sands operators and food processors drive demand for anaerobic digestion and water reuse systems. Health Canada coordinates with provincial regulators on hazardous liquid waste classification. Alberta's oilfield produced water treatment market attracts electrocoagulation-ultrafiltration vendors targeting brine disposal cost reduction.
Global Liquid Waste Management Market Competitive Landscape
Top-tier vendors anchor integrated service networks, while regional haulers compete on collection density and spot pricing. The market structure concentrates revenue among multinational environmental service conglomerates with captive incineration and fuel-blending infrastructure. Three strategic archetypes dominate: asset-heavy treatment network operators, technology-integrated water reuse specialists, and logistics-focused collection platforms. Competitive moves center on long-term industrial service contract bundling and geographic expansion through municipal privatization mandates.
Within the asset-heavy tier, Veolia and Suez exemplify European-integrated treatment network operators with cross-border industrial service capabilities. Clean Harbors occupies a position as a North American hazardous liquid waste specialist anchored by thermal treatment infrastructure. GFL Environmental represents the collection-density archetype competing aggressively in Canadian and US municipal markets through vacuum truck fleet scale.
| Leading Market Players |
|---|
| Republic Services |
| GFL Environmental |
| Veolia |
| Covanta |
| Remondis |
| Clean Harbors |
| Suez |
| Waste Connections |
| Waste Management |
| Others |
Supply & Pricing Matrix
Caustic soda pricing volatility cascades through chlor-alkali supply chains into pH adjustment service tiers, compressing margins for regional treatment operators while multinational networks absorb swings via fuel-blending surcharge mechanisms. Chemical precipitation costs separate premium zero-liquid-discharge contracts from commodity hauling spot markets across Germany's Ruhr Valley and the US Great Lakes corridor.
Pricing Analysis
Bundled long-term service contracts diverge sharply from unbundled spot hauling on total cost of ownership metrics. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade for hazardous waste handling and geographic delivery cost to remote industrial clusters. Pricing pressure stems from caustic soda feedstock volatility in the chlor-alkali sector. Municipal utilities exhibit highest price sensitivity due to rate-base regulatory constraints, while semiconductor fabrication facilities prioritize water reuse reliability over unit cost.
Supply Chain Analysis
Freight costs for vacuum truck fleets and bulk tanker logistics concentrate procurement power among integrated operators with dense collection node networks. Supply concentrates in the United States, Germany, and China for membrane filtration systems and thermal treatment infrastructure. Raw material dependencies span caustic soda for pH adjustment, specialized ceramics for membrane modules, and natural gas for anaerobic digestion heat supplementation. Single-source vulnerability affects North American hazardous liquid waste incineration capacity. Distribution runs through regional treatment hubs linked to final deep-well injection or land application sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Liquid Waste Management Market functions as a stable compounder anchored by tightening EPA effluent limitation guidelines and EU Industrial Emissions Directive enforcement that mandate continuous capital redeployment into compliance infrastructure.
For Market Incumbents: Anchor market position through captive incineration capacity additions in North American thermal treatment networks where permit scarcity blocks new entrants. Deepen backward integration into membrane module manufacturing to offset ceramic supply chain vulnerability. Biological nutrient removal optimization expertise represents a defendable moat as university environmental engineering graduate output lags plant retirement rates.
For New Entrants and Emerging Players: Municipal utilities seeking cybersecurity-compliant SCADA upgrades present a channel partner type with fragmented incumbent coverage. India's textile clusters in Gujarat and Tamil Nadu offer the most penetrable geography for online effluent monitoring hardware and data platform contracts. Electrocoagulation-ultrafiltration units for oilfield produced water in Texas Permian Basin provide a technology-differentiated go-to-market angle against established hauling networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized incineration permit scarcity concentrates hazardous liquid waste disposal among three thermal treatment networks. The five-to-ten year viability window favors asset-heavy treatment network operators with cross-border industrial service capabilities over logistics-focused collection platforms. Acquisition targets should display integrated water-energy-material recovery packaging expertise. The signal to watch is EPA per- and polyfluoroalkyl substances effluent limitation guideline finalization timing, which will force activated carbon retrofit capital commitments across metal finishing and electronics manufacturing facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Liquid-Discharge Infrastructure Deployment | Closed-loop treatment systems capture long-term industrial service contracts in Germany's chemical corridor. |
| Membrane Filtration Technology Licensing | Forward osmosis draw-solute regeneration cuts energy intensity for California Central Valley food processors. |
| Specialized Incineration Capacity Expansion | Thermal treatment network additions address North American hazardous liquid waste disposal bottlenecks. |
| Biological Nutrient Removal Optimization | Phosphorus discharge compliance upgrades respond to EU Industrial Emissions Directive tightening. |
| Digital Twin Analytics Platform Launch | Predictive chemical dosing subscriptions compress commissioning timelines for municipal utilities. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with plant managers, municipal utility procurement officers, environmental engineering consultants, and membrane technology vendors with secondary validation. Secondary sources include EPA effluent limitation guideline dockets, EU Industrial Emissions Directive implementation reports, SEC 10-K filings from publicly traded environmental service conglomerates, and customs data on chlor-alkali trade flows. Bottom-up service contract value aggregation triangulates against top-down macroeconomic wastewater generation estimates.
Granularity-level modeling operates at treatment technology type, service mode, and end-user industry dimensions across the analysis window. Segment-level CAGRs derive from installed base expansion rates, regulatory compliance deadline clustering, and technology substitution curves for membrane filtration displacing conventional activated sludge. Forecast inputs incorporate anaerobic digestion biogas yield sensitivity to temperature variation and zero-liquid-discharge mandate adoption timelines in industrial clusters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to caustic soda price volatility, incineration permit issuance rates, and membrane cost decline trajectories. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption elasticities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Global Naphthalene Water Reducers Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
Slurry Homogenizer Tank Market
Water & Sludge Treatment
Water Gel Market
Water & Sludge Treatment
North America Industrial Water Treatment Market