
 Produced Water Treatment Market | 2026-2036
Produced Water Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Produced Water Treatment Market Intelligence
A capital-intensity divergence between integrated service providers and specialized equipment manufacturers is unwinding. Integrated giants like Halliburton and Schlumberger leverage their extensive oilfield service contracts to bundle water management solutions. In contrast, pure-play specialists such as Evoqua Water Technologies differentiate through advanced membrane and filtration system engineering. This dynamic creates distinct competitive pressures on both service margins and technology pricing, forcing a strategic choice between full-service integration and best-in-class component supply.
Produced water treatment involves processes to remove contaminants from the saline water co-produced during oil and gas extraction. This water typically contains high concentrations of total dissolved solids (TDS), oil, grease, and production chemicals, requiring multi-stage processing for safe disposal or reuse. Within the technology landscape, membrane filtration and advanced oxidation are gaining traction over traditional separation units for meeting stringent discharge limits. Applications for water reuse in hydraulic fracturing and for oilfield injection now represent the primary growth vector, surpassing demand for simple surface water discharge.
Regulatory frameworks established by bodies like the US Environmental Protection Agency (EPA) and China's Ministry of Ecology and Environment (MEE) dictate permissible contaminant levels for water discharge. Compliance with these standards, alongside directives like the EU's REACH regulation on chemical use, compels operators to invest in more effective treatment systems. A key strategic decision for operators revolves around adopting large-scale centralized treatment facilities versus deploying modular, on-site systems for greater operational flexibility.
Market Dynamics
The imperative to comply with stringent water discharge regulations, particularly standards on total dissolved solids (TDS) set by agencies like the US EPA, is the central force shaping the produced water treatment market's technology and service landscape.
Growth Catalysts
- Stricter Discharge Regulations:Environmental bodies, including the US EPA and China's MEE, are enforcing stricter limits on contaminants in discharged water, compelling oil and gas operators to invest in more advanced treatment technologies to achieve compliance.
- Water Reuse in Fracturing:In water-stressed oil and gas production regions like the Permian Basin, the economic and logistical benefits of treating and reusing produced water for hydraulic fracturing operations are a primary demand driver.
- Technological Advancements:Innovations in membrane filtration and advanced oxidation processes are improving treatment efficiency and lowering operational costs, making water reuse a more economically viable option compared to disposal or freshwater sourcing.
Market Restraints
- High Capital Investment:The significant upfront capital expenditure required for sophisticated treatment facilities, particularly those using advanced membrane or thermal distillation technologies, can be prohibitive for small and mid-sized exploration and production companies.
- Feedwater Variability:The chemical and physical composition of produced water varies widely between geological basins and even over the life of a single well, complicating the design and operation of standardized, efficient treatment systems.
- Waste Stream Management:The disposal of concentrated byproducts from the treatment process, such as high-salinity brine and contaminated sludge, presents a significant logistical, environmental, and cost-related challenge for operators.
Strategic Opportunities
- Modular and Mobile Systems:There is a growing opportunity for modular, containerized treatment units that can be deployed on-site, offering greater operational flexibility and scalability compared to large, centralized treatment facilities, especially for remote or short-term projects.
- Digitalization for Optimization:Integrating AI-powered analytics and IoT sensors into treatment systems allows for real-time monitoring and predictive control, optimizing chemical dosing and energy consumption while minimizing downtime.
- Beneficial Reuse Applications:Exploring pathways for the beneficial reuse of treated produced water outside the oilfield, such as for agricultural irrigation or industrial cooling in arid regions, opens up new long-term value streams.
Industry Challenges
- Specialized Labor Shortage:A scarcity of trained operators and water chemists with the skills to manage complex, multi-stage treatment plants is a key operational bottleneck, particularly in remote production areas.
- Integration with Legacy Infrastructure:Retrofitting new, advanced water treatment technologies into existing oilfield production facilities and control systems can be complex, costly, and can lead to significant operational disruptions during installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Produced Water Treatment Market |
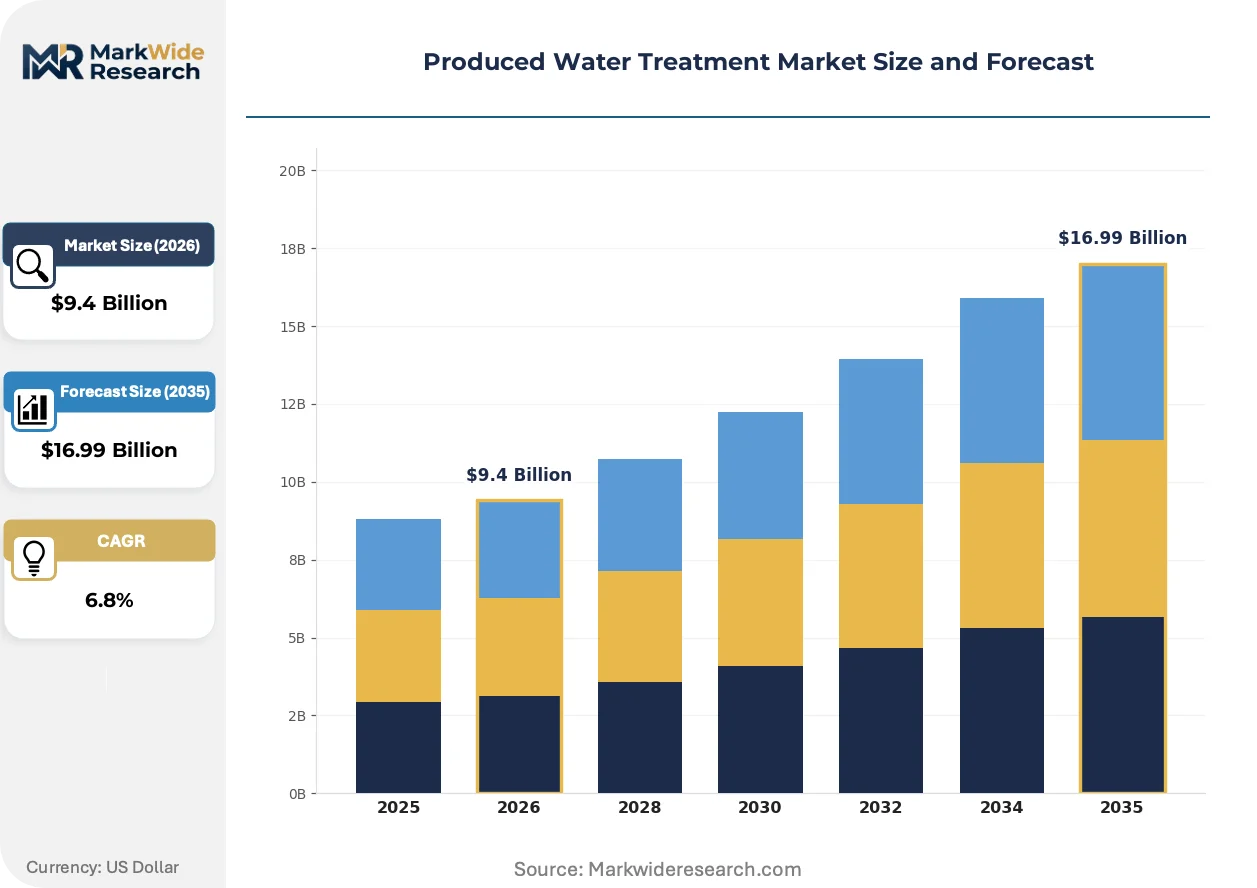
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Membrane Filtration, Ultraviolet Radiation, Electrocoagulation, Advanced Oxidation, Ion Exchange, Thermal Distillation Application: Water Reuse, Oilfield Injection, Surface Water Discharge, Agricultural Irrigation, Industrial Cooling, Dust Suppression End User: Exploration & Production Companies, Water Management Firms, Refining Facilities, Petrochemical Plants, Chemical Manufacturing, Environmental Contractors Product Type: Filtration Systems, Separation Units, Chemical Treatment, Biological Treatment, Desalination Equipment, Clarification Devices |
| Companies Covered | Halliburton, Evoqua Water Technologies, Veolia Water Technologies, Ecolab, Aquatech International, SUEZ Water Technologies & Solutions, Ovivo Inc., Xylem, Schlumberger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Produced Water Treatment Market Strategic Shifts & Innovations
A fundamental shift from a disposal-centric mindset to a value-creation approach defines the market's evolution. Technology is now geared toward enabling water reuse within oilfield operations, creating a circular economy for water resources in the extraction industry.
Advanced membrane technologies like reverse osmosis and forward osmosis provide superior separation of total dissolved solids and other challenging contaminants. Exploration and production companies are adopting these systems to meet the high water quality specifications required for hydraulic fracturing fluid. This move toward high-purity treatment is supplanting traditional physical separation units like hydrocyclones, which cannot meet stringent reuse standards.
The European Union's REACH regulation imposes strict controls on chemicals used in industrial processes, including those for water treatment. This compels oil and gas operators in regions like the North Sea to document and often substitute hazardous treatment chemicals with greener alternatives. The chemical management segment is most affected, with suppliers now prioritizing the development of REACH-compliant biocides, scale inhibitors, and flocculants.
Operators are increasingly favoring water-as-a-service and build-own-operate models for their treatment requirements. This approach shifts the upfront capital investment and operational risk to specialized water service providers, disrupting the traditional model of outright equipment purchasing. This trend is most prominent in active North American shale basins like the Permian and Eagle Ford, where operational agility and capital discipline are paramount.
Produced Water Treatment Market Segmentation
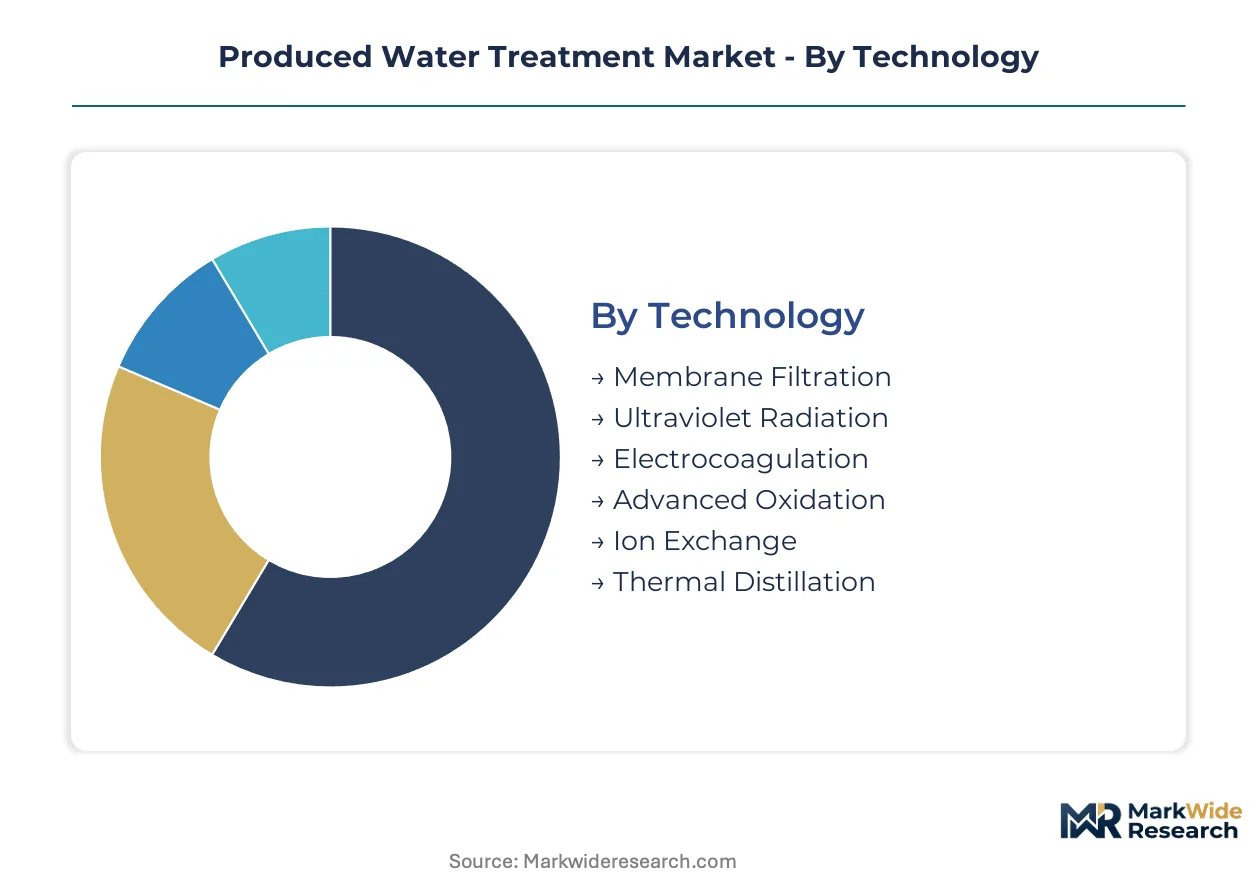
Market segmentation provides a granular view of the diverse technologies, applications, end-users, and product types driving the produced water treatment sector. Understanding these distinct segments helps stakeholders identify specific growth vectors and tailor solutions to varied operational demands across the energy industry.
Technology:
Technology choices for produced water treatment often reflect a blend of localized regulatory demands and the economic viability of domestic versus export-driven oil and gas operations.
- Membrane Filtration:This technology employs semi-permeable membranes to separate dissolved solids and contaminants from water, crucial for meeting stringent reuse quality in hydraulic fracturing operations across the Permian Basin.
- Advanced Oxidation:These processes utilize powerful oxidants like ozone or UV light with hydrogen peroxide to break down complex organic compounds and disinfect water, increasingly adopted for compliance with US EPA discharge limits.
- Ultraviolet Radiation:UV systems disinfect water by destroying microorganisms, providing a chemical-free solution for certain reuse applications.
- Electrocoagulation:This electrochemical process removes suspended solids, heavy metals, and emulsified oils through the generation of coagulants in situ.
- Ion Exchange:Ion exchange resins selectively remove specific dissolved ions, particularly effective for softening water or removing trace contaminants.
- Thermal Distillation:Distillation processes evaporate water and condense the pure vapor, producing very high-quality water but with significant energy consumption.
Membrane Filtration commands the established base. The steepest expansion runs through Advanced Oxidation.
Application:
Application segments are differentiated by the cost structures associated with treatment requirements and the value derived from the treated water.
- Water Reuse:Treated produced water is recycled for various oilfield operations, primarily hydraulic fracturing, significantly reducing freshwater demands in arid regions like the Middle East.
- Oilfield Injection:Treated water is injected into subsurface formations for enhanced oil recovery or disposal, a common practice in mature basins globally.
- Surface Water Discharge:Treated effluent is released into rivers, lakes, or oceans, requiring strict adherence to environmental regulations set by agencies like China's MEE.
- Agricultural Irrigation:Treated produced water can be used for non-potable agricultural purposes, offering a beneficial reuse pathway in water-stressed areas.
- Industrial Cooling:Treated water serves as makeup water for industrial cooling towers, reducing reliance on municipal or freshwater sources.
- Dust Suppression:Produced water is used to control dust on unpaved roads and construction sites, particularly in dry oilfield environments.
Oilfield Injection remains foundational. Water Reuse is expanding most quickly.
End User:
End user segments delineate the primary customer profiles, each with distinct operational scales and procurement strategies for produced water treatment solutions.
- Exploration & Production Companies:These operators directly manage oil and gas wells, requiring on-site or centralized treatment solutions for their co-produced water.
- Water Management Firms:Specialized companies offer comprehensive water treatment and disposal services, often managing large-scale infrastructure for multiple operators.
- Refining Facilities:Refineries generate process water that requires treatment before discharge or reuse, often similar in complexity to produced water.
- Petrochemical Plants:These facilities utilize produced water treatment technologies for their process wastewater, ensuring compliance with environmental standards.
- Chemical Manufacturing:Chemical producers require specialized water treatment for their industrial effluents, often integrating advanced separation techniques.
- Environmental Contractors:These firms provide remediation and treatment services for produced water, particularly for legacy sites or accidental spills.
Exploration & Production Companies form the core demand. Water Management Firms are progressively influencing market dynamics.
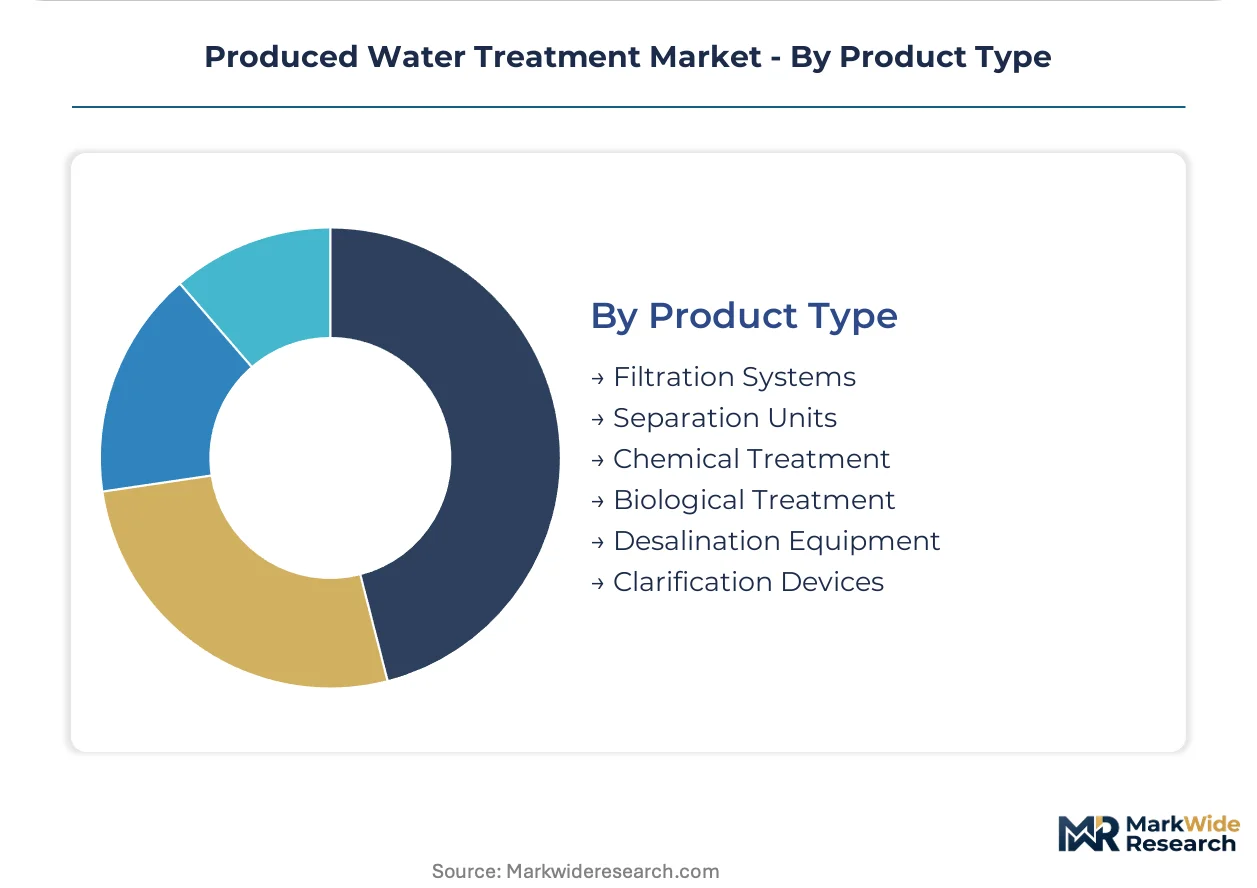
Product Type:
Product type segments are shaped by the concentration of specialized manufacturing capabilities and the supply chain complexities for specific treatment components.
- Filtration Systems:These systems include sand filters, cartridge filters, and membrane units designed to remove suspended solids and dissolved contaminants.
- Separation Units:Equipment like hydrocyclones, API separators, and dissolved air flotation units are used for initial oil-water separation.
- Chemical Treatment:This involves the use of flocculants, coagulants, biocides, and scale inhibitors to aid in contaminant removal and system protection, often regulated by REACH.
- Biological Treatment:Bioreactors and other biological processes break down organic compounds in produced water, particularly effective for certain types of contaminants.
- Desalination Equipment:Technologies such as reverse osmosis and multi-stage flash distillation are employed for significant salt removal, producing freshwater quality water.
- Clarification Devices:These units, including clarifiers and dissolved gas flotation, enhance the removal of suspended solids from water streams.
Separation Units provide essential foundational elements. Filtration Systems are capturing significant new investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Produced water treatment demand is highly inelastic in regions with stringent environmental mandates, while more elastic in areas prioritizing cost-efficiency over advanced reuse. Compliance with discharge limits and the imperative for water reuse in hydraulic fracturing operations drive investment across key oil and gas producing nations. Different regulatory frameworks and operational scales shape technology adoption patterns.
United States
Demand for produced water treatment in the United States stems from extensive hydraulic fracturing activities and the need for water reuse in arid regions. The US EPA enforces strict limits on total dissolved solids (TDS) and other contaminants in discharged water, compelling operators to invest in advanced treatment. In the Permian Basin, new modular systems address operational flexibility for rapidly evolving drilling programs.
China
China's produced water treatment market is driven by its significant domestic oil and gas production and the industrial sector's wastewater management needs. The Ministry of Ecology and Environment (MEE) sets stringent discharge standards, particularly for oil and grease, and chemical oxygen demand. In the Bohai Bay region, new investments target advanced membrane technologies for offshore produced water treatment.
Saudi Arabia
Saudi Arabia's demand for produced water treatment centers on enhanced oil recovery (EOR) projects and broader industrial water management amid acute water scarcity. The country's environmental standards, enforced by bodies like the National Center for Environmental Compliance (NCEC), necessitate effective treatment solutions. In the Eastern Province, large-scale desalination technologies for produced water are under consideration to support industrial expansion.
Canada
Canada's produced water treatment market is shaped by extensive oil sands operations and conventional oil and gas production. Provincial environmental regulations, such as those from the Alberta Energy Regulator (AER), dictate strict limits on water use and discharge from these operations. In Alberta, innovative treatment solutions are being developed for oil sands process water, focusing on reducing fresh water intake.
Brazil
Brazil's produced water treatment requirements originate from its substantial offshore pre-salt oil production and ongoing enhanced oil recovery efforts. IBAMA (Brazilian Institute of Environment and Renewable Natural Resources) sets strict discharge limits for offshore platforms, emphasizing oil-in-water content and toxicity. In the Campos Basin, new projects emphasize compact, high-efficiency treatment units suitable for space-constrained offshore applications.
Produced Water Treatment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the produced water treatment market. The market structure displays a tiered landscape, with global oilfield service providers offering bundled solutions alongside dedicated water technology firms. Strategic archetypes include integrated oilfield service providers, pure-play water technology specialists, and chemical solution suppliers. Dominant competitive moves involve strategic partnerships for technology integration and portfolio diversification into comprehensive water management services.
Integrated oilfield service providers like Halliburton represent one segment, leveraging existing oilfield contracts to offer water management solutions. Evoqua Water Technologies exemplifies specialized water technology firms, focusing on advanced membrane and filtration system engineering. SUEZ Water Technologies & Solutions occupies a position as a comprehensive water and wastewater treatment provider, offering a broad range of solutions across industrial applications.
| Leading Market Players |
|---|
| Halliburton |
| Evoqua Water Technologies |
| Veolia Water Technologies |
| Ecolab |
| Aquatech International |
| SUEZ Water Technologies & Solutions |
| Ovivo Inc. |
| Xylem |
| Schlumberger |
| Others |
Cost & Logistics Intelligence
Scale economies in large-scale produced water treatment facilities shape supply concentration and influence price floors. High capital investment for advanced systems necessitates significant throughput for economic viability, concentrating supply among larger service providers.
Pricing Analysis
After-sales service contracts drive significant lifetime value for produced water treatment providers. Project-based pricing dominates for new facility builds, while subscription-based models emerge for water-as-a-service offerings. Price differentiation stems from technology sophistication and the level of environmental compliance required by agencies like the US EPA. Pricing pressure intensifies due to the commoditization of basic physical separation units, with small and mid-sized exploration companies exhibiting higher price sensitivity.
Supply Chain Analysis
Global membrane manufacturing capacity underwrites the supply of advanced filtration systems for produced water treatment. Key components like specialized resins and advanced membrane materials are sourced from China, Germany, and the United States. Single-source vulnerability for niche membrane types represents a structural risk, particularly for advanced oxidation catalysts. Distribution runs through a network of specialized equipment providers and integrated oilfield service companies directly to exploration and production sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The produced water treatment market is a high-growth disruption, driven by the rapid adoption of advanced membrane technologies for water reuse. Stricter environmental regulations, such as US EPA TDS limits, further accelerate this transformation.
For Market Incumbents: Fortify existing oilfield service contracts by bundling advanced water management solutions, particularly in high-volume areas like the Permian Basin. Integrated players should invest in R&D for modular treatment systems to counter the threat of specialized pure-play technology firms. Capacity addition in key shale plays through strategic partnerships can also enhance market presence and operational flexibility.
For New Entrants and Emerging Players: Lead with specialized, high-efficiency membrane and advanced oxidation technologies tailored for water reuse in hydraulic fracturing. The most penetrable segment lies in modular, on-site systems for independent exploration and production companies in remote locations. Offer water-as-a-service models to shift upfront capital expenditure burdens, providing a compelling go-to-market angle against traditional equipment sales.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among water management firms offering long-term service contracts and build-own-operate models. The market exhibits strong long-term viability due to persistent regulatory pressure and water scarcity. Acquisition targets should focus on pure-play technology specialists with patented advanced oxidation or membrane filtration systems. The widespread adoption of beneficial reuse applications outside the oilfield is a key signal to watch for sustained growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Modular Treatment Units | Modular units enhance operational flexibility for Permian Basin operators, adapting to dynamic drilling programs. |
| Invest in Advanced Membrane R&D | Superior separation capabilities meet stringent US EPA discharge limits and high-purity reuse requirements. |
| Expand Water-as-a-Service Offerings | This model shifts capital expenditure risk from exploration companies to specialized service providers. |
| Pursue Beneficial Reuse Pathways | Agricultural irrigation and industrial cooling represent new long-term value streams for treated produced water. |
| Integrate AI for System Optimization | Digitalization allows real-time monitoring and predictive maintenance, reducing operational costs and downtime. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research validation. Primary insights came from conversations with water chemists, oilfield operations managers, regulatory compliance officers, and technology developers. Secondary data sources included US EPA reports, China MEE environmental directives, and company financial filings. A rigorous bottom-up and top-down triangulation approach ensured data accuracy across all market segments.
The analysis modeled market dynamics across the analysis window using a robust analytical framework. Segmentation dimensions included technology, application, end-user, product type, and regional regulatory stringency. Compound Annual Growth Rates were derived from historical trends and projected technological adoption rates. Key forecast inputs included crude oil prices and hydraulic fracturing activity levels.
The analysis sits within stated boundaries; outcomes outside significant shifts in global energy policy or water resource availability would require recalibration. Forecasts reflect underlying assumptions regarding regulatory enforcement and technological maturity. Practitioners should keep alternative scenarios live as environmental mandates and oilfield economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Water Softeners Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
Electrodeionization (EDI) Technology Market
Water & Sludge Treatment
Australia & New Zealand Water Treatment Chemicals Market
Water & Sludge Treatment
Sludge Treatment and Disposal Equipment Market
Water & Sludge Treatment
Global Wood Activated Carbon Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Market
Water & Sludge Treatment
Global Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
Internal Boiler Treatment Chemicals Market
Water & Sludge Treatment
Industrial Wastewater Treatment Market