
 Hypochlorous Acid Water Generator Market | 2026-2036
Hypochlorous Acid Water Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Hypochlorous Acid Water Generator Market Insights
East Asian electrolytic cell manufacturers are recalibrating capacity allocation toward higher-output industrial systems. OSG Corporation leverages its position in large-scale municipal installations across Japan. Danish Clean Water anchors European demand through specialized agricultural sector units. Electrolytic Technologies competes in North American healthcare with membrane-cell precision engineering.
Hypochlorous acid water generators produce aqueous solutions of HOCl via electrolysis of dilute salt brine, typically yielding concentrations between 50-200 ppm for surface disinfection applications. These systems serve industrial and commercial users seeking on-site chemical generation to eliminate hazardous material transport and storage liabilities. Portable generators lead volume shipments due to low capital thresholds and residential user uptake, while industrial systems command the dominant margin pool through long-term service contracts and membrane replacement revenue. Surface disinfection applications show the fastest structural expansion as food processors replace quaternary ammonium compounds with residue-free alternatives.
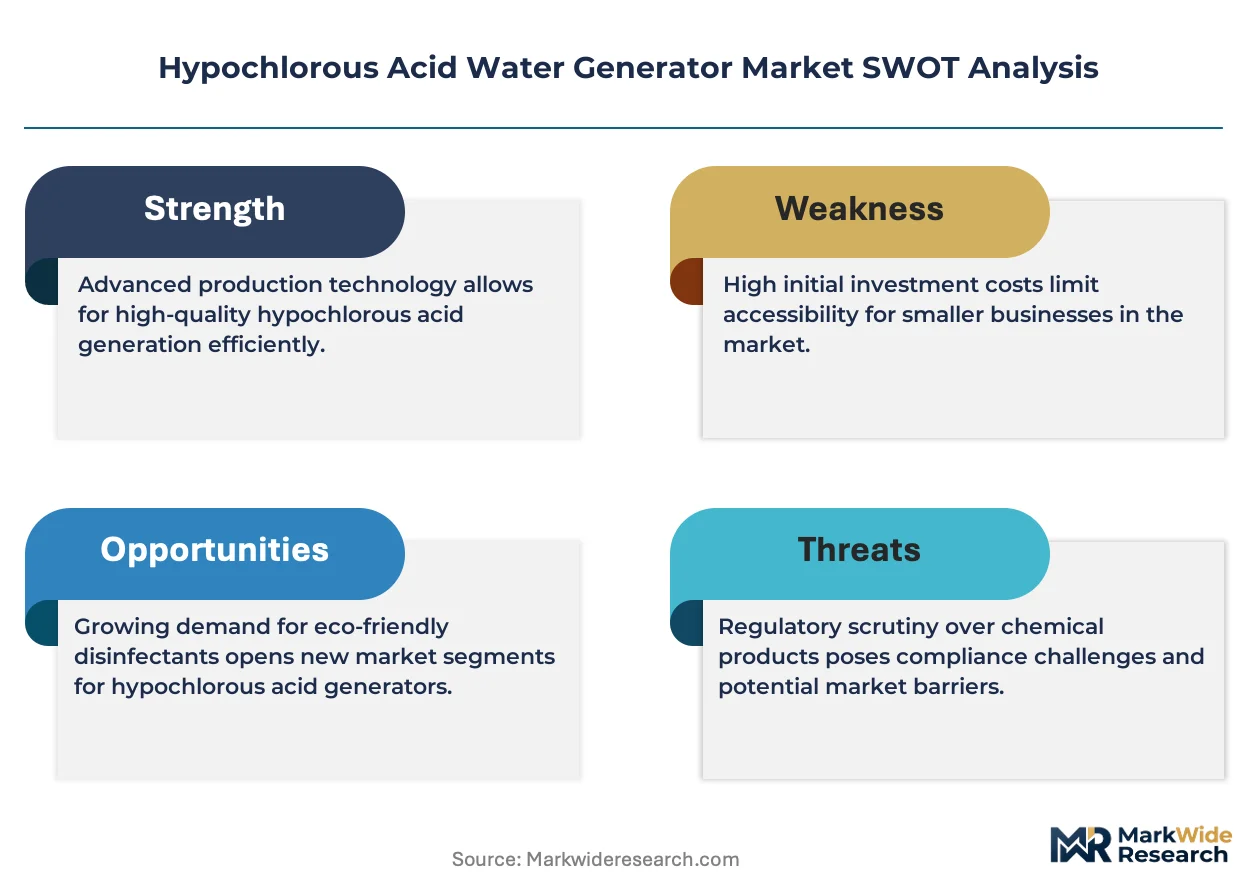
EPA registration requirements under FIFRA govern disinfectant claims in the United States, compelling manufacturers to validate efficacy data through approved laboratories before interstate commerce. Japan's METI enforces electrical appliance safety standards on electrolytic cells, creating compliance barriers for uncertified imports. The EU's Biocidal Products Regulation restricts active substance sourcing, shaping supplier qualification protocols across member states. Stakeholders must monitor evolving peracetic acid substitution rates and electrolyzer energy efficiency benchmarks to preserve margin structures amid rising electricity costs.
Market Dynamics
Electrolytic cell manufacturers face a structural pivot as membrane-cell precision engineering becomes the decisive factor in winning long-term service contracts across food processing and healthcare verticals.
Growth Catalysts
- EU Green Deal compliance pressure:REACH chlorine handling restrictions force European facilities toward on-site generation systems, eliminating hazardous bulk chemical transport liabilities.
- Japan's METI electrical safety standards:Certification requirements for electrolytic cells create competitive moats for approved domestic suppliers serving municipal and hospital installations.
- EFSA sanitation mandates:German food processors accelerate HOCl adoption as residue-free alternatives replace quaternary ammonium compounds in production line disinfection protocols.
Market Restraints
- Electricity cost volatility:Electrolyzer energy efficiency benchmarks determine margin viability, with rising grid prices compressing returns for high-throughput industrial operators.
- East Asian cell supply concentration:Capacity allocation decisions by Japanese and South Korean electrolytic component manufacturers create input bottlenecks for Western system integrators.
- Peracetic acid substitution threat:Sporicidal efficacy advantages in pharmaceutical cleanroom applications limit HOCl penetration in high-grade aseptic environments.
Strategic Opportunities
- Underpenetrated US healthcare procurement:EPA FIFRA registration requirements create compliance barriers that favor established players with validated efficacy data from approved laboratories.
- IoT-enabled predictive maintenance convergence:Sensor-integrated electrolytic systems allow remote monitoring of membrane degradation, unlocking subscription revenue streams.
- Danish agricultural sector specialization:Livestock biosecurity protocols in intensive farming operations drive demand for portable brine-fed units with automated concentration control.
Industry Challenges
- Electrochemical engineering talent scarcity:Specialized expertise in membrane-cell design and brine chemistry optimization remains concentrated among legacy electrolyzer manufacturers.
- EPA efficacy validation timelines:FIFRA-compliant laboratory testing extends product commercialization cycles, delaying revenue recognition for novel system configurations.
- Legacy quaternary ammonium infrastructure lock-in:Food processing facilities face capital write-down costs and retraining requirements when switching to HOCl-based sanitation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypochlorous Acid Water Generator Market |
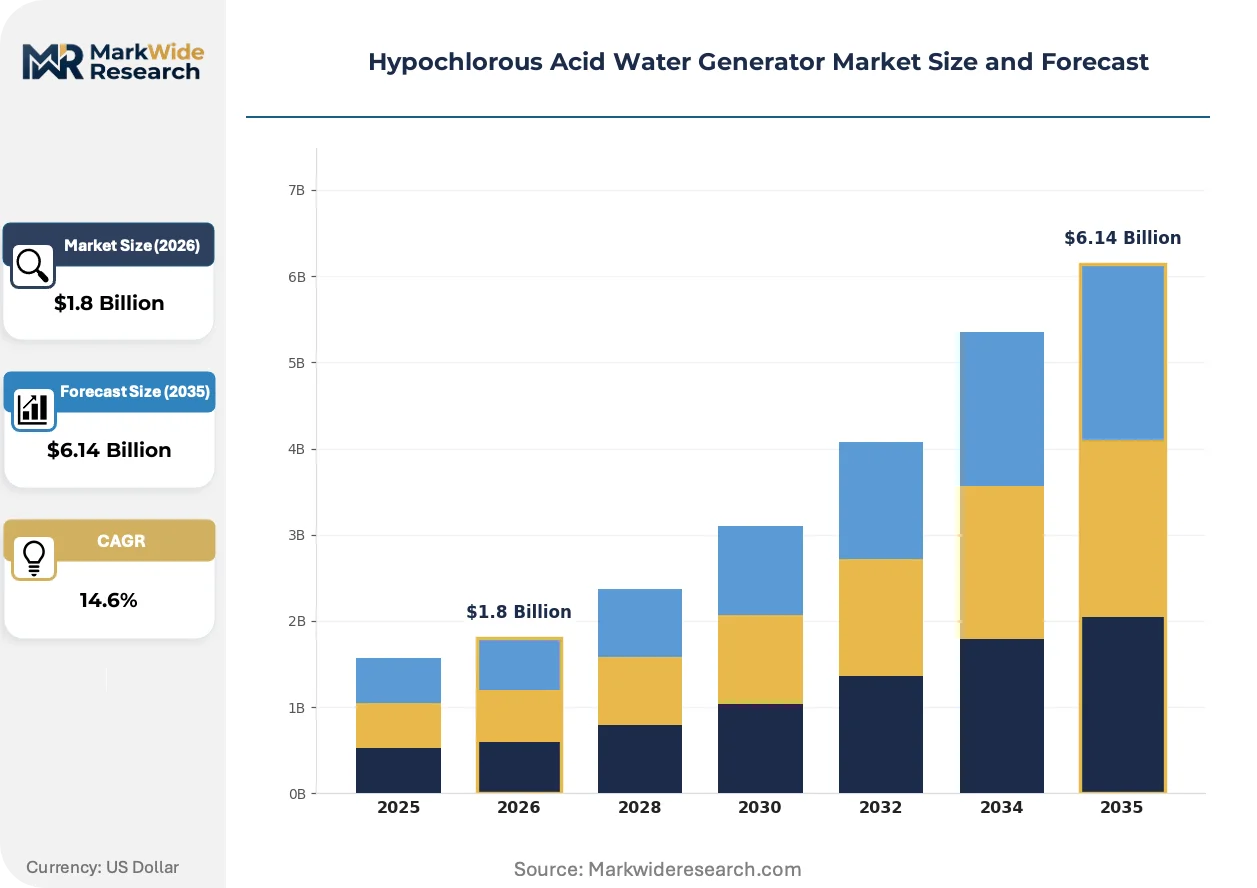
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Industrial Systems, Disinfection Units, Anionic Systems End User: Food Processing, Healthcare Facilities, Agricultural Sector, Residential Users Application: Water Treatment, Surface Disinfection, Medical Use, Cleaning Solutions Technology: Electrolysis, UV-LED, Chemical Mixing, Ion Exchange |
| Companies Covered | OSG Corporation, C & I International, Danish Clean Water, NaOClean, Ecoloxtech, Electrolytic Technologies, Ozone Water Systems, C.I. Agent Solutions, MIOX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypochlorous Acid Water Generator Market Trends and Innovations
Membrane-cell architecture is displacing conventional electrolytic designs as the dominant technical platform, reshaping competitive differentiation around precision concentration control and service contract economics.
Membrane-cell electrolysis is overtaking diaphragm-based systems in premium industrial installations. German food processors and Japanese hospital networks specify membrane configurations for their 50-200 ppm concentration stability. This technical shift is compressing margins for diaphragm-cell suppliers while expanding the addressable market for precision-engineered systems with remote monitoring capabilities.
REACH biocidal product authorization timelines are extending active substance qualification periods across EU member states. The ECHA evaluation process for electrolyzed water precursors now stretches commercialization schedules for new brine formulations. Food processors in Germany and France are responding by consolidating supplier relationships with established authorization holders rather than qualifying novel inputs.
Buyers are unbundling after-sales service from capital equipment procurement in North American healthcare. Hospital purchasing departments now separately negotiate membrane replacement schedules and remote technical support. This behavioral shift is most visible in California and Texas medical center networks, where three-year service contracts command premium pricing over standalone generator sales.
Hypochlorous Acid Water Generator Market Segmentation
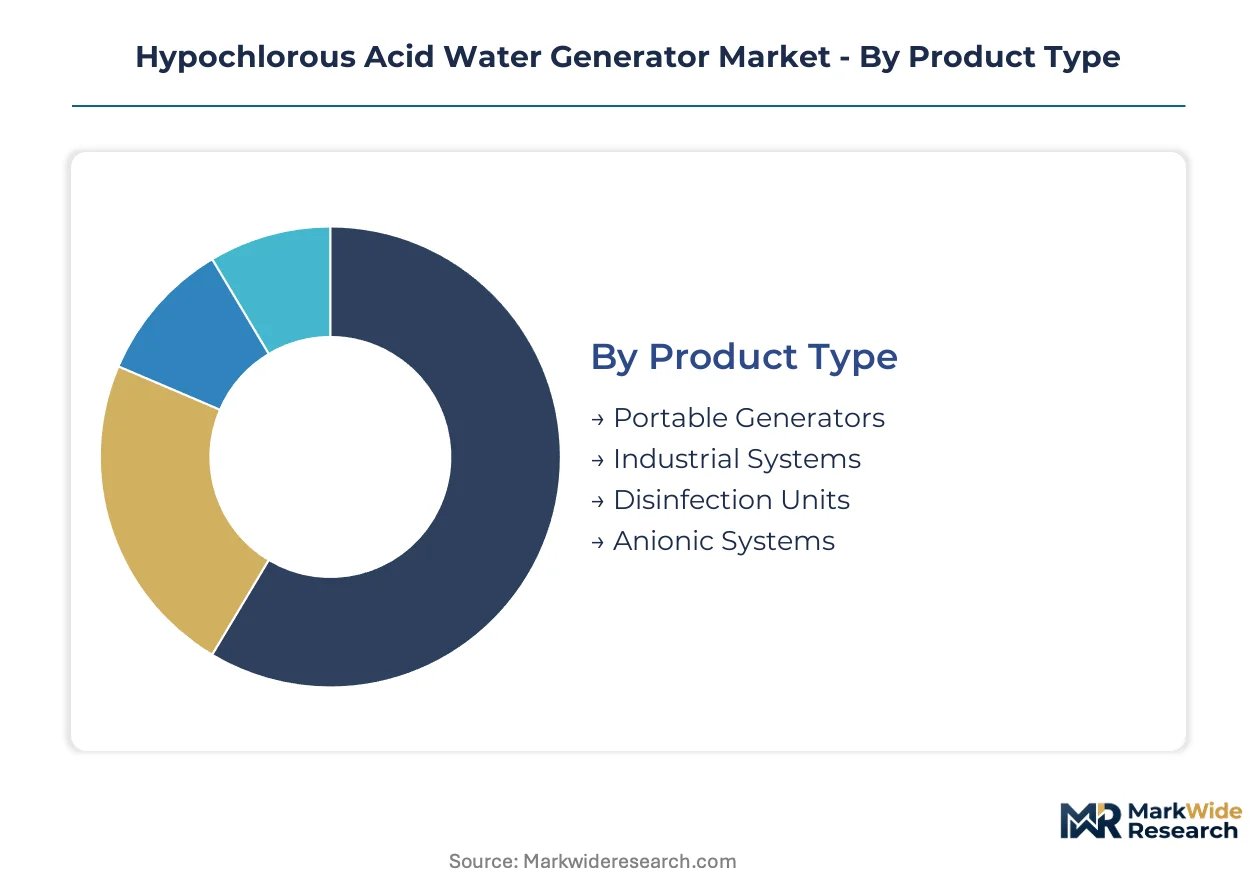
Segmentation in hypochlorous acid water generators reveals divergent margin economics between low-capital portable units and service-intensive industrial installations. Understanding these splits helps suppliers allocate R&D resources between membrane-cell engineering and cost-down manufacturing.
Product Type:
Volume shipments concentrate in entry-level equipment, while margin pools accrue to precision-engineered systems with long-term service attachments.
- Portable Generators:Compact brine-fed units producing 50-200 ppm solutions for small-scale users. Demand clusters in Danish livestock operations and Japanese residential markets where automated concentration control commands premium positioning. Electricity cost volatility compresses returns for high-throughput operators.
- Industrial Systems:Fixed-installation membrane-cell platforms with remote monitoring capabilities. German food processors and Japanese hospital networks specify these configurations for production line integration, generating recurring revenue through membrane replacement schedules and technical support contracts.
- Disinfection Units:Specialized equipment for surface sanitation protocols in commercial environments.
- Anionic Systems:Niche configurations targeting specific water chemistry requirements in select industrial applications.
Today's leader: Industrial Systems. Tomorrow's challenger: Portable Generators.
End User:
Regulatory pressure varies sharply across user categories, with EU biocidal mandates and Japanese electrical safety standards creating divergent compliance burdens.
- Food Processing:German facilities under EFSA sanitation mandates accelerate HOCl adoption to replace quaternary ammonium compounds. Residue-free requirements drive specification of membrane-cell systems with validated concentration stability.
- Healthcare Facilities:Japanese hospital networks expand on-site electrolysis capacity under METI certification requirements. EPA FIFRA registration barriers in the US favor established players with approved efficacy data.
- Agricultural Sector:Intensive farming operations in Denmark deploy portable brine-fed units for livestock biosecurity protocols.
- Residential Users:Low capital thresholds support volume uptake of compact generators for domestic disinfection applications.
Food Processing claims the steepest expansion trajectory. Healthcare Facilities hold the deepest service contract value.
Application:
Performance requirements differentiate between continuous-flow water treatment and intermittent surface disinfection protocols.
- Surface Disinfection:Fastest-climbing application as food processors eliminate quaternary ammonium residue concerns. German production lines specify HOCl for equipment sanitation between batch cycles.
- Water Treatment:Municipal and industrial continuous-flow applications requiring sustained concentration stability. Japanese installations favor membrane-cell precision for large-scale distribution systems.
- Medical Use:Sterilization protocols in healthcare environments with stringent efficacy validation requirements.
- Cleaning Solutions:General-purpose formulations competing with established chemical alternatives in commercial maintenance contracts.
Surface Disinfection is gaining share fastest. Water Treatment retains the largest installed base.
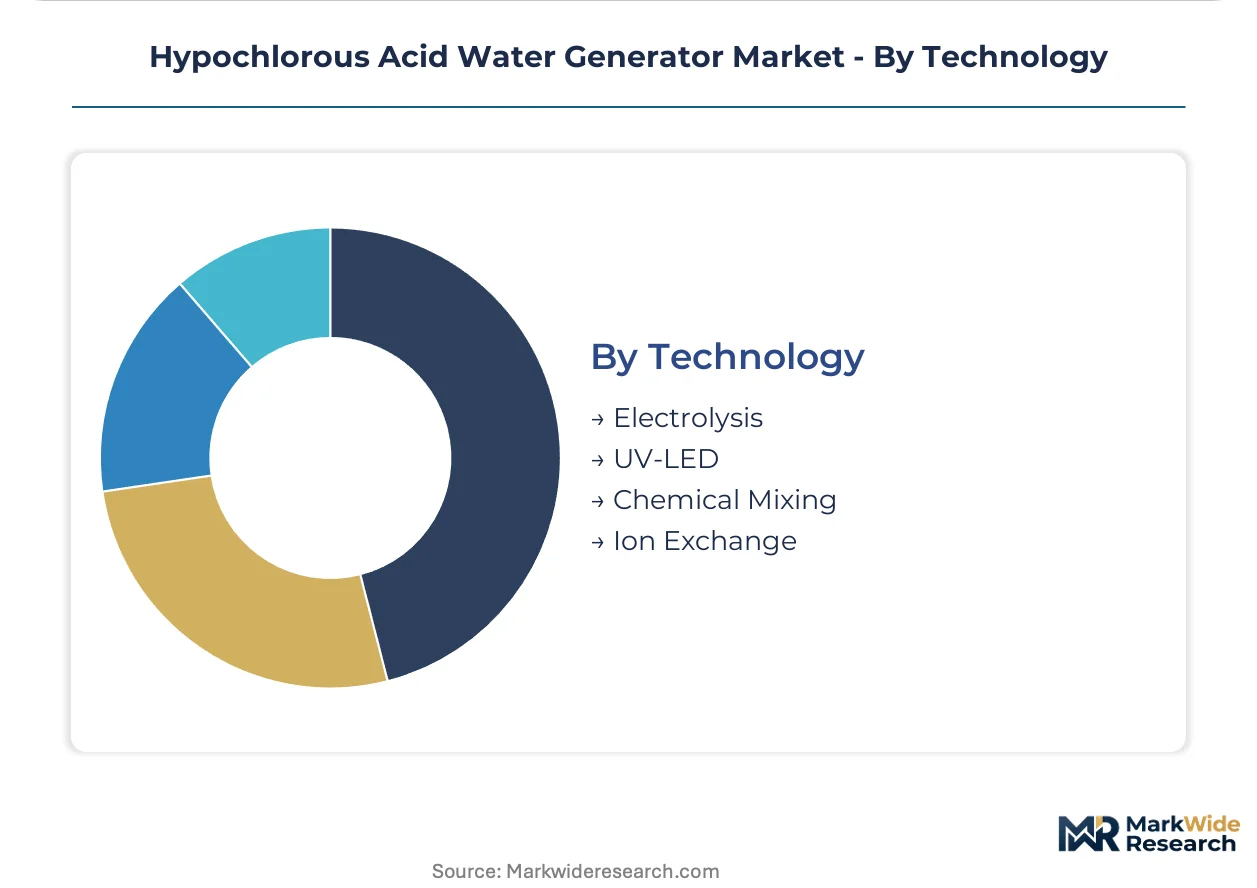
Technology:
Electrochemical engineering capabilities determine competitive differentiation as membrane-cell architectures displace conventional designs.
- Electrolysis:Dominant platform employing membrane-cell or diaphragm configurations. East Asian manufacturers concentrate capacity allocation toward higher-output industrial systems with precision concentration control.
- UV-LED:Emerging complementary technology for post-generation stabilization in premium installations.
- Chemical Mixing:Lower-cost batch production methods facing regulatory scrutiny under REACH biocidal product authorization timelines.
- Ion Exchange:Niche applications for specific water hardness conditions in select geographic markets.
Electrolysis anchors current supply. UV-LED integration represents the technology path to watch.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as compliance cost differentials widen between jurisdictions. Manufacturers migrate electrolytic cell assembly toward regions with streamlined biocidal product authorization, while generator system integration clusters near end-use demand centers to minimize logistics exposure.
United States
Hospital procurement networks in California and Texas drive demand for membrane-cell systems with validated EPA FIFRA registration. The EPA maintains stringent efficacy data requirements for interstate disinfectant claims, creating compliance moats for established authorization holders. Medical center networks in the Southwest concentrate purchasing power through consolidated three-year service contracts.
Germany
EFSA sanitation mandates accelerate HOCl adoption across food processing corridors in Bavaria and North Rhine-Westphalia. REACH biocidal product authorization timelines stretch qualification periods for novel brine formulations, pushing processors toward established authorization holders. Industrial clusters around Munich and Cologne specify membrane-cell precision for production line integration.
Japan
METI electrical appliance safety standards for electrolytic cells create competitive barriers for uncertified imports. Hospital networks in Tokyo and Osaka expand on-site electrolysis capacity to eliminate hazardous bulk chemical deliveries. Municipal installations across the Kanto region favor large-scale membrane-cell platforms with remote monitoring capabilities.
Denmark
Intensive livestock operations in Jutland deploy portable brine-fed units for biosecurity protocols in pig and poultry farming. The EU Green Deal compliance framework tightens chlorine-based disinfectant handling rules, accelerating on-site generation adoption. Agricultural cooperatives concentrate demand for automated concentration control systems.
South Korea
Electrolytic component manufacturers in Gyeonggi-do and Busan recalibrate capacity allocation toward higher-output industrial systems. MFDS medical device regulations govern healthcare applications, shaping supplier qualification protocols. Industrial parks around Seoul supply membrane-cell subsystems to Western system integrators facing East Asian input bottlenecks.
Hypochlorous Acid Water Generator Market Competitive Landscape
East Asian producers anchor the component supply tier; European and North American specialists hold system integration and service contract positions. The vendor base stratifies across membrane-cell precision engineering, portable unit manufacturing, and full-service industrial installation. Three archetypes dominate: electrolytic cell component suppliers, integrated generator manufacturers, and service-centric system providers. Capacity expansion and strategic technology licensing represent the dominant competitive moves as firms secure membrane formulation expertise.
Among Japanese industrial specialists, OSG Corporation exemplifies the large-scale municipal installation archetype. Danish Clean Water occupies a position within the agricultural sector specialization tier. Electrolytic Technologies represents the North American healthcare-focused precision engineering segment. These three entities anchor distinct geographic and vertical positioning strategies without overlapping core competence domains.
| Leading Market Players |
|---|
| OSG Corporation |
| C & I International |
| Danish Clean Water |
| NaOClean |
| Ecoloxtech |
| Electrolytic Technologies |
| Ozone Water Systems |
| C.I. Agent Solutions |
| MIOX Corporation |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal chlorine handling restrictions gate qualified supply for premium-tier membrane-cell systems, forcing German food processors and Japanese hospital networks to pay certification premiums while squeezing diaphragm-cell suppliers toward commodity positioning.
Pricing Analysis
Distributor margins on industrial membrane-cell systems run 18-25 points above portable unit markups due to bundled service contracts and METI certification documentation. Three-tier pricing structure across premium membrane-cell, standard diaphragm-cell, and economy portable levels tracks certification grade and after-sales attachment intensity. Cost compression in the mid-tier diaphragm segment is intensifying because East Asian manufacturers are reallocating capacity toward precision-engineered outputs. Residential users in Japan and Denmark show highest price sensitivity, while German food processors under EFSA mandates demonstrate lowest elasticity due to residue-free compliance requirements.
Supply Chain Analysis
Electrochemical engineering talent scarcity in Gyeonggi-do and Osaka metropolitan areas constrains membrane-cell production scaling despite capital availability. Supply concentrates in Japan, South Korea, and Germany for electrolytic subsystems, with titanium electrode coatings and perfluorinated ionomer membranes drawing from specialized chemical suppliers. Single-source vulnerability in East Asian membrane formulation creates bottleneck exposure for Western system integrators. Distribution runs through authorized service networks in healthcare and direct OEM integration in food processing, bypassing traditional industrial distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory mandates across Japan, Germany, and the United States institutionalize on-site generation requirements, replacing discretionary capital expenditure with compliance-driven procurement.
For Market Incumbents: Anchor service contract economics by locking three-year membrane replacement schedules with Japanese hospital networks and German food processors. Deepen backward integration into electrolytic cell manufacturing to offset East Asian component supply volatility. Peracetic acid substitution in pharmaceutical cleanrooms threatens premium positioning; counter with EPA FIFRA registration moats in US healthcare. For New Entrants and Emerging Players: Begin with Danish agricultural cooperatives and US Southwest medical center networks where procurement decentralization creates white-space. Target portable brine-fed units with IoT-enabled concentration monitoring for livestock biosecurity protocols. Lead with automated service subscription models rather than capital equipment sales to bypass incumbent installed-base advantages. For Investors and Strategic Acquirers: Roll-up economics work for precision membrane-cell specialists because ECHA authorization timelines extend active substance qualification periods, consolidating buyer relationships around established authorization holders. Five-to-ten year viability hinges on electrolyzer energy efficiency improvement trajectories. Watch peracetic acid substitution rates in pharmaceutical applications as inflection indicator for HOCl penetration ceilings.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Cell Capacity Expansion | Japanese and South Korean manufacturers recalibrate toward higher-output industrial systems serving EFSA-mandated German food processors. |
| Backward Integration into Electrode Coating | System integrators secure titanium substrate supply chains against East Asian input concentration and tariff exposure. |
| IoT-Enabled Predictive Maintenance Platform | Sensor-integrated electrolytic systems unlock subscription revenue streams through remote membrane degradation monitoring. |
| EPA FIFRA Registration Investment | Validated efficacy data from approved laboratories creates compliance moats for interstate disinfectant claims in US healthcare. |
| Agricultural Sector Specialization Partnership | Danish livestock cooperatives consolidate demand for portable brine-fed units with automated concentration control. |
Research Methodology
Direct dialogue with electrolytic cell engineers, hospital procurement managers, food processing sanitation directors, and agricultural cooperative technical officers grounded qualitative assessment. Secondary validation drew from METI electrical safety filings, ECHA biocidal product authorization databases, EPA FIFRA registration records, and Japanese customs trade statistics. Bottom-up electrolyzer shipment data triangulated against top-down end-use facility counts across German industrial corridors and Japanese municipal networks.
Installed base projections and revenue estimates emerged from segmentation modeling across product type, end user, application, and technology dimensions throughout the forecast period. CAGRs derived from regression analysis against electrolyzer energy efficiency benchmarks and electricity cost trajectories. Key inputs included membrane replacement cycle frequencies, REACH authorization timeline extensions, and peracetic acid substitution rates in pharmaceutical cleanroom specifications.
Several conditions sit outside the modeled scope, including abrupt shifts in EU electricity pricing, unanticipated ECHA active substance disqualifications, and breakthrough UV-LED stabilization technologies. Forecasts embed assumptions about regulatory continuity and membrane-cell architecture dominance. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
US Water and Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Alkalinity Control Chemicals Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
India Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Global Sodium Hypochlorite Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
Water and Wastewater Treatment Technologies Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market