
 Slurry Valves Market | 2026-2036
Slurry Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Slurry Valves Market Analytics
Buyer concentration among mining multinationals is consolidating procurement around fewer approved vendor lists, squeezing mid-tier suppliers. Flowserve Corporation leverages its aftermarket service network to lock in multi-year maintenance contracts. Weir Group anchors its position through backward integration into foundry operations for specialty alloys. KSB SE & Co. KGaA competes on energy-efficient actuator designs that reduce power draw at remote mine sites.
Slurry valves are flow-control devices engineered with hardened trim, replaceable liners, and extended bonnets to manage abrasive solid-liquid mixtures at pressures up to Class 600 and temperatures exceeding 200°C. Their primary purpose is to isolate, throttle, or divert process streams in applications where conventional valves erode within weeks. Ball valves dominate severe-service mining circuits where tight shutoff against high solids content protects downstream equipment. Stainless steel castings command premium positioning in chemical processing due to corrosion resistance requirements under ECHA REACH substance restrictions. Butterfly valves in cast iron sustain volume leadership in wastewater treatment where cost-per-installation governs municipal procurement.
EPA effluent limitations and OSHA silica exposure rules in the United States force mining operators toward zero-leakage valve specifications and automated isolation systems. EMA and ECHA frameworks in Europe pressure chemical processors to document full material compliance across valve supply chains. Stakeholders must monitor how China's MEE enforcement of tailings storage facility standards and Brazil's ANM dam safety protocols redirect specification priorities toward fail-closed actuation and remote monitoring compatibility.
Market Dynamics
Mining operators in Australia and Chile are compressing replacement cycles for slurry valves as tailings dam regulations tighten, forcing specification upgrades toward fail-closed actuation and ceramic-lined components that withstand higher abrasion.
Growth Catalysts
- MEE tailings enforcement:China's Ministry of Ecology and Environment mandates enhanced containment standards for copper processing facilities, accelerating demand for zero-leakage valve specifications in the Yangtze River corridor.
- Ceramic-lined ball valves:Hardened alumina and silicon carbide inserts now outlast elastomer seats by 8-12 months in iron ore slurry service, reducing unplanned shutdowns at Brazilian pelletizing plants.
- Remote mine electrification:Solar-hybrid power installations at Chilean copper operations favor low-power actuator designs that cut energy draw during isolation sequences.
Market Restraints
- Nickel alloy cost volatility:Super-duplex and Hastelloy trim prices swing with LME nickel futures, squeezing margin on Class 600 severe-service orders.
- Foundry concentration:Specialty casting capacity clusters in India's Coimbatore belt and Germany's Ruhr region, creating single-source vulnerability for hardened alloy components.
- REACH substance documentation:ECHA compliance requirements add 6-9 months to European chemical processor qualification timelines for new valve suppliers.
Strategic Opportunities
- Indonesia's nickel laterite surge:HPAL circuit expansions in Sulawesi and Halmahera create first-mover openings for high-pressure acid slurry valve specialists.
- Digital twin integration:Valve condition monitoring fused with predictive maintenance platforms enables outcome-based service contracts at Australian iron ore ports.
- EU Green Deal carbon border adjustments:Embodied carbon tracking favors European-sourced castings over imported alternatives in German chemical processing procurement.
Industry Challenges
- Weld overlay technician scarcity:Stellite and Inconel surfacing skills concentrate among aging specialists in Pittsburgh and Dusseldorf, constraining repair capacity expansion.
- Legacy SCADA integration:New smart valve actuators face protocol translation friction with 1990s-era distributed control systems still operating at Chilean state-owned mines.
- API 6D certification backlog:Third-party witness testing queues at notified bodies extend delivery schedules for offshore oil sands projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slurry Valves Market |
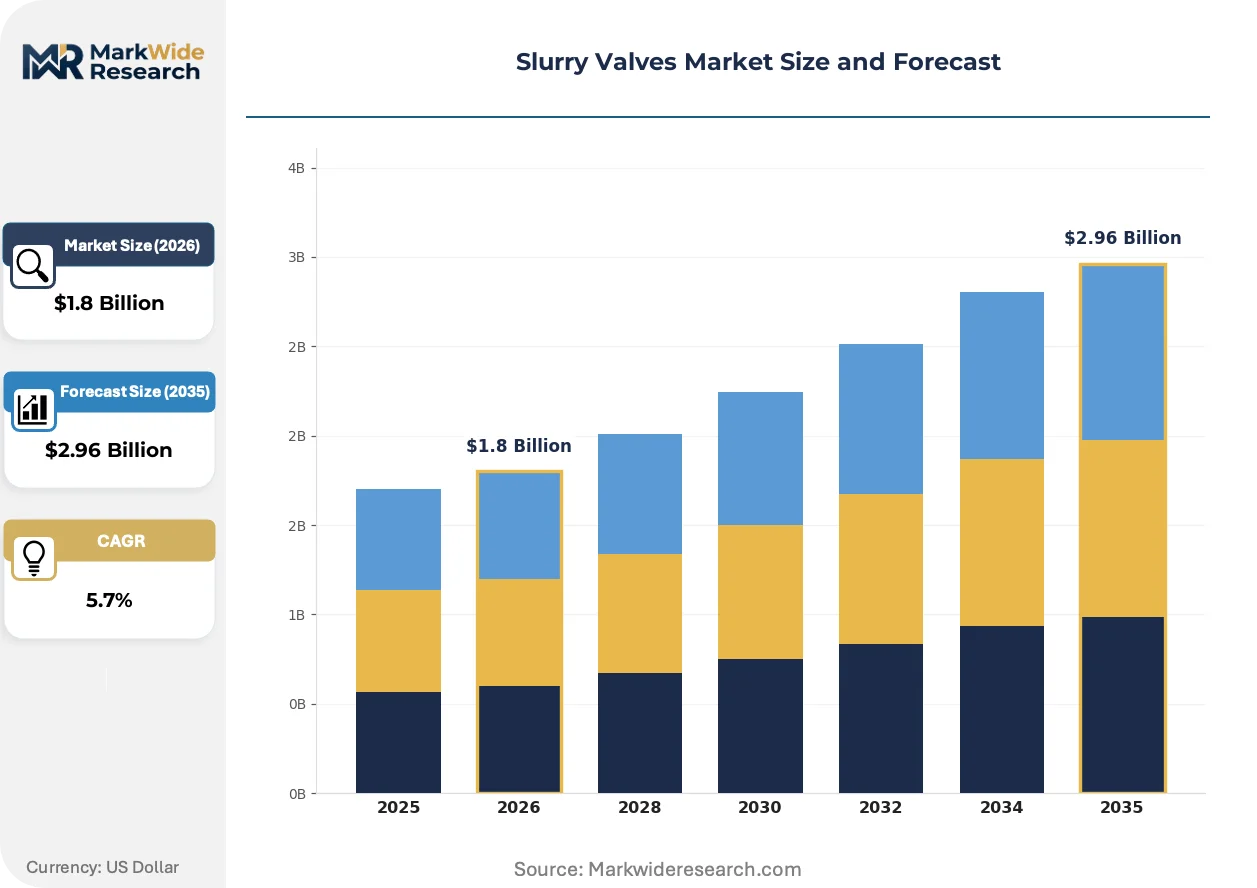
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Gate Valves, Butterfly Valves, Check Valves Material: Cast Iron, Stainless Steel, PVC, PTFE Connection Type: Flanged, Threaded, Welded, Socket End User: Mining, Wastewater Treatment, Chemical Processing, Power Generation |
| Companies Covered | Emerson Electric, Weir Group, Flowserve Corporation, Flowrox, Metso, KSB SE & Co. KGaA, Valmet, Red Valve, ORBINOX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slurry Valves Market Evolving Landscape
Actuation architectures and material science advances are compressing maintenance intervals while regulatory pressure on containment integrity forces specification upgrades across mining and chemical processing verticals.
Electro-hydraulic linear actuation is electrifying valve control at remote mine sites by eliminating pneumatic compressor infrastructure and enabling precise position feedback for automated isolation sequences. Copper operators in Chile's Atacama Desert are retrofitting ball valve arrays with battery-backed electric actuators to comply with ANM dam safety protocols requiring remote closure capability. This electrification is collapsing the total installed cost gap versus conventional pneumatic systems while enabling integration with mine-wide digital control platforms.
EPA effluent limitation guidelines under the Clean Water Act are compelling US hardrock mining operators to specify double-block-and-bleed configurations for tailings line isolation. The rule's technology-based standards force upgrades at legacy Arizona and Nevada copper facilities, redirecting capital toward zero-discharge valve packages. Gold operations in Nevada's Carlin Trend now prioritize metal-seated designs with extended bonnets for freeze protection in high-altitude tailings circuits.
Aftermarket service unbundling is fragmenting traditional full-service contracts as mining multinationals carve out predictive maintenance to specialized technology vendors. Rio Tinto and BHP have separated valve overhaul scope from original equipment supply, awarding condition monitoring and spare parts logistics to third-party specialists. This disintermediation is most pronounced in Western Australia's Pilbara iron ore region, where port maintenance hubs now stock generic ceramic liners compatible across multiple OEM platforms.
Slurry Valves Market Segmentation
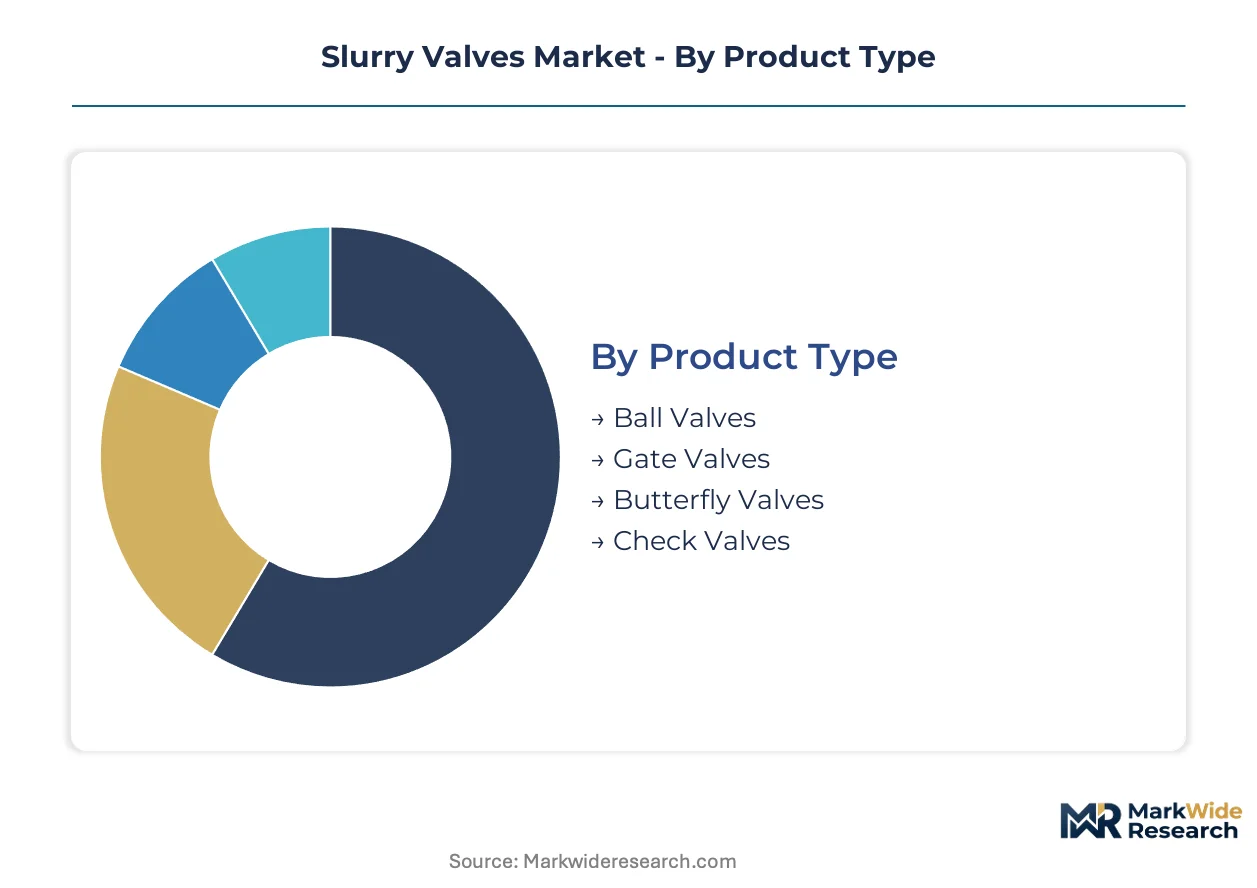
Slurry valve specification varies sharply across process severity, fluid chemistry, and duty cycle requirements. Procurement teams segment purchases by abrasion resistance needs, pressure class, and compatibility with existing piping infrastructure.
Product Type:
Ball valves function as standalone isolation devices in high-pressure mining circuits, while gate and butterfly configurations embed into larger flow control skids with shared actuation.
- Ball Valves:Spherical closure elements with hardened chrome-molybdenum seats achieve bubble-tight shutoff against iron ore slurries at 600 psi. Demand clusters in Brazil's Carajás pelletizing corridor where ANM dam safety rules mandate fail-closed isolation on tailings lines.
- Gate Valves:Rising-stem designs with replaceable elastomer sleeves suit lower-cycle wastewater applications. Municipal procurement in Germany's Ruhr region favors cast iron bodies for cost-per-installation efficiency in combined sewer overflow systems.
- Butterfly Valves:Wafer-style elastomer-lined discs throttle flow in low-pressure chemical transfer.
- Check Valves:Swing and tilting-disc configurations prevent backflow in vertical pump discharge lines.
Volume placements concentrate in ball valves; the faster expansion belongs to ceramic-lined specialty variants.
Material:
Material selection tracks fluid abrasiveness and regulatory exposure limits, with premium alloys commanding standalone specification in severe service.
- Cast Iron:Gray and ductile iron bodies dominate municipal wastewater budgets. German utilities specify EN-GJS-400-15 grades for butterfly valve bodies in phosphate removal circuits.
- Stainless Steel:CF8M and duplex castings resist acid chloride attack in copper solvent extraction. Australian HPAL projects in Queensland specify super-duplex trim for high-pressure acid slurry at 200°C.
- PVC:Thermoplastic construction serves low-temperature chemical dosing skids.
- PTFE:Fluoropolymer linings protect against hydrofluoric acid in specialty chemical transfer.
Cast iron sustains the highest unit volumes; stainless steel is climbing the fastest on tailings containment upgrades.
Connection Type:
Flanged and welded joints dominate permanent installations, while threaded and socket formats serve maintenance-accessible auxiliary lines.
- Flanged:ASME B16.5 raised-face connections enable rapid valve replacement in Chilean copper concentrators. Codelco specifications require 150# and 300# flanged ball valves for thickener underflow isolation.
- Threaded:NPT taper threads suit instrument and sampling lines. US hardrock mines specify threaded stainless valves for leak detection pump discharge.
- Welded:Butt-weld end preparations eliminate leak paths in buried tailings pipelines.
- Socket:Solvent-welded PVC connections serve corrosive chemical dosing systems.
Flanged configurations retain the dominant share; welded connections are expanding most quickly on buried infrastructure projects.
End User:
Mining operators specify premium severe-service valves as standalone capital items, while wastewater and power utilities embed valves into packaged plant deliveries.
- Mining:Copper, iron ore, and nickel laterite operations drive specification for ceramic-lined components. Vale's S11D expansion in Brazil specified 48-inch ceramic ball valves for slurry pipeline isolation.
- Wastewater Treatment:Municipal utilities prioritize total lifecycle cost. Thames Water's London super-sewer project procured resilient-seated gate valves for storm storage tunnel isolation.
- Chemical Processing:ECHA REACH compliance pressures material documentation across valve supply chains.
- Power Generation:Flue gas desulfurization circuits in coal plants specify alloy-lined valves for gypsum slurry handling.
Mining commands the largest revenue pool; wastewater treatment offers the steepest expansion trajectory on infrastructure renewal programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper processing corridors in China and iron ore belts in Brazil concentrate replacement demand for ceramic-lined valves as tailings containment standards tighten. Procurement teams at Australian and Chilean mining multinationals are consolidating approved vendor lists around suppliers with proven aftermarket networks.
China
Copper concentrators along the Yangtze River corridor are retrofitting tailings lines with zero-leakage valve specifications under MEE enforcement of enhanced containment standards. HPAL circuit expansions in Yunnan and Jiangxi provinces are pulling high-pressure acid slurry valves into 200°C service. Foundry clusters in Shanxi province supply hardened alloy castings for domestic valve fabricators serving the nickel laterite processing boom.
Brazil
Vale's Carajás pelletizing corridor and S11D expansion are specifying 48-inch ceramic ball valves for slurry pipeline isolation under ANM dam safety protocols. Iron ore operations in Minas Gerais are compressing replacement cycles for elastomer-seated valves as abrasion rates accelerate. Local procurement teams favor fail-closed actuation packages compatible with remote monitoring infrastructure mandated at tailings storage facilities.
Australia
Pilbara iron ore port maintenance hubs are stocking generic ceramic liners compatible across multiple OEM platforms as Rio Tinto and BHP unbundle aftermarket service contracts. Queensland HPAL projects specify super-duplex trim for high-pressure acid slurry at elevated temperatures. Western Australian copper-gold operations are retrofitting solar-hybrid power installations with low-draw electric actuators for automated isolation sequences.
Chile
Codelco specifications require 150# and 300# flanged ball valves for thickener underflow isolation across Atacama Desert copper concentrators. ANM protocols mandate battery-backed electric actuators with remote closure capability at tailings dams. State-owned mine operators face legacy SCADA integration friction when deploying smart valve actuators against 1990s-era distributed control systems.
Germany
Chemical processors in the Ruhr region document full material compliance across valve supply chains under ECHA REACH substance restrictions, extending qualification timelines for new suppliers. Municipal utilities specify EN-GJS-400-15 grade cast iron butterfly valves for combined sewer overflow systems. EU Green Deal carbon border adjustments favor European-sourced castings over imported alternatives in procurement decisions.
Slurry Valves Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ceramic-lined specialty niches and predictive maintenance platforms. The vendor base clusters around three archetypes: diversified flow control conglomerates with captive foundry capacity, pure-play slurry valve specialists with regional fabrication footprints, and aftermarket service unbundlers leveraging digital condition monitoring. Capacity expansion and backward integration into specialty alloy casting represent the dominant competitive moves as procurement consolidation squeezes mid-tier suppliers.
Among diversified flow control conglomerates, Emerson Electric, Flowserve Corporation, and Weir Group exemplify scale-driven positioning through integrated manufacturing and service networks. Flowserve leverages multi-year maintenance contract structures to lock in mining operator relationships. Weir anchors its market presence through in-house production of specialty alloy components. KSB SE represents the energy-efficient actuator design vector competing on power draw reduction at remote mine sites.
| Leading Market Players |
|---|
| Emerson Electric |
| Weir Group |
| Flowserve Corporation |
| Flowrox |
| Metso |
| KSB SE & Co. KGaA |
| Valmet |
| Red Valve |
| ORBINOX |
| Others |
Value Network & Pricing Analysis
Weld overlay technician scarcity in Pittsburgh and Dusseldorf compresses repair capacity and widens labor-cost differentials between premium certified shops and standard service providers, directly shaping three-tier pricing spreads across severe-service valve tiers.
Pricing Analysis
Volume placements cluster in cast iron butterfly valves for municipal wastewater where procurement teams optimize cost-per-installation, while margins concentrate in ceramic-lined ball valves for mining tailings isolation where ANM dam safety protocols mandate fail-closed actuation packages. Price differentiation rests on certification grade—API 6D witnessed testing commands premium positioning—and geographic delivery cost to remote Australian Pilbara port hubs versus Brazilian iron ore belt access. Cost compression in standard elastomer-seated tiers intensifies as generic ceramic liner compatibility across OEM platforms fragments aftermarket service bundling. Municipal wastewater utilities in Germany's Ruhr region exhibit highest price sensitivity on EN-GJS-400-15 grade cast iron procurement, while copper concentrators in Chile's Atacama Desert prioritize total lifecycle cost over unit price for thickener underflow isolation valves.
Supply Chain Analysis
Dual-sourcing requirements from mining multinationals mandate multi-supplier qualification for hardened alloy castings, forcing procurement teams to qualify foundries in India's Coimbatore belt alongside Germany's Ruhr region despite concentration risk in specialty casting capacity. Raw material dependencies center on nickel alloy feedstock—super-duplex and Hastelloy trim—plus alumina and silicon carbide ceramic inserts, with LME nickel futures volatility transmitting directly to Class 600 severe-service order margins. Single-source vulnerability concentrates in Stellite and Inconel surfacing skills among aging specialists, constraining repair capacity expansion. Distribution runs through OEM-direct channels for original equipment supply and unbundled third-party specialists for predictive maintenance platforms, particularly in Western Australia's Pilbara region where port maintenance hubs stock generic liners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH substance documentation requirements create six-to-nine-month qualification timelines that erect barrier-to-entry moats for European chemical processor suppliers with established material traceability systems.
For Market Incumbents: To counter aftermarket service unbundling by mining multinationals, backward integration into captive foundry operations for specialty alloys secures supply continuity while multi-year maintenance contract structures lock in operator relationships. Foundry capacity expansion in Shanxi province addresses China's HPAL circuit demand surge. For New Entrants and Emerging Players: Aftermarket technology vendors represent the most penetrable channel partner type for predictive maintenance platform integration, particularly in Western Australia's Pilbara iron ore region where Rio Tinto and BHP have separated valve overhaul scope from original equipment supply. White-space targets include ceramic-lined specialty niches for Indonesia's nickel laterite HPAL expansions and digital twin integration for Australian port maintenance hubs. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play slurry valve specialists with regional fabrication footprints given procurement consolidation around fewer approved vendor lists compressing mid-tier supplier margins. Long-term viability favors vendors with demonstrated aftermarket networks and remote monitoring compatibility. The signal to watch is ANM dam safety protocol enforcement acceleration across Brazilian iron ore operations driving specification upgrades toward fail-closed actuation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Foundry | Weir Group's captive casting supply secures hardened component availability amid Coimbatore belt concentration. |
| Multi-Year Maintenance Contract Structuring | Flowserve leverages service network density to lock in Chilean copper operator relationships against unbundling. |
| Predictive Maintenance Platform Development | Digital twin integration enables outcome-based contracts at Australian Pilbara port maintenance hubs. |
| Ceramic-Lined Product Line Expansion | Hardened alumina inserts outlast elastomer seats by 8-12 months in Brazilian iron ore slurry service. |
| Low-Power Actuator Design Investment | KSB SE's energy-efficient architectures reduce draw at Chilean solar-hybrid remote mine installations. |
Research Methodology
Multi-period observation of valve replacement cycle compression, tailings dam regulatory enforcement, and aftermarket service unbundling anchored the trend analysis, supplemented by interviews with maintenance directors at Australian iron ore ports, procurement leads at Chilean copper concentrators, foundry operations managers in India's Coimbatore belt, and aftermarket service heads at unbundled technology vendors. Secondary validation drew from EPA effluent limitation guidelines, ANM dam safety protocol filings, ECHA REACH substance documentation requirements, MEE tailings enforcement notices, customs trade data for hardened alloy castings, and SEC 10-K disclosures from diversified flow control conglomerates. Bottom-up segment sizing triangulated against top-down market consolidation estimates.
Segment-weighting across product type, material grade, connection format, and end-use vertical informed the analytical framework throughout the projection horizon. Modeled dimensions included ball versus butterfly versus gate valve configurations, cast iron versus stainless steel versus ceramic-lined material tiers, flanged versus welded versus threaded connection types, and mining versus wastewater versus chemical processing end-use splits. CAGRs derived from replacement cycle acceleration curves, regulatory compliance cost pass-through coefficients, and aftermarket service revenue migration patterns. Industry-specific forecast inputs incorporated HPAL circuit expansion timelines in Indonesia and nickel laterite processing capacity buildouts.
Caveats apply where LME nickel alloy price volatility, weld overlay technician retirement waves, or API 6D certification backlog extensions at notified bodies could materially shift the outlook. Deviation in China's MEE enforcement intensity or Brazil's ANM dam safety protocol implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Water Treatment Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
North America Industrial Water Treatment Market
Water & Sludge Treatment
Flocculants Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
Sludge Treatment and Disposal Equipment Market
Water & Sludge Treatment
Asia-Pacific Drilling Waste Management Services Market
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Global Municipal Water Treatment Chemicals Market
Water & Sludge Treatment
Salt Water Softeners Market
Water & Sludge Treatment
Electrodeionization (EDI) Technology Market
Water & Sludge Treatment
Global Naphthalene Water Reducers Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
US Sludge Management and Dewatering Market