
 Membrane Water Treatment Chemicals Market | 2026-2036
Membrane Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Membrane Water Treatment Chemicals Market Foresight
Industrial process-water buyers are redrawing procurement priorities as zero-liquid-discharge mandates tighten across manufacturing clusters. Kurita Water Industries Ltd leverages its Asia-Pacific manufacturing footprint to supply antiscalant formulations for semiconductor fabs and power plants. Veolia anchors European demand through integrated service contracts that bundle chemicals with membrane asset management. Evoqua Water Technologies LLC competes in North American municipal desalination through specialized membrane preservation chemistries.
Membrane water treatment chemicals comprise antiscalants, coagulants, disinfectants, and pH adjusters formulated to prevent fouling, scaling, and biological degradation of polymeric or ceramic membranes operating at pressures from 1 to 100 bar. These chemicals extend membrane lifespan, stabilize flux rates, and ensure permeate quality for downstream industrial or potable use. Antiscalants dominate value contribution due to high dosing rates in reverse osmosis desalination and brackish water systems where calcium sulfate and silica precipitation threaten membrane integrity. Disinfectants represent the fastest-growing product class as membrane bioreactor installations expand in wastewater reuse applications requiring continuous biofilm suppression. Process water applications command premium pricing because semiconductor and pharmaceutical end users demand certified chemistries that eliminate trace contamination risks.
EPA effluent guidelines under the Clean Water Act shape product formulation requirements for US discharge compliance, while REACH registrations and the EU Green Deal's water reuse targets drive substitution toward biodegradable antiscalant polymers in Europe. China's MEE enforces GB standards for industrial wastewater recycling that mandate membrane performance thresholds, directly linking chemical specification to operating permits. Stakeholders must monitor regulatory divergence between jurisdictions where chemical registration costs and biodegradability criteria increasingly determine market access and formulation R&D allocation.
Market Dynamics
Zero-liquid-discharge mandates are compressing procurement cycles for membrane water treatment chemicals as industrial buyers bundle antiscalants and biocides into long-term service contracts rather than spot chemical purchases.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Updated discharge standards under the Clean Water Act compel municipal utilities to expand membrane-based purification capacity, directly lifting chemical consumption for fouling control.
- Semiconductor fabrication:Advanced node chip manufacturing requires ultrapure process water with sub-ppt contamination thresholds, mandating certified antiscalant formulations at premium dosing rates.
- Desalination corridors:Coastal zones in Saudi Arabia, Australia, and China concentrate reverse osmosis deployment where silica and calcium sulfate scaling prevention drives systematic biocide and antiscalant procurement.
Market Restraints
- Phosphonate feedstock volatility:Antiscalant polymer production depends on phosphorous derivative supply chains concentrated in Chinese phosphate mining regions, exposing formulators to input cost swings.
- REACH registration burden:Biocide active substance authorization under EU BPR creates multi-year compliance timelines and six-figure dossier costs that filter smaller European chemical suppliers from membrane preservation markets.
- Thermal distillation resurgence:Multi-effect distillation systems compete for brine concentration applications in Middle Eastern power-cogeneration facilities, substituting membrane-based trains in high-salinity feedwater scenarios.
Strategic Opportunities
- Membrane bioreactor expansion:Wastewater reuse mandates in water-stressed Spanish and Italian municipalities accelerate MBR installations requiring continuous biofilm suppression through specialized oxidizing biocide programs.
- Green hydrogen electrolysis:PEM electrolyzer stacks demand ultrapure feedwater with conductivity below 0.1 µS/cm, opening specification-grade chemical channels for antiscalant suppliers serving renewable energy developers.
- Biodegradable polymer R&D:EU Green Deal water reuse targets and France's AGEC law incentivize substitution of conventional phosphonates with bio-based antiscalants that meet OECD 301B biodegradability thresholds.
Industry Challenges
- Membrane preservation chemistry certification:NSF/ANSI 60 and WRAS approvals for potable water applications require 12-18 month toxicology and extraction testing timelines that delay product commercialization.
- Cross-functional technical staffing:Formulation chemists with simultaneous expertise in polymer science, membrane fouling mechanisms, and regulatory toxicology remain scarce across European and North American operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membrane Water Treatment Chemicals Market |
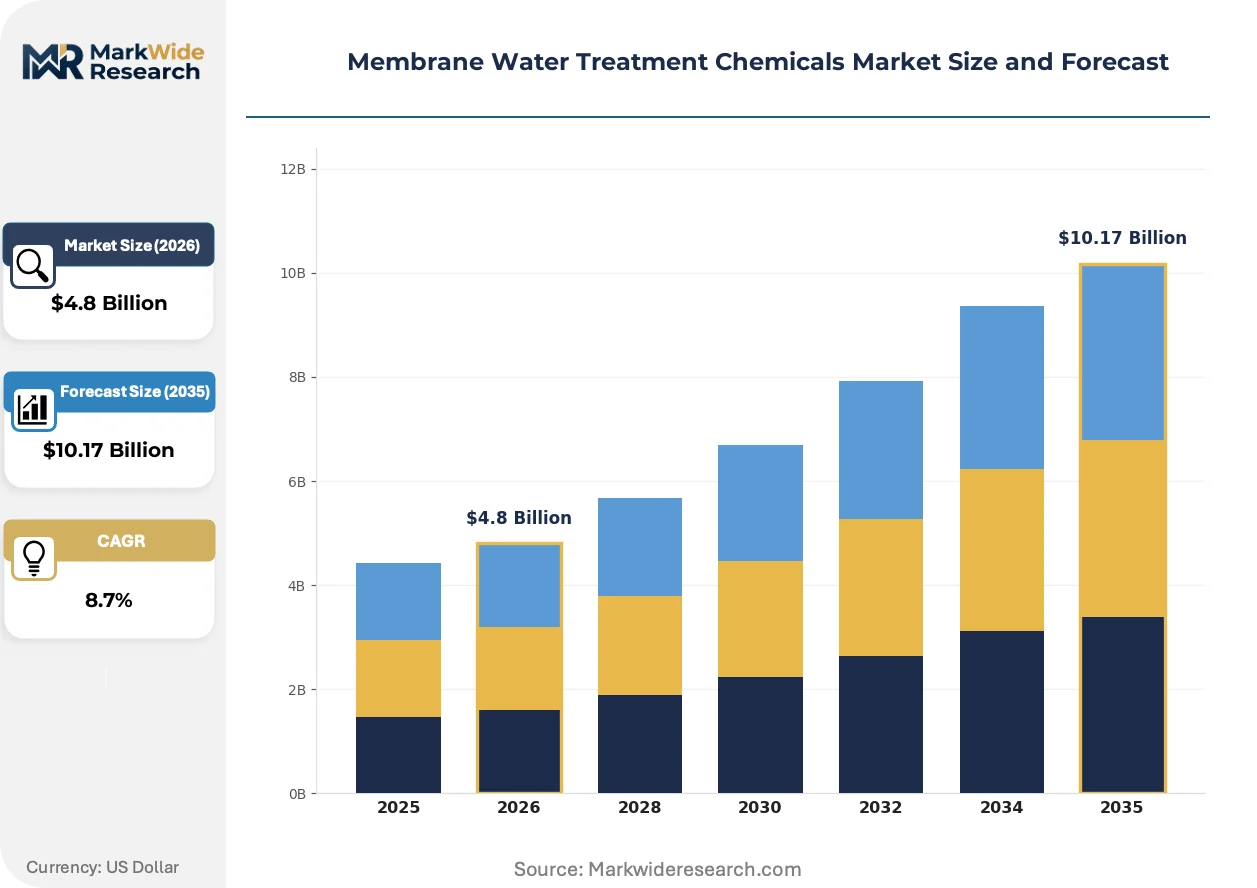
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiscalants, Coagulants, Disinfectants, pH Adjusters End User: Municipal, Industrial, Agricultural, Residential Application: Desalination, Wastewater Treatment, Drinking Water Treatment, Process Water Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Kurita Water Industries Ltd, GE Water Technologies Inc., Veolia, Hydrite Chemical Co., Genesys International Corporation Ltd., Solenis, Ecolab Inc., Evoqua Water Technologies LLC, SUEZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membrane Water Treatment Chemicals Market Shifts & Advancements
Polymeric membrane materials and dosing automation are compressing chemical consumption intensity while tightening performance specifications for fouling prevention across desalination and industrial reuse applications.
Silica-specific antiscalant polymers incorporating dendrimer architectures are decomposing traditional threshold inhibition approaches in high-recovery reverse osmosis plants. Saudi desalination operators and Australian mining utilities have adopted these formulations for brackish water systems exceeding 85% recovery ratios. The technology is decomposing market share concentration among conventional phosphonate suppliers by enabling chemical-free intervals that extend membrane cleaning cycles.
REACH restriction proposals targeting persistent phosphonates are accelerating substitution toward biodegradable polyacrylate alternatives in European membrane treatment facilities. ECHA's 2023-2024 dossier evaluations for tetraphosphonate compounds have triggered pre-registration of bio-based antiscalants by German and Dutch formulators. MBR installations in Netherlands municipal reuse plants represent the most affected segment, with operators now specifying OECD 301B-compliant chemistries in tender documents.
Integrated chemical-membrane service contracts are displacing standalone chemical procurement in North American power generation and semiconductor verticals. Veolia and Suez have consolidated antiscalant supply with membrane asset management under single-source agreements spanning 5-7 year terms. This bundling is most visible in Texas and Arizona data center cooling loops, where hyperscale operators prioritize uptime guarantees over unit chemical pricing.
Membrane Water Treatment Chemicals Market Segmentation
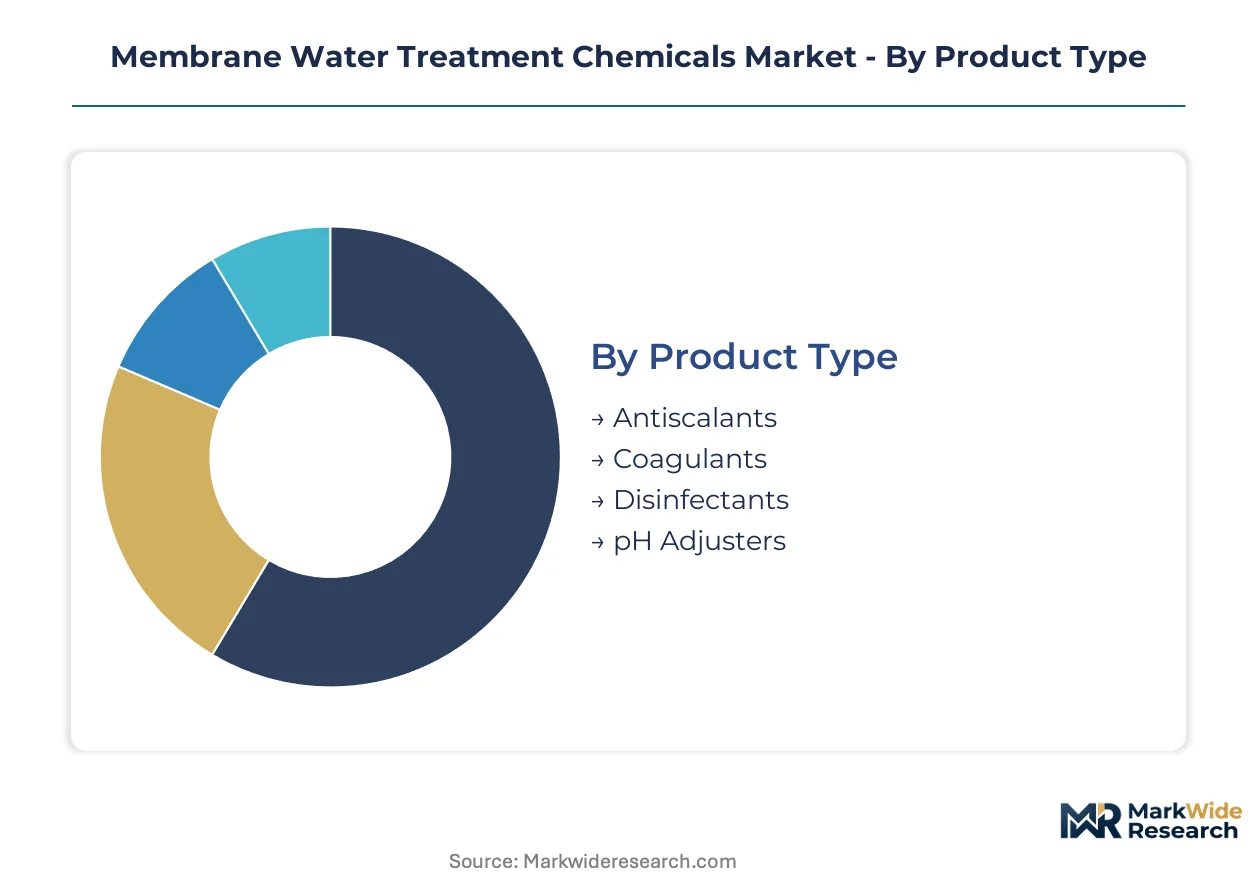
Membrane water treatment chemicals segment along four intersecting dimensions that determine formulation specifications, regulatory compliance burdens, and procurement channel selection. Chemical suppliers must align product portfolios with the divergent certification requirements and dosing protocols that separate municipal potable systems from semiconductor process water loops.
Product Type:
REACH registration tiers and EPA approval pathways create distinct competitive moats across chemical classes, with biocide authorization timelines stretching three to five years longer than antiscalant polymer registrations.
- Antiscalants:Phosphonate and polyacrylate polymers inhibit calcium sulfate, silica, and carbonate precipitation at threshold concentrations below stoichiometric levels. Saudi desalination operators and Australian mining utilities consume these formulations at premium dosing rates in high-recovery reverse osmosis trains exceeding 85% recovery ratios. Established volume favors antiscalants; emerging adoption favors disinfectants.
- Disinfectants:Oxidizing and non-oxidizing biocides suppress biofilm formation on polyamide membrane surfaces through continuous or intermittent dosing protocols. Membrane bioreactor installations in Spanish and Italian municipal reuse plants specify these chemistries for continuous biofilm suppression, with operators now mandating OECD 301B-compliant formulations in tender documents.
- Coagulants:Ferric chloride and aluminum sulfate formulations pretreat feedwater to reduce colloidal fouling of microfiltration and ultrafiltration membranes.
- pH Adjusters:Sulfuric acid and caustic soda solutions maintain optimal membrane surface charge and solubility indices across variable feedwater chemistries.
Antiscalants command the largest revenue share due to irreplaceable dosing in desalination corridors; disinfectants are climbing the fastest as MBR deployment accelerates.
End User:
Customer procurement sophistication spans three orders of magnitude, from residential point-of-use cartridge buyers to industrial zero-liquid-discharge engineering firms negotiating decade-long chemical service bundles.
- Municipal:Drinking water utilities and wastewater reclamation authorities operate membrane plants under EPA effluent limitation guidelines and China's GB standards for reclaimed water. These buyers prioritize NSF/ANSI 60 certified chemistries with 12-18 month toxicology and extraction testing timelines that delay product commercialization but secure long-term supply contracts.
- Industrial:Semiconductor fabs, power plants, and pharmaceutical manufacturers demand certified antiscalant formulations at premium dosing rates for ultrapure process water with sub-ppt contamination thresholds. Texas and Arizona data center cooling loops illustrate this segment's procurement evolution, where hyperscale operators prioritize uptime guarantees over unit chemical pricing through integrated chemical-membrane service contracts spanning 5-7 year terms.
- Agricultural:Drip irrigation and hydroponic operations deploy membrane filtration for dissolved solids reduction in groundwater and recycled agricultural runoff.
- Residential:Point-of-use reverse osmosis systems in water-stressed coastal China and Middle Eastern urban households drive cartridge-scale chemical consumption through replacement filter subscriptions.
Industrial buyers concentrate the highest margin capture; municipal utilities anchor the largest absolute volume.
Application:
Feedwater salinity and target permeate quality specifications fragment chemical formulation requirements across membrane process configurations operating at pressures from 1 to 100 bar.
- Desalination:Seawater and brackish water reverse osmosis systems in Saudi Arabia, Australia, and coastal China deploy antiscalants and biocides at systematic procurement rates to prevent silica and calcium sulfate scaling. Dendrimer-architecture silica-specific polymers are decomposing market share concentration among conventional phosphonate suppliers by enabling chemical-free intervals that extend membrane cleaning cycles.
- Process Water:Semiconductor fabrication and green hydrogen electrolysis demand ultrapure feedwater with conductivity below 0.1 µS/cm, opening specification-grade chemical channels for antiscalant suppliers serving renewable energy developers and advanced node chip manufacturers.
- Wastewater Treatment:Membrane bioreactor installations concentrate biological solids while producing reclaimed water for non-potable reuse applications.
- Drinking Water Treatment:Surface water and groundwater membrane filtration for potable supply requires pH adjusters and disinfectants meeting stringent extraction and toxicology protocols.
Desalination corridors concentrate antiscalant procurement density; process water commands the steepest premium tiering.
Distribution Channel:
Channel selection reflects buyer technical capability, with direct sales penetrating complex industrial applications while distributors serve fragmented municipal and agricultural accounts.
- Direct Sales:Integrated service contracts bundle antiscalant supply with membrane asset management under single-source agreements. Veolia and Suez have consolidated this channel in European power generation and North American semiconductor verticals, displacing standalone chemical procurement through uptime guarantees and predictive dosing automation.
- Distributors:Regional chemical distributors stock standardized antiscalant and pH adjuster formulations for municipal utilities and agricultural operators with predictable consumption patterns and limited in-house water chemistry expertise.
- Online Retail:E-commerce platforms serve residential point-of-use system owners through subscription cartridge replacement programs and bulk chemical concentrates for small-scale commercial membrane units.
- Others:Cooperative purchasing agreements and government procurement frameworks aggregate demand across multiple municipal utilities to secure volume pricing on certified chemistries.
Direct sales capture the highest service margin; distributors maintain the broadest geographic coverage footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Red Sea coast's desalination corridor underwrites Saudi Arabia's commanding position in membrane chemical procurement, while China's coastal industrial clusters anchor Asia-Pacific demand density.
Saudi Arabia
Seawater reverse osmosis plants at Ras Al-Khair and Jubail Industrial City consume antiscalant formulations at systematic rates to combat silica scaling in high-recovery trains. The Saline Water Conversion Corporation's capacity expansion targets align with SFDA chemical registration requirements for potable water applications. NEOM's zero-liquid-discharge industrial zone is piloting dendrimer-architecture polymers to extend membrane cleaning intervals beyond conventional phosphonate limits.
China
Coastal membrane installations in Qingdao and Tianjin deploy biocide programs for brackish water desalination serving petrochemical complexes. MEE enforcement of GB standards for industrial wastewater recycling mandates membrane performance thresholds that directly link chemical specifications to operating permits. Yangtze River Delta semiconductor fabs are procuring certified antiscalants at premium dosing rates for sub-ppt ultrapure process water.
United States
Texas and Arizona data center cooling loops are bundling antiscalant supply into 5-7 year integrated service contracts prioritizing uptime guarantees. EPA effluent limitation guidelines under the Clean Water Act compel municipal utilities in California and Florida to expand membrane-based purification capacity. Permian Basin produced water treatment facilities are adopting specialized membrane preservation chemistries for high-TDS brine management.
Germany
Ruhr Valley municipal reuse plants are specifying OECD 301B-compliant biocides in tender documents following ECHA's tetraphosphonate dossier evaluations. REACH registration burdens for biocide active substances filter smaller suppliers from membrane preservation markets. Bavarian semiconductor fabrication facilities anchor premium-tier chemical demand for ultrapure water systems serving automotive chip manufacturing.
Australia
Mining utilities in Western Australia's Pilbara region deploy silica-specific antiscalants in brackish water systems exceeding 85% recovery ratios. The country's national water regulator enforces discharge standards that accelerate membrane bioreactor adoption in Perth's municipal reuse infrastructure. Victorian desalination operators at the Wonthaggi plant are testing chemical-free intervals enabled by dendrimer polymer architectures.
Membrane Water Treatment Chemicals Market Competitive Landscape
Concentration sits with integrated water service providers that bundle chemical supply with membrane asset management under long-term contracts. The vendor base stratifies across three tiers: multinational environmental service conglomerates, regional specialty chemical formulators, and equipment-integrated chemical suppliers. Dominant competitive moves include geographic expansion through acquisition and backward integration into phosphonate feedstock production.
Within the integrated service tier, Veolia and SUEZ exemplify the contract-bundling model that displaces standalone chemical procurement in European power generation and North American industrial verticals. Kurita Water Industries Ltd occupies a position among Asia-Pacific formulators leveraging regional manufacturing proximity to semiconductor and power plant clusters. Evoqua Water Technologies LLC represents the specialized preservation chemistry vector competing in municipal desalination markets.
| Leading Market Players |
|---|
| Kurita Water Industries Ltd |
| GE Water Technologies Inc. |
| Veolia |
| Hydrite Chemical Co. |
| Genesys International Corporation Ltd. |
| Solenis |
| Ecolab Inc. |
| Evoqua Water Technologies LLC |
| SUEZ |
| Others |
Supply & Pricing Matrix
Ninety-day phosphonate inventory buffers in European antiscalant formulators compress procurement leverage during phosphate feedstock price spikes. This lead-time exposure concentrates pricing power with Chinese phosphate mining conglomerates while forcing membrane chemical buyers into long-term offtake contracts that lock in volume-discount tiering.
Pricing Analysis
Volume-discount tiering separates semiconductor-grade certified formulations from municipal-standard and economy bulk deliveries. Premium-mid-economy pricing differentiation rests on NSF/ANSI 60 certification status and REACH registration completeness, with Texas data center operators least sensitive to unit pricing due to uptime guarantee requirements. Cost compression in municipal tenders is intensifying because Chinese phosphate export quotas tighten raw material availability.
Supply Chain Analysis
Strait of Hormuz transit underwrites phosphonate feedstock flows to Saudi desalination corridors, creating single-source vulnerability for antiscalant polymer production. Manufacturing gravity centers on China, Germany, and the United States, with phosphorous derivative supply chains drawing from Moroccan and Chinese phosphate rock deposits. Distribution runs through integrated service contracts in industrial verticals and regional chemical distributors for fragmented municipal accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane water treatment chemicals sit in early-cycle expansion as zero-liquid-discharge mandates penetrate manufacturing clusters beyond pioneer adopters in semiconductors and power generation.
For Market Incumbents: Compound service contract penetration by bundling predictive dosing automation with membrane asset management in North American data center cooling loops. Backward integration into phosphonate feedstock production defends margin position against Chinese phosphate quota volatility. Prioritize OECD 301B biodegradable polymer R&D to preempt REACH restriction timelines on persistent phosphonates. For New Entrants and Emerging Players: NSF/ANSI 60 certification fast-track opens municipal potable water procurement channels currently filtered by 12-18 month toxicology testing barriers. Spanish and Italian membrane bioreactor installations represent the most penetrable white-space segment, with operators mandating bio-based biocide formulations in tender documents. Pursue direct sales partnerships with regional membrane OEMs to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biodegradable antiscalant polymer manufacturing as EU Green Deal compliance requires dedicated bio-based production lines. Five-to-ten year viability favors formulators with captive phosphonate supply or certified biodegradable alternatives already commercialized. Monitor ECHA dossier evaluation timelines for tetraphosphonate compounds as the signal to watch for substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Feedstock | Captive phosphonate supply insulates margin structure against Chinese export quota volatility. |
| Biodegradable Polymer R&D Program | OECD 301B-compliant antiscalants preempt REACH restriction proposals targeting persistent phosphonates. |
| Integrated Service Contract Expansion | Veolia-style bundling of chemicals with membrane asset management locks in 5-7 year revenue visibility. |
| Certification Fast-Track Investment | NSF/ANSI 60 and WRAS approvals unlock municipal potable water procurement with defensible switching costs. |
| Membrane Bioreactor Biocide Specialization | Spanish and Italian wastewater reuse mandates create specification-grade demand for continuous biofilm suppression chemistries. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with membrane plant operators, procurement leads at semiconductor fabs, technical R&D directors at chemical formulators, and regulatory affairs specialists; and secondary validation through EPA effluent guideline filings, ECHA registration dossiers, customs trade data on phosphonate imports, and SEC disclosures from integrated water service providers. Bottom-up chemical consumption modeling triangulated against top-down membrane installation capacity projections.
Across the analysis window, forecasts segment by product class, end-use vertical, application pressure regime, and geographic regulatory cluster. CAGRs derive from membrane capacity build-out trajectories, chemical dosing intensity benchmarks per recovery ratio tier, and substitution elasticity between phosphonate and polyacrylate formulations. Specific inputs include SFDA chemical registration timelines for Saudi potable projects and MEE enforcement patterns for Chinese industrial wastewater recycling permits.
Underlying assumptions cover stable phosphate feedstock availability, REACH registration continuity, and membrane bioreactor adoption rates in Mediterranean municipalities, with deviation risk concentrated in Chinese phosphate export policy shifts and ECHA restriction proposal acceleration. Practitioners should keep alternative scenarios live as regulatory divergence between EU biodegradability mandates and US EPA discharge guidelines evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Asia-Pacific Water Free/ Waterless Urinals Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
North America Water Treatment Chemicals Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Global Flocculant and Coagulant Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Anionic Flocculants Market
Water & Sludge Treatment
Water Dispersible Granules Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
Ballast Water Treatment Market
Water & Sludge Treatment
Ultrapure Water Market
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Water and Wastewater Treatment Technologies Market
Water & Sludge Treatment
Europe Membrane Water and Wastewater Treatment (WWT) Market