
 Europe Activated Carbon Market | 2026-2036
Europe Activated Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Activated Carbon Market Foresight
Modular containerized filtration units is pivoting procurement patterns across European water authorities. Desotec leverages its mobile carbon exchange service to capture municipal retrofit contracts without requiring permanent infrastructure investment. Jacobi Carbons Group anchors its position through backward integration into coconut shell sourcing in Southeast Asian supply chains. CarboTech competes on specialty chemically activated grades for pharmaceutical solvent recovery applications.
Activated carbon consists of porous carbonaceous material processed to develop extensive internal surface area, typically ranging from 500 to 1,500 square meters per gram, engineered for adsorption of organic compounds, color bodies, and trace contaminants across liquid and gas phase systems. Powdered activated carbon dominates drinking water treatment volumes due to low capital entry and dosing flexibility, while granular activated carbon commands premium replacement cycles in fixed-bed industrial installations where thermal reactivation economics favor longer service life. Extruded activated carbon occupies narrower demand in specialized gas-phase applications where low pressure drop and mechanical integrity override surface area metrics.
REACH registration requirements under ECHA mandate comprehensive substance characterization for activated carbon imports, while the EU Drinking Water Directive enforces parametric standards that directly specify adsorption performance for pesticide and pharmaceutical residue removal. Germany's Federal Environment Agency and France's ANSM both reference EN 12915 testing protocols for activated carbon used in potable water contact. Stakeholders must track the EU Green Deal's emerging carbon border adjustment mechanisms and their potential restructuring of virgin versus reactivated carbon cost economics.
Market Dynamics
The Rhine-Ruhr industrial corridor is driving demand concentration as German municipal utilities accelerate granular activated carbon upgrades for pharmaceutical micropollutant removal, tightening supplier qualification requirements across the value chain.
Growth Catalysts
- EU Drinking Water Directive revisions:The updated parametric standards for pesticide and pharmaceutical residue removal mandate enhanced adsorption performance, forcing municipal procurement toward certified activated carbon grades.
- REACH registration protocols:ECHA's comprehensive substance characterization requirements for imports are filtering out uncertified suppliers and consolidating qualified vendor pools.
- Rhine-Ruhr municipal clustering:Water treatment utilities across Germany's industrial heartland are synchronizing system upgrades, creating concentrated demand windows for specialized carbon suppliers.
Market Restraints
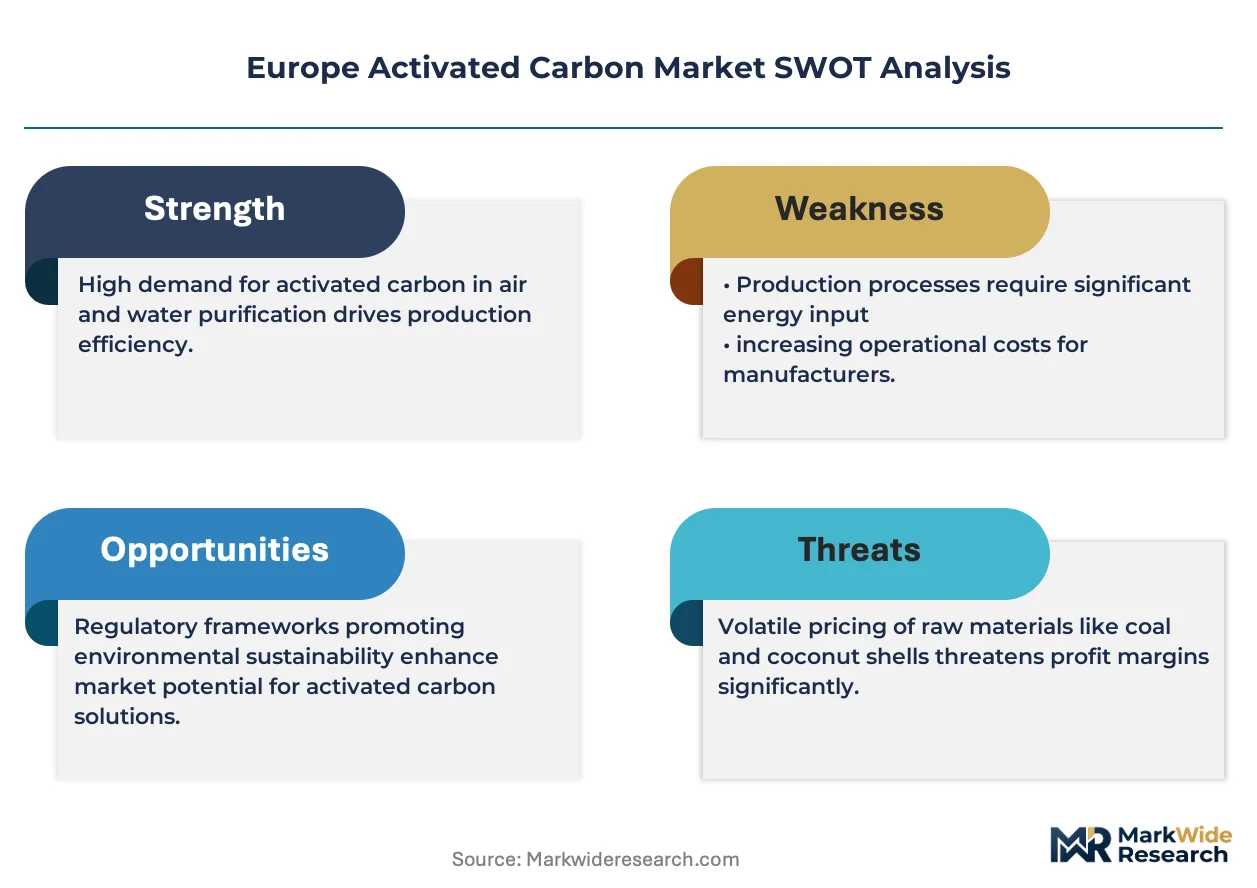
- Coconut shell supply volatility:Southeast Asian sourcing concentration exposes European processors to weather-driven raw material disruptions and freight cost swings.
- Thermal reactivation capex barriers:The capital intensity of on-site regeneration facilities limits municipal adoption, perpetuating virgin carbon dependence.
- EN 12915 testing bottlenecks:France's ANSM and Germany's Federal Environment Agency both reference this protocol, creating certification backlogs for new market entrants.
Strategic Opportunities
- Polish municipal water infrastructure:Underpenetrated treatment capacity in Eastern European member states offers expansion terrain for mobile carbon exchange services.
- EU Green Deal carbon border adjustments:Emerging mechanisms will restructure cost economics to favor reactivated over virgin carbon, rewarding circular business models.
- Containerized filtration convergence:Modular units combined with predictive monitoring enable water authorities to bypass permanent infrastructure commitments.
Industry Challenges
- Reactivation technician scarcity:The specialized skill set for thermal regeneration operations is concentrated among aging workforces in Germany and the Netherlands.
- Legacy fixed-bed integration:Municipal utilities struggle to retrofit existing infrastructure with advanced dosing and monitoring systems without service disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Activated Carbon Market |
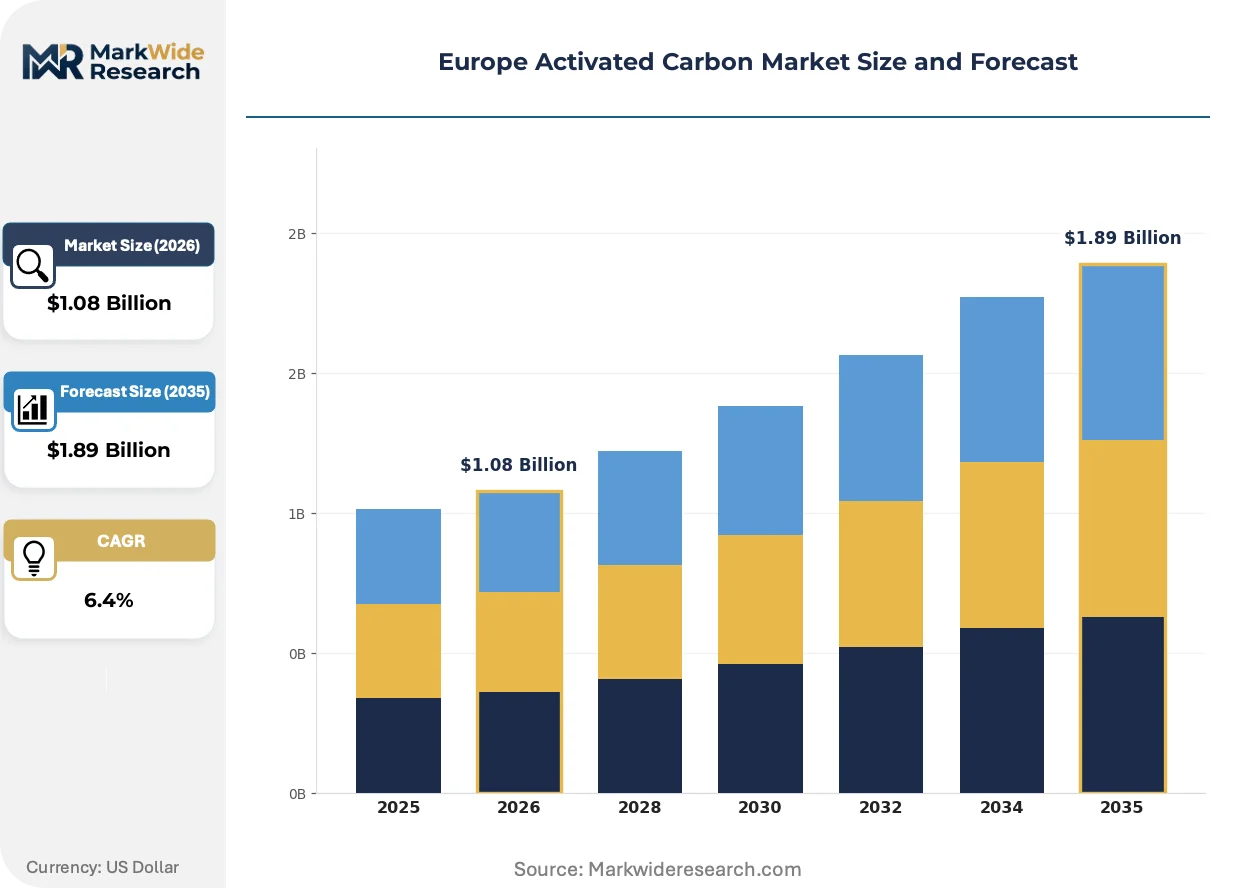
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Activated Carbon, Granular Activated Carbon, Extruded Activated Carbon, Carbon Cloth Application: Water Treatment, Air Purification, Industrial Processing, Food & Beverage End User: Municipalities, Chemical Industry, Pharmaceutical Manufacturers, Food Producers Distribution Channel: Online Sales, Distributors, Retail, Direct Sales |
| Companies Covered | Desotec, Donau Carbon GmbH, Jacobi Carbons Group, Calgon Carbon Corporation, Cabot Corporation, CarboTech, Chemviron, CPL Activated Carbons, Kuraray Europe GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Activated Carbon Market Shifts & Advancements
Containerized mobile carbon exchange services are compressing procurement cycles and displacing permanent infrastructure investments across European water authorities.
Modular containerized filtration is decentralizing activated carbon deployment by enabling utilities to lease capacity rather than own assets. German municipal operators are adopting these units fastest, driven by budget constraints and flexibility mandates. This architecture is decentralizing supplier relationships away from long-term fixed-bed contracts toward service-based arrangements with shorter renewal cycles.
REACH registration requirements under ECHA now mandate full substance characterization for all activated carbon imports into the European Economic Area. Industrial consequence includes elevated compliance costs that disproportionately burden smaller traders and distributors. Powdered activated carbon segments are responding fastest, consolidating procurement toward vertically integrated manufacturers with in-house regulatory capabilities.
Performance-based service contracts are displacing traditional tonnage-based purchasing across French and Belgian water utilities. The segment being disrupted is spot-market carbon trading, replaced by multi-year agreements tying supplier payments to contaminant removal guarantees. This shift is most visible in pharmaceutical manufacturing clusters where discharge permits carry strict micropollutant limits.
Europe Activated Carbon Market Segmentation
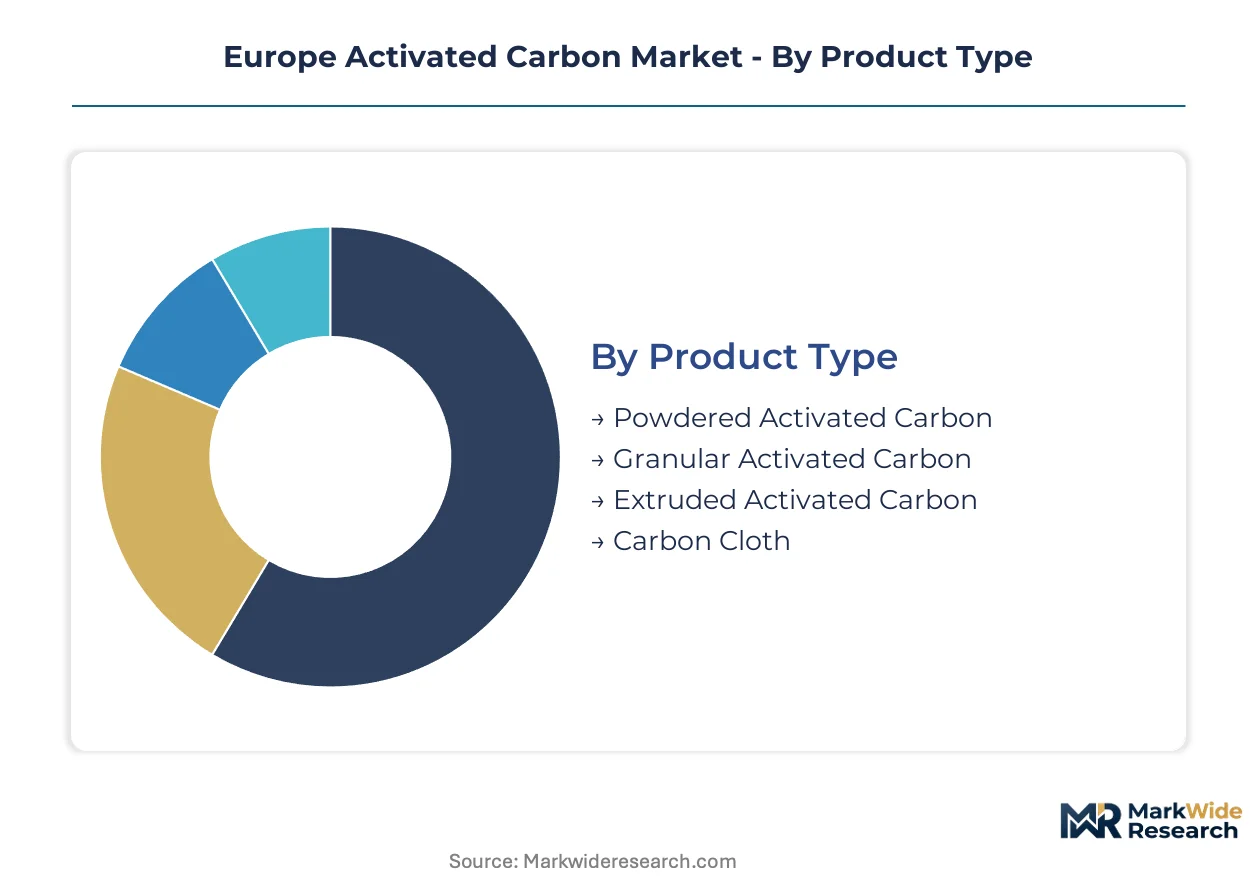
Activated carbon procurement in Europe fragments across technical specifications, regulatory compliance tiers, and service delivery models. Buyers prioritize adsorption performance metrics, reactivation economics, and REACH certification status when selecting grades.
Product Type:
Municipal utilities weigh capital expenditure against operational flexibility when selecting between dosing formats and fixed-bed configurations.
- Powdered Activated Carbon:Finely ground particles with high surface area enable rapid adsorption kinetics in batch treatment processes. German drinking water utilities favor this format for seasonal pesticide spikes, accepting higher dosing labor costs in exchange for minimal infrastructure investment.
- Granular Activated Carbon:Hard, durable particles engineered for fixed-bed column operation with thermal reactivation cycles. The Rhine-Ruhr corridor concentrates demand here as utilities upgrade permanent installations for pharmaceutical micropollutant compliance under revised EU Drinking Water Directive standards.
- Extruded Activated Carbon:Cylindrical pellets optimized for gas-phase applications requiring low pressure drop. Industrial solvent recovery units in Belgium and the Netherlands specify these grades for volatile organic compound capture.
- Carbon Cloth:Woven activated carbon textiles offering uniform porosity and structural flexibility. Specialized applications in protective equipment and precision filtration command premium pricing.
Volume sits with powdered grades in seasonal dosing applications; growth tilts toward granular formats in permanent municipal infrastructure.
Application:
Regulatory stringency varies by end-use, concentrating supplier qualification efforts toward potable water contact certifications.
- Water Treatment:The largest application by tonnage, spanning municipal drinking water, wastewater discharge compliance, and groundwater remediation. France's ANSM and Germany's Federal Environment Agency enforce EN 12915 testing protocols, filtering supplier pools.
- Air Purification:Industrial emissions control and indoor air quality systems drive demand for specialized gas-phase carbons. F-Gas Regulation compliance in the EU accelerates replacement of older adsorbent technologies.
- Industrial Processing:Solvent recovery, catalyst support, and chemical purification operations. Pharmaceutical manufacturers in Switzerland and Ireland specify chemically activated grades for high-purity solvent regeneration.
- Food & Beverage:Decolorization and deodorization in sugar refining, edible oil processing, and alcoholic beverage production. EFSA food contact material regulations govern supplier selection.
Water treatment commands the installed base; industrial processing offers the steepest expansion trajectory as pharmaceutical discharge limits tighten.
End User:
Procurement sophistication diverges sharply between public-sector tendering and private-sector performance contracting.
- Municipalities:Public water utilities across Germany, France, and Benelux operate under budget-constrained capital programs. Containerized carbon exchange services are compressing procurement cycles here.
- Chemical Industry:Petrochemical and specialty chemical producers specify activated carbon for process purification and emission control. REACH registration requirements under ECHA mandate comprehensive substance characterization from suppliers.
- Pharmaceutical Manufacturers:Stringent micropollutant discharge permits drive demand for certified grades with documented trace contaminant removal performance. Performance-based service contracts are displacing tonnage-based purchasing.
- Food Producers:Sugar refineries and edible oil processors prioritize color body adsorption capacity and food-grade certification status.
Municipalities anchor volume demand; pharmaceutical manufacturers are gaining share fastest through micropollutant compliance investments.
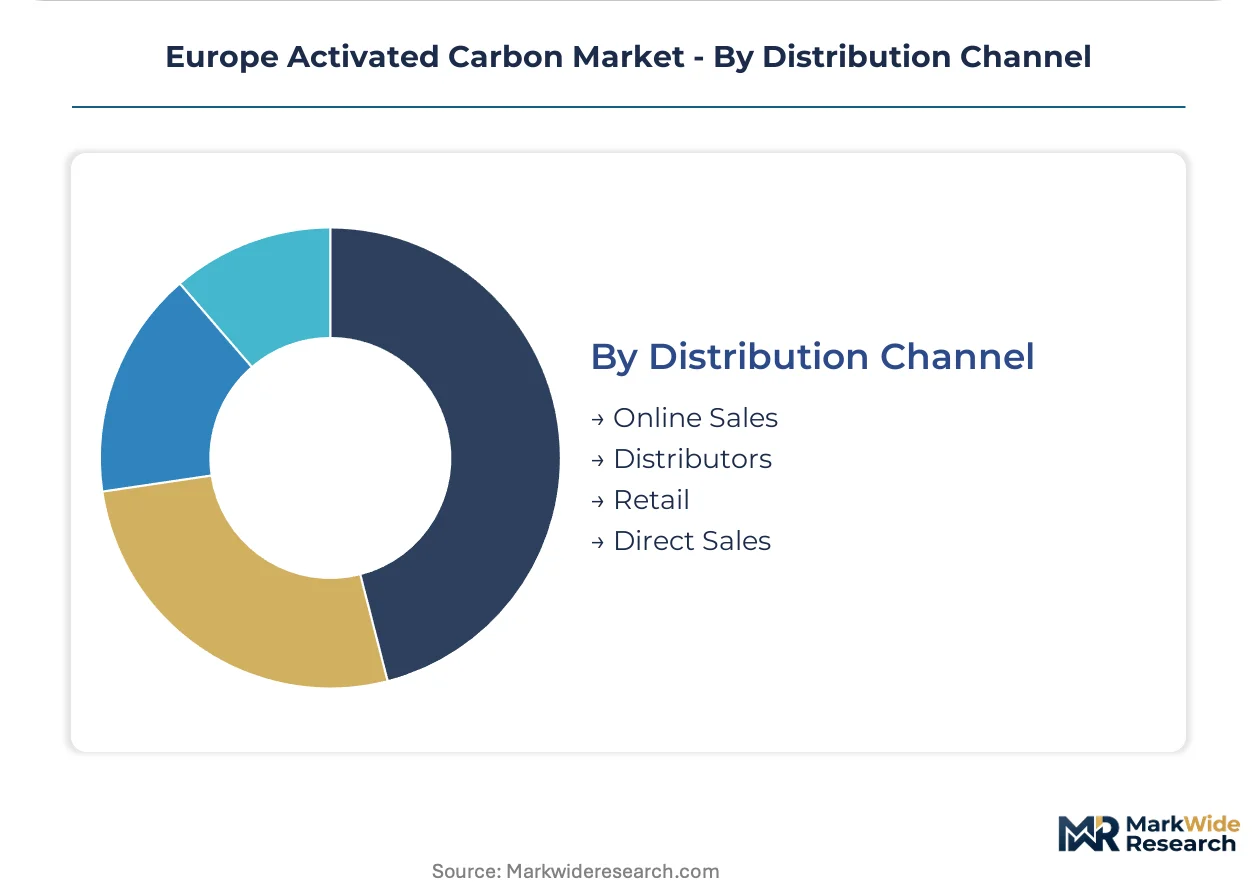
Distribution Channel:
Supply chain configuration reflects customer scale, technical service requirements, and regulatory documentation burdens.
- Direct Sales:Large municipal utilities and industrial accounts contract directly with manufacturers for multi-year supply agreements. REACH documentation and reactivation services bundle here.
- Distributors:Regional stockists serve mid-scale water treatment operators and food processors requiring technical support and just-in-time delivery.
- Online Sales:Standardized grades for laboratory, aquarium, and small-scale industrial applications. Limited to non-critical specifications lacking regulatory filing requirements.
- Retail:Consumer water filtration cartridges and air purifier replacement elements. Big-box and specialty channels in urban centers.
Direct sales capture the municipal and industrial core; distributor networks are expanding most quickly in Eastern European member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European activated carbon consumption outpaces regional production capacity, forcing dependence on Southeast Asian coconut shell imports and German thermal reactivation services. The Rhine-Ruhr corridor concentrates demand for pharmaceutical micropollutant removal, while regulatory divergence between member states shapes supplier qualification requirements.
Germany
Municipal utilities across the Rhine-Ruhr industrial belt are retrofitting granular activated carbon systems for pharmaceutical residue compliance. The Federal Environment Agency enforces EN 12915 testing protocols for all potable water contact applications. Düsseldorf and Essen cluster the densest concentration of fixed-bed upgrade projects, with containerized exchange services compressing procurement timelines.
France
ANSM tightened purity requirements for drinking water treatment carbons under revised EU Drinking Water Directive transpositions. Performance-based service contracts are displacing tonnage-based purchasing across Parisian and Lyonnaise water authorities. The Île-de-France region anchors demand for specialized grades serving pharmaceutical manufacturing discharge permits.
Netherlands
Rotterdam's port infrastructure handles the majority of European coconut shell activated carbon imports before inland distribution. REACH registration requirements under ECHA filter supplier pools toward vertically integrated manufacturers with regulatory filing capabilities. The Randstad region concentrates reactivation facility investments serving Benelux industrial solvent recovery demand.
Belgium
Flemish chemical manufacturers specify extruded activated carbon grades for volatile organic compound capture under F-Gas Regulation compliance deadlines. Antwerp's petrochemical cluster drives demand for high-purity solvent regeneration applications. Walloon municipalities lag in granular carbon adoption, creating service gaps for mobile exchange providers.
Poland
Underpenetrated municipal water infrastructure in Eastern European member states offers expansion terrain for carbon exchange services bypassing capital-intensive fixed-bed investments. National regulators are harmonizing testing protocols with EN 12915 ahead of full EU Drinking Water Directive implementation. Warsaw and Kraków concentrate early upgrade pilot programs.
Europe Activated Carbon Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers, creating a tiered structure where regulatory filing capabilities separate qualified vendors from commodity traders. Three archetypes dominate: vertically integrated manufacturers controlling Southeast Asian raw material sourcing, regional reactivation service operators with mobile exchange fleets, and specialty chemical activation houses serving pharmaceutical purity requirements. Consolidation pressure concentrates among distributors lacking REACH documentation capabilities, while capacity expansion concentrates in thermal reactivation facilities along the Rhine corridor.
Within the European specialist tier, Desotec anchors mobile carbon exchange service provision, Jacobi Carbons Group exemplifies backward integration into coconut shell supply chains, and CarboTech occupies a position in chemically activated specialty grades. These three represent distinct competitive vectors—service-based asset-light models, upstream raw material control, and high-purity process technology—rather than overlapping positioning. Each archetype captures different municipal procurement preferences: flexibility mandates favor exchange services, long-term supply security favors integrated sourcing, and micropollutant compliance favors specialty activation protocols.
| Leading Market Players |
|---|
| Desotec |
| Donau Carbon GmbH |
| Jacobi Carbons Group |
| Calgon Carbon Corporation |
| Cabot Corporation |
| CarboTech |
| Chemviron |
| CPL Activated Carbons |
| Kuraray Europe GmbH |
| Others |
Supply & Pricing Matrix
Municipal water utilities across the Rhine-Ruhr corridor concentrate procurement power through synchronized upgrade programs, forcing suppliers toward long-term contract-based pricing with embedded reactivation service bundles rather than spot-market transactions.
Pricing Analysis
Cost compression in standard powdered grades accelerates as REACH registration requirements under ECHA filter out uncertified traders, consolidating procurement toward vertically integrated manufacturers with in-house regulatory filing capabilities. Three-tier pricing structure across pharmaceutical-grade, potable water-certified, and industrial-standard levels separates suppliers by EN 12915 compliance status and thermal reactivation service bundling. Municipal utilities exhibit the highest price sensitivity due to budget-constrained capital programs, while pharmaceutical manufacturers accept premium positioning for documented micropollutant removal performance.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Antwerp handle inbound coconut shell activated carbon from Southeast Asian production hubs before hub-and-spoke inland distribution across the Benelux and German industrial corridors. European supply draws from Indonesian and Philippine coconut shell char sources, German thermal reactivation facility capacity, and specialty chemical activation houses in Belgium. Single-source vulnerability concentrates in Southeast Asian raw material exposure to weather-driven disruptions. Distribution runs through direct manufacturer relationships for large municipal accounts, with distributor networks serving mid-scale operators in Eastern European member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where REACH registration protocols under ECHA construct formidable barrier-to-entry moats, rewarding incumbent manufacturers with captive regulatory filing capabilities and filtering out commodity traders lacking substance characterization documentation.
For Market Incumbents: Anchor market position through backward integration into coconut shell sourcing partnerships in Southeast Asia, securing raw material continuity against weather-driven supply disruptions. Expand thermal reactivation facility capacity along the Rhine corridor to capture circular economy premiums under emerging EU Green Deal carbon border adjustment mechanisms. Defensive priority centers on mobile carbon exchange fleet scaling to preempt containerized filtration adoption by municipal utilities seeking asset-light procurement models.
For New Entrants and Emerging Players: The EU Drinking Water Directive revisions in Germany and France open a window for specialized certification consultancies bridging EN 12915 compliance gaps for smaller municipal utilities lacking technical procurement expertise. White-space targets concentrate in Polish and Romanian municipal infrastructure, where underpenetrated treatment capacity and harmonizing regulatory frameworks create first-mover terrain for mobile exchange services bypassing capital-intensive fixed-bed investments. Go-to-market execution should prioritize performance-based service contracts with contaminant removal guarantees rather than tonnage-based commodity positioning.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with captive Southeast Asian raw material sourcing and in-house REACH documentation capabilities, positioned for sustained competitive advantage across the medium-term regulatory tightening cycle. Acquisition target archetype encompasses regional reactivation service operators with established mobile exchange fleets and EN 12915 certification track records in the Benelux corridor. Signal to monitor: acceleration of EU Green Deal carbon border adjustment implementation timelines, which would structurally revalue reactivated carbon economics against virgin material alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coconut Shell Sourcing | Secures raw material continuity against Southeast Asian weather disruptions and freight volatility. |
| Thermal Reactivation Facility Expansion | Captures circular economy premiums under EU Green Deal carbon border adjustment mechanisms. |
| Mobile Carbon Exchange Fleet Scaling | Preempts municipal shift toward containerized filtration and asset-light procurement models. |
| EN 12915 Certification Investment | Unlocks potable water contact applications in Germany and France under tightened directive standards. |
| Performance-Based Service Contract Transition | Aligns supplier economics with contaminant removal outcomes, displacing spot-market commodity trading. |
Research Methodology
Multi-period observation of municipal procurement patterns, REACH registration filing volumes, and thermal reactivation facility utilization rates anchored the trend analysis, supplemented by interviews with plant managers at German water utilities, procurement leads at pharmaceutical manufacturers, technical R&D directors at carbon processors, and distribution channel partners across the Benelux corridor. Secondary validation drew from ECHA substance registration databases, EU Drinking Water Directive implementation transpositions, customs trade data for coconut shell char imports, and SEC filings of publicly traded carbon manufacturers. Bottom-up volume modeling across granular, powdered, and extruded product grades triangulated against top-down market sizing from regional production capacity assessments.
Input-output matrices mapped activated carbon demand across water treatment, air purification, industrial processing, and food and beverage applications, with segmentation dimensions spanning product type, certification tier, end-use vertical, and service delivery model. CAGRs were derived from regression analysis of historical procurement volumes against regulatory implementation timelines and infrastructure investment cycles. Forecast inputs incorporated EU Green Deal policy development trajectories, municipal budget allocation patterns for pharmaceutical micropollutant compliance, and Southeast Asian coconut shell harvest yield projections.
The model assumes a particular technology adoption path favoring granular activated carbon in fixed-bed municipal installations; alternative pathways accelerating powdered carbon seasonal dosing or extruded carbon gas-phase applications would alter the outlook for supplier qualification requirements and reactivation service demand. Forecasts reflect documented assumptions regarding regulatory implementation pacing, raw material supply continuity, and infrastructure investment cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Homopolymer Acrylic Filter Bags Market
Filters
Single-Use Filtration Assemblies Market
Filters
Global Filter Market
Filters
Drum Filters Market
Filters
Global Liquid Filtration Market
Filters
Global Industrial Filters Market
Filters
Europe Industrial Air Filtration Market
Filters
GCC Industrial Air Filtration Market
Filters
Global Gas Phase Filtration Market
Filters
Color Filter Glass Market
Filters
Filter Paper Market
Filters
Filtering Centrifuges Market
Filters
Respirator Cartridges and Filters Market
Filters
Filtration and Separation Market
Filters
Global Baghouse Filters Market
Filters
Anti-Microbial Filter Market