
 CMP Slurry Blend and Delivery Systems Market | 2026-2036
CMP Slurry Blend and Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
CMP Slurry Blend and Delivery Systems Market Insights
Transition to single-wafer processing with point-of-use blending is rewriting how CMP slurry reaches the polishing pad, replacing centralized mixing with modular, recipe-driven delivery architectures. Entegris leverages its fluid handling portfolio to anchor positions in high-purity distribution. Fujifilm Corporation sustains R&D intensity in colloidal silica formulations for sub-3nm nodes. DuPont de Nemours competes through specialized abrasives chemistry integrated with delivery system design.
CMP slurry blend and delivery systems encompass the equipment and infrastructure that meter, mix, and transport chemical-mechanical planarization slurries to semiconductor polishing tools, typically operating at flow rates of 1–10 liters per minute with particle size distributions controlled below 100 nanometers to prevent microscratch defects on silicon wafers. Their primary industrial purpose is to maintain consistent removal rates and planarization uniformity across dielectric, metal, and barrier film stacks in integrated circuit manufacturing. Pre-mixed slurries still occupy the largest volume share due to simplicity, yet on-site blending systems are capturing margin pools as foundries seek to reduce waste and customize oxide-to-metal ratios per process step. Among end users, semiconductor manufacturers dominate absolute demand while research labs represent the fastest-growing segment for pilot-line prototyping of advanced packaging schemes.
EPA regulations on per- and polyfluoroalkyl substance discharge constrain formulation choices for slurry additives, while ISO 14644 cleanroom standards govern particle contamination limits in delivery hardware fabrication. Taiwan's Industrial Development Bureau enforces local content requirements that shape procurement patterns for new 2nm fabs. Buyers must weigh capital intensity against operational flexibility as recipe complexity multiplies with gate-all-around transistor architectures.
Market Dynamics
Gate-all-around transistor architectures at sub-3nm nodes are fragmenting slurry recipes into process-specific formulations, forcing foundries to abandon centralized batch mixing in favor of modular point-of-use blending architectures that can switch oxide-to-metal ratios within minutes.
Growth Catalysts
- EU Chips Act localization mandates:Procurement rules now require domestic sourcing percentages for critical fab equipment, accelerating qualification of regional slurry delivery system suppliers.
- Advanced packaging proliferation:3D-IC and chiplet integration schemes multiply CMP steps per wafer, expanding installed base of polish tools and associated slurry infrastructure.
- Hsinchu Science Park cluster expansion:TSMC supplier ecosystem concentration creates demand density that justifies dedicated blending facilities co-located with leading-edge fabs.
Market Restraints
- Colloidal silica supply concentration:High-purity abrasive feedstock production clusters in East Asia, exposing buyers to geographic supply disruption risk.
- EPA PFAS discharge constraints:Per- and polyfluoroalkyl substance regulations limit formulation flexibility for surfactant additives, complicating recipe development.
- Sub-50nm particle filtration costs:Membrane technology capable of removing oversized abrasives without shearing particles commands premium pricing that elevates system capex.
Strategic Opportunities
- Research lab pilot-line prototyping:Advanced packaging development centers represent underpenetrated demand for flexible, small-batch blending systems.
- On-site slurry recycling integration:Waste minimization mandates from Taiwan's Industrial Development Bureau create pull for closed-loop delivery architectures.
- Silicon carbide wafer polishing:Power semiconductor substrate planarization requirements diverge from silicon CMP, opening specialized formulation and delivery design windows.
Industry Challenges
- Cleanroom-qualified technician scarcity:ISO 14644 compliance expertise for installation and maintenance of high-purity distribution hardware remains concentrated among limited service providers.
- Recipe validation timeline compression:Node transition acceleration from 5nm to 3nm to 2nm shrinks qualification windows for new slurry blends and associated delivery parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CMP Slurry Blend and Delivery Systems Market |
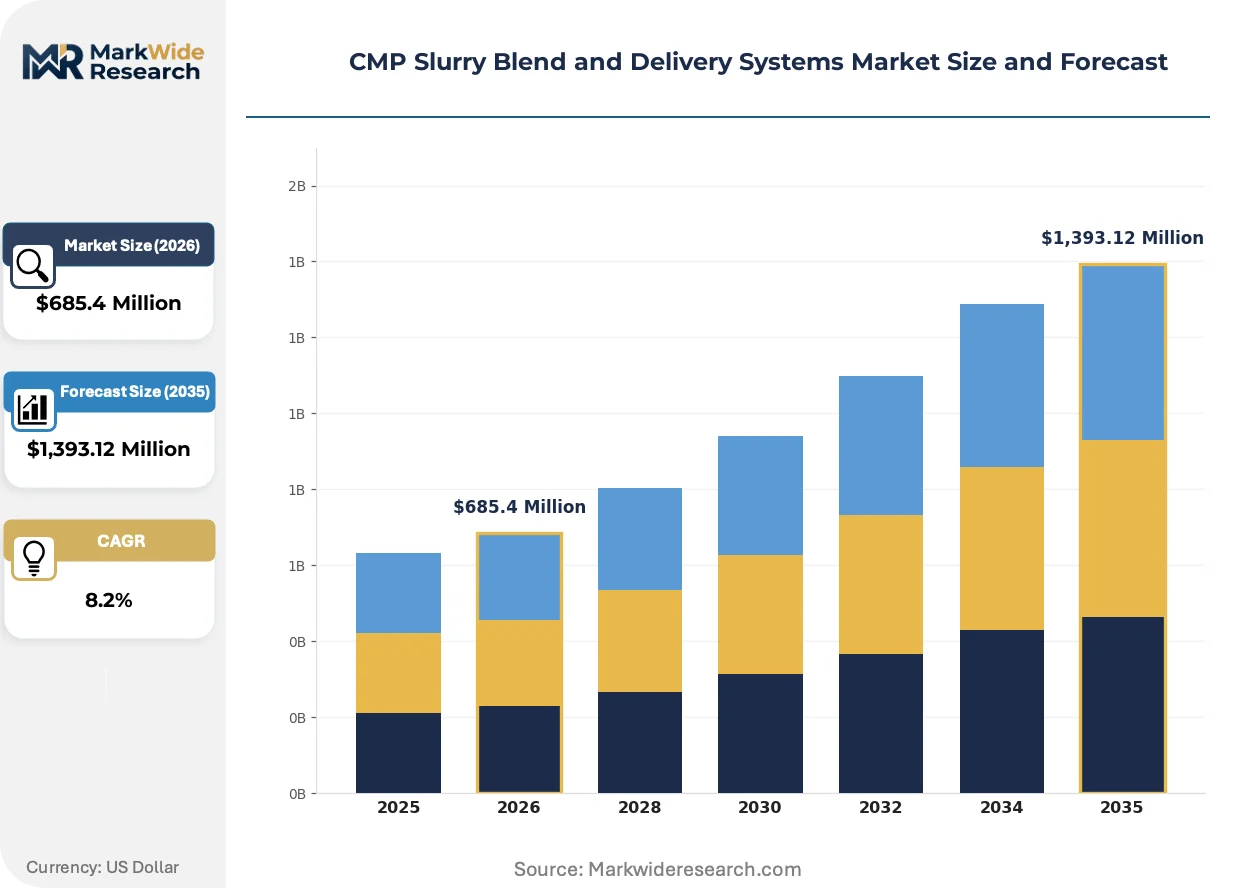
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-Mixed Slurries, On-Site Blending Systems, Delivery Pumps, Storage Tanks End User: Semi-Conductor Manufacturers, Photovoltaic Manufacturers, Research Labs, Industrial Users Delivery Mode: Automated Delivery, Manual Delivery, Bulk Delivery, Containerized Delivery Application: Wafer Polishing, Chemical Etching, Surface Preparation, Equipment Cleaning |
| Companies Covered | AGC, FUJIFILM Corporation, Entegris, Hitachi Chemical, 3M Company, DuPont de Nemours, Resonac Holdings, Saint-Gobain Ceramics & Plastics, Fujimi Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CMP Slurry Blend and Delivery Systems Market Trends and Innovations
Digital twin architectures are penetrating slurry delivery system design, enabling predictive maintenance and real-time recipe optimization before hardware reaches the fab floor.
Point-of-use blending hardware is virtualizing the traditional slurry supply chain by collapsing mixing, filtration, and distribution into single-wafer recipe execution. Leading foundries in Taiwan and South Korea are deploying these systems for gate-all-around process development. This compression is virtualizing the role of regional slurry distribution centers, shifting value capture toward equipment makers with embedded formulation intelligence.
REACH chemical registration requirements in Europe are tightening disclosure obligations for slurry additive compositions, forcing reformulation of proprietary blends to maintain trade secret protection. Semiconductor manufacturers importing into the EU now face extended documentation timelines. Dielectric CMP slurries with complex organic surfactant packages are experiencing the most acute compliance friction.
Buyer consolidation among top-tier foundries is concentrating procurement leverage, compressing supplier margins and demanding outcome-based performance guarantees rather than equipment-only transactions. Mid-sized slurry delivery vendors are responding with service bundling that includes consumables and on-site technical support. This model is most visible in Taiwan's Hsinchu and Tainan Science Park corridors where TSMC and UMC dominate capacity expansion planning.
CMP Slurry Blend and Delivery Systems Market Segmentation
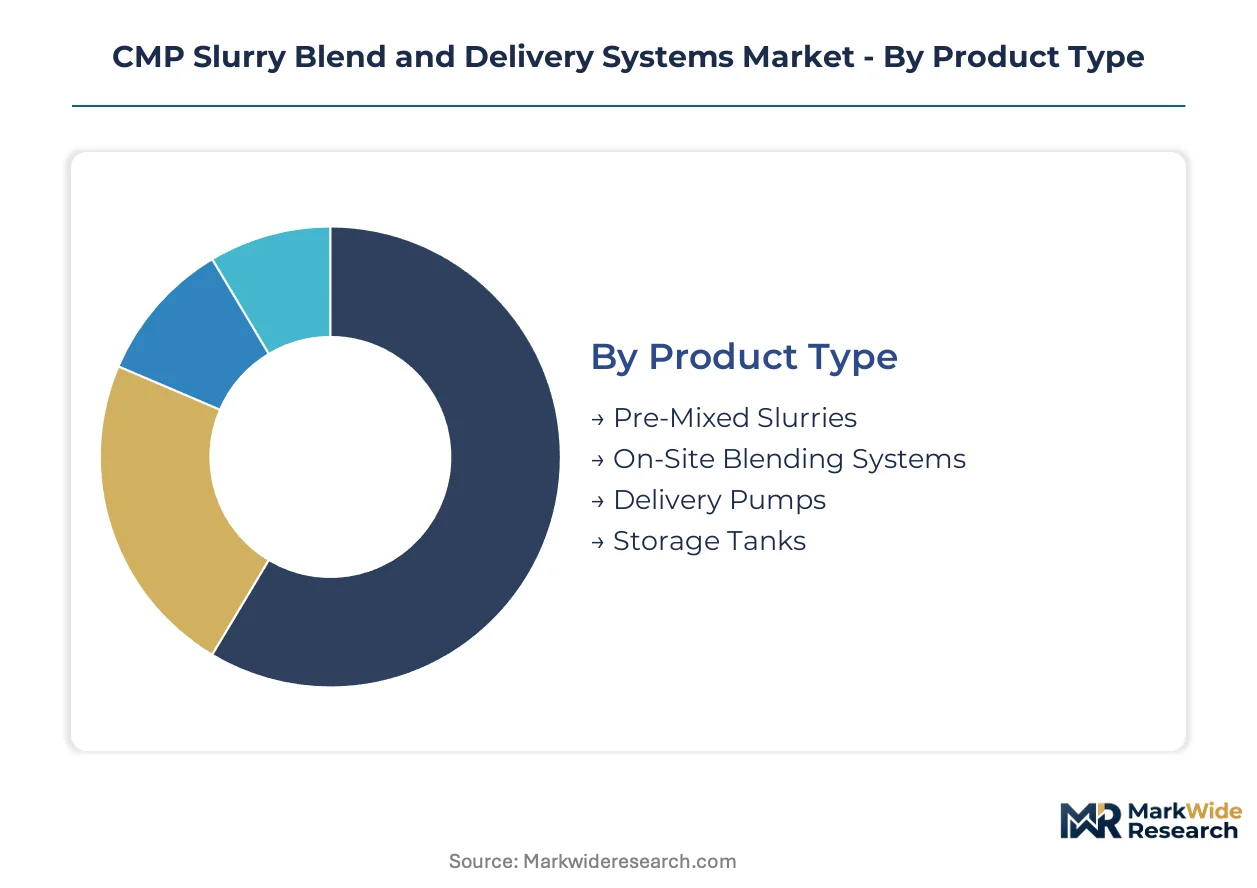
CMP slurry blend and delivery systems fragment across four critical dimensions that determine procurement patterns, technical requirements, and margin structures. Each segmentation axis carries distinct implications for equipment design, service intensity, and customer relationship economics.
Product Type:
After-sales service intensity varies dramatically across product categories, with on-site blending systems demanding continuous technical support while storage tanks require minimal intervention.
- Pre-Mixed Slurries:Factory-blended formulations arrive at fabs ready for direct use, eliminating mixing variables but constraining recipe flexibility. Semiconductor manufacturers in Taiwan's Hsinchu cluster dominate consumption, prioritizing supply security over customization as node transitions accelerate.
- On-Site Blending Systems:Modular hardware meters abrasives, oxidizers, and deionized water at point-of-use, enabling real-time recipe adjustments for gate-all-around process steps. South Korean foundries lead deployment, driven by waste reduction mandates and sub-3nm planarization complexity.
- Delivery Pumps:Precision positive-displacement and peristaltic designs maintain flow stability below 1% variation across 1–10 liter per minute operating ranges. Demand concentrates among fabs upgrading legacy infrastructure rather than greenfield installations.
- Storage Tanks:High-purity polyethylene and stainless steel vessels incorporate nitrogen blanketing and particle filtration to preserve slurry stability during hold periods. Photovoltaic manufacturers represent the primary growth vector as silicon wafer polishing expands beyond semiconductors.
Pre-mixed slurries hold the largest share; momentum sits with on-site blending systems.
End User:
Customer scale determines contract structures, with foundries negotiating multi-year framework agreements while research labs purchase through project-based procurement.
- Semi-Conductor Manufacturers:Integrated device manufacturers and pure-play foundries operate the highest-volume installations, typically consuming thousands of liters monthly across dielectric, metal, and barrier CMP steps. TSMC's supplier ecosystem in Taiwan anchors absolute demand as 2nm fab construction proceeds.
- Photovoltaic Manufacturers:Silicon ingot and wafer producers apply adapted CMP chemistries for substrate planarization, with specifications diverging from semiconductor-grade purity requirements. China's solar cell production expansion drives regional equipment qualification.
- Research Labs:University cleanrooms and national laboratories pilot advanced packaging schemes including hybrid bonding and through-silicon via integration. Equipment flexibility outweighs throughput in purchasing criteria.
- Industrial Users:Hard disk drive substrate polishers and optical component fabricators represent specialized niches with distinct abrasive chemistry requirements. Volume per installation remains an order of magnitude below semiconductor fabs.
Semi-conductor manufacturers command the revenue base; research labs are climbing the fastest.
Delivery Mode:
Automation penetration correlates with fab scale, with leading-edge facilities eliminating manual handling to reduce contamination risk.
- Automated Delivery:PLC-controlled distribution networks integrate with manufacturing execution systems, enabling lot tracking and recipe enforcement across multiple polish tools. Taiwan's Industrial Development Bureau incentivizes automation adoption through cleanroom efficiency standards.
- Manual Delivery:Container transfer and hose connection by cleanroom-qualified technicians persists in legacy fabs and small-batch research environments. Labor cost escalation in South Korea and Japan erodes economic viability.
- Bulk Delivery:Tanker truck and tote systems supply high-volume consumers with dedicated pipeline connections, minimizing packaging waste. Requires substantial capital investment in unloading infrastructure and storage capacity.
- Containerized Delivery:Intermediate bulk containers and drum shipments serve mid-tier fabs and geographic regions lacking bulk distribution infrastructure. Flexibility trades off against per-liter logistics cost premiums.
Automated delivery dominates new installations; containerized delivery retains share in emerging fab geographies.
Application:
Process step criticality determines specification stringency, with wafer polishing commanding the tightest particle control while equipment cleaning tolerates broader distributions.
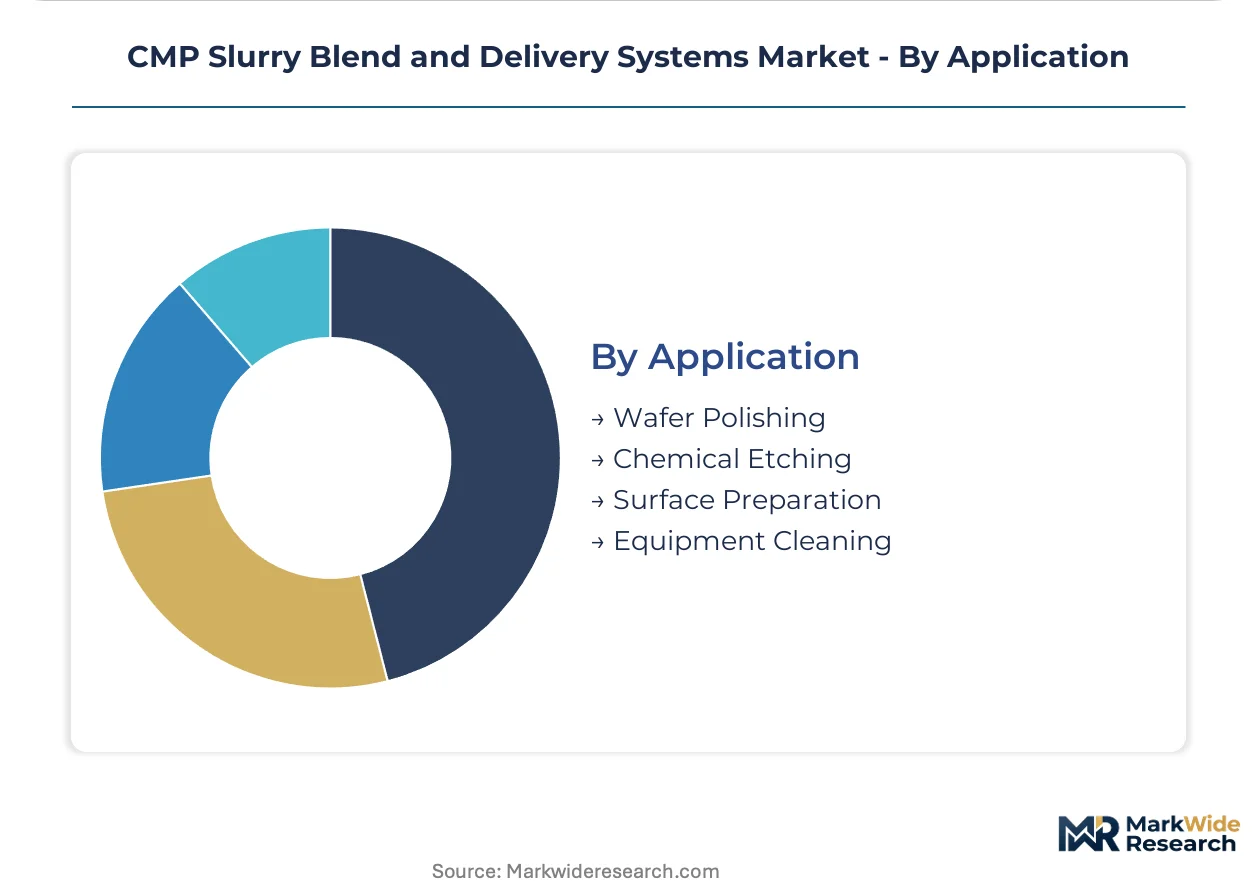
- Wafer Polishing:Chemical-mechanical planarization of dielectric oxides, copper interconnects, and tungsten vias requires sub-100 nanometer particle size distributions to prevent microscratch defects. Gate-all-around transistor architectures multiply polish steps per wafer.
- Chemical Etching:Slurry-based material removal for pattern definition and surface conditioning operates with less stringent planarization uniformity requirements. Research labs pilot novel chemistries for advanced packaging integration.
- Surface Preparation:Pre-CMP conditioning and post-CMP cleaning steps utilize diluted formulations to optimize adhesion and remove residual abrasives. Emerging demand from silicon carbide power semiconductor substrate processing.
- Equipment Cleaning:Polish tool maintenance cycles consume reclaimed and lower-grade slurries for pad conditioning and chamber scrubbing. Circular economy mandates in the EU and Taiwan drive recycling system integration.
Wafer polishing generates the majority of system deployments; surface preparation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in high-purity colloidal silica are reshaping procurement geography, with fabs in Taiwan and South Korea accelerating domestic blending capacity to reduce abrasive feedstock vulnerability. Trade flows now favor regional equipment qualification over long-haul bulk slurry shipments.
Taiwan
TSMC's 2nm fab construction in Hsinchu Science Park is driving point-of-use blending system deployment at unprecedented density. Taiwan's Industrial Development Bureau enforces local content thresholds that steer procurement toward domestic-qualified suppliers. The Tainan Science Park corridor is witnessing co-location of Entegris blending facilities with leading-edge wafer production.
South Korea
Samsung Foundry and SK Hynix are expanding CMP steps per wafer for 3D-IC integration, multiplying slurry consumption at Pyeongtaek and Yongin complexes. Korea's Ministry of Trade, Industry and Energy channels semiconductor R&D subsidies toward waste-reducing on-site blending architectures. The Giheung cluster anchors equipment validation for sub-3nm process development.
United States
Intel's Ohio and Arizona fab investments are resurrecting domestic leading-edge capacity with integrated slurry delivery infrastructure. EPA PFAS discharge regulations constrain surfactant formulation choices for fabs operating in Arizona and Oregon. The Albany Nanotech Complex in New York serves as the primary venue for EUV-era CMP process co-development with equipment vendors.
Japan
Resonac Holdings and Fujimi Incorporated anchor abrasive chemistry production serving both domestic and export markets. METI's semiconductor revitalization subsidies support qualification of next-generation colloidal silica for sub-3nm nodes. The Kyushu region's Kumamoto Prefecture is attracting TSMC-Japan joint venture fab investment with associated supplier ecosystem clustering.
Germany
Bosch and Infineon are expanding automotive-grade semiconductor CMP capacity in Dresden and Regensburg. ECHA REACH registration requirements impose disclosure burdens on slurry additive imports that favor regional formulation sourcing. The Silicon Saxony cluster is integrating blending systems with power semiconductor substrate planarization lines.
CMP Slurry Blend and Delivery Systems Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: diversified materials conglomerates with captive abrasive production, specialized fluid handling equipment vendors, and regional formulation specialists serving single-fab contracts. Japanese and US-based chemical companies exemplify the integrated materials archetype, while fluid management specialists concentrate in North American supply chains. Competitive dynamics center on M&A activity targeting colloidal silica production assets and strategic partnerships binding equipment makers to foundry qualification timelines.
Within the integrated materials tier, Fujifilm Corporation and DuPont de Nemours occupy positions that span abrasive chemistry through delivery system design, representing the convergence of formulation intelligence with hardware deployment. Entegris exemplifies the fluid handling specialization archetype, anchoring high-purity distribution expertise that spans multiple foundry ecosystems. These three companies collectively illustrate how supplier strategies are bifurcating between chemistry-heavy and equipment-heavy competitive vectors.
| Leading Market Players |
|---|
| AGC |
| FUJIFILM Corporation |
| Entegris |
| Hitachi Chemical |
| 3M Company |
| DuPont de Nemours |
| Resonac Holdings |
| Saint-Gobain Ceramics & Plastics |
| Fujimi Incorporated |
| Others |
Pricing and Supply Chain Analysis
Hsinchu Science Park's concentrated supplier ecosystem concentrates pricing leverage among equipment vendors serving TSMC's 2nm expansion, while downstream foundries face cost compression from multi-source abrasive qualification mandates. Taiwan's Industrial Development Bureau local content thresholds amplify regional premium capture against containerized import alternatives.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scale and certification-grade price differentiation. Premium-mid-economy pricing stratification separates ISO 14644 Class 1-qualified systems from standard cleanroom configurations. Cost compression in mid-tier blending hardware intensifies because South Korean foundries are dual-qualifying suppliers for waste-reduction mandates. Research labs exhibit highest price sensitivity due to project-based procurement, while leading-edge foundries prioritize outcome-based performance guarantees over per-unit economics.
Supply Chain Analysis
Tariff exposure between Japan and Taiwan dominates supply chain risk calculations for high-purity colloidal silica feedstock. Production gravity centers on Japan, Taiwan, and South Korea, with abrasive chemistry R&D anchored in Kumamoto Prefecture and Hsinchu corridor. Raw material dependencies rest on fumed silica precursors, precision membrane filtration components, and nitrogen blanketing systems. Single-source vulnerability persists for sub-50nm particle filtration membranes. Distribution runs through co-located blending facilities at leading-edge fab clusters, displacing long-haul bulk slurry tanker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gate-all-around transistor architectures at sub-3nm nodes are compressing recipe validation timelines and fragmenting procurement patterns, creating high-growth disruption for modular point-of-use blending specialists.
For Market Incumbents: Insulate installed base positions through captive colloidal silica production in East Asian supply corridors and accelerated certification investment for EPA PFAS-compliant surfactant formulations. Threat substitution from research lab pilot-line prototyping demands pre-emptive flexible system deployment. Backward integration into abrasive feedstock secures margin control against raw material volatility. For New Entrants and Emerging Players: European power semiconductor clusters in Dresden and Regensburg present underpenetrated demand for silicon carbide wafer polishing adaptations. Target automotive-grade CMP capacity expansion with REACH-registered formulation packages that bypass ECHA disclosure friction. Go-to-market angle: closed-loop recycling integration aligned with EU circular economy mandates. For Investors and Strategic Acquirers: Long-term, this sits as a process-intensity play because CMP steps per wafer multiply with 3D-IC integration regardless of node transition pacing. Acquisition target archetype: regional formulation specialists with captive foundry qualification relationships. Signal to watch: Taiwan Industrial Development Bureau waste minimization enforcement accelerating on-site blending retrofit cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Colloidal Silica | Captive abrasive supply secures margin control against Resonac Holdings and Fujimi Incorporated concentration. |
| Point-of-Use Blending Deployment | Modular architectures align with TSMC gate-all-around process development timelines in Hsinchu. |
| REACH Registration Completion | ECHA compliance enables EU fab qualification for Bosch and Infineon expansion in Dresden. |
| Silicon Carbide Formulation Development | Power semiconductor substrate planarization diverges from silicon CMP specifications in Kumamoto. |
| Closed-Loop Recycling Integration | Taiwan waste mandates create pull for Entegris-style closed-loop delivery architectures. |
Research Methodology
A spread of perspectives from fab procurement directors, cleanroom infrastructure engineers, colloidal silica R&D leads, and slurry formulation chemists converged on the working assumptions. Primary interviews with equipment validation specialists at South Korean foundries and Taiwan's Hsinchu supplier ecosystem were cross-referenced against secondary validation from SEMI equipment market data, Taiwan Industrial Development Bureau local content filings, EPA PFAS regulatory dockets, and SEC 10-K disclosures from integrated materials suppliers. Bottom-up installation base modeling and top-down foundry capex allocation triangulation anchored volume estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include product type tier, end-user scale, delivery mode automation level, and application process criticality. CAGRs were derived from installed base expansion rates and consumption intensity per wafer start. Industry-specific forecast inputs incorporated gate-all-around step multiplication factors and Taiwan local content threshold enforcement timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity addition by Chinese photovoltaic manufacturers or accelerated EPA PFAS restriction timelines would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market
Water & Sludge Treatment
Flocculants Market
Water & Sludge Treatment
Sedimentation and Centrifugation Market
Water & Sludge Treatment
Water Softening Systems Market
Water & Sludge Treatment
North America Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Fluid Waste Disposal Systems Market
Water & Sludge Treatment
Australia Water Treatment Chemicals Market
Water & Sludge Treatment
China Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Membrane Water and Wastewater Treatment (WWT) Market