
 Water Treatment Chemicals Market | 2026-2036
Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Water Treatment Chemicals Market Intelligence
Procurement from large, multi-national food processing and power generation firms is hardening supply chain requirements. Ecolab leverages its extensive service network to secure contracts with these large-scale end-users. BASF SE competes through its specialized chemical portfolio tailored for complex industrial water circuits. Veolia integrates its chemical offerings with its broader water management services.
Water treatment chemicals are specialty formulations that modify water properties to remove impurities, adjust pH, or prevent microbial growth. These compounds, including polymers and inorganic salts, ensure water meets quality standards for consumption or industrial use. Coagulants and flocculants form a high-volume product segment, while advanced corrosion inhibitors command higher margins in industrial process water applications. The wastewater management application segment shows consistent demand driven by municipal regulations.
Regulatory frameworks like the US EPA's Safe Drinking Water Act and the EU's REACH regulation directly influence chemical composition and approved usage. In China, the 'dual carbon goals' policy is pushing for more efficient and less-polluting treatment solutions in industrial sectors. Formulators must now balance performance efficacy with an increasingly complex global matrix of environmental compliance and material sourcing constraints.
Market Dynamics
The push toward circular water economies, driven by water scarcity and stricter effluent discharge limits, is the central force shaping the market. This compels industrial users, particularly in power generation and food processing, to adopt more advanced chemical treatment systems that enable water reuse.
Growth Catalysts
- Stricter Effluent Standards:The US EPA's enforcement of MCLGs and China's 'dual carbon goals' policy are compelling facilities to upgrade treatment processes, boosting demand for high-performance coagulants and flocculants.
- Industrial Water Reuse:The food processing sector is increasingly implementing zero liquid discharge (ZLD) systems to mitigate water scarcity risks, creating sustained demand for specialized scale and corrosion inhibitors.
- Urban Infrastructure Expansion:Rapid urbanization in India necessitates new municipal water and wastewater treatment plant construction, which directly drives volume consumption of basic chemicals like chlorine and lime.
Market Restraints
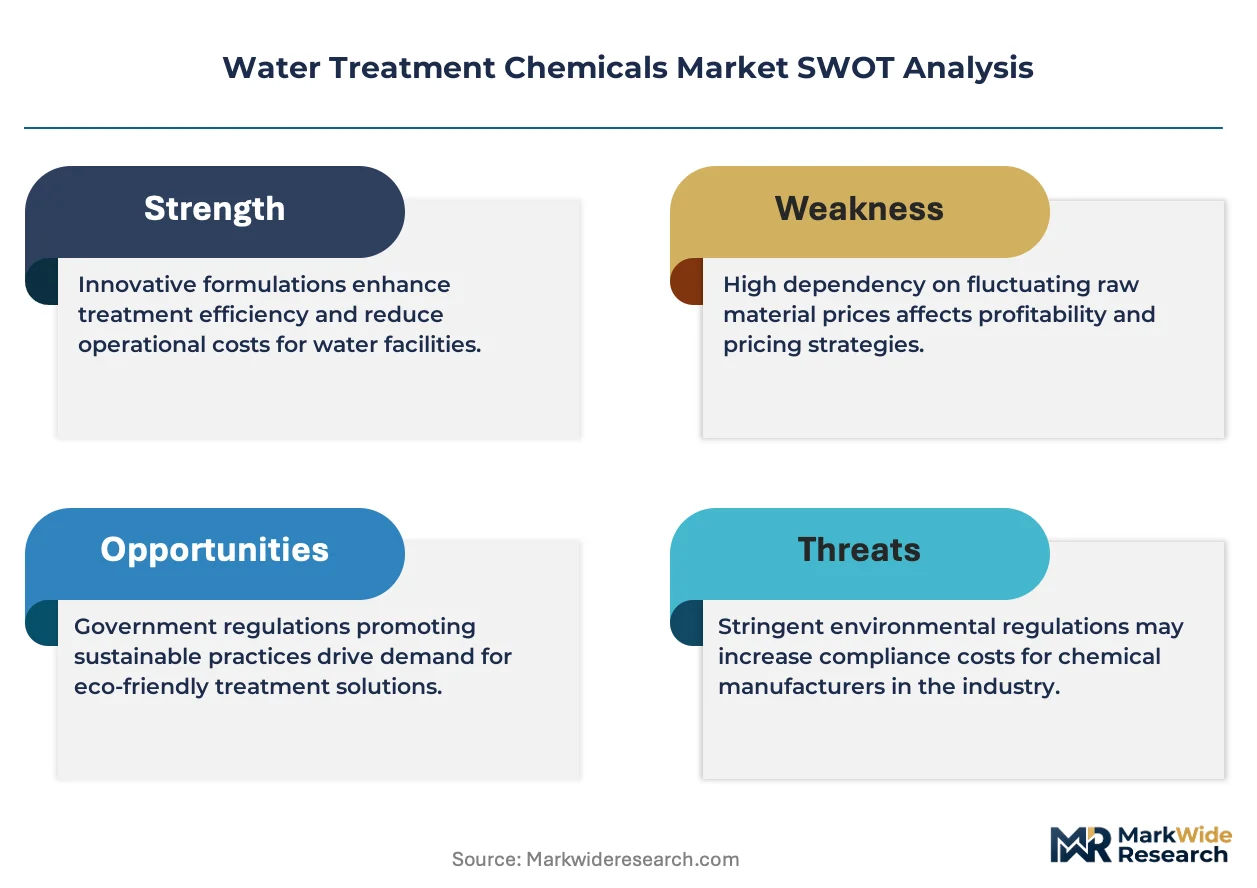
- Raw Material Volatility:Prices for key precursors like acrylic acid and ethylene, fundamental to polymer production, are subject to fluctuations in the petrochemical market, creating margin pressure for formulators.
- Non-Chemical Treatment Adoption:Physical treatment methods, such as UV disinfection and membrane filtration, are gaining traction in certain applications, presenting a substitution threat to chemical biocides and disinfectants.
- Complex Compliance Burden:Adhering to divergent chemical registration requirements of frameworks like EU REACH and South Korea's K-REACH adds significant cost and time-to-market delays for new product introductions.
Strategic Opportunities
- Biocidal Formulation Innovation:Development of non-oxidizing biocides and enzyme-based treatments offers a pathway to displace traditional chlorine-based products, especially in systems with corrosion-sensitive metallurgy like cooling towers.
- Desalination Plant Growth:Expansion of desalination capacity in the Middle East, particularly in Saudi Arabia and the UAE, opens a significant market for antiscalants, corrosion inhibitors, and membrane cleaning chemicals.
- Digital Service Integration:Embedding sensors and data analytics into chemical dosing systems allows for performance-based contracts, creating a new value proposition beyond simple chemical sales for industrial clients.
Industry Challenges
- Field Application Expertise Scarcity:A shortage of water chemists and field service technicians capable of diagnosing complex industrial water circuits and optimizing chemical programs hinders service-led growth models.
- Legacy System Compatibility:Integrating smart dosing pumps and monitoring equipment with older, non-digitized control systems at municipal plants presents significant technical and capital hurdles for facility upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Treatment Chemicals Market |
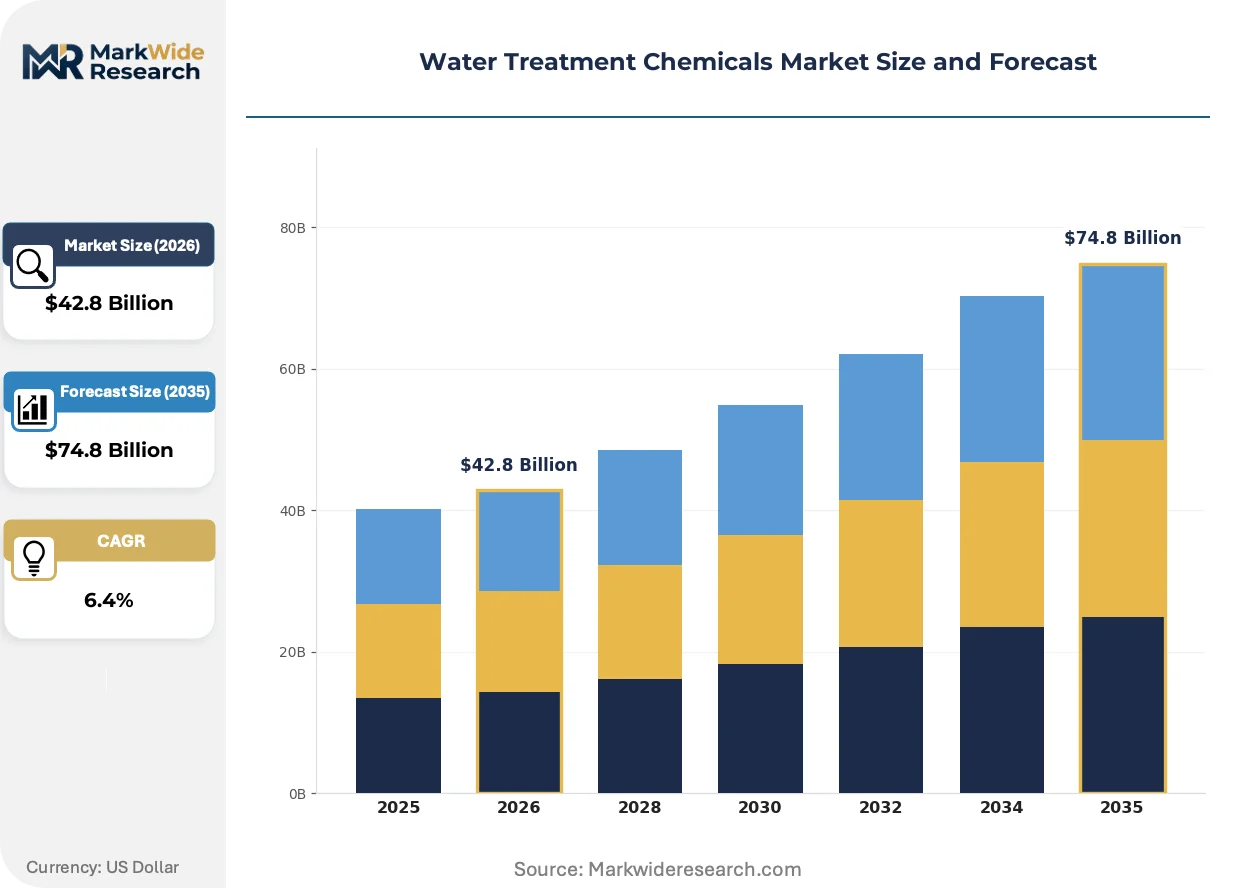
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, Disinfectants, pH Adjusters, Corrosion Inhibitors Application: Drinking Water, Wastewater Management, Industrial Process Water, Cooling Towers, Swimming Pools End User Industry: Municipal Water Authorities, Chemical Manufacturing, Food Processing, Power Generation, Pulp & Paper Packaging Type: Liquid, Powder, Granules, Pellets, Bulk Tanker |
| Companies Covered | Ecolab, BASF SE, Kemira, Veolia, Dow Inc, Solenis, Kurita Water Industries Ltd., Nouryon, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Treatment Chemicals Market Strategic Shifts & Innovations
A focus on resource efficiency and environmental impact reduction is guiding innovation. Chemical formulators are moving beyond simple efficacy to develop solutions that minimize sludge, reduce energy consumption, and comply with a tightening global regulatory landscape.
Digital twin technology for water systems creates a virtual model of a physical treatment process. Industrial end-users in semiconductor and pharmaceutical manufacturing are adopting these systems to predict performance and optimize chemical dosing. This predictive capability is absorbing the risk previously managed through reactive chemical application, lowering operational costs.
The EU's Corporate Sustainability Reporting Directive (CSRD) mandates detailed disclosure on water usage and pollution. This forces large companies to quantify the environmental footprint of their value chain, including chemical inputs for water treatment. The power generation sector is most affected, now demanding products with verified environmental product declarations (EPDs).
Service-based models are gaining traction over transactional chemical sales. Instead of purchasing chemicals by volume, industrial clients contract for guaranteed water quality or system uptime. This shift disrupts traditional distribution channels, a trend highly visible in the North American food and beverage processing market.
Water Treatment Chemicals Market Segmentation
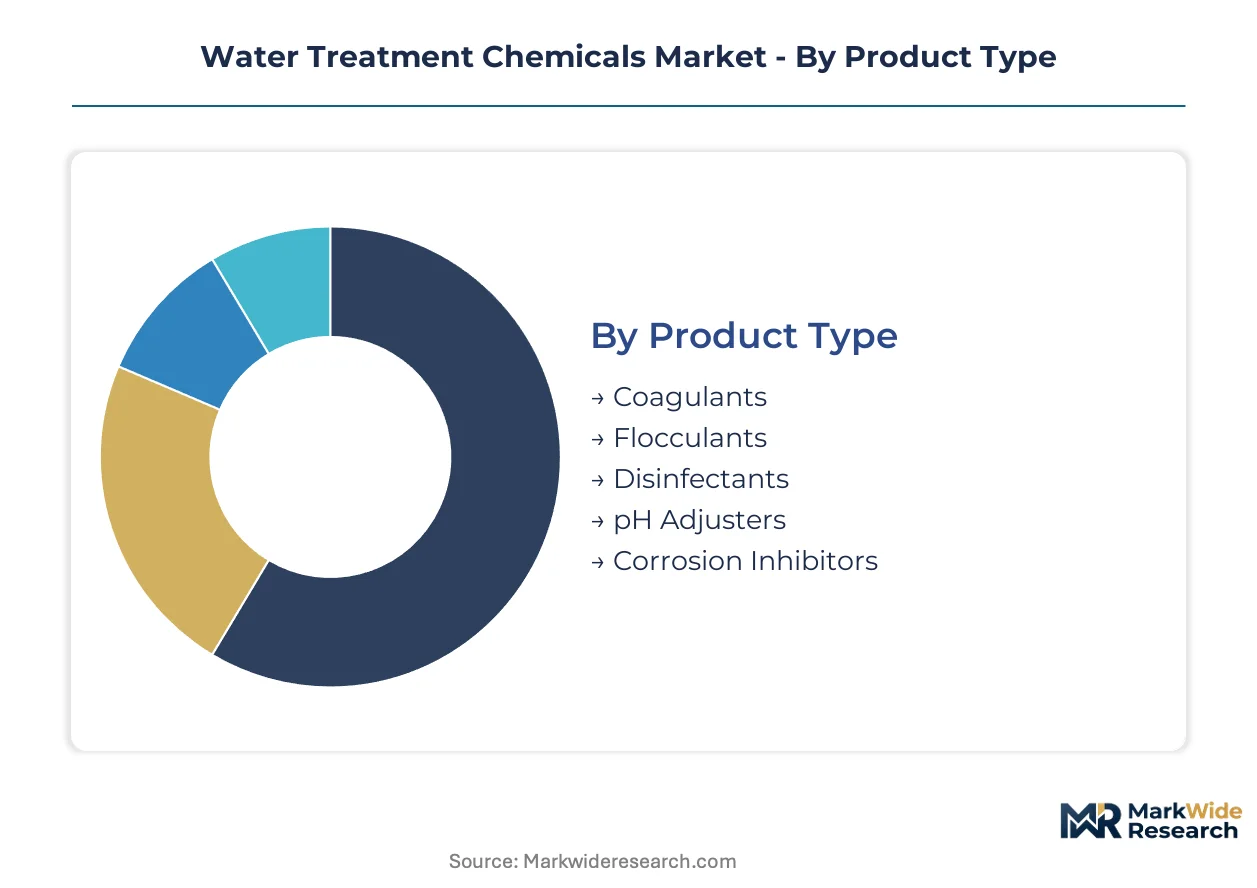
Understanding the distinct segments within the water treatment chemicals market is essential for strategic planning and resource allocation. Each category reflects varying technical requirements, regulatory pressures, and cost structures across diverse applications. This granular view allows stakeholders to identify areas of concentrated demand and specialized chemical needs.
Product Type:
The capital intensity associated with manufacturing different product types varies significantly, influencing production scale and geographic distribution.
- Coagulants:These are chemical agents like aluminum sulfate or ferric chloride that neutralize charges on suspended particles, causing them to aggregate. Demand concentrates in municipal water treatment plants in India, driven by the need for bulk impurity removal from raw water sources.
- Corrosion Inhibitors:These specialty formulations, often organic or inorganic compounds, form a protective film on metal surfaces to prevent degradation. Industrial process water applications in Germany utilize these for complex closed-loop cooling systems to extend asset lifespan.
- Flocculants:Polymeric substances, such as polyacrylamides, bind aggregated particles into larger, settleable flocs for easier separation.
- Disinfectants:Chemicals like chlorine or ozone eliminate pathogenic microorganisms, crucial for public health in drinking water supplies.
- pH Adjusters:Acids or bases, including lime and caustic soda, modify water's acidity or alkalinity for optimal treatment conditions or discharge compliance.
Most installed capacity flows through Disinfectants. Expansion is steepest in Corrosion Inhibitors.
Application:
The volume of chemical consumption varies drastically across different water treatment applications, impacting procurement strategies and supply chain scale.
- Drinking Water:This application involves treating raw water sources to meet potable standards, utilizing a range of chemicals from coagulants to disinfectants. Stricter MCLGs from the US EPA drive advanced chemical use to ensure public health and safety.
- Wastewater Management:This segment focuses on treating municipal and industrial effluents to comply with discharge regulations, frequently employing flocculants and pH adjusters. China's 'dual carbon goals' policy is pushing for more efficient treatment in industrial wastewater.
- Industrial Process Water:Water used in manufacturing processes requires specialized treatment to prevent scaling, corrosion, and biological fouling, ensuring operational efficiency.
- Cooling Towers:These systems demand biocides and corrosion inhibitors to maintain heat exchange efficiency and prevent microbial growth in recirculating water.
- Swimming Pools:Chemicals like chlorine and algaecides are essential for sanitization and maintaining water clarity in recreational facilities.
High-value specialty chemicals find extensive use in Industrial Process Water, while Drinking Water applications represent the largest volume segment.
End User Industry:
Procurement patterns and service requirements differ significantly among end-user industries, influencing how chemical suppliers structure their sales and support.
- Municipal Water Authorities:These government-run or regulated entities manage public water supply and wastewater treatment, requiring bulk chemicals and long-term contracts. Infrastructure upgrades in the US, driven by EPA mandates, boost demand for advanced coagulants.
- Food Processing:This industry demands high-purity water for production and extensive wastewater treatment, with a focus on food-grade chemicals and zero liquid discharge systems. Water scarcity in regions like California compels food processors to adopt advanced reuse technologies.
- Chemical Manufacturing:This sector uses water for cooling, process, and wastewater, often requiring highly specialized and robust chemical formulations due to complex effluent streams.
- Power Generation:Plants utilize water for cooling and steam generation, necessitating scale and corrosion inhibitors to protect boilers and heat exchangers from mineral deposits.
- Pulp & Paper:This industry consumes large volumes of water, requiring chemicals for process optimization, sludge dewatering, and effluent treatment to meet discharge limits.
Regulatory compliance is a primary driver for Municipal Water Authorities, while Food Processing prioritizes water reuse and quality control.
Packaging Type:
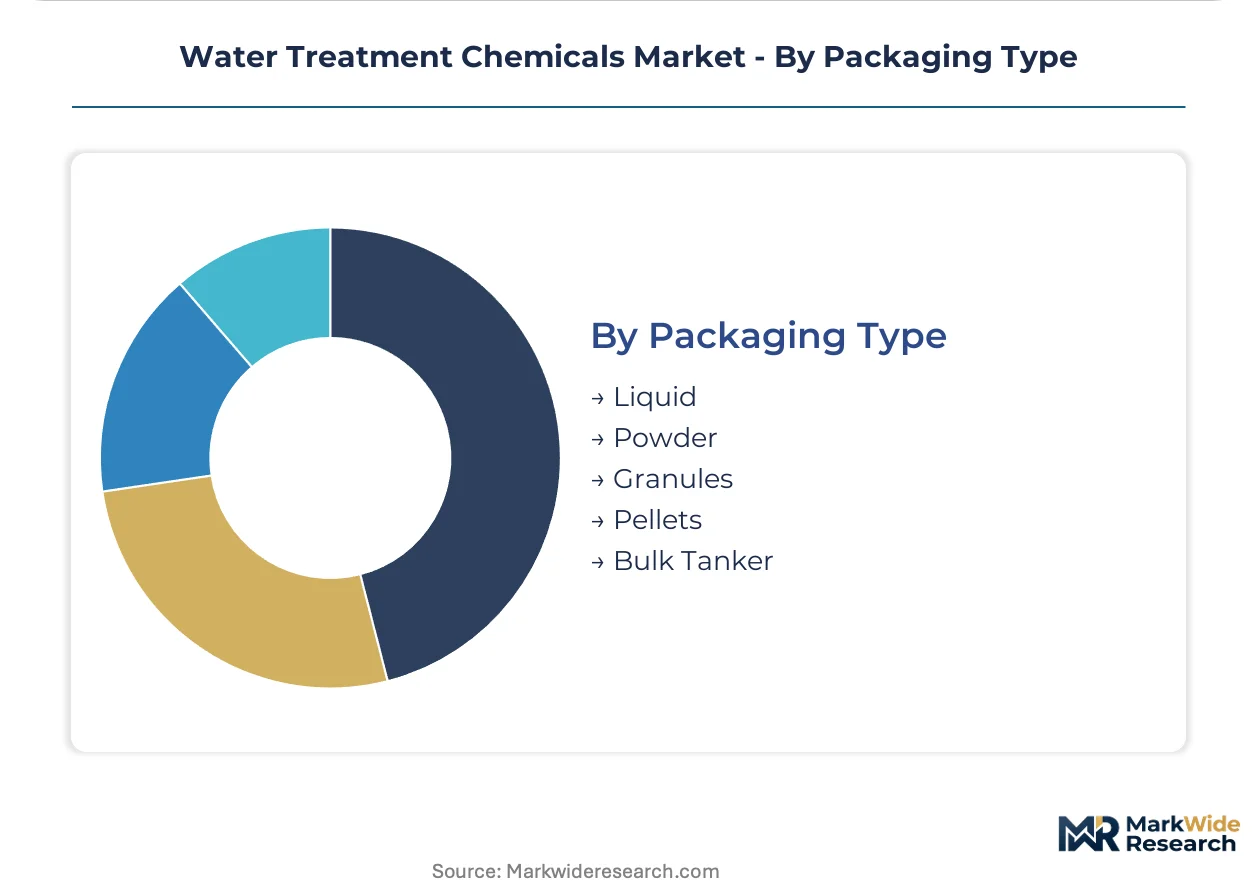
The choice of packaging type directly impacts logistics costs, storage requirements, and handling safety across the supply chain for water treatment chemicals.
- Liquid:Chemicals supplied in liquid form offer ease of dosing and mixing, commonly used for disinfectants and pH adjusters in municipal plants. European regulations like REACH influence the formulation and transport of liquid chemical products.
- Bulk Tanker:Large volumes of commodity chemicals, such as coagulants or lime slurry, are transported via bulk tankers directly to major industrial sites or municipal facilities. This method optimizes cost efficiency for high-volume consumers in Saudi Arabia's desalination plants.
- Powder:Dry chemical forms, like some flocculants or activated carbon, offer advantages in storage stability and reduced shipping weight for remote locations.
- Granules:Granular chemicals provide controlled dissolution rates and minimize dusting, suitable for applications requiring precise dosing without airborne particles.
- Pellets:Pelletized chemicals are dense and free-flowing, often used for slow-release applications or where dust generation must be strictly avoided, such as in certain industrial processes.
Cost efficiency drives the preference for Bulk Tanker deliveries for large-scale operations, while Liquid packaging offers operational convenience for many users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States focuses on upgrading aging infrastructure, China is prioritizing industrial effluent treatment. These distinct regional priorities shape demand for specific chemical formulations. Global regulatory shifts and water scarcity concerns continue to drive market evolution across diverse geographies.
United States
Demand for water treatment chemicals in the United States is driven by infrastructure upgrades and stricter US EPA mandates. The US EPA's Safe Drinking Water Act and Maximum Contaminant Level Goals compel municipal authorities to adopt advanced chemical use. Municipal water authorities in states like California are investing in advanced treatment for potable water reuse systems.
China
China's industrial coastal regions concentrate demand for water treatment chemicals, particularly for managing manufacturing effluent. The country's 'dual carbon goals' policy pushes for more efficient and less-polluting treatment solutions in industrial sectors. Industrial clusters in the Yangtze River Delta are adopting advanced chemical systems to meet stringent discharge limits.
India
India's rapid urbanization necessitates new municipal water and wastewater treatment plant construction, which directly drives volume consumption of basic chemicals. BIS standards are influencing water quality requirements for public water supply. Urban centers like Mumbai and Delhi are driving demand for coagulants and disinfectants for bulk impurity removal.
Germany
Germany's industrial process water applications utilize specialized corrosion inhibitors for complex closed-loop cooling systems to extend asset lifespan. The EU's REACH regulation directly influences chemical composition and approved usage within the country. Industrial facilities in the Ruhr Area prioritize high-performance formulations for efficient water management.
Saudi Arabia
Saudi Arabia's expansion of desalination capacity creates significant demand for antiscalants, corrosion inhibitors, and membrane cleaning chemicals. SFDA regulations ensure water quality for both potable and industrial use across the kingdom. Large-scale desalination plants along the Red Sea coast require continuous supply of specialty chemicals for optimal operation.
Water Treatment Chemicals Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a tiered market structure. Large chemical manufacturers often offer a broad portfolio, while specialized firms target niche applications like advanced corrosion inhibition. Strategic archetypes include global chemical suppliers, integrated water solution providers, and regional specialty formulators. Companies are pursuing strategic partnerships, technology innovation, and service-based models to secure market share and differentiate offerings.
Within the integrated water management segment, Veolia, a France-based environmental services company, exemplifies a comprehensive service approach, combining chemical offerings with broader water management solutions. Ecolab, a US-based company, represents firms leveraging extensive service networks to secure contracts with large-scale food processing and power generation end-users, emphasizing service-led growth. BASF SE, a German-headquartered chemical company, competes through its specialized chemical portfolio tailored for complex industrial water circuits, focusing on performance efficacy and environmental compliance for industrial clients.
| Leading Market Players |
|---|
| Ecolab |
| BASF SE |
| Kemira |
| Veolia |
| Dow Inc |
| Solenis |
| Kurita Water Industries Ltd. |
| Nouryon |
| Baker Hughes Company |
Cost & Logistics Intelligence
Petrochemical market volatility, particularly for acrylic acid and ethylene, cascades through the water treatment chemicals supply chain, influencing pricing tiers for polymer-based flocculants and specialty inhibitors. This directly impacts formulator margins and end-user procurement costs.
Pricing Analysis
Capacity additions in China's industrial coastal regions are reshaping price floors for commodity coagulants and flocculants. The market operates primarily on contract-based long-term offtake agreements for municipal authorities, while industrial clients increasingly prefer value-based service models. Price differentiation stems from performance efficacy in complex industrial circuits and verified environmental product declarations (EPDs). Pricing softness stems from raw material volatility and the increasing adoption of non-chemical treatment alternatives like membrane filtration. Municipal water authorities are highly price-sensitive for bulk chemicals, whereas industrial process water users prioritize performance and reliability.
Supply Chain Analysis
High logistics and freight costs significantly impact the delivered price of bulk water treatment chemicals, particularly for commodity coagulants transported to municipal plants in India. Supply concentrates in China for polymer precursors and in Europe for specialized industrial formulations. The market relies heavily on petrochemical feedstocks like acrylic acid and ethylene. Raw material price volatility represents a key structural risk. Distribution runs through bulk tankers for large-scale operations in Saudi Arabia and regional specialty distributors for diverse industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water treatment chemicals market presents a clear margin-expansion story, driven by the shift towards high-value specialty formulations for complex industrial applications. Digital service integration and performance-based contracts are enabling premium-tier offerings.
For Market Incumbents: Acquire specialized field application expertise to mitigate the scarcity of water chemists and optimize chemical programs for complex industrial circuits. Incumbents should invest in advanced formulation R&D, particularly for non-oxidizing biocides, to counter the threat from non-chemical treatment adoption. Securing long-term supply agreements for key precursors like acrylic acid can also stabilize margins against raw material volatility.
For New Entrants and Emerging Players: Enter via niche advanced chemical formulations for desalination plants in Saudi Arabia, leveraging the expansion of capacity in the Middle East. Another white-space target involves developing enzyme-based treatments to displace traditional chlorine products in corrosion-sensitive systems. A strong go-to-market angle involves offering performance-based contracts, guaranteeing water quality or system uptime, especially in industrial process water applications.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized formulators possessing proprietary biocidal innovation or advanced digital integration capabilities. The long-term viability of this market hinges on increasing global water scarcity and stricter effluent discharge limits driving circular water economies. Investors should target companies offering solutions for complex industrial water circuits. The signal to watch for inflection is the accelerated adoption of zero liquid discharge (ZLD) systems in water-stressed regions.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Biocidal Formulation Innovation | Develops non-oxidizing biocides to displace chlorine in corrosion-sensitive cooling towers. |
| Expand Digital Service Integration | Embeds sensors and data analytics to offer performance-based contracts for industrial clients. |
| Secure Raw Material Supply Agreements | Mitigates margin pressure from petrochemical market volatility for polymer production. |
| Target Desalination Plant Growth | Addresses the significant market for antiscalants and corrosion inhibitors in Saudi Arabia. |
| Enhance Field Application Expertise | Optimizes chemical programs for complex industrial water circuits, addressing a key scarcity. |
Research Approach
Direct dialogue with plant managers, procurement leads, technical R&D directors, and municipal water authorities formed the primary data foundation. This primary research was rigorously validated through comprehensive secondary data sources, including US EPA filings, EU REACH documentation, Chinese environmental ministry reports, and global trade statistics. A bottom-up approach to market sizing was then triangulated with top-down industry reports to ensure accuracy.
A bottom-up analytical framework projected market values by product type, application, end-user industry, packaging type, and regional regulatory compliance. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected demand drivers across the analysis window. Key forecast inputs included industrial water reuse rates and municipal infrastructure upgrade investments.
The model holds under current raw material price stability and projected regulatory frameworks; deviation in petrochemical market volatility or accelerated non-chemical treatment adoption would shift forecasts. Forecasts reflect these underlying assumptions. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Semiconductor Wastewater Treatment Market
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Produced Water Treatment Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Fluid Waste Disposal Systems Market
Water & Sludge Treatment
Water Gel Market
Water & Sludge Treatment
Industrial Wastewater Treatment Market
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Ultrapure Water Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Ballast Water Treatment Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market