
 Nanotechnology in Water Treatment Market | 2026-2036
Nanotechnology in Water Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Nanotechnology in Water Treatment Market Foresight
Subscription-based membrane monitoring and predictive maintenance software is consolidating around nanofiltration and reverse osmosis installations. Veolia Water Technologies leverages digital service contracts to sustain recurring revenue across European municipal contracts. Pentair anchors its position through control of aftermarket cartridge replacement channels in North American industrial facilities. SUEZ competes by extending its Oxyblue platform into remote diagnostics for Middle Eastern desalination plants.
Nanotechnology in water treatment deploys engineered materials—typically 1–100 nanometers in dimension—including carbon nanotube membranes with pore densities exceeding 10⁹ pores per cm² and photocatalytic titanium dioxide coatings that mineralize organic pollutants under UV activation. Its primary purpose is to achieve selective separation, catalytic degradation, or antimicrobial action at energy intensities below conventional thermal or chemical processes. Nanofiltration membranes occupy the largest value pool due to their balance of permeability and divalent ion rejection in brackish water applications. Photocatalysis represents the fastest-expanding technology segment as industrial facilities seek zero-liquid-discharge compliance without chemical sludge generation. Contaminant removal applications command premium pricing relative to bulk desalination because of specialized PFAS and heavy metal capture requirements.
The EPA Office of Water enforces maximum contaminant level targets that directly shape membrane certification requirements for US municipal suppliers. The EU F-Gas Regulation and REACH restrictions on fluoropolymer precursors are forcing membrane manufacturers to reformulate coating chemistries for European market access. Saudi Arabia's National Water Regulator and India's Central Pollution Control Board are both tightening effluent standards that favor nanoparticle-enhanced tertiary treatment. Stakeholders must monitor how regulatory divergence between jurisdictions affects membrane material approval timelines and cross-border equipment certification costs.
Market Dynamics
Membrane manufacturers face mounting pressure to decouple from fluoropolymer feedstocks as REACH and F-Gas restrictions tighten across European jurisdictions, forcing simultaneous chemistry reformulation and performance recertification.
Growth Catalysts
- EPA PFAS MCL enforcement:Municipal utilities in the United States must deploy nanofiltration membranes to meet binding contamination limits, triggering system procurement cycles.
- Saudi National Water Strategy:Agricultural and industrial reuse mandates concentrate demand for advanced tertiary treatment in the Kingdom's procurement pipelines.
- Photocatalytic TiO₂ coatings:Industrial zero-liquid-discharge compliance drives UV-activated mineralization adoption without chemical sludge generation.
Market Restraints
- Fluoropolymer precursor concentration:REACH restrictions on perfluorinated compound manufacturing concentrate supply risk among limited European coating suppliers.
- Membrane fouling degradation:Organic and biological fouling reduces operational lifespan, elevating replacement frequency and total cost of ownership.
- Thermal distillation substitution:Mature multi-stage flash desalination retains cost advantages in high-salinity applications across the Middle East.
Strategic Opportunities
- India's Central Pollution Control Board tightening:Effluent standard enforcement creates nanoparticle-enhanced tertiary treatment demand in textile and pharmaceutical clusters.
- Carbon nanotube membrane convergence:Integration with graphene oxide layers enables tunable pore architectures for selective contaminant capture.
- Digital service contracts:Predictive maintenance platforms for remote desalination diagnostics unlock recurring revenue streams.
Industry Challenges
- Nanomaterial toxicology assessment:Ecotoxicity evaluation protocols for released nanoparticles remain underdeveloped, delaying regulatory approval timelines.
- Legacy infrastructure integration:Retrofitting nanofiltration skids into existing coagulation-flocculation trains requires hydraulic reconfiguration and operator retraining.
- Cross-border certification friction:Divergent membrane material approval standards between EPA, ECHA, and Saudi Arabia's National Water Regulator fragment market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanotechnology in Water Treatment Market |
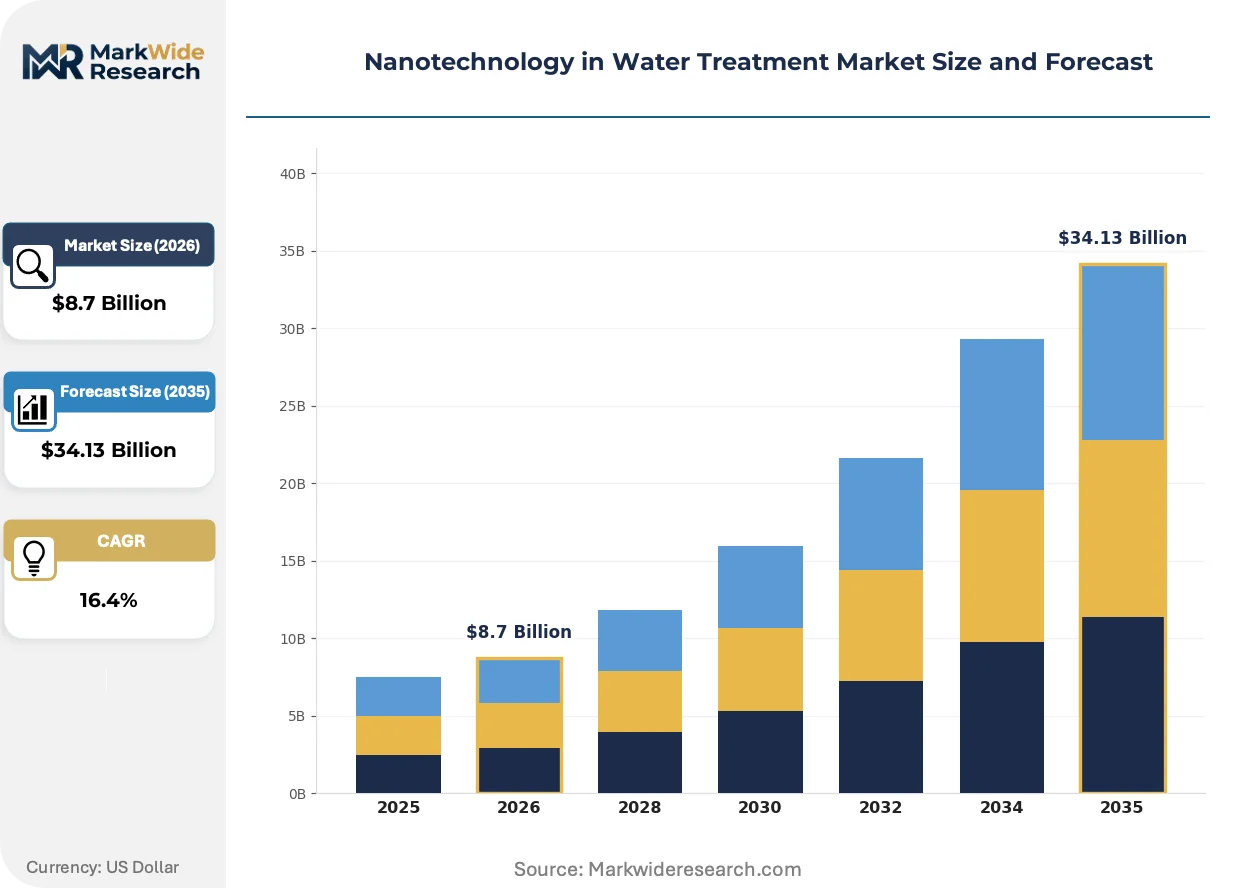
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Nanofiltration, Reverse Osmosis, Carbon Nanotubes, Photocatalysis Application: Desalination, Wastewater Treatment, Contaminant Removal, Water Purification End User: Municipalities, Industrial Facilities, Residential Users, Agricultural Sector Product Type: Membranes, Nanoparticles, Coatings, Devices |
| Companies Covered | Kran, Veolia Water Technologies, NanoH2O, Pentair, SUEZ, AquaB, Nanostone Water, Toray Industries, NSS Water Enhancement Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanotechnology in Water Treatment Market Shifts & Advancements
Carbon-based membrane architectures and photocatalytic surface engineering are compressing energy intensity thresholds while regulatory chemistry bans force material substitutions across manufacturing bases.
Graphene oxide composite membranes achieve selective ion transport through angstrom-precision interlayer spacing. Industrial facilities in semiconductor fabrication and pharmaceutical manufacturing adopt these stacks for high-purity process water. The technology is modularizing into standardized skid configurations that reduce field installation complexity and commissioning timelines.
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon blowing agents in membrane substrate production. Manufacturers reformulate polysulfone support layers with physical foaming agents to maintain porosity targets. European nanofiltration suppliers absorb reformulation costs while pursuing CE marking recertification under revised MDR-equivalent construction standards.
Subscription-based performance guarantees displace capital purchase models for municipal membrane installations. Saudi Arabia's National Water Regulator and India's state pollution control boards increasingly specify outcome-based contracts where vendors assume operational risk. Channel intermediaries in North American industrial distribution consolidate around cartridge replacement fulfillment to capture aftermarket value.
Nanotechnology in Water Treatment Market Segmentation
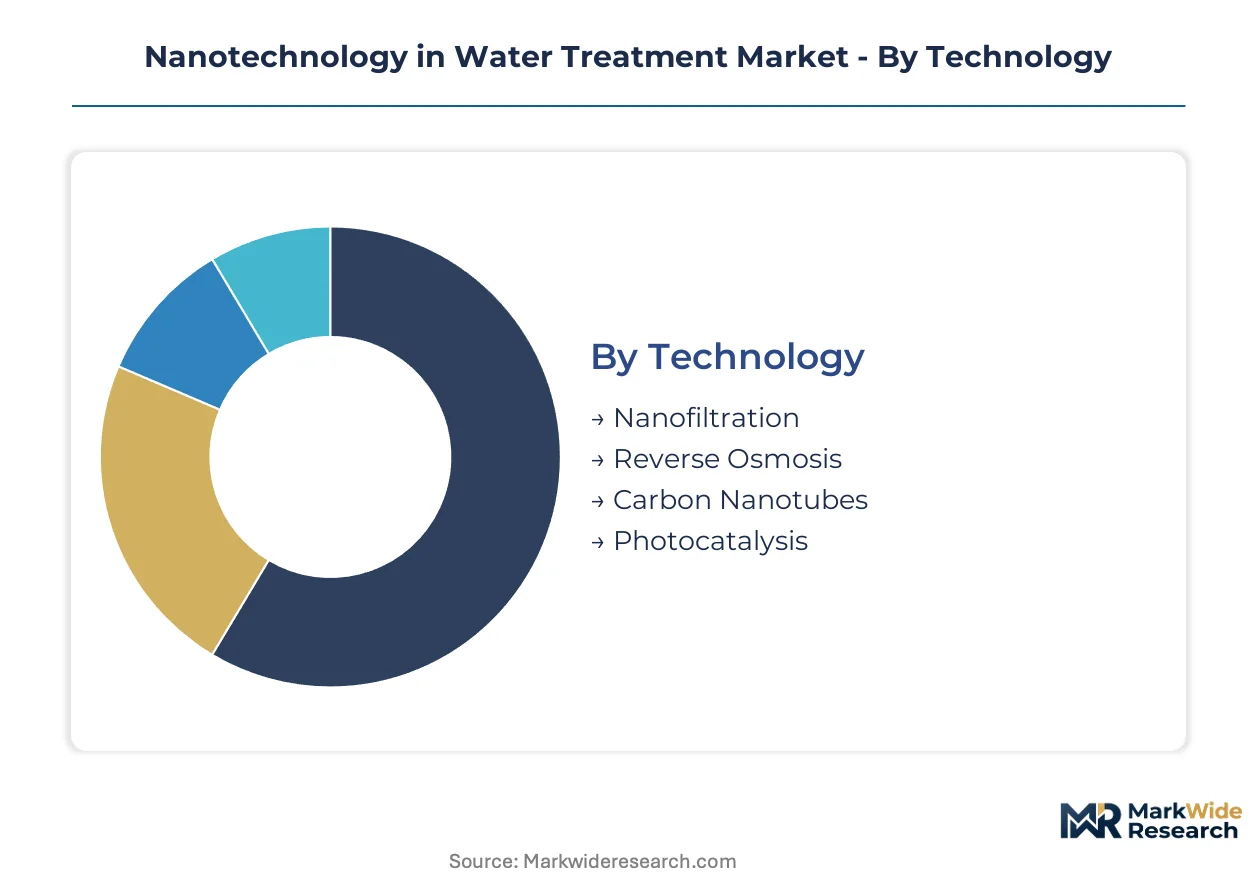
Capital allocation across nanotechnology water treatment segments varies sharply by technology maturity and infrastructure requirements. Procurement patterns diverge between municipalities seeking long-term asset life and industrial facilities prioritizing rapid commissioning cycles.
Technology:
Capital intensity peaks with membrane manufacturing infrastructure and specialized coating deposition equipment, while photocatalytic systems require lower upfront hardware investment but higher operational energy inputs.
- Nanofiltration:Polymeric thin-film composite membranes with molecular weight cut-offs between 200-1000 Daltons deliver selective divalent ion rejection. Saudi Arabia's National Water Regulator mandates this technology for agricultural reuse compliance, concentrating procurement in Kingdom desalination retrofits.
- Photocatalysis:UV-activated titanium dioxide coatings mineralize organic pollutants without chemical sludge generation. Industrial zero-liquid-discharge mandates in EU jurisdictions under REACH enforcement are accelerating facility-level adoption.
- Reverse Osmosis:Tighter pore architectures than nanofiltration achieve monovalent ion rejection for high-salinity seawater applications.
- Carbon Nanotubes:Vertically aligned arrays with pore densities exceeding 10⁹ pores per cm² enable tunable selectivity.
Most installed capacity flows through nanofiltration. Expansion is steepest in photocatalysis.
Application:
Contract structures vary by contamination risk profile, with contaminant removal commanding outcome-based pricing premiums against bulk desalination's volume-based tariffs.
- Contaminant Removal:Targeted PFAS and heavy metal capture using specialized membrane surface chemistries achieves regulatory compliance for EPA maximum contaminant levels. US municipal utilities facing binding enforcement timelines are consolidating procurement around certified membrane skids.
- Desalination:Thermal distillation substitution with membrane-based processes reduces energy intensity for brackish water treatment. Middle Eastern municipalities under national water strategy mandates are expanding nanofiltration procurement pipelines.
- Wastewater Treatment:Tertiary polishing for industrial effluent compliance with tightening discharge standards.
- Water Purification:Point-of-use and point-of-entry systems for residential and commercial quality assurance.
Contract value concentrates in contaminant removal. Volume expansion runs fastest in desalination.
End User:
Procurement authority structures shape vendor engagement models, from municipal tender boards with multi-year evaluation cycles to industrial facilities with delegated engineering procurement authority.
- Municipalities:Public sector procurement governed by EPA and EU Drinking Water Directive compliance schedules drives system-level contracting. Subscription-based performance guarantees are displacing capital purchase models in European and Middle Eastern jurisdictions.
- Industrial Facilities:Semiconductor fabrication and pharmaceutical manufacturing require high-purity process water with angstrom-level contaminant control. Graphene oxide composite membranes are modularizing into standardized skid configurations for rapid commissioning.
- Agricultural Sector:Irrigation water reuse mandates under Saudi Arabia's National Water Strategy create concentrated demand for tertiary treatment.
- Residential Users:Point-of-use devices and aftermarket cartridge replacement channels.
Revenue scale favors municipalities. Margin expansion is strongest in industrial facilities.
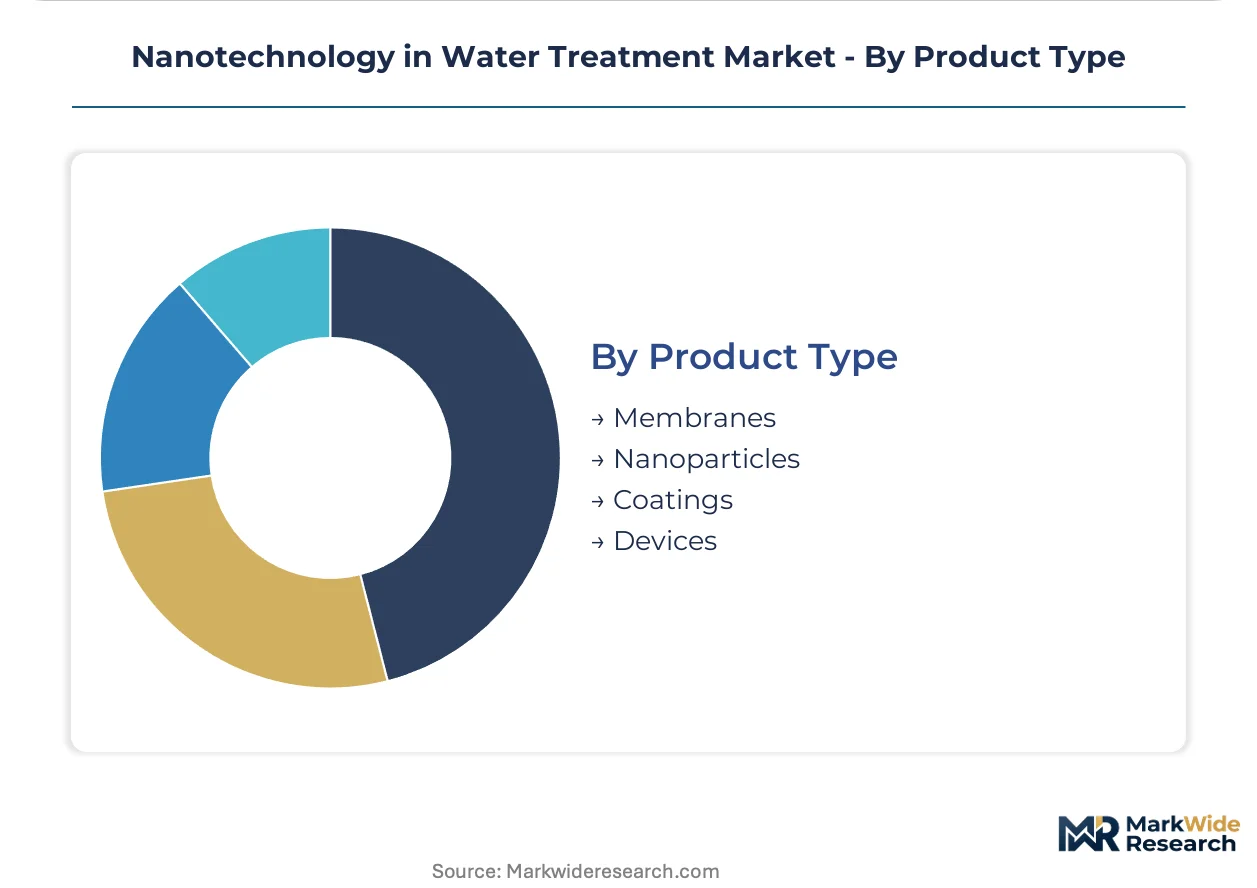
Product Type:
Aftermarket replacement economics differ materially between consumable cartridges with predictable refresh cycles and capital equipment with extended depreciation schedules.
- Membranes:Spiral-wound and hollow-fiber configurations dominate system value, with fouling degradation driving replacement frequency. North American industrial distribution channels are consolidating around cartridge replacement fulfillment.
- Coatings:Photocatalytic and antimicrobial surface treatments extend asset life while enabling regulatory compliance without hardware replacement.
- Nanoparticles:Dispersed metal oxides and carbon-based materials for adsorptive and reactive applications.
- Devices:Integrated systems combining multiple nanotechnologies with monitoring and control hardware.
Value capture concentrates in membranes. Technology differentiation is advancing fastest in coatings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's National Water Strategy concentrates procurement for agricultural reuse, while the United States enforces binding PFAS limits that trigger municipal membrane upgrades. Regulatory divergence between EPA, ECHA, and national water regulators shapes certification timelines and cross-border equipment flows.
United States
EPA maximum contaminant level enforcement drives nanofiltration procurement cycles across municipal utilities. The Office of Water mandates membrane certification requirements that directly shape supplier qualification timelines. California and Texas municipal water districts are consolidating system contracts around certified skids for PFAS compliance.
Saudi Arabia
Agricultural and industrial reuse mandates under the National Water Strategy concentrate tertiary treatment demand. The National Water Regulator tightens effluent standards that favor nanoparticle-enhanced membrane systems. Eastern Province desalination facilities are expanding nanofiltration retrofits for brackish water agricultural supply.
Germany
REACH restrictions on fluoropolymer precursors force membrane chemistry reformulation for European market access. ECHA oversight of perfluorinated compound manufacturing concentrates supply risk among limited coating suppliers. Industrial clusters in North Rhine-Westphalia are absorbing reformulation costs while pursuing CE marking recertification.
India
The Central Pollution Control Board tightens effluent standards for textile and pharmaceutical clusters. BIS certification requirements for membrane materials create approval bottlenecks for imported equipment. Maharashtra and Gujarat industrial zones are driving nanoparticle-enhanced tertiary treatment adoption for zero-liquid-discharge compliance.
United Arab Emirates
MOHAP and federal water authorities prioritize advanced treatment for municipal desalination expansion. Dubai and Abu Dhabi procurement pipelines specify outcome-based performance contracts with operational risk transfer to vendors. Northern Emirates municipalities are adopting subscription-based membrane monitoring platforms for remote desalination diagnostics.
Nanotechnology in Water Treatment Market Competitive Landscape
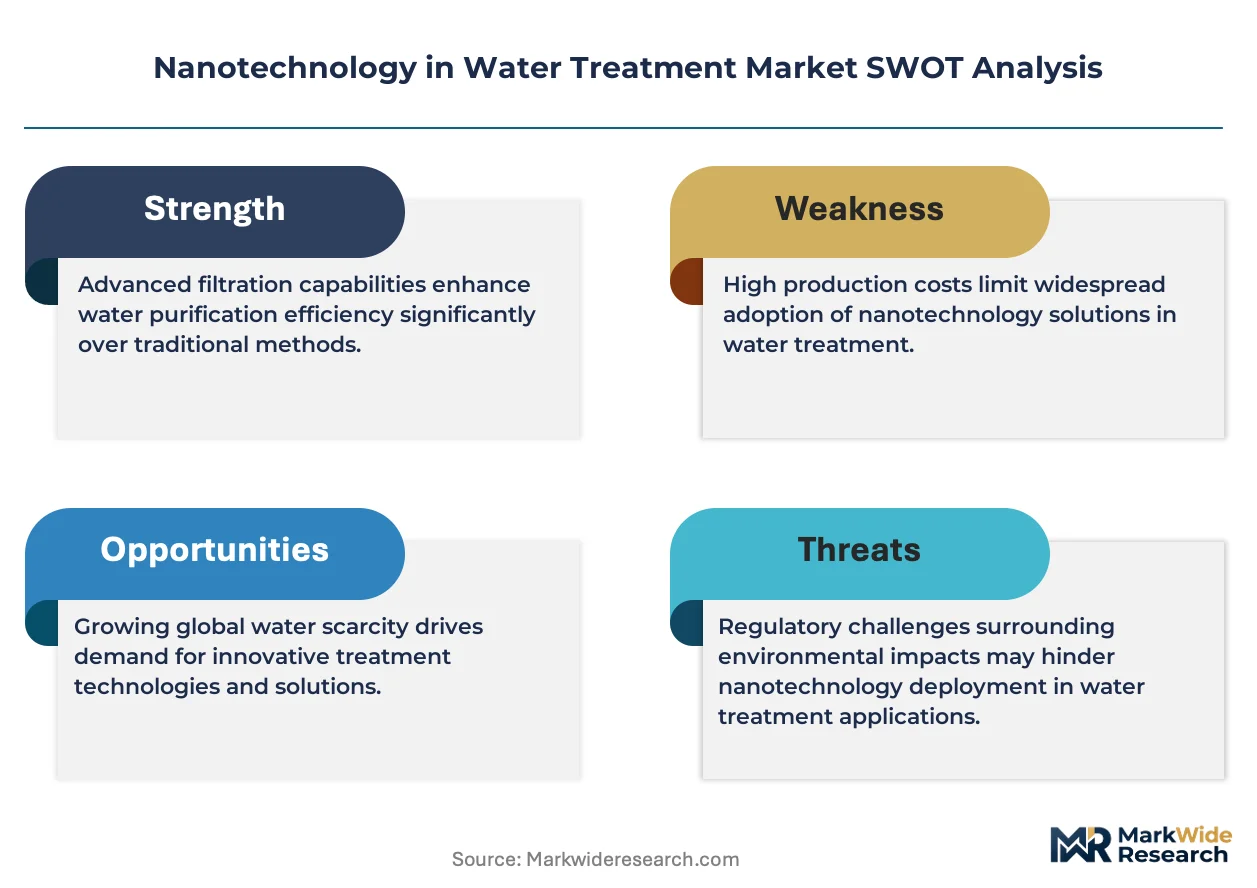
Top-tier vendors anchor municipal and industrial system integration, while mid-tier specialists concentrate on membrane material science and coating deposition. The competitive field organizes around three archetypes: diversified environmental service conglomerates with digital platform extensions, membrane-focused technology developers with proprietary nanomaterial architectures, and regional system integrators with localized aftermarket channels. Dominant competitive moves include chemistry reformulation to escape fluoropolymer feedstock dependence and geographic expansion through outcome-based contracting models.
Within the diversified environmental services tier, Veolia Water Technologies and SUEZ exemplify platform-centric positioning with recurring revenue architectures. Pentair anchors the North American industrial distribution vector through control of cartridge replacement channels. Among membrane-focused developers, NanoH2O and Nanostone Water occupy positions emphasizing proprietary nanomaterial configurations for selective contaminant capture.
| Leading Market Players |
|---|
| Kran |
| Veolia Water Technologies |
| NanoH2O |
| Pentair |
| SUEZ |
| AquaB |
| Nanostone Water |
| Toray Industries |
| NSS Water Enhancement Technology |
| Others |
Supply & Pricing Matrix
EPA PFAS maximum contaminant level enforcement is compressing procurement timelines for US municipal utilities, forcing membrane manufacturers to absorb chemistry reformulation costs while maintaining certified performance tiers. This demand-side pressure concentrates pricing power among suppliers with pre-qualified fluoropolymer-free coating portfolios.
Pricing Analysis
Capacity additions in Germany and Saudi Arabia are reshaping price floors for nanofiltration membranes as regional suppliers compete for municipal desalination contracts. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European systems from BIS-certified Indian assemblies and unmarked aftermarket cartridges. Price differentiation rests on certification tier and after-sales service bundling. Cost compression in standard-tier membranes is intensifying because REACH reformulation expenses flow through to end-user quotes. Industrial facilities demonstrate lowest price sensitivity due to zero-liquid-discharge compliance deadlines.
Supply Chain Analysis
Freight costs for spiral-wound membrane modules from German and Japanese manufacturing hubs have elevated landed costs for Middle Eastern desalination projects. Raw material sourcing draws from polysulfone resin producers in Germany, titanium dioxide refiners in China, and carbon nanotube growers in the United States. Single-source vulnerability concentrates in fluoropolymer precursor supply as ECHA restrictions consolidate European coating chemistry providers. Distribution runs through regional system integrators with localized aftermarket cartridge fulfillment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe create margin expansion opportunities for Saudi-certified suppliers serving price-sensitive Indian industrial clusters.
For Market Incumbents: Anchor market position through backward integration into polysulfone support layer manufacturing to escape fluoropolymer feedstock dependence. Deepen control of aftermarket cartridge replacement channels in North American industrial facilities to defend against emerging graphene oxide membrane specialists. For New Entrants and Emerging Players: Launch via subscription-based performance guarantee contracts targeting Maharashtra and Gujarat textile clusters under tightening Central Pollution Control Board enforcement. India's zero-liquid-discharge compliance gap represents the most penetrable entry vector for photocatalytic coating specialists. For Investors and Strategic Acquirers: Asymmetric upside sits with membrane-focused developers possessing proprietary carbon nanotube architectures and pre-qualified fluoropolymer-free coating chemistries. Five-to-ten year viability favors acquisition targets with established CE marking and Saudi National Water Regulator certification pipelines. Monitor EPA Office of Water membrane certification queue depth as inflection indicator for US municipal procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Chemistry Reformulation Program | Eliminates fluoropolymer dependence ahead of REACH phase-down deadlines in European jurisdictions. |
| Outcome-Based Contracting Expansion | Transfers operational risk to vendors while securing recurring revenue from Saudi and Indian municipal clients. |
| Predictive Maintenance Platform Deployment | Enables remote diagnostics for Middle Eastern desalination assets via SUEZ Oxyblue-equivalent architectures. |
| Graphene Oxide Membrane Scale-Up | Addresses semiconductor fabrication demand for angstrom-precision contaminant control in process water. |
| Regional Certification Pre-Qualification | Accelerates market access across EPA, ECHA, and Saudi National Water Regulator approval pipelines. |
Research Methodology
Coverage spans North America, Europe, Middle East, and South Asia, with primary inputs from each region combined with secondary validation. Interviews incorporated membrane manufacturing executives, municipal water utility procurement directors, industrial plant engineers, and aftermarket distribution channel managers. Secondary sources included EPA Office of Water certification databases, ECHA REACH restriction filings, Saudi National Water Regulator tender announcements, and customs trade data for membrane module imports. Bottom-up unit economics triangulated against top-down market sizing across technology and application segments.
Rate-of-change decomposition separated volume growth from price evolution across the projection horizon. Segmentation dimensions modeled include technology type, application category, end-user archetype, and regional regulatory cluster. CAGRs derived from installed base expansion rates, replacement frequency assumptions, and penetration curves for emerging technologies. Industry-specific inputs incorporated desalination capacity buildout pipelines, PFAS enforcement timelines, and zero-liquid-discharge mandate adoption curves.
Several conditions sit outside the modeled scope, including nanomaterial ecotoxicity protocol finalization delays, tariff regime modifications affecting membrane module trade flows, and breakthrough thermal distillation cost reductions. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology substitution elasticities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Internal Boiler Treatment Chemicals Market
Water & Sludge Treatment
Australia & New Zealand Water Treatment Chemicals Market
Water & Sludge Treatment
Global Industrial Sludge Treatment Chemicals Market
Water & Sludge Treatment
Global Wet Waste Management Market
Water & Sludge Treatment
India Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Polish Water Treatment Chemicals Market
Water & Sludge Treatment
Liquid Waste Container Market
Water & Sludge Treatment
Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Global Wood Activated Carbon Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Sludge Treatment and Disposal Equipment Market
Water & Sludge Treatment
China Water Treatment Chemicals Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market
Water & Sludge Treatment
United States Water Treatment Chemicals Market