
 Global Sludge Treatment Chemicals Market | 2026-2036
Global Sludge Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sludge Treatment Chemicals Market Foresight
Modular chemical dosing systems bundled with real-time sludge monitoring is realigning procurement patterns across municipal buyers. Kemira Oyj leverages its Nordic manufacturing scale to dominate polymer supply for Scandinavian utilities. BASF SE anchors its position through backward integration into acrylic acid feedstocks for flocculant production. Ecolab Inc. differentiates via service-intensive contracts that combine chemical delivery with on-site technical support.
Sludge treatment chemicals encompass coagulants, flocculants, pH adjusters, and disinfectants formulated to dewater, stabilize, and reduce the volume of residual solids from wastewater processes, typically dosed at concentrations calibrated to suspended solids load and target cake dryness. Their primary purpose is enabling compliant disposal or agricultural reuse while minimizing transportation and landfill costs. Coagulants occupy mature, price-sensitive positions in municipal applications where aluminum- and iron-based salts face substitution pressure from organic alternatives. Flocculants represent higher-margin growth pockets as high-molecular-weight polyacrylamides displace conventional lime in advanced dewatering centrifuge operations. Polymer emulsions in liquid delivery form capture expanding share in automated dosing systems across European and North American water treatment plants.
EPA Clean Water Act discharge limits, EU Urban Wastewater Treatment Directive revisions, and China's MEE sludge disposal standards collectively tighten permissible contaminant thresholds and mandate phosphorus recovery, directly expanding chemical consumption per dry ton processed. BIS effluent regulations in India and WHO guidelines on safe sludge reuse in agriculture further fragment compliance requirements across export-oriented suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether localized formulation registration or technology licensing offers superior capital efficiency.
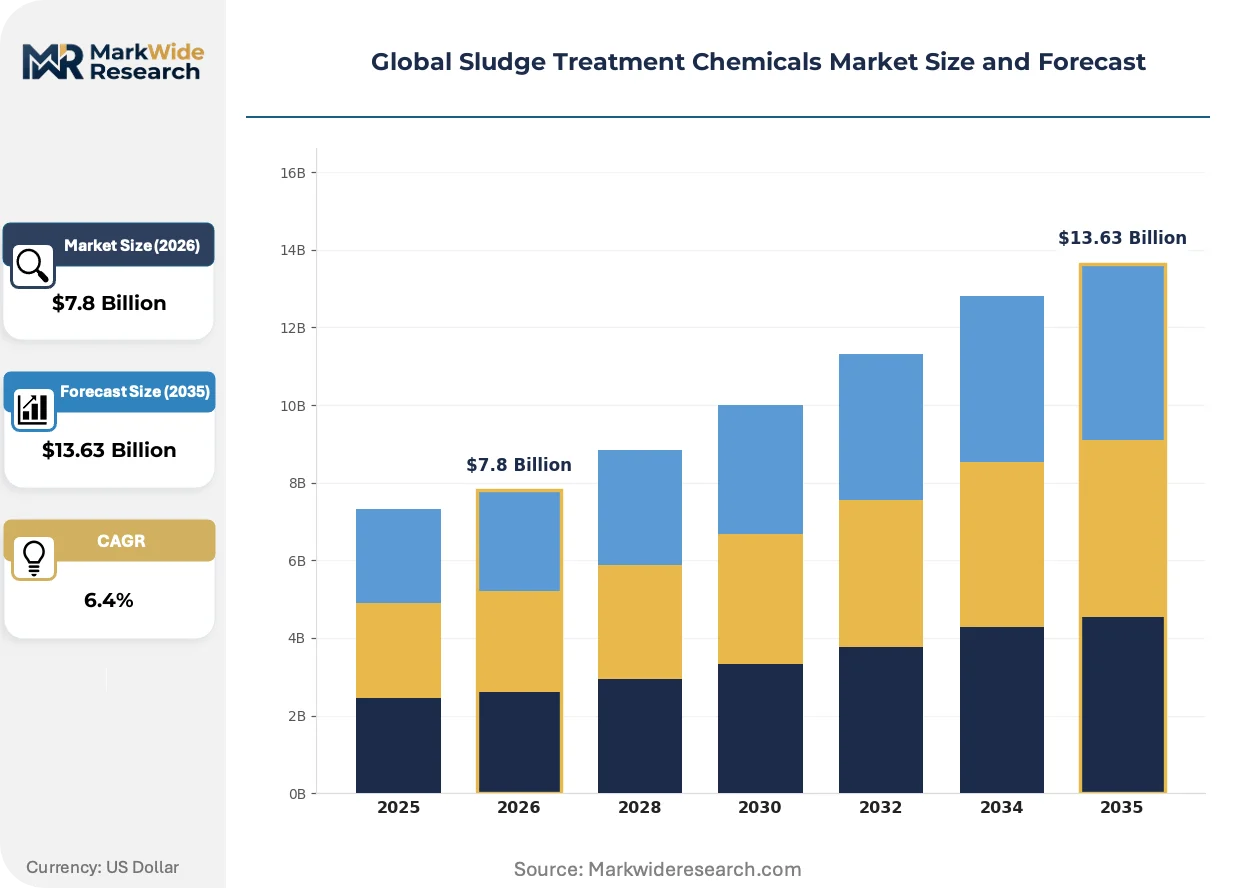
Market Dynamics
Stringent phosphorus recovery mandates under revised EU Urban Wastewater Treatment Directive and China's MEE sludge disposal standards are forcing municipal utilities to triple chemical dosing intensity per dry ton processed, compressing operating margins while expanding absolute volume demand.
Growth Catalysts
- EU Directive Revisions:The Urban Wastewater Treatment Directive's phosphorus recovery mandates require German, Dutch, and Danish utilities to deploy enhanced coagulation and flocculant regimes. This regulatory pressure directly expands chemical consumption per treatment plant.
- Dual Carbon Goals:China's provincial treatment networks are accelerating anaerobic digestion chemical demand as MEE standards tighten disposal thresholds. Municipal operators in Jiangsu and Zhejiang provinces represent concentrated demand pockets.
- BIS Standards:India's Bureau of Indian Standards effluent regulations for Ganga basin cities are concentrating coagulant and flocculant procurement. Kanpur, Varanasi, and Patna utilities face compliance deadlines driving chemical volume.
Market Restraints
- Acrylonitrile Feedstock Volatility:Polyacrylamide flocculant production depends on acrylonitrile prices tied to propylene markets. Petrochemical input swings compress formulation margins unpredictably.
- Aluminum Salt Substitution Pressure:Iron-based and organic coagulants are displacing aluminum sulfate in municipal applications. Legacy aluminum producers face volume erosion in price-sensitive segments.
- REACH Registration Burden:European Chemicals Agency polymer registration requirements create compliance friction for specialty flocculant entrants. Small-scale Asian suppliers encounter market access barriers.
Strategic Opportunities
- Automated Dosing Convergence:Integration of polymer emulsion chemistry with real-time suspended solids monitoring creates bundled procurement packages. European water treatment plants lead adoption of closed-loop dosing systems.
- Phosphorus Recovery Chemicals:Struvite precipitation chemicals represent underdeveloped white space. Netherlands and Germany pilot plants demonstrate viable revenue streams from recovered nutrient products.
- Service-Intensive Contracts:Chemical delivery bundled with on-site technical support and dewatering optimization captures premium pricing. North American industrial wastewater operators show preference for performance-guaranteed arrangements.
Industry Challenges
- Polymer Chemist Scarcity:Formulation expertise for high-molecular-weight polyacrylamide design concentrates among aging specialists. Recruitment pipelines fail to replace retiring technical talent.
- Legacy Dosing Infrastructure:Manual lime-based systems in older North American and European plants resist automation retrofit. Capital allocation conflicts delay chemical conversion timelines.
- Multi-Jurisdiction Registration:Divergent polymer safety assessments across EPA, ECHA, and China's MEE create redundant toxicology expenditure. Registration cost duplication burdens mid-scale suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sludge Treatment Chemicals Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Chemical Type: Flocculants, Coagulants, Polymers, pH Adjusters, Disinfectants Application: Municipal Wastewater, Industrial Effluent, Agricultural Runoff, Food Processing, Textile Manufacturing End User Industry: Water Treatment Plants, Paper & Pulp Facilities, Chemical Manufacturing, Mining Operations Delivery Form: Liquid, Powder, Granular, Emulsions |
| Companies Covered | Kemira Oyj, BASF SE, Ecolab Inc., Ashland Inc., Kurita Water Industries Ltd, SNF Group, Veolia Environnement S.A., Accepta Ltd, Hubbard-Hall Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sludge Treatment Chemicals Market Shifts & Advancements
Digital dosing control systems are converging with advanced polymer chemistry to enable real-time sludge characterization and automated chemical adjustment, fundamentally altering how municipal utilities specify and procure treatment chemicals.
Smart polymer emulsion technology is integrating spectroscopic suspended solids sensors with variable-rate dosing pumps. Scandinavian utilities in Sweden, Norway, and Denmark deploy these systems at scale. The technology is integrating cake dryness optimization with labor reduction, compressing total dewatering costs per dry ton.
REACH polymer registration requirements and EPA Clean Water Act discharge limit tightening are mandating comprehensive ecotoxicology documentation for flocculant chemistries. Industrial consequence includes extended product development timelines and elevated registration expenditure. Specialty polymer suppliers serving German and French municipal markets are consolidating formulation portfolios to focus on highest-volume registered products.
Municipal procurement teams are unbundling chemical supply from equipment service contracts that historically locked utilities into single-source arrangements. North American water treatment plants now separate polymer procurement from centrifuge maintenance agreements. This pattern is most visible in California and Texas utilities seeking competitive bidding transparency.
Global Sludge Treatment Chemicals Market Segmentation
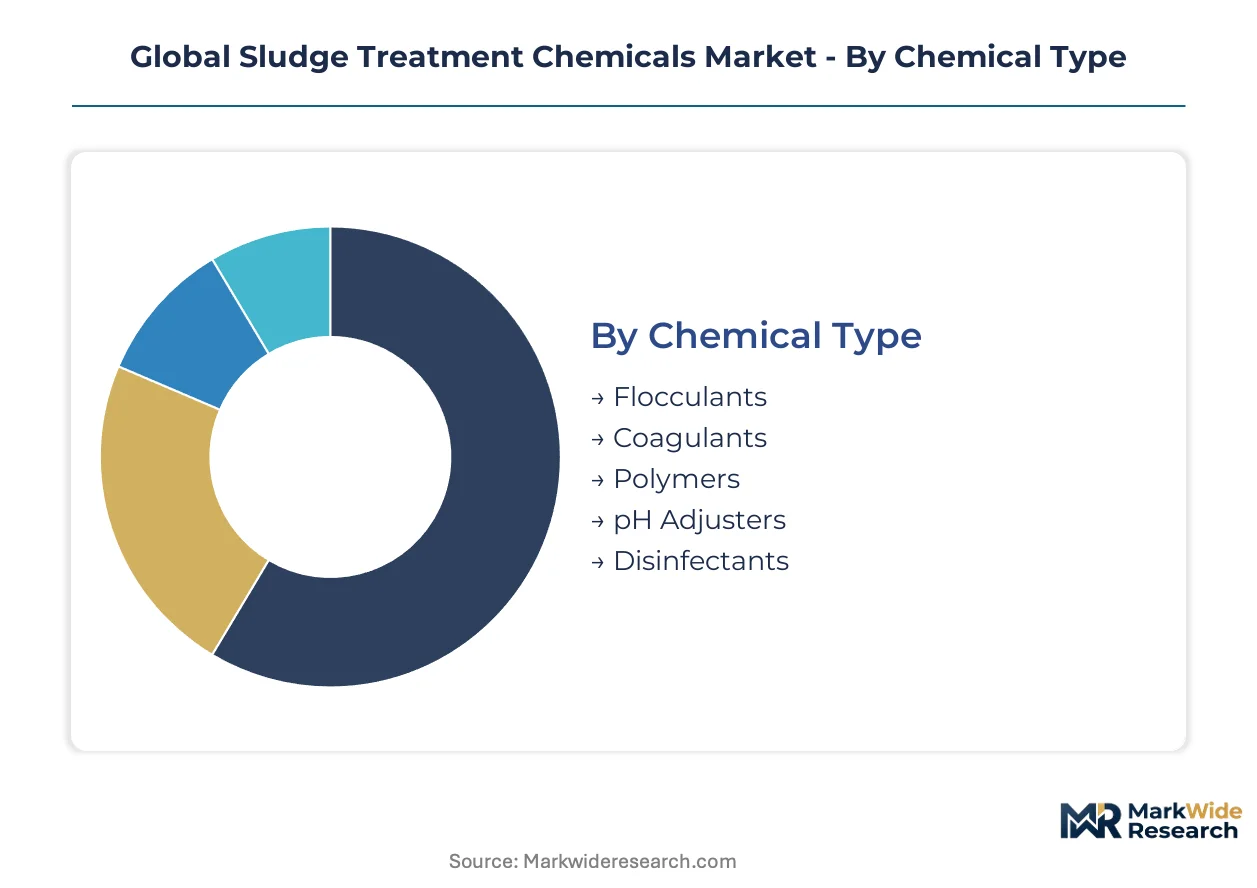
Sludge treatment chemicals segment along four interlocking dimensions that determine procurement specifications, dosing infrastructure requirements, and supplier qualification criteria. Chemical type dictates formulation chemistry and regulatory registration burden. Application context shapes performance requirements and compliance thresholds. These segmentation layers collectively determine pricing architecture and contract structure across municipal and industrial buyers.
Chemical Type:
Procurement teams prioritize dewatering efficiency and cake dryness targets when selecting chemical categories, with polymer performance specifications dominating technical evaluation criteria.
- Flocculants:High-molecular-weight polyacrylamides aggregate fine suspended solids into settleable flocs through charge neutralization and bridging mechanisms. Demand concentrates in German, Dutch, and Danish municipal utilities deploying advanced centrifuge dewatering under EU phosphorus recovery mandates. These formulations command premium pricing against conventional alternatives due to superior cake dryness performance and reduced transportation costs.
- Coagulants:Aluminum- and iron-based salts destabilize colloidal particles through charge neutralization, forming dense precipitates suitable for primary clarification and thickening operations. Indian Ganga basin cities including Kanpur, Varanasi, and Patna are concentrating procurement as BIS effluent deadlines approach, though substitution pressure from organic alternatives constrains legacy aluminum sulfate volumes in price-sensitive segments.
- Polymers:Synthetic and natural long-chain molecules enhance flocculation kinetics and solids capture efficiency across diverse sludge matrices. Paper and pulp facilities in Scandinavia represent concentrated demand for cationic polymer variants optimized for fiber-laden waste streams.
- pH Adjusters:Sulfuric acid, caustic soda, and lime compounds condition sludge matrices for optimal coagulant and flocculant performance. Mining operations in Australia and Canada deploy these chemicals for acid mine drainage neutralization and metal precipitation.
- Disinfectants:Chlorine-based and peroxygen compounds reduce pathogen loads in biosolids destined for agricultural land application. WHO guidelines on safe sludge reuse are expanding specification requirements across developing economy treatment networks.
Flocculants lead on scale; coagulants lead on momentum as organic substitution accelerates.
Application:
Regulatory stringency and disposal cost structures vary dramatically across application contexts, fragmenting chemical specification requirements and supplier qualification protocols.
- Municipal Wastewater:Biological and chemical sludge streams from activated sludge and anaerobic digestion processes require comprehensive dewatering, stabilization, and disinfection chemical regimes. China's provincial treatment networks in Jiangsu and Zhejiang are expanding anaerobic digestion chemical demand under MEE disposal standard tightening.
- Industrial Effluent:Heavy metal-laden, oily, or chemically complex sludge matrices demand specialized coagulant and flocculant formulations with targeted contaminant affinity. North American petroleum refineries and petrochemical complexes represent concentrated demand for emulsion-breaking polymer systems.
- Agricultural Runoff:Nutrient-saturated sediments and livestock waste slurries require phosphorus-binding and solids-liquid separation chemicals. Netherlands pilot plants are demonstrating struvite precipitation chemical viability for nutrient recovery from agricultural drainage.
- Food Processing:High-organic, grease-laden sludge from dairy, meat, and beverage operations demands specialized flocculant chemistries compatible with anaerobic digestion biogas production. Scandinavian food sector clusters are adopting automated polymer dosing systems.
- Textile Manufacturing:Dye-laden and chemically complex sludge streams from finishing and dyeing operations require heavy metal precipitants and color-removing coagulants. Tamil Nadu and Gujarat industrial zones in India are concentrating procurement as state pollution control boards enforce zero-liquid-discharge mandates.
Municipal wastewater dominates absolute volume; food processing gains share fastest through automation convergence.
End User Industry:
Capital intensity and technical staffing levels across end-user facilities determine preference for bundled service contracts versus commodity chemical procurement.
- Water Treatment Plants:Municipal and industrial facilities with dedicated operations teams specify chemicals based on total dewatering cost optimization and cake dryness targets. California and Texas utilities are unbundling polymer procurement from centrifuge maintenance agreements to enhance bidding transparency.
- Paper & Pulp Facilities:Fiber-recovery and primary clarification operations consume substantial flocculant volumes for white water treatment and sludge dewatering. Nordic integrated mills leverage Kemira's regional manufacturing scale for polymer supply security.
- Chemical Manufacturing:Process wastewater with variable composition and intermittent discharge patterns demands flexible dosing systems and rapid-response technical support. German chemical parks are consolidating chemical procurement across tenant facilities.
- Mining Operations:Tailings thickening and acid mine drainage treatment require high-dose coagulant regimes and specialized pH adjustment protocols. Western Australian iron ore and Chilean copper concentrators represent concentrated demand for high-density slurry flocculants.
Water treatment plants anchor volume demand; mining operations expand most quickly through tailings reprocessing mandates.
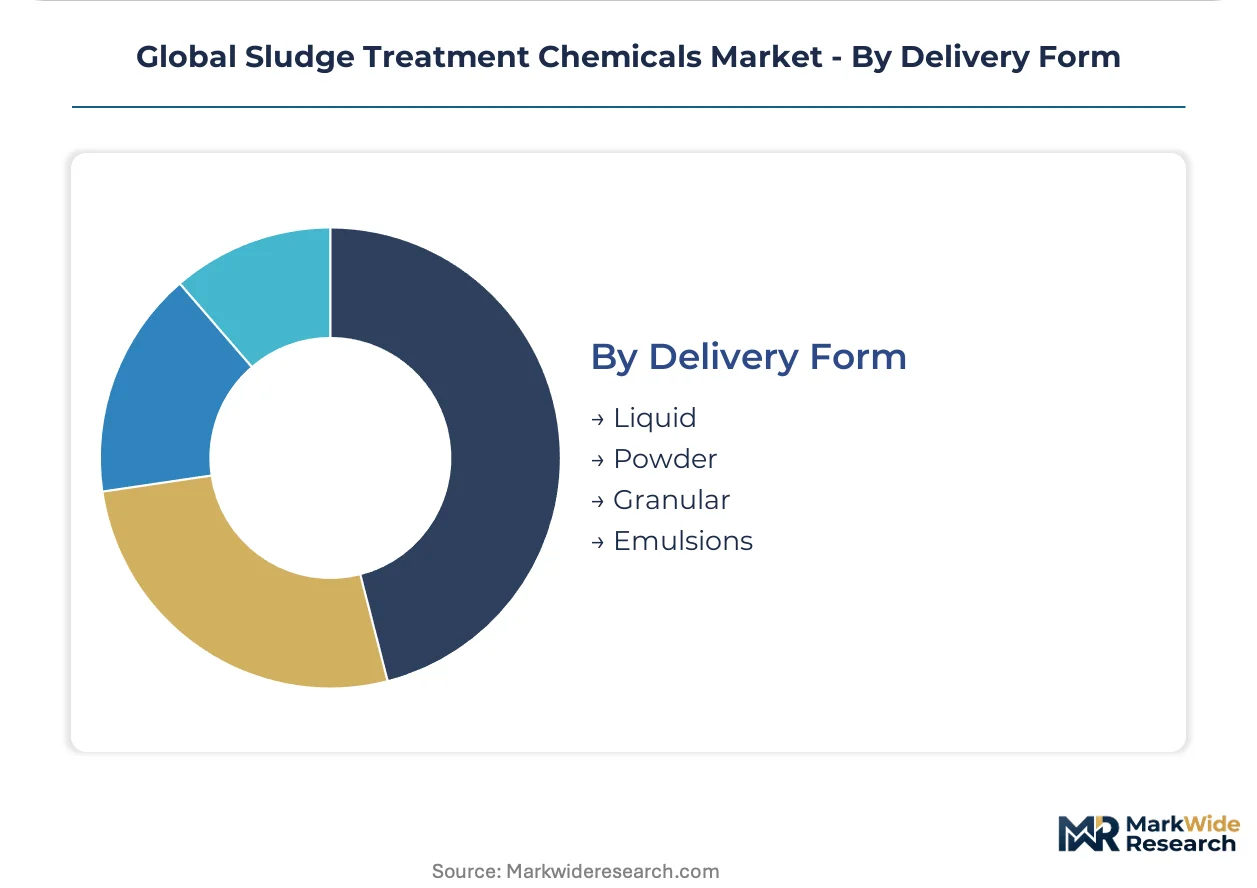
Delivery Form:
Dosing infrastructure maturity and labor cost economics drive form selection, with automated systems favoring liquid and emulsion formats over manual powder handling.
- Liquid:Ready-to-dose aqueous solutions eliminate dissolution equipment requirements and reduce operator exposure to dust hazards. European water treatment plants with advanced automation infrastructure are capturing expanding share for liquid polymer delivery.
- Powder:Concentrated dry formulations reduce transportation costs and storage footprint but require dedicated dissolution systems and skilled operators. Legacy North American lime-based installations resist conversion due to capital allocation conflicts.
- Granular:Free-flowing solid forms with controlled dissolution kinetics suit remote mining and agricultural applications with intermittent dosing requirements. Australian and Canadian mining camps favor granular formats for logistics simplicity.
- Emulsions:Oil-continuous polymer dispersions enable high-molecular-weight product delivery in pumpable form, optimizing performance in high-shear dewatering equipment. Scandinavian utilities are deploying emulsion-based systems with real-time suspended solids monitoring for closed-loop dosing optimization.
Liquid formulations dominate procurement volume; emulsions climb the fastest through smart dosing system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered large-scale municipal chemical dosing infrastructure under early EU wastewater directives. This established the operational template now diffusing across high-regulation jurisdictions worldwide.
Germany
Dutch and Danish utilities are expanding coagulant procurement under revised phosphorus recovery mandates. The EU Urban Wastewater Treatment Directive revisions force tripled chemical intensity per dry ton processed. Municipal operators in North Rhine-Westphalia and Bavaria are retrofitting plants with automated polymer dosing systems.
China
Jiangsu and Zhejiang provincial treatment networks are accelerating anaerobic digestion chemical demand. The Ministry of Ecology and Environment tightened sludge disposal standards under dual carbon goals. Municipal operators in the Yangtze River Delta are deploying enhanced flocculant regimes for phosphorus capture.
India
Kanpur, Varanasi, and Patna utilities are concentrating coagulant and flocculant procurement. The Bureau of Indian Standards effluent regulations for Ganga basin cities impose compliance deadlines. State pollution control boards in Uttar Pradesh and Bihar are enforcing zero-liquid-discharge mandates for textile clusters.
United States
California and Texas utilities are unbundling polymer procurement from centrifuge maintenance agreements. The EPA Clean Water Act discharge limits tighten permissible contaminant thresholds. Municipal water treatment plants in the Southwest are capturing expanding share for liquid polymer delivery formats.
Netherlands
Struvite precipitation chemicals represent underdeveloped demand pockets in pilot plant networks. REACH polymer registration requirements mandate comprehensive ecotoxicology documentation. Municipal utilities in Randstad are deploying closed-loop dosing systems with real-time suspended solids monitoring.
Global Sludge Treatment Chemicals Market Competitive Landscape
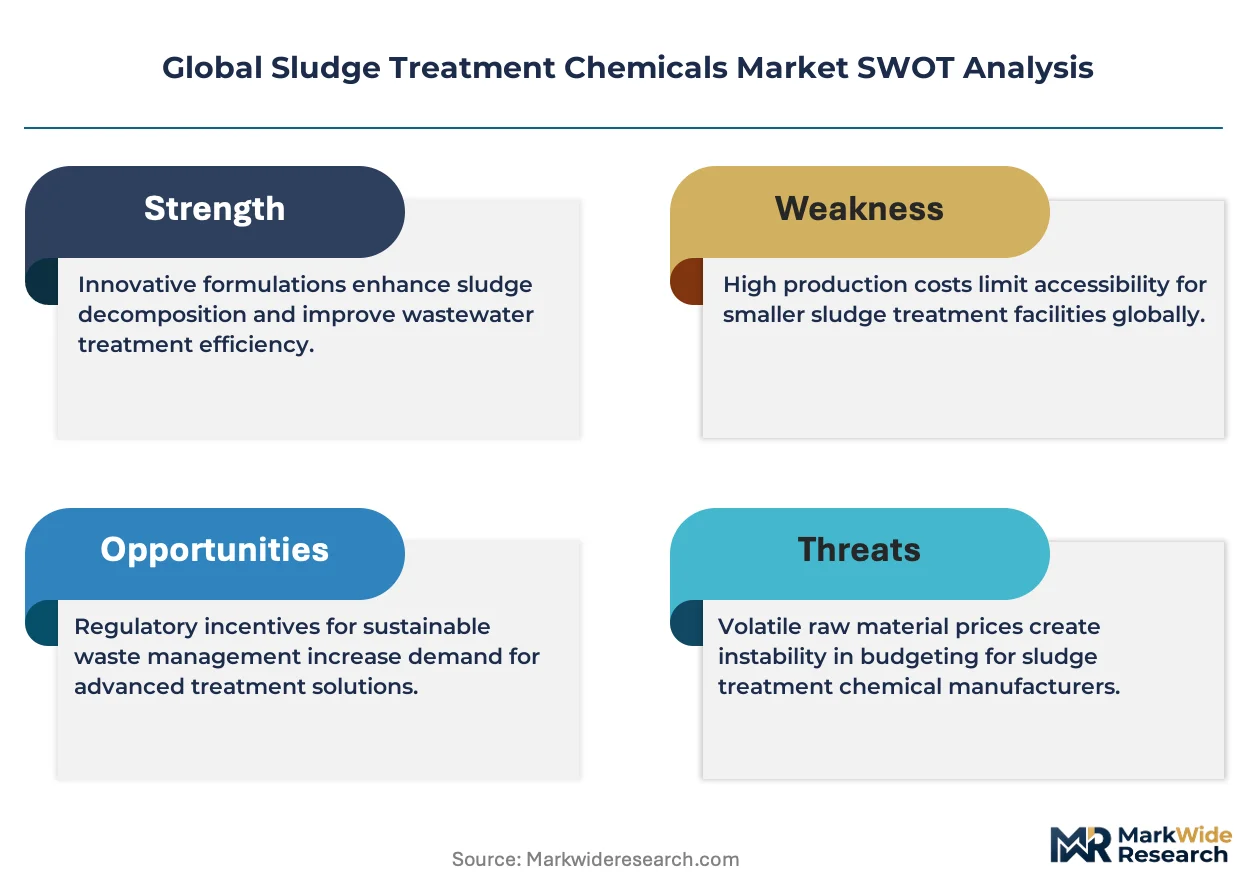
The competitive structure tilts toward integrated chemical suppliers with captive feedstock positions. Market concentration clusters among Nordic and German industrial conglomerates with backward integration into acrylic acid and acrylonitrile supply chains. Three archetypes dominate: polymer specialists with formulation depth, diversified chemical majors with service bundling capabilities, and regional water treatment integrators with utility contracting expertise. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with European players prioritizing REACH-registered product consolidation.
Among Nordic-integrated suppliers, Kemira Oyj and BASF SE exemplify the feedstock-anchored archetype. Kemira leverages regional manufacturing scale for polymer supply security across Scandinavian utilities. BASF SE occupies a position defined by upstream control over acrylic acid feedstocks for flocculant production. Ecolab Inc. represents the service-intensive tier, anchoring its positioning through bundled chemical delivery contracts with on-site technical support components.
| Leading Market Players |
|---|
| Kemira Oyj |
| BASF SE |
| Ecolab Inc. |
| Ashland Inc. |
| Kurita Water Industries Ltd |
| SNF Group |
| Veolia Environnement S.A. |
| Accepta Ltd |
| Hubbard-Hall Inc. |
| Others |
Supply & Pricing Matrix
Polymer chemist scarcity in the Rhine-Ruhr industrial corridor amplifies labor-cost differentials between premium formulation houses and commodity coagulant suppliers, widening pricing-tier spreads across the European market.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with price differentiation driven by REACH registration status and cake dryness performance guarantees. Cost compression in the economy tier is intensifying because aluminum sulfate faces substitution pressure from iron-based and organic alternatives. Municipal utilities in price-sensitive segments exhibit highest price sensitivity, while Scandinavian water treatment plants with automation infrastructure show lowest sensitivity due to total dewatering cost optimization priorities.
Supply Chain Analysis
REACH polymer registration requirements and EPA ecotoxicology documentation create qualification gating that filters supplier participation. Manufacturing concentrates in Germany, China, and the United States for high-molecular-weight polyacrylamide production. Acrylonitrile feedstock supply draws from propylene markets tethered to regional petrochemical complexes. Single-source vulnerability around acrylonitrile exposes formulation margins to commodity volatility. Distribution runs through regional chemical distributors with technical service capabilities and direct mill-to-plant contracts for large municipal accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Sludge Treatment Chemicals Market operates as a stable compounder, with regulatory tightening of phosphorus recovery mandates across EU and Chinese jurisdictions ensuring steady volume expansion per dry ton processed.
For Market Incumbents: Cement feedstock security through backward integration into acrylic acid supply chains or long-term offtake agreements with propylene derivatives producers. Expand automated dosing system partnerships with Scandinavian utilities to lock in polymer emulsion volumes against emerging Asian suppliers. Prioritize REACH-registered product portfolio consolidation to defend margin position against specialty entrants facing registration cost barriers. For New Entrants and Emerging Players: Smart polymer emulsion technology with integrated suspended solids sensing offers a technology-first wedge into the European municipal automation upgrade cycle. Target struvite precipitation chemicals for phosphorus recovery in Netherlands and German pilot plant networks as the most penetrable white space. Pursue service-intensive contract structures bundling chemical delivery with on-site dewatering optimization to bypass incumbent supply relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional water treatment integrators with utility contracting expertise but limited formulation depth. The five-to-ten year viability framing favors suppliers with captive feedstock positions and multi-jurisdiction registration portfolios. Monitor acrylonitrile price volatility as the key inflection signal for margin compression risk across polyacrylamide-dependent players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid Feedstocks | BASF SE anchors flocculant production cost position through captive supply of polymer precursors. |
| Automated Dosing System Partnerships | Kemira Oyj captures Scandinavian utility volume through real-time sludge monitoring integration. |
| REACH-Registered Product Consolidation | Specialty suppliers streamline portfolios to focus on highest-volume registered chemistries for German and French markets. |
| Service-Intensive Contract Expansion | Ecolab Inc. differentiates via bundled chemical delivery with on-site technical support for North American industrial operators. |
| Struvite Precipitation Chemical Development | Netherlands pilot plants demonstrate viable revenue streams from recovered nutrient products under EU phosphorus mandates. |
Research Methodology
Bottom-up municipal and industrial modeling reconciled against top-down polymer production tracking forms the analytical core of this study. Primary interviews with plant managers at water treatment facilities, procurement leads at downstream paper and pulp mills, distribution channel partners, and technical R&D directors at formulation houses informed demand-side assumptions. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC filings, and national environmental agency discharge records. Triangulation between bottom-up end-use consumption estimates and top-down manufacturer shipment data ensured consistency across the analysis window.
Input-output matrices mapped chemical type, application context, end-user industry, and delivery form against regional regulatory clusters to generate segment-level projections. CAGRs were derived from regression analysis of historical dosing intensity trends against regulatory tightening schedules. Forecast inputs incorporated anaerobic digestion capacity expansion in Chinese provincial networks, BIS effluent compliance deadlines for Indian Ganga basin cities, and automation retrofit adoption curves across European water treatment plants.
The model holds under stable petrochemical feedstock pricing and continued regulatory enforcement; deviation in acrylonitrile volatility or suspension of phosphorus recovery mandates would shift volume and margin trajectories. A model refresh is warranted upon material change in EU Urban Wastewater Treatment Directive implementation timelines or MEE sludge disposal standard revisions in China.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Semiconductor Wastewater Treatment Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Water Dispersible Granules Market
Water & Sludge Treatment
North America Water Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Chemicals Market
Water & Sludge Treatment
South America Membrane Water and Wastewater (WWT) Treatment Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
US Sludge Management and Dewatering Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market
Water & Sludge Treatment
Asia-Pacific Drilling Waste Management Services Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Slurry Heaters Market