
 US Water and Wastewater Treatment Chemicals Market | 2026-2036
US Water and Wastewater Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
US Water and Wastewater Treatment Chemicals Market Insights
Municipal procurement consolidation across Midwestern and Southeastern water authorities is decoupling from traditional distributor channels. Ecolab sustains its position through service-integrated chemical programs that lock in multi-year municipal contracts. Dow leverages its Gulf Coast petrochemical integration to dominate bulk coagulant supply chains. Solenis specializes in paper and pulp wastewater applications where its on-site technical service model creates switching costs.
Water and wastewater treatment chemicals comprise formulated substances designed to remove contaminants, adjust pH, disinfect pathogens, or precipitate solids from water streams, with active concentrations typically ranging from percent-level solutions to near-neat formulations depending on application intensity. These chemicals serve essential functions in maintaining public health standards, protecting industrial equipment from scaling and corrosion, and ensuring environmental compliance before discharge. Coagulants and flocculants anchor municipal water treatment operations where suspended solids removal drives the largest volume demand, while disinfectants command premium positioning in drinking water applications due to stringent residual chlorine and alternative oxidant requirements. pH control agents represent a mature, cost-competitive segment where regional lime and caustic soda suppliers compete on logistics proximity rather than formulation differentiation.
EPA regulations under the Safe Drinking Water Act and Clean Water Act mandate maximum contaminant levels and pretreatment standards that directly determine chemical selection, dosage rates, and monitoring protocols across municipal and industrial facilities. The Department of Energy's efficiency standards for power plant cooling systems intersect with NPDES permits to create layered compliance obligations that favor multi-functional treatment chemistries. State-level primacy agencies in Texas, California, and Pennsylvania add supplementary testing and reporting requirements that fragment procurement specifications. Stakeholders must monitor emerging PFAS regulations and the EPA's forthcoming effluent limitation guidelines for steam electric power generation, as these frameworks will force replacement of legacy chemistries and open contracting opportunities for suppliers with demonstrated analytical and technical support capabilities.
Market Dynamics
The EPA's Lead and Copper Rule revisions are forcing municipal utilities to accelerate chemical procurement for corrosion control and filtration upgrades, restructuring supplier relationships around technical service capabilities rather than commodity pricing.
Growth Catalysts
- Aging Infrastructure Mandates:The EPA's Lead and Copper Rule revisions compel municipal utilities across the Great Lakes industrial corridor to upgrade treatment systems, expanding demand for phosphate-based corrosion inhibitors and advanced coagulants.
- Industrial Wastewater Intensification:Legacy manufacturing clusters in Michigan and Ohio generate concentrated effluent streams requiring specialized metal precipitation chemistries and enhanced biological nutrient removal formulations.
- PFAS Regulatory Tailwinds:Emerging state-level maximum contaminant limits for per- and polyfluoroalkyl substances in Michigan and New Jersey are accelerating adoption of activated carbon and ion exchange pretreatment chemicals.
Market Restraints
- Chlor-Alkali Feedstock Volatility:Caustic soda and chlorine prices track Gulf Coast electricity and salt costs, compressing margins for pH adjustment and disinfection chemical producers during energy price spikes.
- Gulf Coast Supply Concentration:Bulk aluminum sulfate and ferric chloride production clusters along the Texas and Louisiana petrochemical corridor create hurricane-related disruption risks for Midwestern municipal buyers.
- Legacy Fluorosurfactant Substitution Limits:PFAS-free foam formulations for industrial fire suppression remain technically immature, delaying full chemical transitions at airports and military installations.
Strategic Opportunities
- Appalachian Shale Brine Processing:Produced water from Pennsylvania and West Virginia oil and gas operations represents an underpenetrated feedstock source for recovered coagulants and magnesium hydroxide recovery systems.
- Smart Dosing System Convergence:Integration of real-time turbidity sensors with automated polymer feed controls enables predictive chemical optimization at small and medium municipal plants.
- Buy America Procurement Preferences:The EPA's Infrastructure Investment and Jobs Act implementation favors domestic chemical manufacturers with certified domestic content for federal water infrastructure grants.
Industry Challenges
- Analytical Chemist Talent Scarcity:Municipal utilities struggle to recruit operators capable of running LC-MS/MS instrumentation for emerging contaminant monitoring under revised Unregulated Contaminant Monitoring Rule requirements.
- Legacy SCADA Integration Friction:Cloud-based chemical inventory management platforms face interoperability barriers with decades-old control systems at mid-sized treatment plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Water and Wastewater Treatment Chemicals Market |
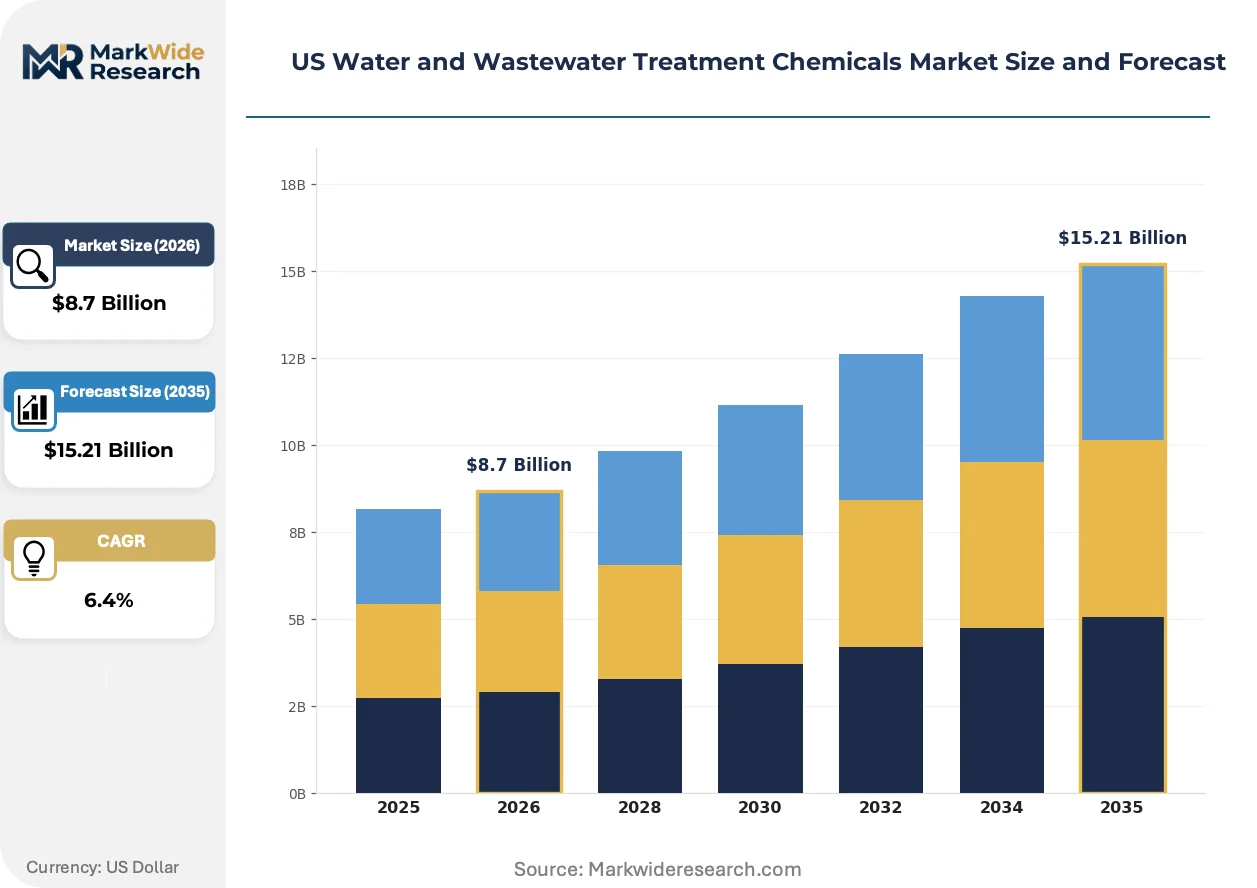
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, Disinfectants, pH Control Agents Application: Municipal Water Treatment, Industrial Wastewater Treatment, Drinking Water, Sewage Treatment Form: Liquid, Powder, Granular, Tablets End User: Municipalities, Power Plants, Food Industry, Manufacturing Sector |
| Companies Covered | Veolia, BASF, Ecolab, Dow, Kurita Water Industries, Solenis, SNF, ChemTreat, Kemira, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Water and Wastewater Treatment Chemicals Market Trends and Innovations
On-site chemical generation systems and predictive dosing algorithms are compressing traditional bulk chemical delivery models, while regulatory pressure on persistent contaminants forces formulation reinvention across municipal and industrial segments.
Electrochlorination technology is decentralizing sodium hypochlorite production for municipal disinfection. Mid-sized utilities in Florida and Arizona are adopting skid-mounted brine electrolysis systems to eliminate bulk bleach transportation and storage liabilities. This shift is decentralizing supply chain risk and reducing per-gallon delivered costs for plants serving populations between 50,000 and 200,000.
The EPA's forthcoming effluent limitation guidelines for steam electric power generation will tighten discharge limits for selenium, mercury, and arsenic. Coal-fired plants in the Ohio River Valley must retrofit wet flue gas desulfurization wastewater treatment with enhanced precipitation chemistries. This regulatory pressure is accelerating pilot programs for zero liquid discharge configurations at facilities in Kentucky and Indiana.
Integrated service contracts now bundle chemical supply with residual testing and regulatory reporting. Large municipal authorities in Texas and California are displacing traditional distributor relationships with single-source accountability models where suppliers guarantee effluent compliance metrics. This consolidation is most visible in the Southwest, where water scarcity intensifies performance penalties for treatment failures.
US Water and Wastewater Treatment Chemicals Market Segmentation
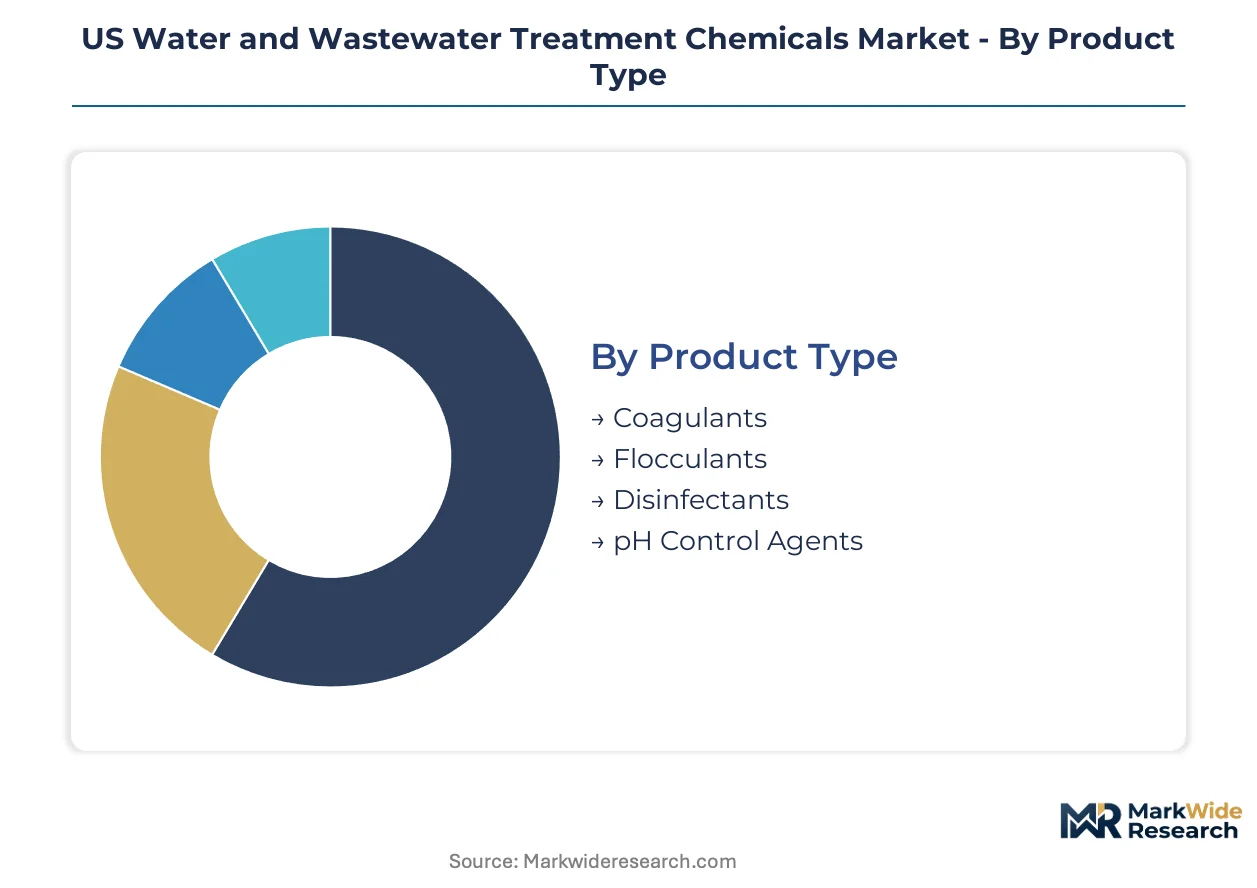
Segmentation in the US water and wastewater treatment chemicals market reveals how procurement patterns diverge between commodity-driven municipal buyers and specification-intensive industrial operators. Chemical form factors and dosing infrastructure further fragment supplier strategies across the Great Lakes corridor and Gulf Coast production hubs.
Product Type:
Supply concentration varies sharply across chemistries, with bulk inorganic coagulants clustering along Gulf Coast petrochemical infrastructure while formulated flocculants distribute through regional blending facilities.
- Coagulants:Aluminum sulfate and ferric chloride formulations precipitate suspended solids through charge neutralization. Demand concentrates in Midwestern municipal utilities confronting EPA Lead and Copper Rule corrosion control mandates, where phosphate-stabilized coagulants anchor filtration upgrade programs.
- Flocculants:High-molecular-weight polyacrylamides bridge destabilized particles into settleable flocs. Paper and pulp mills across Michigan and Wisconsin drive specification-grade procurement, where cationic charge density requirements lock in technical service relationships.
- Disinfectants:Chlorine-based oxidants and alternative chemistries maintain residual pathogen suppression.
- pH Control Agents:Caustic soda and lime adjust alkalinity across municipal and industrial effluent streams.
Coagulants absorb the bulk of installed capacity; disinfectants are expanding most quickly under tightened residual monitoring requirements.
Application:
Application intensity tracks regulatory enforcement geography, with municipal procurement consolidating around federal infrastructure grants while industrial discharge permits fragment across state-level primacy agencies.
- Municipal Water Treatment:Surface water and groundwater facilities serving populations above 50,000 deploy multi-barrier treatment trains. Great Lakes utilities facing legacy agricultural runoff and combined sewer overflow pressures drive advanced oxidation chemical adoption.
- Industrial Wastewater Treatment:Metal finishing and chemical manufacturing effluent requires specialized precipitation and chelation chemistries. Ohio River Valley coal-fired power plants confront forthcoming EPA selenium and mercury effluent guidelines, forcing wet flue gas desulfurization wastewater retrofits.
- Drinking Water:Finished water disinfection and distribution system residuals management.
- Sewage Treatment:Biological nutrient removal and solids dewatering chemical programs.
Municipal water treatment commands the largest procurement volumes; industrial wastewater treatment is climbing the fastest on regulatory tightening.
Form:
Form factor selection depends on dosing equipment compatibility and transportation economics, with liquid concentrates dominating high-volume municipal contracts while solid forms penetrate remote or storage-constrained sites.
- Liquid:Ready-to-feed solutions and emulsions minimize on-site handling. Bulk tanker deliveries to Texas and California municipal authorities reduce per-gallon logistics costs where storage infrastructure exists.
- Powder:Dry polymer grades require dedicated dissolution systems but reduce shipping weight. Small and medium utilities in Appalachian shale regions favor powder flocculants where electrochlorination skids displace bulk bleach deliveries.
- Granular:Controlled-release formulations for specific industrial applications.
- Tablets:Precision-dosed solid forms for remote or intermittent treatment needs.
Liquid formulations capture the majority of contract value; powder forms are gaining share fastest among cost-constrained rural utilities.
End User:
End-user procurement sophistication ranges from compliance-driven municipal bidding to integrated service contracts where chemical supply bundles with analytical and reporting obligations.
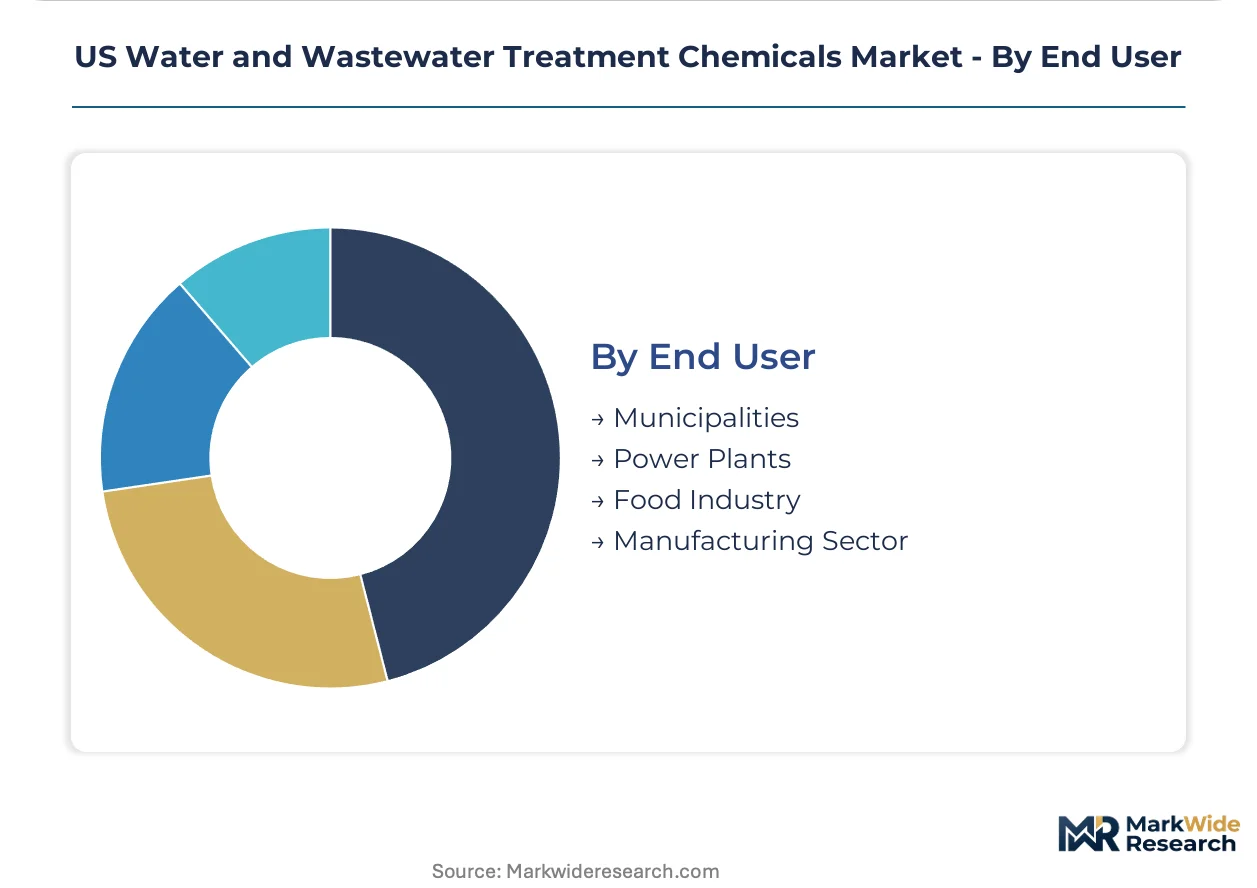
- Municipalities:City and county water authorities operate under Safe Drinking Water Act and Clean Water Act compliance frameworks. Consolidated procurement across Midwestern and Southeastern authorities is decoupling from traditional distributor channels toward multi-year technical service agreements.
- Power Plants:Cooling water and wastewater treatment at thermal generation facilities. Ohio River Valley coal plants face layered Department of Energy efficiency standards intersecting with NPDES permit requirements, favoring multi-functional treatment chemistries.
- Food Industry:Process water and effluent treatment with organic load management requirements.
- Manufacturing Sector:Metal fabrication, electronics, and chemical production effluent streams.
Municipalities anchor procurement volume; power plants are expanding chemical intensity fastest on cooling system and effluent guideline convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast salt dome deposits and chlor-alkali infrastructure anchor domestic production capacity for caustic soda and chlorine derivatives that feed water treatment formulations nationwide.
Great Lakes Industrial Corridor
Michigan and Ohio municipal utilities confront EPA Lead and Copper Rule corrosion control mandates that expand phosphate-based inhibitor procurement. State-level primacy agencies in Michigan enforce emerging PFAS maximum contaminant limits that accelerate activated carbon pretreatment adoption. Detroit and Cleveland metropolitan water authorities consolidate chemical procurement around multi-year technical service agreements.
Gulf Coast Petrochemical Hub
Texas and Louisiana host concentrated bulk aluminum sulfate and ferric chloride production serving Midwestern municipal buyers. Hurricane exposure creates periodic supply disruption risks that Midwestern utilities hedge through inventory pre-positioning. Houston-area integrated producers leverage captive chlorine and caustic soda capacity to compress logistics costs for high-volume coagulant contracts.
Southwest Water-Stressed Regions
Arizona and Nevada utilities deploy electrochlorination skids for decentralized sodium hypochlorite generation, eliminating bulk bleach transportation liabilities. Department of Energy efficiency standards for power plant cooling systems intersect with NPDES permits to favor multi-functional treatment chemistries. Phoenix and Tucson water authorities bundle chemical supply with residual testing and regulatory reporting obligations.
Appalachian Shale Basins
Pennsylvania and West Virginia produced water from oil and gas operations represents underpenetrated feedstock for recovered coagulants and magnesium hydroxide recovery systems. State environmental agencies enforce coal mine drainage treatment requirements that sustain lime and caustic soda demand. Pittsburgh-area treatment technology providers pilot brine processing systems for circular chemical recovery.
US Water and Wastewater Treatment Chemicals Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital dosing integration and on-site generation systems. The vendor base stratifies between Gulf Coast-integrated bulk suppliers and regional formulation specialists with embedded technical service capabilities. Three archetypes dominate: petrochemical-integrated commodity producers, application-specific formulation houses, and service-integrated solution providers. Capacity expansion and strategic partnerships represent the dominant competitive vectors as suppliers defend position against electrochlorination and predictive dosing technologies.
Among service-integrated providers, Ecolab and Solenis occupy positions exemplifying the technical-service-lock archetype through multi-year municipal accountability contracts. Dow represents Gulf Coast petrochemical integration, anchoring bulk coagulant supply chains through captive chlorine and caustic soda capacity. Kurita Water Industries and Kemira exemplify international specialists competing on application-specific formulation depth.
| Leading Market Players |
|---|
| Veolia |
| BASF |
| Ecolab |
| Dow |
| Kurita Water Industries |
| Solenis |
| SNF |
| ChemTreat |
| Kemira |
| Others |
Pricing and Supply Chain Analysis
Analytical chemist talent scarcity in the Great Lakes industrial corridor widens pricing-tier spreads between municipal utilities with in-house LC-MS/MS capabilities and smaller authorities outsourcing compliance testing. Labor-cost differentials compress margins for regional distributors serving price-sensitive rural systems while premium technical service contracts lock in multi-year pricing power for integrated solution providers.
Pricing Analysis
High-volume commodity coagulants trade on thin margins against contract-indexed caustic soda and chlorine feedstock costs, while formulated flocculants and specialty corrosion inhibitors command premium positioning through technical service bundling. Price differentiation rests on EPA certification tier and on-site analytical support depth. Cost compression in bulk inorganic segments is intensifying because Gulf Coast energy volatility feeds directly into chlor-alkali production economics. Small and medium municipal utilities in Appalachia and the rural Southeast exhibit the sharpest price sensitivity, whereas consolidated Great Lakes authorities prioritize compliance guarantee structures over per-gallon procurement savings.
Supply Chain Analysis
Bulk aluminum sulfate and ferric chloride production rests on captive chlorine and caustic soda capacity concentrated along the Texas and Louisiana Gulf Coast petrochemical corridor. Key inputs draw from regional salt dome deposits, Gulf Coast natural gas feedstocks, and imported bauxite ore processed through integrated alumina refineries. Hurricane exposure creates periodic disruption vulnerability for Midwestern municipal buyers dependent on tanker and rail deliveries. Distribution runs through a bifurcated structure: direct bulk contracts from integrated producers to large municipal authorities, and regional blending facilities serving smaller industrial accounts through distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
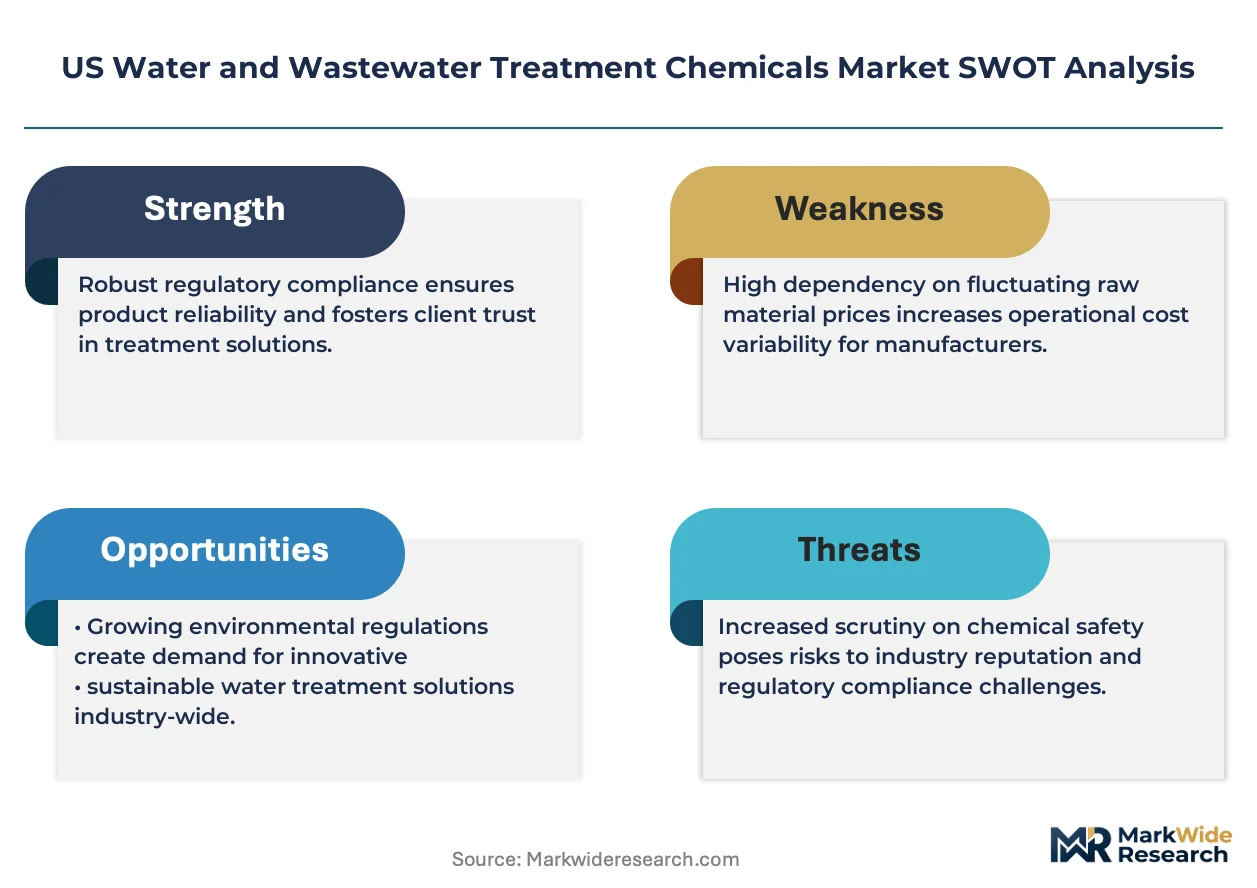
The US water and wastewater treatment chemicals market functions as a cost-of-compliance arena where EPA Lead and Copper Rule revisions and emerging PFAS maximum contaminant limits erect substantial technical and capital barriers against unqualified entrants. Regulatory stringency creates durable moats for suppliers with demonstrated analytical capabilities and multi-year municipal accountability track records.
For Market Incumbents: Hedge Gulf Coast feedstock concentration by pre-positioning inventory buffers at Midwestern rail terminals and expanding on-site electrochlorination system deployment to displace bulk bleach logistics exposure. Backward integration into Appalachian shale brine processing for recovered magnesium hydroxide coagulants defends margin position against commodity price spikes while satisfying Buy America procurement preferences for federal infrastructure grants.
For New Entrants and Emerging Players: Capture white-space opportunity in smart dosing system convergence, where real-time turbidity sensor integration with automated polymer feed controls penetrates small and medium municipal plants lacking legacy SCADA interoperability. The most penetrable segment sits among rural utilities in Appalachian shale regions where powder flocculant substitution for liquid deliveries reduces transportation liability. A go-to-market angle anchored in predictive chemical optimization software-as-a-service bypasses capital-intensive bulk production requirements.
For Investors and Strategic Acquirers: Re-rating potential sits with regional formulation specialists possessing embedded technical service relationships in paper and pulp wastewater applications, given EPA effluent limitation guidelines for steam electric power generation accelerating wet flue gas desulfurization retrofit demand. Long-term viability favors suppliers with demonstrated PFAS treatment chemistry portfolios and analytical support infrastructure. The signal to watch is state-level primacy agency adoption of binding PFAS maximum contaminant limits beyond Michigan and New Jersey, which would force replacement of legacy chemistries and open contracting opportunities for compliant suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Processing | Appalachian shale produced water recovery reduces feedstock cost exposure and satisfies domestic content requirements for federal water infrastructure grants. |
| Smart Dosing System Deployment | Real-time sensor integration with automated polymer controls enables predictive optimization at small and medium municipal plants lacking legacy SCADA interoperability. |
| Technical Service Contract Consolidation | Multi-year accountability agreements bundling chemical supply with residual testing displace traditional distributor relationships at consolidated Great Lakes authorities. |
| PFAS Treatment Chemistry Portfolio Expansion | Activated carbon and ion exchange pretreatment formulations position suppliers for state-level maximum contaminant limit enforcement beyond Michigan and New Jersey. |
| Electrochlorination Skid Manufacturing Scale-Up | Decentralized sodium hypochlorite production eliminates bulk bleach transportation liabilities for Southwest utilities serving populations between 50,000 and 200,000. |
Research Methodology
Document review covered EPA enforcement actions, state primacy agency discharge permit databases, and American Chemistry Council production statistics, complemented by interviews with municipal water utility procurement directors, industrial wastewater treatment plant managers, chlor-alkali producer sales executives, and regional chemical distributor operations heads. Secondary validation drew from SEC 10-K filings of listed chemical producers, customs and trade data on bauxite and alumina imports, and Department of Energy cooling water efficiency standard dockets. Bottom-up triangulation across facility-level chemical consumption estimates and top-down reconciliation against national production capacity data anchored volume and value assessments.
Segment-level outputs across the projection horizon reflect modeled interactions between product type, application intensity, form factor logistics economics, and end-user procurement sophistication. The analytical framework incorporated grade tier differentiation, regional production hub clustering, and packaging format constraints. CAGRs were derived from regression-weighted capacity expansion schedules, regulatory implementation timelines, and historical procurement elasticity patterns. Industry-specific forecast inputs included EPA effluent limitation guideline draft schedules and Infrastructure Investment and Jobs Act water infrastructure grant disbursement trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PFAS regulatory finalization timing, Gulf Coast hurricane frequency, and chlor-alkali feedstock cost volatility. Forecasts reflect assumptions around municipal consolidation continuity, electrochlorination technology adoption curves, and state-level primacy agency staffing capacity for emerging contaminant monitoring. A small set of named triggers warrants ongoing watch: EPA Lead and Copper Rule implementation pace, binding PFAS maximum contaminant limit adoption geography, and integrated service contract renewal rates at consolidated Midwestern authorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Water Dispersible Granules Market
Water & Sludge Treatment
Slurry Homogenizer Tank Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Global Industrial Sludge Treatment Chemicals Market
Water & Sludge Treatment
Water Gel Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Process Water Treatment Market
Water & Sludge Treatment
Global Flocculant and Coagulant Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Semiconductor Wastewater Treatment Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Flocculants Market