
 Global Industrial Chain Market | 2026-2036
Global Industrial Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Chain Market Outlook
Skilled metallurgical engineering capacity is collapsing across traditional European chain manufacturing centers, forcing producers to restructure workforce pipelines. Tsubakimoto Chain Co. leverages its captive forging expertise to sustain premium roller chain output in Japan. Regal Rexnord Corporation anchors North American supply through vertically integrated heat-treatment facilities. Donghua Chain Group dominates cost-optimized volume segments by operating massive automated assembly lines in Zhejiang province.
Industrial chains are mechanical power transmission and conveying components fabricated from hardened alloy or stainless steel, typically precision-rolled to ANSI or ISO pitch standards and subjected to induction hardening for fatigue resistance. Their primary purpose is transferring mechanical energy or moving materials reliably under sustained load in continuous-operation environments. Roller chains capture the dominant share of replacement demand across mature manufacturing economies where downtime costs dwarf initial component pricing. Stainless steel formulations are gaining fastest in food processing and pharmaceutical conveyor applications where washdown corrosion resistance mandates material upgrades. Steel-grade leaf chains retain entrenched positions in forklift mast lifting equipment where proof-load certification requirements create specification stickiness.
FDA food-contact regulations and EU Machinery Directive safety standards enforce traceable material certification and prescribed fatigue-testing protocols for chains deployed in consumer-goods handling and worker-proximate equipment. EPA emissions scrutiny on captive heat-treatment furnaces and China's MIIT energy-efficiency mandates for heavy industry are elevating capital requirements for new melt-and-forge capacity. Stakeholders must monitor evolving carbon-border tariff implementations and alloy-grade scrap availability before committing to regional manufacturing footprints or long-term supply agreements.
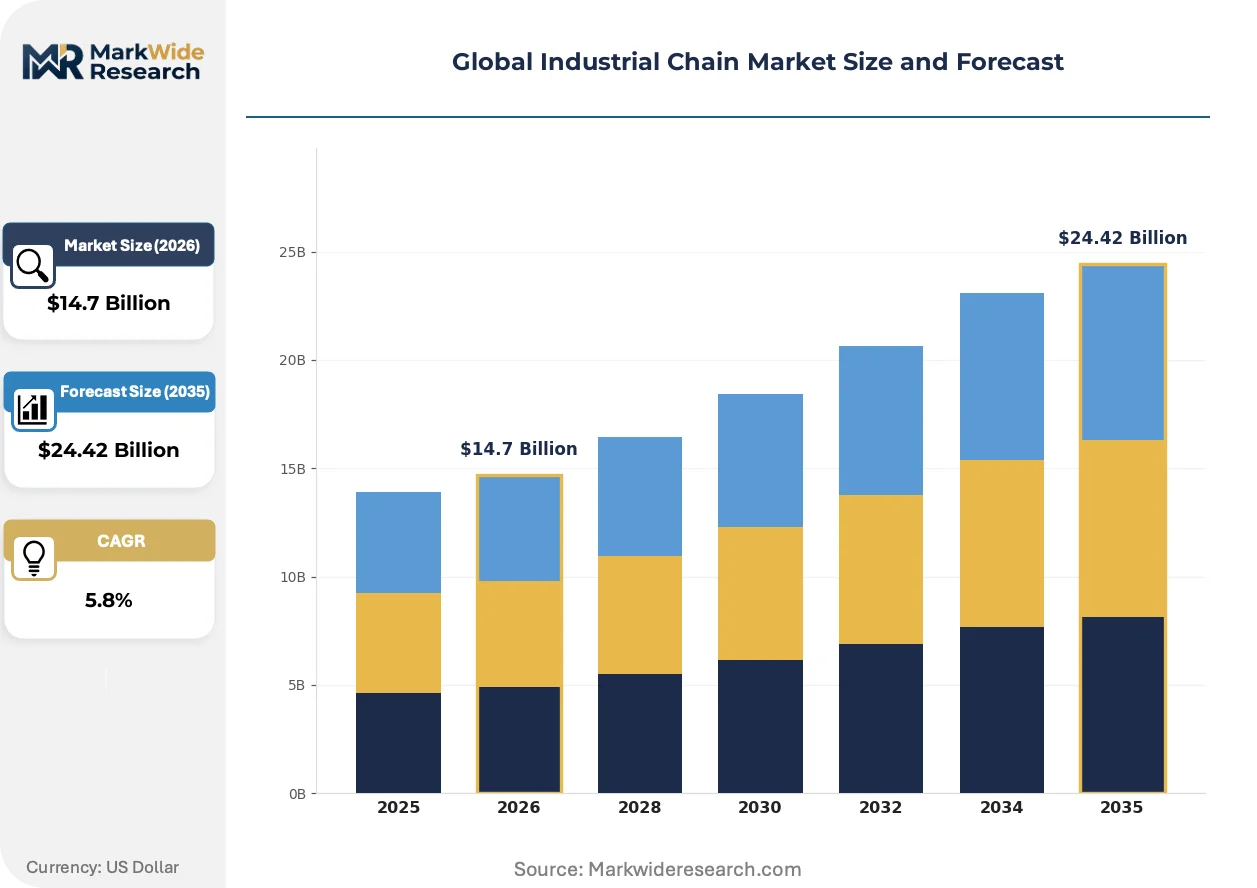
Market Dynamics
Carbon border adjustments and REACH compliance are forcing alloy-grade producers to restructure material sourcing and captive heat-treatment footprints, collapsing legacy supply configurations that depended on unverified scrap streams and outsourced metallurgical processing.
Growth Catalysts
- EU Machinery Directive safety standards:Mandates for traceable fatigue-testing protocols and material certification are elevating specification stickiness in worker-proximate equipment, locking in premium roller chain demand across German automotive assembly lines.
- Automated conveyor deployment:Precision-engineered roller chains are capturing replacement volume in logistics fulfillment centers where downtime costs exceed component pricing by orders of magnitude.
- Stainless steel formulation advances:Washdown corrosion resistance in food processing and pharmaceutical conveying is displacing carbon steel in FDA-regulated cleanroom environments.
Market Restraints
- Alloy-grade scrap availability constraints:China's MIIT energy-efficiency mandates for heavy industry are restricting melt-and-forge capacity expansion, concentrating upstream supply among state-controlled smelters.
- Skilled metallurgical engineering collapse:Traditional European chain manufacturing centers face workforce pipeline failures that limit premium output scaling regardless of demand pull.
- Heat-treatment furnace emissions scrutiny:EPA emissions standards on captive furnaces in the United States are elevating capital requirements for new regional manufacturing footprints.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for capital goods are creating greenfield assembly capacity opportunities for cost-optimized volume segments.
- Digital twin integration:Convergence of IoT sensor chains with predictive maintenance platforms is opening subscription-based monitoring revenue streams in continuous-operation environments.
- Saudi Arabia's industrial diversification:NEOM and Red Sea Project logistics infrastructure buildouts are generating specification demand for high-load leaf chains in materials handling equipment.
Industry Challenges
- ISO 606 fatigue-testing certification timelines:Extended validation protocols for ANSI and ISO pitch standard compliance are delaying new product introductions and locking incumbents into specification maintenance.
- Legacy ERP integration friction:Automated assembly line data systems from Zhejiang province suppliers face protocol mismatches with European end-user MES platforms, complicating traceability handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Chain Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Chains, Sprocket Chains, Leaf Chains, Drive Chains Material: Steel, Stainless Steel, Plastic, Alloy End User: Manufacturing, Construction, Automotive, Aerospace Application: Conveyor Systems, Transmission Systems, Lifting Equipment, Machinery |
| Companies Covered | Tsubakimoto Chain Co., Regal Rexnord Corporation, Renold plc, iwis antriebssysteme GmbH & Co. KG, Donghua Chain Group, SKF, Daido Kogyo Co., Ltd., Zhuji Chain General Factory, KettenWulf Betriebs GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Chain Market Strategic Shifts
Material science advances and regulatory traceability mandates are compressing traditional supply configurations while opening premium segments for certified alloy formulations. Three developments are actively restructuring competitive positioning.
Self-lubricating polymer-infused roller chains are fragmenting maintenance-intensive segments in pharmaceutical and food-grade conveying. Bosch and Siemens operating units in Germany are specifying these formulations for cleanroom environments where grease contamination risks exceed wear-rate concerns. The technology is fragmenting aftermarket service revenue pools by eliminating scheduled lubrication intervals and extending replacement cycles.
REACH substance restrictions on hexavalent chromium plating are forcing conversion to trivalent alternatives or plasma-nitrided surfaces across European supply chains. Surface treatment vendors in the Czech Republic and Poland are consolidating heat-treatment capacity to serve cross-border OEM specifications. German forklift mast producers are absorbing 15-20% surface treatment cost premiums to maintain CE marking compliance for export sales.
Buyers in automotive Tier-1 conveying are consolidating vendor relationships around suppliers offering integrated chain-and-sprocket lifecycle guarantees. Single-source contracting is displacing component-level spot purchasing in Michigan and Stuttgart assembly corridors. Japanese trading houses are capturing this procurement consolidation by bundling Tsubakimoto output with predictive replacement scheduling software.
Global Industrial Chain Market Segmentation
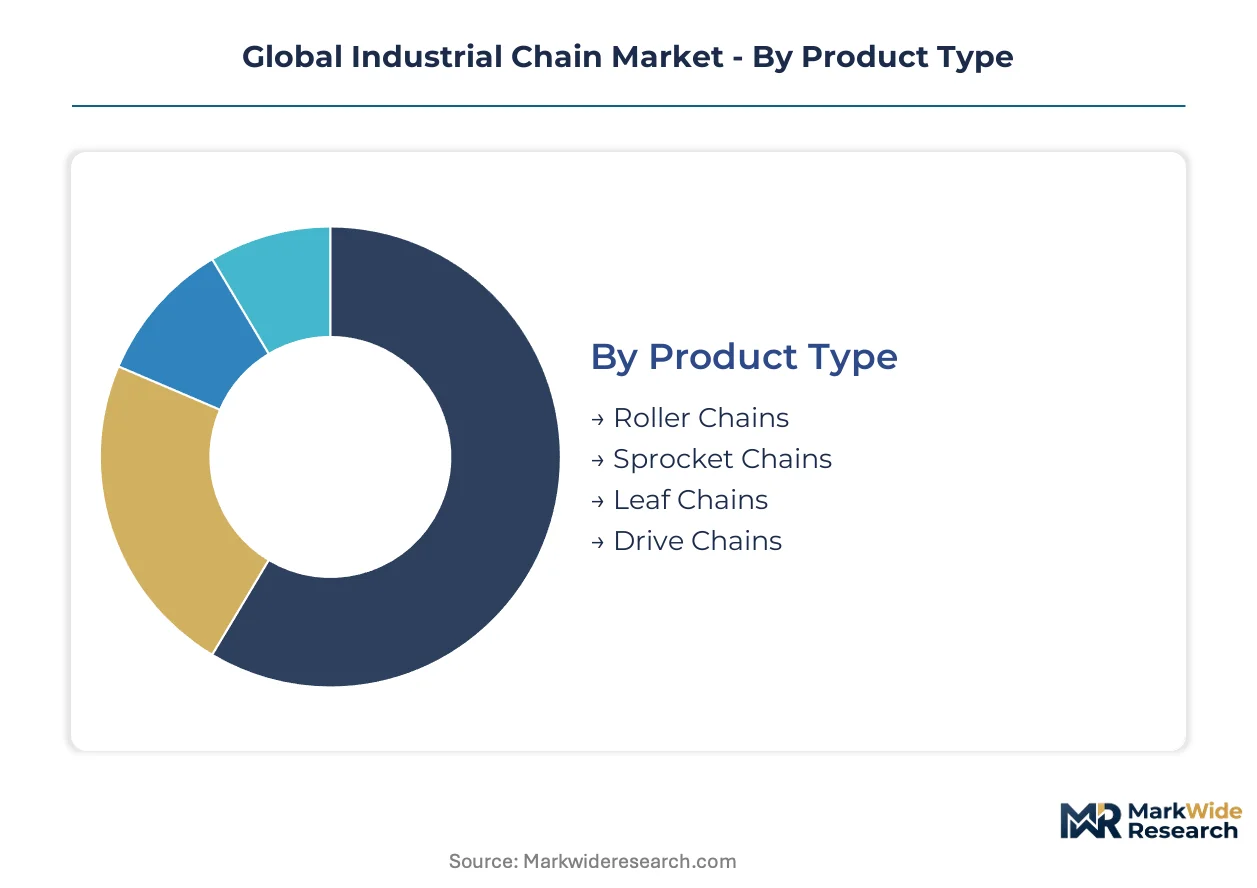
Industrial chain procurement decisions hinge on specification-grade differentiation, where fatigue-testing protocols and material certification requirements fragment demand across performance tiers. Regulatory mandates from ECHA REACH and FDA food-contact standards enforce traceable sourcing that segments supply into compliant and non-compliant tiers, reshaping vendor selection criteria across automotive assembly and pharmaceutical conveying.
Product Type:
REACH substance restrictions and EU Machinery Directive safety standards enforce divergent certification burdens across product architectures, concentrating procurement around fatigue-tested formulations in worker-proximate equipment.
- Roller Chains:Precision-rolled to ANSI or ISO pitch standards and subjected to induction hardening, these components dominate replacement demand in automated manufacturing facilities where downtime costs dwarf initial component pricing. German automotive assembly lines and Michigan logistics fulfillment centers specify these for continuous-operation conveyor systems under EU Machinery Directive traceability mandates.
- Leaf Chains:Steel-grade formulations with proof-load certification requirements retain entrenched positions in forklift mast lifting equipment. CE marking compliance for export sales from German producers absorbs 15-20% surface treatment cost premiums, locking specification stickiness despite REACH-driven hexavalent chromium conversion costs.
- Sprocket Chains:Engage toothed wheels for precise power transmission in synchronized drive systems.
- Drive Chains:Transfer mechanical energy between shafts in heavy-load industrial machinery applications.
Established volume favors roller chains; emerging adoption favors leaf chains as logistics infrastructure buildouts accelerate.
Material:
Cost tier stratification separates premium alloy formulations from commodity carbon steel, with corrosion-resistant grades commanding specification premiums in regulated cleanroom environments.
- Steel:Carbon steel formulations retain cost-optimized dominance in general industrial conveying where washdown requirements are absent.
- Stainless Steel:Washdown corrosion resistance properties displace carbon steel in FDA-regulated food processing and pharmaceutical conveyor applications. Bosch and Siemens operating units in Germany specify these formulations for cleanroom environments where grease contamination risks exceed wear-rate concerns.
- Alloy:Hardened alloy compositions precision-engineered for fatigue resistance capture premium roller chain demand in automotive Tier-1 conveying. Carbon border adjustments and REACH compliance are forcing producers to restructure material sourcing away from unverified scrap streams.
- Plastic:Self-lubricating polymer-infused variants fragment maintenance-intensive segments by eliminating scheduled lubrication intervals.
Steel maintains the deepest installed base; stainless steel climbs the fastest on regulatory corrosion mandates.
End User:
Application-specific duty cycles and safety proximity requirements concentrate specification complexity in worker-adjacent deployment scenarios.
- Manufacturing:Automated conveyor deployment in continuous-operation environments drives precision-engineered roller chain specification where predictive maintenance platforms integrate IoT sensor monitoring.
- Automotive:Tier-1 conveying buyers consolidate vendor relationships around suppliers offering integrated chain-and-sprocket lifecycle guarantees, displacing component-level spot purchasing in Stuttgart and Michigan assembly corridors.
- Construction:Heavy-load lifting applications specify proof-load certified leaf chains for materials handling equipment.
- Aerospace:Traceable material certification and prescribed fatigue-testing protocols enforce stringent sourcing requirements for flight-critical control systems.
Manufacturing commands the largest replacement volume; aerospace exhibits the steepest specification premium escalation.
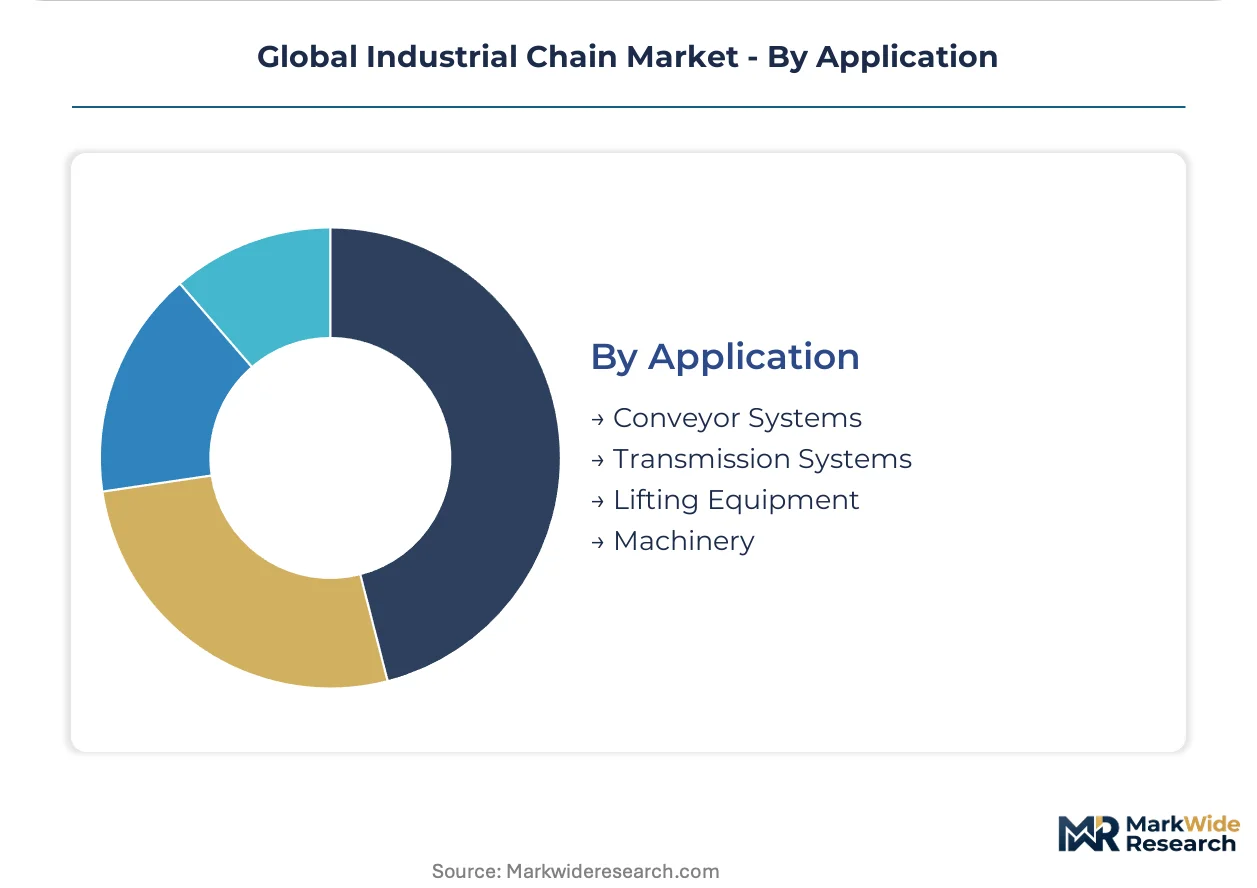
Application:
Operational intensity and accessibility constraints determine maintenance regime economics, favoring self-lubricating formulations in sealed or remote installations.
- Conveyor Systems:Logistics fulfillment centers and pharmaceutical cleanrooms drive demand for corrosion-resistant and polymer-infused variants.
- Transmission Systems:Power transfer between rotating shafts in industrial machinery requires fatigue-tested roller chain architectures.
- Lifting Equipment:Forklift mast applications and construction hoists mandate proof-load certified leaf chains with documented material traceability.
- Machinery:General industrial equipment spans carbon steel economy grades through premium alloy formulations based on duty cycle severity.
Conveyor systems absorb the widest material grade span; lifting equipment enforces the most rigid certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT energy-efficiency mandates in China are reshaping upstream alloy supply, while ECHA REACH compliance in Germany and EPA emissions standards in the United States force parallel restructuring of heat-treatment footprints across three distinct regulatory jurisdictions.
China
Zhejiang province hosts massive automated assembly lines serving cost-optimized volume segments. MIIT energy-efficiency mandates for heavy industry restrict new melt-and-forge capacity expansion, concentrating upstream supply among state-controlled smelters. The Yangtze River Delta cluster absorbs displaced European procurement seeking alternative alloy-grade sources.
Germany
Automotive Tier-1 conveying buyers in Stuttgart consolidate vendor relationships around integrated lifecycle guarantees. ECHA REACH substance restrictions on hexavalent chromium plating force 15-20% surface treatment cost premiums for CE marking compliance. Bavarian forklift mast producers absorb these premiums to maintain export certification.
United States
Michigan logistics fulfillment centers drive precision-engineered roller chain specification where downtime costs exceed component pricing. EPA emissions scrutiny on captive heat-treatment furnaces elevates capital requirements for new regional manufacturing footprints. Midwest assembly corridors favor single-source contracting over component-level spot purchasing.
Japan
Kanto region manufacturers leverage captive forging expertise to sustain premium roller chain output. METI industrial standards enforcement maintains specification stickiness in worker-proximate equipment. Nagoya-area automotive assembly lines specify fatigue-tested formulations under traceable material certification protocols.
India
Maharashtra and Gujarat production-linked incentive schemes for capital goods create greenfield assembly capacity opportunities. BIS standards alignment with ISO 606 fatigue-testing protocols delays new product introductions but locks compliant producers into specification maintenance. Tamil Nadu automotive clusters drive initial precision chain adoption.
Global Industrial Chain Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive heat-treatment and forging capabilities separating premium-positioned producers from assembly-dependent competitors. Japanese and German manufacturers anchor the upper tier through metallurgical engineering depth, while Chinese operators dominate cost-optimized volume segments through scale. Two strategic archetypes predominate: vertically integrated alloy-grade specialists with in-house forging and heat-treatment, and automated assemblers sourcing certified components from state-controlled smelters. Competitive moves center on capacity consolidation around integrated lifecycle guarantees and geographic repositioning to evade carbon-border tariff exposure.
Among Japanese manufacturers, Tsubakimoto Chain Co. and Daido Kogyo Co., Ltd. exemplify the integrated specialist archetype through their positioning in precision-engineered roller chain supply. Donghua Chain Group represents the scale-driven automated assembly model concentrated in Zhejiang province. German-based iwis antriebssysteme GmbH & Co. KG and KettenWulf Betriebs GmbH occupy positions within the European premium tier, navigating REACH compliance through surface treatment consolidation across Czech and Polish facilities.
| Leading Market Players |
|---|
| Tsubakimoto Chain Co. |
| Regal Rexnord Corporation |
| Renold plc |
| iwis antriebssysteme GmbH & Co. KG |
| Donghua Chain Group |
| SKF |
| Daido Kogyo Co., Ltd. |
| Zhuji Chain General Factory |
| KettenWulf Betriebs GmbH |
| Others |
Value Chain & Pricing Dynamics
Massive automated assembly lines in Zhejiang province generate scale economies that compress price floors for commodity carbon steel chains while simultaneously elevating entry barriers for regional competitors lacking equivalent melt-and-forge integration. This concentration of production capacity among state-controlled smelters and vertically integrated Japanese specialists bifurcates the market into cost-optimized volume tiers and premium fatigue-tested formulations with divergent margin structures.
Pricing Analysis
Price spreads between German-engineered premium roller chains and Zhejiang-produced carbon steel equivalents exceed threefold on a per-meter basis, reflecting divergent certification burdens and captive heat-treatment investments. Three-tier pricing structure across premium alloy, standard carbon, and economy grades tracks ISO 606 fatigue-testing compliance and REACH material traceability. Cost compression in the economy tier intensifies as Donghua Chain Group scales automated output, while automotive Tier-1 buyers in Stuttgart and Michigan absorb premium pricing for integrated lifecycle guarantees. Logistics fulfillment centers exhibit highest price sensitivity due to replacement volume procurement, whereas pharmaceutical cleanrooms prioritize corrosion-resistant stainless formulations regardless of unit cost.
Supply Chain Analysis
China, Japan, and Germany anchor global industrial chain fabrication, with Zhejiang province hosting cost-optimized volume production, Kanto region manufacturers sustaining captive forging expertise, and Bavarian specialists navigating REACH-compliant surface treatment. Raw material flows draw from state-controlled alloy-grade smelters under MIIT energy-efficiency mandates, specialty steel mills in Japan, and scrap-dependent European melt shops facing carbon border adjustment exposure. Single-source vulnerability concentrates in heat-treatment furnace capacity, where EPA emissions scrutiny and ECHA substance restrictions constrain expansion. Distribution runs through OEM direct contracting for automotive Tier-1 applications, aftermarket service networks for replacement demand, and industrial distributor channels for general manufacturing procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance platform subscriptions and integrated chain-and-sprocket lifecycle guarantees expand recurring revenue pools faster than hardware unit sales, transforming procurement relationships from transactional component supply to outcome-based service partnerships. This service-attach dynamic favors vendors with IoT sensor integration capabilities and field engineering depth.
For Market Incumbents: Shield premium positioning by deepening captive heat-treatment investments in jurisdictions with stable regulatory trajectories, while consolidating surface treatment capacity across Czech and Polish facilities to absorb REACH-driven hexavalent chromium conversion costs. Certification stickiness from EU Machinery Directive traceability mandates provides defensive moats against Zhejiang-based cost competitors, though polymer-infused self-lubricating formulations threaten scheduled maintenance revenue streams. For New Entrants and Emerging Players: Aftermarket digital twin integration for continuous-operation environments represents underserved white space where incumbent ERP systems face protocol friction with European MES platforms. India's PLI scheme for capital goods manufacturing offers the most penetrable geography for greenfield assembly capacity, with Maharashtra and Gujarat production clusters seeking ISO 606-compliant suppliers. A go-to-market angle bundling IoT-enabled wear monitoring with predictive replacement scheduling bypasses incumbent channel control. For Investors and Strategic Acquirers: Regional heat-treatment specialists with proven ECHA REACH compliance and CE marking certification infrastructure present acquisition targets with irreplaceable regulatory positioning. Long-term viability in this market hinges on backward integration into alloy-grade material sourcing or forward integration into predictive service platforms, with carbon border tariff implementation serving as the critical inflection signal for geographic footprint restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy-Grade Smelting | Captive supply from state-controlled Chinese smelters or Japanese specialty mills secures material traceability for REACH compliance. |
| Digital Twin Platform Development | IoT sensor convergence with predictive maintenance software opens subscription revenue in automotive Tier-1 conveying. |
| Regional Heat-Treatment Consolidation | Czech and Polish surface treatment capacity absorption reduces CE marking cost premiums for German forklift mast producers. |
| India Greenfield Assembly Expansion | Maharashtra PLI scheme incentives enable cost-optimized volume positioning without MIIT capacity restrictions. |
| Self-Lubricating Polymer Formulation Launch | Bosch and Siemens cleanroom specifications drive pharmaceutical and food-grade displacement of grease-dependent chains. |
Study Parameters
A standing panel of maintenance directors at automotive assembly plants, aftermarket service heads at industrial distributors, OEM procurement teams in logistics fulfillment, and plant engineers in pharmaceutical conveying provided ongoing calibration across primary interview cycles. Secondary validation incorporated customs and trade data from alloy-grade steel flows, SEC filings from listed component suppliers, MIIT energy-efficiency mandate disclosures, and ECHA REACH substance restriction updates. Bottom-up volume modeling from end-use equipment installation bases triangulated against top-down value estimates from supplier revenue disclosures.
Consistency checks against external benchmarks validated projections across the analysis window, with segmentation dimensions spanning product architecture, material grade tier, end-use industry duty cycle, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to equipment replacement cycles and industrial automation investment trajectories. Forecast inputs incorporated carbon border adjustment implementation timelines and ISO 606 fatigue-testing certification pipeline durations.
Material uncertainties — abrupt alloy-grade scrap availability constraints, MIIT capacity restriction tightening, or ECHA substance restriction expansion — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement continuity and industrial automation capital commitment stability. Recalibration cycles align with material shifts in carbon border tariff implementation and REACH compliance cost pass-through dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Couplings Market
Industrial Materials
Injection Mold Hot Runners Market
Industrial Materials
Flat Enameled Wires Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
Middle East Activated Carbon Market
Industrial Materials
Hose Reinforcement Wire Market
Industrial Materials
Powder Funnels Market
Industrial Materials
Solid Surface Materials Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Isotropic Graphite Market
Industrial Materials
North America Machined Seals Market
Industrial Materials
Metal Based Safety Gratings Market
Industrial Materials
Shrink Tanks Market
Industrial Materials
Thermal Spray Guns Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
Soil Stabilization Materials Market