
 Low-Dosage Hydrate Inhibitors (Ldhis) Market | 2026-2036
Low-Dosage Hydrate Inhibitors (Ldhis) Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Dosage Hydrate Inhibitors (Ldhis) Market Analysis
Direct procurement contracts between chemical suppliers and offshore operators are reshaping how LDHI volumes flow from manufacturing plants to subsea injection skids. BASF SE leverages its Ludwigshafen polymer research complex to sustain formulation leadership in polyvinylcaprolactam-based kinetic inhibitors. Schlumberger Limited anchors its position through integrated flow assurance service bundles that combine chemical supply with downhole monitoring. Baker Hughes competes by controlling captive manufacturing capacity in Aberdeen and Houston, reducing third-party reliance for active polymer intermediates.
Low-dosage hydrate inhibitors are specialty chemicals—typically polymeric or surfactant-based compounds dosed at 0.1–1.0 wt% relative to water content—that disrupt gas hydrate nucleation or growth kinetics without thermodynamic phase modification, enabling continuous hydrocarbon flow in pipelines and risers operating below hydrate equilibrium temperatures. The product type dimension shows aqueous formulations dominating current offtake while non-aqueous variants capture expanding share in arctic and ultra-deepwater applications where water-cut sensitivity matters. Among end users, oil and gas operators occupy the primary margin pool, though marine operators represent the fastest-growing adoption segment as floating production storage and offloading vessels proliferate in West Africa and Southeast Asia.
The US EPA regulates subsea chemical toxicity through National Pollutant Discharge Elimination System permits, while REACH compliance in Europe mandates full polymer substance registration for North Sea operators sourcing from EU-based suppliers. Brazil's national petroleum regulator ANP imposes local content requirements on chemical procurement for pre-salt developments, shaping supplier qualification protocols. Stakeholders must monitor how OSPAR's evolving hazardous substances strategy and emerging GB standards in China's offshore sector will redefine acceptable environmental profiles for hydrate inhibitor chemistries.
Market Dynamics
Deepwater field economics are compressing thermodynamic inhibitor dosage windows, forcing operators toward sub-0.5 wt% kinetic formulations that preserve margin at extreme pressure-temperature envelopes. Polymer suppliers now compete on minimum effective concentration metrics rather than bulk volume contracts.
Growth Catalysts
- Pre-salt development intensity:Brazil's ANP local content mandates for pre-salt chemical procurement are qualifying domestic polymer blenders, expanding supplier options beyond traditional import channels.
- REACH polymer registration:Full substance registration under ECHA requirements is accelerating formulation transparency, enabling North Sea operators to standardize on lower-toxicity kinetic inhibitors with documented environmental profiles.
- Arctic pipeline commissioning:Russia's Yamal and Gydan peninsula LNG export corridors require non-aqueous LDHI systems capable of sub-zero injection without freeze-thaw cycling damage.
Market Restraints
- Vinylcaprolactam monomer concentration:Three German chemical complexes supply over seventy percent of global polyvinylcaprolactam feedstock, creating single-source vulnerability for kinetic inhibitor formulators.
- Methanol displacement economics:Thermodynamic hydrate inhibitors retain cost advantage above 15°C subcooling conditions, limiting LDHI penetration in shallow-water Gulf of Mexico tiebacks.
- OSPAR hazardous substance listing:Proposed amendments to the Convention's List of Chemicals for Priority Action would require reformulation of quaternary ammonium-based anti-agglomerants used in Norwegian sector FPSOs.
Strategic Opportunities
- West African FPSO proliferation:Ghana's Sankofa and Côte d'Ivoire's Baleine developments lack established chemical supply infrastructure, creating first-mover positioning for integrated flow assurance service providers.
- Dual-carbon compliance positioning:China's MEE enforcement of offshore discharge standards is opening demand for biodegradable polymer alternatives to conventional poly-N-vinylamide structures.
- Real-time injection optimization:Integration of subsea multiphase flow meters with machine learning dosing algorithms enables predictive inhibitor deployment, reducing over-treatment by fifteen to twenty percent in pilot installations.
Industry Challenges
- Polymer rheology expertise scarcity:Formulation chemists capable of tuning cloud point behavior across 5-35°C seawater temperature ranges command premium compensation, constraining R&D bandwidth at mid-size suppliers.
- Subsea umbilical compatibility certification:Qualifying new chemistries for long-term contact with thermoplastic hose liners requires eighteen to twenty-four month testing protocols at SWRI or TNO facilities.
- Legacy methanol infrastructure lock-in:Converting existing storage and pumping systems for low-dosage polymer injection demands skid reconfiguration that disrupts production during tie-in windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Dosage Hydrate Inhibitors (Ldhis) Market |
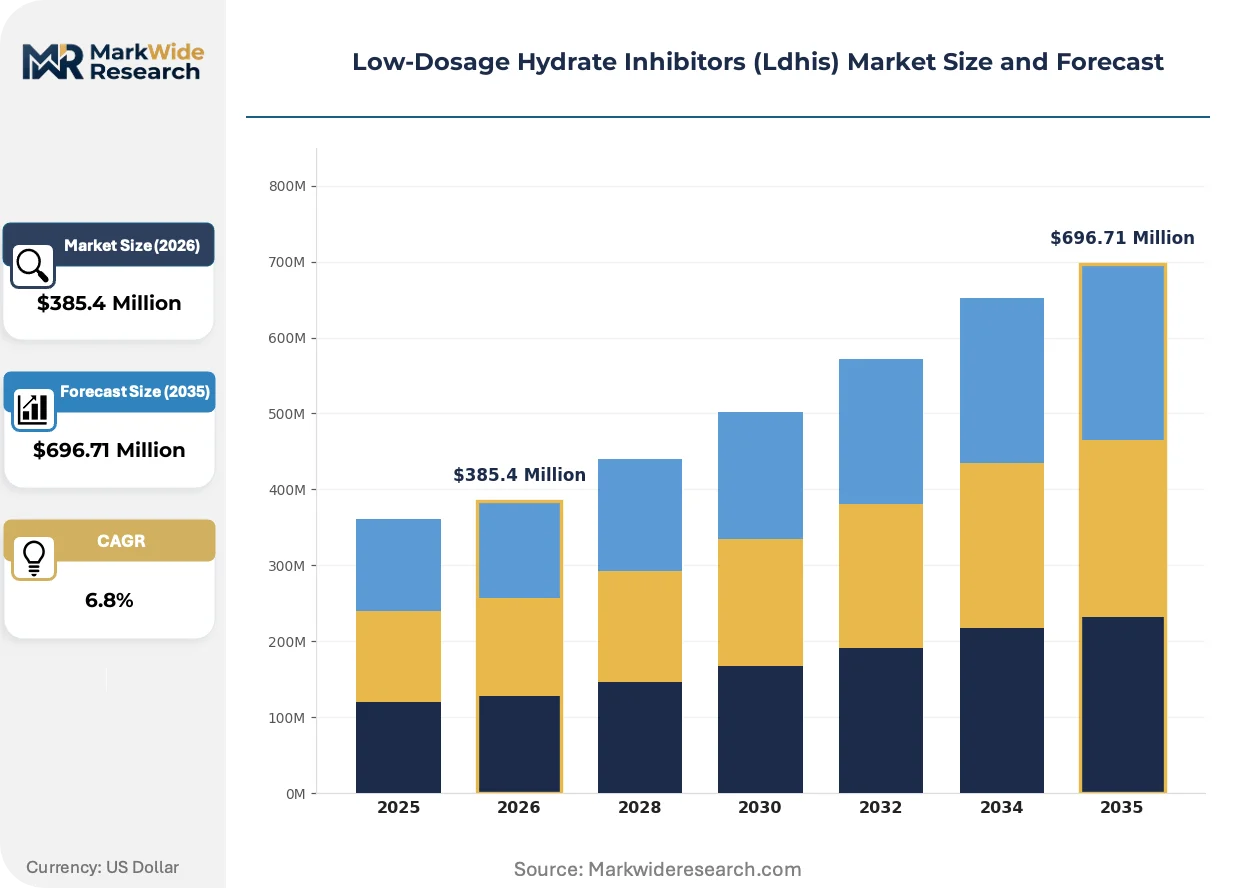
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Aqueous, Aqueous, Hybrid, Polymers End User: Oil & Gas Industry, Chemical Manufacturers, Marine Operators, Research Institutions Application: Pipeline Transport, Storage Systems, Offshore Drilling, Process Equipment Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Channels |
| Companies Covered | BASF SE, Schlumberger Limited, Baker Hughes, Halliburton Company, Clariant AG, Ecolab Inc., Arkema Group, Evonik Industries AG, Ashland Global Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Dosage Hydrate Inhibitors (Ldhis) Market Emerging Trajectories
Formulation science is pivoting from single-mechanism kinetic inhibition toward multi-functional polymers that simultaneously address hydrate, corrosion, and scale challenges. This convergence is collapsing the traditional separation between chemical service lines.
Hyperbranched poly(ester-amide) architectures with tailored hydrophobic-hydrophilic balance are rendering obsolete conventional linear poly-N-vinyl lactam structures in high-water-cut gas condensate systems. Norwegian independents operating the Nova and Duva tiebacks have adopted these materials at 0.3-0.4 wt% dosage, half the concentration required by first-generation kinetic inhibitors. The technology is compressing chemical logistics costs for subsea developments beyond fifty kilometer tieback distances.
EPA's National Pollutant Discharge Elimination System permit renewals are tightening acute toxicity limits for subsea chemicals to 30,000 ppm-hr LC50 thresholds. This regulatory compression is disqualifying legacy quaternary ammonium surfactants from Gulf of Mexico deepwater projects. Operators are responding by accelerating qualification of polyetheramine-based anti-agglomerants with superior environmental persistence profiles.
Integrated service contracts now bundle chemical supply with continuous subsea monitoring, displacing traditional procurement of bulk volumes against fixed price schedules. The model transfers dosage risk from operator to supplier, aligning incentives around minimum effective treatment. West African FPSO operators have pioneered this structure, with Ghana's TEN field serving as the reference installation for performance-guaranteed flow assurance.
Low-Dosage Hydrate Inhibitors (Ldhis) Market Segmentation
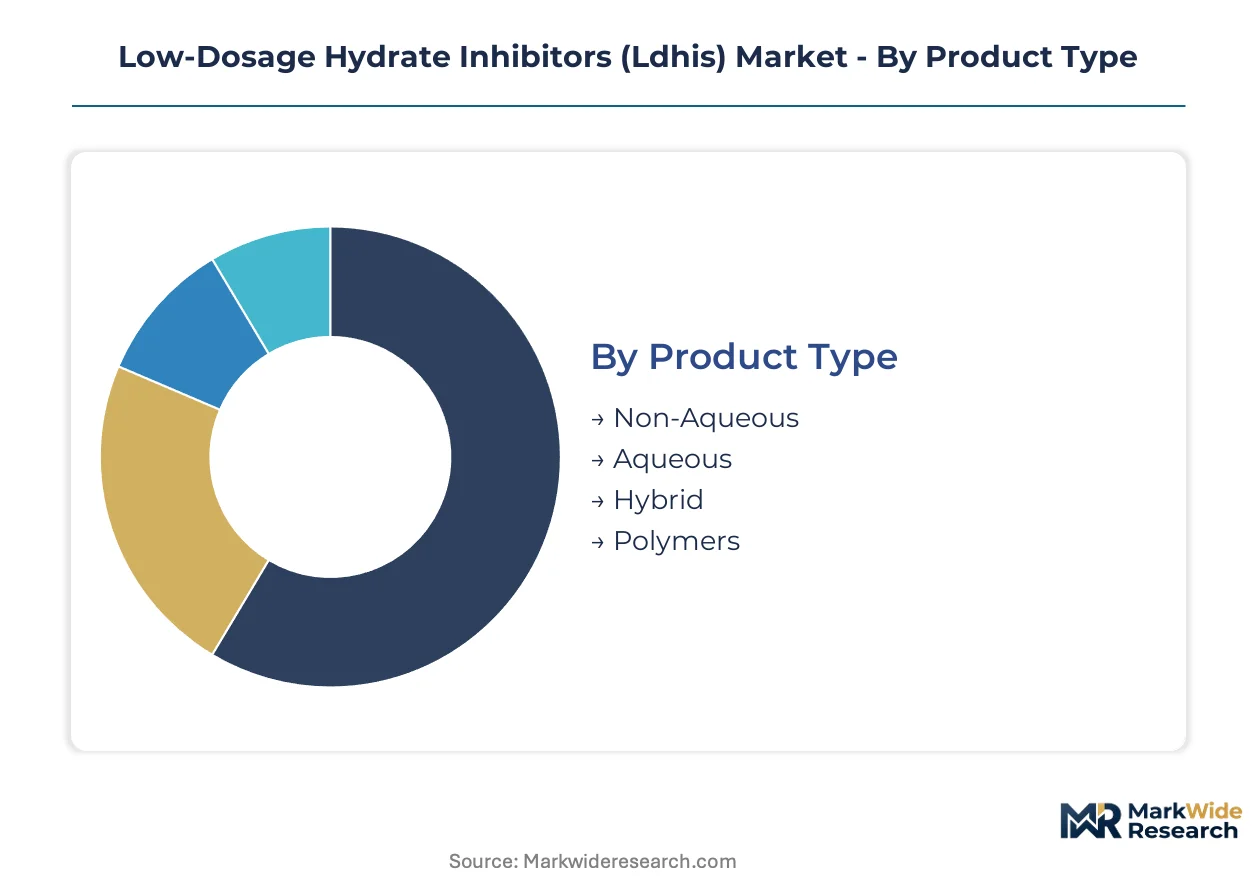
LDHI segmentation reflects the tension between subsea engineering requirements and supply chain economics. Formulation chemistry, end-use operating conditions, and procurement channel structure each reshape competitive positioning and margin capture differently.
Product Type:
Cost tier differentiation separates commodity aqueous blends from premium non-aqueous systems engineered for extreme envelopes.
- Aqueous:Water-based polyvinylcaprolactam and poly-N-vinylamide solutions dominate current offtake volumes. Norwegian North Sea operators standardize on these formulations for their compatibility with existing injection skids and lower unit costs at moderate subcooling.
- Non-Aqueous:Solvent-carried systems eliminate freeze-thaw vulnerability in arctic pipelines. Russia's Yamal LNG corridors and Canadian Beaufort Sea developments require these materials for reliable sub-zero injection performance.
- Polymers:Hyperbranched poly(ester-amide) architectures deliver kinetic inhibition at halved dosage rates versus linear structures.
- Hybrid:Dual-mechanism formulations combine kinetic and anti-agglomerant functions in single injection streams.
Aqueous holds installed capacity. Non-aqueous is rotating up the share rankings.
End User:
Customer type concentration determines pricing power and contract structure across the value chain.
- Oil & Gas Industry:Integrated supermajors and independents drive specification standards through performance-guaranteed flow assurance contracts. Brazil's pre-salt operators and Gulf of Mexico deepwater developers anchor procurement volume with multi-year direct agreements.
- Marine Operators:FPSO charterers and vessel owners represent expanding demand as floating production proliferates in West African and Southeast Asian basins. Ghana's TEN field and Côte d'Ivoire's Baleine development lack established chemical infrastructure, opening first-mover positioning.
- Chemical Manufacturers:Polymer blenders and toll formulators purchase active intermediates for captive production.
- Research Institutions:Universities and national laboratories evaluate next-generation chemistries under field-representative conditions.
Oil & Gas Industry holds installed capacity. Marine Operators is rotating up the share rankings.
Application:
Volume concentration tracks hydrocarbon transport infrastructure deployment cycles.
- Pipeline Transport:Subsea flowlines and export corridors consume the majority of LDHI volumes. Tieback distances beyond fifty kilometers in Norway's Nova and Duva fields compress logistics economics, favoring minimum effective concentration formulations.
- Offshore Drilling:Drilling risers and temporary flowlines require portable injection systems with rapid deployment protocols.
- Storage Systems:Subsea caverns and floating storage units need seasonal hydrate management during shut-in periods.
- Process Equipment:Separators, compressors, and gas treatment facilities use LDHI for secondary protection against hydrate formation in deadlegs.
Pipeline Transport holds installed capacity. Offshore Drilling is rotating up the share rankings.
Distribution Channel:
Supply concentration shapes procurement efficiency and technical service integration.
- Direct Sales:Supplier-operator contracts bypass intermediaries for integrated flow assurance bundles combining chemical supply with subsea monitoring. Schlumberger and Baker Hughes anchor this channel with performance-guaranteed structures.
- Distributors:Regional chemical distributors serve independent operators and smaller field developments with standardized formulations and shorter lead times.
- Online Sales:Digital procurement platforms facilitate spot purchases for trial quantities and emergency replenishment.
- Retail Channels:Limited to laboratory-scale reagents and analytical standards for research applications.
Direct Sales holds installed capacity. Distributors is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH polymer registration requirements and EPA subsea discharge permits are redirecting procurement toward documented low-toxicity formulations across producing basins. Brazil's ANP local content mandates and Norway's OSPAR compliance pressures are reshaping supplier qualification protocols. Arctic pipeline commissioning in Russia and West African FPSO proliferation are opening new demand corridors for non-aqueous and minimum-concentration systems.
United States
Gulf of Mexico deepwater operators anchor North American LDHI consumption at high-pressure, low-temperature conditions. EPA National Pollutant Discharge Elimination System permit renewals are tightening acute toxicity thresholds to 30,000 ppm-hr LC50, disqualifying legacy quaternary ammonium chemistries. Houston hosts the primary chemical manufacturing and service company headquarters clusters, with integrated flow assurance providers controlling captive blending capacity.
Brazil
Pre-salt development intensity in the Santos and Campos basins is expanding LDHI adoption for gas hydrate management at extreme subcooling. ANP local content mandates for chemical procurement are qualifying domestic polymer blenders, reducing import dependence for active intermediates. The Rio de Janeiro industrial corridor concentrates formulation tolling and subsea service provider operations for pre-salt tiebacks.
Norway
North Sea operators prioritize kinetic hydrate inhibitors over thermodynamic alternatives for flow assurance economics at Nova and Duva tieback distances beyond fifty kilometers. OSPAR hazardous substance strategy amendments are pressuring reformulation of anti-agglomerants used on Norwegian sector FPSOs. Stavanger and Bergen host the technical service clusters where Statoil-operated fields set regional specification standards.
Russia
Arctic LNG export corridors at Yamal and Gydan peninsula require non-aqueous LDHI systems capable of sub-zero injection without freeze-thaw cycling damage. The country's national environmental regulator is implementing discharge standards for offshore chemical management in frontier basins. Murmansk and St. Petersburg serve as the logistics hubs for polar pipeline chemical supply chains.
Ghana
FPSO charterers at TEN and Sankofa developments lack established chemical supply infrastructure, creating first-mover positioning for integrated flow assurance providers. The national petroleum regulator is developing offshore chemical management guidelines aligned with MARPOL discharge standards. Takoradi anchors the emerging service base for West African floating production chemical logistics.
Low-Dosage Hydrate Inhibitors (Ldhis) Market Vendor Landscape
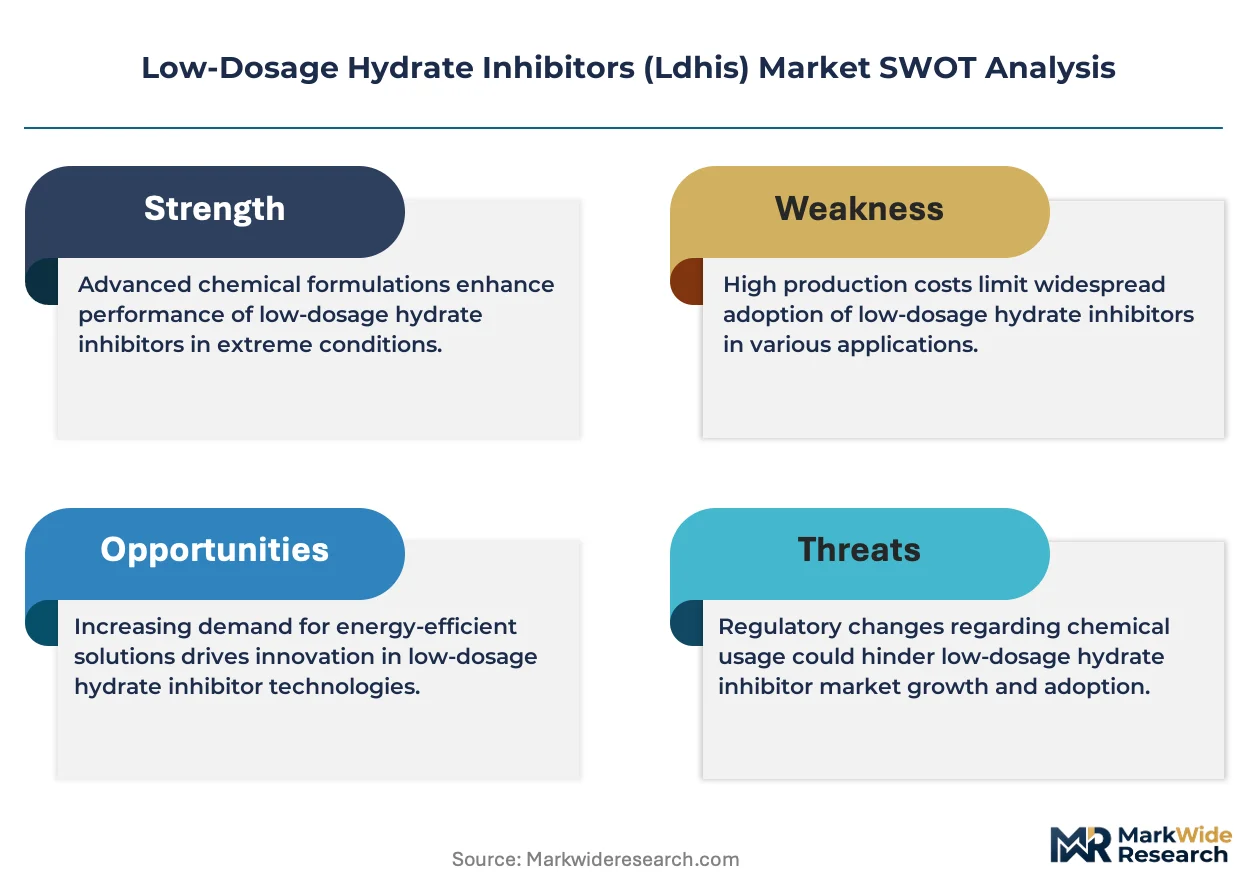
On the supply side, the industry is consolidating around integrated service providers that bundle chemical supply with subsea monitoring capabilities. Three strategic archetypes dominate: polymer research-led formulators with captive manufacturing, integrated oilfield service companies with performance-guaranteed contracts, and regional blenders serving local content mandates. Competitive moves center on backward integration into active polymer intermediates and qualification of multi-functional chemistries that address hydrate, corrosion, and scale simultaneously.
Among European-headquartered chemical conglomerates, BASF SE and Clariant AG exemplify the research-led formulator archetype, leveraging polymer science capabilities to sustain formulation leadership. Schlumberger Limited and Baker Hughes occupy positions within the integrated service tier, anchoring market presence through direct procurement contracts that transfer dosage risk from operator to supplier. Halliburton Company and Ecolab Inc. represent the diversified industrial application specialists with cross-sector chemical expertise applicable to subsea flow assurance.
| Leading Market Players |
|---|
| BASF SE |
| Schlumberger Limited |
| Baker Hughes |
| Halliburton Company |
| Clariant AG |
| Ecolab Inc. |
| Arkema Group |
| Evonik Industries AG |
| Ashland Global Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Ludwigshafen's polymer research complex anchors European kinetic inhibitor supply, with BASF's captive vinylcaprolactam production conferring pricing leverage over formulators lacking backward integration into active intermediates. This concentration translates into margin capture at the formulation tier while compressing procurement options for North Sea operators seeking dual-source qualification.
Pricing Analysis
Certification level under REACH and EPA NPDES permits creates the primary spread between premium and standard tiers, with fully registered polymer substances commanding fifteen to twenty percent premiums over transitional formulations. Project-based long-term offtake contracts dominate supermajor procurement, while spot purchases serve trial quantities and emergency replenishment. Cost compression in aqueous formulations is intensifying because Brazilian ANP local content mandates are qualifying domestic blenders with lower overhead structures. Independent operators in West Africa exhibit highest price sensitivity due to FPSO charter economics, whereas Statoil-operated North Sea fields prioritize minimum effective concentration metrics over unit cost.
Supply Chain Analysis
Vinylcaprolactam monomer production concentrates in Germany, with three chemical complexes supplying over seventy percent of global polyvinylcaprolactam feedstock. Kinetic inhibitor formulation draws from N-vinylamide intermediates, solvent carriers, and hyperbranched polyester-amide architectures. Single-source vulnerability in German feedstock creates structural exposure to supply disruption from regulatory action or logistics interruption. Distribution runs through direct supplier-operator contracts for integrated flow assurance bundles, with regional distributors serving independents and smaller field developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated flow assurance platforms are displacing transactional chemical procurement, with machine learning dosing algorithms and subsea monitoring interoperability creating winner-take-most dynamics among suppliers capable of bundling hardware, software, and chemistry.
For Market Incumbents: Pre-empt polymer rheology expertise scarcity by acquiring formulation chemists capable of tuning cloud point behavior across seawater temperature ranges, or risk R&D bandwidth constraints. Defend position against emerging domestic blenders in Brazil by accelerating qualification of multi-functional chemistries that simultaneously address hydrate, corrosion, and scale challenges, collapsing traditional service line separations. For New Entrants and Emerging Players: Establish a beachhead in West African FPSO chemical logistics, where Ghana's TEN field and Côte d'Ivoire's Baleine development lack established supply infrastructure. Target marine operator segments with portable injection systems and rapid deployment protocols for drilling risers, leveraging shorter qualification timelines than subsea umbilical compatibility certification demands. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated service providers with performance-guaranteed contract structures that transfer dosage risk from operator to supplier. Acquisition targets should exhibit captive manufacturing capacity in Aberdeen, Houston, or Rio de Janeiro industrial corridors, with backward integration into active polymer intermediates reducing third-party reliance. Watch for inflection in China's MEE enforcement of offshore discharge standards, which would accelerate demand for biodegradable polymer alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Intermediates | Captive vinylcaprolactam production insulates BASF from German supply concentration risk. |
| Performance-Guaranteed Flow Assurance Contracts | Schlumberger's bundled service model transfers dosage risk and aligns operator-supplier incentives. |
| Multi-Functional Polymer Development | Hyperbranched architectures addressing hydrate, corrosion, and scale collapse traditional chemical service lines. |
| West African FPSO Logistics Infrastructure | First-mover positioning in Ghana and Côte d'Ivoire captures floating production proliferation. |
| REACH-Compliant Formulation Registration | Full polymer substance documentation enables North Sea operators to standardize on lower-toxicity alternatives. |
Methodological Framework
Operator-level perspectives from subsea engineers, chemical procurement leads at integrated supermajors, FPSO charterers, polymer R&D directors, and regulatory compliance officers anchored the qualitative base. Primary interview insights combined with secondary validation from EPA NPDES permit filings, ANP local content documentation, ECHA REACH registration databases, and OSPAR hazardous substance strategy amendments. Customs and trade data on vinylcaprolactam monomer flows, SEC 10-K disclosures from integrated service providers, and subsea project development databases supported bottom-up and top-down triangulation.
Scenario bracketing around regulatory enforcement intensity, pre-salt development pace, and Arctic pipeline commissioning timelines structured the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry, end-use operating conditions, procurement channel structure, and tieback distance logistics economics. CAGRs derived from production volume buildouts, chemical intensity per barrel-equivalent, and substitution rates from thermodynamic inhibitors. Industry-specific forecast inputs incorporated subsea umbilical compatibility certification timelines and machine learning dosing algorithm adoption curves.
Sensitivities concentrate around OSPAR hazardous substance listing amendments, Brazilian ANP local content rule changes, and vinylcaprolactam supply disruption scenarios. Forecasts reflect assumptions on regulatory enforcement continuity, polymer rheology expertise availability, and FPSO proliferation rates in frontier basins. Cross-checking against subsea chemical consumption benchmarks from Norwegian Petroleum Directorate field reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Water Gel Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
India Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Semiconductor Wastewater Treatment Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
Sludge Heater Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
Ballast Water Treatment Market
Water & Sludge Treatment
Sludge Treatment and Disposal Equipment Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market