
 Hazardous Waste Treatment System Market | 2026-2036
Hazardous Waste Treatment System Market Size, Share, and Industry Trends Forecast 2026-2036
Hazardous Waste Treatment System Market Foresight
The EU Green Deal's industrial emissions targets are shifting procurement priorities across European chemical producers. Veolia Environment SA leverages integrated incineration and physical treatment platforms to sustain long-term service contracts with multinational industrial clients. Clean Harbors Inc. anchors North American market presence through specialized remediation and landfill management capabilities. Waste Management Inc. competes on scale, operating one of the continent's largest networks of permitted treatment, storage, and disposal facilities.
Hazardous waste treatment systems encompass engineered installations that neutralize, stabilize, or destroy toxic, corrosive, ignitable, or reactive waste streams through thermal, chemical, biological, or physical processes operating at temperatures ranging from ambient to over 1,100°C in incineration configurations. These systems serve primary industrial and commercial purposes of regulatory compliance, environmental liability reduction, and resource recovery from regulated waste streams. Incineration technology dominates value generation due to its destruction and removal efficiency for persistent organic pollutants and pharmaceutical residues. Chemical treatment segments attract capital as mercury-laden and acid-bearing wastes require specialized neutralization before landfill disposal. Biological treatment occupies a narrower but expanding niche for hydrocarbon-contaminated soils and select pharmaceutical effluents where microbial degradation achieves cost advantages.
EPA enforcement under the Resource Conservation and Recovery Act shapes demand patterns across US industrial and healthcare facilities, mandating cradle-to-grave tracking and permitted treatment pathways. EMA waste directives and REACH compliance obligations in Europe compel chemical manufacturers to verify downstream treatment standards. India's Central Pollution Control Board and evolving hazardous waste management rules tighten import restrictions and domestic handling certifications. Stakeholders must monitor regulatory divergence between jurisdictions to optimize facility siting and technology portfolio decisions.
Market Dynamics
EPA enforcement under the Resource Conservation and Recovery Act is intensifying cradle-to-grave tracking mandates, forcing chemical manufacturers and healthcare facilities to upgrade treatment infrastructure rather than rely on legacy disposal pathways. This regulatory compression is redrawing competitive boundaries between integrated service providers and specialized technology vendors.
Growth Catalysts
- RCRA Compliance Deadlines:EPA inspection frequency for large quantity generators has doubled since 2022, accelerating capital deployment into permitted treatment, storage, and disposal facilities.
- Pharmaceutical Residue Destruction:Incineration technology with destruction and removal efficiency above 99.99% is capturing expanded volume from healthcare systems managing expired controlled substances.
- India:Central Pollution Control Board import restrictions on hazardous waste are redirecting regional treatment demand toward domestic capacity expansion.
Market Restraints
- Energy Input Volatility:Thermal treatment configurations consuming natural gas above 850°C face margin compression from fuel price swings, particularly affecting rotary kiln incineration economics.
- Permitting Concentration:US commercial hazardous waste landfill capacity concentrates in fewer than twelve permitted sites, creating geographic supply bottlenecks for generators in the Northeast and Pacific Coast.
- Mercury Recovery Limitations:Amalgamation and retort technologies face technical ceilings on extraction efficiency from complex mixed waste streams, limiting landfill diversion rates.
Strategic Opportunities
- EU Green Deal Industrial Emissions Targets:Chemical producers in Germany, France, and the Netherlands are procuring integrated physical-chemical treatment platforms to verify downstream compliance with REACH obligations.
- Biological Treatment Expansion:Hydrocarbon-contaminated soil remediation using ex-situ bioreactors is penetrating construction and petroleum refining sectors where thermal desorption costs prove prohibitive.
- Plasma Gasification Convergence:Syngas capture systems combined with vitrification units are opening municipal and industrial waste co-processing applications previously reserved for pure hazardous streams.
Industry Challenges
- Specialized Technician Scarcity:Operations requiring combined mechanical, chemical, and regulatory expertise face recruitment gaps for permitted facility managers and waste characterization chemists.
- Legacy System Integration:Brownfield upgrades must reconcile 1970s-era tank farm configurations with modern leak detection and secondary containment standards, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hazardous Waste Treatment System Market |
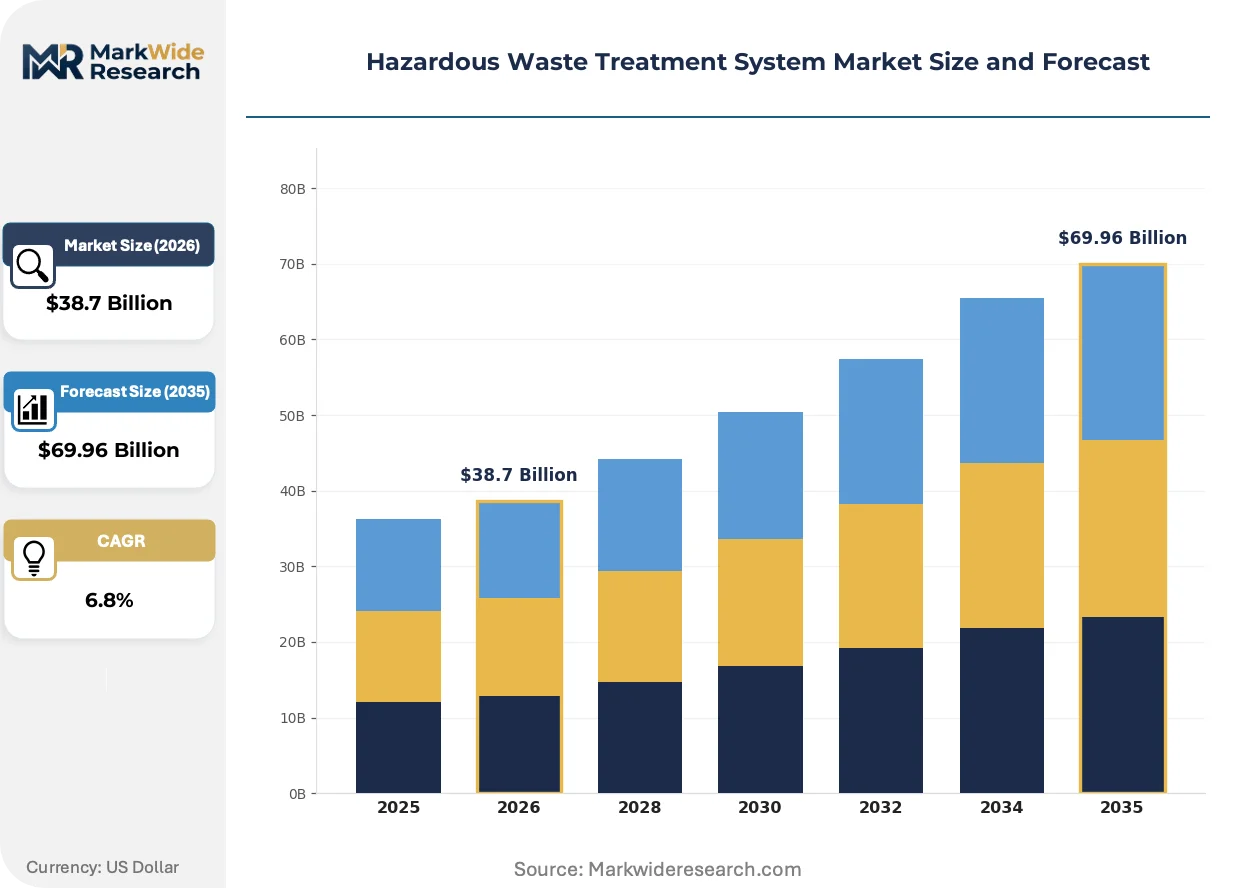
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Incineration, Chemical Treatment, Biological Treatment, Physical Treatment End User: Industrial Sector, Healthcare Facilities, Chemical Manufacturers, Educational Institutions Service Type: Consulting Services, Waste Disposal Services, Safety Audits, Compliance Services Application: Landfill Management, Remediation, Recycling, Hazardous Waste Storage |
| Companies Covered | Veolia Environment SA, Clean Harbors Inc., Republic Services Inc., Waste Management Inc., Waste Connections Inc., Stericycle Inc., SUEZ Group, REMONDIS Medison GmbH, Bechtel Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hazardous Waste Treatment System Market Shifts & Advancements
Technology developers are fragmenting monolithic treatment trains into standardized sub-units, enabling site-specific reconfiguration without full engineering redesign. This architectural shift is compressing deployment timelines and lowering minimum efficient scale thresholds.
Containerized thermal treatment units are modularizing hazardous waste processing for remote industrial sites and emergency response scenarios. Mining operations in Canada and oilfield services in Texas are deploying these skid-mounted configurations to eliminate transportation liability for reactive wastes. The approach is compressing capital requirements for generators below ten thousand tons annual throughput.
REACH authorization procedures are tightening downstream verification requirements for chemical manufacturers exporting into European markets. ECHA substance evaluation cycles now demand documented treatment chain compliance for SVHC-containing wastes. Specialty chemical producers in China and India are responding by certifying partner facilities against EU waste framework standards.
Service unbundling is fragmenting long-term treatment contracts into discrete waste-stream-specific agreements. Multinational industrial clients in the automotive and aerospace sectors are separating transportation, treatment, and certificate-of-destruction procurement to optimize unit economics by geography. This pattern is most visible in Germany and the US Midwest where generator density supports competitive bidding for individual waste codes.
Hazardous Waste Treatment System Market Segmentation
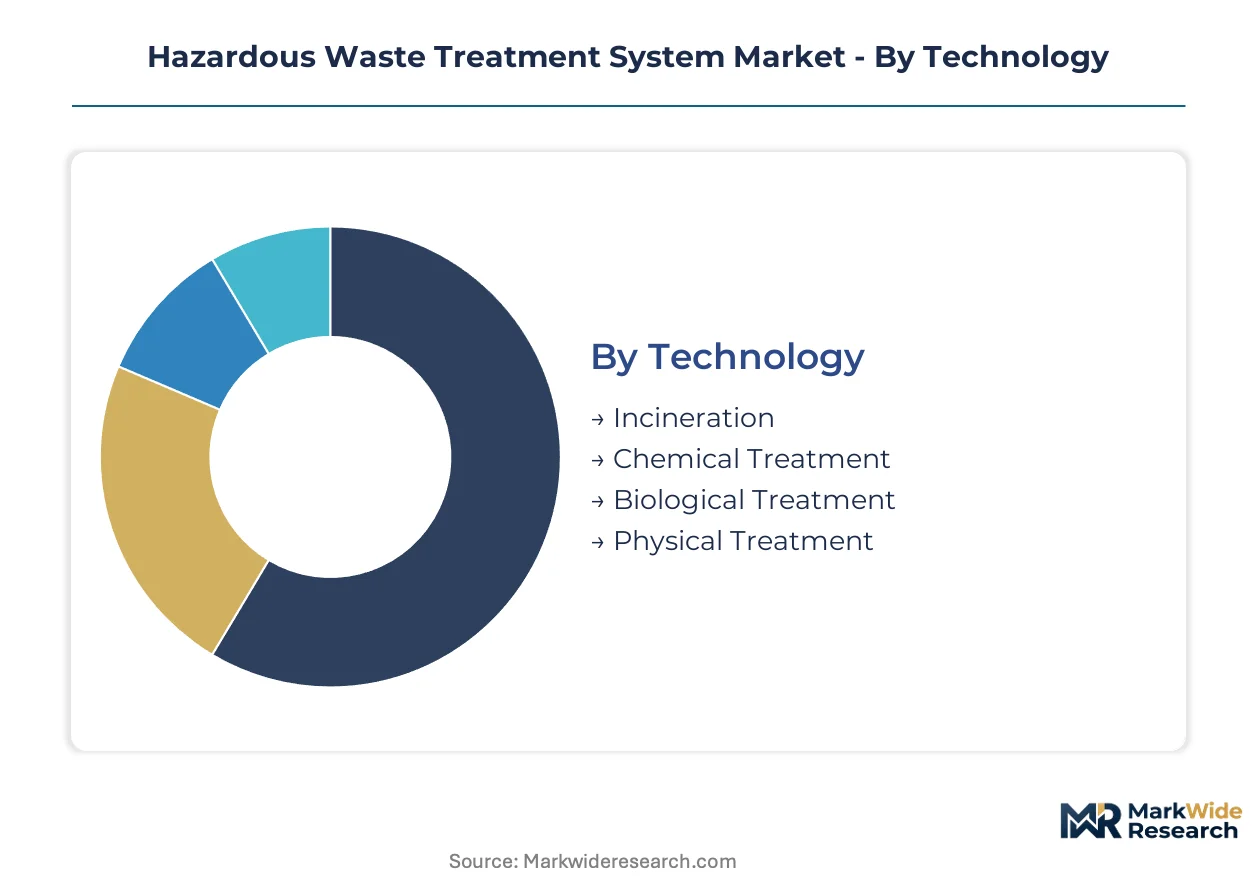
Technology selection dictates capital intensity and permitting complexity for hazardous waste treatment operators. End-user concentration and service unbundling trends are reshaping procurement patterns across industrial and healthcare verticals.
Technology:
Retrofit cycles for legacy thermal systems are compressing as EPA enforcement intensifies destruction and removal efficiency requirements.
- Incineration:Rotary kiln and liquid injection configurations operate above 1,100°C to achieve 99.99% destruction and removal efficiency for persistent organic pollutants. Pharmaceutical manufacturers in Germany and the US are prioritizing these systems for expired controlled substance destruction under tightening DEA and EMA oversight.
- Chemical Treatment:Neutralization, precipitation, and oxidation-reduction processes handle acid-bearing and mercury-laden wastes before landfill disposal. Chemical manufacturers in India are expanding neutralization capacity as Central Pollution Control Board import restrictions redirect domestic treatment demand.
- Biological Treatment:Ex-situ bioreactors and land farming degrade hydrocarbon-contaminated soils through microbial action.
- Physical Treatment:Filtration, centrifugation, and solidification/stabilization reduce waste volume and mobility prior to final disposal.
Volume placements concentrate in Incineration; the faster expansion belongs to Biological Treatment.
End User:
Cost-tier stratification separates large-quantity generators with captive treatment infrastructure from smaller facilities relying on commercial service providers.
- Industrial Sector:Petroleum refining, metal finishing, and electronics manufacturing generate complex mixed waste streams requiring multi-stage treatment trains. Automotive suppliers in the US Midwest are unbundling transportation and treatment procurement to optimize unit economics by waste code.
- Chemical Manufacturers:Specialty and commodity chemical producers face REACH authorization and downstream verification mandates for SVHC-containing wastes. Producers in China and India are certifying partner facilities against EU waste framework standards to maintain European market access.
- Healthcare Facilities:Hospitals and pharmaceutical distributors manage expired drugs, chemotherapeutic agents, and infectious wastes.
- Educational Institutions:University research laboratories generate small-quantity hazardous wastes with diverse chemical profiles.
Procurement scale peaks with Industrial Sector; Healthcare Facilities are climbing the fastest on pharmaceutical residue destruction mandates.
Service Type:
Customer-type fragmentation is driving modular service offerings that separate advisory, operational, and compliance functions.
- Waste Disposal Services:Transportation, treatment, and certificate-of-destruction provision for cradle-to-grave liability management. Clean Harbors Inc. and Waste Management Inc. compete on permitted facility networks and geographic coverage density.
- Compliance Services:RCRA manifest preparation, biennial reporting, and permit application support for large quantity generators. EPA inspection frequency doubling since 2022 is expanding retainer-based advisory engagements.
- Consulting Services:Waste minimization audits, treatment technology selection, and brownfield upgrade planning.
- Safety Audits:Facility assessments for leak detection, secondary containment, and personnel exposure protocols.
Revenue concentration sits with Waste Disposal Services; Compliance Services are gaining share fastest on regulatory enforcement intensity.
Application:
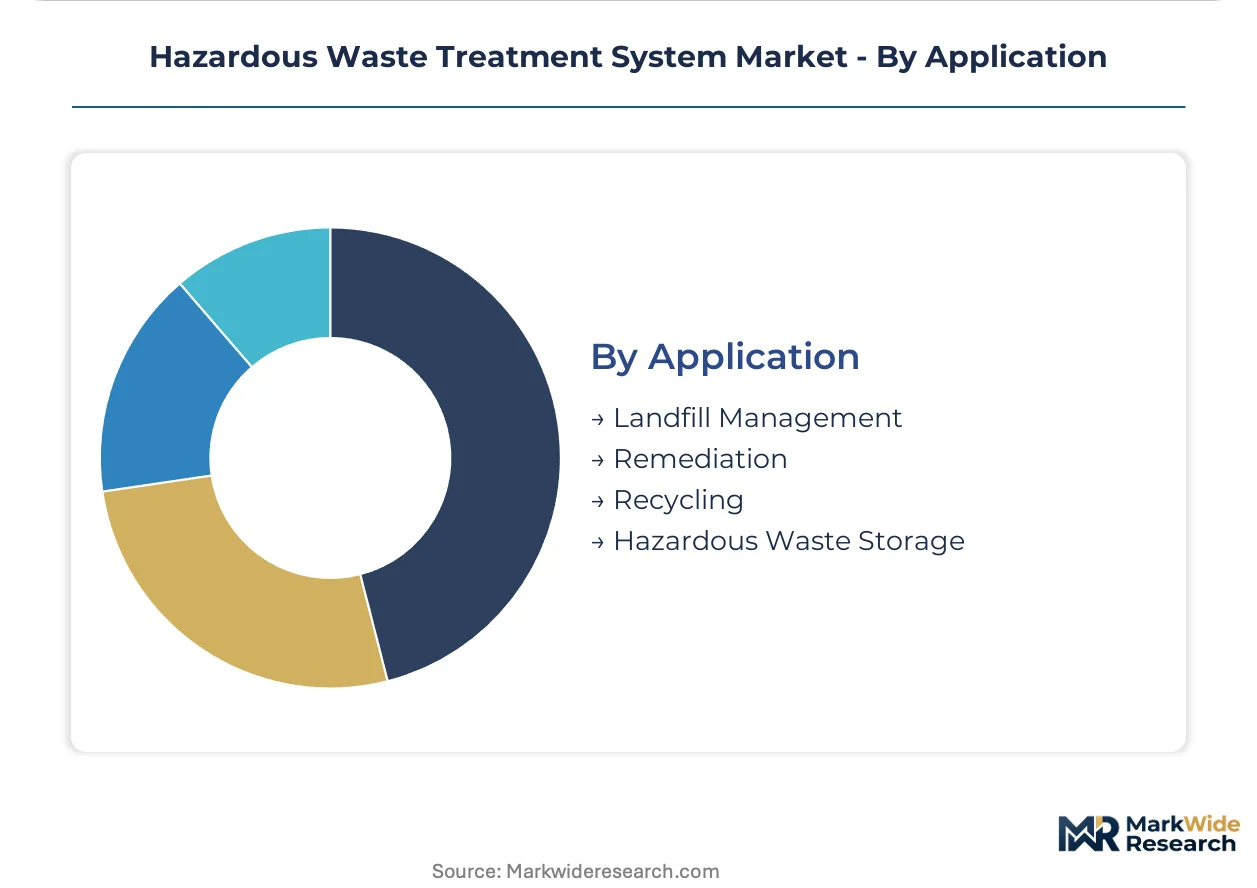
Geographic supply concentration shapes generator options, with fewer than twelve permitted commercial hazardous waste landfills serving the entire US market.
- Landfill Management:Permitted hazardous waste landfill operation with leachate collection and groundwater monitoring systems. Capacity bottlenecks in the US Northeast and Pacific Coast are extending transportation distances and elevating tipping fees.
- Remediation:Soil and groundwater cleanup at contaminated industrial sites using thermal desorption, bioremediation, or excavation. Construction and petroleum sectors in Texas and Alberta are deploying containerized thermal units for remote site processing.
- Hazardous Waste Storage:RCRA-permitted accumulation and container management pending treatment or disposal.
- Recycling:Solvent reclamation, metal recovery, and energy recovery from combustible wastes.
Activity levels peak in Landfill Management; Remediation is expanding most quickly on brownfield redevelopment and mining closure obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel anchors North American hazardous waste treatment capacity, hosting one of the continent's densest concentrations of permitted thermal processing facilities serving Gulf Coast petrochemical operations.
United States
Petrochemical complexes along the Texas-Louisiana corridor and pharmaceutical manufacturing in New Jersey drive treatment demand. EPA enforcement under RCRA has doubled inspection frequency since 2022, forcing generators toward permitted incineration infrastructure. Clean Harbors operates specialized remediation facilities across the Midwest while Waste Management maintains landfill networks in the Southeast.
Germany
Chemical producers in the Rhine-Ruhr industrial belt and pharmaceutical manufacturers in Bavaria require integrated treatment platforms. EU Green Deal industrial emissions targets and REACH downstream verification mandates compel facility upgrades. REMONDIS Medison GmbH and SUEZ Group maintain thermal processing infrastructure serving BASF and Bayer operations in Ludwigshafen and Leverkusen.
India
Specialty chemical manufacturing in Gujarat and petroleum refining in Maharashtra generate complex mixed waste streams. Central Pollution Control Board import restrictions redirect regional demand toward domestic neutralization capacity. Treatment operators in Ankleshwar and Vapi industrial estates are expanding acid-bearing waste handling certifications.
China
Electronics manufacturing in the Pearl River Delta and petrochemical operations in Shandong Province create persistent organic pollutant streams. Ministry of Ecology and Environment standards tighten destruction and removal efficiency requirements for pharmaceutical residues. Treatment infrastructure in the Yangtze River Delta is retrofitting rotary kiln configurations to meet updated emission limits.
Canada
Oil sands operations in Alberta and mining closures in British Columbia drive remote site remediation demand. Containerized thermal treatment units serve Fort McMurray extraction sites where transportation liability for reactive wastes proves prohibitive. Provincial regulators in Ontario are tightening leachate standards for permitted landfill operations serving Toronto-Windsor industrial corridors.
Hazardous Waste Treatment System Market Competitive Landscape
The competitive structure tilts toward integrated service providers with permitted facility networks rather than pure technology vendors. Market concentration reflects high barriers from RCRA permitting timelines and geographic supply bottlenecks. Two strategic archetypes dominate: multinational environmental services conglomerates with continental landfill networks, and specialized remediation operators with captive incineration assets. Capacity expansion and regulatory compliance bundling represent the dominant competitive moves as generators seek single-source liability management.
Among North American integrated providers, Clean Harbors Inc. and Waste Management Inc. exemplify the scale-driven archetype through extensive permitted treatment, storage, and disposal facility networks. Veolia Environment SA occupies a position representing European conglomerate integration of incineration and physical treatment platforms. These three entities anchor competitive positioning across their respective home markets while service unbundling trends create openings for specialized compliance advisory firms.
| Leading Market Players |
|---|
| Veolia Environment SA |
| Clean Harbors Inc. |
| Republic Services Inc. |
| Waste Management Inc. |
| Waste Connections Inc. |
| Stericycle Inc. |
| SUEZ Group |
| REMONDIS Medison GmbH |
| Bechtel Corp. |
| Others |
Supply & Pricing Matrix
Natural gas feedstock costs cascade through thermal treatment economics, compressing margins for rotary kiln operators in Texas and Louisiana while elevating tipping fees for generators in the US Northeast and Pacific Coast where landfill capacity bottlenecks concentrate. This input-cost pathway stratifies pricing tiers between integrated service providers with captive energy hedging and smaller operators exposed to spot fuel markets.
Pricing Analysis
Outcome-based pricing anchored to destruction and removal efficiency certifications dominates contract structures for pharmaceutical residue incineration. Pricing stratifies across RCRA-permitted facilities with 99.99% DRE verification, standard thermal platforms meeting baseline EPA standards, and economy tiers relying on chemical stabilization prior to landfill. Cost compression in economy tiers intensifies because mercury recovery limitations restrict landfill diversion rates. Large-quantity generators with captive transportation fleets exhibit lowest price sensitivity; small-quantity educational and research facilities face acute cost pressure.
Supply Chain Analysis
Freight costs for reactive and explosive wastes constrain generator options to permitted facilities within 500-mile radii, reinforcing geographic supply concentration. Thermal treatment capacity concentrates in the United States, Germany, and China where EPA, EU industrial emissions frameworks, and Ministry of Ecology and Environment standards enforce stringent operating permits. Equipment supply draws from specialized refractory manufacturers in Germany, combustion control system providers in Japan, and emissions monitoring technology from the United States. Single-source vulnerability sits with rotary kiln refractory supply where German producers anchor global output. Distribution runs through long-term offtake agreements with integrated environmental service providers rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around RCRA enforcement intensity that eliminates subscale operators lacking permitted facility networks. EPA inspection frequency doubling since 2022 accelerates this pressure, forcing capital deployment toward integrated infrastructure.
For Market Incumbents: Lock in generator relationships through bundled compliance services spanning manifest preparation, biennial reporting, and certificate-of-destruction provision. Substitute technology threats from plasma gasification vendors require defensive patent positioning and exclusive equipment supply agreements with rotary kiln refractory producers. Capacity addition in the US Midwest captures unbundling trends among automotive suppliers separating transportation and treatment procurement. For New Entrants and Emerging Players: Industrial laboratories and university research facilities represent the most penetrable segment given acute price sensitivity and fragmented incumbent service. Containerized thermal treatment units for remote mining and oilfield sites in Alberta and Texas offer white-space expansion where transportation liability proves prohibitive for established networks. Go-to-market execution should prioritize equipment-leasing partnerships with regional environmental consultants already embedded in generator compliance workflows. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale remediation operators with captive incineration assets in the US Southeast where landfill capacity concentration creates geographic bottlenecks. Long-term viability rests on RCRA permit renewal timelines extending operational moats beyond the analysis window. Watch EPA enforcement budget allocations as the inflection signal indicating generator compliance spending acceleration or deceleration.| Strategic Initiative | Industry Significance |
|---|---|
| RCRA Permit Expansion | Extends geographic coverage density for integrated service providers competing on cradle-to-grave liability management. |
| Backward Integration into Refractory Supply | Secures kiln lining replacement schedules against German producer capacity constraints and import lead times. |
| Containerized Thermal Unit Deployment | Captures remote site remediation demand in Alberta oil sands and Texas Permian Basin where transportation liability dominates. |
| EU Waste Framework Certification | Enables Indian and Chinese chemical producers to maintain REACH downstream verification for European market access. |
| Plasma Gasification Pilot Partnerships | Positions incumbents for municipal and industrial waste co-processing applications previously reserved for pure hazardous streams. |
Research Methodology
Independent corroboration across facility operations directors, RCRA compliance officers at large-quantity generators, refractory supply chain managers, and EPA regional enforcement staff underwrites the qualitative findings. Primary interviews with thermal treatment plant engineers and pharmaceutical waste coordinators combined with secondary validation from EPA enforcement data, ECHA substance evaluation cycles, Central Pollution Control Board import restriction filings, and SEC 10-K disclosures from publicly traded environmental services firms. Bottom-up capacity modeling across permitted treatment, storage, and disposal facilities triangulates against top-down expenditure estimates from chemical manufacturing and healthcare verticals.
Comparable-period anchoring to historical RCRA inspection frequency trends and thermal treatment capacity utilization rates structures the projection horizon. Segmentation dimensions span technology type, end-user vertical, service unbundling configuration, and geographic regulatory cluster. CAGRs derive from facility-level throughput projections weighted by EPA enforcement intensity indices and EU Green Deal industrial emissions compliance deadlines. Industry-specific forecast inputs include pharmaceutical residue volume growth from healthcare system consolidation and mercury-laden waste generation rates from specialty chemical manufacturing expansion.
Caveats apply where EPA enforcement budget reallocations, EU waste framework directive amendments, or refractory supply disruptions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Alkalinity Control Chemicals Market
Water & Sludge Treatment
Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
US Sludge Management and Dewatering Market
Water & Sludge Treatment
Sludge Treatment and Disposal Equipment Market
Water & Sludge Treatment
Salt Water Softeners Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
Water Treatment Market
Water & Sludge Treatment
Africa Water Treatment Chemicals Market
Water & Sludge Treatment
India Water Treatment Market
Water & Sludge Treatment
Global Sodium Hypochlorite Market
Water & Sludge Treatment
Water Softening Systems Market
Water & Sludge Treatment
Semiconductor Wastewater Treatment Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Saudi Arabia Industrial Hazardous Waste Management Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market