
 Middle-East and Africa Membrane Water Treatment Chemicals Market | 2026-2036
Middle-East and Africa Membrane Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Membrane Water Treatment Chemicals Market Foresight
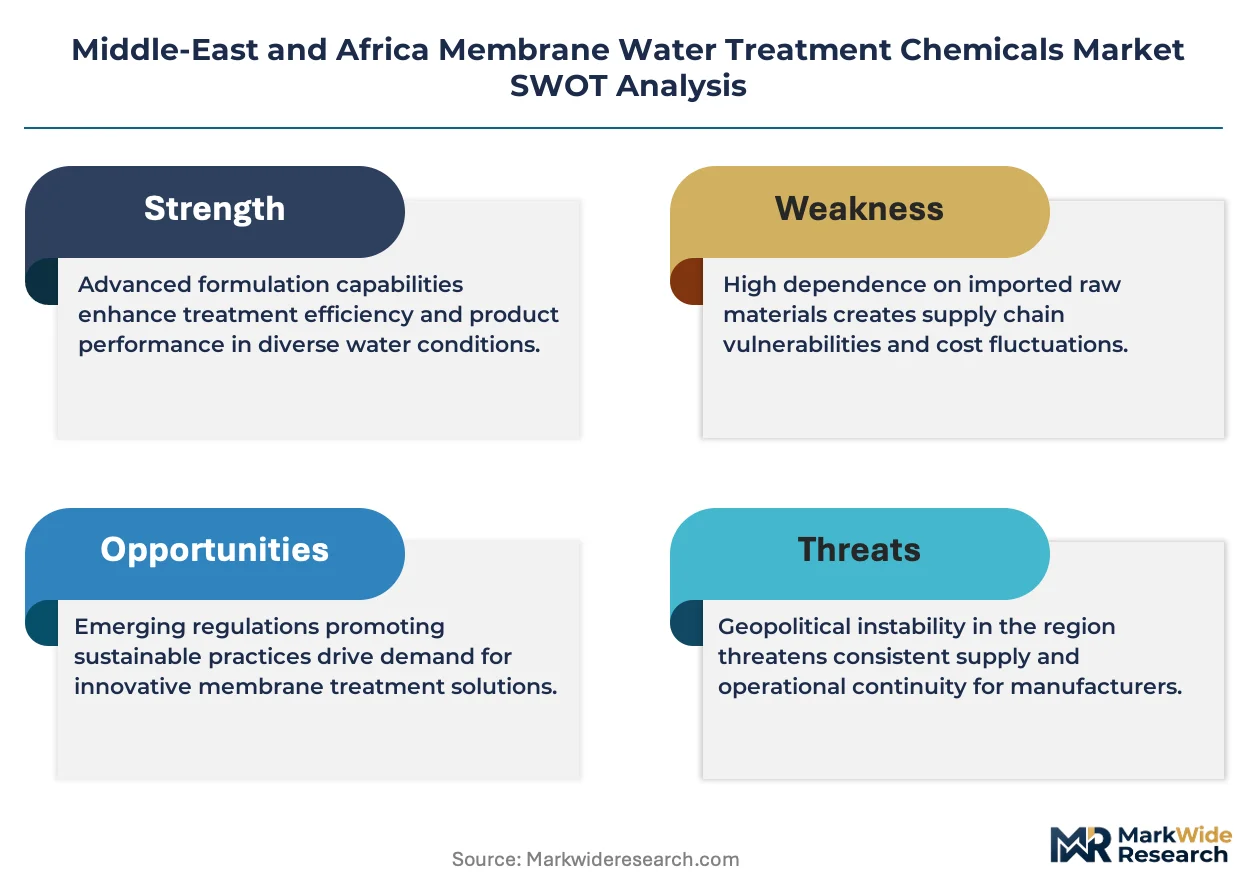
Project finance tied to desalination megaprojects is fragmenting the competitive landscape for membrane chemical supply contracts. Ecolab leverages its integrated water management platform to secure long-term service agreements with municipal operators across the Gulf. Kemira anchors its position through backward integration into polymer manufacturing, ensuring supply security for coagulant and flocculant volumes. Suez competes by specializing in high-salinity antiscalant formulations engineered for Red Sea intake conditions.
Middle-East and Africa membrane water treatment chemicals comprise functional additives dosed into membrane-based separation systems to prevent mineral scaling, biofouling, and particulate deposition, with antiscalants typically formulated from phosphonates or polyacrylic acids at active concentrations of 2–10 ppm depending on feedwater chemistry. These chemicals sustain permeate flux rates and extend membrane element lifespans in thermal and pressure-driven desalination trains. Antiscalants command the largest product type share due to the extreme calcium sulfate and silica saturation indices encountered in regional seawater feeds, while biocides represent the fastest-expanding category as operators confront accelerated biofilm formation in warm Gulf waters. Reverse osmosis technology dominates application volumes, though ultrafiltration pretreatment trains are gaining chemical intensity as hybrid membrane configurations spread across new municipal installations.
Saudi Arabia's SFDA and the UAE's MOHAP enforce potable water quality standards that directly specify maximum allowable residual antiscalant concentrations, forcing reformulation toward more biodegradable chemistries. Egypt's holding company for water and wastewater and South Africa's Department of Water and Sanitation are tightening discharge limits that elevate biocide selection criteria for industrial membrane plants. Stakeholders must monitor how evolving national water security strategies across the region reshape procurement centralization and qualification requirements for chemical suppliers.
Market Dynamics
Project finance structures for desalination megaprojects are fragmenting membrane chemical procurement into long-term service agreements, forcing suppliers to absorb operational risk and embed technical staff at plant sites across the Gulf Cooperation Council states.
Growth Catalysts
- SFDA Antiscalant Mandates:Saudi Arabia's tightening potable water quality standards are forcing reformulation toward biodegradable phosphonates, expanding the addressable market for compliant chemistries.
- Red Sea Intake Conditions:Extreme calcium sulfate saturation indices in regional seawater feeds are elevating antiscalant dosing intensity across thermal and reverse osmosis desalination trains.
- Hybrid Membrane Configurations:Ultrafiltration pretreatment trains spreading across new municipal installations in the UAE are raising chemical consumption per unit of permeate output.
Market Restraints
- Phosphonate Feedstock Volatility:Concentrated global production of phosphonic acid precursors in Chinese manufacturing clusters exposes regional formulators to input cost swings and supply interruptions.
- Discharge Limit Stringency:Egypt's holding company for water and wastewater and South Africa's Department of Water and Sanitation are tightening biocide effluent standards, constraining active ingredient selection and complicating formulation.
- Membrane Element Standardization:Proprietary interconnector geometries from dominant element manufacturers lock chemical suppliers into compatibility testing protocols that delay product qualification cycles.
Strategic Opportunities
- East African Municipal Expansion:Kenya and Tanzania are tendering their first large-scale reverse osmosis plants for coastal cities, creating virgin territory for membrane chemical specification.
- Biocide Polymer Convergence:Combination products integrating antiscalant and biofouling control functions are gaining traction in offshore oil and gas facilities seeking simplified dosing logistics.
- Service Contract Bundling:Remote membrane performance monitoring platforms are enabling chemical suppliers to capture recurring revenue streams through predictive cleaning and replacement scheduling.
Industry Challenges
- Specialized Field Chemist Scarcity:Plants operating large-scale reverse osmosis trains require personnel capable of interpreting saturation indices and adjusting dosing protocols in real time, yet regional training pipelines remain underdeveloped.
- Qualification Timeline Compression:Accelerated project delivery schedules for desalination megaprojects are compressing the window for pilot-scale membrane compatibility testing, elevating risk of premature element failure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Membrane Water Treatment Chemicals Market |
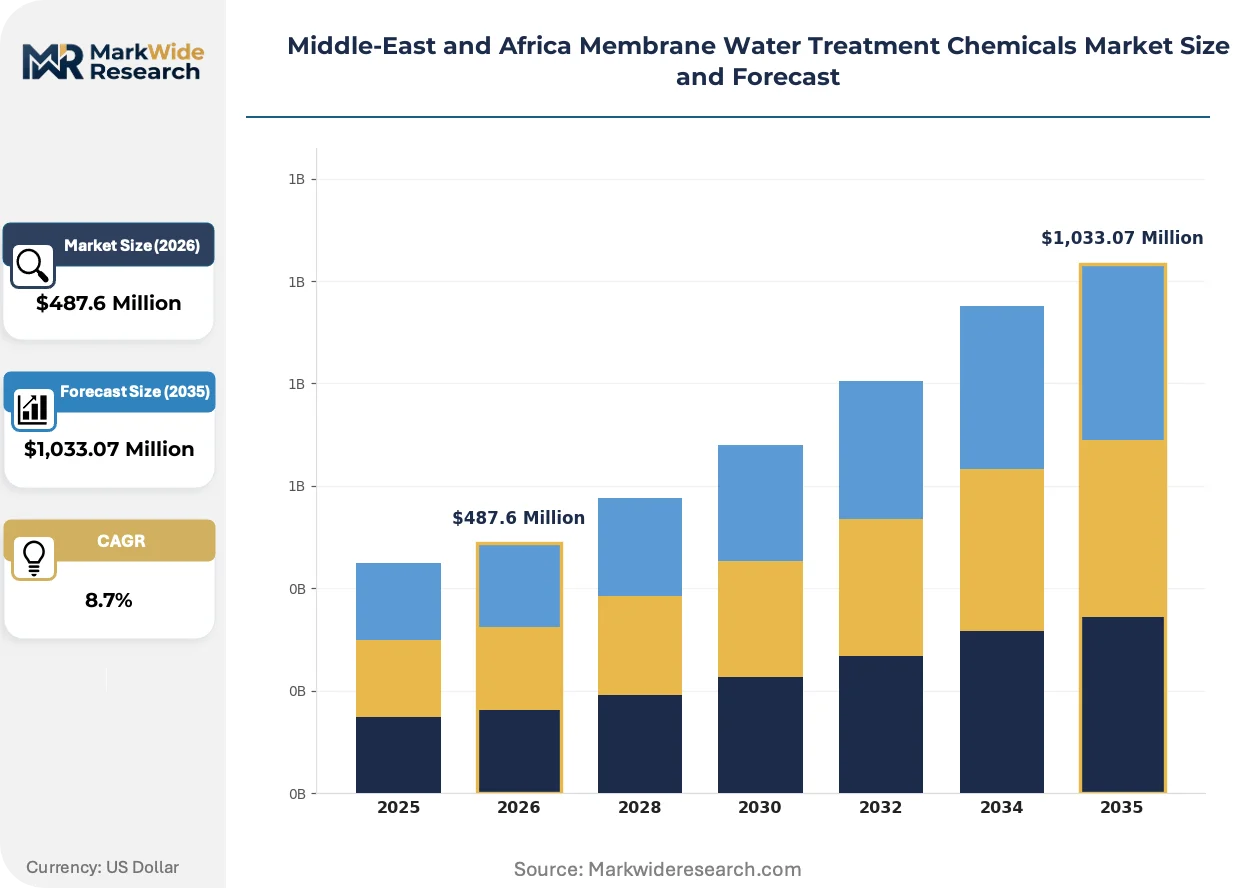
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiscalants, Biocides, Flocculants, Coagulants End User: Municipal, Industrial, Oil & Gas, Power Generation Application: Desalination, Wastewater Treatment, Process Water, Drinking Water Technology: Reverse Osmosis, Ultrafiltration, Nanofiltration, Electrodialysis |
| Companies Covered | Ecolab, Kemira, Kurita Water Industries Ltd, Solenis, Dow, AES Arabia Ltd, Veolia, Suez, Genesys International Ltd, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Membrane Water Treatment Chemicals Market Shifts & Advancements
Membrane water treatment chemistry across the Middle-East and Africa is pivoting toward predictive dosing systems and biodegradable actives as operators confront warm-water biofouling acceleration and tightening discharge oversight.
Polymeric antiscalant formulations incorporating hyperbranched dendrimer structures are rendering obsolete conventional polyacrylic acid chemistries in high-silica feedwaters. Saudi Arabia's Saline Water Conversion Corporation and Qatar's Kahramaa have adopted these materials for new megaproject tenders. The shift is compressing margins for suppliers lacking polymer synthesis capabilities while rewarding backward-integrated formulators.
MOHAP in the UAE has enacted maximum residual concentration limits for antiscalant byproducts in potable water outputs, mirroring trajectory of Saudi SFDA standards. Industrial membrane plants serving food and beverage processors must now document biodegradability profiles through standardized OECD testing protocols. Formulators are responding by accelerating phosphonate replacement with carboxylate-rich polymer alternatives.
Long-term chemical supply agreements are displacing spot procurement across municipal desalination operators in Oman and Bahrain. EPC contractors are bundling membrane chemical provisions into 15-20 year operations contracts, transferring specification authority from plant chemists to finance-driven procurement desks. This consolidation is most visible in Abu Dhabi's independent water and power project pipeline, where single-source chemical provisioning has become a standard tender requirement.
Middle-East and Africa Membrane Water Treatment Chemicals Market Segmentation
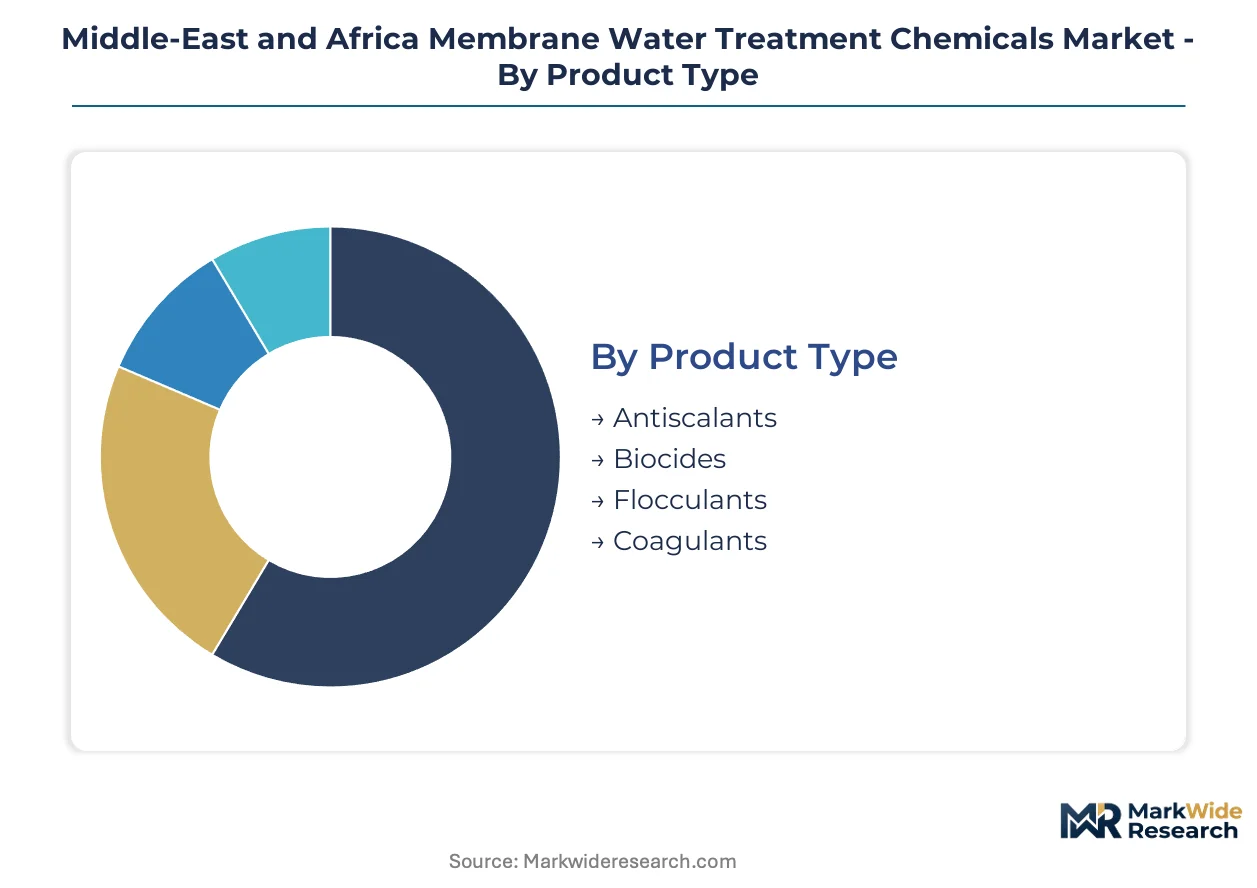
Membrane chemical procurement across the Middle-East and Africa fragments along distinct technical and operational axes. Product chemistry, end-use facility type, application severity, and membrane technology each dictate dosing protocols, qualification requirements, and supplier selection criteria.
Product Type:
Cost tier positioning separates commodity formulations from specialty polymers with proprietary dendrimer architectures.
- Antiscalants:Phosphonate-based and polyacrylic acid formulations dominate at 2–10 ppm active concentrations. Demand concentrates in Saudi Arabia's Saline Water Conversion Corporation megaprojects where extreme calcium sulfate saturation indices in Red Sea intake waters force continuous high-rate dosing.
- Biocides:Oxidizing and non-oxidizing actives combat accelerated biofilm formation in warm Gulf waters. Procurement is intensifying across UAE industrial zones where power generation and oil and gas facilities operate large-scale reverse osmosis trains requiring specialized biofouling control.
- Flocculants:Cationic and anionic polymer variants assist suspended solids removal upstream of membrane trains. Egyptian municipal tenders specify these for Nile Delta surface water pretreatment.
- Coagulants:Aluminum and iron-based chemistries reduce organic fouling potential. South African Department of Water and Sanitation discharge limits are tightening selection criteria for industrial membrane plants.
Antiscalants hold installed capacity. Biocides is rotating up the share rankings.
End User:
Application context determines specification authority and contract structure across facility ownership models.
- Municipal:National water security strategies reshape procurement centralization. Gulf Cooperation Council desalination operators are consolidating chemical supply into 15–20 year operations contracts with single-source provisioning requirements.
- Industrial:Food and beverage processors must document antiscalant biodegradability profiles through OECD testing protocols under tightening SFDA and MOHAP residual concentration limits.
- Oil & Gas:Offshore facilities seek simplified dosing logistics through combination products integrating antiscalant and biofouling control functions.
- Power Generation:Independent water and power projects in Abu Dhabi mandate bundled membrane chemical provisions within project finance structures.
Municipal holds installed capacity. Oil & Gas is rotating up the share rankings.
Application:
Feedwater severity and product water quality requirements differentiate chemical intensity and active selection.
- Desalination:Thermal and pressure-driven trains encounter extreme mineral scaling potential. Hybrid membrane configurations spreading across new UAE municipal installations raise chemical consumption per unit of permeate output.
- Wastewater Treatment:Membrane bioreactor applications require biofouling management alongside nutrient removal. Kenya and Tanzania coastal city tenders are creating virgin specification territory.
- Process Water:Industrial boiler feed and cooling tower makeup demand consistent permeate quality. Qatar's Kahramaa specifications govern procurement for utility-scale installations.
- Drinking Water:Potable output mandates directly specify maximum allowable residual antiscalant concentrations, forcing reformulation toward biodegradable phosphonate alternatives.
Desalination holds installed capacity. Wastewater Treatment is rotating up the share rankings.
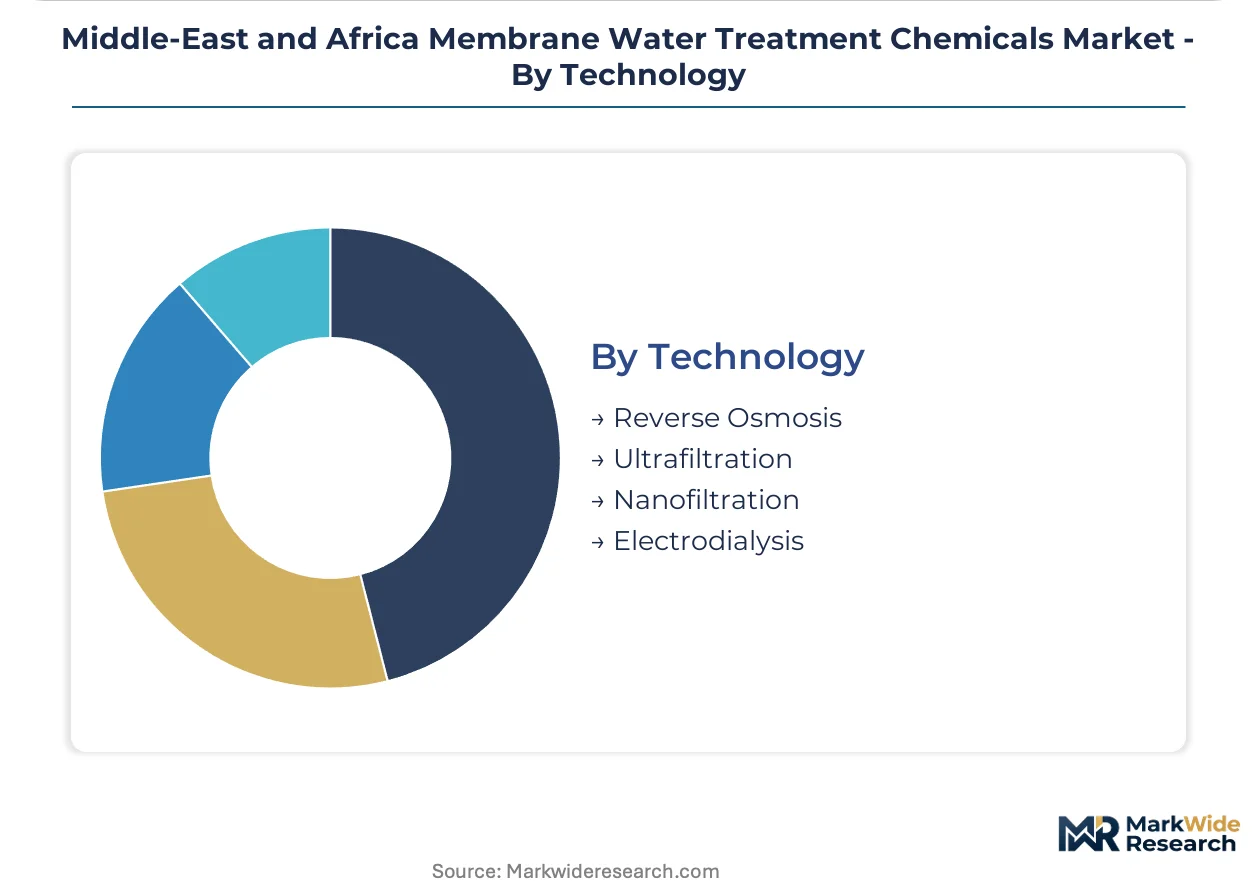
Technology:
Membrane pore size and driving force determine fouling mechanisms and compatible chemical actives.
- Reverse Osmosis:Spiral-wound elements dominate desalination capacity. Proprietary interconnector geometries from dominant element manufacturers lock chemical suppliers into compatibility testing protocols.
- Ultrafiltration:Hollow fiber configurations serve as pretreatment to reverse osmosis or stand-alone filtration. Ultrafiltration trains are gaining chemical intensity as hybrid configurations spread.
- Nanofiltration:Selective ion rejection suits softening and partial desalination applications. Industrial process water circuits in South Africa deploy these for specific contaminant removal.
- Electrodialysis:Electrically driven ion exchange serves niche brackish water applications. Limited deployment concentrates in research and pilot installations.
Reverse Osmosis holds installed capacity. Ultrafiltration is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for phosphonate precursors shapes regional procurement strategies, with Gulf Cooperation Council states sourcing concentrated feedstocks from Asian manufacturing clusters while local formulators compete on technical service proximity.
Saudi Arabia
Saline Water Conversion Corporation megaprojects drive antiscalant consumption at extreme dosing rates. SFDA potable water quality mandates enforce maximum residual concentration limits for phosphonate byproducts. Riyadh-based procurement desks centralize chemical supply into 15-20 year operations contracts.
United Arab Emirates
Power generation and oil and gas facilities operate large-scale reverse osmosis trains requiring specialized biocide formulations. MOHAP residual concentration limits mirror Saudi SFDA standards for potable outputs. Abu Dhabi's independent water and power project pipeline mandates single-source chemical provisioning.
South Africa
Industrial membrane plants face tightening discharge limits from the Department of Water and Sanitation constraining biocide selection. Process water circuits deploy nanofiltration for specific contaminant removal. Gauteng province concentrates membrane chemical demand from mining and manufacturing sectors.
Egypt
The holding company for water and wastewater elevates biocide effluent standards for municipal and industrial installations. Nile Delta surface water pretreatment specifications drive flocculant procurement. Coastal city tenders are creating specification territory for first large-scale reverse osmosis plants.
Qatar
Kahramaa utility-scale installations govern procurement for boiler feed and cooling tower makeup applications. New megaproject tenders specify hyperbranched dendrimer antiscalant structures for high-silica feedwaters. Doha-based operators consolidate chemical supply into long-term service agreements.
Middle-East and Africa Membrane Water Treatment Chemicals Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation expertise. The supplier base organizes around three archetypes: integrated water management platforms, backward-integrated polymer manufacturers, and specialty chemical formulators. Competitive positioning hinges on securing long-term operations contracts and embedding technical staff at plant sites. Dominant moves include service contract bundling and predictive dosing platform deployment.
Within the integrated platform tier, Ecolab leverages its water management infrastructure to anchor municipal positions across the Gulf. Kemira exemplifies backward-integrated formulators through captive polymer manufacturing capabilities. Suez occupies a position among specialty formulators engineering high-salinity antiscalant chemistries for Red Sea conditions.
| Leading Market Players |
|---|
| Ecolab |
| Kemira |
| Kurita Water Industries Ltd |
| Solenis |
| Dow |
| AES Arabia Ltd |
| Veolia |
| Suez |
| Genesys International Ltd |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese phosphonic acid precursor manufacturing clusters is compressing input costs for regional formulators while simultaneously eroding pricing power for commodity antiscalant grades. Gulf Cooperation Council procurement desks exploit this softness to extract longer payment terms and bundled service concessions from suppliers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels differentiated by active concentration and biodegradability certification. Gulf municipal operators with 15-20 year operations contracts command the lowest unit economics, while offshore oil and gas facilities absorbing technical risk pay premiums for combination biocide-antiscalant formulations. Cost compression in phosphonate feedstocks is intensifying because of concentrated Asian manufacturing, though SFDA-mandated biodegradable reformulations sustain margin pockets for compliant polymer suppliers. Municipal desalination operators exhibit the highest price sensitivity, whereas isolated industrial sites with membrane performance guarantees show minimal elasticity.
Supply Chain Analysis
Contract manufacturing for phosphonate precursors concentrates in Zhejiang and Shandong province chemical parks, with formulation tolling distributed across Jebel Ali and Jubail industrial zones. Regional supply chains draw from concentrated Chinese phosphonic acid output, Saudi polymer synthesis capabilities, and European specialty additive imports. Single-source vulnerability in phosphonate feedstocks exposes formulators to export license interruptions and shipping chokepoint delays through the Strait of Hormuz. Distribution runs through bulk liquid tanker networks serving desalination megaproject sites, supplemented by drum packaging for smaller industrial membrane plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating across Gulf Cooperation Council municipal operators consolidating chemical procurement into single-source 15-20 year operations contracts, fragmenting supplier negotiating leverage.
For Market Incumbents: Entrench positions through backward integration into hyperbranched dendrimer polymer manufacturing and embedding field chemists at Saline Water Conversion Corporation megaproject sites. Ecolab-style integrated water management platforms threaten standalone formulators lacking predictive dosing capabilities. Prioritize certification investment for SFDA and MOHAP biodegradable compliance to defend margin tiers against commodity phosphonate suppliers. For New Entrants and Emerging Players: Establish a beachhead in Kenya and Tanzania coastal city reverse osmosis tenders where virgin specification territory exists and incumbent technical service networks remain undeveloped. East African municipal expansion offers the most penetrable geography given limited existing supplier relationships. Pursue a go-to-market angle bundling remote membrane performance monitoring with chemical supply to capture recurring revenue streams. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biodegradable polymer synthesis sub-segments as reformulation mandates multiply. The 5-10 year viability window favors acquiring backward-integrated formulators with captive dendrimer production capabilities rather than asset-light distributors. Watch for Kahramaa and SWCC tender specifications mandating hyperbranched antiscalant structures as the inflection signal for polymer synthesis capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Kemira's captive manufacturing model ensures supply security for coagulant volumes across Gulf municipal tenders. |
| Long-term Service Agreement Bundling | Ecolab secures 15-20 year municipal contracts by embedding technical staff at plant sites. |
| Biodegradable Formulation Reformulation | SFDA and MOHAP residual limits force phosphonate replacement with carboxylate-rich polymer alternatives. |
| Predictive Dosing Platform Deployment | Remote membrane monitoring enables suppliers to capture recurring revenue through cleaning scheduling. |
| Regional Manufacturing Footprint Expansion | Jebel Ali and Jubail tolling capacity reduces logistics exposure through Hormuz chokepoints. |
Research Methodology
Cross-validation between primary interviews with desalination plant chemists, municipal procurement officers, and polymer R&D directors and secondary sources including customs trade data, SWCC tender documentation, and SEC chemical company filings anchors the qualitative findings. Bottom-up triangulation against top-down membrane installation capacity estimates validates volume assumptions across product chemistry and end-use segments.
Calibration against historical antiscalant dosing intensity patterns and biocide consumption rates in Red Sea versus Arabian Gulf intake conditions shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use facility ownership structure, membrane technology configuration, and regional regulatory cluster. CAGRs derive from installed capacity buildout schedules and chemical intensity coefficients per permeate output, with specific inputs from hybrid ultrafiltration-reverse osmosis configuration spreads and biodegradable reformulation adoption curves.
Sensitivities concentrate around phosphonate feedstock export restrictions, accelerated SFDA biodegradability mandate timelines, and project finance delays for desalination megaprojects. Forecasts reflect documented assumptions on dosing rate evolution and membrane element replacement cycles. Quarterly review of Kahramaa and SWCC tender specifications, Chinese phosphonic acid production utilization rates, and Red Sea salinity index anomalies is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Membrane Bioreactor (MBR) Market
Water & Sludge Treatment
Liquid Waste Container Market
Water & Sludge Treatment
Australia & New Zealand Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
Global Water Softeners Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market
Water & Sludge Treatment
Saudi Arabia Industrial Hazardous Waste Management Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market
Water & Sludge Treatment
Alkalinity Control Chemicals Market
Water & Sludge Treatment
India Water Treatment Market