
 Global Valves in Water and Wastewater Market | 2026-2036
Global Valves in Water and Wastewater Market Size, Share, and Industry Trends Forecast 2026-2036
Global Valves in Water and Wastewater Market Insights
Municipal water infrastructure is repositioning capital toward smart distribution networks and leakage reduction systems. Flowserve Corporation leverages its rotating equipment heritage to compete in high-pressure pumping station applications. KSB SE & Co. KGaA anchors European supply through its deep specialization in wastewater treatment plant configurations. Emerson Electric Co. differentiates via integrated digital valve monitoring platforms that extend service intervals and reduce unplanned downtime.
Valves in water and wastewater are flow control devices manufactured from ductile iron, stainless steel, or thermoplastic composites, designed to operate at pressures ranging from ambient to over 25 bar depending on distribution network specifications; they regulate, isolate, or throttle fluid movement across treatment and conveyance systems. Butterfly valves dominate large-diameter municipal installations where cost efficiency and quarter-turn actuation matter most, while ball valves command premium positioning in precision dosing and industrial process streams. Gate valves retain mature, steady demand in underground distribution networks where full-bore, low-friction isolation remains the functional priority.
The EPA enforces drinking water quality standards that mandate material compliance and lead-free construction, while the EU Drinking Water Directive and REACH framework restrict hazardous substance migration into potable systems. China's MEE imposes discharge limits that force wastewater facilities to upgrade control valve precision and automation density. Stakeholders must monitor regulatory divergence between jurisdictions to align product certification roadmaps with procurement timelines.
Market Dynamics
Municipal utilities are consolidating valve procurement around predictive maintenance platforms that compress replacement cycles and reduce emergency callouts. EPA Lead and Copper Rule revisions in the United States are forcing wholesale infrastructure audits across aging distribution networks.
Growth Catalysts
- Smart Water Infrastructure Mandates:China's MEE discharge limits are accelerating automation retrofits in wastewater treatment facilities, driving precision control valve demand.
- EU Drinking Water Directive:REACH-compliant material specifications are expanding specification requirements for lead-free brass and polymer-lined ductile iron across European municipal tenders.
- Leakage Reduction Targets:Singapore's PUB and Thames Water in the United Kingdom are deploying pressure management valves to achieve sub-10% non-revenue water metrics.
Market Restraints
- Raw Material Volatility:Nickel and copper price swings are compressing margins on stainless steel and bronze alloy valve production.
- Foundry Capacity Concentration:Ductile iron casting capacity clusters in China and India, creating supply vulnerability for Western valve assemblers.
- Technical Limitation:Thermoplastic valves face pressure-temperature constraints above 16 bar that limit penetration in high-head pumping stations.
Strategic Opportunities
- Underpenetrated Geography:Indonesia's urban water utilities are replacing manual gate valves with automated butterfly configurations in Jakarta and Surabaya distribution zones.
- Technology Convergence:Digital twin platforms are converging with valve actuation systems to enable real-time hydraulic modeling in Danish and Dutch water networks.
- Regulatory Tailwind:Australia's Water Efficiency Labelling and Standards scheme is creating specification pull for low-flow precision valves in residential metering applications.
Industry Challenges
- Skill Gap in Actuation Integration:Municipal maintenance crews lack training in troubleshooting smart positioners and networked valve controllers.
- Certification Timeline Compression:NSF/ANSI 61 and WRAS approvals require 12-18 month validation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Valves in Water and Wastewater Market |
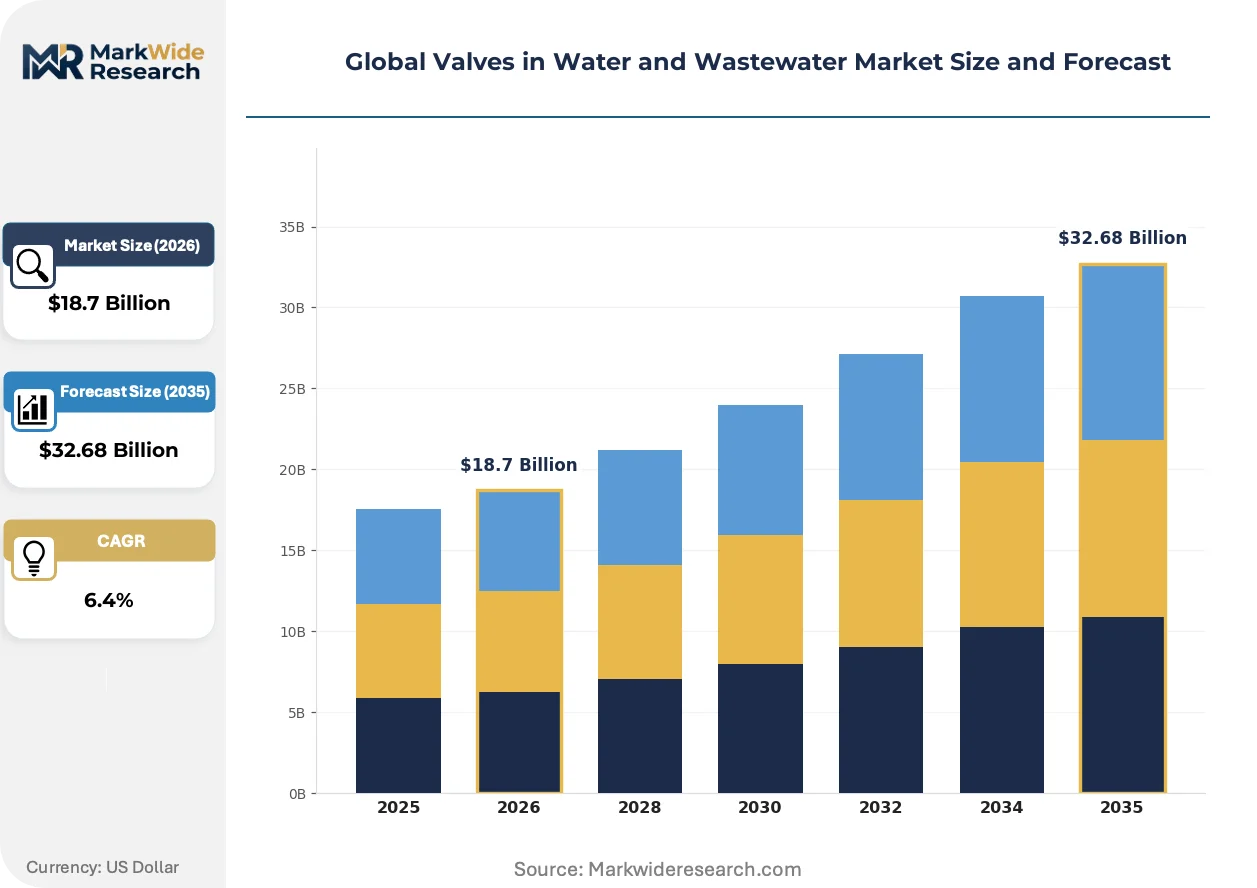
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Gate Valves, Butterfly Valves, Check Valves Application: Pumping Stations, Treatment Plants, Distribution Networks, Fire Protection Systems End User: Municipal, Industrial, Agricultural, Commercial Installation Type: Above Ground, Underground, Onshore, Offshore |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, Watts Water Technologies, Inc., Pentair plc, AVK Holding A/S, Mueller Water Products, Inc., KSB SE & Co. KGaA, VAG GmbH, Crane Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Valves in Water and Wastewater Market Trends and Innovations
Actuation intelligence and material science advances are redefining valve lifecycle economics. Equipment suppliers are repositioning around data-enabled service models rather than discrete hardware transactions.
Advanced polymer composites reinforced with glass fiber are converging with metal valve architectures to deliver corrosion resistance at 40% weight reduction. Coastal desalination plants in Saudi Arabia and Israel are specifying these hybrid constructions for seawater intake systems. The convergence is compressing stainless steel demand in moderate-pressure saline applications while expanding addressable scope for thermoplastic specialists.
REACH Annex XVII restrictions on lead content are mandating gunmetal replacement with silicon bronze and engineered polymers in potable water contact surfaces. Valve foundries in Germany and Italy are retooling casting lines to meet the 2026 compliance deadline. Specifiers in France and Spain are accelerating procurement of pre-certified alternatives to avoid project delays.
Performance contracting is displacing capital purchase models for large-diameter valve installations. French and British water operators are transferring operational risk to OEM service providers through availability-based agreements. The shift is most visible in sewage pumping stations where unplanned downtime penalties now exceed equipment capital costs.
Global Valves in Water and Wastewater Market Segmentation
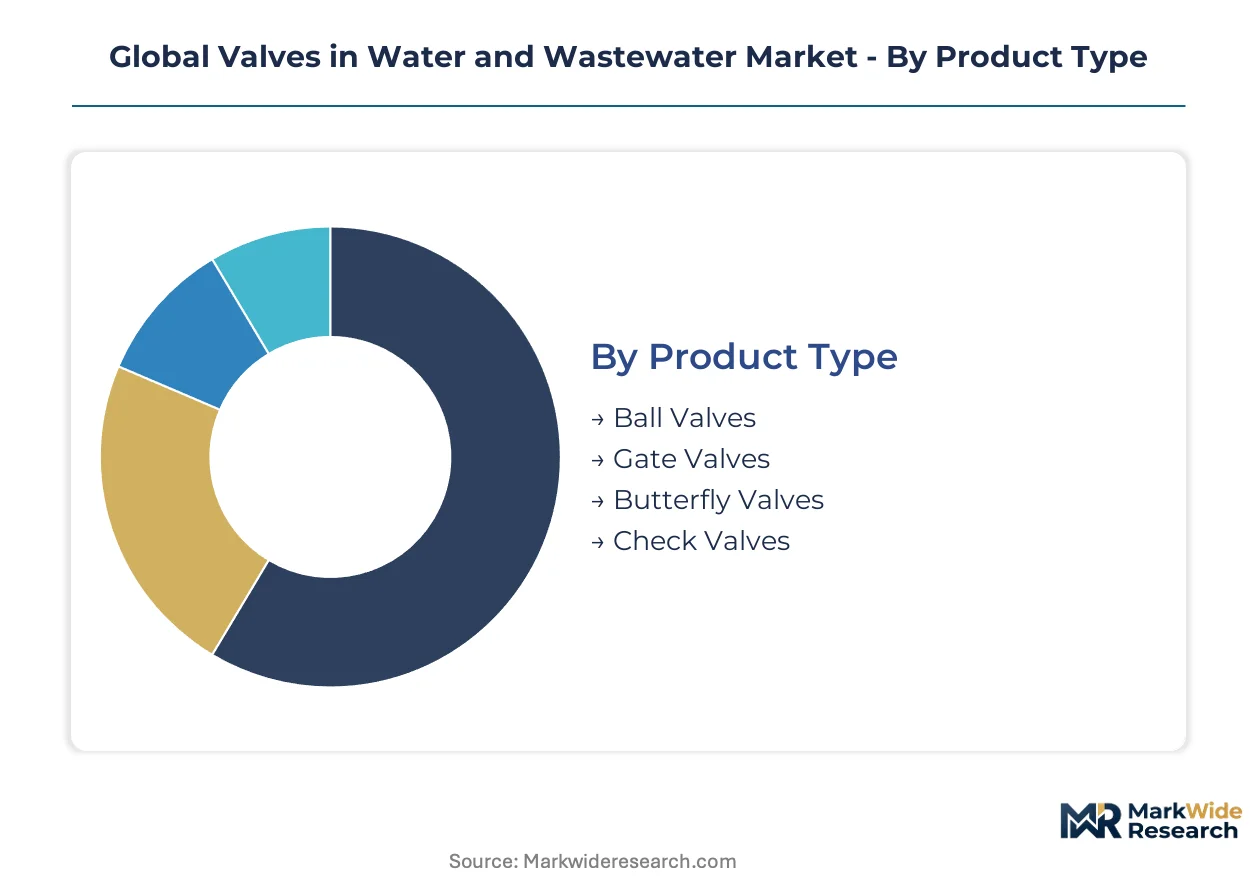
Valve specification in water and wastewater infrastructure hinges on pressure ratings, corrosion exposure, and actuation requirements that vary sharply across treatment, conveyance, and emergency systems. Procurement committees weight lifecycle cost against capital expenditure differently in municipal tenders versus industrial process specifications.
Product Type:
Material selection and actuation complexity drive buyer evaluation more than unit price.
- Butterfly Valves:Wafer and lug configurations dominate large-diameter municipal installations where quarter-turn electric actuation reduces operator burden. China's urban water network upgrades in Shanghai and Guangzhou absorb substantial procurement volumes for resilient-seated variants rated to 16 bar.
- Gate Valves:Full-bore, low-friction isolation remains the functional priority in underground distribution networks. Germany's Ruhrverband and France's Veolia specify OS&Y rising stem designs for buried service in legacy cast-iron mains replacement programs.
- Ball Valves:Precision dosing applications in chemical feed systems and high-pressure industrial process streams. Saudi Arabia's SWCC desalination plants specify super-duplex stainless trim for seawater reverse osmosis skids.
- Check Valves:Silent and swing configurations protect pumping infrastructure from water hammer. Netherlands' Waternet deploys spring-assisted axial designs in below-grade booster stations throughout Amsterdam's polder districts.
Volume sits with butterfly configurations; growth tilts toward ball valve precision instrumentation for smart network integration.
Application:
Operating pressure and fluid contamination levels determine specification rigor across the value chain.
- Treatment Plants:Multi-stage processes demand corrosion-resistant alloys and polymer-lined ductile iron for chemical dosing, sludge handling, and membrane filtration skids. Australia's Melbourne Water and Sydney Water specify NSF/ANSI 61-certified materials for potable contact surfaces.
- Pumping Stations:High-head applications above 25 bar require robust sealing systems and cavitation-resistant trim. Israel's Mekorot operates pressure-boosting facilities along the National Water Carrier with specialized valve stations rated for continuous duty cycles.
- Distribution Networks:Leakage reduction mandates accelerate pressure management valve deployment. Thames Water in the United Kingdom targets sub-10% non-revenue water through district metered area automation.
- Fire Protection Systems:UL/FM certification requirements govern butterfly and gate valve selection in commercial and industrial sprinkler networks. Dubai's civil defense authority mandates tamper-proof supervisory switches on all post-indicator valves.
Capital allocation concentrates in treatment plant expansions; retrofit urgency is accelerating fastest in aging distribution infrastructure.
End User:
Contracting mechanisms and maintenance capabilities diverge sharply across ownership structures.
- Municipal:Public procurement frameworks prioritize lifecycle costing and predictive maintenance compatibility. EPA Lead and Copper Rule revisions in the United States are forcing wholesale infrastructure audits across aging distribution networks.
- Industrial:Process reliability requirements drive specification toward redundant sealing and fail-safe actuation. Brazil's mining sector and South Africa's petrochemical complexes demand API-compliant designs for aggressive service conditions.
- Commercial:Building automation integration influences smart valve specification in high-rise developments. Singapore's PUB mandates water efficiency labeling for cooling tower makeup systems in commercial properties.
- Agricultural:Cost sensitivity favors thermoplastic and cast-iron configurations in irrigation districts. India's PM-KUSUM program is expanding drip and sprinkler coverage across Maharashtra and Gujarat with compatible valve infrastructure.
Revenue concentration remains with municipal utilities; industrial process automation is expanding most quickly.
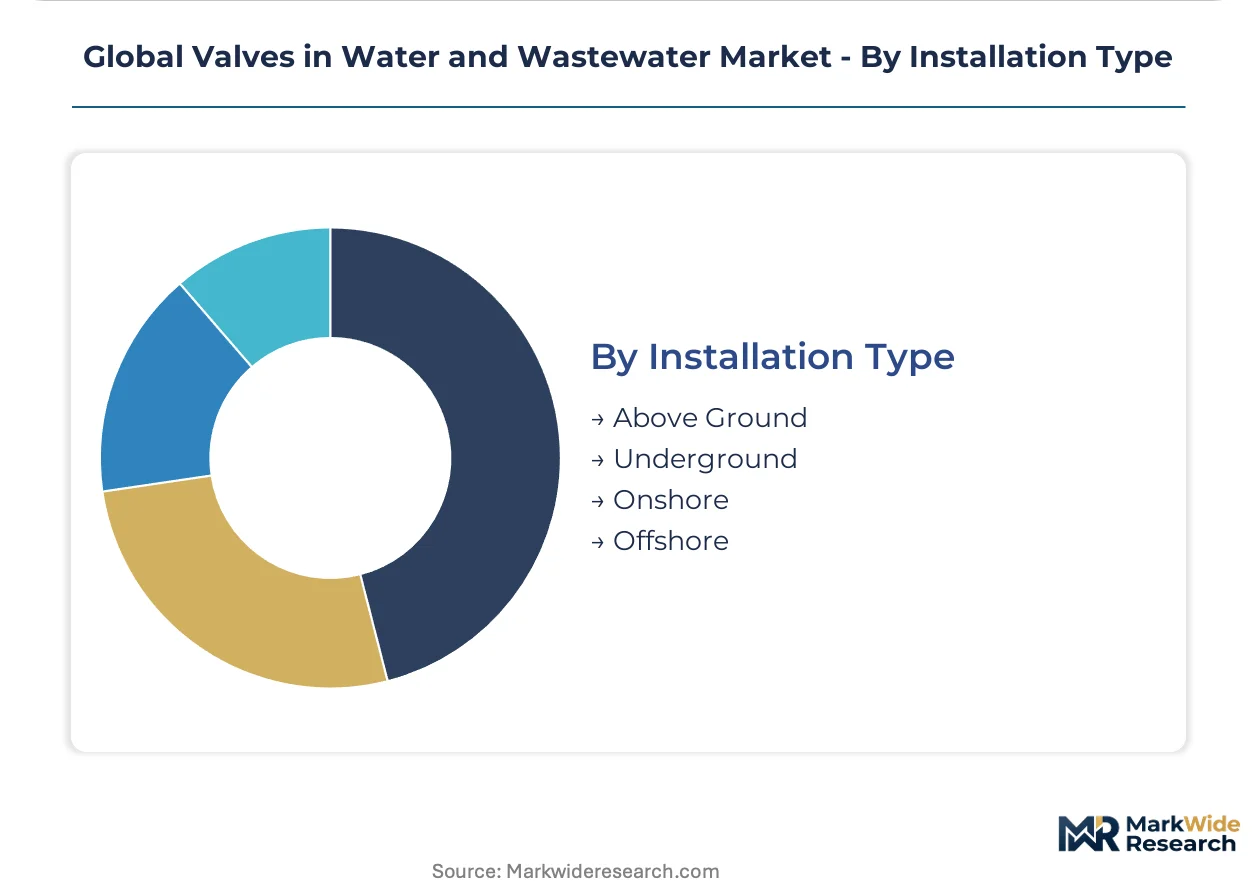
Installation Type:
Access constraints and environmental exposure dictate material and actuation packaging decisions.
- Underground:Buried service demands corrosion-resistant coatings and extension stems for valve operation without excavation. Paris and London water utilities specify fusion-bonded epoxy finishes for century-long service life expectations.
- Above Ground:Accessible installations enable electric and pneumatic actuation with minimal weatherproofing. Danish water networks prioritize above-grade valve vaults for smart sensor integration and rapid maintenance response.
- Onshore:Coastal and flood-prone sites require enhanced sealing against tidal intrusion and storm surge. Florida's water management districts specify marine-grade enclosures for above-ground pumping stations.
- Offshore:Platform and subsea installations demand hyper-duplex stainless steel and hydraulic actuation rated for extreme pressure and salinity. Norway's Equinor operates subsea valve trees for produced water reinjection in North Sea fields.
Specification volume clusters in underground configurations; above-ground smart retrofits are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of ductile iron valve castings consumed worldwide, while the United States and Germany drive premium specification demand through regulatory upgrade cycles. Production capacity clusters in Asia-Pacific foundries, whereas procurement value concentrates in Western municipal infrastructure renewal programs.
United States
EPA Lead and Copper Rule revisions are forcing wholesale distribution network audits across aging municipal systems. The agency mandates lead-free construction standards that accelerate valve replacement cycles in legacy cast-iron mains. Chicago and Detroit water utilities are deploying pressure management infrastructure to achieve federal compliance deadlines.
China
Urban water network upgrades in Shanghai and Guangzhou absorb substantial procurement volumes for resilient-seated butterfly valves. MEE discharge limits are accelerating automation retrofits in wastewater treatment facilities nationwide. The Yangtze River Delta anchors foundry capacity serving both domestic demand and Western valve assembler supply chains.
Germany
Ruhrverband and other regional water associations specify OS&Y rising stem gate valves for buried service in legacy infrastructure replacement. REACH Annex XVII lead restrictions are mandating gunmetal replacement with silicon bronze and engineered polymers before the 2026 deadline. Foundries in Bavaria and North Rhine-Westphalia are retooling casting lines to meet compliance timelines.
Saudi Arabia
SWCC desalination plants specify super-duplex stainless steel ball valve trim for seawater reverse osmosis skids. The kingdom's civil defense authority mandates tamper-proof supervisory switches on fire protection post-indicator valves. Coastal desalination clusters along the Red Sea and Arabian Gulf are driving hybrid polymer-metal valve adoption for saline intake systems.
Australia
Melbourne Water and Sydney Water specify NSF/ANSI 61-certified materials for all potable contact surfaces in treatment plant expansions. The Water Efficiency Labelling and Standards scheme is creating specification pull for low-flow precision valves in residential metering applications. Queensland and New South Wales utilities are prioritizing smart network integration in above-ground valve vault retrofits.
Global Valves in Water and Wastewater Market Competitive Landscape
Top-tier vendors anchor premium specification markets, while mid-scale fabricators compete on municipal tender participation. The competitive structure tiers around foundry integration depth, actuation technology capability, and service network density. Three archetypes dominate: vertically integrated casting-to-assembly specialists, digital valve monitoring platform providers, and regional fabrication houses serving utility maintenance channels. Competitive moves concentrate on predictive maintenance service contracting and material certification pre-positioning ahead of regulatory deadlines.
Among Germany-based industrial valve specialists, KSB SE & Co. KGaA and VAG GmbH exemplify the foundry-integrated archetype with deep exposure to wastewater treatment configurations. Flowserve Corporation and Emerson Electric Co. represent the digital convergence tier, with the latter anchoring integrated valve monitoring platforms that extend service intervals. AVK Holding A/S occupies a position within the municipal-specialist cluster, reflecting Danish water utility heritage and resilient-seated butterfly valve standardization.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| Watts Water Technologies, Inc. |
| Pentair plc |
| AVK Holding A/S |
| Mueller Water Products, Inc. |
| KSB SE & Co. KGaA |
| VAG GmbH |
| Crane Company |
| Others |
Pricing and Supply Chain Analysis
EPA Lead and Copper Rule revisions in the United States are forcing municipal utilities toward lead-free brass and silicon bronze specifications, compelling foundries to absorb retooling costs and pass through material premiums to procurement committees. This specification-driven demand compression is reshaping supplier pricing power across Western valve markets.
Pricing Analysis
Short-lead-time premiums dominate municipal tender responses, with utilities paying 15-25% markups for WRAS or NSF/ANSI 61 pre-certified inventory against standard 12-18 month certification cycles. Three-tier pricing structure across premium certified, standard industrial, and economy cast-iron levels segments buyers by compliance urgency. Cost compression in economy ductile iron tiers is intensifying because Chinese foundry overcapacity floods spot markets. Agricultural irrigation districts exhibit highest price sensitivity; desalination operators in Saudi Arabia and Israel show lowest.
Supply Chain Analysis
Refurbishment flows from Dutch and Danish water utilities are extending valve service lifecycles and cannibalizing new unit demand in mature European networks. Manufacturing gravity centers on China, India, and Germany, with Yangtze River Delta foundries supplying 60% of global ductile iron castings. Nickel and copper price volatility rests on London Metal Exchange swings that compress stainless steel and bronze alloy margins. Single-source vulnerability concentrates in Chinese ductile iron capacity. Distribution runs through regional valve assembler networks that integrate casting, machining, and actuation packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
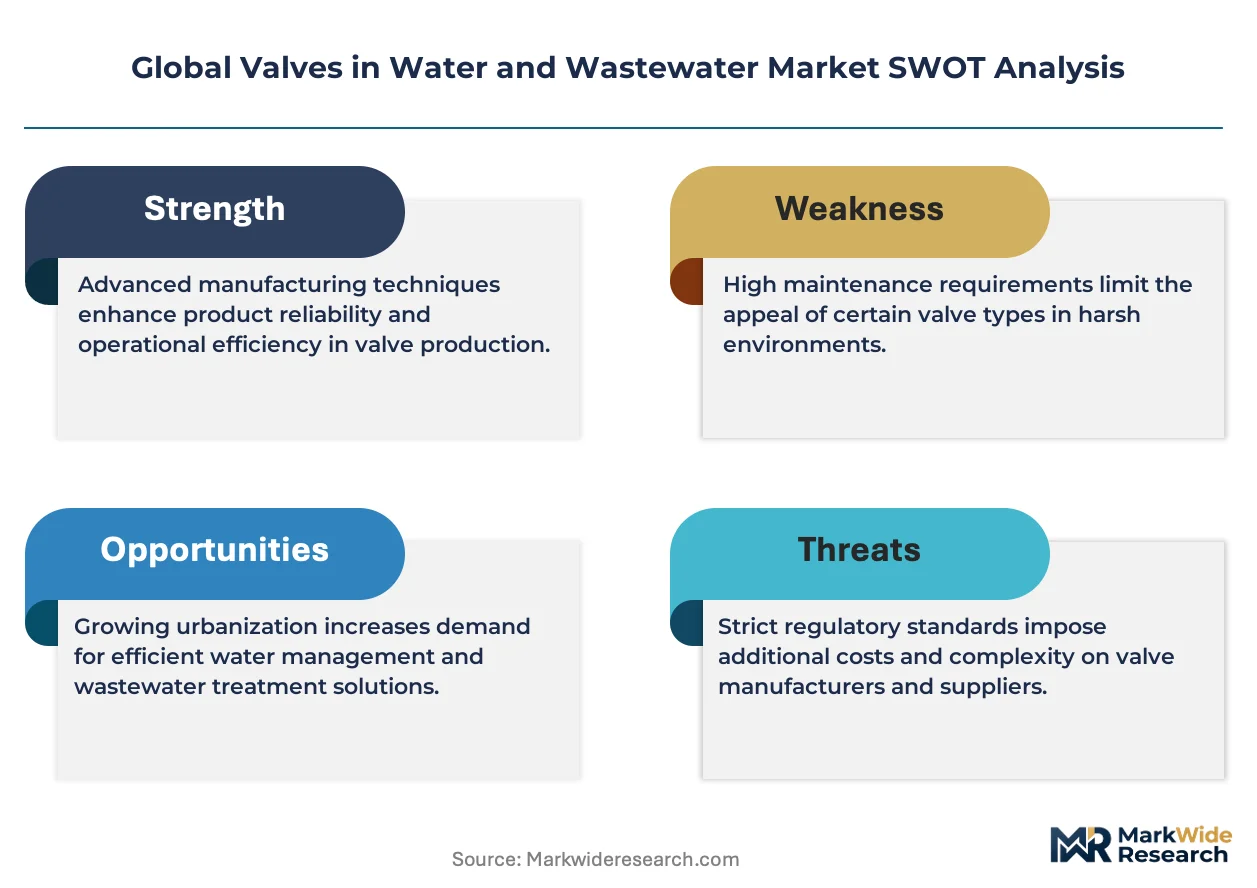
This market reads as a cost-of-compliance story where REACH Annex XVII lead restrictions and EPA lead-free mandates erect certification barriers that favor incumbents with pre-positioned material roadmaps and validated foundry relationships.
For Market Incumbents: Deploy predictive maintenance service contracting to lock municipal utilities into availability-based agreements that displace capital purchase models. Fortify certification pre-positioning ahead of 2026 REACH deadlines to capture specification share from retooling-lagged competitors. Threat substitution from thermoplastic valve specialists in sub-16 bar applications demands polymer competency acquisition or partnership. For New Entrants and Emerging Players: Capture Indonesian urban water utility automation retrofits in Jakarta and Surabaya distribution zones where manual gate valve replacement cycles concentrate procurement volume. White-space sits in hybrid polymer-metal valve architectures for coastal desalination saline intake systems. Go-to-market through Danish and Dutch digital twin platform partnerships enables real-time hydraulic modeling integration. For Investors and Strategic Acquirers: The window for entry favors foundry-integrated mid-cap specialists with captive ductile iron capacity and wastewater treatment plant configuration expertise. Long-term viability hinges on automation density in municipal retrofit cycles and material science differentiation in corrosion-resistant alloys. Signal to watch: municipal utility consolidation events that compress supplier counts and favor scale players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ductile Iron Casting | Captures margin from Chinese foundry concentration and secures supply for EPA-compliant production. |
| Certification Pre-Positioning Investment | Locks specification share ahead of 2026 REACH lead-content deadlines in German and Italian markets. |
| Predictive Maintenance Platform Launch | Converts hardware transactions into recurring revenue with Thames Water and Singapore PUB contracts. |
| Hybrid Polymer-Metal Valve Development | Addresses Saudi SWCC desalination demand for 40% weight reduction in saline intake systems. |
| Geographic Expansion into Indonesian Utilities | Targets Jakarta and Surabaya automation retrofit cycles replacing manual gate valve infrastructure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with municipal procurement directors, water utility maintenance engineers, valve foundry operations managers, and OEM aftermarket service heads combined with secondary validation from EPA enforcement databases, EU ECHA REACH registrations, and Chinese MEE discharge compliance records. Bottom-up unit shipment estimates triangulated against top-down infrastructure spending projections.
Granularity-level modeling operated at product type, application, end user, and installation type dimensions, with additional regional regulatory cluster segmentation capturing divergence between EPA, REACH, and MEE compliance timelines. CAGRs derived from regression against historical infrastructure spending correlation and forward projection of regulatory mandate acceleration. Forecast inputs incorporated foundry capacity utilization rates and nickel-copper price elasticity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to raw material price volatility, foundry capacity relocation, and regulatory timeline slippage. Assumptions reflect documented municipal spending commitments and disclosed compliance deadlines. Material deviation in Chinese environmental enforcement intensity or Western trade policy toward ductile iron imports warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Deionized Water Systems Market
Water & Sludge Treatment
Alkalinity Control Chemicals Market
Water & Sludge Treatment
Anionic Flocculants Market
Water & Sludge Treatment
Asia-Pacific Water Free/ Waterless Urinals Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Sedimentation and Centrifugation Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
Global Water Treatment Technology Market
Water & Sludge Treatment
Low-Dosage Hydrate Inhibitors (Ldhis) Market
Water & Sludge Treatment
Electrodeionization (EDI) Technology Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market