
 India Water Treatment Chemicals Market | 2026-2036
India Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
India Water Treatment Chemicals Market Outlook
Market Context
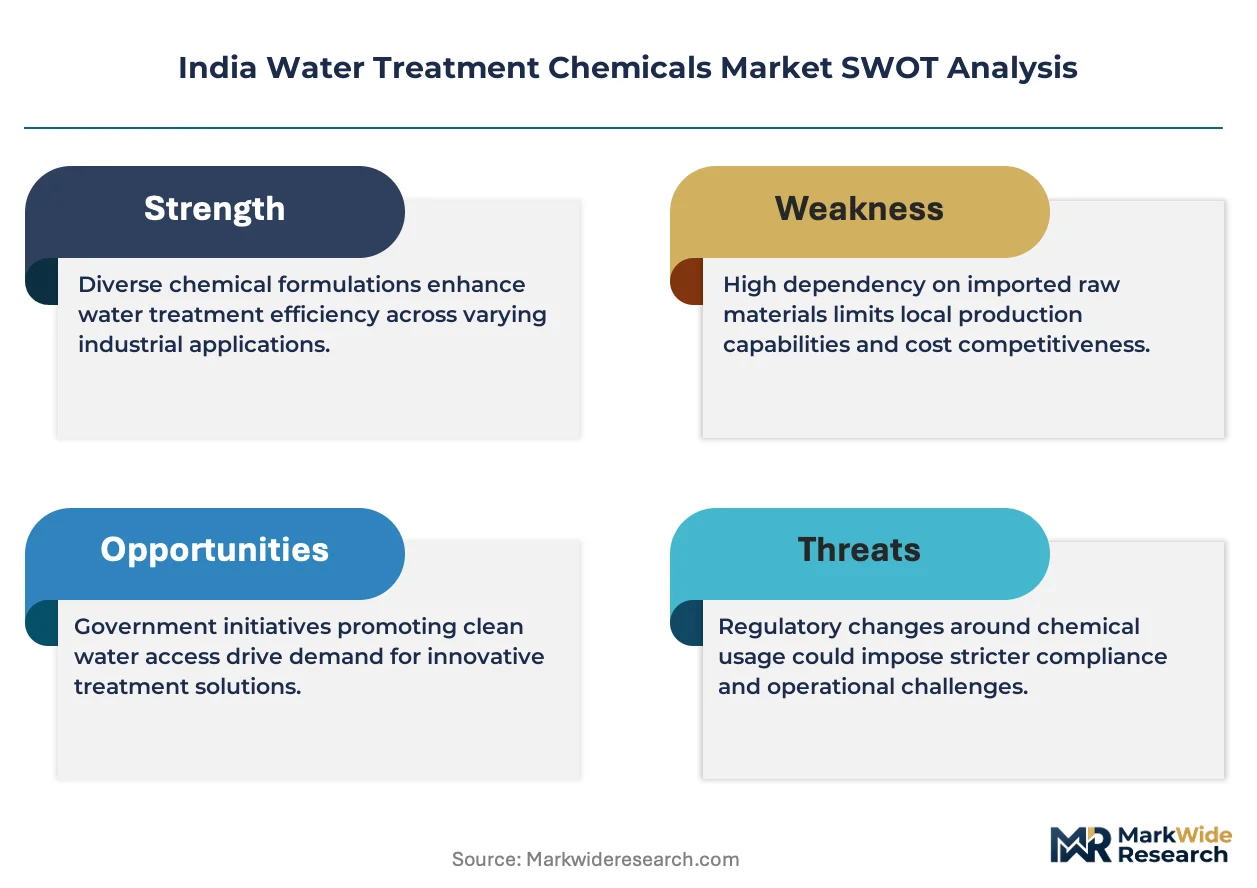
BIS IS 10500 certification for drinking water quality is collapsing the supplier base, forcing smaller traders to exit or consolidate. Ecolab Inc. (Nalco Water) leverages its integrated water management platform to dominate municipal contracts in western India. Thermax Limited anchors its position through captive manufacturing of boiler water chemicals for power utilities. Ion Exchange (India) Ltd. differentiates via membrane-chemical hybrid systems for zero-liquid-discharge installations.
Technical Definition and Segment Structure
India water treatment chemicals comprise formulated additives—coagulants (aluminum sulfate, polyaluminum chloride), flocculants (polyacrylamide polymers), disinfectants (chlorine, chlorine dioxide), and pH adjusters (caustic soda, sulfuric acid)—designed to remove suspended solids, pathogens, and dissolved contaminants from raw water and wastewater streams, typically dosed at 5–50 ppm depending on turbidity and organic load. Coagulants capture the largest volume share due to universal deployment across municipal clarification plants, while flocculants command margin premiums in oil and gas produced-water treatment where polymer molecular weight dictates separation efficiency. Industrial wastewater treatment applications are outpacing municipal growth as semiconductor and textile clusters in Tamil Nadu and Telangana face zero-discharge mandates.
Regulatory Framework and Outlook
BIS, the Central Pollution Control Board (CPCB), and state-level pollution control authorities enforce tightening effluent standards under the Water (Prevention and Control of Pollution) Act, compelling industrial users to upgrade chemical dosing infrastructure and shift from commodity chlorine to advanced oxidants. The Ministry of Jal Shakti's Jal Jeevan Mission drives rural water scheme expansion, creating bulk procurement opportunities for tablet and granular disinfectant forms. Stakeholders must track state-level tender aggregation and BIS certification timelines to anticipate procurement consolidation.
Market Dynamics
BIS IS 10500 certification mandates are collapsing the supplier base across Maharashtra and Gujarat, forcing consolidation among municipal chemical vendors while thermal power stations along the Narmada belt scale coagulant procurement to meet discharge norms.
Growth Catalysts
- Jal Jeevan Mission expansion:The Ministry of Jal Shakti's rural water scheme drives bulk tablet and granular disinfectant procurement across village panchayat networks.
- Zero-liquid-discharge mandates:Semiconductor and textile clusters in Tamil Nadu and Telangana face compulsory effluent recycling, accelerating membrane-chemical hybrid system deployment.
- Thermal power sector offtake:Coal-fired stations require enhanced boiler water treatment chemicals to manage cycle chemistry under CEA efficiency directives.
Market Restraints
- Caustic soda price volatility:pH adjuster costs fluctuate with chlorine-alkali plant operating rates, compressing formulation margins for regional blenders.
- Alumina supply concentration:Polyaluminum chloride production depends on captive alumina feedstock from eastern smelters, creating geographic vulnerability.
- Legacy chlorine substitution friction:Municipal plants face capital barriers upgrading from commodity chlorine to chlorine dioxide under BIS residual limits.
Strategic Opportunities
- Membrane-chemical convergence:Zero-liquid-discharge installations in Gujarat's petrochemical corridor reward integrated system suppliers with decade-long service contracts.
- Rural tablet distribution:Jal Jeevan Mission procurement aggregation creates white space for packaged disinfectant formats bypassing traditional bulk chemical channels.
- PLI scheme alignment:Domestic manufacturing incentives for specialty chemicals enable import substitution of high-molecular-weight polyacrylamide flocculants.
Industry Challenges
- BIS certification timelines:New chemical formulations face 18-24 month approval windows, delaying product launches and freezing R&D pipelines.
- Legacy dosing infrastructure:Municipal plants require complete automation retrofitting to handle precision polymer injection, straining capex budgets.
- Membrane-chemical integration complexity:Hybrid system deployments demand cross-functional expertise spanning polymer chemistry and membrane fouling management, tightening talent availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Water Treatment Chemicals Market |
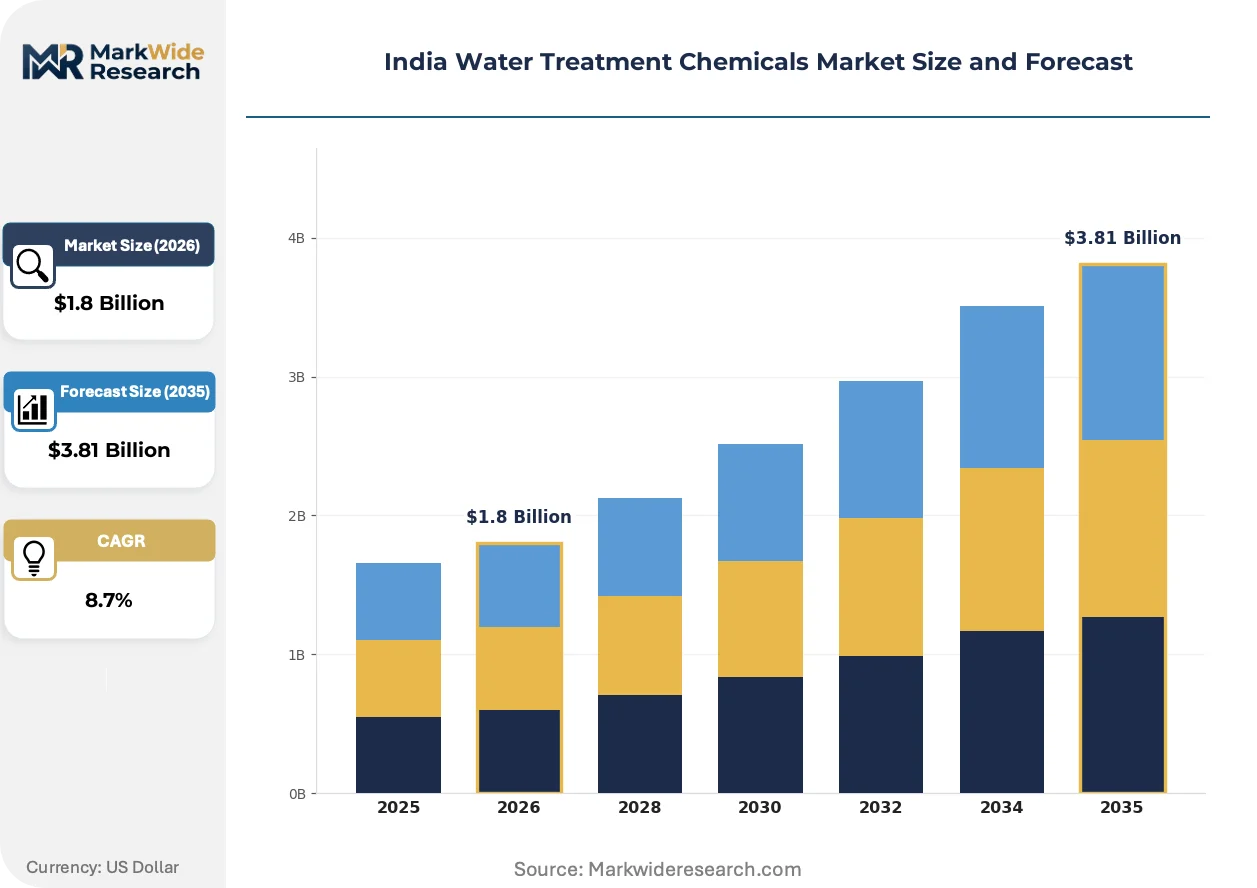
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Disinfectants, pH Adjusters, Flocculants Application: Municipal Water Treatment, Industrial Wastewater Treatment, Power Generation, Oil & Gas Form: Liquid, Powder, Granular, Tablets Customer Type: Municipalities, Industrial Users, Commercial Enterprises, Residential Users |
| Companies Covered | Ecolab Inc. (Nalco Water), Thermax Limited, Ion Exchange (India) Ltd., Chembond Chemicals Limited, SNF, Kemira, Atul Ltd., Chemtex Speciality Limited, Vasu Chemicals LLP, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Water Treatment Chemicals Market Strategic Shifts
Advanced oxidant chemistry and digital dosing platforms are restructuring competitive advantage across municipal and industrial water treatment, compressing traditional commodity supply relationships.
Peracetic acid and ozone-based disinfection systems are displacing legacy chlorine dosing in food and beverage processing plants across Karnataka and Punjab. Breweries and dairy cooperatives adopt these technologies to eliminate trihalomethane formation risks under FSSAI water quality protocols. The shift is compressing regional chlorine trader margins while rewarding specialty chemical distributors with technical service capabilities.
CPCB's 2023 effluent standard amendments for heavy metals and emerging contaminants now mandate tertiary treatment stages for electroplating clusters in Delhi-NCR and Tamil Nadu. Metal finishing facilities must deploy chelating polymers and advanced oxidation processes to meet discharge limits. The regulatory pressure is accelerating chemical supplier partnerships with engineering procurement contractors for integrated turnkey solutions.
State-level tender aggregation through Maharashtra Jal Bhavan and Gujarat Water Supply and Sewerage Board is consolidating municipal procurement into multi-year framework agreements. Single-source chemical supply contracts now span 3-5 year periods with embedded technical service obligations. The concentration is visible across western India municipal corporations, squeezing spot-market traders and favoring integrated water management platforms with captive logistics networks.
India Water Treatment Chemicals Market Segmentation
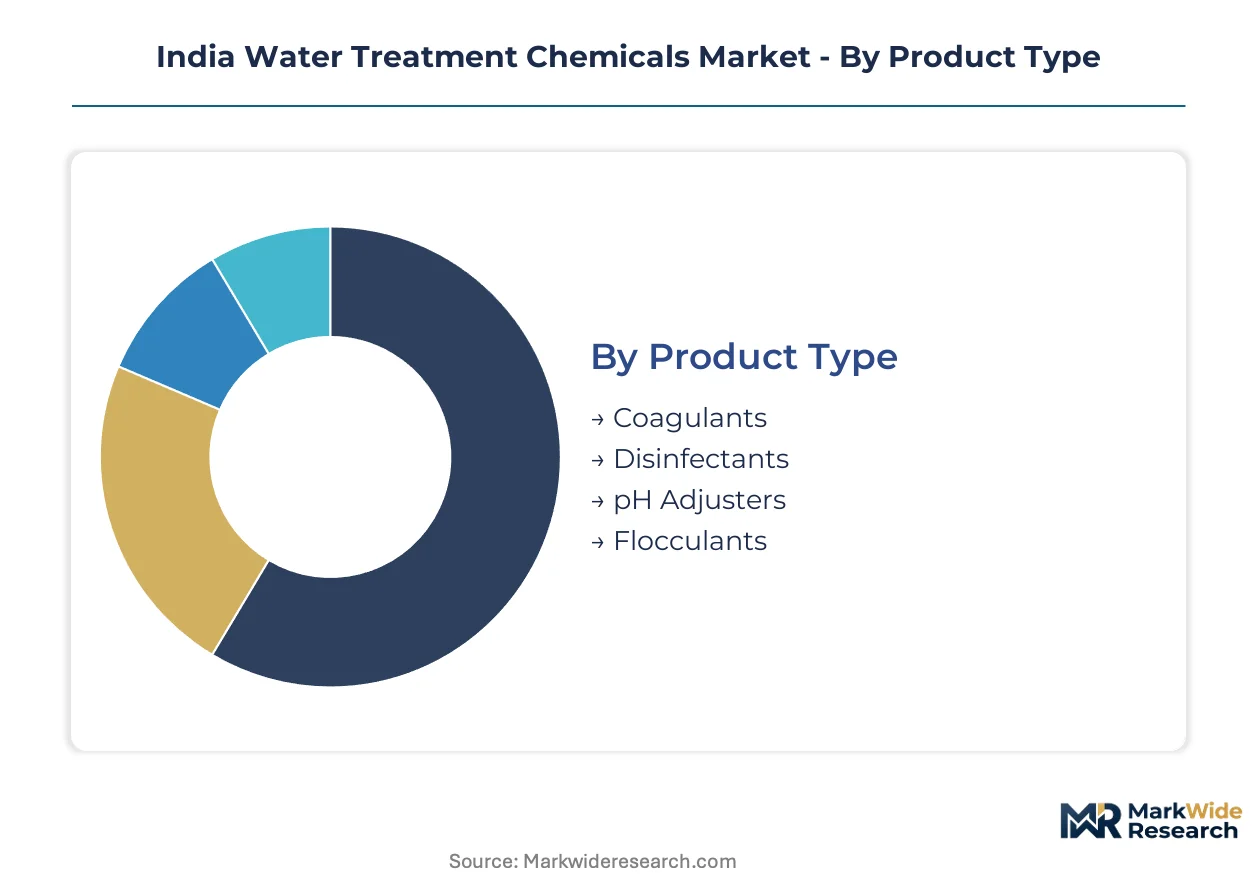
Segmentation in India's water treatment chemicals market reveals divergent margin pools between commodity coagulants and specialty formulations. Understanding these structural differences enables targeted positioning across municipal tenders and industrial specifications.
Product Type:
Margin concentration sits with polymer-based formulations where molecular weight customization commands pricing premiums over commodity inorganics.
- Coagulants:Aluminum sulfate and polyaluminum chloride formulations dominate municipal clarification basins across Maharashtra and Gujarat. Thermal power stations along the Narmada belt are scaling procurement volumes to meet tightened CPCB discharge norms for suspended solids.
- Flocculants:High-molecular-weight polyacrylamide polymers enable precision separation in oil and gas produced-water treatment. Demand concentrates in Gujarat's petrochemical corridor where zero-liquid-discharge mandates require advanced dewatering chemistry.
- Disinfectants:Chlorine tablets and chlorine dioxide generators serve Jal Jeevan Mission rural distribution networks.
- pH Adjusters:Caustic soda and sulfuric acid formulations balance alkalinity in boiler water cycles.
Coagulants hold installed capacity. Flocculants is rotating up the share rankings.
Application:
Volume leadership belongs to municipal procurement, though industrial wastewater commands superior per-tonne economics.
- Industrial Wastewater Treatment:Semiconductor and textile clusters in Tamil Nadu and Telangana face compulsory effluent recycling under state pollution control board mandates. Membrane-chemical hybrid systems are displacing conventional biological treatment, creating sustained demand for antiscalants and cleaning chemicals.
- Municipal Water Treatment:BIS IS 10500 certification requirements are collapsing the supplier base across urban local bodies. Maharashtra Jal Bhavan and Gujarat Water Supply and Sewerage Board tender aggregation is compressing spot-market participation.
- Power Generation:CEA efficiency directives mandate enhanced cycle chemistry management at coal-fired stations.
- Oil & Gas:Produced-water treatment specifications in western offshore blocks require polymer-compatible formulations.
Municipal Water Treatment holds installed capacity. Industrial Wastewater Treatment is climbing the fastest.
Form:
Logistics economics favor liquid concentrates in industrial corridors, while solid formats penetrate rural distribution constraints.
- Liquid:Bulk tanker deliveries serve continuous-dosing municipal plants and captive power station chemical houses. Western India industrial belts maintain dedicated storage infrastructure for polyaluminum chloride and caustic soda solutions.
- Tablets:Sodium dichloroisocyanurate and calcium hypochlorite tablets bypass bulk chemical channels for village panchayat procurement under Jal Jeevan Mission aggregation.
- Powder:Polyacrylamide dry polymers enable on-site dissolution for remote industrial facilities.
- Granular:Activated carbon and ion exchange resins serve point-of-use filtration installations.
Liquid holds installed capacity. Tablets is rotating up the share rankings.
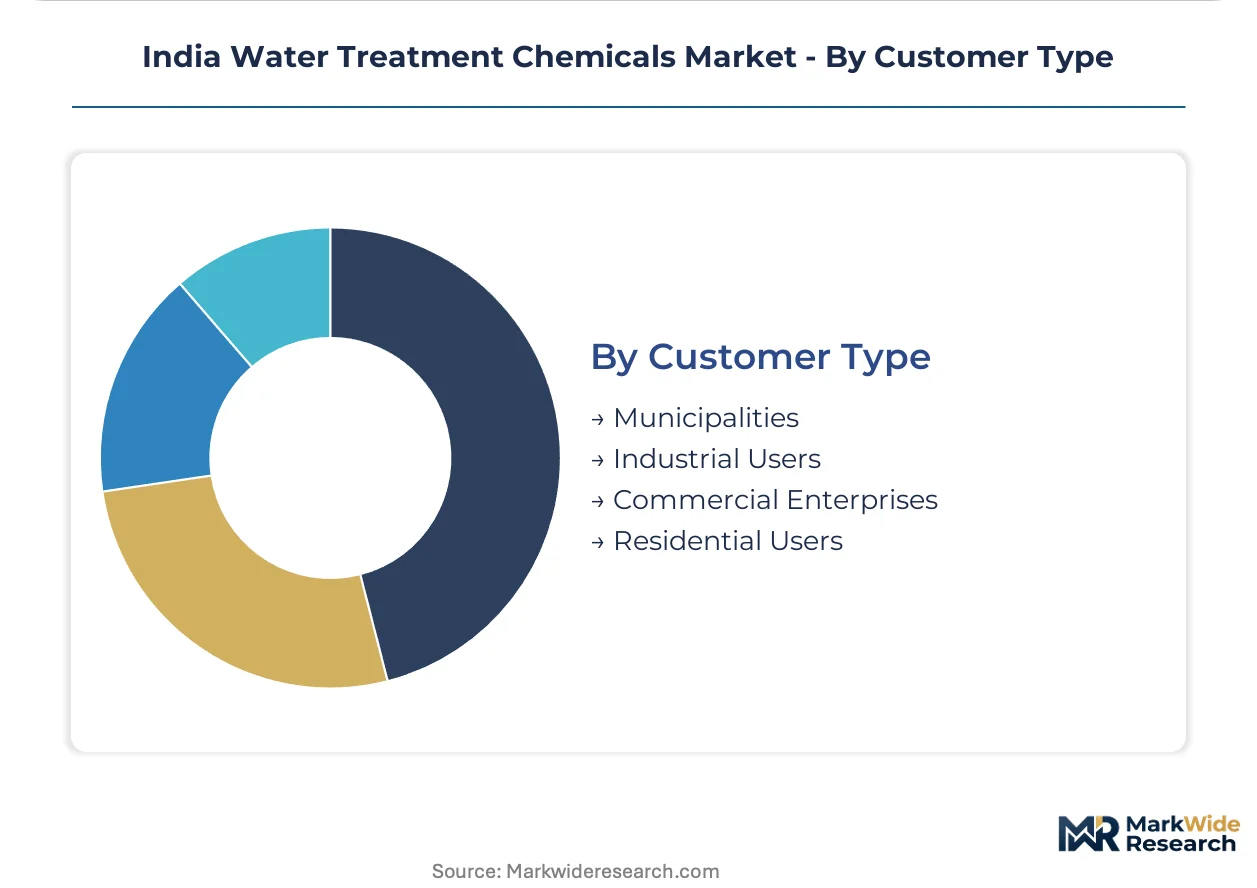
Customer Type:
Purchasing sophistication varies sharply between framework-contract municipalities and specification-driven industrial buyers.
- Municipalities:State-level tender aggregation through Jal Bhavan structures is consolidating procurement into multi-year technical service agreements. BIS certification requirements are forcing vendor consolidation among urban local bodies.
- Industrial Users:Zero-liquid-discharge mandates in Tamil Nadu and Telangana textile clusters are accelerating membrane-chemical hybrid system deployment with decade-long service contracts.
- Commercial Enterprises:Food and beverage processors adopt peracetic acid systems under FSSAI water quality protocols.
- Residential Users:Point-of-use filtration drives granular activated carbon and disinfectant tablet consumption.
Municipalities hold installed capacity. Industrial Users is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jal Jeevan Mission's rural water infrastructure rollout is redistributing procurement volumes toward state-level tender aggregation, while zero-liquid-discharge mandates in industrial corridors concentrate chemical demand in specific manufacturing belts.
Maharashtra
Municipal corporations in Mumbai, Pune, and Nagpur are consolidating chemical procurement through Maharashtra Jal Bhavan framework agreements. BIS IS 10500 certification requirements are collapsing the supplier base among urban local bodies. Thermal power clusters in Chandrapur and Koradi anchor coagulant offtake for boiler water treatment cycles.
Gujarat
The Narmada belt thermal power stations are scaling polyaluminum chloride procurement to meet tightened CPCB discharge norms for suspended solids. Zero-liquid-discharge mandates in the petrochemical corridor at Vadodara and Dahej are accelerating membrane-chemical hybrid system deployment. Gujarat Water Supply and Sewerage Board tender aggregation is compressing spot-market participation.
Tamil Nadu
Semiconductor and textile clusters around Chennai and Tiruppur face compulsory effluent recycling under state pollution control board mandates. Membrane-chemical hybrid systems are displacing conventional biological treatment, creating sustained demand for antiscalants and cleaning chemicals. Electroplating facilities in Ambattur must deploy chelating polymers to meet CPCB heavy metal discharge limits.
Telangana
Pharmaceutical and bulk drug manufacturing zones in Hyderabad and Medak are upgrading chemical dosing infrastructure under revised effluent standards. Zero-discharge mandates are accelerating demand for high-molecular-weight polyacrylamide flocculants in wastewater treatment. The state's industrial corridor development is concentrating procurement among integrated water management platforms.
Karnataka
Food and beverage processors in Bengaluru and Mysuru are adopting peracetic acid and ozone-based disinfection systems under FSSAI water quality protocols. Breweries and dairy cooperatives are eliminating trihalomethane formation risks through advanced oxidant chemistry. The shift is compressing regional chlorine trader margins while rewarding specialty chemical distributors.
India Water Treatment Chemicals Market Competitive Environment
Player mix skews toward integrated water management platforms with captive manufacturing capabilities and regional specialty chemical blenders serving fragmented municipal procurement. Market structure exhibits tiered consolidation, with three to four national platforms capturing multi-year framework agreements while dozens of regional traders compete for spot municipal tenders. Strategic archetypes include integrated chemical-service hybrids, captive power sector suppliers, and membrane-chemical system integrators. Dominant competitive moves center on backward integration into alumina feedstock and state-level tender aggregation partnerships.
Within the integrated platform tier, Ecolab Inc. (Nalco Water) and Thermax Limited exemplify divergent approaches to municipal and industrial verticals. Ecolab leverages its water management platform to anchor western India municipal contracts, while Thermax occupies a position in captive boiler water chemical manufacturing for power utilities. Among specialty chemical specialists, Ion Exchange (India) Ltd. represents the membrane-chemical convergence archetype, with Chembond Chemicals Limited and Chemtex Speciality Limited sitting within the regional formulation blender tier. SNF and Kemira anchor the high-molecular-weight polymer segment where import substitution incentives are reshaping competitive positioning.
| Leading Market Players |
|---|
| Ecolab Inc. (Nalco Water) |
| Thermax Limited |
| Ion Exchange (India) Ltd. |
| Chembond Chemicals Limited |
| SNF |
| Kemira |
| Atul Ltd. |
| Chemtex Speciality Limited |
| Vasu Chemicals LLP |
| Others |
Value Chain & Pricing Dynamics
Long-term framework agreements with embedded technical service obligations lock in supply access for municipal buyers while flattening price visibility across Maharashtra and Gujarat procurement cycles. These multi-year contracts compress spot-market participation and tether formulation margins to BIS certification timelines rather than raw material spot indices.
Pricing Analysis
Certification level (BIS IS 10500-grade) creates the primary spread between commodity traders and integrated platform suppliers. Three-tier pricing structure across premium polymer formulations, standard inorganic coagulants, and economy-grade disinfectants reflects molecular weight customization and after-sales bundling intensity. Pricing pressure stems from caustic soda feedstock volatility in the chlorine-alkali chain, squeezing regional blender margins. Municipal corporations show highest price sensitivity due to tender aggregation, while zero-liquid-discharge industrial users accept premium positioning for membrane-chemical hybrid systems.
Supply Chain Analysis
Strategic stockpiling of polyaluminum chloride feedstock dominates inventory strategy among western India municipal suppliers facing alumina supply concentration. Manufacturing draws from captive alumina facilities in eastern India, high-molecular-weight polyacrylamide imports from France and Finland, and caustic soda from domestic chlor-alkali plants. Single-source vulnerability sits with alumina feedstock dependency on eastern smelters. Distribution runs through dedicated tanker fleets for liquid concentrates and rural distribution networks for tablet formats under Jal Jeevan Mission aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through state-level tender aggregation, forcing supplier consolidation as Maharashtra Jal Bhavan and Gujarat Water Supply and Sewerage Board collapse vendor bases into framework-contract oligopolies.
For Market Incumbents: Compound technical service intensity within municipal contracts to deepen switching costs against emerging membrane-chemical hybrid specialists. Backward integration into alumina feedstock secures polyaluminum chloride margin control against eastern smelter supply volatility. Prioritize automation retrofitting partnerships with urban local bodies to lock in precision dosing infrastructure upgrades. For New Entrants and Emerging Players: Rural tablet distribution under-serve by incumbent bulk chemical channels offers white-space penetration under Jal Jeevan Mission procurement aggregation. Target semiconductor and textile clusters in Tamil Nadu and Telangana facing compulsory zero-liquid-discharge mandates with packaged membrane-chemical solutions. Deploy direct village panchayat go-to-market models bypassing traditional municipal tender channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated water management platforms with captive manufacturing and decade-long service contracts. Long-term viability favors membrane-chemical convergence specialists over commodity formulation blenders. Watch BIS certification timeline compression as inflection signal for procurement consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Feedstock | Captive polyaluminum chloride supply secures margin control against eastern smelter concentration. |
| Membrane-Chemical Hybrid System Deployment | Zero-liquid-discharge mandates in Gujarat's petrochemical corridor reward decade-long service contracts. |
| Rural Tablet Distribution Network Buildout | Jal Jeevan Mission aggregation creates bypass channel outside municipal tender consolidation. |
| Precision Dosing Automation Partnerships | Municipal retrofit requirements lock in incumbent technical service relationships. |
| High-Molecular-Weight Polymer Localization | PLI scheme alignment enables import substitution of specialty flocculant grades. |
Study Parameters
Cross-validation between plant manager interviews at thermal power stations and customs trade data anchors the qualitative findings on coagulant procurement patterns. Primary fieldwork with municipal procurement officers, chemical distribution channel partners, and CPCB regional directors combined with secondary validation through BIS certification databases, state pollution control board effluent compliance records, and Ministry of Jal Shakti scheme disclosures. Bottom-up tender aggregation analysis and top-down chemical consumption modeling triangulate volume estimates.
Sensitivity analysis on alumina feedstock pricing and BIS certification approval timelines tests forecast robustness across the projection horizon. Segmentation dimensions include product type tier, end-use industry vertical, customer procurement sophistication, and regional regulatory cluster. CAGRs derive from installed capacity utilization trends and mandate-driven replacement cycles. Forecast inputs incorporate Jal Jeevan Mission rural network rollout pace and zero-liquid-discharge enforcement intensity.
Forecasts assume regulatory continuity in BIS IS 10500 certification regimes and CPCB effluent standard enforcement; material policy shifts would require re-modeling. Specific risks include caustic soda supply disruption from chlorine-alkali plant operating rate volatility and municipal capex freeze from fiscal stress. Revision becomes warranted when BIS certification timeline compression crosses thresholds that freeze new formulation pipelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Sludge Heater Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Global Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Global Wood Activated Carbon Market
Water & Sludge Treatment
North America Industrial Water Treatment Market
Water & Sludge Treatment
Water and Wastewater Treatment Technologies Market
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Process Water Treatment Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
Global Water Treatment Technology Market
Water & Sludge Treatment
US Liquid Waste Management Market