
 Wastewater Treatment Chemicals Market | 2026-2036
Wastewater Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Wastewater Treatment Chemicals Market Analysis
The gap between premium formulated chemicals and commodity bulk treatments is broadening as utilities demand performance guarantees and industrial users chase lowest unit cost. Ecolab leverages its integrated service model to capture long-term municipal contracts with bundled chemical-plus-equipment offerings. BASF SE anchors its position through backward integration into acrylic acid monomers that feed polyacrylamide production. Kemira competes on geographic density in Northern Europe where it controls local blending and logistics networks.
Wastewater treatment chemicals encompass coagulants, flocculants, pH adjusters, and disinfectants dosed at 0.5–50 mg per liter depending on influent turbidity and target effluent quality, with polyacrylamide flocculants achieving 90–99% suspended solids removal in clarifier systems. Their primary purpose is to neutralize charged particles, aggregate fine solids, and eliminate pathogens before discharge or reuse. Coagulants and flocculants together occupy the largest value pool due to universal demand across municipal and industrial facilities, while disinfectants command premium pricing in reuse applications where microbial standards are strictest. Oil & gas applications represent the fastest-growing segment as produced water volumes rise and discharge limits tighten.
EU Urban Wastewater Treatment Directive revisions, EPA National Pollutant Discharge Elimination System permits, and REACH chemical registration requirements collectively dictate product approval pathways, environmental fate testing, and maximum concentration limits in effluent streams. These frameworks force reformulation away from acrylamide monomer residuals and toward bio-based coagulant alternatives. Stakeholders must monitor emerging per- and polyfluoroalkyl substance restrictions that could eliminate certain fluorinated flocculant chemistries from approved use lists.
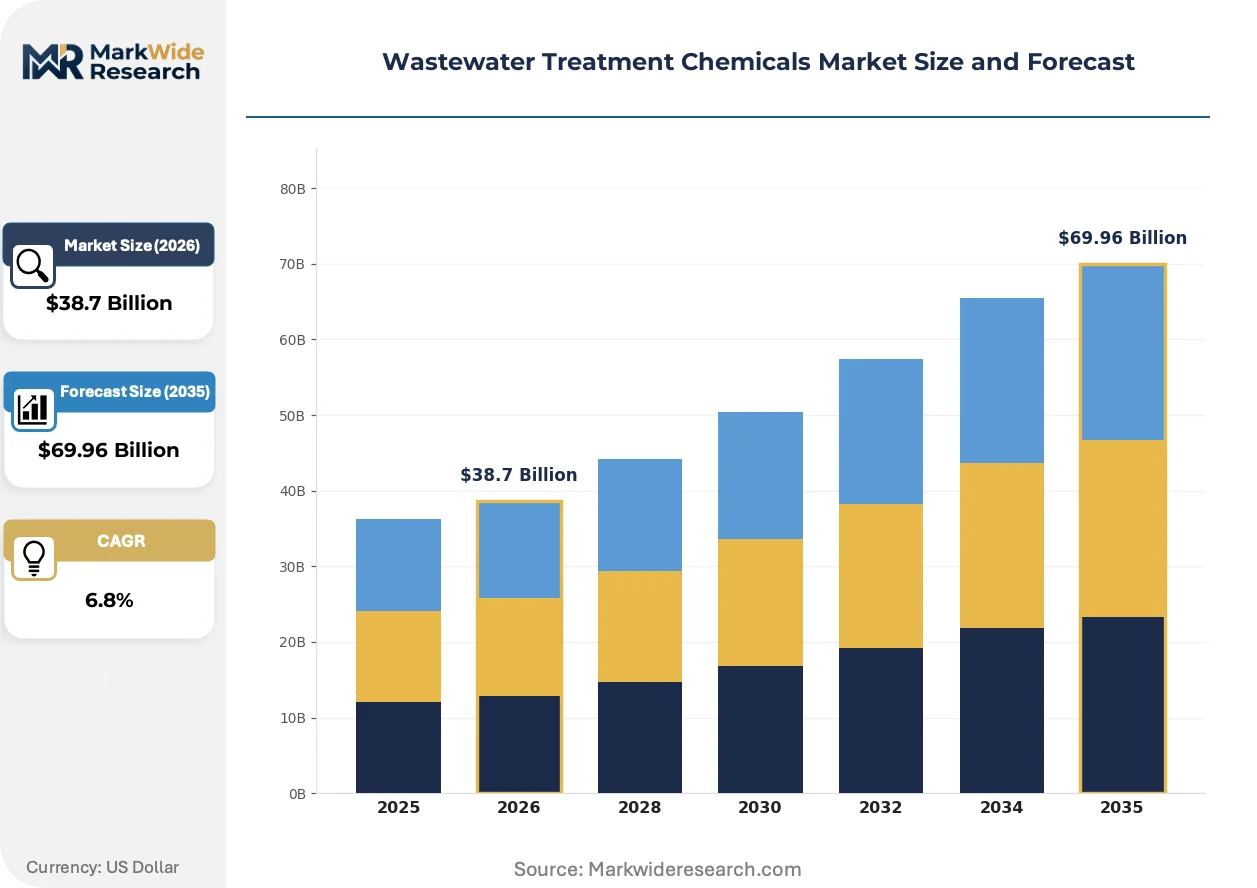
Market Dynamics
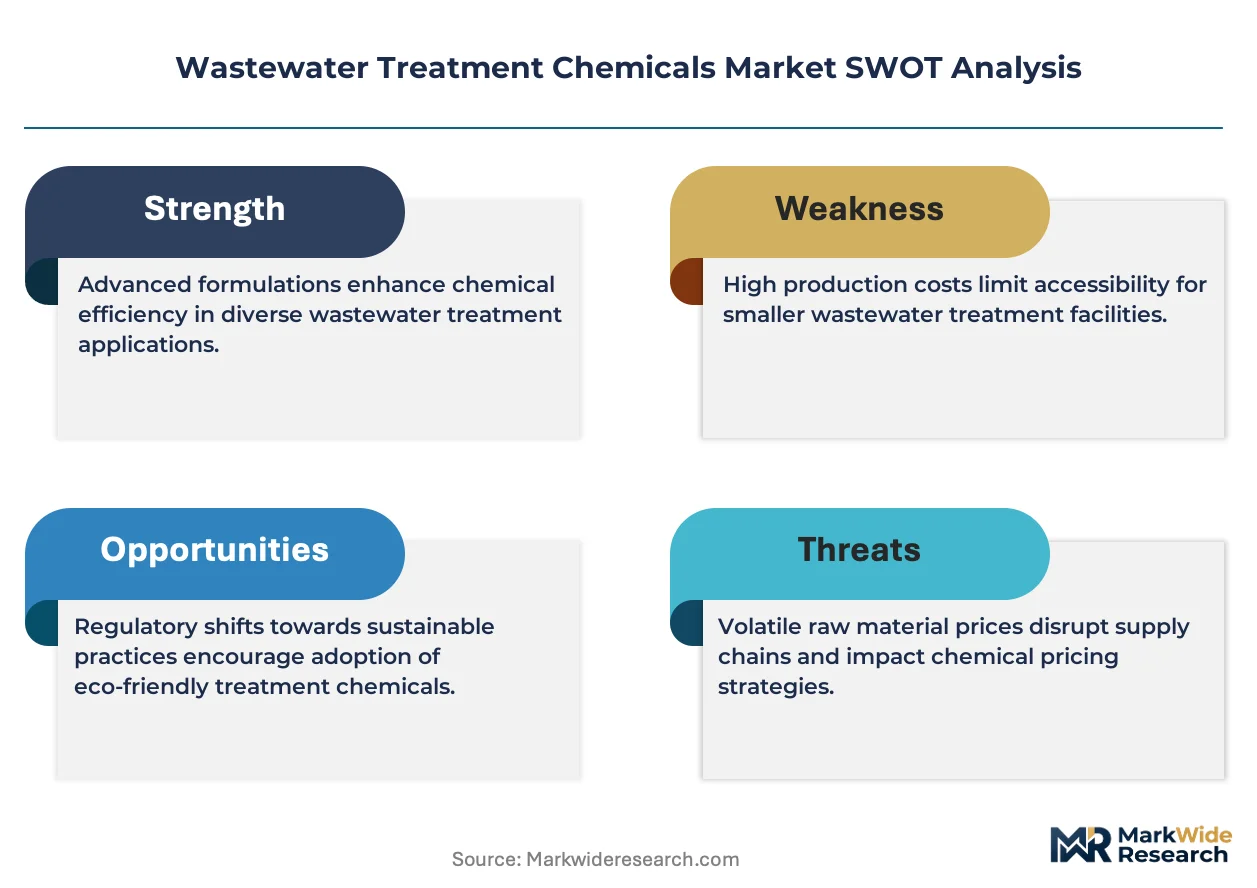
The transition from alum-based coagulants to polyacrylamide flocculants is compressing product margins while elevating performance requirements across municipal procurement. This chemistry shift, driven by EU phosphate removal mandates, is forcing chemical suppliers to restructure formulation capabilities and service models simultaneously.
Growth Catalysts
- EU Urban Wastewater Treatment Directive amendments:Tightened effluent standards in Germany, France, and the Netherlands are mandating advanced phosphorus removal, expanding demand for high-performance flocculant systems in municipal facilities.
- Produced water volumes in oil & gas:Rising unconventional extraction activity is generating larger wastewater streams with stricter discharge limits, accelerating chemical consumption in hydraulic fracturing operations.
- Acrylic acid monomer supply:Backward integration into polyacrylamide feedstocks is securing raw material access for European formulators amid volatile petrochemical input costs.
Market Restraints
- Acrylamide monomer residual limits:REACH registration requirements and EPA toxicity thresholds are restricting traditional polyacrylamide formulations, forcing costly reformulation cycles.
- Concentrated acrylic acid supply:European petrochemical complexes control critical monomer output, creating single-source dependency risks for independent blenders.
- Fluorinated flocculant phaseout:Emerging per- and polyfluoroalkyl substance restrictions threaten elimination of certain high-performance chemistries from approved use lists.
Strategic Opportunities
- Industrial reuse applications:Microbial standards for process water recycling are tightening in food & beverage and semiconductor fabrication, opening premium pricing tiers for disinfectant formulations.
- Bio-based coagulant development:Chitosan and tannin-derived alternatives are gaining regulatory preference under EU Green Deal procurement guidelines, creating first-mover positioning for natural polymer suppliers.
- Digital dosing integration:Real-time turbidity monitoring combined with automated chemical feed systems is enabling outcome-based service contracts that bundle hardware with chemical supply.
Industry Challenges
- Polymer characterization expertise:Municipal utilities lack in-house capability to evaluate molecular weight distribution and charge density in complex flocculant formulations, creating specification ambiguity.
- Legacy clarifier retrofit compatibility:Existing sedimentation infrastructure operates on fixed hydraulic loading rates, limiting uptake of advanced high-molecular-weight polymers that require modified mixing energy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wastewater Treatment Chemicals Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, pH Adjusters, Disinfectants Application: Municipal Treatment, Industrial Processing, Oil & Gas, Agricultural Runoff End User: Water Utilities, Manufacturing, Power Generation, Agriculture Delivery Mode: Liquid, Powder, Granular, Tablet |
| Companies Covered | Ecolab, BASF SE, Kemira, Veolia, Dow, Solenis, Kurita Water Industries Ltd., Nouryon, SNF Floerger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wastewater Treatment Chemicals Market Emerging Trajectories
Formulation science is converging with digital process control, collapsing the traditional separation between chemical supply and equipment optimization. This integration is redefining how utilities evaluate total cost of treatment rather than unit chemical price.
Hybrid organic-inorganic coagulant systems are unifying charge neutralization and sweep flocculation mechanisms in single-dose products. Water treatment operators in Northern European utilities are piloting these formulations to reduce chemical inventory complexity. The technology is unifying previously separate procurement categories into consolidated supply agreements that emphasize performance guarantees over volume commitments.
REACH authorization procedures for acrylamide monomer residuals are accelerating migration toward bio-based alternatives. ECHA substance evaluation timelines are compressing product registration windows, forcing smaller formulators to exit or partner. Northern European municipal tenders now specify maximum residual monomer thresholds that disqualify legacy product grades.
Performance-based contracting is displacing traditional volume-based chemical supply agreements. Industrial end-users in oil & gas and mining are unbundling chemical procurement from equipment service, then rebundling under integrated operator contracts. This restructuring is most visible in German and Dutch industrial clusters where water treatment outsourcing has matured.
Wastewater Treatment Chemicals Market Segmentation
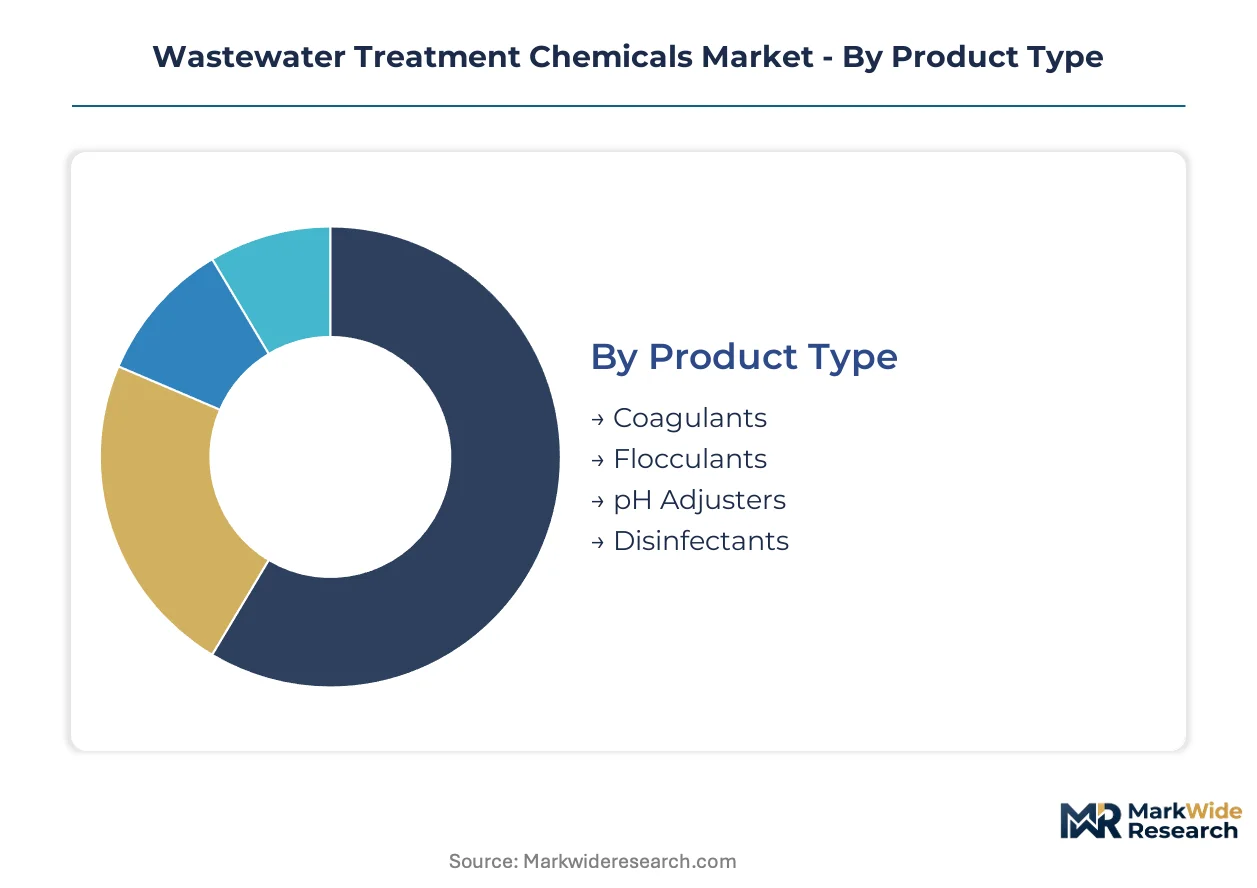
Chemical suppliers structure product portfolios around treatment performance guarantees rather than commodity specifications. Procurement officers in German and Dutch utilities evaluate formulations based on clarifier throughput and sludge dewatering efficiency. The four segmentation dimensions reveal where margin pools concentrate and which delivery formats command premium positioning.
Product Type:
Supply concentration in acrylic acid monomers shapes competitive dynamics across formulation categories. Backward-integrated producers capture margin in high-molecular-weight polymers while independent blenders compete on service density.
- Coagulants:Aluminum sulfate and ferric chloride formulations neutralize negative charges on colloidal particles. Demand concentrates in German municipal facilities facing tightened EU phosphate removal mandates under Urban Wastewater Treatment Directive amendments.
- Flocculants:Polyacrylamide chains with anionic, cationic, or nonionic charge densities aggregate destabilized solids into settleable flocs. Northern European utilities specify maximum residual acrylamide monomer thresholds that disqualify legacy product grades.
- pH Adjusters:Sulfuric acid, caustic soda, and lime products correct influent alkalinity for biological process stability.
- Disinfectants:Chlorine compounds, peracetic acid, and UV-activated formulations eliminate pathogens prior to discharge or reuse.
Flocculants absorb the bulk of installed capacity; disinfectants are expanding most quickly in food & beverage reuse applications.
Application:
Cost tier differentiation separates municipal procurement—driven by compliance deadlines—from industrial users optimizing total treatment cost per cubic meter.
- Municipal Treatment:Clarifier and biological nutrient removal systems in France, Germany, and the Netherlands consume coagulant-flocculant combinations. REACH registration timelines compress product qualification windows for formulators serving public tenders.
- Industrial Processing:Semiconductor fabrication and pharmaceutical manufacturing demand ultrapure water with strict microbial limits. Power plant cooling tower blowdown treatment drives consumption of scale inhibitors alongside pH correction chemicals.
- Oil & Gas:Hydraulic fracturing produced water volumes strain existing treatment infrastructure in extraction basins.
- Agricultural Runoff:Nutrient recovery systems capture phosphorus and nitrogen from livestock operations and intensive crop production.
Municipal treatment absorbs the bulk of installed capacity; oil & gas applications are climbing the fastest as unconventional extraction expands.
End User:
Customer type determines whether procurement emphasizes performance guarantees or lowest unit dosing cost.
- Water Utilities:Public operators in the Netherlands bundle chemical supply with equipment maintenance under long-term service contracts. ECHA substance evaluation procedures force rapid reformulation cycles to maintain approved product lists.
- Manufacturing:Food & beverage processors and electronics fabricators specify disinfectant residuals for process water recycling. German automotive plants integrate chemical dosing with real-time turbidity monitoring for automated feed control.
- Power Generation:Cooling water systems require continuous pH adjustment and biocide treatment to prevent biofouling.
- Agriculture:Large-scale livestock operations deploy lagoon treatment chemicals to meet discharge permit conditions.
Water utilities absorb the bulk of installed capacity; manufacturing end users are gaining share fastest as industrial water reuse standards tighten.
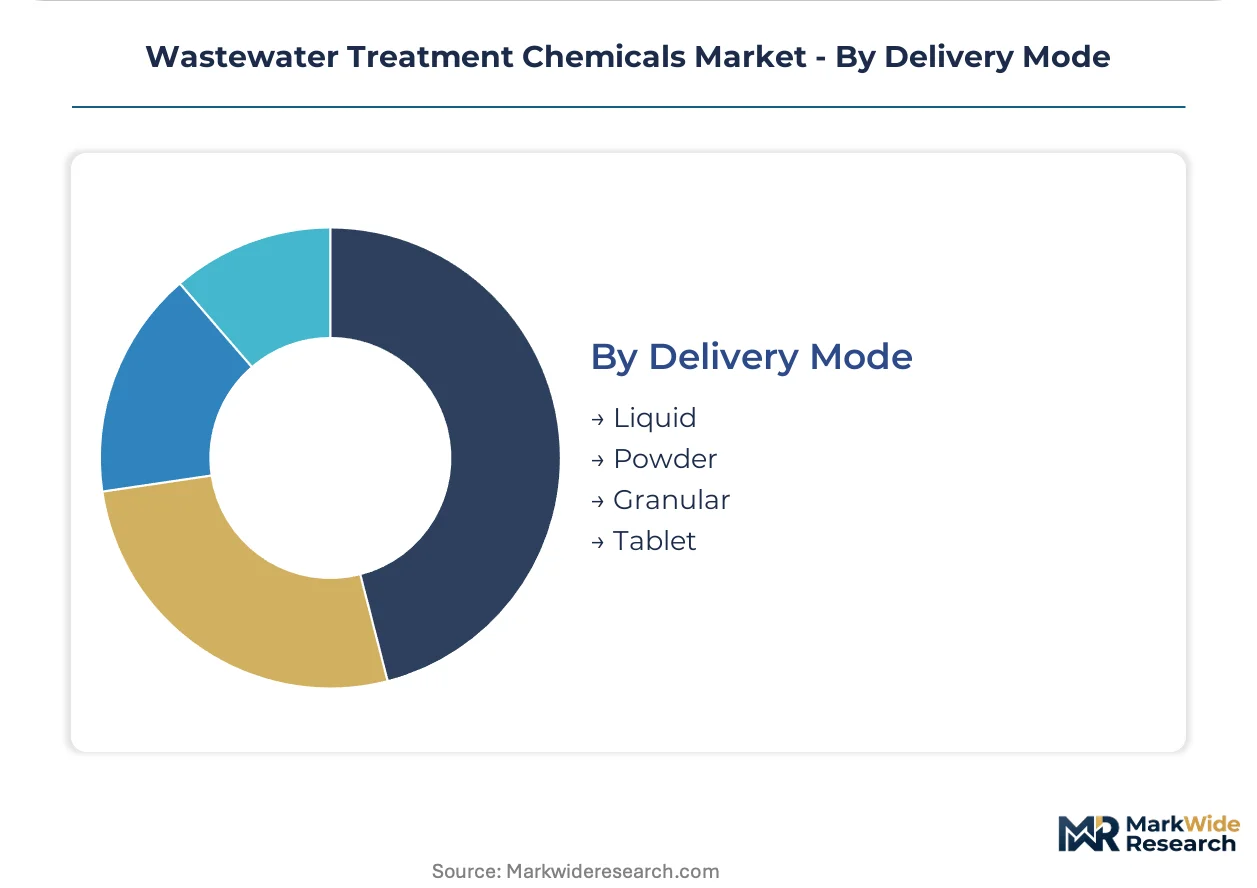
Delivery Mode:
Volume and logistics economics favor liquid formats for high-throughput facilities while powder and granular products reduce transport costs for remote sites.
- Liquid:Ready-to-feed solutions eliminate on-site dissolution equipment. French municipal clarifiers specify liquid polyacrylamide emulsions for automated dosing precision.
- Powder:Dry polymers require controlled wetting and aging systems to achieve full hydration before injection. Powder formats reduce shipping weight for inland treatment plants in agricultural regions.
- Granular:Slow-dissolving alum or ferric chloride granules suit batch treatment operations with intermittent dosing requirements.
- Tablet:Compressed disinfectant tablets enable emergency chlorination and remote lagoon applications without liquid handling infrastructure.
Liquid formats absorb the bulk of installed capacity; tablet delivery is expanding most quickly in decentralized and emergency treatment scenarios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European chemical procurement for municipal wastewater facilities, with Dutch and German utilities driving specification changes under tightened EU discharge mandates.
Germany
North Rhine-Westphalia's municipal treatment plants are scaling polyacrylamide flocculant procurement under EU Urban Wastewater Treatment Directive amendments. ECHA substance evaluation timelines are compressing product registration windows for formulators. The Rhine-Ruhr metropolitan region hosts concentrated blending operations serving Dutch and Belgian cross-border utilities.
France
Île-de-France water utilities are bundling chemical supply with clarifier automation under long-term service contracts. REACH authorization procedures for acrylamide monomer residuals are accelerating reformulation cycles. The Paris metropolitan cluster demands liquid polyacrylamide emulsions for precision dosing in high-throughput facilities.
Netherlands
Randstad municipal operators specify maximum residual acrylamide thresholds that disqualify legacy flocculant grades. The country's national pharmaceutical regulator influences bio-based coagulant approval pathways under EU Green Deal procurement guidelines. Rotterdam's port industrial zone integrates chemical dosing with real-time turbidity monitoring for automated feed control.
United States
EPA National Pollutant Discharge Elimination System permits are tightening effluent limits for oil and gas produced water treatment in the Permian Basin. The agency's toxicity thresholds restrict traditional polyacrylamide formulations. Texas and Louisiana industrial clusters are unbundling chemical procurement from equipment service, then rebundling under integrated operator contracts.
China
Yangtze River Delta municipalities are deploying advanced phosphorus removal systems under MEE discharge standard revisions. The country's dual carbon goals are pressuring petrochemical complexes that supply acrylic acid monomer feedstocks. Shanghai's industrial wastewater treatment parks are piloting hybrid organic-inorganic coagulant systems to reduce chemical inventory complexity.
Wastewater Treatment Chemicals Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the formulation landscape. The vendor base clusters around three strategic archetypes: backward-integrated petrochemical majors controlling monomer supply, regional blenders competing on logistics density, and integrated service providers bundling chemicals with equipment. Dominant competitive moves include captive supply of acrylic acid feedstocks and geographic expansion through local blending networks.
Within the integrated service tier, Ecolab exemplifies outcome-based contracting that bundles hardware with chemical supply. Among European-based formulators, BASF SE and Kemira occupy positions anchored by upstream control over acrylic acid monomers and regional logistics networks respectively. These three names represent the competitive tension between formulation science and distribution economics.
| Leading Market Players |
|---|
| Ecolab |
| BASF SE |
| Kemira |
| Veolia |
| Dow |
| Solenis |
| Kurita Water Industries Ltd. |
| Nouryon |
| SNF Floerger |
| Others |
Supply Flow & Price Mechanics
Backward-integrated petrochemical majors with captive acrylic acid monomer supply exercise asymmetric pricing power over independent European blenders, compressing margins at the formulation tier while protecting upstream returns through supply rationing during feedstock volatility.
Pricing Analysis
Outcome-based pricing tied to clarifier throughput and sludge dewatering efficiency anchors municipal procurement in Germany and the Netherlands. Three-tier pricing structure across premium formulated guarantees, standard technical grades, and economy bulk commodities separates Ecolab's bundled service contracts from commodity spot transactions. Cost compression in standard-grade polyacrylamides is intensifying as REACH-driven reformulation cycles elevate R&D recovery burdens. Industrial oil and gas operators exhibit lowest price sensitivity due to penalty structures for treatment failure, while agricultural runoff applications remain most cost-conscious.
Supply Chain Analysis
Specialized polymer chemist and process engineer availability constraints in the Rhine-Ruhr corridor and Antwerp petrochemical cluster are elevating labor costs for European formulators. Manufacturing concentrates in Germany, Belgium, and the Netherlands, with acrylic acid monomer production anchored in Ludwigshafen and Antwerp complexes. Formulation draws from acrylamide monomer, acrylic acid feedstocks, and bio-based chitosan alternatives. Single-source vulnerability permeates acrylic acid supply where BASF and Nouryon control European output. Distribution runs through regional blending terminals with just-in-time delivery to municipal clarifier sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acrylic acid monomer capacity constraints in European petrochemical corridors prop pricing discipline, as backward-integrated majors ration feedstock access to independent blenders during input cost spikes.
For Market Incumbents: Deploy geographic density expansion through local blending networks in Northern European municipal clusters. BASF SE and Kemira should fortify Rhine-Ruhr logistics hubs against bio-based coagulant entrants gaining preference under EU Green Deal procurement guidelines. Capacity addition in Rotterdam-Antwerp corridor secures cross-border utility contracts. For New Entrants and Emerging Players: Begin with bio-based coagulant formulations targeting Dutch and German municipal tenders specifying maximum residual acrylamide thresholds. Chitosan and tannin-derived alternatives present the most penetrable white space as REACH authorization procedures accelerate legacy product phaseout. Partner with established equipment OEMs for bundled digital dosing integration. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional blenders with dense Northern European logistics networks and existing ECHA product registrations. Mid-cap formulators facing REACH compliance cost burdens represent acquisition targets with recoverable positioning. Watch ECHA substance evaluation timelines as inflection indicator for consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid Monomers | BASF SE secures feedstock access against petrochemical volatility in European supply corridors. |
| Digital Dosing System Integration | Ecolab bundles real-time turbidity monitoring with chemical supply under outcome-based municipal contracts. |
| Bio-Based Coagulant Development | Natural polymer suppliers capture first-mover advantage under EU Green Deal procurement guidelines. |
| Regional Blending Network Expansion | Kemira deepens logistics density in cross-border Dutch-German-Belgian utility clusters. |
| Long-Term Municipal Service Contracts | Integrated providers lock in clarifier automation and chemical procurement under multi-year performance guarantees. |
Methodological Framework
Customs databases, ECHA substance registration filings, and municipal procurement tender records formed the secondary backbone, cross-referenced with primary interviews of plant managers at German and Dutch utilities, procurement leads at downstream oil and gas operators, distribution channel partners in the Rhine-Ruhr corridor, and technical R&D directors at European formulators. Bottom-up chemical volume estimates triangulated against top-down market value reconstruction.
Historical trendline analysis of polyacrylamide consumption patterns, coagulant procurement cycles, and disinfectant adoption curves informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type tier, application end-use, delivery mode format, and regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for REACH compliance cost impacts and EU Urban Wastewater Treatment Directive implementation timelines.
Acrylic acid supply disruptions, accelerated PFAS restriction timelines, and municipal budget austerity measures are the dominant revision risks to forecast assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
US Sludge Management and Dewatering Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Alkalinity Control Chemicals Market
Water & Sludge Treatment
North America Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Water Softening Systems Market
Water & Sludge Treatment
Global Sodium Hypochlorite Market
Water & Sludge Treatment
Europe Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Water Purification Systems Market
Water & Sludge Treatment
North America Industrial Water Treatment Market
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market
Water & Sludge Treatment
Process Chemicals for Water Treatment Market
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
Australia Water Treatment Chemicals Market