
 Saudi Arabia Industrial Hazardous Waste Management Market | 2026-2036
Saudi Arabia Industrial Hazardous Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Industrial Hazardous Waste Management Market Insights
ISO 14001 environmental management certification is unwinding the competitive landscape for new entrants seeking Royal Commission contracts. Veolia Environment SA leverages its integrated treatment and disposal footprint across Jubail and Yanbu to sustain long-term service agreements with SABIC affiliates. REMONDIS anchors its position through specialized incineration capacity at the Jeddah hazardous waste facility, while Averda competes aggressively on transportation logistics coverage across the Eastern Province.
Industrial hazardous waste management encompasses the controlled handling, treatment, and final disposition of wastes exhibiting ignitability, corrosivity, reactivity, or toxicity above thresholds defined by the Saudi Waste Management Regulation, with thermal destruction achieving 99.99% destruction removal efficiency for organic contaminants. Treatment services command premium pricing due to the capital intensity of rotary kiln incinerators and stabilization ponds required for heavy metal sludges. Chemical waste from petrochemical cracking and polymerization dominates volume flows, while radioactive waste from upstream oilfield operations generates disproportionate margin pools given its restricted disposal pathway to the King Abdulaziz City for Science and Technology licensed facilities.
The Saudi Environmental Special Forces, the Presidency of Meteorology and Environment (PME), and the Royal Commission for Jubail and Yanbu collectively enforce manifesting, cradle-to-grave tracking, and landfill liner specifications that dictate operational compliance costs. SFDA oversight of pharmaceutical manufacturing waste and MOHAP clinical waste protocols further segment service requirements across the Kingdom. Stakeholders must monitor how the Saudi Green Initiative's circular economy targets reshape permitted disposal routes before committing to long-term incineration asset deployments.
Market Dynamics
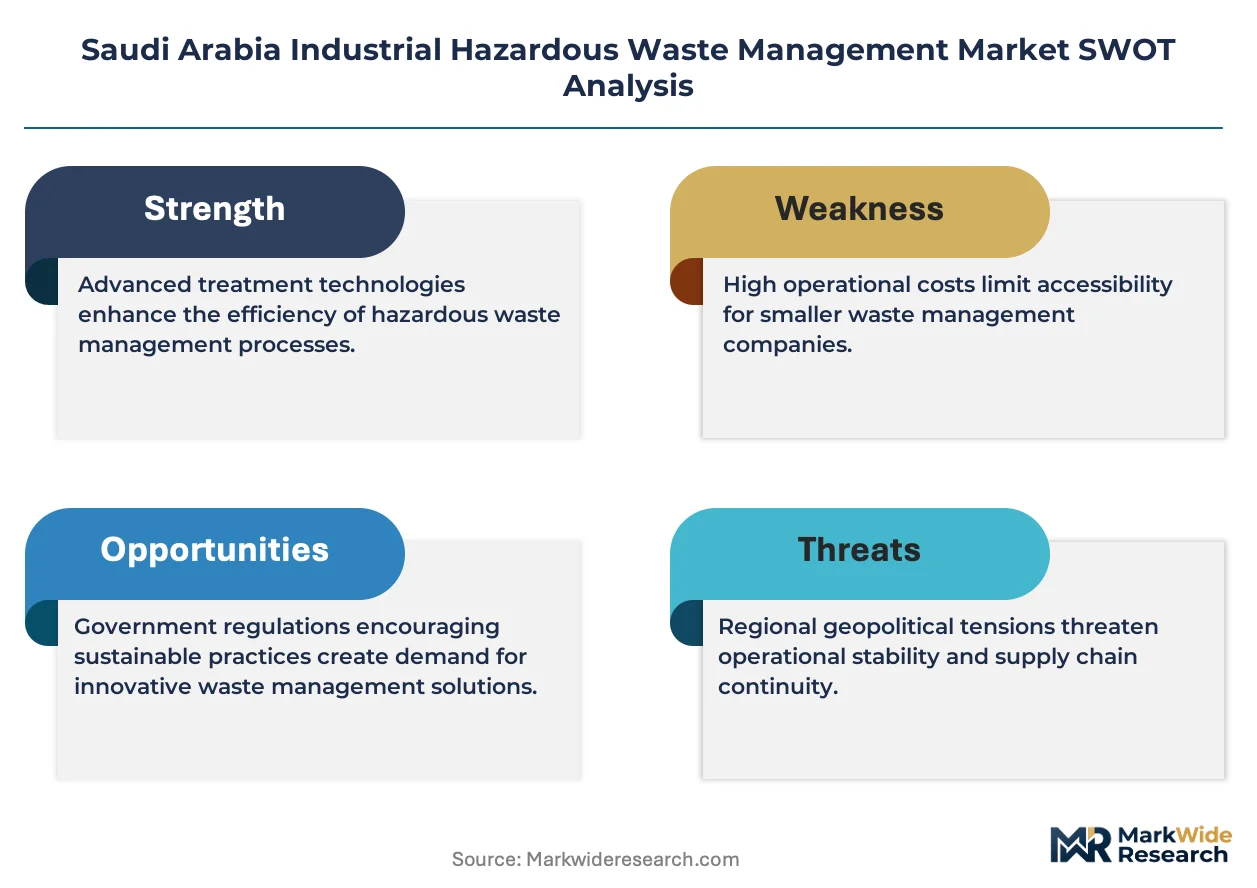
The Saudi Environmental Special Forces' enforcement of updated waste manifesting rules is compressing compliance timelines and forcing operators to upgrade tracking infrastructure ahead of asset depreciation cycles.
Growth Catalysts
- Downstream Petrochemical Expansion:Saudi Aramco's integrated refining and petrochemical complexes along the Gulf coast generate sustained volume flows of chemical sludge and spent catalysts requiring thermal treatment.
- Royal Commission Infrastructure Mandates:Dedicated hazardous waste pipelines and central treatment facilities in Jubail Industrial City reduce logistics costs for generators clustering within the zone.
- SFDA Pharmaceutical Oversight:Stringent disposal protocols for active pharmaceutical ingredients and cytotoxic manufacturing residues create specialized service demand distinct from general industrial waste streams.
Market Restraints
- Rotary Kiln Capital Intensity:High-temperature incineration systems require substantial upfront investment with extended payback periods, limiting new entrant participation.
- Licensed Disposal Pathway Concentration:Radioactive waste from upstream oilfield operations faces restricted routing to King Abdulaziz City for Science and Technology facilities, creating single-point dependency.
- Stabilization Chemical Input Volatility:Heavy metal sludge treatment depends on reagent availability whose pricing fluctuates with sulfur and lime supply chains.
Strategic Opportunities
- Yanbu Industrial City Underpenetration:The Red Sea corridor lacks comparable integrated treatment infrastructure, presenting greenfield development potential for operators with marine logistics capabilities.
- Circular Economy Mandates:The Saudi Green Initiative's waste-to-resource targets may expand permitted recycling pathways for certain solvent and oil-bearing wastes currently routed to destruction.
- Digital Manifest Convergence:Integration of blockchain tracking with existing cradle-to-grave systems offers differentiation for operators seeking Royal Commission technology upgrade contracts.
Industry Challenges
- ISO 14001 Certification Timeline:New entrants face extended approval windows for environmental management certification required for Royal Commission contract eligibility.
- Cross-Regulatory Compliance Burden:Operators serving pharmaceutical, petrochemical, and clinical waste generators simultaneously must maintain parallel protocols under SFDA, PME, and MOHAP jurisdictions.
- Specialized Incineration Talent Scarcity:Rotary kiln operation and maintenance expertise remains concentrated among a limited pool of technicians with thermal destruction system experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Industrial Hazardous Waste Management Market |
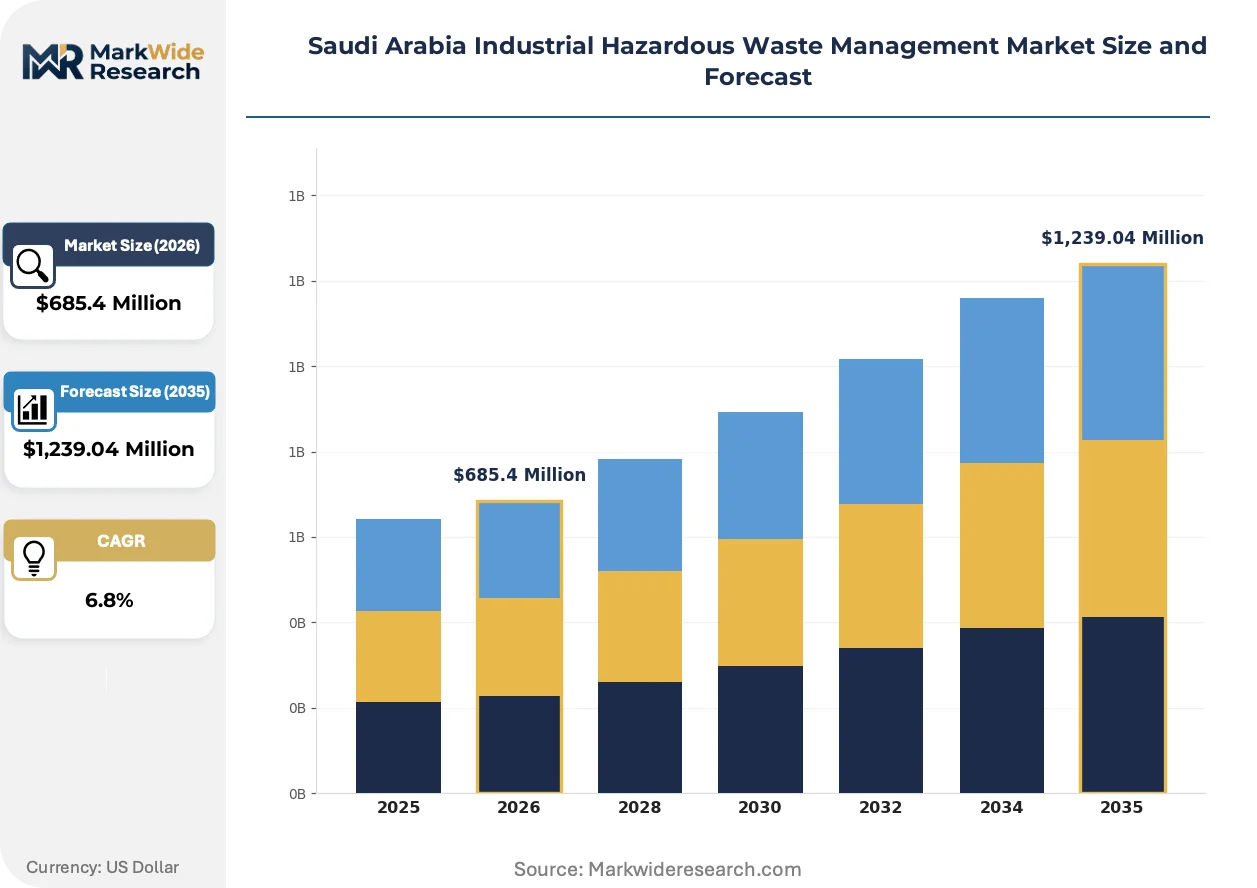
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Transportation, Treatment, Disposal Waste Type: Chemical, Biological, Radioactive, Electronic End User: Manufacturing, Construction, Healthcare, Energy Regulatory Framework: Local Regulations, International Standards, Compliance Guidelines, Risk Management |
| Companies Covered | Averda, REMONDIS, Veolia Environment SA, EnviroServe, Tradebe Environmental Services, SUEZ Environnement S.A., BEEAH Group, Bee'ah, Clean Harbors, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Industrial Hazardous Waste Management Market Trends and Innovations
Thermal treatment technologies and digital compliance systems are reshaping operational requirements for hazardous waste service providers across the Kingdom's industrial corridors.
Plasma arc gasification is bifurcating the high-temperature destruction segment. SABIC affiliates and large petrochemical complexes are piloting units for complex organic waste streams that exceed rotary kiln efficiency thresholds. The technology is bifurcating capital deployment patterns, concentrating advanced thermal capacity among integrated operators while marginalizing conventional incineration for lower-calorific waste categories.
PME manifesting rule updates are mandating real-time GPS tracking and electronic signature capture for all hazardous waste shipments. The regulation forces transportation providers to retrofit fleet management systems and integrate with Royal Commission databases. Small logistics operators lacking digital infrastructure face exclusion from Eastern Province contract pools.
Service unbundling is fragmenting traditional bundled contracts. Petrochemical generators are separating transportation, treatment, and disposal functions to optimize costs across specialized providers. The shift is most pronounced in Jubail, where Royal Commission zone access allows multi-vendor coordination without geographic penalty.
Saudi Arabia Industrial Hazardous Waste Management Market Segmentation
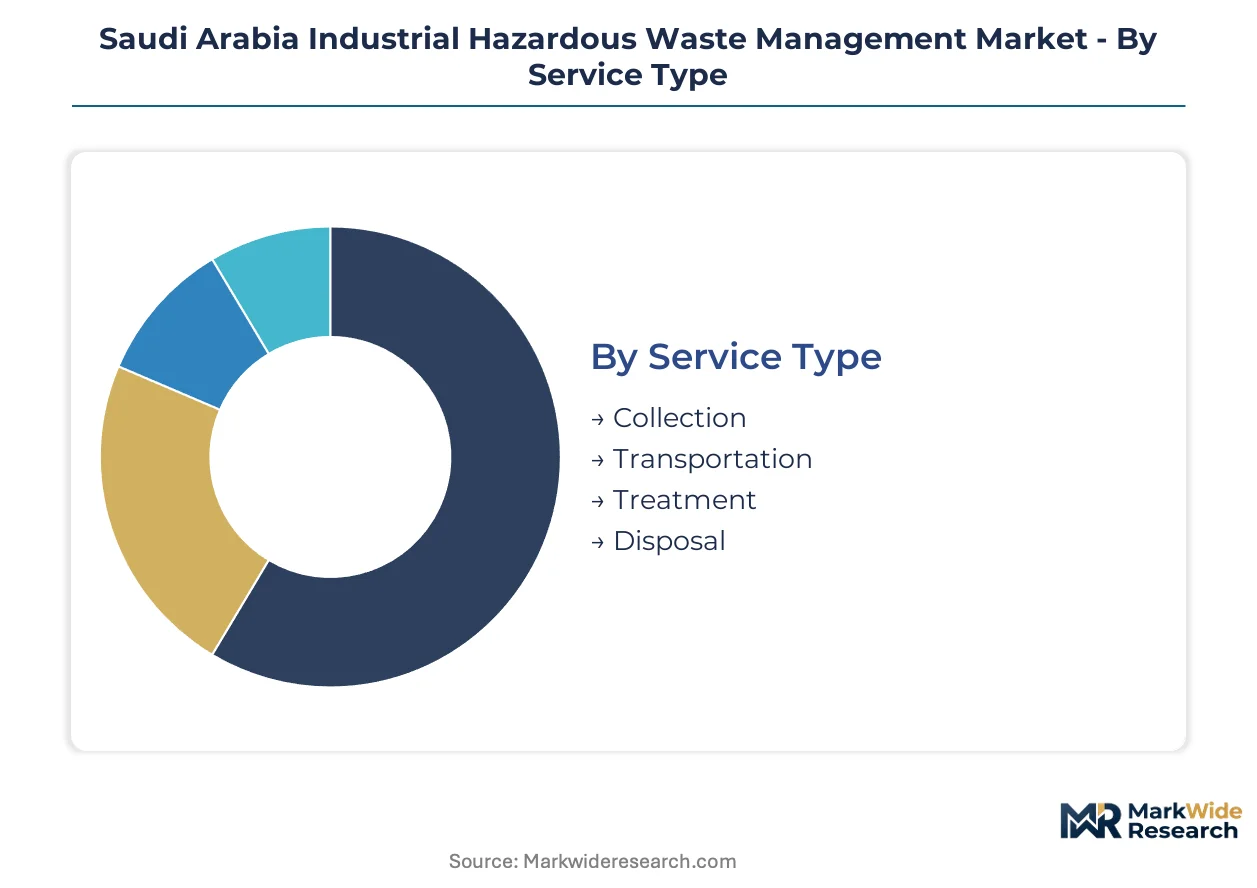
Service differentiation across the hazardous waste value chain determines contract profitability and regulatory risk exposure for operators serving Saudi Arabia's industrial zones. Segmentation reveals where capital deployment concentrates versus where logistics arbitrage opportunities emerge.
Service Type:
Domestic demand dominates collection and transportation, while treatment and disposal services attract specialized international operators through Royal Commission joint ventures.
- Collection:On-site segregation and containerization at generator facilities requires PME-certified personnel and specialized containment for corrosive or reactive streams. Demand clusters in Jubail Industrial City, where Royal Commission mandates dictate standardized bin specifications and pickup frequencies for SABIC-affiliated complexes.
- Treatment:Thermal destruction, chemical neutralization, and stabilization processes achieve regulatory thresholds before final disposition. Rotary kiln incineration commands premium pricing due to 99.99% destruction removal efficiency requirements for organic contaminants from petrochemical cracking operations.
- Transportation:GPS-tracked hazmat fleets with ADR-equivalent certification move waste between generator sites and licensed facilities. Eastern Province operators compete on route density and manifesting software integration with Saudi Environmental Special Forces databases.
- Disposal:Secure landfill placement and salt dome containment for stabilized residues require Royal Commission-approved liner specifications and leachate monitoring systems.
Collection commands the established base. The steepest expansion runs through Treatment.
Waste Type:
Volume flows concentrate in chemical streams from downstream petrochemical expansion, while margin pools disproportionately favor restricted-pathway categories.
- Chemical:Spent catalysts, solvent residues, and polymerization byproducts from Saudi Aramco's integrated refining complexes constitute the dominant volume category. Thermal treatment capacity constraints in Jubail and Yanbu create periodic bottlenecks during turnaround seasons.
- Radioactive:NORM and sealed sources from upstream oilfield operations face single-point routing dependency to King Abdulaziz City for Science and Technology licensed facilities. Disposal scarcity generates premium pricing multiples relative to conventional industrial waste.
- Biological:Infectious agents and cytotoxic residues from pharmaceutical manufacturing fall under SFDA oversight with distinct manifesting protocols from general industrial streams.
- Electronic:Circuit boards and battery assemblies containing heavy metals require dismantling and component separation before metal recovery or hazardous fraction treatment.
Chemical waste anchors volume throughput. Radioactive streams deliver the steepest margin expansion.
End User:
Petrochemical-led manufacturing drives treatment capacity utilization, while healthcare and energy generators fragment service requirements across specialized protocols.
- Manufacturing:SABIC affiliates and downstream chemical producers in Jubail Industrial City generate sustained flows of organic sludge and spent solvents requiring rotary kiln incineration. ISO 14001 certification requirements for Royal Commission contracts favor established operators with integrated treatment footprints.
- Energy:Upstream oilfield operations produce NORM-contaminated equipment and drilling wastes with restricted disposal pathways. King Abdulaziz City for Science and Technology licensing creates bottleneck risk for generators without long-term treatment agreements.
- Healthcare:MOHAP clinical waste protocols and SFDA pharmaceutical manufacturing oversight impose parallel compliance frameworks distinct from PME industrial regulations.
- Construction:Asbestos-containing materials and treated wood preservatives from infrastructure projects require specialized transportation and landfill cells with enhanced liner specifications.
Manufacturing anchors contracted capacity. Energy sector waste commands the steepest tariff escalation.
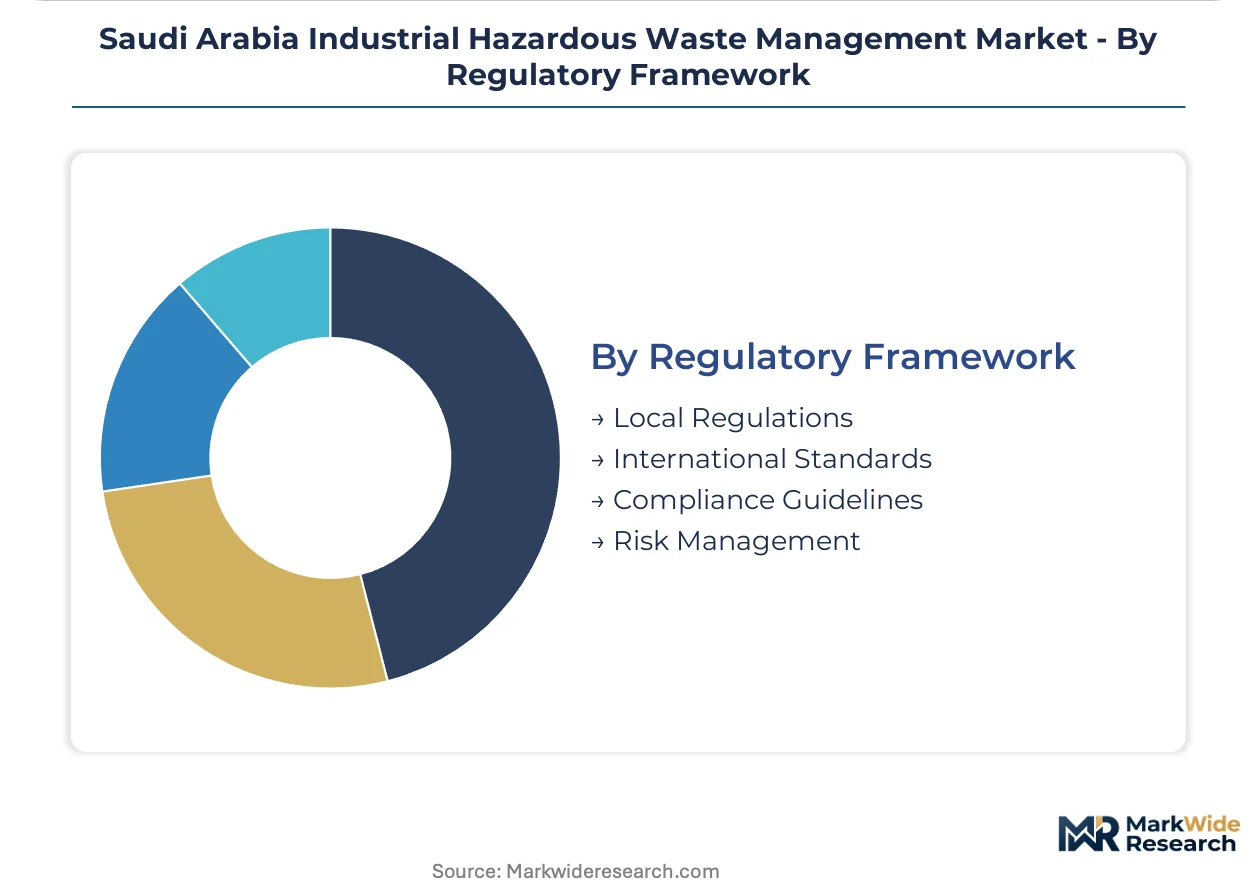
Regulatory Framework:
Local PME and Royal Commission rules dictate operational compliance costs, while international certification gates access to premium contract pools.
- Local Regulations:Saudi Waste Management Regulation thresholds for ignitability, corrosivity, reactivity, and toxicity define waste classification and permitted handling protocols. Saudi Environmental Special Forces enforcement of updated manifesting rules compresses compliance timelines for transportation providers.
- International Standards:ISO 14001 environmental management certification and Basel Convention transboundary movement protocols enable cross-border service provision and joint venture eligibility for multinational operators.
- Compliance Guidelines:Sector-specific protocols under SFDA pharmaceutical oversight and MOHAP clinical waste rules fragment service requirements for multi-sector operators.
- Risk Management:Cradle-to-grave liability frameworks and financial assurance requirements for post-closure care shape long-term contract structuring and insurance costs.
Local Regulations anchor enforcement activity. International Standards certification unlocks the steepest contract tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Saudi Environmental Special Forces' enforcement of updated manifesting rules is compressing compliance timelines across industrial zones. Royal Commission infrastructure mandates in Jubail and Yanbu create distinct operational environments for hazardous waste service providers. Sub-regional differentiation reflects proximity to petrochemical complexes, regulatory jurisdiction boundaries, and specialized treatment capacity concentration.
Eastern Province
Jubail Industrial City anchors volume flows through SABIC-affiliated petrochemical complexes generating spent catalysts and organic sludge. Royal Commission mandates dictate standardized container specifications and dedicated hazardous waste pipelines reducing logistics costs. Yanbu Industrial City on the Red Sea corridor lacks comparable integrated infrastructure, presenting greenfield development potential for operators with marine logistics capabilities.
Riyadh
Central region pharmaceutical manufacturing under SFDA oversight generates cytotoxic residues and active pharmaceutical ingredient waste requiring specialized incineration. The Saudi Green Initiative's circular economy targets are reshaping permitted disposal routes for solvent-bearing wastes. Industrial zones south of the capital concentrate medical device and electronics assembly operations producing heavy metal-contaminated process water.
Western Region
Jeddah's hazardous waste facility anchors REMONDIS specialized incineration capacity for biological and chemical streams from Red Sea port operations. MOHAP clinical waste protocols impose distinct manifesting requirements on healthcare generators across Makkah and Madinah provinces. Construction activity around the King Abdullah Economic City generates asbestos-containing materials requiring landfill cells with enhanced liner specifications.
NEOM Northwest
The giga-project's zero-waste targets are piloting plasma arc gasification for complex organic streams exceeding conventional incineration efficiency thresholds. PME manifesting rule updates mandate real-time GPS tracking for all shipments entering the zone. Marine logistics integration with Red Sea shipping lanes positions the region for circular economy waste-to-resource pathways currently restricted under existing regulations.
Saudi Arabia Industrial Hazardous Waste Management Market Competitive Landscape
Player mix skews toward multinational environmental services conglomerates with Royal Commission joint venture histories. Three domestic logistics specialists compete on Eastern Province route density. The competitive structure splits between integrated treatment-disposal operators and unbundled transportation providers. Capacity expansion and ISO 14001 certification acceleration represent the dominant competitive moves as new entrants face extended approval windows.
Among France-based environmental services conglomerates, Veolia Environment SA exemplifies the integrated treatment archetype through its Jubail and Yanbu footprint. REMONDIS anchors the specialized incineration tier with Jeddah facility positioning. Averda occupies the logistics-coverage position competing on Eastern Province transportation network reach.
| Leading Market Players |
|---|
| Averda |
| REMONDIS |
| Veolia Environment SA |
| EnviroServe |
| Tradebe Environmental Services |
| SUEZ Environnement S.A. |
| BEEAH Group |
| Bee'ah |
| Clean Harbors, Inc. |
| Others |
Pricing and Supply Chain Analysis
Rotary kiln incineration scale economies in Jubail Industrial City establish price floors that marginalize smaller operators lacking comparable throughput volumes. Royal Commission infrastructure mandates compress logistics costs for integrated treatment providers while forcing unbundled transportation competitors into rate-based competition.
Pricing Analysis
Certification level creates the primary spread between contract tiers. Royal Commission eligibility demands ISO 14001 environmental management certification, which gates access to premium SABIC-affiliated petrochemical contracts. Three-tier pricing structure across certified integrated operators, qualified domestic specialists, and unbundled logistics providers reflects capability differentiation. Cost compression in transportation services is intensifying because PME manifesting rule upgrades force fleet management system investments. Small Eastern Province logistics operators exhibit highest price sensitivity due to digital infrastructure retrofit requirements.
Supply Chain Analysis
Stabilization chemical lead times stretch 6-10 weeks for sulfur and lime reagents used in heavy metal sludge treatment. Germany, the Netherlands, and Saudi Arabia supply rotary kiln incineration systems and specialized containment equipment. Chemical reagent availability draws from global sulfur supply chains and regional lime production. Single-source vulnerability concentrates in radioactive waste routing to King Abdulaziz City for Science and Technology facilities. Distribution runs through Royal Commission-sanctioned hazardous waste pipelines in Jubail and GPS-tracked hazmat fleets serving dispersed generators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Limited rotary kiln operation expertise and extended ISO 14001 certification timelines create asset-specific scarcity that shapes competitive dynamics. The market rewards operators with captive thermal destruction capacity and Royal Commission joint venture histories.
For Market Incumbents: Fortify treatment capacity utilization through long-term offtake agreements with Saudi Aramco downstream complexes ahead of plasma arc gasification pilots. Secure backward integration into stabilization chemical supply through sulfur procurement partnerships. Capacity addition in Yanbu Industrial City addresses Red Sea corridor underpenetration before marine logistics specialists establish beachheads. For New Entrants and Emerging Players: Differentiate on blockchain-enabled manifesting integration with Saudi Environmental Special Forces databases. Yanbu Industrial City presents the most penetrable geography given absent integrated treatment infrastructure. Target pharmaceutical manufacturing waste under SFDA oversight where specialized incineration requirements fragment service competition away from petrochemical-dominated incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with proven plasma arc gasification deployment capabilities for NEOM giga-project zero-waste targets. Long-term viability hinges on circular economy pathway expansion under Saudi Green Initiative mandates. Watch for PME rule updates permitting solvent and oil-bearing waste recycling as inflection signal for incineration asset stranded risk.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Arc Gasification Deployment | NEOM's zero-waste targets pilot advanced thermal destruction exceeding rotary kiln efficiency thresholds. |
| Blockchain Manifesting Integration | Real-time GPS tracking mandates from Saudi Environmental Special Forces create technology upgrade contract pools. |
| Yanbu Greenfield Development | Red Sea corridor lacks comparable integrated treatment infrastructure to Jubail's Royal Commission zone. |
| Stabilization Chemical Backward Integration | Sulfur and lime reagent supply security mitigates input volatility for heavy metal sludge treatment. |
| SFDA Pharmaceutical Certification | Specialized incineration protocols for cytotoxic residues fragment service requirements from general industrial waste. |
Research Methodology
A standing panel of rotary kiln operations managers, Royal Commission contract officers, pharmaceutical manufacturing EHS directors, and hazmat fleet logistics coordinators provided ongoing calibration throughout the study. Primary interviews with SABIC-affiliated facility managers and SFDA regulatory affairs specialists combined with secondary validation from PME enforcement bulletins, Royal Commission infrastructure disclosures, and Saudi Green Initiative circular economy policy documents. Bottom-up treatment capacity utilization modeling and top-down petrochemical waste generation estimates underwent cross-referencing.
Consistency checks validated volume and value outputs against external benchmarks including customs records for stabilization chemical imports and Royal Commission zone occupancy filings. Segmentation modeling spanned service type, waste category, end-user industry, and regulatory jurisdiction tier across the projection horizon. CAGRs derived from installed incineration capacity expansion schedules and petrochemical complex turnaround patterns. Forecast inputs incorporated Saudi Aramco downstream investment timelines and PME manifesting rule implementation phases.
The analysis sits within stated boundaries; outcomes outside sustained petrochemical capacity expansion or accelerated circular economy mandate adoption would require recalibration. Forecasts reflect assumptions regarding Royal Commission infrastructure continuity and SFDA pharmaceutical oversight stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Salt Water Softeners Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Membrane Bioreactor (MBR) Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
Ultrapure Water Market
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Australia & New Zealand Water Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Water Treatment Market
Water & Sludge Treatment
Alkalinity Control Chemicals Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Global Water Treatment Technology Market