
 Global Spiral Membrane Market | 2026-2036
Global Spiral Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spiral Membrane Market Foresight
Polyamide thin-film composite chemistry is narrowing the performance gap between seawater and brackish water reverse osmosis elements, enabling standardized platform designs across salinity gradients. DuPont leverages its materials science heritage to sustain proprietary interfacial polymerization know-how at scale. Toray Industries anchors Asian supply chains through integrated membrane sheet and element manufacturing. Hydranautics specializes in high-productivity low-energy configurations for municipal desalination plants.
Spiral membrane denotes a flat-sheet membrane wound around a permeate collection tube, with feed spacers creating turbulent flow channels typically 28–34 mil thick; this geometry maximizes surface area within pressure vessel housings for continuous crossflow filtration. Reverse osmosis dominates value capture due to energy-intensive desalination applications requiring high salt rejection above 99.5 percent. Ultrafiltration segments compete on replacement frequency in food and beverage processing, where dairy protein concentration drives membrane consumption. Polyamide materials lead product type margins, though polysulfone substrates retain share in pH-tolerant industrial wastewater streams.
EPA effluent guidelines and the EU Water Framework Directive shape product specifications for discharge compliance across North American and European installations. FDA process validation requirements for pharmaceutical manufacturing constrain membrane supplier qualification timelines for biopharmaceutical firms. Saudi Arabia's Saline Water Conversion Corporation procurement standards and China's GB/T standards for membrane elements collectively determine market access thresholds in the two largest national desalination programs. Stakeholders must monitor evolving boron rejection specifications and anti-scaling chemical compatibility as project developers specify longer element lifecycles.
Market Dynamics
Polyamide thin-film composite chemistry is compressing the performance differential between seawater and brackish water reverse osmosis elements, forcing manufacturers toward unified platform architectures that serve multiple salinity grades without element redesign.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Tightened discharge standards for industrial wastewater in the United States are mandating membrane-based tertiary treatment, expanding retrofit demand across chemical processing and power generation facilities.
- Saudi Arabia's Megaproject Pipeline:Reverse osmosis trains at Jubail and Yanbu industrial cities require high-rejection spiral-wound elements, concentrating procurement volume in a single national program.
- Thin-Film Nanocomposite Integration:Zeolite and metal-organic framework incorporation into active layers is boosting boron rejection above 93 percent, enabling single-pass compliance with WHO drinking water guidelines.
Market Restraints
- Polymer Feedstock Volatility:Bisphenol-A and m-phenylenediamine prices fluctuate with benzene derivatives markets, compressing gross margins for polysulfone substrate and polyamide active layer producers.
- Asian Supply Concentration:Integrated membrane sheet manufacturing clusters in Japan and South Korea create geographic risk exposure for European and North American element assemblers dependent on imported roll goods.
- Fouling-Induced Lifecycle Compression:Biological and colloidal fouling in high-organic feedwaters limits element service life to 3-5 years versus 7-10 in clean applications, accelerating replacement cost burdens for municipal operators.
Strategic Opportunities
- India's Industrial Wastewater Mandate:Zero liquid discharge requirements under Central Pollution Control Board directives are creating first-time membrane adoption in textile dyeing and tannery clusters across Tamil Nadu and Gujarat.
- Direct Potable Reuse Regulatory Tailwind:California's Title 22 and Colorado's direct potable reuse framework are legalizing membrane-treated municipal effluent for drinking water, opening municipal procurement channels previously restricted to non-potable applications.
- Forward Osmosis-Concentrator Hybridization:Integration of forward osmosis draw-solute systems with thermal brine concentrators is enabling zero liquid discharge at half the energy intensity of conventional crystallizers, targeting oilfield produced water in Texas and Alberta.
Industry Challenges
- Interfacial Polymerization Process Control:Thin-film composite manufacturing requires sub-micron thickness uniformity across 1.5-meter membrane sheets; skilled technician scarcity limits yield rates at new production facilities.
- FDA Process Validation Timelines:Biopharmaceutical membrane qualification requires 12-18 month validation protocols for extractables and particulate shedding, delaying supplier switching and freezing incumbent positions.
- Legacy Pressure Vessel Retrofit Friction:Existing 8-inch diameter vessel fleets cannot accommodate newer 16-inch high-area elements without header modification, slowing adoption of next-generation configurations at brownfield sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spiral Membrane Market |
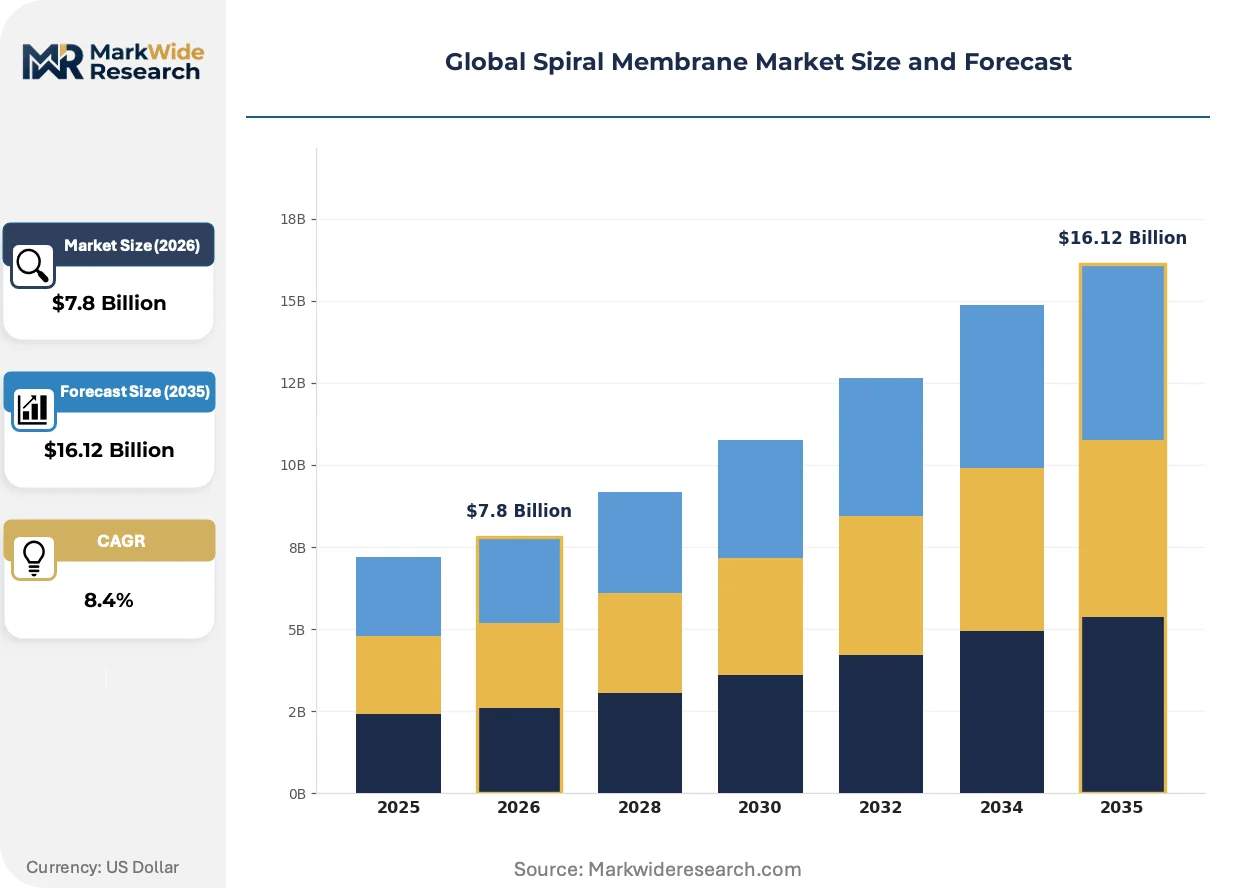
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis, Nanofiltration, Ultrafiltration, Microfiltration Application: Wastewater Treatment, Food & Beverage Processing, Pharmaceutical Manufacturing, Desalination Material: Polyamide, Polyethersulfone, Polysulfone, Cellulose Acetate End User: Water Treatment Facilities, Beverage Producers, Biopharmaceutical Firms, Chemical Manufacturers |
| Companies Covered | Alfa Laval, Toray Industries Inc, DuPont, Hydranautics, LG Chem, Pentair, Koch Membrane Systems, Pall Corporation, SUEZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spiral Membrane Market Shifts & Advancements
Membrane chemistry and system architecture are converging toward energy-minimized configurations that reduce specific energy consumption below 2.5 kWh per cubic meter in seawater applications, reshaping competitive differentiation around lifecycle cost rather than capital expenditure.
Graphene oxide-polyamide nanocomposite active layers are hybridizing conventional interfacial polymerization with two-dimensional material deposition, enabling 15-20 percent permeability gains without salt passage degradation. Desalination developers in Israel and Singapore are piloting these elements at 800-psi operating pressures. The technology is hybridizing the boundary between seawater and brackish water product categories, collapsing SKU proliferation.
REACH restriction proposals on per- and polyfluoroalkyl substances are pressuring membrane manufacturers to eliminate PTFE-based feed spacers and permeate carrier fabrics from element construction. The European Chemicals Agency's 2023 restriction roadmap targets fluoropolymer persistence in wastewater streams. Element producers are responding with polypropylene and polyethylene terephthalate spacer alternatives that sacrifice some chemical tolerance for regulatory compliance.
Long-term service agreements are displacing spot-element procurement in large municipal desalination plants, with contractors assuming membrane replacement risk and guaranteeing permeate quality over 10-15 year concessions. Acciona and Suez are structuring these contracts in Saudi Arabia and Australia. The shift concentrates supplier selection power with engineering-procurement-construction firms rather than plant operators.
Global Spiral Membrane Market Segmentation
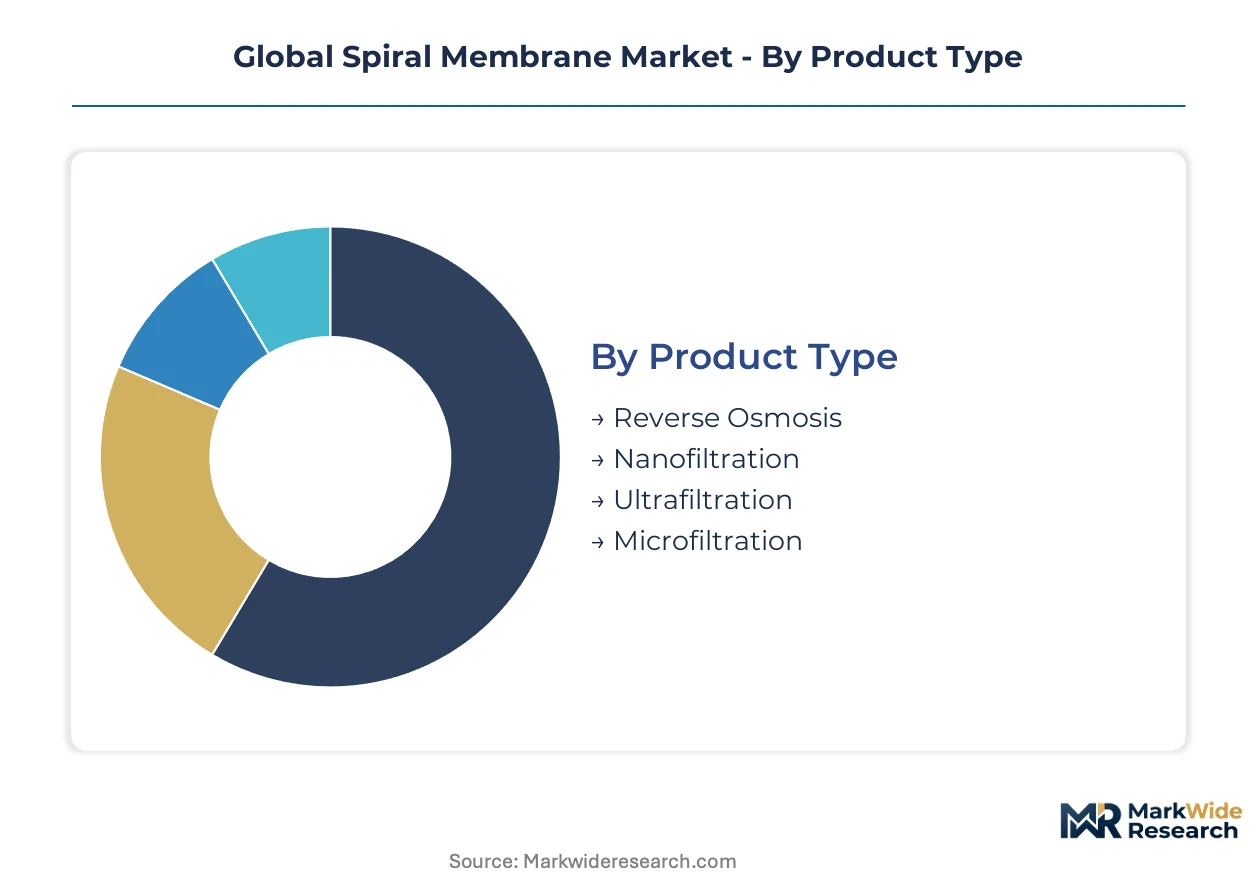
Spiral membrane procurement patterns diverge sharply across application contexts, with desalination operators prioritizing element longevity over replacement frequency while food processors accept shorter cycles to maintain hygienic standards. Material selection cascades through specification chains, locking end users into compatible cleaning chemistries and spare parts ecosystems for decade-long operational horizons.
Product Type:
After-sales intensity peaks in reverse osmosis, where membrane replacement represents 15-20 percent of lifecycle operating cost and technical service contracts extend 10-15 years.
- Reverse Osmosis:Polyamide thin-film composite layers achieve salt rejection above 99.5 percent at operating pressures of 800-1,200 psi. Saudi Arabia's Saline Water Conversion Corporation procurement concentrates demand for 8-inch and 16-inch seawater elements at Jubail and Yanbu industrial complexes, with boron rejection specifications tightening to 93 percent for single-pass compliance.
- Nanofiltration:Divalent ion-selective separation enables water softening and selective contaminant removal without full desalination energy burden. Municipal utilities in California's Central Valley are adopting nanofiltration trains for agricultural drainage remediation, where sulfate and hardness reduction precedes groundwater recharge.
- Ultrafiltration:0.01-0.1 micron pore structures retain macromolecules and colloids in dairy protein concentration and beverage clarification. Replacement cycles compress to 2-4 years in high-organic feedwaters.
- Microfiltration:0.1-10 micron ratings target suspended solids and bacteria in pre-treatment and wine filtration. Cellulose acetate variants serve cost-sensitive industrial streams.
By volume, reverse osmosis leads. By growth pace, nanofiltration is ahead in municipal softening applications.
Application:
Cost tier stratification separates capital-intensive desalination infrastructure from operational-expense-driven food processing installations.
- Wastewater Treatment:Tertiary membrane bioreactors and polishing trains achieve EPA effluent limitation guideline compliance for nitrogen, phosphorus, and emerging contaminants. Industrial facilities in Texas and Louisiana are retrofitting chemical plant outfalls with ultrafiltration-nanofiltration hybrid systems to meet discharge permit renewal conditions.
- Food & Beverage Processing:Dairy whey protein concentration and juice clarification drive high-frequency membrane replacement, with sanitary design requirements mandating 3-A standard compliance. European dairy cooperatives in the Netherlands and Denmark specify polysulfone ultrafiltration cassettes for MPC-80 and MPI-90 protein isolate production.
- Pharmaceutical Manufacturing:FDA process validation requirements for extractables and particulate shedding extend supplier qualification timelines to 12-18 months. Biopharmaceutical firms in Massachusetts and North Carolina source validated polyethersulfone membranes for monoclonal antibody concentration and diafiltration.
- Desalination:Seawater and brackish water reverse osmosis trains dominate installed capacity in Israel, Singapore, and Australia's Western Corridor Recycled Water scheme. Energy recovery device integration has compressed specific consumption below 2.5 kWh per cubic meter.
Desalination commands the highest unit values. Wastewater treatment is expanding most quickly on retrofit mandates.
Material:
Supply concentration in aromatic polyamide chemistry creates margin pressure when benzene derivative feedstocks fluctuate.
- Polyamide:Interfacial polymerization of m-phenylenediamine and trimesoyl chloride creates 0.2-micron selective layers on polysulfone substrates. Thin-film nanocomposite variants incorporating zeolites or metal-organic frameworks are gaining share in high-boron rejection applications at Israel's national water carrier and Singapore's Tuas Desalination Plant.
- Polysulfone:pH tolerance from 1-13 and chlorine resistance up to 200 ppm enable aggressive cleaning protocols in industrial wastewater streams. German chemical manufacturers specify polysulfone ultrafiltration for caustic recovery in textile mercerization operations.
- Polyethersulfone:Low protein binding and gamma sterilization compatibility serve biopharmaceutical downstream processing. South Korean biologics contract manufacturers are qualifying PES membranes for viral clearance validation.
- Cellulose Acetate:Hydrophilic surface chemistry resists organic fouling in food applications but hydrolyzes above pH 8.0, limiting service life. Legacy installations in Brazilian sugar-ethanol mills continue replacement procurement.
Polyamide dominates value capture. Polyethersulfone is gaining share fastest in biopharma validation pipelines.
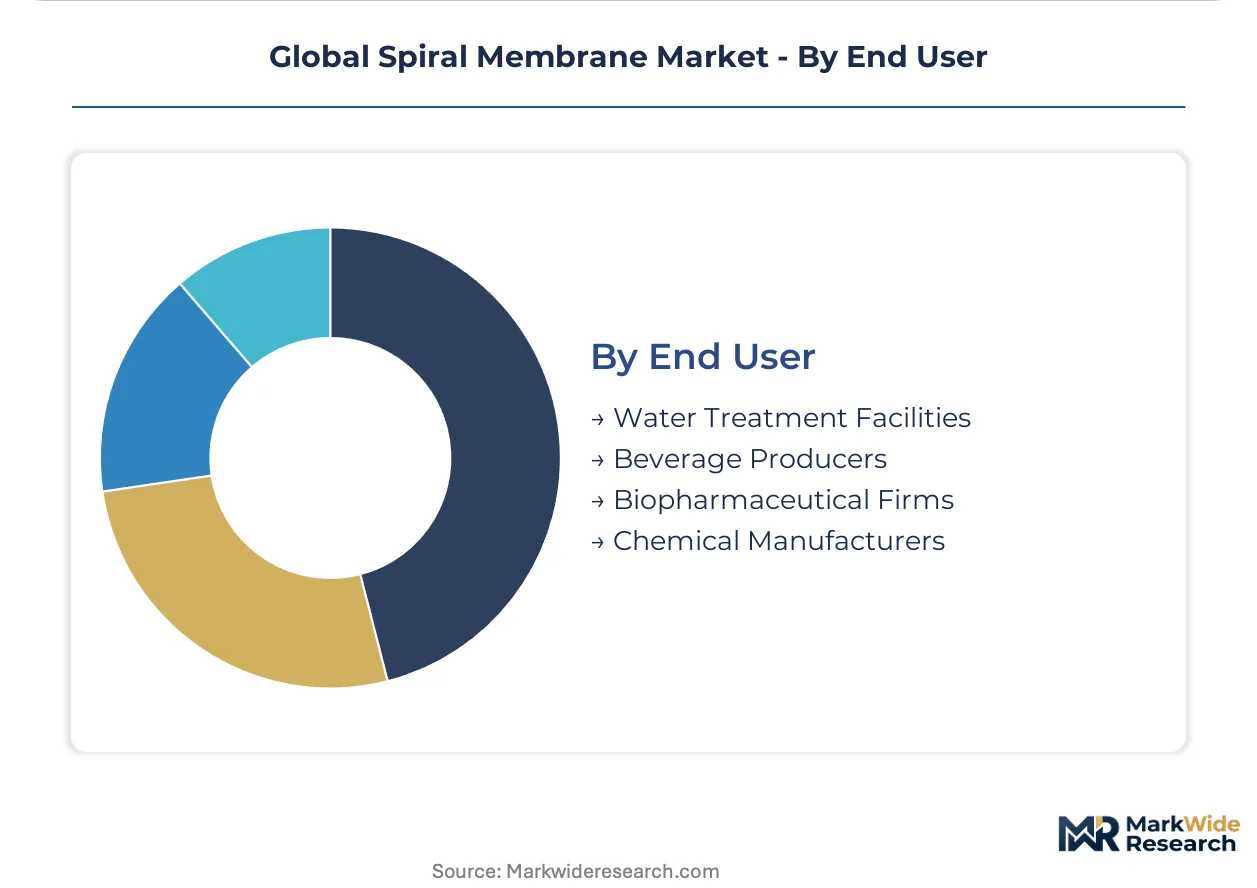
End User:
Customer type determines procurement channel structure, with engineering-procurement-construction firms consolidating supplier selection power in municipal concessions.
- Water Treatment Facilities:Municipal and industrial operators specify membrane elements within 20-30 year design-build-operate contracts. Acciona and Suez are assuming replacement risk in Saudi Arabia's Ras Al-Khair and Taweelah desalination plants, shifting procurement authority from plant owners to contractors.
- Beverage Producers:High-volume low-margin operations prioritize total cost of ownership over capital expenditure, accepting shorter element life for reduced cleaning chemical consumption. Mexican beverage bottlers are adopting standardized 4-inch brackish water elements across multiple plant locations to simplify inventory management.
- Biopharmaceutical Firms:Single-use system integration and process analytical technology requirements drive membrane qualification documentation intensity. Massachusetts-based cell therapy developers are qualifying alternate suppliers to reduce dependency on incumbent validated sources.
- Chemical Manufacturers:Zero liquid discharge mandates in India's Tamil Nadu textile belt and Gujarat chemical parks are creating first-time membrane adoption for evaporator feed pre-concentration. Central Pollution Control Board enforcement is accelerating procurement timelines.
Water treatment facilities represent the largest installed base. Chemical manufacturers are climbing the fastest on regulatory mandate timing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering-procurement-construction firms consolidate procurement authority in Saudi Arabia's megaproject pipeline, while municipal operators in the United States and Israel drive retrofit demand through regulatory tightening. Chemical manufacturers in India and Germany accelerate first-time membrane adoption under zero liquid discharge mandates.
Saudi Arabia
Saline Water Conversion Corporation procurement concentrates demand for high-rejection seawater elements at Jubail and Yanbu industrial complexes. The kingdom's Vision 2030 water security targets mandate membrane-based desalination expansion. Ras Al-Khair and Taweelah plants anchor the Eastern Province's installed capacity, with contractors assuming 10-15 year replacement risk.
United States
EPA effluent limitation guidelines tighten discharge standards for nitrogen and emerging contaminants across Texas and Louisiana chemical corridors. California's Title 22 framework legalizes direct potable reuse of membrane-treated municipal effluent. Permian Basin oilfield operators in West Texas pilot forward osmosis-thermal hybrid systems for produced water management.
Israel
The national water carrier specifies thin-film nanocomposite elements with boron rejection above 93 percent for single-pass WHO compliance. Government-backed desalination capacity targets drive procurement at Ashkelon and Sorek facilities. Tel Aviv-area technology developers pilot graphene oxide-polyamide active layers at 800-psi operating pressures.
India
Central Pollution Control Board zero liquid discharge mandates create first-time membrane adoption in Tamil Nadu textile dyeing and Gujarat tannery clusters. Enforcement timelines compress procurement cycles for evaporator feed pre-concentration systems. Surat and Ahmedabad chemical parks anchor western demand, while Tiruppur's knitwear belt drives southern installations.
Germany
REACH restriction proposals on per- and polyfluoroalkyl substances pressure membrane manufacturers to eliminate PTFE-based feed spacers from element construction. ECHA's 2023 restriction roadmap targets fluoropolymer persistence in industrial wastewater. North Rhine-Westphalia's chemical manufacturers specify polysulfone ultrafiltration for caustic recovery in textile mercerization operations.
Global Spiral Membrane Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement hierarchies, with consolidated upstream membrane sheet manufacturing in Japan and South Korea feeding fragmented element assembly in Europe and North America. The structure separates integrated chemistry-to-element producers from component assemblers dependent on imported roll goods. Two archetypes dominate: materials-science heritage firms with proprietary interfacial polymerization know-how, and system-integrators bundling membrane replacement into long-term service concessions. Competitive moves concentrate on backward integration into membrane sheet production and geographic expansion through engineering-procurement-construction partnerships.
Within the materials-science tier, DuPont and Toray Industries occupy positions reflecting integrated manufacturing capabilities from polymer chemistry through element assembly. Hydranautics exemplifies the specialist configuration focused on high-productivity low-energy municipal desalination configurations. These three anchors represent contrasting strategic postures: captive raw material control versus application-specific optimization versus project-based service integration. Their collective positioning shapes procurement channel dynamics across Saudi Arabia's megaprojects, Israel's national water carrier, and California's municipal reuse programs.
| Leading Market Players |
|---|
| Alfa Laval |
| Toray Industries Inc |
| DuPont |
| Hydranautics |
| LG Chem |
| Pentair |
| Koch Membrane Systems |
| Pall Corporation |
| SUEZ |
| Others |
Supply & Pricing Matrix
Polymer feedstock volatility tied to benzene derivatives markets compresses gross margins unevenly across material tiers, forcing three-tier pricing stratification across premium nanocomposite, standard polyamide, and economy cellulose acetate configurations while simultaneously driving element assemblers toward captive membrane sheet production in Japan and South Korea.
Pricing Analysis
Cost-plus contracts with benzene indexation dominate procurement for polyamide active layers and polysulfone substrates, linking element pricing to commodity chemical swings. Price differentiation separates FDA-validated biopharmaceutical grades from industrial wastewater specifications, with certification timelines adding 40-60 percent premiums. Cost compression in standard seawater elements is intensifying as Saudi procurement concentrates volume with engineering-procurement-construction firms. Municipal operators in Israel and Singapore show lowest price sensitivity due to energy-recovery device integration lowering lifecycle cost, while Indian textile processors face acute margin pressure under zero liquid discharge mandates.
Supply Chain Analysis
Upstream aromatic polyamide chemistry draws from m-phenylenediamine and trimesoyl chloride feedstocks concentrated in Japanese and South Korean integrated manufacturing clusters. Element assembly rests on imported roll goods from Toray Industries and LG Chem, creating single-source vulnerability for European and North American assemblers. Distribution runs through engineering-procurement-construction channels in Saudi Arabia and Australia, where Acciona and Suez bundle replacement risk into 10-15 year concessions. REACH restrictions on per- and polyfluoroalkyl substances are forcing spacer material transitions from PTFE to polypropylene alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spiral membrane incumbents face substitution pressure from ceramic and hollow-fiber configurations in high-fouling industrial streams, requiring defensive positioning around interfacial polymerization expertise and service contract integration to maintain pricing power.
For Market Incumbents: Insulate proprietary thin-film nanocomposite know-how through technician retention programs and yield-rate optimization at existing facilities. Secure backward integration into membrane sheet production to reduce dependency on Japanese and South Korean roll goods. Lock in 10-15 year replacement risk contracts with Saudi Saline Water Conversion Corporation and Australian municipal operators to freeze out ceramic membrane substitutes. For New Entrants and Emerging Players: India's Tamil Nadu textile belt and Gujarat chemical parks offer first-mover positioning under Central Pollution Control Board zero liquid discharge enforcement, where incumbent qualification timelines create procurement gaps. Target forward osmosis-thermal hybrid configurations for Permian Basin oilfield produced water, where energy intensity advantages over crystallizers justify premium positioning. Lead with evaporator feed pre-concentration pilot programs to bypass established reverse osmosis supplier relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors materials-science heritage firms with captive polymer chemistry capabilities over pure-play element assemblers. Long-term viability hinges on boron rejection specification tightening and anti-scaling chemical compatibility validation extending replacement cycles. Watch for Saline Water Conversion Corporation procurement standard revisions as the inflection signal for thin-film nanocomposite adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Sheet Production | Captive supply of interfacial polymerization capacity reduces roll goods dependency on Japanese and South Korean clusters. |
| Long-term Service Agreement Structuring | Replacement risk assumption by Acciona and Suez concentrates procurement authority with engineering-procurement-construction firms. |
| Thin-Film Nanocomposite R&D Investment | Zeolite and metal-organic framework incorporation enables 93 percent boron rejection for WHO single-pass compliance. |
| Zero Liquid Discharge System Integration | Forward osmosis-thermal hybridization targets Permian Basin and Alberta oilfield produced water at halved energy intensity. |
| PTFE Spacer Substitution Program | Polypropylene and polyethylene terephthalate alternatives address ECHA REACH restriction proposals on fluoropolymer persistence. |
Research Methodology
Operator-level perspectives from desalination plant engineers, municipal procurement officers, biopharmaceutical process validation specialists, and textile zero liquid discharge compliance managers anchored the qualitative base. Primary interviews triangulated with secondary validation from EPA effluent limitation guideline filings, Saudi Saline Water Conversion Corporation procurement documents, ECHA REACH restriction roadmaps, and India Central Pollution Control Board enforcement circulars. Bottom-up element demand modeling across reverse osmosis, nanofiltration, ultrafiltration, and microfiltration product categories reconciled with top-down membrane materials consumption estimates.
Scenario-bracketing framed low, base, and high cases across the projection horizon based on boron rejection specification evolution and anti-scaling chemical compatibility timelines. Segmentation dimensions modeled include filtration technology, active layer material chemistry, application context, and end-user procurement channel structure. CAGRs derived from installed capacity buildout in Saudi Arabia's megaproject pipeline, India's regulatory mandate timing, and California direct potable reuse framework adoption curves. Energy recovery device penetration rates and specific energy consumption compression below 2.5 kWh per cubic meter informed demand elasticity assumptions.
Practitioners should monitor polymer feedstock volatility indices, REACH fluoropolymer restriction finalization, and Saline Water Conversion Corporation tender standard revisions for early signals of pricing tier compression or supply chain reconfiguration. Quarterly review of benzene derivative futures, thin-film nanocomposite pilot results at Israel's national water carrier, and engineering-procurement-construction contract award flows is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Breather Membranes Market
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
PTFE Membrane Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Global Membrane Chromatography Market
Membrane Materials
Polymer Electrolyte Membrane Fuel Cells (Pemfcs) Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
North America below Grade Waterproofing Membranes Market
Membrane Materials
Global Waterproofing Membrane Market
Membrane Materials
Breathable Films and Membranes Market
Membrane Materials
Membrane Touch Switch Material Market
Membrane Materials
Global Bitumen Membranes Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
SBS Modified Bitumen Membrane Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market