
 Malted Wheat Flour Market | 2026-2036
Malted Wheat Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Malted Wheat Flour Market Outlook
Bakery end-use is decoupling from commodity flour sourcing as craft bakers seek enzymatically active ingredients for flavor depth and crust color. Muntons Malt leverages its vertically integrated malting infrastructure to secure supply continuity for European bakers. IREKS GmbH anchors its position through specialized malt formulations tailored to artisan dough rheology. Archer Daniels Midland competes on global grain procurement scale, extending its advantage into specialty malted wheat derivatives.
Malted wheat flour consists of wheat grains that undergo controlled germination, kilning, and milling to develop diastatic enzymes, soluble sugars, and Maillard-reactive compounds for browning and fermentation enhancement. The malting process typically achieves moisture levels of 42-46% during steeping and germination temperatures between 12-20°C to optimize alpha-amylase development. Specialty Flour commands premium positioning due to customized enzyme profiles for industrial bakers, while Whole Grain variants sustain volume leadership in health-oriented retail channels. Breakfast Cereals represent the fastest-growing end-use segment as malted wheat inclusions replace refined sweeteners in clean-label formulations.
EU Green Deal emissions targets and REACH chemical safety protocols are reshaping malting energy use and input material traceability across European production facilities. EFSA nutritional labeling requirements further influence how malted wheat flour positions itself in functional food claims. The US FDA and USDA maintain distinct standards for enzyme activity declarations and organic certification pathways that affect cross-border product registration. Stakeholders must monitor evolving carbon border adjustment mechanisms and regional clean-label definitions to align capacity investments with compliance trajectories.
Market Dynamics
EU Green Deal emissions mandates and REACH chemical safety protocols are forcing malting operations to reconfigure energy-intensive kilning processes while maintaining enzymatic activity standards for bakery customers.
Growth Catalysts
- Artisan bakery expansion:Craft bread and pastry segments in Germany and France are sourcing enzymatically active malted wheat flour for superior crust color and fermentation control.
- REACH chemical safety compliance:The EU's stricter input material traceability requirements are accelerating facility upgrades that improve batch consistency and quality certification.
- Breakfast cereal reformulation:Clean-label product developers are replacing refined sweeteners with malted wheat inclusions to achieve natural browning and flavor depth.
Market Restraints
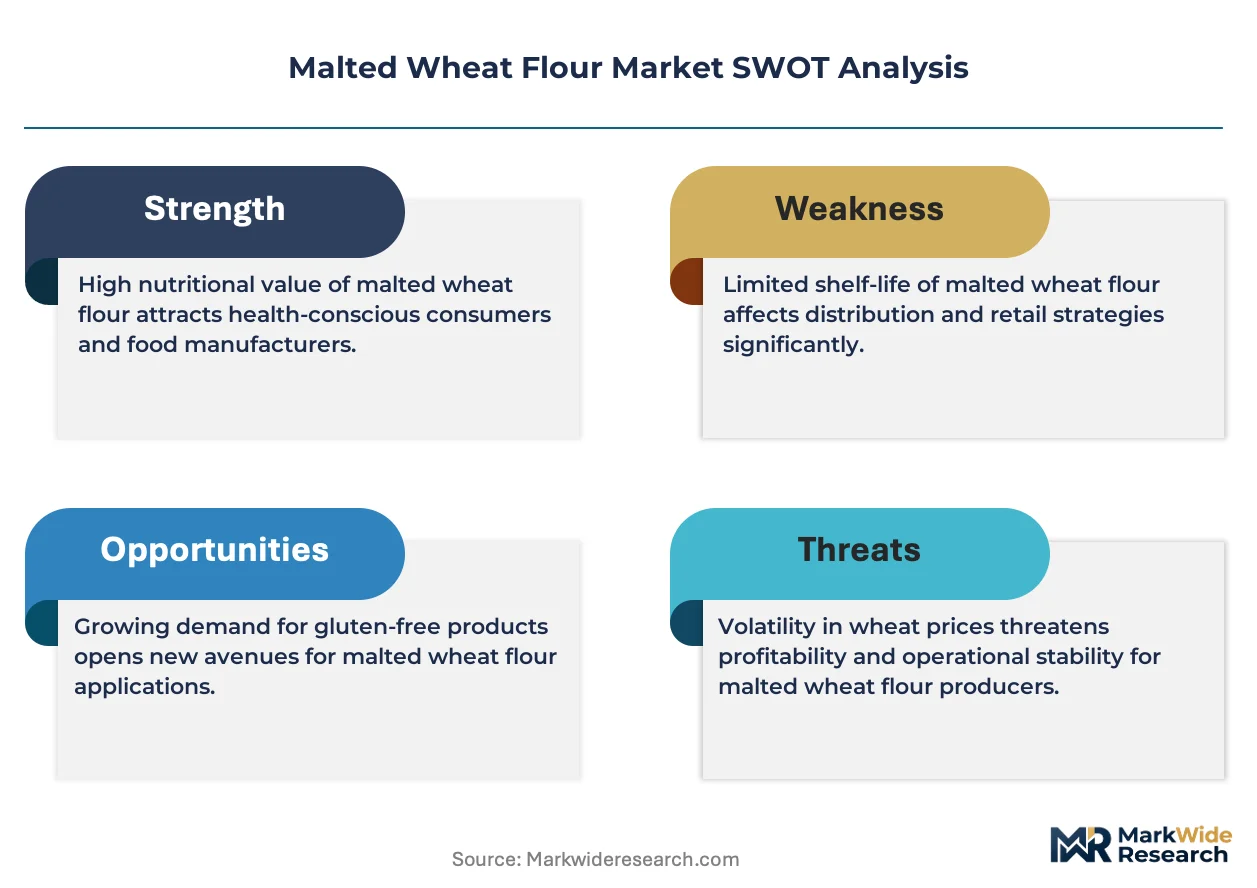
- Energy cost volatility:Natural gas and electricity price spikes in European malting regions compress margins on kilning-intensive specialty flour production.
- Supply concentration risk:Premium malted wheat germplasm and specialized malting infrastructure cluster in Germany, creating single-source dependencies for high-enzyme formulations.
- Technical substitution pressure:Commercial enzyme additives and modified wheat starches offer cheaper alternatives for industrial bakers prioritizing cost over artisan credentials.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Denmark exhibit rising craft bakery density but limited domestic malting capacity, creating import substitution potential.
- EU F-Gas Regulation phase-down:Refrigeration-dependent malting facilities must retrofit cooling systems, opening equipment upgrade contracts and process optimization services.
- Direct-to-baker distribution:Specialty millers are bypassing traditional ingredient distributors to capture margin and build formulation partnerships with artisan customers.
Industry Challenges
- Malting technician scarcity:Germination control and enzyme profiling require specialized expertise that vocational programs in Central Europe are not producing at replacement rates.
- Organic certification timelines:EFSA nutritional labeling and EU organic conversion periods delay product launches by 24-36 months for growers transitioning conventional wheat acreage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malted Wheat Flour Market |
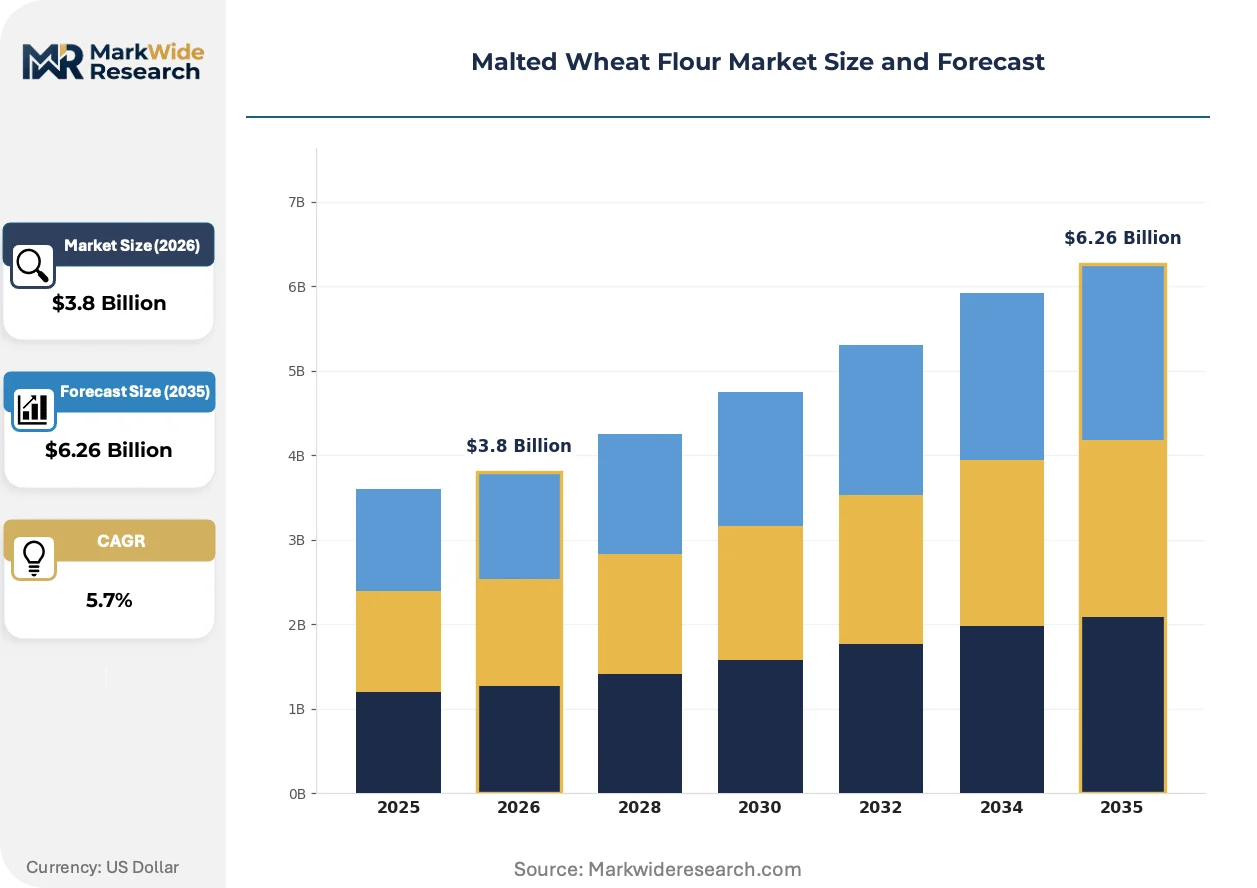
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Grain, White Flour, All-Purpose, Specialty Flour End Use: Bakery, Confectionery, Snacks, Breakfast Cereals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers Packaging Type: Bags, Boxes, Bulk Containers, Pouches |
| Companies Covered | Bairds Malt, Muntons Malt, Archer Daniels Midland, IREKS GmbH, Imperial Malts, Malteurop Group, Simpsons Malt, King Arthur Flour Company, Crisp Malting Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malted Wheat Flour Market Strategic Shifts
Controlled germination technologies and precision kilning systems are transforming how malted wheat flour develops diastatic enzymes and Maillard-reactive compounds for targeted bakery applications.
Precision kilning with real-time moisture and temperature feedback is expanding into high-value specialty flour production. Artisan and industrial bakers in Germany and France are adopting these enzyme-standardized ingredients to reduce batch-to-batch fermentation variation. The technology is expanding into mid-tier bakery segments previously dependent on commodity flour blending.
REACH chemical safety protocols and the EU F-Gas Regulation are tightening input traceability and refrigeration emissions standards across malting operations. Facilities must document germination water sources, steeping additives, and cooling system refrigerant types for compliance audits. Small-scale maltsters in Belgium and the Netherlands face disproportionate compliance costs relative to integrated competitors with dedicated regulatory staff.
Clean-label procurement priorities are compressing switching cycles between ingredient suppliers as bakery R&D teams reformulate around reduced additive declarations. Industrial breakfast cereal manufacturers are displacing malt extract syrups with whole-milled malted wheat inclusions to achieve shorter ingredient lists. This pattern is most visible in Scandinavian retail channels where consumer scrutiny of E-number additives runs highest.
Malted Wheat Flour Market Segmentation
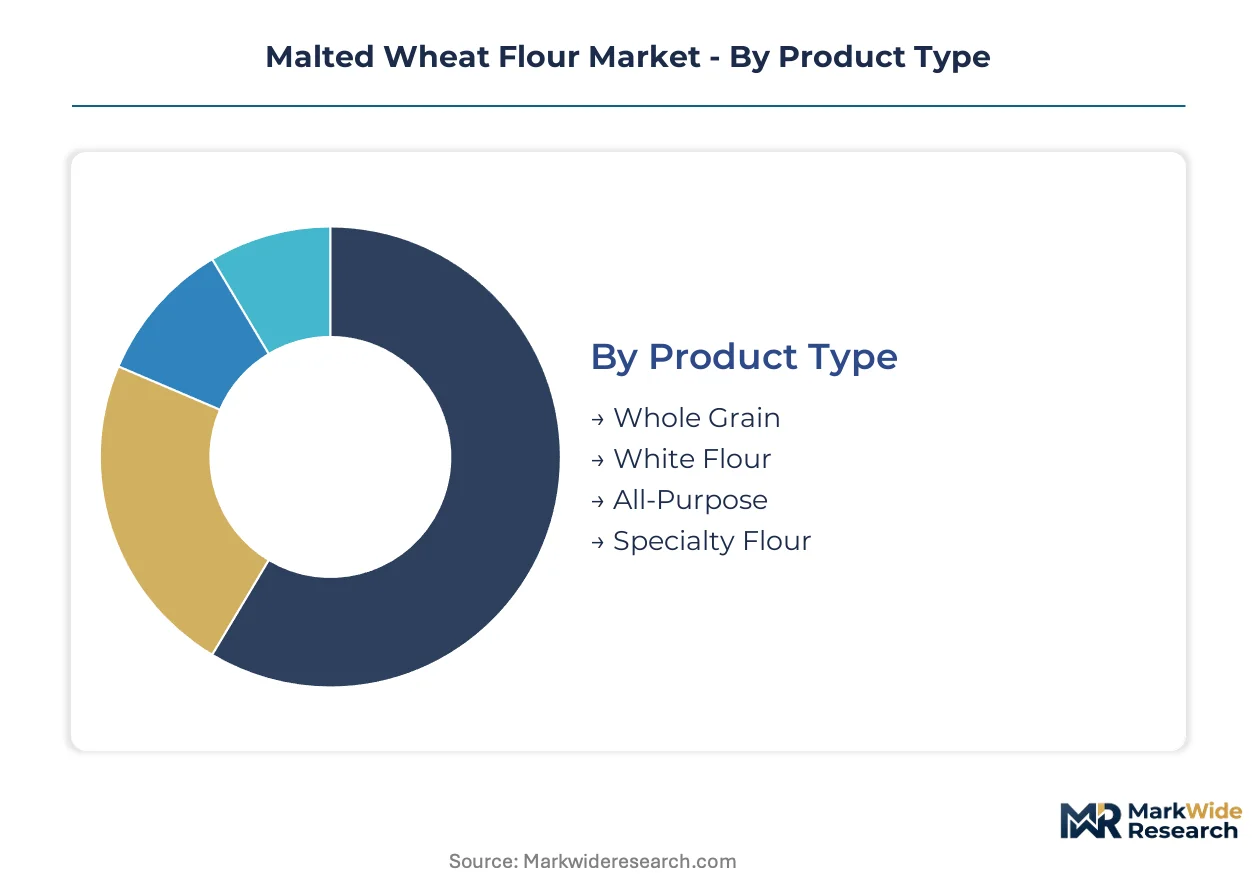
Malted wheat flour segments diverge sharply between commodity volume plays and enzyme-standardized premium grades. Bakery procurement teams now specify alpha-amylase activity levels rather than generic flour categories, forcing suppliers to align product portfolios with functional performance tiers.
Product Type:
Volume leadership sits with standard-milled grades, while enzyme-customized variants capture expanding premium margins.
- Specialty Flour:Customized diastatic enzyme profiles target industrial bakers requiring precise fermentation control and Maillard browning predictability. German craft bakeries in Munich and Berlin are specifying 200-300 Windisch-Kolbach units for sourdough applications, paying premiums for batch-certified activity levels.
- Whole Grain:Retains bran and germ layers through controlled germination, delivering fiber retention and deeper flavor compounds for health-positioned retail channels. Scandinavian clean-label cereal manufacturers in Stockholm and Copenhagen are displacing refined malt extracts with whole-milled inclusions to shorten ingredient declarations.
- White Flour:Standard enzyme activity for cost-sensitive industrial bakery applications.
- All-Purpose:Mid-tier positioning bridging artisan and commodity procurement budgets.
Today's leader: Whole Grain. Tomorrow's challenger: Specialty Flour.
End Use:
Application demand clusters around crust-color engineering and natural sweetener replacement.
- Breakfast Cereals:Malted wheat inclusions replace refined syrups and caramel colorings in clean-label reformulations. Swiss and Danish cereal producers are advancing fastest here, leveraging EFSA nutritional labeling flexibility for reduced-additive positioning.
- Bakery:Artisan bread and viennoiserie segments in France and Germany specify kilning profiles for targeted crust development and fermentation timing.
- Confectionery:Limited penetration in chocolate and praline applications due to moisture sensitivity constraints.
- Snacks:Emerging use in extruded savory applications for flavor depth without artificial enhancers.
Breakfast Cereals are expanding most quickly. Bakery retains volume concentration.
Distribution Channel:
Procurement patterns are shifting from commodity distributors toward direct technical partnerships.
- Specialty Stores:Artisan bakers in Hamburg and Lyon source small-batch malted wheat flour with documented steeping water provenance and germination temperature logs. These buyers prioritize traceability documentation over price elasticity.
- Wholesalers:Industrial bakery conglomerates in Belgium and the Netherlands rely on volume contracting for standardized enzyme activity ranges, with REACH compliance documentation bundled into supply agreements.
- Online Retail:Direct-to-baker platforms are gaining share among micro-bakeries seeking formulation support alongside ingredient supply.
- Supermarkets:Retail-packaged malted wheat flour for home bakers remains a marginal category.
Wholesalers dominate transaction volume. Specialty Stores are climbing fastest in value per kilogram.
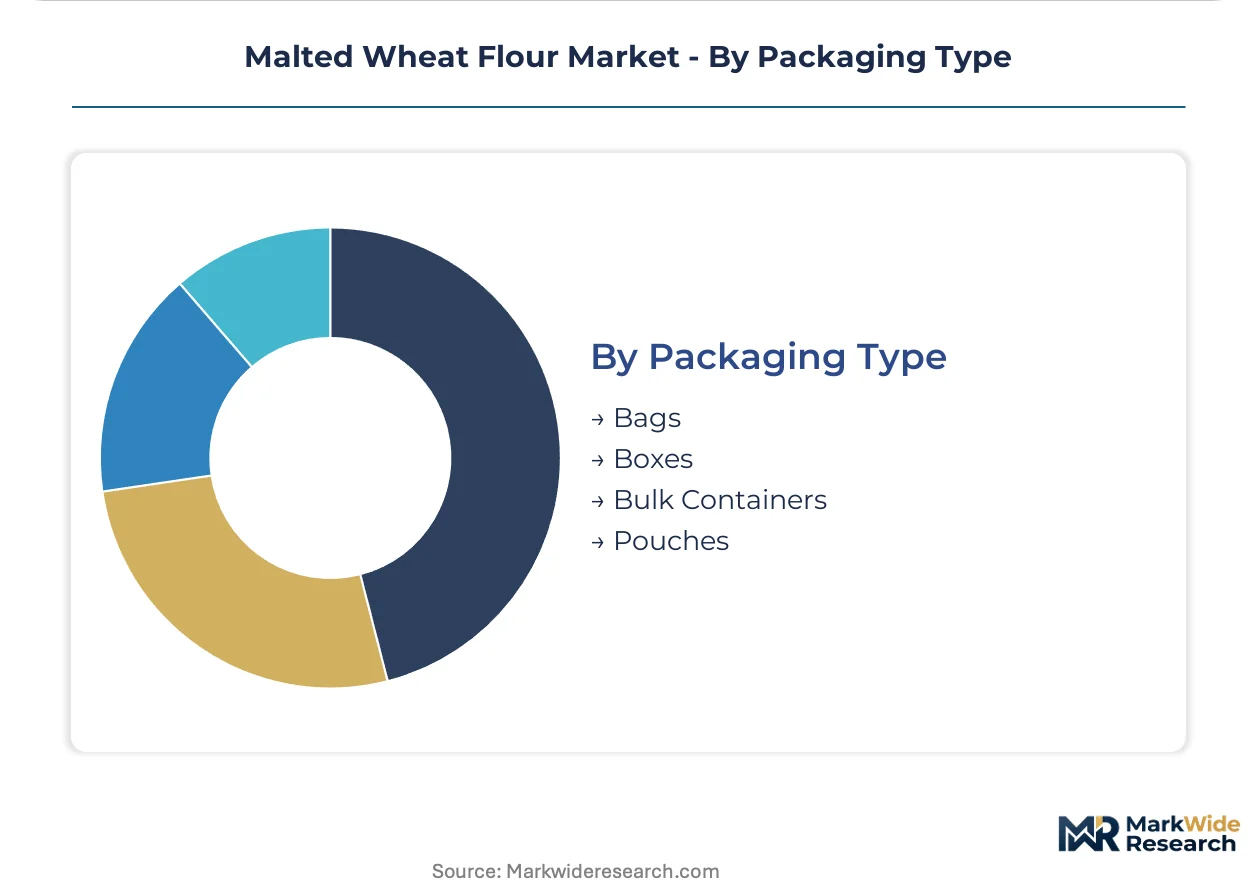
Packaging Type:
Packaging selection tracks batch size and shelf-life requirements across customer tiers.
- Bulk Containers:500kg totes serve industrial mills and cereal manufacturers with rapid throughput and climate-controlled storage infrastructure.
- Bags:25kg multi-wall paper sacks remain standard for mid-size bakery operations.
- Pouches:Retail-format packaging for specialty store and online channels.
- Boxes:Protective secondary packaging for export shipments requiring extended transit stability.
Bulk Containers anchor industrial procurement. Pouches are gaining share in direct-to-artist distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing malting capacity toward jurisdictions where REACH compliance costs and F-Gas retrofitting timelines create competitive gaps. German facilities absorb disproportionate regulatory burden while Belgian and Dutch operators exploit proximity advantages.
Germany
Artisan bakery density in Munich and Berlin sustains demand for enzyme-standardized specialty grades. EFSA nutritional labeling requirements and EU Green Deal emissions mandates force kilning facility upgrades across Bavaria and North Rhine-Westphalia. The Hamburg industrial corridor concentrates malting infrastructure serving both domestic craft bakers and export cereal manufacturers.
France
Viennoiserie and traditional bread segments in Paris and Lyon specify kilning profiles for crust-color engineering. REACH chemical safety protocols tighten input material traceability for malting operations in the Hauts-de-France grain belt. The Grand Est region hosts expanding malting capacity targeting clean-label breakfast cereal exporters.
Belgium
Mid-size bakery conglomerates in Flanders procure standardized enzyme activity ranges through volume contracting. F-Gas Regulation phase-down deadlines accelerate refrigeration system retrofits at germination facilities near Antwerp. Brussels-based distributors bundle REACH compliance documentation into supply agreements for cross-border industrial buyers.
Netherlands
Rotterdam port logistics enable import-dependent malting operations serving Scandinavian cereal manufacturers. EU Green Deal carbon border adjustment mechanisms influence sourcing decisions for wheat germplasm entering Dutch processing facilities. The Eindhoven region exhibits emerging craft bakery density with limited domestic malting capacity.
Sweden
Clean-label cereal manufacturers in Stockholm displace refined malt extracts with whole-milled inclusions to shorten ingredient declarations. EFSA flexibility on reduced-additive positioning supports reformulation investments by Nordic retail brands. Malmö craft bakeries source enzyme-active supplies through direct import channels from German specialty millers.
Malted Wheat Flour Market Competitive Environment
Capacity expansion dominates the current landscape as integrated maltsters retrofit kilning systems for F-Gas compliance and precision enzyme control. The vendor base clusters around three tiers: large-scale grain processors with captive malting divisions, specialized European maltsters with artisan formulation expertise, and regional millers serving direct-to-baker distribution channels. Strategic archetypes include vertically integrated agricultural conglomerates, precision-kilning technology specialists, and craft-focused specialty formulators. M&A activity and direct-to-baker distribution partnerships represent the dominant competitive moves.
Among UK-based maltsters, Bairds Malt and Simpsons Malt occupy positions within the specialty tier, leveraging proximity to craft bakery clusters. Muntons Malt exemplifies the integrated archetype with vertically controlled malting infrastructure. IREKS GmbH anchors the precision-formulation segment through German technical expertise. Archer Daniels Midland represents scale-driven agricultural processing with upstream grain procurement advantages.
| Leading Market Players |
|---|
| Bairds Malt |
| Muntons Malt |
| Archer Daniels Midland |
| IREKS GmbH |
| Imperial Malts |
| Malteurop Group |
| Simpsons Malt |
| King Arthur Flour Company |
| Crisp Malting Group |
| Others |
Value Chain & Pricing Dynamics
Artisan bakery procurement teams in Germany and France are demanding documented steeping water provenance and batch-certified enzyme activity levels, forcing malting operations to absorb certification and traceability costs that compress margins on commodity-grade output while widening premiums for specialty flour.
Pricing Analysis
Distributor margins in the malted wheat flour channel typically capture 12-18% for standard grades but compress to 8-12% for direct-to-baker specialty supply. Three-tier pricing structure across premium, standard, and economy levels reflects enzyme activity certification, organic conversion status, and kilning precision. Pricing pressure stems from energy cost volatility in European natural gas markets hitting kilning-intensive production. Industrial bakery conglomerates in Belgium exhibit highest price sensitivity, while Hamburg craft bakers prioritize traceability documentation over cost elasticity.
Supply Chain Analysis
Freight cost differentials between Rotterdam port entry and inland German malting facilities create sourcing advantages for Dutch import-dependent operations serving Scandinavian cereal manufacturers. Supply concentrates in Germany, Belgium, and the Netherlands, with premium germplasm and specialized kilning infrastructure clustering in Bavaria and North Rhine-Westphalia. Raw material flows draw from French wheat belts, German malting barley regions, and Black Sea grain corridors. Single-source vulnerability runs through German high-enzyme formulation capacity. Distribution runs through specialty millers bypassing traditional ingredient distributors to capture margin and build direct formulation partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The malted wheat flour market reads as a late-cycle quality story where artisan bakery specification drift toward enzyme-standardized, traceability-documented ingredients rewards suppliers with precision-kilning capabilities and penalizes commodity-grade volume players.
For Market Incumbents: Deepen backward integration into wheat germplasm selection and steeping water source control to defend against commercial enzyme additive substitution. Prioritize F-Gas Regulation compliance retrofitting at German facilities to maintain access to EU craft bakery demand. Lock in long-term supply agreements with Scandinavian cereal manufacturers before import-dependent Dutch competitors capture Nordic clean-label reformulation contracts. For New Entrants and Emerging Players: Direct-to-baker digital platforms offer the lowest-friction entry path for micro-maltsters seeking to bypass established distributor networks. Target Sweden and Denmark where craft bakery density rises but domestic malting capacity remains limited. Lead with formulation partnership services bundled with ingredient supply to differentiate from commodity flour traders. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-kilning technology specialists holding artisan formulation expertise and REACH compliance documentation capabilities. Long-term viability favors suppliers with captive germplasm access and energy-efficient kilning infrastructure positioned for EU Green Deal emissions trajectory. Watch for inflection signals in organic certification conversion timelines as EFSA nutritional labeling flexibility creates premium positioning windows.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Kilning System Retrofit | Enables F-Gas Regulation compliance while maintaining enzyme activity standards for German craft bakers. |
| Direct-to-Baker Distribution Launch | Captures margin compression from traditional ingredient distributors in Hamburg and Lyon artisan clusters. |
| Organic Certification Investment | Positions for EFSA nutritional labeling flexibility driving Scandinavian cereal manufacturer procurement. |
| Backward Integration into Wheat Germplasm | Secures supply continuity against Black Sea grain corridor volatility for high-enzyme specialty grades. |
| Formulation Partnership Program | Builds switching costs with micro-bakeries through technical support beyond commodity flour supply. |
Study Parameters
Multiple input streams — malting facility engineering assessments, artisan bakery procurement pattern analysis, and regulatory compliance documentation review — were reconciled through structured primary interviews with plant managers at European malting operations, procurement leads at Belgian industrial bakery conglomerates, and technical R&D directors at specialty flour formulators. Secondary validation incorporated EU trade statistics, ECHA REACH registration databases, EFSA nutritional labeling guidance documents, and customs records for wheat germplasm flows. Bottom-up volume modeling and top-down value reconciliation triangulated segment-level outputs.
Historical consumption patterns were cross-referenced against expert panel input from maltsters and bakery R&D directors to anchor projection assumptions across the analysis window. Segmentation modeling incorporated product type tiers, end-use application clusters, distribution channel structures, and regional regulatory framework variations. CAGRs were derived from trend extrapolation moderated by capacity constraint analysis and substitution elasticity estimates for commercial enzyme additives.
The model assumes a particular technology adoption path for precision kilning with real-time moisture feedback; alternative pathways for germination control automation would alter the outlook for batch consistency premiums and facility upgrade timelines. Forecasts reflect assumptions about EU Green Deal implementation pace, F-Gas Regulation enforcement intensity, and artisan bakery specification drift toward documented traceability. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Roll-Dried Starch Market
Ingredients
Apple Extract Market
Ingredients
Egg Membrane Powder Market
Ingredients
India Protein Market
Ingredients
Bangladesh Mustard Oil Market
Ingredients
Freeze-Dried Vegetable Powder Market
Ingredients
Fermented Ingredients Market
Ingredients
Potato & Yam Derivatives Market
Ingredients
Textured Milk Protein Market
Ingredients
Liquid Egg Market
Ingredients
Europe Potato Protein Market
Ingredients
Hydrolyzed Vegetable Protein Market
Ingredients
Pine Needle Oil Market
Ingredients
North America Alcohol Ingredients Market
Ingredients
Ximenia Oil Market
Ingredients
Asia-Pacific Yeast Market