
 Almond Ingredients Market | 2026-2036
Almond Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Almond Ingredients Market Analysis
California's Central Valley is narrowing the gap between raw nut supply and value-added ingredient output as processors expand flour and butter capacity. Blue Diamond Growers leverages its cooperative structure to control upstream orchards and downstream processing simultaneously. The Wonderful Company anchors its position through integrated branding that spans retail almond milk and bulk ingredient sales. Olam Food Ingredients competes by operating multi-origin sourcing networks that extend beyond California into Australia and Spain.
Almond ingredients encompass processed derivatives including flour, butter, milk, and sugar obtained by milling, pressing, or blanching Prunus dulcis kernels, typically requiring protein content above 20% for baking applications and fat profiles near 50% for confectionery binding. These ingredients serve primarily as functional replacements for wheat flour, dairy fat, and refined sugar in clean-label and allergen-managed formulations. Almond flour occupies the largest margin pool among product types due to its premium positioning in gluten-free and keto-aligned portfolios, while almond milk experiences the fastest volume expansion as dairy alternatives command expanded shelf space. Within applications, baked goods sustain the most mature demand base, whereas confectionery represents an emerging growth vector as chocolatiers seek nut-based texture modifiers.
FDA allergen labeling requirements under FALCPA and subsequent FSMA traceability mandates shape product specifications and lot-tracking investments for US-market suppliers. EFSA's ongoing evaluations of acrylamide formation in roasted nut products influence thermal processing standards across European export channels. California's State Water Resources Control Board irrigation regulations constrain orchard expansion, directly tightening raw material availability for ingredient processors. Stakeholders must monitor water rights adjudication and pollinator health policy as these factors determine long-term supply elasticity more than near-term price signals.
Market Dynamics
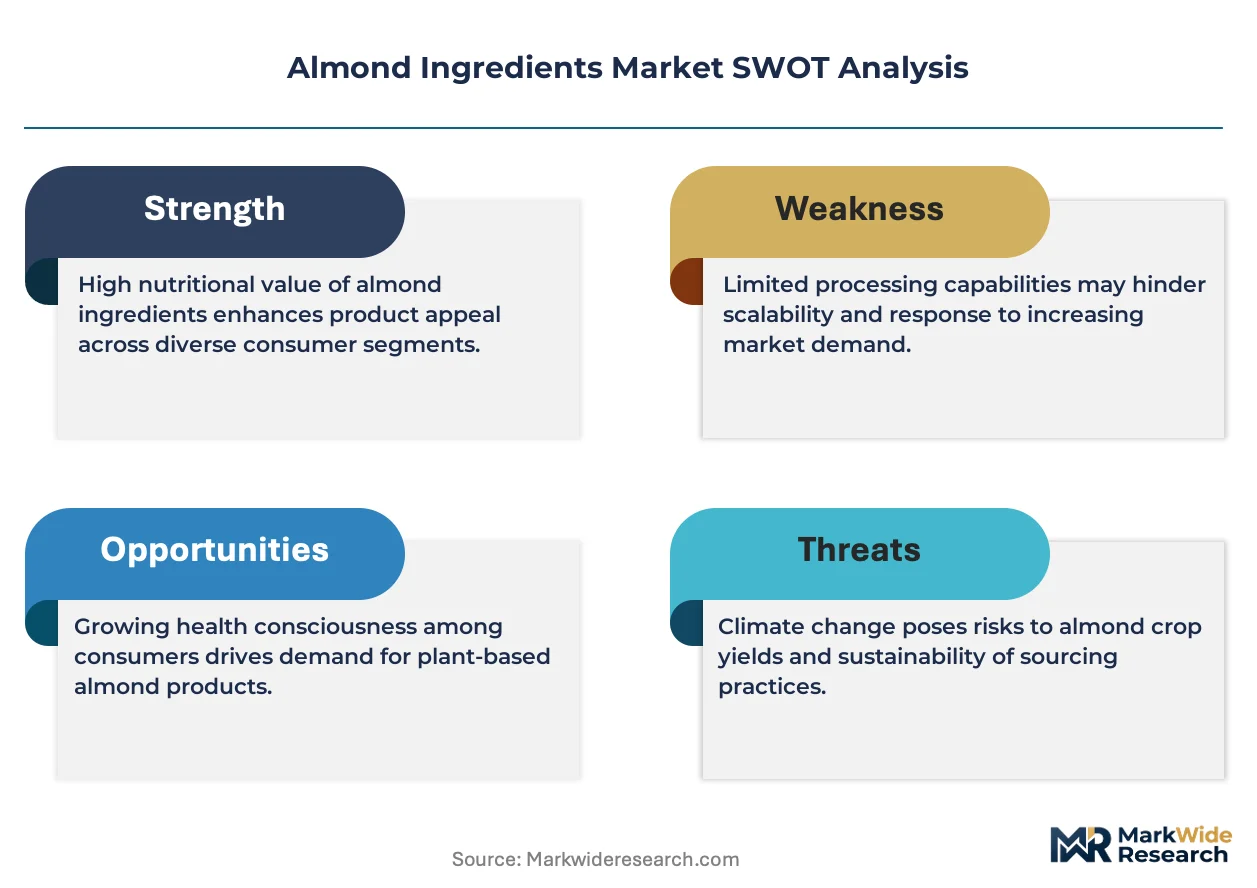
California's State Water Resources Control Board irrigation regulations are tightening raw almond supply faster than processors can expand value-added capacity, compressing the margin window between orchard gate and ingredient output. This regulatory constraint on water rights is the dominant structural force reshaping competitive positioning across the entire value chain.
Growth Catalysts
- Plant-based dairy reformulation:Food manufacturers are accelerating clean-label portfolio redesigns, pulling almond milk and butter into mainstream retail formulations as functional replacements for dairy fat.
- EFSA allergen labeling mandates:The EU's updated traceability requirements for tree nuts across packaged goods are forcing ingredient standardization that favors established processors with lot-tracking infrastructure.
- Keto and gluten-free portfolio expansion:Almond flour's premium positioning in specialty baking applications is capturing expanded shelf space as bakery chains reformulate around low-carbohydrate positioning.
Market Restraints
- Water rights adjudication:California's Central Valley irrigation constraints directly limit orchard expansion, tightening raw material availability for ingredient processors regardless of downstream demand signals.
- Pollinator dependency:Commercial bee colony health volatility creates supply elasticity risk that no single processor can hedge through contracting alone.
- Oat milk substitution:Oat-based dairy alternatives are capturing price-sensitive shelf space in mass retail, pressuring almond milk's volume expansion trajectory in conventional channels.
Strategic Opportunities
- Australia multi-origin sourcing:Olam Food Ingredients' established processing networks in Australian growing regions offer template for geographic diversification beyond California water stress.
- Confectionery texture modification:Chocolatiers are actively seeking nut-based binding agents as clean-label replacements for synthetic emulsifiers in premium chocolate formulations.
- Spain Mediterranean expansion:Spanish almond growing regions offer underdeveloped processing infrastructure that integrated operators can capture for EU market proximity.
Industry Challenges
- FSMA traceability compliance:FDA lot-tracking mandates require capital-intensive serialization infrastructure that mid-scale processors must deploy to maintain US market access.
- Acrylamide thermal processing standards:EFSA evaluations of roasted nut products are forcing reformulation of roasting protocols without standardized industry testing methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Almond Ingredients Market |
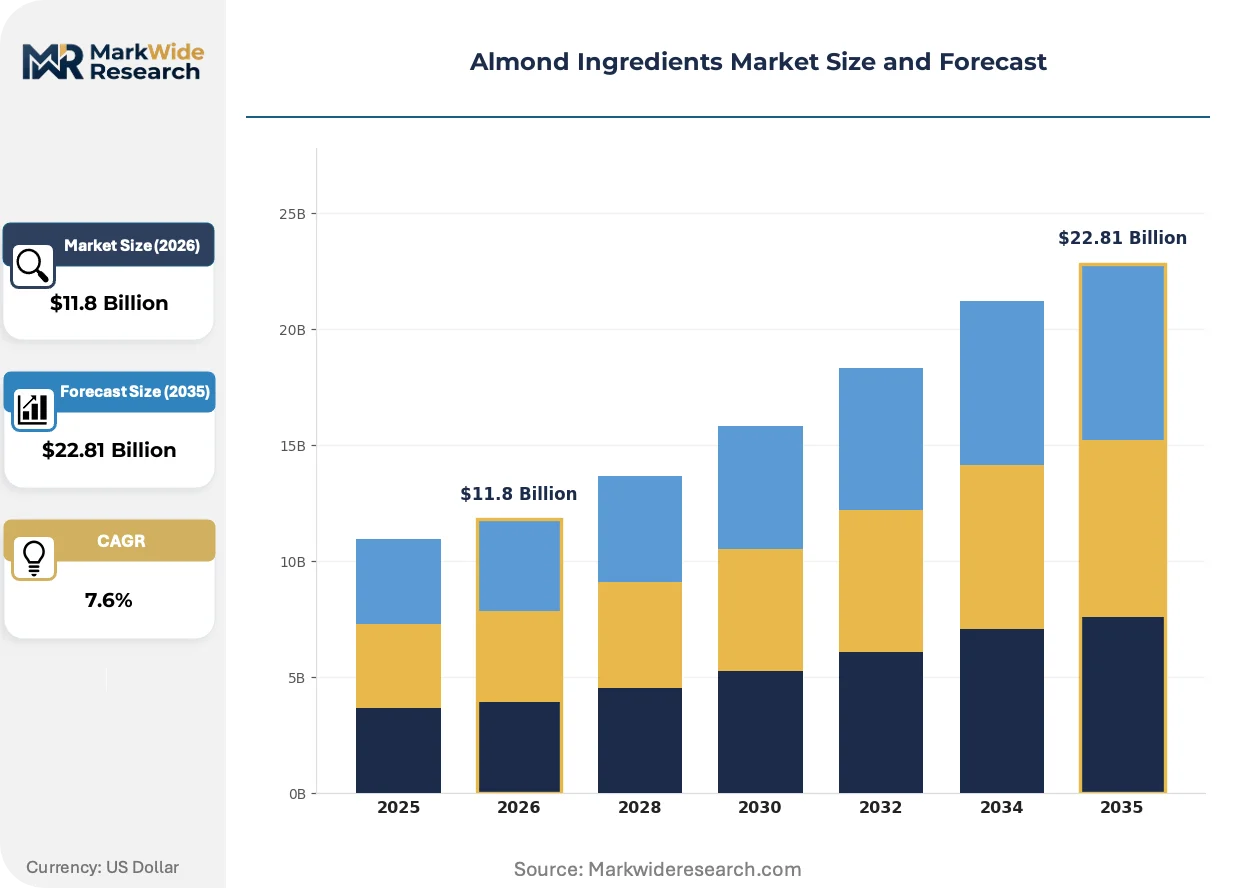
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $22.81 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Flour, Almond Butter, Almond Milk, Almond Sugar Application: Baked Goods, Dairy Alternatives, Snacks, Confectionery Customer Type: Food Manufacturers, Retailers, Wholesalers, Food Service Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Blue Diamond Growers, The Wonderful Company, Olam Food Ingredients, John B. Sanfilippo & Son, ADM, Barry Callebaut Group, Borges Agricultural & Industrial Nuts, Harris Woolf California Almonds, Treehouse California Almonds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Almond Ingredients Market Emerging Trajectories
Digital quality assurance systems are virtualizing traditional sensory evaluation protocols across almond processing facilities, compressing the gap between harvest intake and finished ingredient certification. This technological shift is redrawing capability requirements for mid-tier processors.
Hyperspectral imaging technology deployed at receiving stations is virtualizing manual kernel defect sorting that previously required skilled labor pools. Large cooperatives are adopting these systems fastest, compressing the quality assurance timeline from days to hours while reducing dependence on seasonal sorting expertise. The structural consequence is a widening capability gap between automated and manual processing operations.
EFSA's ongoing acrylamide formation evaluations are forcing thermal processing standardization across European export channels. Roasted almond ingredient suppliers must now document precise time-temperature profiles to maintain market access, with smaller processors facing compliance timeline compression. The confectionery segment is responding by shifting toward blanched rather than roasted ingredient specifications where formulation flexibility permits.
Buyer concentration among multinational food manufacturers is compressing supplier qualification cycles and unbundling traditional full-service relationships. Procurement teams at major bakery and dairy-alternative brands are now separating ingredient supply from technical formulation support, forcing processors to compete on specification compliance alone. This pattern is most visible in North American private-label manufacturing where retailer consolidation has reduced the number of qualified vendor slots.
Almond Ingredients Market Segmentation
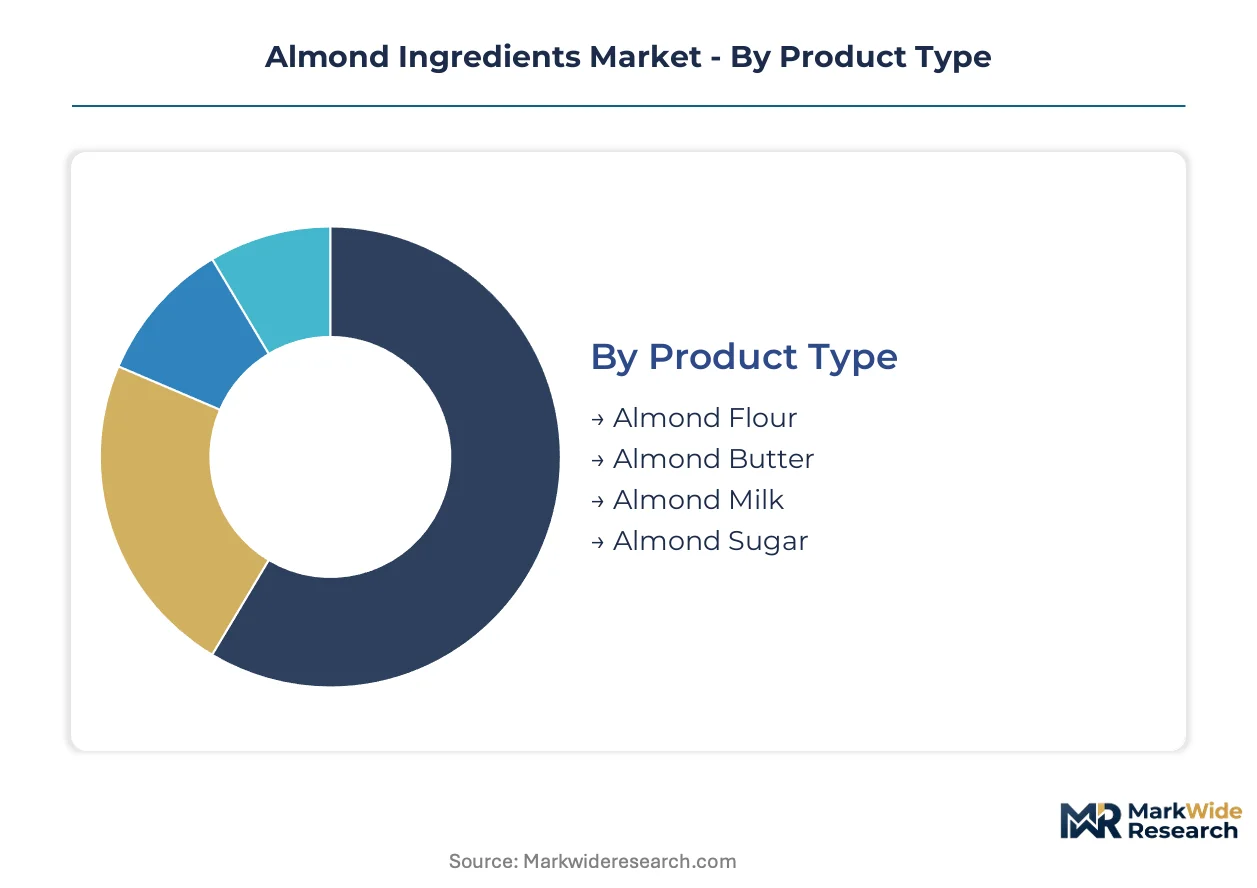
Almond ingredient specifications vary sharply across end-use applications, from protein thresholds in baking to fat profiles in confectionery binding. Processors configure milling and pressing equipment differently for each segment, creating specialized production lines that resist rapid switching.
Product Type:
The use-case spectrum spans gluten-free flour substitution, dairy fat replacement, beverage emulsion, and clean-label sweetening.
- Almond Flour:Milled from blanched kernels with protein content above 20%, this ingredient serves keto-aligned and gluten-free bakery formulations. California processors command premium positioning through controlled particle size distribution.
- Almond Butter:Produced via hydraulic pressing of roasted kernels to achieve fat profiles near 50%, this paste functions as confectionery binding agents and spreadable alternatives to dairy fat. Clean-label portfolio redesigns in North American retail chains are accelerating volume uptake.
- Almond Milk:Homogenized emulsion of ground kernels and water, fortified for beverage applications. Oat-based alternatives are capturing price-sensitive shelf space in conventional retail channels.
- Almond Sugar:Granulated or powdered form derived from milled kernels with reduced oil content, serving as refined sugar replacement in allergen-managed formulations.
Established volume favors almond flour; emerging adoption favors almond butter.
Application:
Cost tier differentiation separates commodity-scale bakery procurement from premium confectionery ingredient sourcing.
- Baked Goods:The most mature demand base, utilizing almond flour for gluten-free bread, pastry, and cake formulations. Bakery chains reformulating around low-carbohydrate positioning are sustaining steady offtake.
- Dairy Alternatives:Almond milk and butter serve as functional replacements for dairy fat in plant-based beverage and spread categories. This segment is expanding most quickly as food manufacturers accelerate clean-label portfolio redesigns.
- Snacks:Roasted and flavored kernel products, plus almond butter as dip and bar ingredients. EFSA acrylamide evaluations are forcing thermal processing protocol adjustments.
- Confectionery:Chocolatiers seek nut-based texture modifiers as clean-label replacements for synthetic emulsifiers. Blanched rather than roasted specifications are gaining preference where formulation flexibility permits.
Margin concentration sits with confectionery; volume scale sits with baked goods.
Customer Type:
Procurement sophistication varies from multinational food manufacturers with serialization requirements to fragmented food service operators.
- Food Manufacturers:Large-scale bakery, dairy-alternative, and confectionery producers with FSMA lot-tracking mandates. Buyer concentration is compressing supplier qualification cycles and unbundling traditional full-service relationships.
- Retailers:Private-label brands and specialty grocers sourcing packaged almond ingredients. Consolidation among North American retailers has reduced qualified vendor slots.
- Wholesalers:Intermediate distributors serving smaller manufacturers and regional food service. These intermediaries face margin pressure from direct sourcing trends.
- Food Service:Restaurants, cafes, and institutional kitchens purchasing bulk butter and milk for menu applications.
Compliance burden weighs heaviest on food manufacturers; price sensitivity concentrates among food service.
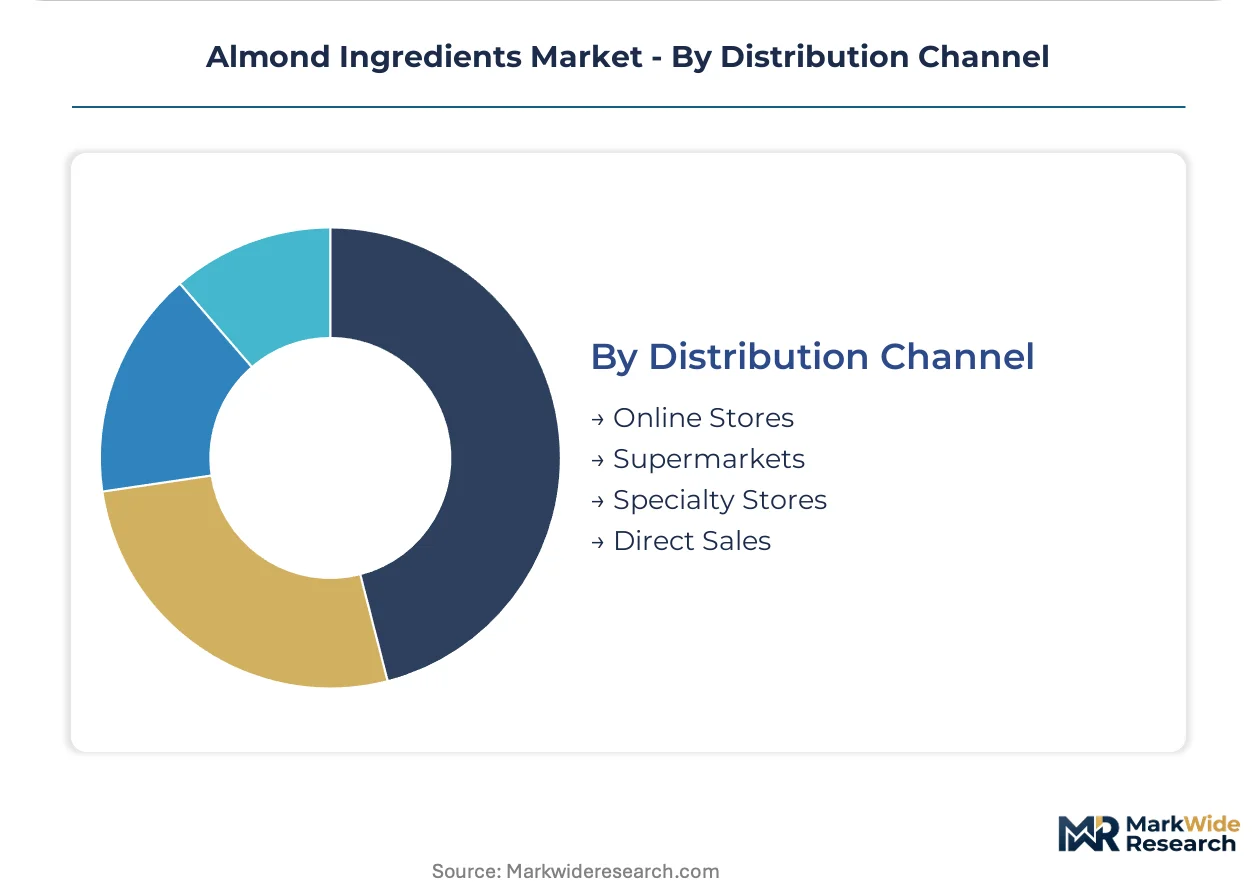
Distribution Channel:
Supply chain configuration separates direct relationships with large processors from fragmented retail and specialty store networks.
- Online Stores:E-commerce platforms serving specialty diet consumers and small-scale food manufacturers. Digital quality assurance systems are virtualizing traditional sensory evaluation protocols for remote verification.
- Supermarkets:Mass retail shelf space for almond milk and packaged flour. Oat milk substitution is pressuring almond milk's expansion trajectory in this channel.
- Specialty Stores:Health food and gourmet retailers focusing on organic and premium-positioned ingredients.
- Direct Sales:Processor-to-manufacturer relationships bypassing intermediaries, typical for large food manufacturers with volume commitments.
Scale economies favor direct sales; market access breadth favors supermarket placement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA allergen labeling requirements under FALCPA anchor the United States as the regulatory benchmark for almond ingredient traceability standards worldwide. California's Central Valley concentrates over 80% of global almond processing capacity, creating supply-side dependencies that ripple through international markets. Water rights adjudication and pollinator health policy now determine long-term supply elasticity more than near-term price signals.
United States
Plant-based dairy reformulation by major food manufacturers pulls almond milk and butter into mainstream retail portfolios. FSMA traceability mandates require capital-intensive serialization infrastructure for lot-tracking compliance. California's Central Valley processors expand flour and butter capacity to narrow the gap between raw nut supply and value-added ingredient output.
Spain
Mediterranean almond growing regions offer underdeveloped processing infrastructure for EU market proximity expansion. EFSA allergen labeling rules under updated guidance mandate clearer traceability for tree nuts across packaged goods. Andalusian and Valencia growing clusters present acquisition targets for integrated operators seeking geographic diversification beyond California water stress.
Australia
Multi-origin sourcing networks extend processing capacity into southern hemisphere growing regions with irrigation advantages. The country's national food safety regulator enforces strict import parity standards for nut-based ingredients. Riverina and Sunraysia processing hubs attract capital deployment from operators hedging California water rights constraints.
Germany
Industrial bakery and confectionery manufacturers drive demand for standardized almond flour with controlled particle size distribution. EFSA acrylamide formation evaluations force thermal processing protocol documentation for roasted ingredient exports. Hamburg and Frankfurt logistics corridors consolidate EU distribution for bulk ingredient shipments.
India
Specialty diet consumers and small-scale food manufacturers expand procurement through e-commerce platforms. FSSAI labeling requirements for imported nut ingredients create compliance barriers for unstandardized suppliers. Maharashtra and Gujarat processing clusters develop domestic capacity for allergen-managed bakery formulations.
Almond Ingredients Market Vendor Landscape
Capability concentration sits with cooperative-structured operators controlling upstream orchards and downstream processing simultaneously; scale advantage sits with diversified agricultural conglomerates with multi-origin sourcing networks. The vendor base organizes around three strategic archetypes: integrated cooperatives with captive supply, multi-national traders with geographic diversification, and specialized processors with technical formulation support. Competitive moves center on backward integration into orchard assets and capacity expansion in value-added flour and butter production.
Within the cooperative-structured tier, Blue Diamond Growers exemplifies upstream-downstream control through member-owned orchard networks. The Wonderful Company occupies a position spanning retail-branded finished goods and bulk ingredient sales to industrial customers. Olam Food Ingredients represents the geographic diversification archetype with established processing networks extending beyond California into Australian and Mediterranean growing regions.
| Leading Market Players |
|---|
| Blue Diamond Growers |
| The Wonderful Company |
| Olam Food Ingredients |
| John B. Sanfilippo & Son |
| ADM |
| Barry Callebaut Group |
| Borges Agricultural & Industrial Nuts |
| Harris Woolf California Almonds |
| Treehouse California Almonds |
| Others |
Supply Flow & Price Mechanics
Undercapacity in California's Central Valley processing facilities is compressing supplier margins while concentrating pricing power among integrated cooperatives with captive orchard supply. Water rights adjudication tightens raw material availability faster than value-added capacity expansion, forcing processors to prioritize contract-based offtake over spot market exposure.
Pricing Analysis
Geographic price spreads between California-origin and Australian-origin almond flour have widened as irrigation constraints tighten Central Valley supply elasticity. Three-tier pricing structure across premium organic, standard conventional, and economy-grade conventional levels dominates contract negotiations, with organic certification commanding substantial premia over conventional grades. Pricing pressure stems from oat milk substitution in mass retail channels, compressing almond milk's volume expansion trajectory. Food service operators exhibit highest price sensitivity due to thin menu margins, while multinational food manufacturers prioritize specification compliance over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and European Union destinations dominates supply chain risk assessment for roasted ingredient exporters facing EFSA acrylamide documentation requirements. Geographic supply concentrates in California, Australia, and Spain, with California's Central Valley anchoring over 80% of global processing capacity. Raw material dependencies rest on commercial bee colony health for orchard pollination, irrigation water allocation, and seasonal labor availability for harvest intake. Distribution runs through direct processor-to-manufacturer relationships for large-scale food manufacturers, bypassing intermediaries for volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Almond ingredient markets are cycling through a supply-constrained recovery phase driven by California water policy tightening raw material availability faster than demand normalization. Pollinator health volatility and regulatory compliance burdens are accelerating consolidation toward integrated operators with captive supply chains.
For Market Incumbents: Pre-empt margin compression by securing long-term water rights through orchard asset acquisition in Australian Riverina and Spanish Andalusia regions. Accelerate deployment of hyperspectral imaging quality assurance systems to compress supplier qualification cycles before FSMA traceability mandates harden compliance barriers for mid-scale competitors.
For New Entrants and Emerging Players: Build out processing infrastructure in Spain's Valencia growing cluster to capture EU market proximity advantages while California water stress persists. Target confectionery texture modification applications as the most penetrable segment, where blanched ingredient specifications bypass EFSA acrylamide compliance complexity and chocolatiers actively seek clean-label binding alternatives.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cooperative-structured operators with backward integration into member-owned orchards and long-term supply contracts with multinational food manufacturers. Prioritize acquisition targets with established lot-tracking infrastructure for FDA and EFSA compliance, monitoring pollinator health policy developments as the critical inflection signal for supply elasticity restoration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Assets | Captive supply secures water rights and pollination access against California regulatory tightening. |
| Multi-Origin Sourcing Network Expansion | Australian and Spanish processing hubs hedge Central Valley irrigation constraints for EU market access. |
| Digital Quality Assurance Deployment | Hyperspectral imaging compresses certification timelines from days to hours for buyer concentration pressures. |
| Confectionery Texture Modification Focus | Blanched ingredient specifications bypass EFSA acrylamide protocols while capturing clean-label demand. |
| FSMA Traceability Infrastructure Investment | Lot-tracking serialization maintains US market access as FDA mandates harden compliance barriers. |
Methodological Framework
Operator-level perspectives from almond processing facility managers, cooperative member-owners, multinational food manufacturer procurement directors, and agricultural water rights attorneys anchored the qualitative base for this study. Primary field engagement combined with secondary validation from California State Water Resources Control Board adjudication records, FDA FSMA guidance documents, EFSA scientific opinions on acrylamide formation, and USDA almond acreage reports. Bottom-up capacity and utilization estimates triangulated against top-down trade flow analysis across the analysis window.
Scenario-bracketing around water rights policy intensity and pollinator health outcomes structured the analytical framework for projection modeling. Segmentation dimensions included product type, application category, customer procurement sophistication, and regional regulatory cluster. CAGRs derived from regression analysis of historical processing capacity expansion against demand pull from plant-based dairy reformulation, with almond flour particle size distribution and butter fat profile specifications as industry-specific forecast inputs.
Practitioners should monitor California water rights adjudication outcomes, commercial bee colony health surveys, and EFSA thermal processing standard finalization for early signals of forecast revision. Forecasts reflect documented assumptions about irrigation allocation continuity and regulatory compliance timeline stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hops Market
Ingredients
Fiber Rich Flours Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
North America Carrageenan Market
Ingredients
Soy and Milk Protein Ingredients Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Jojoba Oil Market
Ingredients
Global Whey Protein Ingredients Market
Ingredients
North America Corn Starch Market
Ingredients
Blue Light Protection Ingredients Market
Ingredients
Sunflower Oil Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
Protein Extracts from Single Cell Protein and Other Conventional Sources Market
Ingredients
Germany Gelatin Market