
 Dysphagia Diet Thickening Agents Market | 2026-2036
Dysphagia Diet Thickening Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Dysphagia Diet Thickening Agents Market Foresight
Buyer concentration is shifting from institutional healthcare facilities toward fragmented home-care settings as post-acute discharge protocols expand. Nestlé Health Science leverages its clinical nutrition infrastructure to serve both hospital and direct-to-consumer channels. Kent Precision Foods Group, Inc. anchors its position through specialized manufacturing of starch-based thickeners for institutional foodservice. SimplyThick LLC differentiates via ready-to-drink liquid formulations that reduce preparation variability for caregivers.
Dysphagia diet thickening agents are hydrocolloid or polysaccharide additives that increase liquid viscosity to prescribed IDDSI levels, typically achieving nectar-thick to pudding-thick consistencies within 30-60 seconds of incorporation. These agents prevent aspiration during swallowing in patients with neurological impairment, head and neck cancer, or age-related pharyngeal dysfunction. Starch-based formulations occupy the largest volume share due to cost efficiency and familiar clinical protocols, while gum-based alternatives command premium positioning through superior clarity and stable viscosity across temperature ranges. Powder formulations sustain dominant distribution through pharmacies and medical supply stores, though liquid concentrates are gaining traction in home care for dosing convenience.
The FDA exercises oversight through food additive regulations and medical food classifications that determine labeling requirements and reimbursement eligibility. The International Dysphagia Diet Standardisation Initiative establishes texture-modified diet frameworks adopted by CMS and Joint Commission-accredited facilities, creating compliance-driven product specifications. Stakeholders must monitor evolving IDDSI implementation timelines and state-level Medicaid coverage expansions for texture-modified products to anticipate channel demand redistribution.
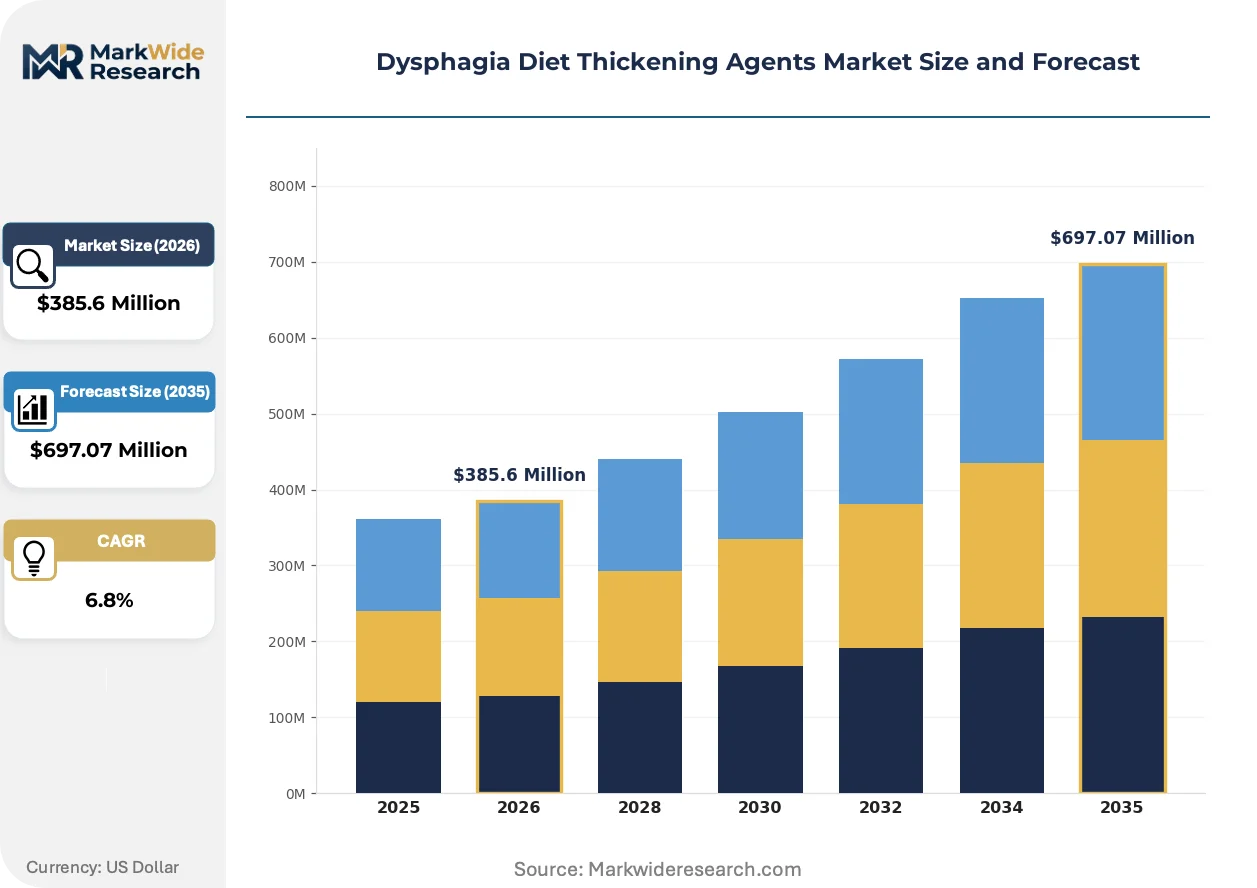
Market Dynamics
The transition from institutional procurement to home-care purchasing is restructuring distribution economics and forcing reformulation toward single-serve convenience formats that accommodate non-clinical caregivers.
Growth Catalysts
- IDDSI Framework Adoption:The International Dysphagia Diet Standardisation Initiative's level-based viscosity standards are mandating calibrated thickener performance specifications across Joint Commission-accredited US facilities, expanding compliant product demand.
- Medicare Reimbursement Expansion:Outpatient dysphagia management protocols in the United States now cover texture-modified products for post-acute discharge patients, accelerating home-care channel development.
- Aging Demographics:Neurological impairment prevalence among populations over 75 years is expanding the addressable patient base for nectar-thick and pudding-thick liquid formulations in residential settings.
Market Restraints
- Input Cost Volatility:Guar gum and xanthan gum prices fluctuate with Indian and Chinese agricultural harvest cycles, compressing margin stability for hydrocolloid-dependent formulations.
- Supply Concentration Risk:Starch-based thickener manufacturing clusters in the US Midwest create geographic vulnerability to weather-related logistics disruptions.
- Technical Limitation:Powdered starch thickeners produce cloudy beverages and variable viscosity across temperature ranges, limiting acceptance in premium hospitality and senior living environments.
Strategic Opportunities
- Underpenetrated Home-Care Markets:Germany's statutory long-term care insurance expansion creates reimbursement pathways for texture-modified products in community-based elder care.
- Ready-to-Drink Liquid Concentrates:Pre-thickened beverages eliminate caregiver preparation errors and reduce nursing time in assisted living facilities.
- Regulatory Tailwind:Japan's Ministry of Health, Labour and Welfare reimbursement revisions for texture-modified foods in long-term care insurance are opening institutional procurement channels.
Industry Challenges
- IDDSI Compliance Certification:Laboratory validation of viscosity stability across pH and temperature ranges requires specialized rheology expertise that mid-tier manufacturers struggle to staff.
- Legacy System Integration:Hospital foodservice operations utilizing conventional tray-line equipment face retrofit costs to accommodate pre-thickened liquid delivery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dysphagia Diet Thickening Agents Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch-Based, Gum-Based, Protein-Based, Others Formulation: Powder, Liquid, Granule, Paste End Use: Healthcare Facilities, Home Care, Long-Term Care, Rehabilitation Centers Distribution Channel: Pharmacies, Online Retail, Medical Supply Stores, Supermarkets |
| Companies Covered | Nestlé Health Science, Kent Precision Foods Group, Inc., Hormel Health Labs, SimplyThick LLC, Danone Nutricia, Fresenius Kabi, Abbott Nutrition, Flavour Creations, Medtrition Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dysphagia Diet Thickening Agents Market Shifts & Advancements
Formulation science and caregiver workflow optimization are intersecting to redefine product architecture, with clarity, stability, and dosing precision emerging as the dominant performance vectors displacing legacy starch protocols.
Gum-based hydrocolloid systems, particularly xanthan and carrageenan blends, are converging with beverage manufacturing to deliver transparent, heat-stable viscosity that maintains IDDSI Level 2 consistency from refrigeration through microwave reheating. Premium senior living operators and hospital hospitality services are adopting these formulations to improve patient acceptance of thickened water and coffee. This technology convergence is compressing the price premium between starch and gum platforms while raising baseline performance expectations across institutional procurement specifications.
The FDA's updated food labeling requirements for texture-modified medical foods are mandating quantitative viscosity ranges and preparation instructions calibrated to IDDSI levels. Manufacturers must now submit analytical data supporting shelf-stability claims, increasing regulatory compliance costs but creating barriers against unverified imported alternatives. Powder formulations face the most significant labeling burden, accelerating investment in ready-to-drink liquid concentrates that require simpler compliance documentation.
Caregiver purchasing patterns in home-care settings favor single-serve packaging and pre-measured dosing systems that eliminate measurement errors associated with bulk powder scoops. Durable medical equipment suppliers and pharmacy chains are capturing this demand through subscription-based replenishment models that displace traditional hospital discharge kit distribution. This behavioral shift is most visible in the United States, where Medicare Advantage plans increasingly authorize direct-to-patient shipping for post-acute dysphagia management supplies.
Dysphagia Diet Thickening Agents Market Segmentation
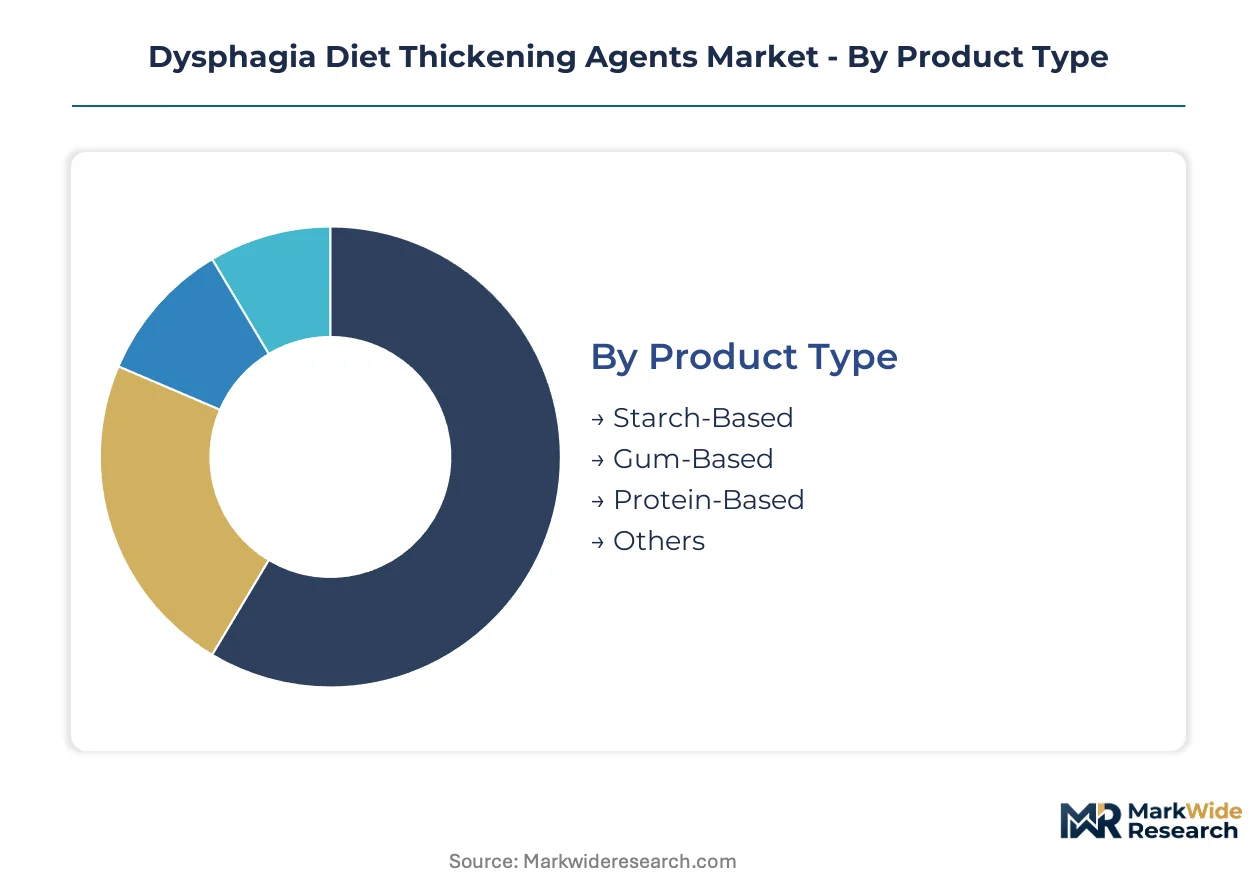
Segmentation in dysphagia diet thickening agents reveals how formulation chemistry, care setting workflows, and procurement channels intersect to determine product specifications and margin structures. Each dimension carries distinct regulatory and reimbursement implications that reshape competitive positioning across institutional and home-care markets.
Product Type:
Replacement cycles accelerate as IDDSI compliance requirements displace legacy starch protocols with precision-calibrated hydrocolloid systems in Joint Commission-accredited US facilities.
- Starch-Based:Modified corn and potato starch derivatives achieve viscosity through granular swelling in aqueous solutions, producing economical nectar-thick to pudding-thick consistencies. Demand concentrates in US hospital foodservice operations where CMS reimbursement protocols prioritize cost containment over beverage clarity, though temperature-dependent viscosity degradation limits acceptance in premium senior living environments.
- Gum-Based:Xanthan, guar, and carrageenan hydrocolloids deliver transparent, heat-stable viscosity maintaining IDDSI Level 2 consistency across refrigeration-to-microwave temperature swings. Faster expansion belongs to gum-based formulations as Japan's Ministry of Health, Labour and Welfare reimbursement revisions and US Medicare Advantage direct-to-patient shipping models reward preparation precision and patient acceptance metrics.
- Protein-Based:Whey and collagen peptide thickeners serve niche populations with starch intolerance or diabetes management requirements in German statutory long-term care insurance programs.
- Others:Cellulose-derived and pectin alternatives occupy specialty positions in organic-certified home-care channels and pediatric dysphagia protocols.
Volume placements concentrate in Starch-Based formulations; the faster expansion belongs to Gum-Based alternatives.
Formulation:
Cost tier stratification separates bulk institutional procurement from convenience-premium home-care delivery, with liquid concentrates commanding per-dose premiums that powder formulations cannot capture.
- Powder:Bulk canisters and single-serve sachets dominate pharmacy and medical supply store distribution through established clinician familiarity and flexible dosing calibration. Demand concentrates in US discharge kit protocols where Medicare reimbursement favors lowest-unit-cost procurement, though caregiver measurement error rates and IDDSI compliance validation burdens accelerate substitution toward pre-measured alternatives.
- Liquid:Pre-thickened beverages and concentrated drops eliminate preparation variability and reduce nursing labor in assisted living facilities. Steepest expansion trajectory belongs to liquid formulations as durable medical equipment suppliers deploy subscription-based replenishment models capturing behavioral shifts in post-acute home-care purchasing patterns.
- Granule:Rapid-dissolving starch granules serve institutional tray-line operations requiring faster incorporation times than conventional powders.
- Paste:Ultra-concentrated gel formats address severe dysphagia requiring honey-thick or spoon-thick IDDSI Level 4-5 consistencies in rehabilitation center protocols.
Procurement volume clusters in Powder formats; the margin expansion opportunity sits with Liquid concentrates.
End Use:
Customer type migration from institutional purchasers toward fragmented non-clinical caregivers restructures packaging specifications, training requirements, and reimbursement documentation.
- Healthcare Facilities:Acute care hospitals and skilled nursing facilities operate under Joint Commission IDDSI implementation timelines with centralized foodservice procurement. Demand concentrates in US metropolitan hospital systems where CMS quality metrics and readmission penalty frameworks institutionalize texture-modified diet protocols.
- Home Care:Post-acute discharge patients and aging-in-place populations purchase through pharmacy chains, online retail, and Medicare Advantage authorized shipping. Gaining share fastest is Home Care as outpatient dysphagia management protocols expand reimbursement eligibility and caregiver error reduction becomes a clinical priority.
- Long-Term Care:Nursing homes and assisted living facilities balance Medicaid reimbursement constraints with regulatory compliance requirements across state-level variation.
- Rehabilitation Centers:Stroke and head injury recovery programs require graduated viscosity progression from thin liquids to normal textures during swallowing therapy.
Revenue concentration remains in Healthcare Facilities; the addressable market expansion centers on Home Care.
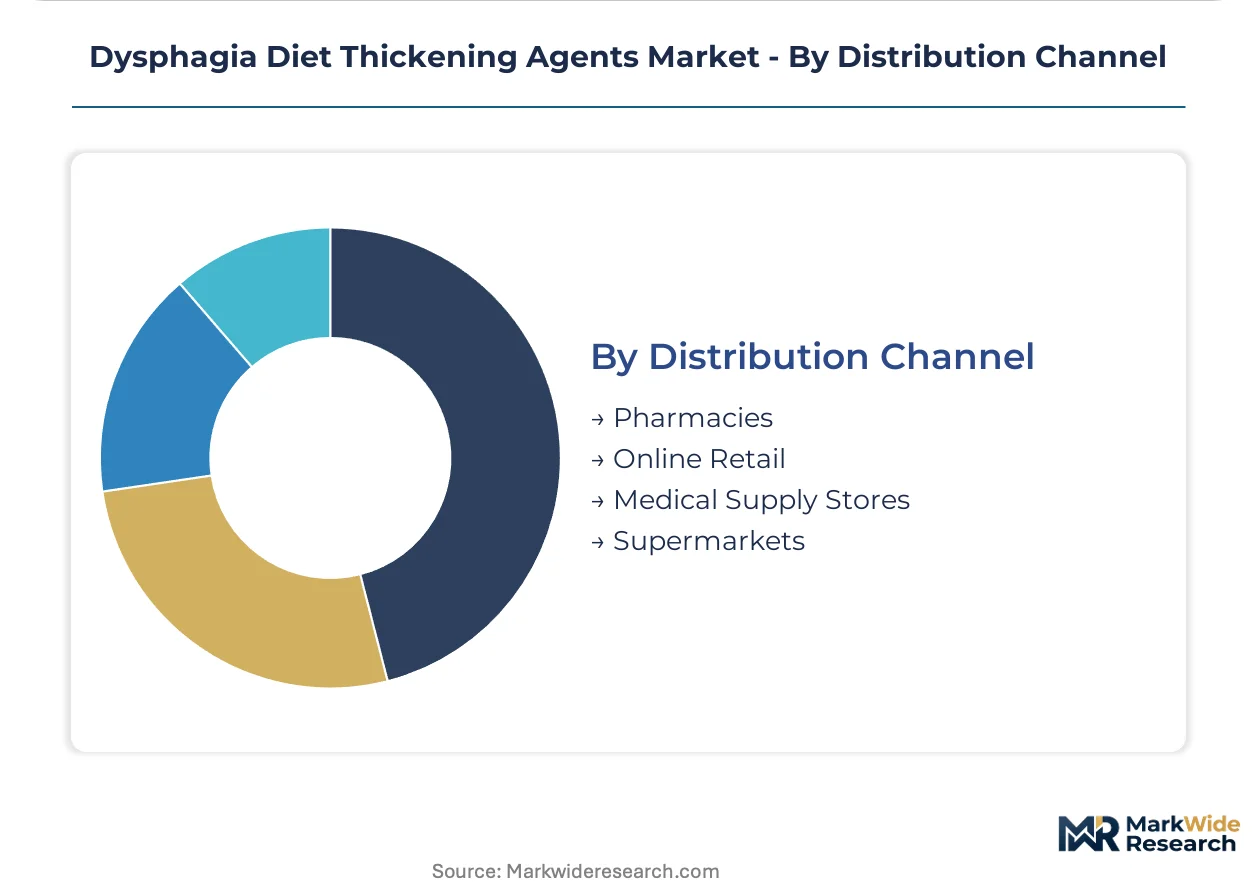
Distribution Channel:
Supply concentration in pharmacy and medical supply infrastructure creates vulnerability to channel shift as online retail and direct-to-patient models displace traditional discharge kit distribution.
- Pharmacies:Hospital outpatient, retail, and long-term care pharmacies maintain formulary control and clinician trust relationships for prescription-grade thickeners. Demand concentrates in US Medicare Part B reimbursement pathways where pharmacy benefit managers influence product selection through prior authorization requirements.
- Online Retail:Amazon, specialized medical supply platforms, and manufacturer direct sites capture subscription replenishment demand from home-care caregivers. Expanding most quickly is Online Retail as Medicare Advantage plans authorize direct-to-patient shipping and caregiver purchasing behavior shifts toward digital convenience.
- Medical Supply Stores:Durable medical equipment dealers serve institutional contracts and individual cash-pay customers with bulk and single-serve formats.
- Supermarkets:Mass-market retail channels carry limited starch-based offerings for informal caregiver purchase without clinical prescription.
Transaction volume flows through Pharmacies; the channel disruption originates from Online Retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for dysphagia diet thickening agents concentrates in the United States, where Medicare reimbursement expansion and Joint Commission IDDSI mandates drive institutional procurement. Germany and Japan follow as reimbursement frameworks mature for texture-modified products in long-term care insurance programs.
United States
Outpatient dysphagia management protocols and Medicare Advantage direct-to-patient shipping models accelerate home-care channel development. The FDA's updated food labeling requirements for medical foods mandate quantitative viscosity ranges calibrated to IDDSI levels. Manufacturing clusters in the US Midwest supply starch-based thickeners to hospital foodservice operations, though weather-related logistics disruptions create periodic supply vulnerability.
Germany
Statutory long-term care insurance expansion creates reimbursement pathways for texture-modified products in community-based elder care settings. The EFSA maintains oversight of hydrocolloid food additives while national pharmacy benefit frameworks influence product selection. Industrial concentration in North Rhine-Westphalia supports specialized manufacturing of protein-based thickeners for diabetic and starch-intolerant patient populations.
Japan
Ministry of Health, Labour and Welfare reimbursement revisions for texture-modified foods in long-term care insurance open institutional procurement channels. METI coordinates with industry associations on IDDSI implementation timelines for acute care facilities. The Kanto region around Tokyo anchors domestic formulation development, with Kansai-based distributors serving the aging population in Osaka and surrounding prefectures.
United Kingdom
NHS England's post-acute discharge protocols expand texture-modified diet coverage for stroke and neurological rehabilitation patients. The MHRA regulates medical food classifications that determine pharmacy reimbursement eligibility. Manufacturing activity clusters in the Midlands and North England, supplying both hospital trusts and growing home-care pharmacy networks.
Australia
TGA oversight of food additive safety and medical food claims shapes product registration requirements for imported hydrocolloid formulations. State-level aged care quality standards increasingly reference IDDSI compliance in facility accreditation. New South Wales and Victoria concentrate demand through metropolitan hospital systems and private aged care operators in Sydney and Melbourne.
Dysphagia Diet Thickening Agents Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue clarity-optimized gum formulations and subscription-based home-care delivery. The vendor base spans multinational nutrition conglomerates, regional foodservice specialists, and single-product innovators. Three archetypes dominate: clinical nutrition platforms with hospital channel integration, institutional foodservice manufacturers with cost-optimized starch production, and convenience-focused innovators with liquid concentrate formats. Competitive intensity centers on IDDSI compliance certification and Medicare Advantage direct-to-patient shipping authorization.
Among clinical nutrition platforms, Nestlé Health Science and Danone Nutricia represent the integrated hospital-to-home archetype, leveraging existing enteral nutrition infrastructure to serve discharge protocols. Kent Precision Foods Group, Inc. anchors the institutional manufacturing tier with specialized starch-based production capabilities. SimplyThick LLC exemplifies the convenience innovation vector through ready-to-drink liquid formulations that reduce caregiver preparation variability.
| Leading Market Players |
|---|
| Nestlé Health Science |
| Kent Precision Foods Group, Inc. |
| Hormel Health Labs |
| SimplyThick LLC |
| Danone Nutricia |
| Fresenius Kabi |
| Abbott Nutrition |
| Flavour Creations |
| Medtrition Inc. |
| Others |
Supply & Pricing Matrix
Family-owned Midwest starch processors and private-equity-rolled-up gum specialists exercise divergent pricing discipline based on captive agricultural sourcing versus spot-market hydrocolloid exposure. Their ownership structures directly determine margin resilience when Indian guar harvests falter or US corn belt logistics seize.
Pricing Analysis
Volume placements concentrate in starch-based economy tiers where hospital foodservice procurement prioritizes lowest-unit-cost compliance; margin expansion sits with gum-based premium formulations commanding clarity premiums in senior living hospitality. Price differentiation separates IDDSI-certified precision products from unverified imports facing FDA labeling rejection. Pricing pressure stems from Medicare Advantage reimbursement compression favoring generic starch alternatives over patented hydrocolloid blends. Home-care caregivers exhibit highest price sensitivity due to out-of-pocket exposure, while hospital GPO contracts absorb cost pass-throughs.
Supply Chain Analysis
Japan's domestic-content preferences for long-term care insurance reimbursement and Germany's pharmacy-benefit localization requirements are reshaping regional sourcing patterns away from concentrated US manufacturing. Hydrocolloid supply draws from Indian guar gum harvests, Chinese xanthan fermentation capacity, and Philippine carrageenan extraction. Raw material dependency on South Asian agricultural cycles creates commodity volatility exposure absent in corn starch supply. Distribution runs through pharmacy benefit managers and durable medical equipment suppliers capturing Medicare Part B and Advantage authorization workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
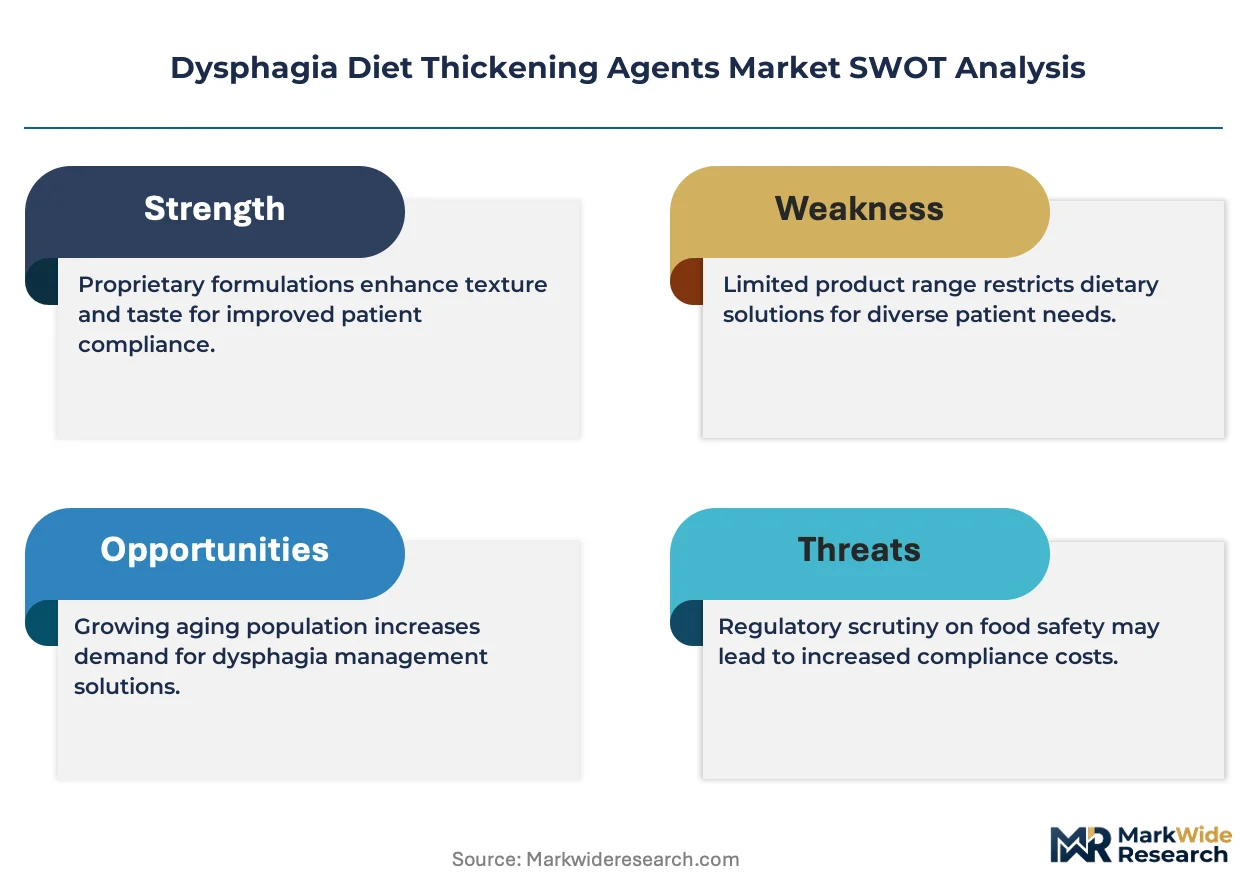
The dysphagia diet thickening agents market functions as a cost-of-compliance story where FDA medical food labeling requirements and IDDSI certification standards erect capital-intensive barriers that filter out commodity imitators.
For Market Incumbents: To counter gum-based entrants eroding clarity premiums in senior living channels, Nestlé Health Science and Danone Nutricia should deepen backward integration into xanthan fermentation capacity while securing exclusive Medicare Advantage direct-to-patient shipping contracts that lock caregiver subscription loyalty. For New Entrants and Emerging Players: Durable medical equipment suppliers represent the most accessible channel partner archetype for pre-thickened liquid concentrate launches targeting home-care reimbursement expansion. White-space concentration sits in Germany's statutory long-term care insurance community-based elder care protocols and Japan's texture-modified food reimbursement revisions. A subscription-based replenishment model capturing caregiver error-reduction priorities bypasses entrenched hospital formulary control. For Investors and Strategic Acquirers: Distressed-cycle entries favor IDDSI-certified mid-cap specialists with validated rheology laboratories in the US Midwest or Kanto region when Medicare reimbursement compression triggers margin stress. Long-term viability centers on regulatory compliance moats widening through FDA enforcement against unverified imports. The inflection signal to monitor is state-level Medicaid coverage expansion for texture-modified products accelerating channel demand redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| IDDSI Compliance Certification Investment | FDA labeling requirements mandate validated viscosity stability data that mid-tier competitors cannot staff. |
| Backward Integration into Xanthan Fermentation | Chinese and Indian agricultural volatility threatens margin stability for hydrocolloid-dependent formulations. |
| Medicare Advantage Direct-to-Patient Shipping Authorization | Subscription models displace traditional hospital discharge kit distribution in post-acute dysphagia management. |
| Single-Serve Liquid Concentrate Format Development | Caregiver error reduction priorities in home care accelerate substitution from bulk powder measurement. |
| German Long-Term Care Insurance Reimbursement Pathway Establishment | Statutory expansion creates procurement channels for texture-modified products in community-based elder care. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital foodservice directors, GPO contract managers, durable medical equipment suppliers, Medicare Advantage plan administrators, and IDDSI implementation consultants combined with FDA medical food registration databases, CMS reimbursement policy documents, and hydrocolloid import manifests. Bottom-up volume modeling across formulation chemistry and care setting channels triangulated against top-down spending flow estimates from national health accounts.
Granularity-level modeling deployed product-type splits across starch, gum, protein, and cellulose-derived chemistries; formulation formats spanning powder, liquid, granule, and paste; and end-use segmentation across acute care hospitals, skilled nursing facilities, home care, and rehabilitation centers. CAGRs derived from patient population epidemiology, reimbursement expansion timelines, and IDDSI implementation schedules across Joint Commission-accredited facilities. Forecast inputs incorporated aging demographic projections, neurological impairment prevalence curves, and outpatient dysphagia management protocol adoption rates.
Several conditions sit outside the modeled scope, including pandemic-era supply chain disruptions, abrupt FDA enforcement actions against non-compliant imports, and radical reform of Medicare reimbursement structures. Forecasts reflect assumptions documented in the segmentation and regional frameworks above. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Fortified Eggs Market
Food Enhancers and Additives
South Africa Water Enhancer Market
Food Enhancers and Additives
Kaempferol Market
Food Enhancers and Additives
Germany Food Flavor and Enhancer Market
Food Enhancers and Additives
Europe Feed Palatability Enhancers Market
Food Enhancers and Additives
Asia-Pacific Flavor Enhancer Market
Food Enhancers and Additives
United Kingdom Water Enhancer Market
Food Enhancers and Additives
Mexico Food Flavor and Enhancer Market
Food Enhancers and Additives
Italy Anti-Caking Market
Food Enhancers and Additives
Gut Modifiers Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
Africa Water Enhancer Market
Food Enhancers and Additives
Raising Agents Market
Food Enhancers and Additives
Australia Food Flavor and Enhancer Market
Food Enhancers and Additives
Australia Water Enhancer Market