
 India Gelatin Market | 2026-2036
India Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
India Gelatin Market Foresight
Enzymatic extraction and cold-water soluble gelatin variants are reshaping how Indian manufacturers process raw collagen into finished hydrocolloids. Nitta Gelatin India Limited leverages its integrated tannery-to-gelatin pipeline to control raw material quality across southern supply zones. Sterling Gelatin (India) Pvt. Ltd. sustains dominance in pharmaceutical-grade output through dedicated acid-processing lines. Rousselot India Pvt. Ltd. competes on global technical standards, positioning its Mumbai facility as an export-qualified operation.
Gelatin is a heterogeneous mixture of peptides and proteins derived from partial hydrolysis of collagen extracted from mammalian connective tissues, with bloom strength ranging from 50 to 300 grams defining gel firmness and industrial utility. Pharmaceutical Grade gelatin commands premium positioning due to stringent endotoxin and heavy metal limits required for hard and soft capsule shells. Food Grade gelatin anchors volume throughput as gummy candy manufacturers in Ahmedabad and Mumbai expand capacity. Nutraceuticals emerges as the fastest-growing end user segment driven by collagen peptide fortification in functional beverages and dietary supplements.
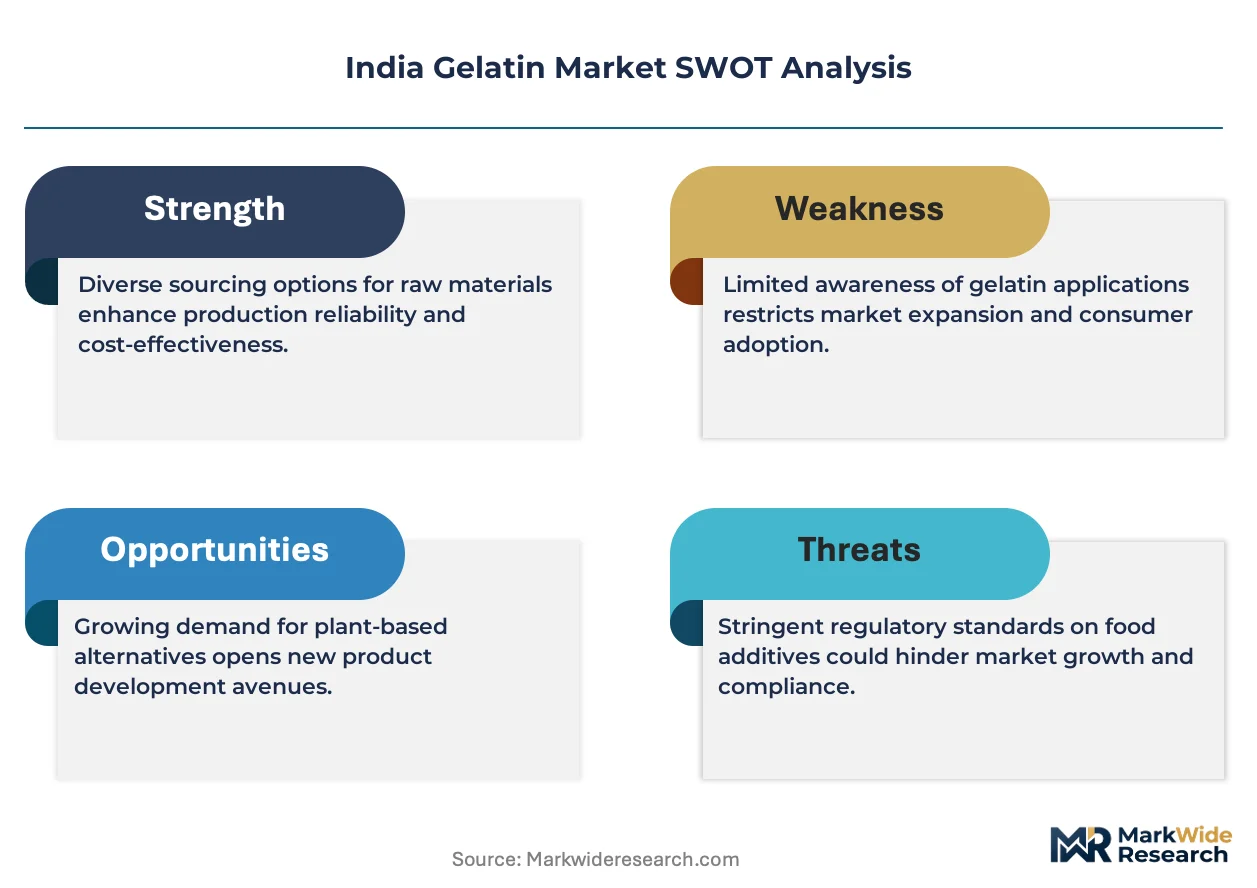
BIS pharmaceutical gelatin standards and FSSAI food additive regulations together determine market access thresholds, with CDSCO drug master file requirements adding compliance layers for capsule-grade suppliers. The country's national food safety regulator enforces labeling and origin traceability rules that constrain imported raw material sourcing options. State pollution control boards in Tamil Nadu and West Bengal impose effluent discharge limits on rendering and extraction facilities. Stakeholders must monitor evolving CDSCO active pharmaceutical ingredient notification rules and state-level environmental clearance timelines to secure capacity expansion approvals.
Market Dynamics
Pharmaceutical capsule demand from Maharashtra and Gujarat manufacturing clusters is compressing gelatin supply chains toward dedicated acid-processing capacity and BIS-certified purity benchmarks.
Growth Catalysts
- CDSCO capsule-grade certification:Domestic drug formulation output is pulling pharmaceutical-grade gelatin through mandatory drug master file compliance, tightening supplier qualification windows.
- Collagen peptide fortification:Functional beverage manufacturers in Mumbai and Ahmedabad are absorbing hydrolyzed gelatin derivatives for nutraceutical applications.
- Enzymatic extraction:Cold-water soluble variants are expanding food-grade utility beyond traditional thermal-gel applications into instant beverage systems.
Market Restraints
- Raw material concentration:Southern tannery clusters in Tamil Nadu control over half of bovine hide supply, creating single-source vulnerability for collagen feedstock.
- FSSAI traceability mandates:Origin documentation requirements for imported porcine materials are extending procurement cycles by 40-60 days.
- Plant-based hydrocolloids:Pectin and carrageenan alternatives are capturing vegan confectionery contracts from traditional gelatin buyers.
Strategic Opportunities
- West Bengal rendering capacity:Underutilized eastern tannery infrastructure offers expansion terrain for integrated extraction-to-gelatin operations.
- PLI scheme alignment:Pharmaceutical manufacturing incentives are subsidizing domestic capsule shell production, pulling localized gelatin supply.
- Direct-to-supplement distribution:E-commerce collagen peptide sales are bypassing traditional ingredient distributor markups for end-consumer brands.
Industry Challenges
- Bloom strength calibration:Pharmaceutical capsule shell production requires precise 150-250 gram gel firmness control that few domestic facilities consistently achieve.
- Effluent discharge compliance:Tamil Nadu and West Bengal pollution control boards are rejecting expansion permits for rendering facilities lacking zero-liquid-discharge systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Gelatin Market |
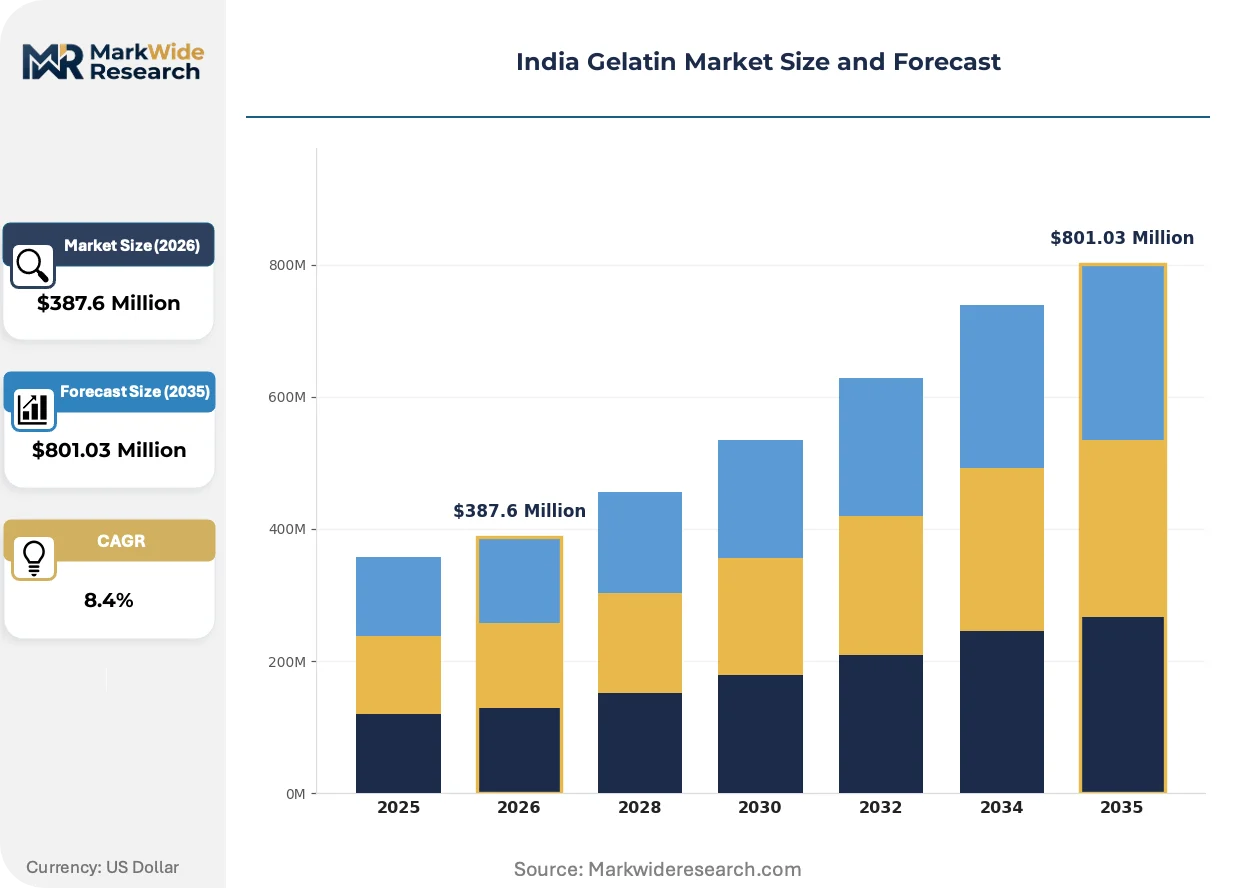
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Food Grade, Industrial Grade, Technical Grade Application: Capsules, Gummy Candies, Film Coating, Stabilizers End User: Pharmaceuticals, Food & Beverages, Cosmetics, Nutraceuticals Distribution Channel: Online, Wholesalers, Retailers, Direct Sales |
| Companies Covered | Nitta Gelatin India Limited, India Gelatine & Chemicals Ltd, Sterling Gelatin (India) Pvt. Ltd., PB Gelatins India Pvt. Ltd., Geltech India, Rousselot India Pvt. Ltd., Narmada Gelatines Ltd., ITALGELATINE India Pvt. Ltd., Pioneer Jellice India Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Gelatin Market Shifts & Advancements
Processing technology and regulatory stringency are compressing the viable supplier base toward integrated operations with certified pharmaceutical output and environmental clearance.
Membrane filtration systems for endotoxin removal are rendering obsolete traditional multi-stage washing protocols in pharmaceutical-grade production. Hard capsule manufacturers in Gujarat are adopting these systems ahead of CDSCO inspection cycles. The capital barrier is eliminating semi-integrated processors without captive tannery supply.
FSSAI's 2023 amendment to food additive labeling rules now mandates species origin disclosure on all gelatin-containing products. Confectionery exporters are reformulating to single-species bovine sources to avoid import rejection in Middle Eastern markets. Domestic gummy manufacturers in Ahmedabad are absorbing 8-12% ingredient cost premiums for certified halal supply chains.
Long-term offtake contracts are displacing spot market purchasing among pharmaceutical capsule producers. Sterling Gelatin and Rousselot India have secured three-year supply agreements with Mumbai-based formulation houses, locking volume ahead of capacity expansions. This procurement consolidation is visible most acutely in Maharashtra, where three buyers now represent over half of pharmaceutical-grade offtake.
India Gelatin Market Segmentation
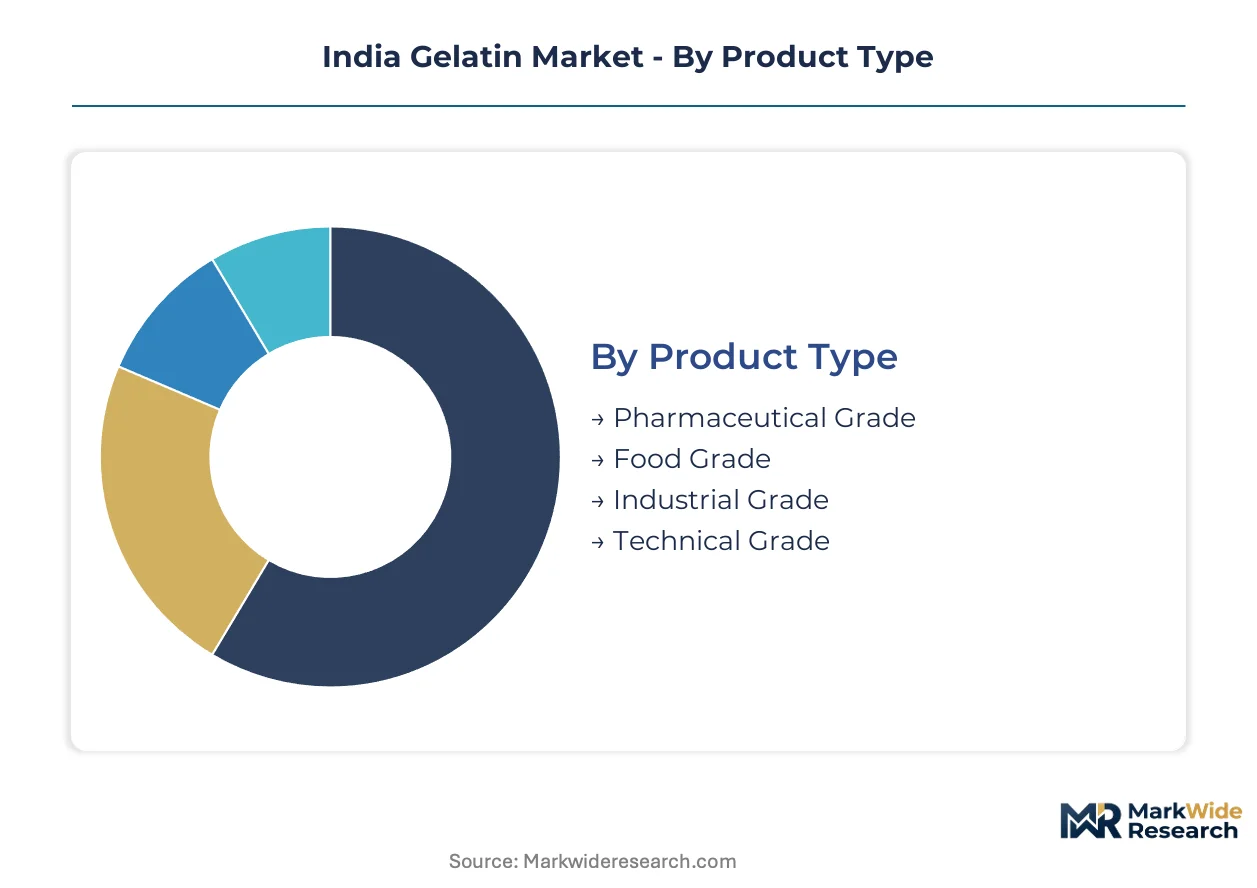
India's gelatin market fragments across purity tiers and end-use specifications that determine BIS certification pathways and CDSCO compliance requirements. Each segment carries distinct margin profiles and regulatory burdens that reshape supplier positioning.
Product Type:
Pharmaceutical capsule shell production, edible confectionery formulations, and industrial adhesive applications each demand differentiated bloom strength and endotoxin specifications.
- Pharmaceutical Grade:Stringent endotoxin limits below 10 EU/g and heavy metal thresholds define this segment. Maharashtra and Gujarat formulation clusters absorb over half of domestic pharmaceutical-grade output as CDSCO drug master file compliance tightens supplier qualification.
- Food Grade:Bloom strength ranges of 100-250 grams serve gummy candy manufacturers and dessert stabilizer applications. Ahmedabad confectionery clusters drive volume absorption despite FSSAI species-origin disclosure mandates adding procurement complexity.
- Industrial Grade:Lower purity specifications serve adhesive and photographic emulsion manufacturers with minimal regulatory burden.
- Technical Grade:Intermediate specifications support matchstick head binding and paper sizing applications across Tamil Nadu industrial zones.
Established volume favors Food Grade; emerging adoption favors Pharmaceutical Grade.
Application:
Cost tiers separate high-purity pharmaceutical shells from commodity confectionery inclusions and functional stabilizers.
- Capsules:Hard and soft gelatin shells for oral drug delivery require precise 150-250 gram bloom strength calibration. Mumbai and Hyderabad formulation houses are consolidating procurement through multi-year offtake agreements with certified suppliers.
- Gummy Candies:Chewy confectionery matrices demand rapid-set gelatin with 150-200 bloom characteristics. Domestic manufacturers face 8-12% cost premiums for halal-certified bovine sourcing to maintain Middle East export eligibility.
- Film Coating:Tablet surface sealing applications utilize lower-viscosity gelatin derivatives with modified dissolution profiles.
- Stabilizers:Dairy and dessert applications employ cold-water soluble variants for instant beverage systems and frozen product texture control.
Margin concentration sits with Capsules; volume expansion runs through Gummy Candies.
End User:
Customer type determines specification stringency from CDSCO-regulated drug production to FSSAI-monitored food systems.
- Pharmaceuticals:Capsule shell manufacturers and tablet coating operations constitute the highest-specification demand pool. Domestic drug formulation output growth is compressing supply chains toward dedicated acid-processing capacity.
- Food & Beverages:Confectionery, dairy, and beverage stabilization represent the volume anchor. Mumbai and Ahmedabad processing clusters absorb standard and instant-soluble variants for diverse texture applications.
- Cosmetics:Collagen peptide incorporation into topical formulations and hair care products utilizes hydrolyzed gelatin derivatives with enhanced solubility profiles.
- Nutraceuticals:Functional beverage fortification and dietary supplement matrices are climbing the fastest as direct-to-consumer collagen peptide sales bypass traditional distribution markups.
Regulatory burden peaks with Pharmaceuticals; steepest expansion trajectory belongs to Nutraceuticals.
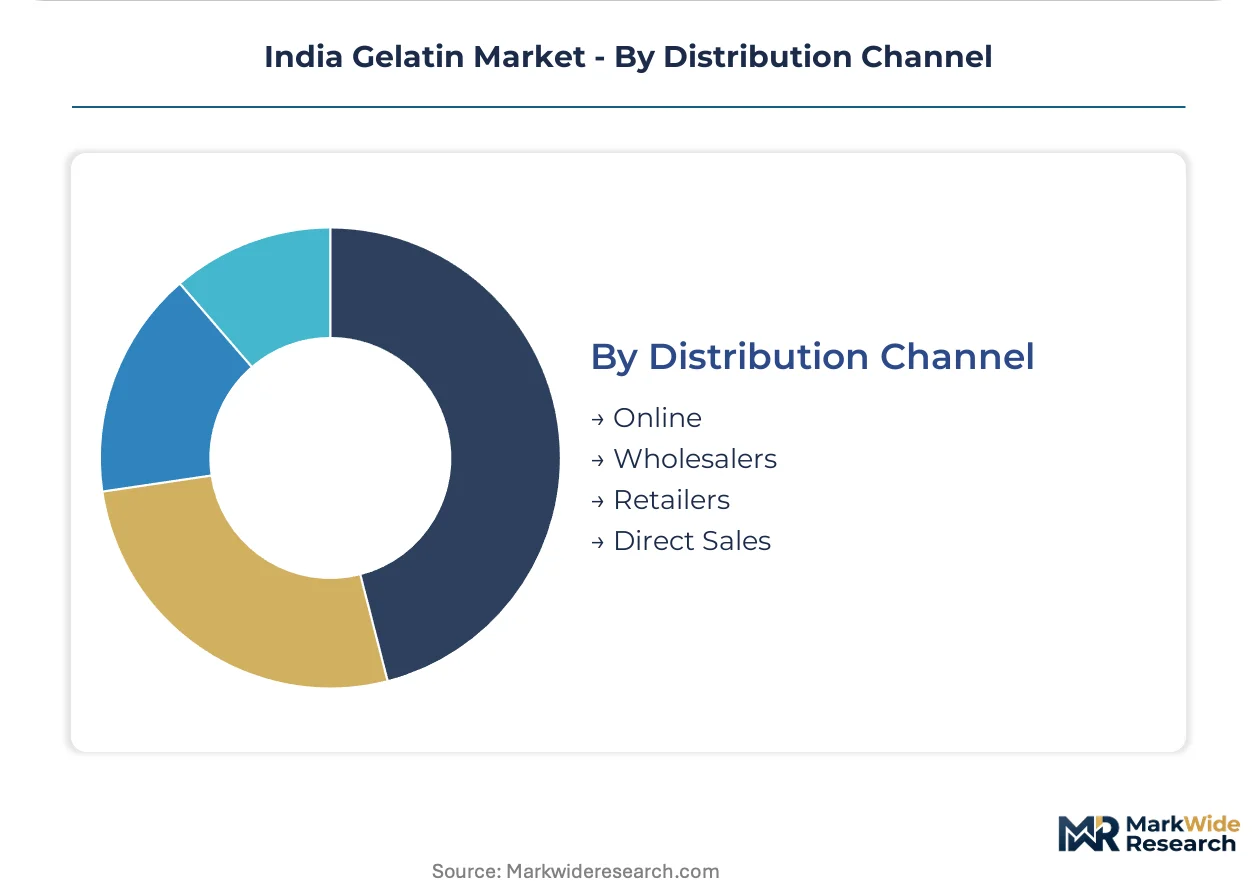
Distribution Channel:
Supply concentration in southern tannery belts shapes how finished gelatin reaches dispersed manufacturing clusters.
- Direct Sales:Long-term contracts dominate pharmaceutical-grade movement, with Sterling Gelatin and Rousselot India locking three-year agreements with Maharashtra formulation houses ahead of capacity expansions.
- Wholesalers:Food-grade volume flows through regional distributors serving Ahmedabad and Mumbai confectionery clusters with standard bloom strength inventories.
- Retailers:Small-batch nutraceutical and cosmetic manufacturers procure through specialty chemical distributors with technical support services.
- Online:E-commerce collagen peptide sales to end-consumer brands are displacing traditional ingredient distributor markups, particularly in direct-to-supplement distribution models.
Contract security favors Direct Sales; channel disruption runs through Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical capsule manufacturers in Maharashtra and Gujarat absorb the majority of domestic pharmaceutical-grade gelatin output, while food-grade demand concentrates in Ahmedabad and Mumbai confectionery clusters. Southern tannery belts in Tamil Nadu supply raw collagen feedstock, creating a geographic mismatch between rendering infrastructure and finished goods consumption. State-level environmental regulations and BIS certification requirements are reshaping where new extraction capacity can locate.
Maharashtra
Mumbai and Pune formulation houses drive pharmaceutical-grade gelatin absorption through hard and soft capsule shell production. CDSCO drug master file compliance requirements are compressing supplier qualification windows toward BIS-certified acid-processing facilities. Three-year offtake agreements now dominate procurement, with Sterling Gelatin and Rousselot India locking volume ahead of capacity expansions in this western manufacturing cluster.
Gujarat
Ahmedabad confectionery manufacturers anchor food-grade gelatin demand for gummy candy and dessert stabilizer applications. FSSAI species-origin disclosure mandates are forcing 8-12% cost premiums for halal-certified bovine sourcing to maintain Middle East export eligibility. The state's pharmaceutical corridor near Vadodara is simultaneously pulling acid-processed gelatin for tablet coating operations.
Tamil Nadu
Southern tannery clusters control over half of domestic bovine hide supply, creating single-source vulnerability for collagen feedstock. State pollution control board effluent discharge limits are rejecting expansion permits for rendering facilities lacking zero-liquid-discharge systems. Chennai-based extraction operations face capital barriers from membrane filtration requirements for endotoxin removal in pharmaceutical-grade output.
West Bengal
Underutilized eastern tannery infrastructure offers expansion terrain for integrated extraction-to-gelatin operations. State pollution control regulations are tightening faster than southern counterparts, favoring greenfield facilities with captive environmental systems. Kolkata's proximity to Bangladesh leather markets provides alternative raw material sourcing channels for processors willing to navigate FSSAI traceability documentation.
Karnataka
Bengaluru nutraceutical manufacturers are climbing the fastest-growing demand vector for collagen peptide fortification in functional beverages. Direct-to-consumer e-commerce distribution is bypassing traditional ingredient distributor markups for local supplement brands. The state's food processing incentives are pulling cold-water soluble gelatin variants for instant beverage system applications.
India Gelatin Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated tannery-to-gelatin operators dominate raw material security, while dedicated pharmaceutical-grade processors command premium positioning through BIS certification. The market structure favors backward integration into rendering capacity and long-term offtake contracting with formulation houses. Competitive moves concentrate on membrane filtration technology adoption and multi-year supply agreement locking.
Among Japan-anchored multinationals, Nitta Gelatin India Limited exemplifies the integrated archetype with tannery pipeline control. Sterling Gelatin (India) Pvt. Ltd. and Rousselot India Pvt. Ltd. occupy positions on the pharmaceutical-specialist vector, with the latter representing global technical standards through export-qualified operations. These three names anchor the supplier base visible in Maharashtra and Gujarat procurement consolidation.
| Leading Market Players |
|---|
| Nitta Gelatin India Limited |
| India Gelatine & Chemicals Ltd |
| Sterling Gelatin (India) Pvt. Ltd. |
| PB Gelatins India Pvt. Ltd. |
| Geltech India |
| Rousselot India Pvt. Ltd. |
| Narmada Gelatines Ltd. |
| ITALGELATINE India Pvt. Ltd. |
| Pioneer Jellice India Pvt Ltd |
| Others |
Supply & Pricing Matrix
The Chennai-Visakhapatnam freight corridor carries tannery-derived collagen feedstock from Tamil Nadu rendering clusters to western pharmaceutical manufacturers, with logistics costs amplifying the price spread between acid-processed pharmaceutical grades and standard food-grade output. This geographic asymmetry between southern raw material concentration and Maharashtra-Gujarat consumption centers forces buyers to absorb distance-based premiums or accept longer procurement cycles.
Pricing Analysis
Long-term offtake contracts with bovine hide price indexation dominate pharmaceutical-grade transactions, insulating capsule manufacturers from spot volatility while locking suppliers into thin margin bands. Three-tier pricing structure across premium pharmaceutical, standard food-grade, and economy industrial levels reflects BIS certification intensity and endotoxin control investment. Cost compression in food-grade segments is intensifying because FSSAI halal-certification mandates add 8-12% procurement premiums for Middle East export eligibility. Small-batch nutraceutical buyers exhibit highest price sensitivity, while CDSCO-compliant pharmaceutical houses prioritize supply security over unit cost.
Supply Chain Analysis
Export-control restrictions on membrane filtration technology from Germany and Japan constrain domestic pharmaceutical-grade capacity expansion, forcing Indian processors to source endotoxin-removal systems through extended procurement channels. Raw material supply draws from Tamil Nadu tannery belts, Bangladesh leather markets, and limited domestic porcine rendering operations. Single-source vulnerability in southern bovine hide concentration threatens supply continuity during regional environmental enforcement actions. Distribution runs through direct sales contracts for pharmaceutical grades and regional wholesalers serving Ahmedabad-Mumbai confectionery clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among Maharashtra pharmaceutical capsule manufacturers has shifted negotiating leverage toward volume-buying formulation houses, fragmenting supplier pricing power across fewer dominant accounts. This buyer-power concentration demands defensive repositioning from incumbents and targeted white-space entry from challengers.
For Market Incumbents: Harden acid-processing certification moats through CDSCO drug master file pre-qualification ahead of competitor capacity additions. Deepen backward integration into West Bengal tannery infrastructure to escape Tamil Nadu pollution-control bottlenecks and secure captive collagen feedstock against raw material concentration risk. For New Entrants and Emerging Players: Pursue nutraceutical-grade collagen peptide production for Bengaluru functional beverage brands, where direct-to-consumer e-commerce distribution bypasses entrenched wholesaler relationships. Target Karnataka's underdeveloped rendering-to-extraction pipeline as the most penetrable geography, leveraging state food-processing incentives and cold-water soluble variant demand. For Investors and Strategic Acquirers: Integrated extraction-to-gelatin operators with captive tannery supply and zero-liquid-discharge environmental clearance represent the most defensible acquisition archetype in a tightening regulatory environment. Monitor CDSCO active pharmaceutical ingredient notification amendments as the critical inflection signal for pharmaceutical-grade capacity valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Operations | Captive bovine hide supply secures raw material continuity against Tamil Nadu environmental enforcement volatility. |
| Membrane Filtration Technology Adoption | Endotoxin removal systems satisfy CDSCO pharmaceutical-grade certification requirements ahead of inspection cycles. |
| Long-term Supply Agreement Locking | Three-year offtake contracts with Maharashtra formulation houses defend volume share against emerging competitors. |
| Halal-Certified Bovine Sourcing | Single-species origin documentation maintains Middle East export eligibility under FSSAI disclosure mandates. |
| Zero-Liquid-Discharge System Installation | Tamil Nadu and West Bengal pollution control boards require advanced effluent treatment for expansion permit approval. |
Research Methodology
Cross-validation between regulatory filing analysis and trade data anchors the qualitative findings on supply chain concentration and pricing dynamics. Primary interviews with pharmaceutical procurement managers, tannery operations directors, FSSAI compliance officers, and confectionery supply chain heads combined with secondary validation through CDSCO drug master file records, BIS certification databases, customs import-export statistics, and state pollution control board clearance documents. Bottom-up capacity modeling and top-down demand estimation from end-use absorption data were reconciled to establish market sizing.
Calibration against historical capacity utilization rates and announced expansion timelines shaped the projection framework across the analysis window. Segmentation dimensions modeled include product grade tier, application specification, end-user industry, and regional production cluster. CAGRs were derived from slope analysis of normalized growth trajectories against base-year benchmarks. Forecast inputs incorporated PLI scheme disbursement patterns for pharmaceutical manufacturing and FSSAI enforcement intensity indices for food-grade compliance costs.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates, leather commodity price cycles, or central environmental court rulings would shift the trajectory. Forecasts reflect assumptions on regulatory enforcement continuity and tannery cluster operational status. Material shifts in CDSCO capsule-grade certification timelines or Tamil Nadu pollution control moratorium extensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Potato Protein Market
Ingredients
Mastic Gum Market
Ingredients
Clean Label Starch Market
Ingredients
Soy Flour Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
Sesame Seed Extract Market
Ingredients
Hen Egg White Protein Market
Ingredients
Barley Flake Market
Ingredients
North America Cheese Powder Market
Ingredients
North America Corn Starch Market
Ingredients
Food Grade Hydrolyzed Casein Market
Ingredients
Dried Fruit Ingredients Market
Ingredients
Europe Feed Yeast Market
Ingredients
Hops Market
Ingredients
North America Carrageenan Market
Ingredients
Cocoa Derivatives Market