
 Dry Blended Products Market | 2026-2036
Dry Blended Products Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Blended Products Market Foresight
India is rewriting competitive dynamics in dry blended products as new toll-manufacturing clusters near Mumbai and Hyderabad attract multinational investment. Cargill Incorporated leverages its oilseed processing backbone to backward-integrate into spice and seasoning blending for quick-service restaurant chains. Ingredion Incorporated anchors the North American modified starch and protein premix segment through dedicated R&D facilities in Illinois. Archer Daniels Midland Company dominates South American grain-based blending with captive supply of corn and soy derivatives.
Dry blended products consist of two or more powdered, granulated, or flake ingredients mechanically mixed to achieve uniform distribution without chemical bonding, typically requiring moisture content below 5% to prevent caking and microbial growth. These formulations serve as cost-efficient, scalable inputs across food manufacturing, enabling consistent flavor, nutrition, and functionality in finished goods. Protein powder and seasoning blends occupy the highest-margin pools within the product type dimension, driven by sports nutrition and clean-label savory applications. Snack foods and ready meals represent the fastest-growing application segments as convenience-oriented consumers shift toward shelf-stable, portion-controlled formats.
FDA preventive controls under FSMA mandate hazard analysis and supply chain verification for domestic and imported dry blends, elevating compliance costs for smaller compounders. BIS standards in India and EFSA additive regulations in Europe impose divergent labeling and compositional requirements that fragment formulation strategies across export markets. Stakeholders must monitor evolving front-of-pack disclosure mandates and carbon footprint reporting obligations under the EU Green Deal and CSRD, as these frameworks increasingly penetrate ingredient-tier procurement criteria.
Market Dynamics
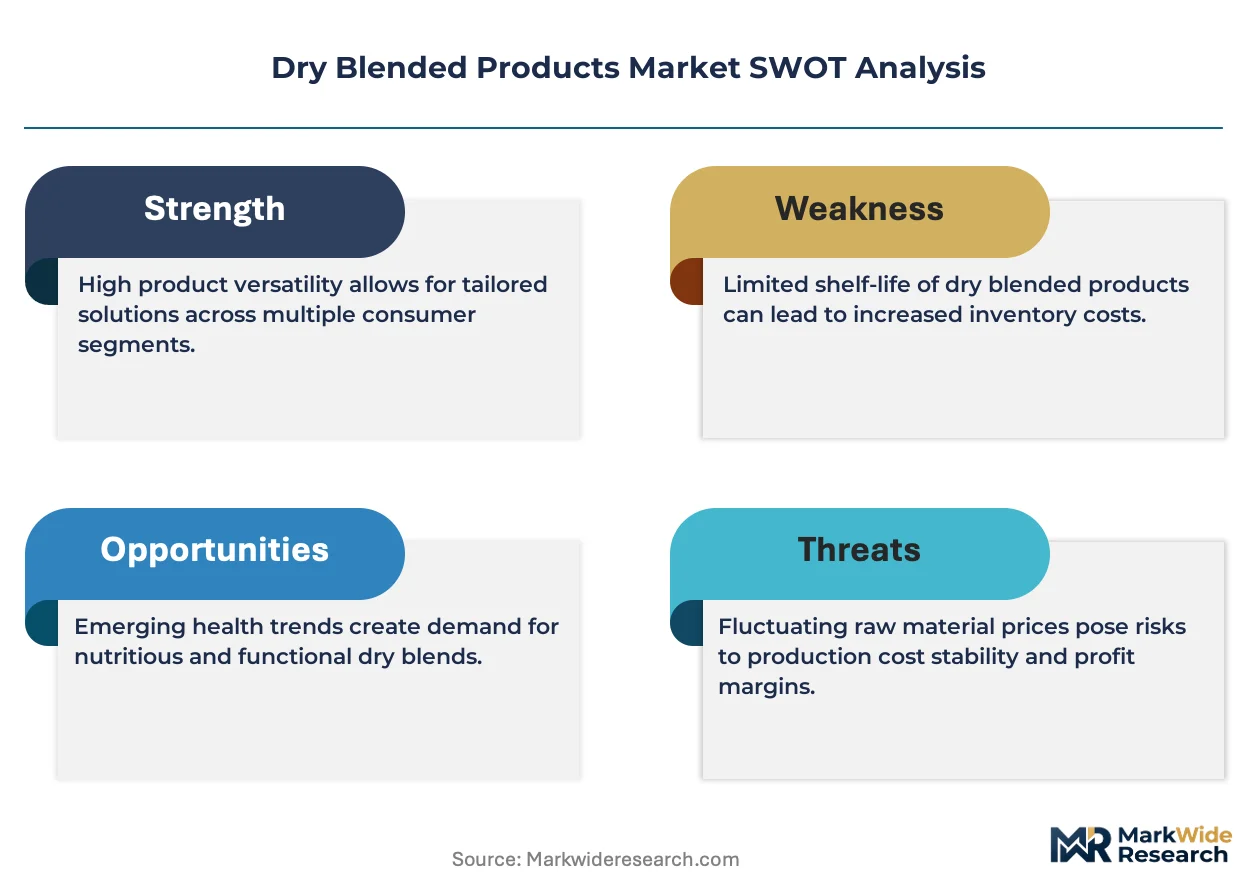
FSMA preventive controls are compressing the supplier base by forcing capital upgrades for traceability, creating a bifurcation between compliant compounders and commodity blenders facing exit pressure.
Growth Catalysts
- Plant-based protein premixes:Food manufacturers are scaling procurement of neutral-flavor pea and rice protein blends for meat-analogue ready meals, driven by flexitarian dietary shifts in North American and European retail channels.
- BIS certification harmonization:India's alignment of food-grade blending standards with Codex Alimentarius is reducing export friction for international ingredient suppliers establishing toll-manufacturing near Mumbai.
- Clean-label seasoning demand:Quick-service restaurant chains are reformulating proprietary spice blends to eliminate maltodextrin and anti-caking agents, pulling high-margin custom compounding volumes from generic off-the-shelf suppliers.
Market Restraints
- Input cost volatility:whey protein concentrate and natural flavor extracts face price swings tied to dairy commodity cycles and weather-driven botanical harvests, squeezing margin predictability for mid-size blenders.
- Supply concentration risk:modified starch and hydrocolloid premix capacity clusters in the US Midwest and Western Europe, creating geographic vulnerability to logistics disruptions and regional energy price spikes.
- Substitution threat:liquid seasoning systems and retort-pouch wet marinades are capturing share in snack food applications where moisture tolerance allows, displacing traditional dry rubs in some savory categories.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and Kenya present white space for fortified flour and micronutrient premixes as national food fortification mandates expand beyond iodized salt to vitamin A and iron blends.
- Regulatory tailwind from EU Green Deal:carbon footprint disclosure requirements under CSRD are creating procurement preference for regional blending operations with renewable energy sourcing and reduced transport emissions.
- Sports nutrition personalization:direct-to-consumer brands are converging AI-driven formulation tools with micro-batch blending capabilities, enabling individualized amino acid ratios and adaptogen combinations at scale.
Industry Challenges
- Specialized blending technician scarcity:operational expertise in gravimetric dosing, powder flow characterization, and allergen segregation protocols remains concentrated among legacy compounders, constraining capacity expansion timelines.
- Legacy MES integration friction:paper-based batch records and siloed quality systems in established facilities impede real-time traceability mandates, requiring costly ERP overlays to achieve FSMA-compliant electronic documentation.
- Cross-contamination certification delays:third-party audits for gluten-free, kosher, and halal status create 6-12 month qualification backlogs, bottlenecking new product launches for contract manufacturers serving multiple dietary certification tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Blended Products Market |
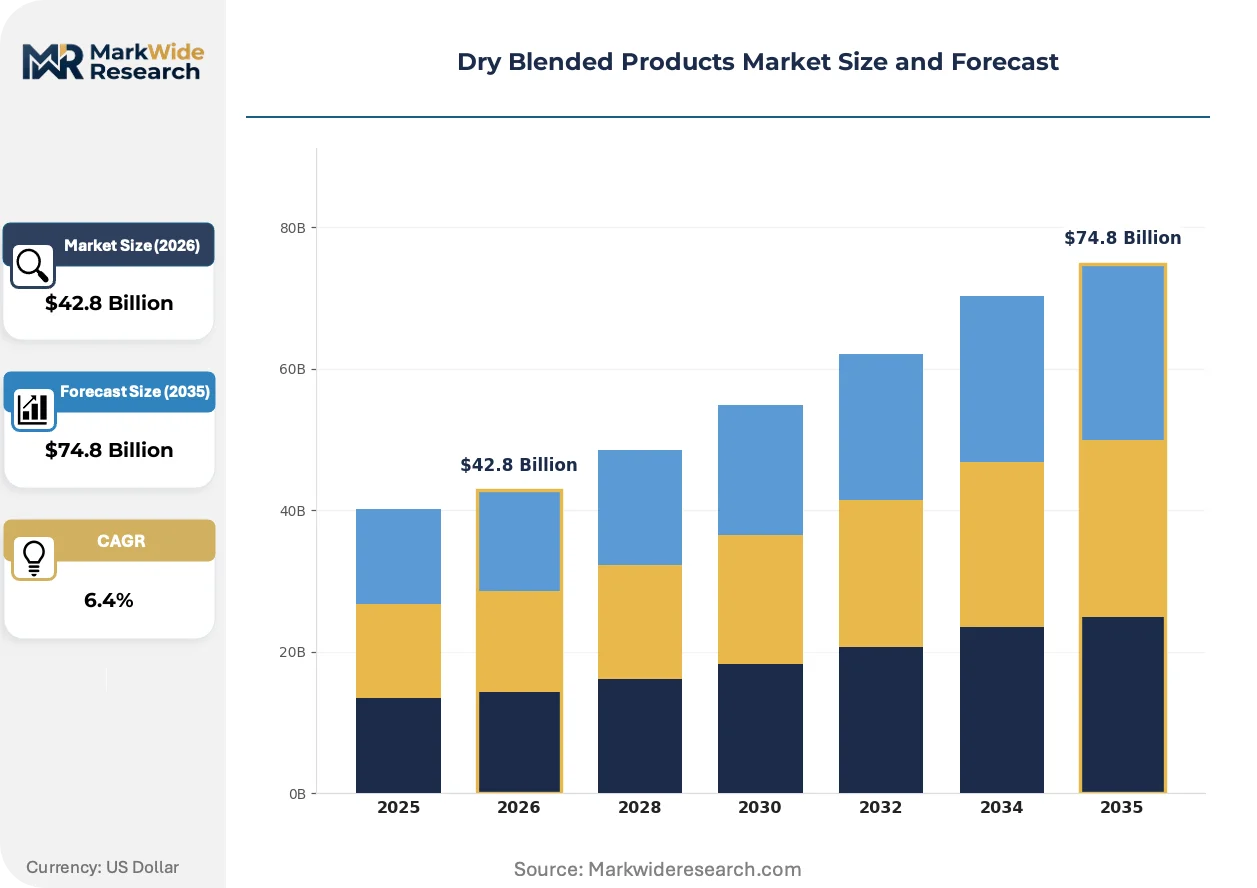
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
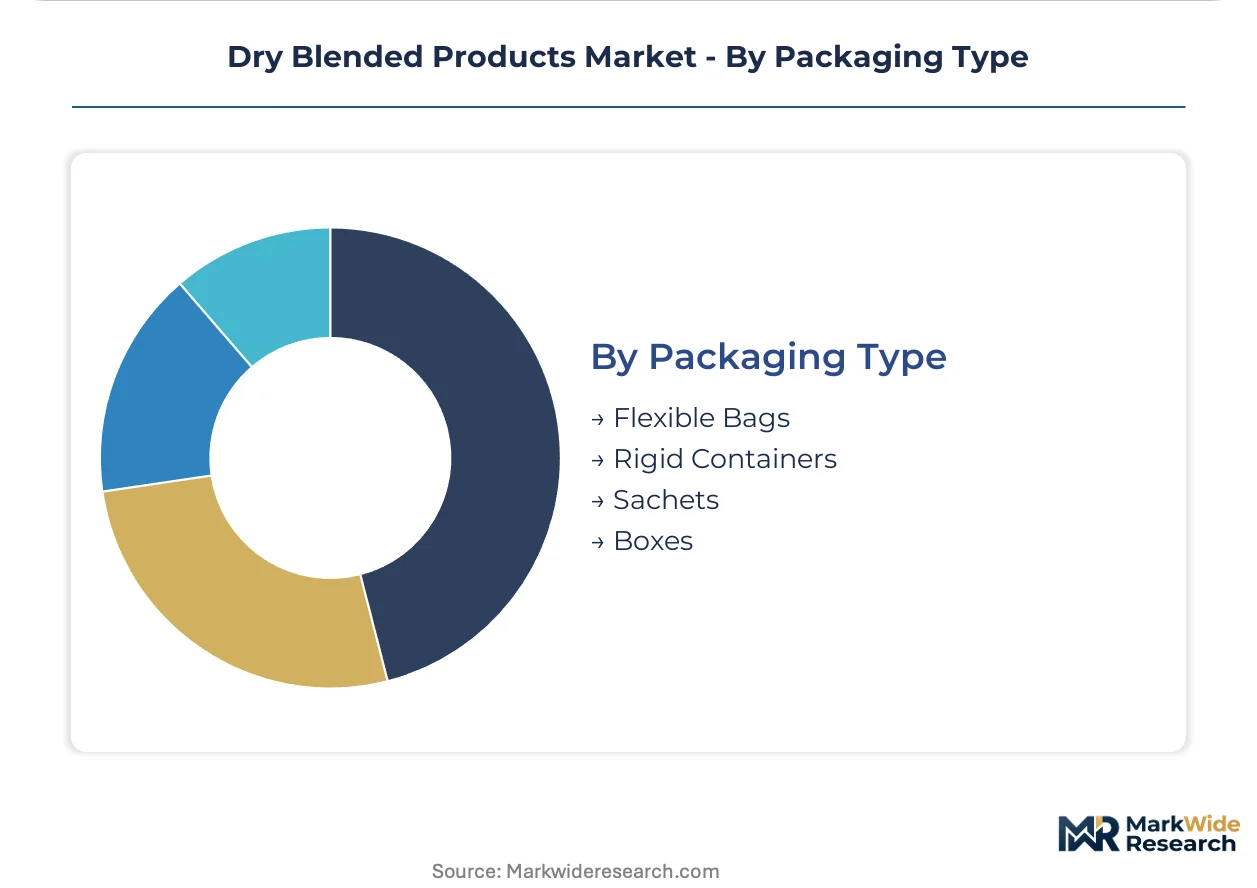
| Segmentation | Product Type: Seasoning, Flavoring, Protein Powder, Baking Mixes End User: Food Manufacturers, Beverage Companies, Restaurants, Households Application: Snack Foods, Dairy Products, Ready Meals, Sauces Packaging Type: Flexible Bags, Rigid Containers, Sachets, Boxes |
| Companies Covered | Ingredion Incorporated, Cargill Incorporated, Archer Daniels Midland Company, Bunge Limited, Tate & Lyle, Olam International, Associated British Foods, Fonterra Co-operative Group Limited, SunOpta Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Blended Products Market Shifts & Advancements
Active reformulation cycles are compressing product lifecycles across savory and nutrition categories, with digital blending controls and sustainability-linked procurement emerging as the primary vectors of competitive differentiation.
Continuous blending systems with inline NIR spectroscopy are collapsing the traditional batch-to-batch quality assurance timeline by enabling real-time moisture and particle size adjustment during production rather than post-blend testing. Snack food manufacturers in the US and Mexico are adopting these systems at replacement cycle pace, compressing lead times from formulation approval to commercial scale from weeks to days and eroding the inventory-holding advantage of large centralized compounders.
EFSA's updated guidance on novel food additive safety assessments is tightening the evidentiary threshold for enzyme-modified starches and encapsulated flavor carriers used in dry seasoning matrices. The industrial consequence is extended pre-market authorization timelines and elevated toxicology study costs for European suppliers, with reformulation activity concentrating on grandfathered ingredients while novel delivery systems face commercialization delays of 18-24 months.
Consolidated procurement desks at multinational food manufacturers are unbundling technical service from ingredient supply, awarding blending contracts to lowest-unit-cost compounders while retaining in-house formulation IP. This disintermediation of R&D support is most visible in North American protein powder contract manufacturing, where brands now specify exact amino acid profiles and sweetener systems rather than relying on supplier-developed base matrices, compressing value capture at the blending tier.
Dry Blended Products Market Segmentation
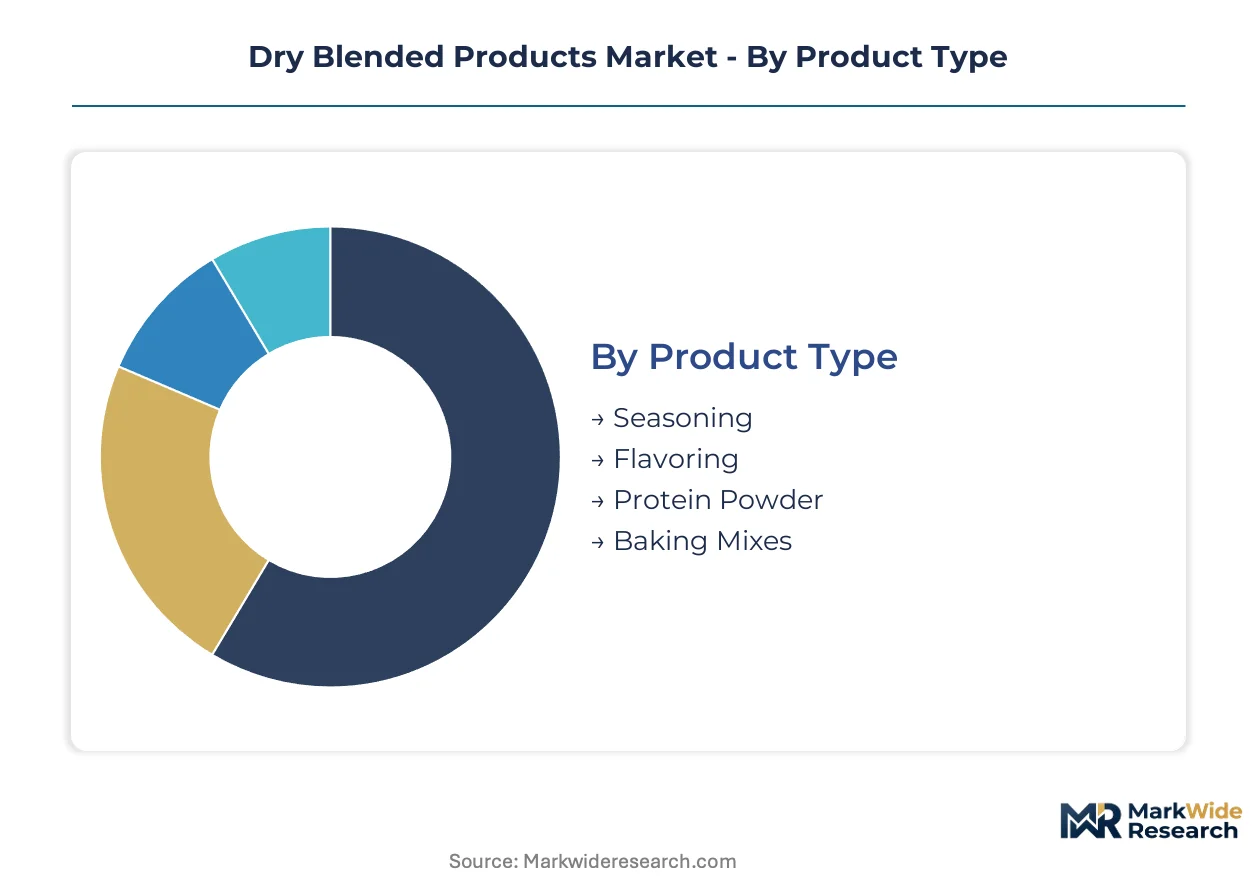
Dry blended products fragment across four distinct dimensions, each carrying divergent margin profiles and regulatory exposure. Understanding these fault lines reveals where formulation complexity commands premium pricing versus where scale economies dominate procurement decisions.
Product Type:
Cost tier stratification separates commodity-grade blends from precision-compounded nutritionals, with formulation complexity determining margin capture.
- Protein Powder:Neutral-flavor pea and rice isolates require particle size standardization below 200 microns for mouthfeel consistency. Sports nutrition brands in North American direct-to-consumer channels are specifying exact amino acid profiles rather than accepting supplier-developed base matrices, pulling high-margin custom volumes from generic compounders.
- Seasoning:Clean-label reformulations eliminating maltodextrin and silicon dioxide anti-caking agents demand specialized flow agents and encapsulation technologies. Quick-service restaurant chains are consolidating procurement around toll-manufacturers with dedicated allergen segregation protocols.
- Flavoring:Encapsulated volatile oil carriers and spray-dried natural extracts face extended EFSA pre-market timelines.
- Baking Mixes:Leavening system stability and gluten-free certification requirements concentrate production among legacy compounders with established third-party audit relationships.
Protein powder commands the established base. The steepest expansion runs through seasoning.
End User:
Customer type determines service intensity, with institutional buyers unbundling technical support from ingredient supply while household channels demand finished-format convenience.
- Food Manufacturers:Procurement desks at multinational ready-meal producers are retaining in-house formulation IP while awarding blending contracts to lowest-unit-cost compounders, compressing value capture at the supply tier.
- Restaurants:Proprietary spice blend specifications for chain consistency require micron-level particle distribution and shelf-life stability testing.
- Beverage Companies:Instant drink premixes with cold-water solubility specifications face hydrocolloid sourcing constraints.
- Households:Single-serve sachet formats and clean-label claims are reshaping retail assortment toward premium-positioned convenience.
Food manufacturers anchor volume demand. Restaurants are gaining share fastest.
Application:
Application maturity dictates growth trajectory, with convenience-oriented formats outpacing traditional categories as portion-control and shelf-stability priorities reshape formulation requirements.
- Ready Meals:Plant-based protein premixes for meat-analogue applications require neutral flavor masking and texturant synergy with modified starches.
- Snack Foods:Continuous blending systems with inline NIR spectroscopy are collapsing batch-to-batch quality assurance timelines from weeks to days.
- Dairy Products:Fortified milk powder and yogurt premixes face whey protein concentrate price volatility tied to dairy commodity cycles.
- Sauces:Dry gravy and dressing bases compete with liquid seasoning systems where moisture tolerance allows.
Snack foods hold the volume base. Ready meals are climbing the fastest.
Packaging Type:
Packaging configuration directly determines distribution economics and shelf-life performance, with barrier properties and format flexibility driving procurement segmentation.
- Flexible Bags:Multi-layer laminates with oxygen scavengers dominate bulk food-service distribution.
- Sachets:Single-serve portions for hospitality and airline channels require precise fill-weight consistency.
- Rigid Containers:Reclosable formats command retail premium positioning.
- Boxes:Carton-based secondary packaging for retail shelf presence.
Flexible bags represent the incumbent standard. Sachets are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: India and China favor protein fortification for mass-market staples, while the United States and Germany concentrate premium spend on sports nutrition and clean-label seasonings for foodservice chains.
United States
Quick-service restaurant chains drive proprietary seasoning blend procurement with strict micron-level particle specifications. FDA preventive controls under FSMA mandate electronic batch records and supply chain verification, elevating compliance costs. Continuous blending clusters in Illinois and California leverage inline NIR spectroscopy to collapse formulation-to-scale timelines from weeks to days.
India
Plant-based ready-meal manufacturers scale neutral-flavor protein premix sourcing as flexitarian diets expand in urban retail. BIS certification harmonization with Codex Alimentarius reduces export friction, while the PLI scheme for food processing draws toll-manufacturing investment near Mumbai and Hyderabad. Toll-manufacturing clusters in Maharashtra and Telangana now host international ingredient suppliers establishing regional blending capacity.
Germany
Sports nutrition brands specify exact amino acid profiles and sweetener systems, disintermediating supplier-developed base matrices. EFSA additive regulations tighten evidentiary thresholds for novel encapsulation technologies, extending pre-market timelines. Modified starch and hydrocolloid premix production concentrates in North Rhine-Westphalia and Bavaria, creating geographic exposure to regional energy price volatility.
China
Instant beverage and dairy fortification applications absorb micronutrient premix volumes as national nutrition improvement programs expand. SAMR food safety standards impose traceability requirements that accelerate ERP system adoption among compounders. Blending capacity clusters in the Yangtze River Delta and Shandong Peninsula serve both domestic retail and export-ready food manufacturers.
Brazil
Snack food manufacturers adopt dry seasoning systems for shelf-stable portion-controlled formats targeting convenience-oriented consumers. ANVISA food additive regulations govern encapsulated flavor carriers and enzyme-modified starches used in savory matrices. Grain-based blending operations in São Paulo and Minas Gerais leverage captive supply of corn and soy derivatives from adjacent agricultural processing.
Dry Blended Products Market Competitive Landscape
Capability concentration sits with legacy compounders possessing third-party audit relationships and allergen segregation protocols; scale advantage sits with diversified agricultural processors with captive raw material supply. The supplier base bifurcates between FSMA-compliant operations with electronic traceability systems and commodity blenders facing exit pressure from preventive control mandates. Three archetypes dominate: integrated agricultural processors with backward integration into spice and protein blending, specialized toll-manufacturers with dedicated allergen segregation facilities, and regional compounders serving quick-service restaurant chains with proprietary formulation IP. Competitive moves center on toll-manufacturing partnerships near demand clusters and unbundling of technical service from ingredient supply to capture lowest-unit-cost procurement awards.
Among North American ingredient suppliers, Ingredion Incorporated and Cargill Incorporated occupy positions reflecting divergent strategic anchors: the former exemplifies the R&D-intensive modified starch and protein premix specialist with dedicated technical facilities, while the latter represents the integrated agricultural processor leveraging oilseed processing infrastructure into downstream seasoning compounding. Archer Daniels Midland Company sits within the South American grain-based blending tier, its position deriving from captive supply chain integration rather than standalone compounding expertise. These three names illustrate how geographic raw material access, regulatory compliance capability, and customer relationship intensity separate sustainable competitive position from commodity pressure.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Bunge Limited |
| Tate & Lyle |
| Olam International |
| Associated British Foods |
| Fonterra Co-operative Group Limited |
| SunOpta Inc. |
| Others |
Supply & Pricing Matrix
Freight corridors connecting US Midwest grain terminals to East Coast blending facilities carry cost volatility that concentrates pricing power among compounders with captive rail contracts, while downstream buyers face tiered cost structures tied to certification tiers and volume commitments.
Pricing Analysis
Long-term offtake agreements dominate procurement between multinational food manufacturers and established compounders, insulating volume buyers from whey protein concentrate and natural extract commodity swings. Pricing stratifies across premium, standard, and economy tiers based on FSMA compliance certification and custom formulation complexity. Cost compression in mid-tier seasoning blends is intensifying as quick-service restaurant chains consolidate procurement around lowest-unit-cost toll-manufacturers. Food manufacturers exhibit highest price sensitivity due to unbundled technical service expectations, while sports nutrition brands tolerate premium positioning for exact amino acid profile specifications.
Supply Chain Analysis
Upstream feedstock supply draws from corn and soy derivatives concentrated in the US Midwest, modified starch production in Western Europe, and spice sourcing clusters in India. Key inputs include pea protein isolate, rice protein concentrate, encapsulated flavor carriers, and hydrocolloid texturants. Single-source vulnerability concentrates in Midwest grain processing infrastructure exposed to regional energy price spikes. Distribution runs through bulk flexible bag formats for food-service channels and single-serve sachets for hospitality and direct-to-consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Operational expertise in gravimetric dosing, allergen segregation protocols, and powder flow characterization remains trapped within legacy compounders, creating bottlenecks that constrain capacity expansion and elevate acquisition premiums for qualified facilities.
For Market Incumbents: Harden electronic traceability infrastructure to preempt FSMA enforcement escalation, embedding inline NIR spectroscopy and ERP-integrated batch records that commodity blenders cannot replicate. Expand toll-manufacturing footprint near Mumbai and Hyderabad to capture PLI scheme incentives and BIS certification harmonization tailwinds before regional capacity saturates. For New Entrants and Emerging Players: Establish a beachhead in African fortified flour and micronutrient premix segments where national food fortification mandates are expanding beyond iodized salt. Target Nigeria and Kenya with AI-driven micro-batch blending capabilities for personalized sports nutrition, leveraging direct-to-consumer channels that bypass entrenched food manufacturer procurement desks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized toll-manufacturers with dedicated allergen segregation facilities and established third-party audit relationships over integrated agricultural processors facing margin compression. Watch for inflection signals in cross-contamination certification backlogs, as six-to-twelve month qualification delays indicate capacity constraints that elevate acquisition multiples for pre-qualified assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Protein Processing | Oilseed processors in Illinois and Iowa secure margin control over pea and rice isolate supply chains. |
| Toll-Manufacturing Cluster Expansion | International suppliers near Mumbai leverage BIS certification alignment to reduce export friction into Middle Eastern markets. |
| Continuous Blending System Adoption | Inline NIR spectroscopy collapses formulation-to-scale timelines from weeks to days for US snack food manufacturers. |
| Clean-Label Reformulation Partnership | Quick-service restaurant chains eliminate maltodextrin and silicon dioxide through specialized encapsulation technology licensing. |
| Carbon Footprint Disclosure Certification | Regional blending operations with renewable energy sourcing capture procurement preference under EU Green Deal and CSRD mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with food manufacturing procurement directors, quick-service restaurant chain supply chain managers, toll-manufacturing facility operators, and regulatory compliance officers at compounders across the United States, India, Germany, and Brazil. Secondary validation drew from FDA FSMA guidance documents, EFSA additive safety assessments, BIS food-grade standards, customs and trade flow data, and SEC filings from publicly traded ingredient suppliers. Bottom-up volume estimates by product type and application were triangulated against top-down market sizing derived from production capacity assessments and end-use consumption patterns.
Calibration against historical price indices for whey protein concentrate, modified starch, and natural flavor extracts anchored growth trajectory assumptions across the analysis window. Segmentation modeling incorporated product type, end user archetype, application, and packaging format dimensions, with regional regulatory clusters treated as distinct demand environments. CAGRs were computed from fitted trend lines applied to validated base-year consumption estimates, with cross-checks against capacity expansion announcements and import-export parity calculations.
Stress conditions across dairy commodity cycle volatility, energy price spikes in European production clusters, and logistics disruption scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding BIS certification harmonization timelines, FSMA enforcement intensity, and flexitarian dietary shift penetration rates. Cross-checking against customs trade data and regional production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
South America Feed Yeast Market
Ingredients
Asia Pacific Feed Yeast Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Acetylated Starch Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Peanut Ingredients Market
Ingredients
Multi-Grain Premixes Market
Ingredients
Vitamin D Ingredients Market
Ingredients
Gymnema Extract Market
Ingredients
Global Whey Protein Ingredients Market
Ingredients
Desiccated Coconut Market
Ingredients
Omega 3 Ingredients Market
Ingredients
Macleaya Cordata Extract Market
Ingredients
Stock Cubes Market
Ingredients
Specialty Yeast Market
Ingredients
Potato Granules Market