
 North America Soy Protein Market | 2026-2036
North America Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
North America Soy Protein Market Analytics
Foodservice distributors and plant-based meat startups are reorganizing procurement priorities toward higher-protein soy isolates and concentrates. Archer Daniels Midland Company leverages its vertical crushing and extraction network across the U.S. Midwest to anchor supply security for industrial buyers. Cargill Incorporated competes through its non-GMO and organic soy protein lines, while DuPont de Nemours, Inc. specializes in functional protein systems for dairy alternative applications.
Soy protein comprises refined or textured preparations of defatted soybean meal containing protein concentrations ranging from approximately fifty percent in flour to over ninety percent in isolates, produced through aqueous extraction, isoelectric precipitation, or extrusion cooking to achieve specific functional properties such as emulsification, gelation, and water binding for food manufacturing. Textured soy protein dominates volume flows into meat alternative applications where fiber alignment and chew structure command premium positioning. Soy protein isolate captures the fastest growth trajectory within dairy alternatives and nutritional supplements, where solubility and neutral flavor profiles justify higher unit economics. Soy concentrate maintains mature demand in bakery and snack applications where moderate protein enrichment meets cost-sensitive formulation targets.
The FDA governs protein content claims and allergen labeling under the Food Allergen Labeling and Consumer Protection Act, while USDA oversees soy protein inclusion in school nutrition programs and meat product standards. Canada's Health Canada and PMRA coordinate with the FDA on cross-border ingredient approvals, creating aligned but distinct compliance pathways for suppliers operating across both jurisdictions. Stakeholders must monitor evolving protein quality scoring methodologies and state-level clean-label mandates that could shift formulation specifications faster than federal rulemaking cycles.
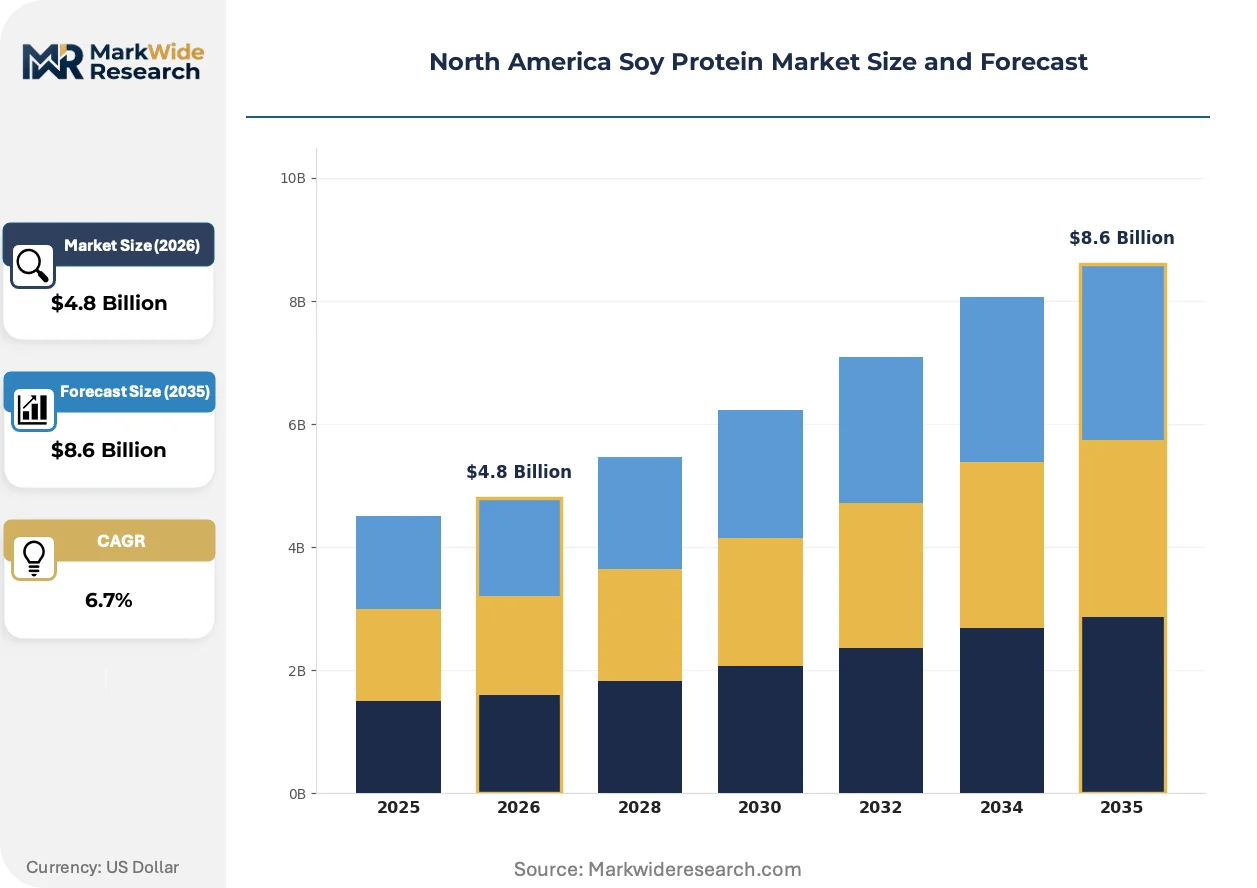
Market Dynamics
The FDA's updated protein labeling requirements are forcing plant-based meat manufacturers to reformulate around higher-protein soy isolates, concentrating procurement power among Midwestern crushing facilities with extraction capabilities.
Growth Catalysts
- USDA School Nutrition Standards:Expanded soy protein inclusion in K-12 meal programs creates institutional volume anchors for concentrate suppliers.
- Midwest Crushing Infrastructure:Iowa and Illinois soybean processing clusters enable just-in-time isolate delivery to meat alternative manufacturers.
- Extrusion Cooking Advances:High-moisture extrusion technology improves fiber alignment in textured proteins, narrowing sensory gaps with animal muscle tissue.
Market Restraints
- Input Cost Volatility:Soybean meal prices fluctuate with drought cycles in Argentina and Brazil, compressing isolate margins.
- Supply Concentration Risk:Three Midwestern states control over seventy percent of North American crushing capacity, creating geographic vulnerability.
- Allergen Labeling Burden:The Food Allergen Labeling and Consumer Protection Act mandates prominent soy disclosure, limiting clean-label positioning.
Strategic Opportunities
- Canadian Regulatory Alignment:Health Canada's coordinated ingredient approvals with the FDA streamline cross-border supplier expansion.
- Sports Nutrition Formulation:Neutral-flavor isolates penetrate ready-to-drink protein beverages previously dominated by whey.
- Precision Fermentation Convergence:Hybrid products combining soy protein scaffolding with fermented fats target premium meat alternative tiers.
Industry Challenges
- Extrusion Technician Scarcity:High-moisture extrusion operation requires specialized food engineering expertise concentrated at legacy meat processing facilities.
- Organic Certification Timelines:Three-year transition periods for non-GMO soybean sourcing delay organic line launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Soy Protein Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Soy Protein, Soy Protein Isolate, Soy Flour, Soy Concentrate End User: Food & Beverage, Nutritional Supplements, Animal Feed, Pharmaceutical Form: Powder, Granules, Ready-to-Drink, Bars Application: Meat Alternatives, Dairy Alternatives, Bakery Products, Snacks |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Bunge Limited, Kerry Group plc, DuPont de Nemours, Inc., CHS Inc., Wilmar International Ltd., International Flavors & Fragrances Inc., Fuji Oil Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Soy Protein Market Evolving Landscape
Protein extraction technology and regulatory clarity are reshaping competitive positioning between isolate and concentrate tiers, while foodservice procurement models compress supplier qualification cycles.
High-moisture extrusion is bifurcating textured soy protein into two performance tiers: commodity chunks for foodservice and precision-aligned fibers for retail meat alternatives. Plant-based meat startups in California and Texas are adopting the advanced systems fastest. This technology is bifurcating supplier relationships, as equipment-intensive extrusion requires multi-year tolling agreements rather than spot purchasing.
The FDA's updated protein quality scoring methodology is recalibrating label claims across dairy alternative formulations. Manufacturers must now demonstrate PDCAAS equivalence to animal proteins for "excellent source" positioning. Soy isolate suppliers serving oat milk and yogurt applications face the steepest reformulation requirements, with Q3 2024 compliance deadlines accelerating R&D spend.
Foodservice distributors are consolidating soy protein purchasing through category captains rather than fragmented supplier bases. Sysco and US Foods now specify functional protein systems with guaranteed gelation profiles, displacing commodity flour contracts. This consolidation is most visible in the quick-service burger chain segment, where standardized patty specifications demand batch-to-batch consistency.
North America Soy Protein Market Segmentation
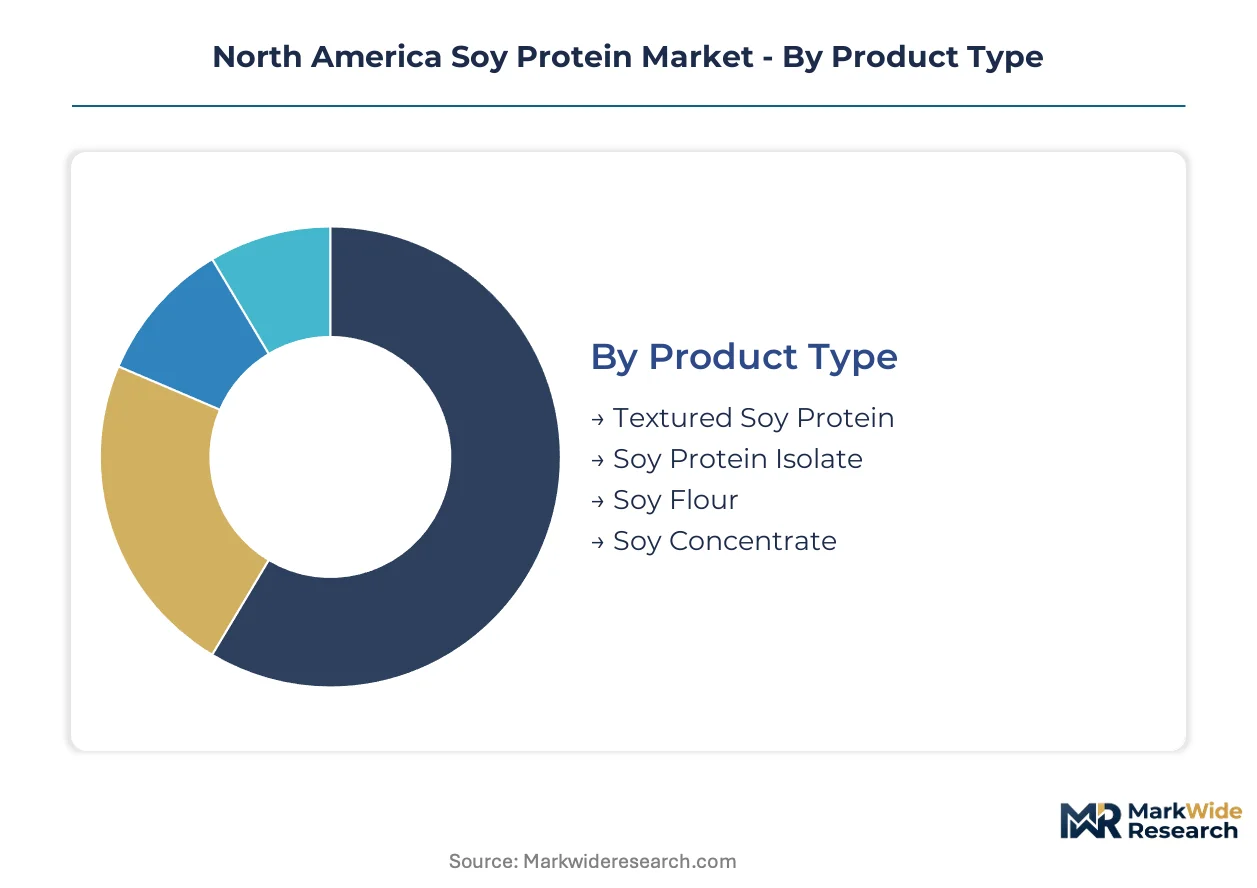
Soy protein segmentation in North America reflects divergent functional requirements across meat and dairy alternatives, with FDA protein quality scoring and USDA school nutrition standards creating distinct procurement tiers for isolates versus concentrates. Manufacturers align product development with these regulatory frameworks to secure label claims and institutional volume contracts.
Product Type:
FDA protein quality thresholds and USDA commodity purchase specifications differentiate isolate and concentrate procurement across institutional and retail channels.
- Textured Soy Protein:Extruded defatted soy flour with fiber alignment engineered through high-moisture extrusion delivers chew structure for plant-based meat applications. Midwestern foodservice distributors in Iowa and Illinois anchor volume procurement for quick-service burger chains where batch consistency commands premium positioning.
- Soy Protein Isolate:Refined to over ninety percent protein through aqueous extraction and isoelectric precipitation, achieving neutral flavor and complete solubility. Dairy alternative manufacturers in California reformulate oat milk and yogurt lines to meet PDCAAS equivalence requirements for "excellent source" claims.
- Soy Flour:Ground whole or defatted soybeans retaining natural oil content for cost-sensitive bakery enrichment.
- Soy Concentrate:Intermediate protein level between sixty-five and ninety percent, serving snack and nutrition bar applications where moderate enrichment meets price targets.
Textured soy protein handles the majority of throughput; soy protein isolate is the fastest mover on share.
End User:
Procurement scale and formulation sophistication separate institutional buyers from specialized health applications.
- Food & Beverage:Plant-based meat startups and established dairy alternative brands drive isolate demand for neutral-flavor, high-solubility systems. Cargill and Archer Daniels Midland anchor supply through Midwestern crushing networks with just-in-time delivery to Texas and California manufacturing clusters.
- Nutritional Supplements:Sports nutrition brands in the Mountain West region adopt soy isolate for ready-to-drink protein beverages, displacing whey in lactose-free positioning. PDCAAS scoring requirements accelerate R&D spend to demonstrate amino acid completeness.
- Animal Feed:Defatted meal byproducts from isolate extraction flow into aquaculture and poultry feed formulations.
- Pharmaceutical:High-purity isolates serve specialized medical nutrition and excipient applications requiring allergen-controlled supply chains.
Food and beverage commands absolute volume; nutritional supplements is expanding most quickly on reformulation activity.
Form:
Processing intensity and convenience positioning stratify margin capture across the value chain.
- Powder:Bulk isolate and concentrate powders dominate ingredient supply to manufacturing facilities, with functional specifications for gelation and emulsification dictating supplier qualification. Sysco and US Foods consolidate purchasing through category captain relationships specifying guaranteed performance profiles.
- Ready-to-Drink:Pre-formulated beverages in aseptic packaging capture premium retail positioning through convenience and portability. California-based brands lead adoption of hybrid soy-fermented fat systems targeting premium meat alternative tiers.
- Granules:Rehydratable textured chunks serve foodservice reconstitution applications.
- Bars:Compressed concentrate and isolate blends with binding systems for sports nutrition and meal replacement positioning.
Powder moves the greatest tonnage; ready-to-drink is climbing the fastest on consumer convenience demand.
Application:
Sensorial benchmarks against animal-derived products determine isolate versus concentrate selection.
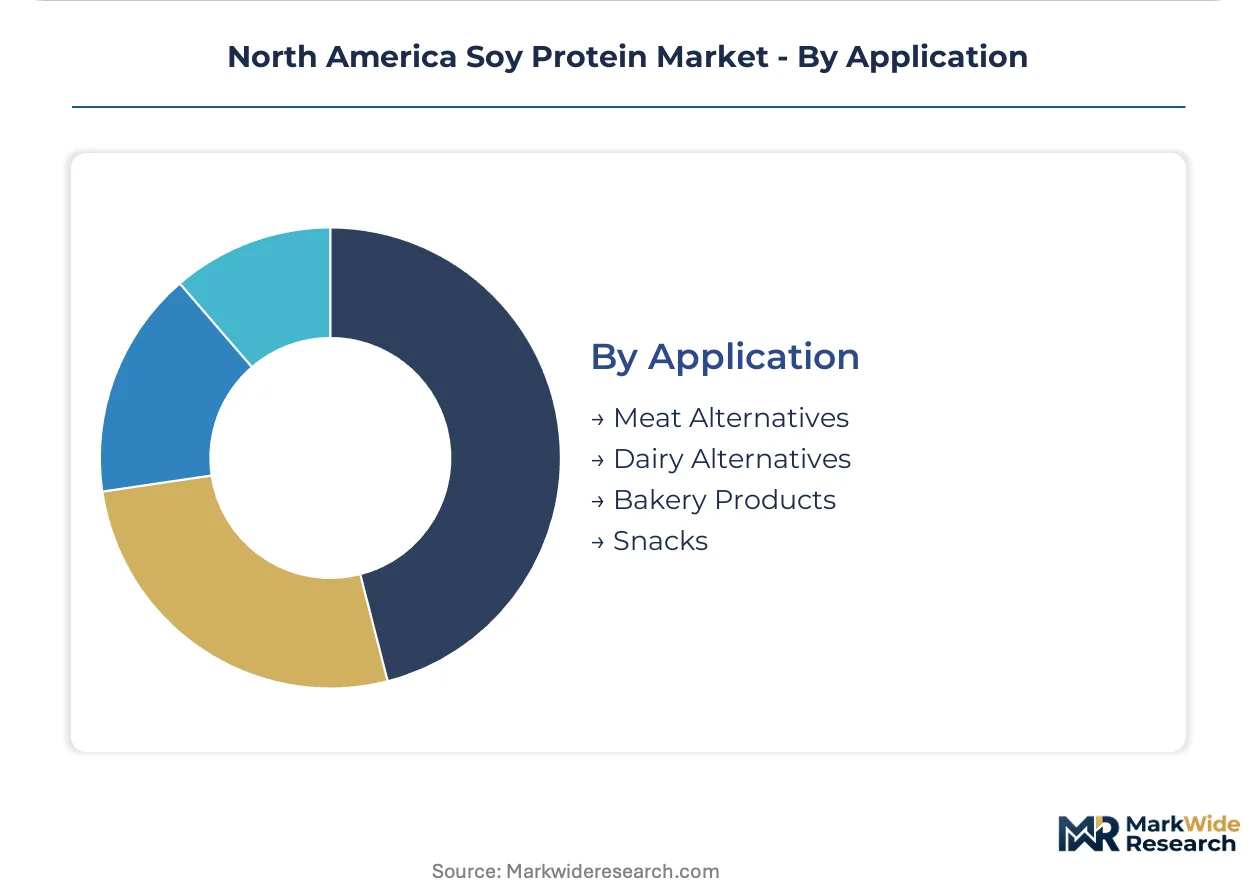
- Meat Alternatives:High-moisture extrusion of textured soy protein achieves fiber alignment and chew structure that narrows sensory gaps with animal muscle tissue. Equipment-intensive processing requires multi-year tolling agreements rather than spot purchasing, concentrating supplier relationships.
- Dairy Alternatives:Soy isolate solubility and neutral flavor enable complete dairy replacement in milk, yogurt, and ice cream applications. FDA's updated protein quality scoring methodology forces reformulation to demonstrate PDCAAS equivalence for premium label positioning.
- Bakery Products:Concentrate and flour grades provide moderate protein enrichment with cost-sensitive formulation targets.
- Snacks:Extruded puffs and crisps leverage textured protein for crunch and satiety claims.
Meat alternatives absorb the largest volume flows; dairy alternatives is gaining share fastest on regulatory-driven reformulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge network and Great Lakes rail corridors anchor North American soy protein logistics, connecting Iowa and Illinois crushing clusters to California dairy alternative manufacturers and Texas meat alternative startups.
United States
Midwestern soybean processing infrastructure in Iowa, Illinois, and Indiana generates over seventy percent of North American isolate and concentrate supply. The FDA's updated protein quality scoring methodology forces California oat milk and yogurt manufacturers to reformulate for PDCAAS equivalence by Q3 2024. Texas plant-based meat startups adopt high-moisture extrusion systems fastest, creating equipment-intensive tolling demand.
Canada
Health Canada coordinates ingredient approvals with the FDA, streamlining cross-border supplier expansion for Ontario and Quebec food processors. The Canadian Grain Commission maintains distinct organic certification pathways that delay three-year transition timelines for non-GMO soybean sourcing. Saskatchewan and Manitoba crushing facilities supply prairie aquaculture feed markets with defatted meal byproducts from isolate extraction.
Mexico
Sonora and Sinaloa soybean production regions feed domestic crushing capacity serving foodservice distributors in Mexico City and Monterrey. COFEPRIS alignment with FDA allergen labeling standards enables integrated North American packaging for export-oriented manufacturers. Jalisco dairy alternative brands source isolate through Laredo-Nuevo Laredo cross-border logistics corridors.
North America Soy Protein Market Competitive Landscape
Concentration sits with diversified agribusiness conglomerates controlling upstream crushing and downstream extraction infrastructure. Three strategic archetypes dominate: integrated processors with captive soybean supply, specialty ingredient formulators targeting functional protein systems, and toll manufacturers operating high-moisture extrusion equipment for contract production. Competitive moves center on multi-year supply agreements locking in isolate volumes and backward integration into organic soybean origination to secure non-GMO certification pipelines.
Within the integrated processor tier, Archer Daniels Midland Company and Cargill Incorporated exemplify scale-driven supply security models, while DuPont de Nemours, Inc. occupies a position among specialty formulators targeting dairy alternative applications. These three anchors represent divergent competitive vectors: crushing network dominance versus functional protein system development.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Bunge Limited |
| Kerry Group plc |
| DuPont de Nemours, Inc. |
| CHS Inc. |
| Wilmar International Ltd. |
| International Flavors & Fragrances Inc. |
| Fuji Oil Group |
| Others |
Value Network & Pricing Analysis
Multi-year offtake agreements between Iowa and Illinois crushing facilities and California dairy alternative manufacturers lock in isolate volumes while capping price volatility exposure for buyers facing FDA protein quality compliance deadlines. These contracts concentrate procurement power among Midwestern processors with aqueous extraction capabilities, squeezing spot-market flexibility for smaller plant-based meat startups.
Pricing Analysis
Volume-discount tiering separates premium organic isolates from standard non-GMO concentrates and economy-grade textured flour for foodservice. Price differentiation hinges on PDCAAS scoring certification and organic transition timelines, with premium tiers commanding spreads based on allergen-controlled supply chains. Cost compression in standard concentrates is intensifying because Argentine and Brazilian drought cycles feed soybean meal volatility. Quick-service burger chains exhibit lowest price sensitivity due to standardized patty specifications, while bakery formulators remain most elastic.
Supply Chain Analysis
Just-in-time inventory preferences dominate among California and Texas plant-based meat manufacturers, though strategic stockpiling of organic-certified soybeans extends lead times for non-GMO line launches. Supply concentrates in Iowa, Illinois, and Indiana, where over seventy percent of North American crushing capacity feeds from domestic soybean origination. Raw material flows draw from defatted meal processing, high-moisture extrusion equipment, and aseptic packaging materials. Single-source vulnerability sits with the Mississippi River barge network. Distribution runs through Sysco and US Foods category captain relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through foodservice distributor consolidation, with Sysco and US Foods displacing fragmented supplier bases and demanding guaranteed gelation profiles that commoditize smaller isolate vendors.
For Market Incumbents: Compound crushing network dominance by locking organic soybean origination contracts in Iowa and Illinois before three-year certification timelines expire, while accelerating high-moisture extrusion capacity to capture tolling demand from California startups facing equipment scarcity. Precision fermentation hybrid products represent the substitute technology threat requiring R&D hedging. For New Entrants and Emerging Players: USDA organic certification fast-tracks market access for isolate suppliers targeting sports nutrition brands in the Mountain West region, where whey displacement creates penetrable white space. White-space targets include ready-to-drink protein beverages and precision fermentation scaffolding partnerships. A co-manufacturing go-to-market angle bypasses capital-intensive extrusion equipment barriers. For Investors and Strategic Acquirers: Capital is best deployed toward toll manufacturers with operational high-moisture extrusion assets and backward integration into organic soybean origination. Long-term viability over the next decade rests on regulatory alignment between FDA and Health Canada streamlining cross-border expansion. The signal to watch is PDCAAS scoring methodology adoption rates across dairy alternative reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Soybean Origination | Three-year certification timelines in Iowa and Illinois secure non-GMO pipeline access ahead of competitor launches. |
| High-Moisture Extrusion Capacity Expansion | Equipment-intensive tolling agreements with California startups capture multi-year contract visibility. |
| USDA School Nutrition Program Certification | K-12 institutional volume anchors provide concentrate demand stability against retail volatility. |
| Health Canada Cross-Border Alignment | FDA-coordinated ingredient approvals streamline Ontario and Quebec processor market entry. |
| Precision Fermentation Hybrid Development | Fermented fat integration with soy protein scaffolding targets premium meat alternative tier positioning. |
Research Methodology
A spread of perspectives from crushing facility operations managers, dairy alternative R&D directors, foodservice procurement leads, and sports nutrition brand formulators converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined structured interviews with secondary validation against FDA labeling guidance documents, USDA commodity purchase specifications, Canadian Grain Commission organic certification records, and SEC filings from publicly traded agribusiness conglomerates. Bottom-up isolate and concentrate tonnage estimates were triangulated against top-down market sizing.
Segmentation dimensions modeled include protein concentration tier, end-use application, form factor, and regional crushing cluster proximity across the projection horizon. CAGRs were derived from trend extrapolation of procurement pattern shifts and regulatory compliance timelines. Industry-specific forecast inputs incorporated high-moisture extrusion adoption curves and PDCAAS scoring methodology implementation rates.
Decision-makers should treat outputs as directional under assumptions of sustained FDA protein quality enforcement and stable Mississippi River logistics capacity; material deviation would warrant model refresh. Revision becomes warranted when Argentine or Brazilian drought severity crosses thresholds that compress soybean meal margins beyond historical ranges.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Fruit and Vegetable Ingredients Market
Ingredients
India Bakery Ingredients Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
Broccoli Powder Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Oyster Peptide Market
Ingredients
Europe Malt Ingredient Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Liquid Malt Extract Products Market
Ingredients
Cacao Extracts Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Low Calorie Cooking Oil Market
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market