
 Potato & Yam Derivatives Market | 2026-2036
Potato & Yam Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Potato & Yam Derivatives Market Analytics
Snack producers is broadening their share of potato derivative offtake as clean-label and extended-shelf-life requirements reshape buyer specifications. McCain Foods leverages its frozen potato infrastructure to supply foodservice chains with consistent flake quality. Lamb Weston anchors North American processing volume through specialized fry-grade potato cultivars. Roquette competes in modified starch applications with plant-based texturizing solutions for meat alternatives.
Potato and yam derivatives encompass starches, flours, flakes, and powders extracted from Solanum tuberosum and Dioscorea species through wet milling, drying, and modification processes; these ingredients function as thickeners, binders, and moisture-retention agents across industrial formulations. Potato starch leads in food processing applications due to its neutral flavor profile and high gelatinization temperature, while yam flour occupies expanding nutraceutical channels driven by resistant starch and prebiotic positioning. Yam powder sustains premium pricing in direct-to-consumer wellness segments where glycemic index claims differentiate finished products.
The FDA governs food additive status and GRAS determinations for modified potato starches in US commerce, while EFSA and REACH compliance shape European import specifications for processed tuber ingredients. BIS standards in India mandate purity thresholds for yam flour sold through wholesale and supermarket channels, directly affecting market access for uncertified suppliers. Stakeholders must monitor evolving allergen labeling requirements and carbon intensity disclosures across multiple jurisdictions to preserve formulation flexibility and channel eligibility.
Market Dynamics
Clean-label reformulation mandates from retail chains are compressing additive approval timelines and forcing snack manufacturers to validate unmodified potato starch performance in extended-shelf-life applications.
Growth Catalysts
- EU Green Deal emissions standards:Food processors in Germany and the Netherlands are retrofitting drying facilities to capture biogas from potato waste streams, cutting Scope 1 emissions while generating captive energy.
- India PLI scheme incentives:Domestic yam flour processors in Odisha and Gujarat are expanding wet-milling capacity to substitute imported tapioca starch in regional bakery formulations.
- Resistant starch positioning:Nutraceutical formulators in North American direct-to-consumer channels are driving yam powder offtake for glycemic management claims backed by clinical validation.
Market Restraints
- Input cost volatility:Fry-grade potato cultivar prices fluctuate with irrigation water allocation disputes between Idaho and Washington state agricultural districts.
- Supply concentration risk:Modified starch hydroxypropylation capacity clusters in the Rhine-Ruhr industrial corridor, exposing buyers to F-Gas Regulation refrigerant phase-out disruptions.
- Substitution threat:Cassava starch from Southeast Asian processors is capturing clean-label bakery accounts through lower gelatinization temperature specifications.
Strategic Opportunities
- Brazil ANVISA novel food pathway:Yam flour producers can access Latin American nutraceutical channels through accelerated prebiotic ingredient registration.
- Cell-cultured meat binders:Potato protein isolate demand is emerging from cultivated meat startups seeking plant-based scaffolding alternatives to soy and pea isolates.
- Direct-to-institution channels:Foodservice distributors in India are bypassing traditional mandi intermediaries to contract yam flour supply directly from Odisha processing clusters.
Industry Challenges
- Specialized drying technician shortage:Flash-drying and drum-drying equipment operation requires skills scarce outside established European and North American processing hubs.
- BIS certification timeline compression:Yam flour purity testing backlog at Indian laboratories is extending market access delays for uncertified domestic entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potato & Yam Derivatives Market |
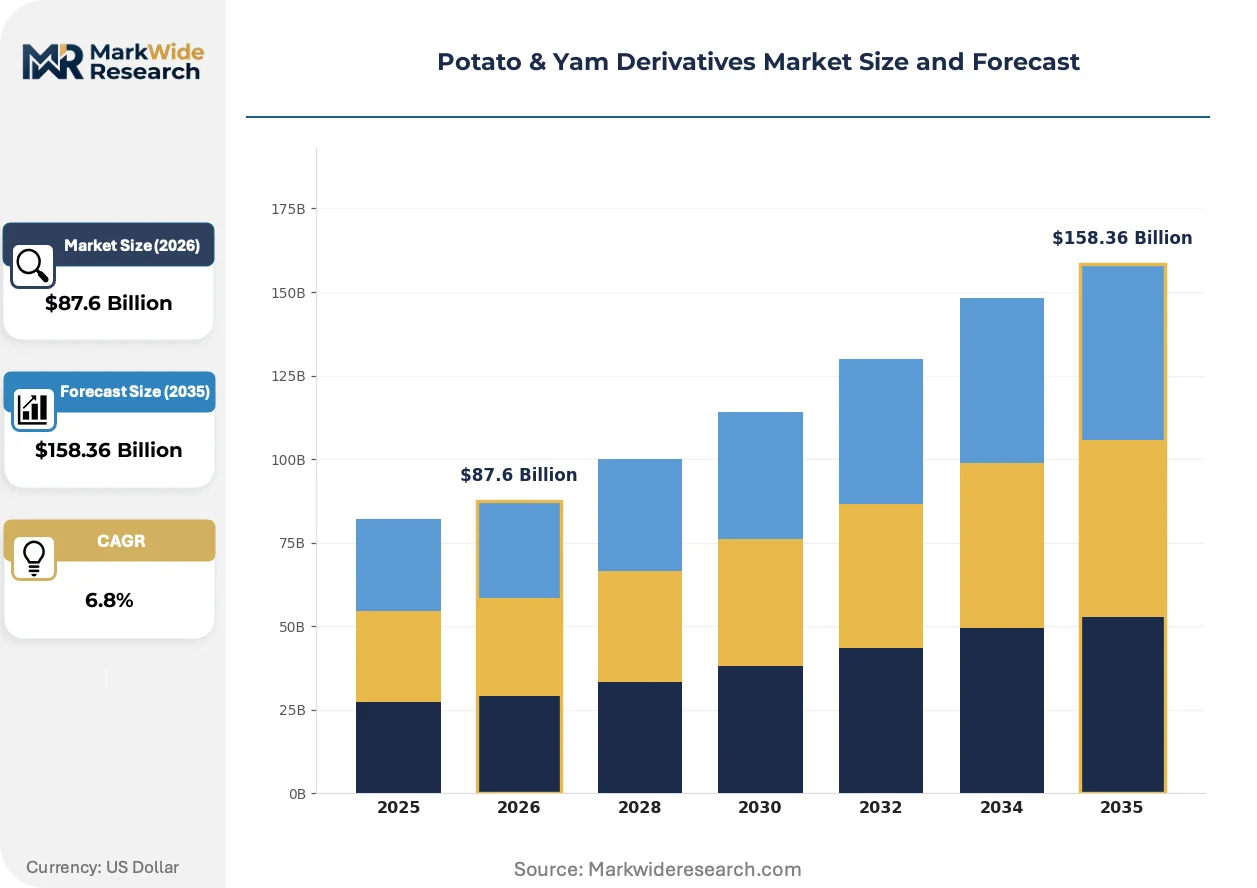
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potato Starch, Yam Powder, Potato Flakes, Yam Flour Application: Food Processing, Animal Feed, Pharmaceuticals, Industrial Uses End User: Beverage Industry, Bakery Sector, Snack Producers, Nutraceuticals Distribution Channel: Direct Sales, Online Retail, Wholesale, Supermarkets |
| Companies Covered | Aviko, Ingredion Incorporated, McCain Foods, Avebe, Tate & Lyle, Lamb Weston, Agrana, Roquette, Simplot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potato & Yam Derivatives Market Evolving Landscape
Processing technology convergence and procurement model fragmentation are reconfiguring how derivative specifications travel from cultivar selection through finished ingredient qualification.
Enzymatic modification is unifying texturizing and shelf-life extension functions in a single potato starch treatment. Snack manufacturers in Mexico and Poland are piloting these dual-function starches to reduce additive line items on ingredient declarations. The technology is unifying previously separate clean-label and performance requirements, compressing supplier qualification cycles.
REACH chemical safety dossier requirements are tightening import documentation for modified starches entering European compound food manufacturing. ECHA substance evaluation timelines are extending pre-market approval periods for hydroxypropylated derivatives. Small-scale Indian and Chinese exporters are diverting volume to Middle Eastern and African markets with less stringent chemical registration frameworks.
Buyer consolidation among North American quick-service chains is compressing potato flake specification variance into single-source contracts with integrated processors. Procurement teams at major foodservice distributors are mandating carbon intensity disclosures alongside traditional quality metrics. The tightest specification compression is visible in fry-grade flake contracts for institutional feeding programs.
Potato & Yam Derivatives Market Segmentation
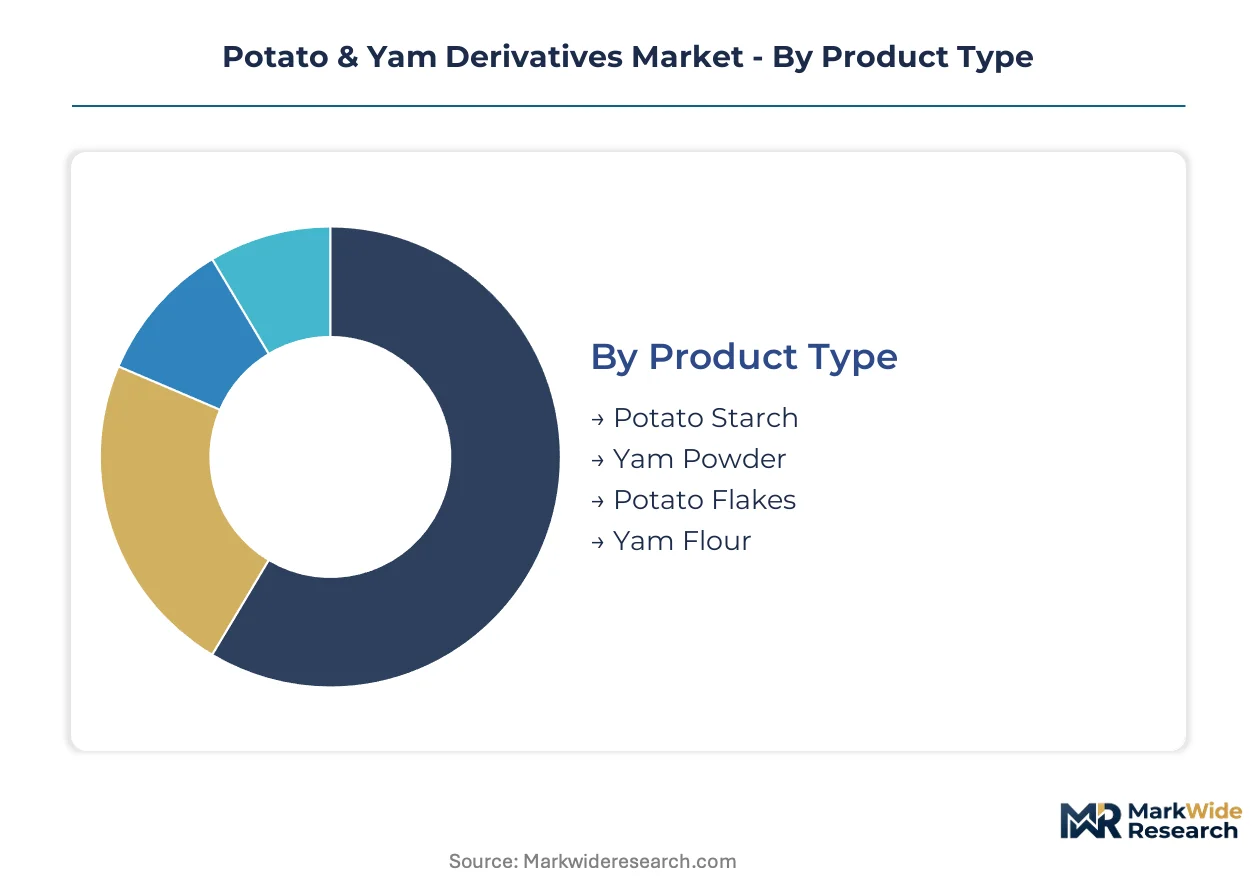
Derivative specifications diverge sharply across buyer categories, with clean-label mandates compressing additive portfolios for snack manufacturers while nutraceutical channels reward glycemic-index positioning. Procurement teams now qualify suppliers against dual criteria: functional performance and carbon intensity disclosure.
Product Type:
Buyers in this category separate by thermal processing requirements and shelf-life extension needs, not commodity sourcing alone.
- Potato Starch:Extracted through wet milling and refined to neutral flavor with high gelatinization temperature; modified variants dominate clean-label snack formulations where McCain Foods and Lamb Weston anchor procurement volume. FDA GRAS determinations and EFSA additive approvals govern cross-border trade specifications.
- Yam Powder:Drum-dried Dioscorea species retaining resistant starch content for prebiotic claims; nutraceutical formulators in North American direct-to-consumer channels sustain premium pricing through clinical glycemic management validation.
- Potato Flakes:Dehydrated mash with standardized flake geometry for institutional foodservice reconstitution.
- Yam Flour:Coarser particle size than powder, occupying regional bakery substitution for tapioca starch in Indian PLI-supported processing clusters.
Volume sits with potato starch; growth tilts toward yam powder.
Application:
Margin capture in this category tracks regulatory burden intensity, with pharmaceutical and food processing commanding qualification premiums over commodity channels.
- Food Processing:Thickeners and binders in soups, sauces, and bakery formulations; EFSA and FDA compliance costs filter supplier pools while REACH dossier requirements extend European approval timelines for hydroxypropylated derivatives.
- Pharmaceuticals:Excipient-grade starches for tablet binding and controlled release; excipient monograph compliance with USP-NF and EP standards creates entry barriers for uncertified Indian and Chinese producers.
- Animal Feed:Carbohydrate energy sources in compound feed rations, price-sensitive to grain substitute economics.
- Industrial Uses:Adhesive and textile sizing applications competing with petrochemical alternatives on volatility spreads.
Food processing absorbs the greatest volume; pharmaceuticals offer the steepest expansion trajectory.
End User:
Specification variance in this category maps to channel concentration, with consolidated quick-service chains compressing variance against fragmented nutraceutical buyers tolerating wider purity ranges.
- Snack Producers:Modified starch offtake for extended shelf-life without synthetic additive declarations; enzymatic modification pilots in Mexico and Poland unify texturizing and preservation functions to reduce ingredient line items.
- Nutraceuticals:Resistant starch positioning for gut health and glycemic management claims; clinical validation requirements differentiate premium yam powder from commodity flour grades.
- Bakery Sector:Volume buyers of native and modified starches for crumb structure and moisture retention.
- Beverage Industry:Limited adoption in dairy alternatives and functional drinks, constrained by solubility specifications.
Snack producers dominate current procurement; nutraceuticals are climbing the fastest.
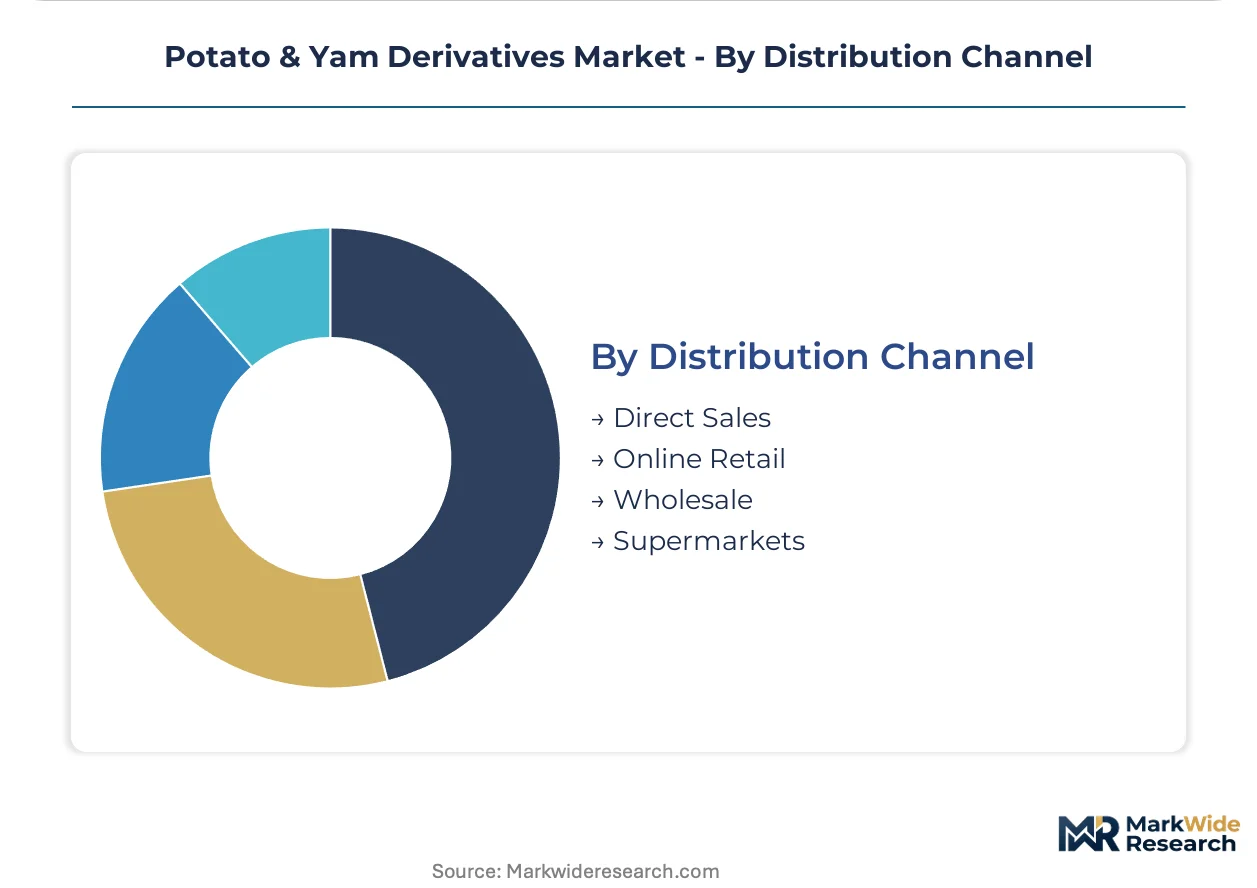
Distribution Channel:
Channel selection in this category reflects buyer scale and certification urgency, with institutional buyers bypassing intermediaries while uncertified entrants rely on wholesale price discovery.
- Direct Sales:Foodservice distributors in India contract yam flour supply directly from Odisha processing clusters, bypassing traditional mandi intermediaries; carbon intensity disclosures now accompany quality metrics in North American quick-service chain contracts.
- Wholesale:BIS-certified yam flour moves through established agri-commodity networks to regional bakery formulators.
- Supermarkets:Packaged consumer formats with label claims driving premium positioning.
- Online Retail:Direct-to-consumer wellness segments for yam powder with glycemic index differentiation.
Direct sales capture institutional volume; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing capacity concentrates in temperate potato-growing belts while tropical yam cultivation feeds regional flour mills. Consumption gravity shifts toward Asian nutraceutical channels and European clean-label manufacturing. Regulatory divergence across jurisdictions fragments supplier qualification requirements.
United States
Idaho and Washington state agricultural districts supply fry-grade potato cultivars to frozen food processors. EPA emissions standards and OSHA workplace safety rules govern drying facility operations. The Pacific Northwest processing corridor anchors modified starch hydroxypropylation capacity serving North American quick-service chains.
Germany
Snack manufacturers retrofit drying facilities to capture biogas from potato waste streams under EU Green Deal mandates. ECHA REACH dossier requirements extend pre-market approval periods for hydroxypropylated derivatives. The Rhine-Ruhr industrial corridor clusters modified starch production exposed to F-Gas Regulation refrigerant phase-out disruptions.
India
Domestic yam flour processors in Odisha and Gujarat expand wet-milling capacity to substitute imported tapioca starch in regional bakery formulations. BIS certification mandates purity thresholds for wholesale and supermarket channels. PLI scheme incentives accelerate processing capacity buildout in Gujarat processing clusters.
Netherlands
Foodservice distributors contract directly with integrated processors for fry-grade flake supply. EFSA additive approvals govern cross-border trade specifications for modified starches. Dutch processing hubs specialize in enzymatic modification pilots unifying texturizing and preservation functions.
Brazil
Nutraceutical formulators access Latin American prebiotic ingredient channels through ANVISA novel food pathways. Yam flour producers target direct-to-consumer wellness segments with glycemic management positioning. São Paulo-based distributors bypass traditional import intermediaries to source from Asian processing clusters.
Potato & Yam Derivatives Market Competitive Landscape
Top-tier vendors anchor integrated processing infrastructure, while mid-tier specialists compete on modification technology and regional sourcing relationships. The market structures around three tiers: multinational ingredient conglomerates with captive cultivar supply, regional processors with BIS or EFSA certification advantages, and niche nutraceutical suppliers with clinical validation capabilities. Strategic moves concentrate on backward integration into cultivar breeding programs and carbon intensity disclosure standardization for institutional procurement.
Among integrated potato processors, McCain Foods and Lamb Weston occupy positions exemplifying frozen infrastructure leverage for flake quality consistency. Roquette represents the plant-based texturizing archetype competing in modified starch applications for meat alternatives. These three anchors illustrate how supplier qualification now requires dual certification against functional performance metrics and emissions disclosure standards.
| Leading Market Players |
|---|
| Aviko |
| Ingredion Incorporated |
| McCain Foods |
| Avebe |
| Tate & Lyle |
| Lamb Weston |
| Agrana |
| Roquette |
| Simplot |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between BIS-certified yam flour and uncertified commodity grades manifests in parallel pricing premiums and supply chain exclusion. Indian wholesale channels enforce this divide through mandatory purity thresholds, while European REACH compliance costs create a second tier of documentation-intensive pricing for hydroxypropylated starches.
Pricing Analysis
Short lead-time premiums dominate contract structures for enzymatically modified potato starches serving Mexico and Poland snack pilots, while spot inventory of native starches trades at discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, carbon disclosure depth, and flake geometry consistency. Cost compression in standard-grade native starch intensifies because cassava substitutes from Southeast Asia undercut gelatinization performance claims. Quick-service chains exhibit lowest price sensitivity through single-source contracts; regional bakery formulators in India show highest sensitivity to tapioca substitution economics.
Supply Chain Analysis
Dual-sourcing requirements now mandate that North American quick-service chains qualify at least two modified starch suppliers despite Rhine-Ruhr concentration of hydroxypropylation capacity. Geographic supply concentrates in Germany, the Netherlands, and the United States for processing infrastructure, while raw tuber sourcing draws from Idaho-Washington districts and Odisha-Gujarat clusters. Input dependencies rest on fry-grade cultivar availability, F-Gas compliant refrigerant access, and drum-drying equipment spares. Single-source vulnerability looms where flash-drying technician scarcity constrains capacity expansion. Distribution runs through direct institutional contracts in India and foodservice distributor networks in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic modification technology is displacing legacy dual-additive systems in clean-label snack formulations, compressing supplier qualification cycles and reconfiguring competitive advantage around unified texturizing-preservation performance.
For Market Incumbents: Hedge against cassava starch substitution by accelerating backward integration into fry-grade cultivar breeding programs in Idaho and Washington agricultural districts. Secure F-Gas Regulation-compliant refrigerant supply contracts in Rhine-Ruhr facilities before phase-out deadlines strand hydroxypropylation capacity. Carbon intensity disclosure standardization represents the priority lever for preserving institutional procurement relationships against emerging European competitors. For New Entrants and Emerging Players: Small-scale nutraceutical formulators in Brazil represent the most penetrable buyer archetype given ANVISA novel food pathway acceleration and limited domestic resistant starch supply. Target direct-to-consumer wellness channels with clinical glycemic management validation rather than competing on commodity flour pricing. Go-to-market positioning should emphasize prebiotic ingredient registration expertise as a service layer alongside yam powder supply. For Investors and Strategic Acquirers: Re-rating potential sits with Indian yam flour processors holding BIS certification and PLI scheme incentives given domestic substitution tailwinds against imported tapioca starch. Long-term viability over a five-to-ten-year window favors processors with captive wet-milling capacity in Gujarat and Odisha clusters. Monitor BIS laboratory testing backlog resolution as the signal indicating market access acceleration for certified entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivar Breeding | McCain Foods and Lamb Weston secure fry-grade supply consistency against irrigation allocation disputes. |
| Enzymatic Modification Capacity Buildout | Roquette and Avebe capture clean-label snack reformulation mandates in Mexico and Poland pilot programs. |
| BIS Certification Fast-Track Investment | Domestic Indian processors unlock wholesale and supermarket channel access ahead of uncertified competitors. |
| Biogas Capture Facility Retrofit | German and Dutch processors align with EU Green Deal emissions standards while generating captive energy. |
| Direct-to-Institution Channel Development | Odisha processing clusters bypass mandi intermediaries to capture foodservice distributor contracts in India. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with snack manufacturer procurement directors, yam flour processing plant managers, and nutraceutical formulator R&D leads combined with secondary validation from FDA GRAS determinations, EFSA additive approval databases, and BIS certification registries. Bottom-up capacity modeling across Odisha and Gujarat processing clusters triangulated against top-down consumption estimates derived from regional bakery substitution trends.
Data-stream reconciliation across wet-milling capacity surveys, cultivar yield statistics, and modified starch trade flows informed the analytical framework. Segmentation dimensions modeled include product type, application, end-user category, and distribution channel across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections incorporating PLI scheme incentive uptake rates and clean-label reformulation penetration curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to F-Gas Regulation phase-out timing, BIS laboratory backlog resolution, and cassava starch price volatility. Deviation in EU Green Deal emissions enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Food Minerals Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Global Malt Ingredients Market
Ingredients
Beef Concentrate Market
Ingredients
Virginiamycin Market
Ingredients
Corn Gluten Meal Market
Ingredients
Low Fat Cooking Oil Market
Ingredients
Agar Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
South America Fats and Oil Market
Ingredients
South America Phytosterols Market
Ingredients
Kilned Malt Market
Ingredients
Coconut Flour Market
Ingredients
Cheese Powder Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Ground-Nut Oil Market