
 North America Gums Market | 2026-2036
North America Gums Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gums Market Insights
Convenience store distribution is reconfiguring as impulse-buy placement strategies shift toward checkout-adjacent premium SKUs. Mondelēz International Inc. leverages its shelf-space dominance to sustain front-of-store visibility across major pharmacy chains. Mars Incorporated anchors its position through backward integration into gum base resin sourcing. Wrigley's competes on flavor longevity technology, differentiating its pellet formats from standard stick alternatives.
Gums comprise polymeric elastomer bases—typically polyvinyl acetate, natural chicle, or styrene-butadiene rubber—plasticized with resins and waxes, then sweetened and flavored for mastication or functional delivery. Chewing gum formulations rely on precise glass-transition temperatures between 15°C and 35°C to maintain chew texture across climate zones. Functional gums represent the fastest-expanding product type, with active-ingredient incorporation driving margin pools above conventional confectionery tiers. Gummy candies remain the volume leader, though formulation costs for clean-label gelatin alternatives are compressing producer margins.
FDA GRAS self-affirmation requirements, Health Canada's Natural Health Product Directorate regulations, and EPA industrial chemical reporting standards collectively shape ingredient approval timelines and cross-border shipment compliance. The PUR Company Inc. positions its aspartame-free portfolio to navigate tightening additive scrutiny from both regulators. Stakeholders must monitor state-level sugar-tax proposals and federal synthetic dye restriction movements to anticipate reformulation investment cycles.
Market Dynamics
Functional ingredient integration is compressing traditional confectionery margins while expanding addressable revenue pools in pharmaceutical and nutraceutical adjacencies across the United States and Canada. FDA GRAS self-affirmation protocols and Health Canada's Natural Health Product Directorate timelines are extending product development cycles by 12-18 months for novel delivery formats.
Growth Catalysts
- Sugar-tax momentum:State-level levy proposals in California and New York are accelerating aspartame-free and xylitol-heavy reformulations. Manufacturers pivoting early capture shelf-space premiums in pharmacy channels.
- Functional delivery systems:Active-ingredient incorporation into gum matrices enables nicotine cessation, caffeine delivery, and vitamin supplementation. Pharmaceutical partnerships expand beyond traditional confectionery buyers.
- Clean-label gelatin alternatives:Pectin and carrageenan substitution addresses vegetarian and halal demand concentrations in Toronto and Chicago metropolitan corridors. Ingredient suppliers scale capacity to match pull-through.
Market Restraints
- Resin supply concentration:Gum base elastomer sourcing clusters with three petrochemical suppliers in the US Gulf Coast. Hurricane-season disruption risk elevates working capital requirements.
- Plasticizer cost volatility:Paraffin wax and polyvinyl acetate prices track crude oil indices with 60-day lag. Formulation cost hedging remains underdeveloped among mid-tier producers.
- Chew-texture technical limits:Glass-transition temperature maintenance across 15°C to 35°C range fails in extreme humidity zones. Product returns concentrate in southeastern US distribution.
Strategic Opportunities
- Underpenetrated Canadian functional segment:Health Canada approval pathways for natural health product gums remain 40% less congested than FDA equivalents. Early entrants secure monograph positioning.
- Convenience channel premiumization:Checkout-adjacent placement strategies shift toward pellet formats with extended flavor release. Impulse-buy margins exceed standard stick alternatives by double digits.
- Synthetic dye restriction tailwinds:California Assembly Bill 418 momentum drives botanical colorant adoption. Spirulina and beetroot extract suppliers scale to replace FD&C certifications.
Industry Challenges
- Flavor chemist talent scarcity:Extended-release formulation expertise concentrates with three specialist firms. In-house capability building requires 24-month training cycles.
- Cross-border compliance friction:EPA industrial chemical reporting standards and PMRA import documentation create shipment delays at Detroit and Buffalo crossings. Dual-track quality systems inflate overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gums Market |
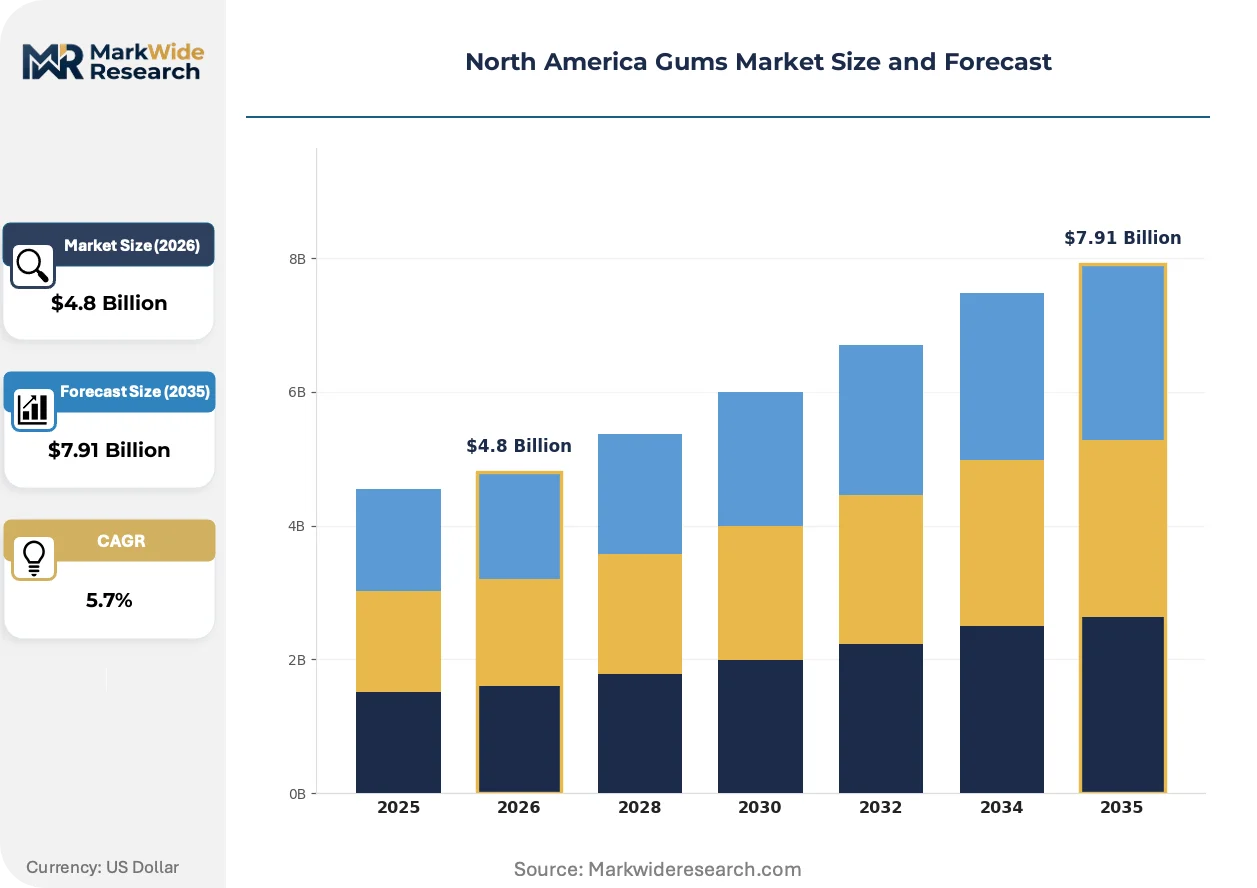
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chewing Gum, Gummy Candies, Functional Gums, Gum Bases End User: Retail Consumers, Food Manufacturers, Pharmacies, Health Stores Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Shops Application: Confectionery, Dietary Supplements, Oral Care, Functional Foods |
| Companies Covered | Mondelēz International Inc., The Hershey Company, Perfetti Van Melle B.V., Mars Incorporated, The PUR Company Inc., Wrigley’s, Lotte, Kraft Foods Inc., GSK PLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gums Market Trends and Innovations
Active-ingredient delivery mechanisms and clean-label formulation protocols are reconfiguring competitive advantage away from flavor novelty toward functional efficacy and regulatory pre-clearance speed.
Microencapsulation technology for sustained-release caffeine and nicotine is migrating from pharmaceutical transdermal patches into confectionery gum matrices. Functional food divisions at major CPG conglomerates pilot these formats for 18-month stability testing. The technology is compressing traditional chew-gum refresh cycles while opening prescription-adjacent distribution channels previously inaccessible to confectionery brands.
Health Canada's Natural Health Product Directorate enforcement of site licensing requirements is tightening contract manufacturer qualification standards. Small-batch producers face 90-day facility audit backlogs. Vitamin-infused and botanical-extract SKUs in the Canadian market are consolidating toward vertically integrated manufacturers with captive quality-assurance laboratories.
Pharmacy chain buyers are consolidating supplier rosters toward three-year exclusive distribution agreements with flavor-longevity guarantees. Front-of-store placement fees now bundle category management services previously unbundled. This concentration is most visible in CVS and Walgreens corridors across California and Texas, where private-label gum programs absorb mid-tier branded volume.
North America Gums Market Segmentation
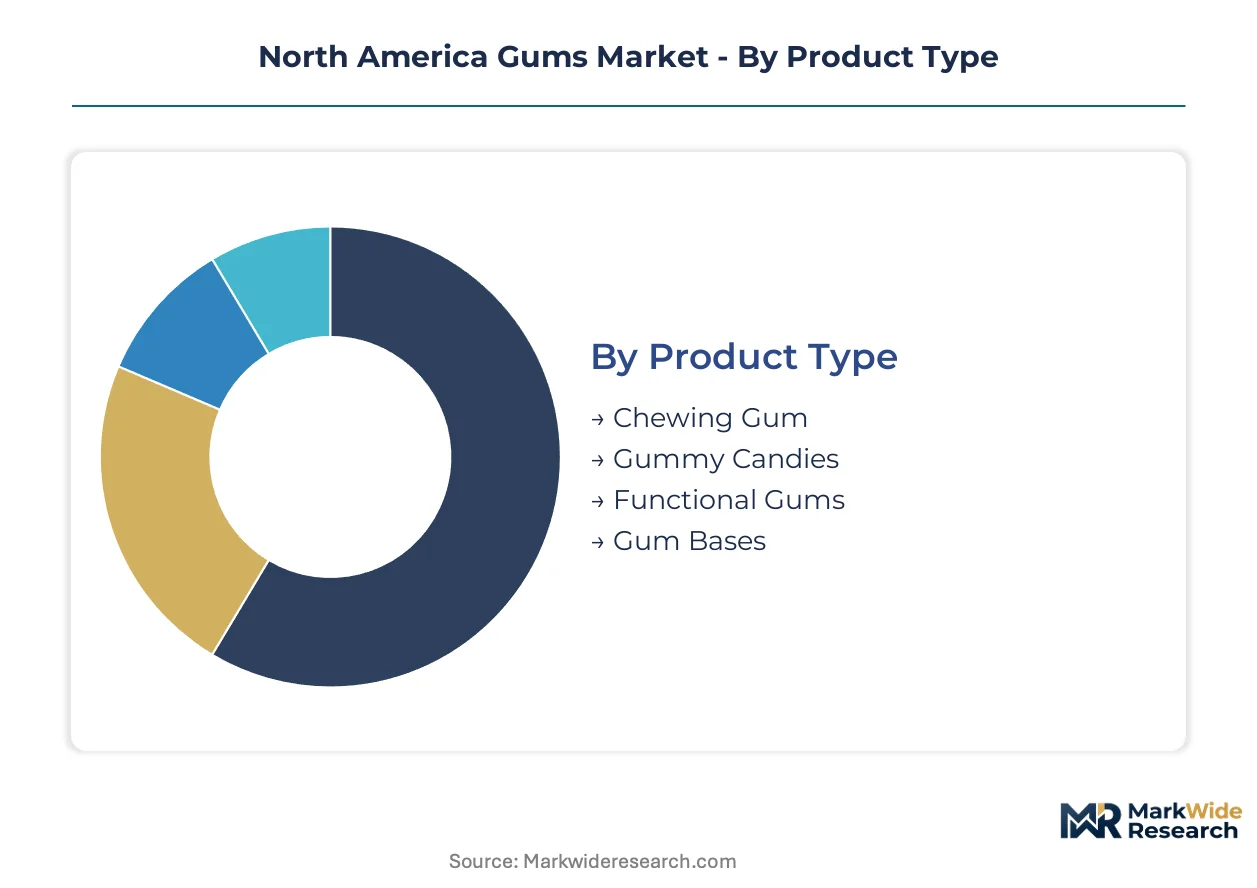
Segmentation in the North America gums market reveals divergent margin profiles and regulatory exposure across product formats. Manufacturers prioritize portfolio mix to balance volume stability against functional premium capture.
Product Type:
Chewing gum formats turn inventory fastest in convenience channels, while gum bases and functional variants operate on longer production cycles tied to pharmaceutical qualification timelines.
- Chewing Gum:Polyvinyl acetate and natural chicle elastomer bases plasticized with resin-wax blends maintain glass-transition temperatures between 15°C and 35°C for chew consistency. Demand concentrates in California and New York metropolitan corridors where impulse-buy placement at pharmacy checkouts drives velocity.
- Functional Gums:Active-ingredient matrices incorporate caffeine, nicotine, or vitamins through microencapsulation for sustained release. Pharmaceutical partnerships in Toronto and Chicago metropolitan areas expand distribution beyond traditional confectionery channels.
- Gummy Candies:Gelatin-based or pectin-substituted formulations dominate volume throughput in mass retail.
- Gum Bases:Raw elastomer-resin-wax compounds supply downstream manufacturers; procurement cycles track petrochemical price indices with 60-day lag.
Chewing gum anchors the volume base while functional gums gain share at the steepest rate.
End User:
Cost tiers separate commodity procurement by food manufacturers from premium positioning targeted at health stores and pharmacy buyers.
- Retail Consumers:Individual purchasers drive impulse-buy volume through front-of-store placement in CVS and Walgreens corridors across Texas and California.
- Pharmacies:Chain buyers consolidate supplier rosters toward three-year exclusive agreements with flavor-longevity guarantees; private-label programs absorb mid-tier branded volume.
- Food Manufacturers:Industrial gum base procurement scales for functional food applications with extended product development cycles.
- Health Stores:Clean-label and aspartame-free SKUs command shelf-space premiums in Toronto and Chicago vegetarian and halal demand concentrations.
Retail consumers anchor the volume base while health stores expand most quickly on clean-label migration.
Distribution Channel:
Volume concentration favors supermarkets, though margin extraction peaks in channels with premium placement control.
- Convenience Stores:Checkout-adjacent pellet formats with extended flavor release capture impulse-buy margins exceeding standard stick alternatives by double digits.
- Supermarkets:Mass-volume gummy candy distribution dominates throughput in standard confectionery aisles.
- Online Retail:Direct-to-consumer functional gum subscriptions bypass pharmacy chain placement fees.
- Specialty Shops:Curated botanical-colorant and clean-label assortments serve vegetarian and halal segments in urban corridors.
Supermarkets anchor the volume base while convenience stores climb the fastest on premiumization strategies.
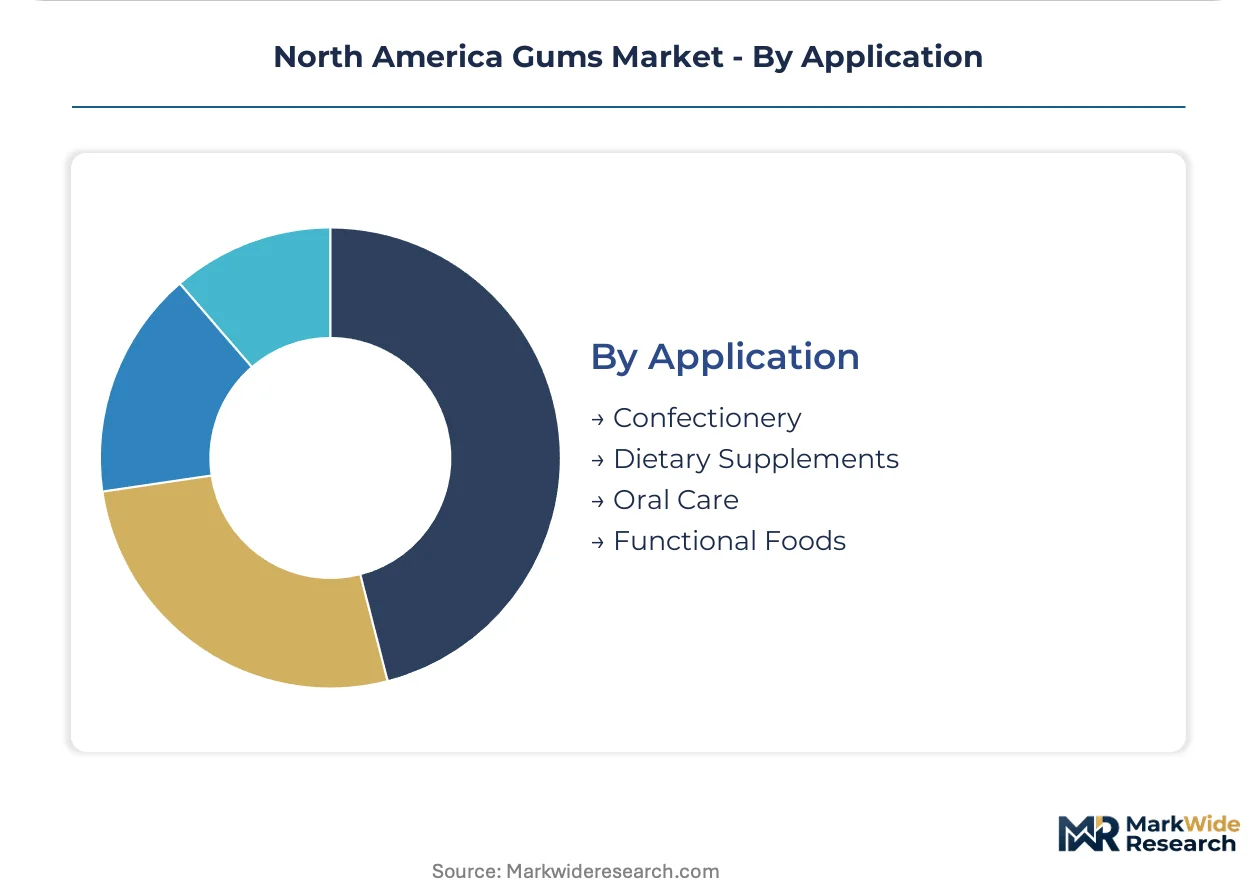
Application:
Maturity gradients separate established confectionery from nascent pharmaceutical-adjacent formats.
- Confectionery:Traditional sweetened and flavored mastication products face compressed margins from sugar-tax proposals in California and New York.
- Functional Foods:Active-ingredient delivery systems open prescription-adjacent channels previously inaccessible to confectionery brands.
- Dietary Supplements:Vitamin-infused SKUs consolidate toward vertically integrated manufacturers with captive quality-assurance laboratories.
- Oral Care:Xylitol-heavy formulations navigate tightening additive scrutiny from FDA and Health Canada.
Confectionery anchors the volume base while functional foods expand most quickly on pharmaceutical partnership migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex handles the majority of gum base resin imports from Asian petrochemical suppliers, anchoring West Coast distribution networks for functional gum manufacturers.
United States
California and New York metropolitan corridors concentrate impulse-buy demand through pharmacy checkout placement. FDA GRAS self-affirmation protocols extend product development timelines for novel active-ingredient formats. Chicago and Dallas-Fort Worth serve as inland distribution hubs for xylitol-heavy reformulations targeting sugar-tax avoidance.
Canada
Toronto and Vancouver metropolitan areas drive clean-label gelatin alternative demand from vegetarian and halal consumer segments. Health Canada's Natural Health Product Directorate maintains less congested approval pathways than FDA equivalents. Montreal hosts contract manufacturing facilities scaling pectin and carrageenan substitution capacity.
Mexico
Mexico City Metro anchors mass-market chewing gum consumption through traditional convenience channel penetration. COFEPRIS regulatory alignment with FDA standards facilitates cross-border formulation consistency. Guadalajara and Monterrey industrial corridors concentrate flavor house operations serving North American brand owners.
North America Gums Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in elastomer resin and flavor-chemistry supply. The North America gums market structures around three tiers: multinational CPG conglomerates with captive distribution, mid-tier regional formulators with pharmacy chain exclusives, and niche clean-label specialists with direct-to-consumer channels. Dominant competitive moves include backward integration into gum base resin sourcing and three-year exclusive distribution agreements with flavor-longevity guarantees.
Within the multinational tier, Mondelēz International Inc., Mars Incorporated, and Wrigley's occupy positions defined by shelf-space dominance and front-of-store visibility across major pharmacy chains. These entities exemplify platform-scale competitive positioning through checkout-adjacent premium SKU placement and backward integration into upstream resin supply. The PUR Company Inc. represents the clean-label specialist archetype, navigating tightening additive scrutiny with aspartame-free portfolio positioning.
| Leading Market Players |
|---|
| Mondelēz International Inc. |
| The Hershey Company |
| Perfetti Van Melle B.V. |
| Mars Incorporated |
| The PUR Company Inc. |
| Wrigley's |
| Lotte |
| Kraft Foods Inc. |
| GSK PLC |
| Others |
Pricing and Supply Chain Analysis
US Gulf Coast petrochemical suppliers concentrate gum base elastomer production, anchoring margin pools downstream with pharmacy chains and functional food manufacturers who command checkout-adjacent placement premiums. This upstream clustering shapes pricing power across pellet formats and active-ingredient delivery systems.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical procurement contracts from convenience store spot purchases. Three-tier pricing stratifies across premium functional gums with microencapsulation technology, standard chewing gum formats, and economy stick alternatives. Price differentiation hinges on FDA GRAS certification status and flavor longevity guarantees. Cost compression in mid-tier branded segments intensifies as private-label programs expand through CVS and Walgreens. Food manufacturers exhibit lowest price sensitivity due to captive formulation requirements, while impulse-buy retail consumers drive hardest bargain at checkout.
Supply Chain Analysis
Upstream feedstock channels draw from US Gulf Coast petrochemical complexes, Indonesian natural chicle harvests, and Canadian resin processing facilities. Gum base production rests on polyvinyl acetate, paraffin wax, and styrene-butadiene rubber inputs. Hurricane-season disruption risk elevates working capital requirements for manufacturers without dual-source qualification. Distribution runs through Port of Los Angeles-Long Beach for Asian resin imports, with inland hubbing at Chicago and Dallas-Fort Worth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional ingredient integration in chewing gum matrices represents early-cycle expansion, with pharmaceutical partnership pipelines accelerating beyond traditional confectionery penetration rates.
For Market Incumbents: Pre-empt private-label encroachment by securing three-year exclusive pharmacy distribution agreements with flavor-longevity guarantees. Deepen backward integration into gum base resin sourcing to offset petrochemical price volatility. FDA GRAS self-affirmation capabilities serve as the critical defensive moat against mid-tier reformulation challengers. For New Entrants and Emerging Players: Canadian natural health product gums under Health Canada jurisdiction offer the most penetrable white-space entry point, with approval pathways 40% less congested than FDA equivalents. Toronto and Vancouver metropolitan corridors concentrate vegetarian and halal demand for clean-label pectin-based alternatives. Direct-to-consumer subscription models bypass pharmacy chain placement fee structures. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturers with captive quality-assurance laboratories and Health Canada site licensing. Long-term viability favors entities bridging confectionery and pharmaceutical adjacencies. Monitor California Assembly Bill 418 synthetic dye restriction momentum as inflection indicator for botanical colorant supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive gum base production insulates Mars Incorporated from Gulf Coast hurricane disruption risk. |
| Microencapsulation Technology Licensing | Sustained-release caffeine and nicotine formats open prescription-adjacent CVS and Walgreens channels. |
| Health Canada Site Licensing Investment | Natural Health Product Directorate qualification accelerates vitamin-infused SKU approval timelines. |
| Botanical Colorant Supplier Partnership | Spirulina and beetroot extract sourcing addresses California Assembly Bill 418 compliance requirements. |
| Three-Year Exclusive Distribution Agreement | Pharmacy chain consolidation secures front-of-store placement against private-label absorption. |
Research Methodology
Cross-validation between primary interviews with flavor chemists, pharmacy chain category buyers, gum base procurement managers, and Health Canada regulatory consultants anchors the qualitative findings. Secondary validation draws from FDA GRAS filings, Health Canada Natural Health Product Directorate submissions, EPA industrial chemical reporting standards, and Nielsen retail audit data. Bottom-up demand modeling triangulates against top-down petrochemical consumption indices.
Calibration against historical elasticity patterns and regulatory approval timeline distributions shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, end user archetype, distribution channel, and application maturity gradient. CAGRs derive from petrochemical price index correlations and functional ingredient adoption curve analysis. Stability testing protocols and glass-transition temperature maintenance requirements inform chewing gum format forecasts.
Macroeconomic conditions sit as an overlay; deviation in crude oil indices and state-level sugar-tax implementation schedules would shift the trajectory. Forecasts reflect assumptions regarding Health Canada enforcement continuity and FDA GRAS self-affirmation protocol stability. Cross-checking against EIA petrochemical production data and provincial health product registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Fruit Powder Market
Ingredients
Calcium Caseinate Market
Ingredients
Middle East Feed Palatability Enhancers Market
Ingredients
China Protein Market
Ingredients
Shortening Fats Market
Ingredients
Corn Oil Cake Market
Ingredients
Egg Albumin Protein Market
Ingredients
Isoamyl Laurate Market
Ingredients
Bakery Ingredients Market
Ingredients
Arachidonic Acid Market
Ingredients
South America Clean Ingredients Market
Ingredients
Europe Vegetable Oil Market
Ingredients
Dried Fruit Ingredients Market
Ingredients
Global Starch Derivatives Market
Ingredients
Sweet Almond Oil Market
Ingredients
Vitamin and Mineral Premixes Market