
 Natural Food Color Additives Market | 2026-2036
Natural Food Color Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Food Color Additives Market Foresight
Clean-label beverage producers is bifurcating from conventional food manufacturers as the primary volume buyer archetype in natural color procurement. Döhler Group leverages integrated botanical extraction capabilities to anchor European supply contracts for anthocyanin-based reds. GNT Group specializes in vertical farming of vegetable raw materials to sustain year-round chlorophyll and betalaine output. Sensient Technologies Corporation competes through fermentation-derived color platforms that reduce agricultural land dependency.
Natural food color additives comprise pigments extracted from plants, algae, minerals, or agricultural byproducts, standardized to specific color intensity measured in EBC or absorbance units at defined wavelengths, and stabilized against pH degradation and light oxidation for shelf-stable incorporation. Their primary commercial purpose is to restore or enhance visual appeal in processed foods where thermal treatment, storage, or formulation strips native pigmentation. Caramel color and spirulina extract lead product type volume due to established beverage deployment and regulatory approval breadth across jurisdictions. Powder form commands premium unit economics versus liquid equivalents because of superior stability in dry-mix bakery and confectionery applications where moisture sensitivity dictates format selection.
FDA color additive batch certification requirements and EFSA re-evaluation programs for existing food colors jointly compress synthetic alternatives while creating compliance pathways for natural substitutes through GRAS self-determination or novel food authorization. BIS harmonization with Codex Alimentarius specifications in India accelerates import substitution for annatto and turmeric oleoresins in domestic processed food manufacturing. Stakeholders must monitor evolving maximum permissible levels for heavy metals and mycotoxins in botanical raw materials, as these specifications increasingly determine supplier qualification and procurement contract duration.
Market Dynamics
Clean-label procurement mandates from Western European beverage manufacturers are compressing synthetic azo dye contracts while accelerating multi-year supply agreements for spirulina and anthocyanin sources, restructuring supplier qualification criteria around heavy metal testing protocols.
Growth Catalysts
- EFSA azo dye re-evaluation:The European regulator's tightened safety scrutiny on synthetic colorants creates immediate displacement demand for botanical alternatives in beverage and confectionery reformulations.
- Front-of-pack labeling mandates:Supermarket private-label procurement teams in Germany and France now require plant-based colorant declarations, shifting RFP specifications toward natural pigment portfolios.
- Fermentation-derived color platforms:This biotechnology reduces agricultural land dependency and stabilizes year-round supply for chlorophyll and betalaine outputs regardless of seasonal crop variation.
Market Restraints
- Input cost volatility:Spirulina biomass and vegetable raw material prices fluctuate with climate-induced harvest variability, compressing margin predictability for extractors.
- Supply concentration risk:Year-round chlorophyll output depends on a limited number of vertical farming operations in the Netherlands and southern Spain.
- Regulatory friction:FDA batch certification requirements for new color additives extend commercialization timelines versus GRAS self-determination pathways.
Strategic Opportunities
- India import substitution:BIS harmonization with Codex Alimentarius specifications accelerates domestic annatto and turmeric oleoresin production for processed food manufacturing.
- Powder format premiumization:Dry-mix bakery and confectionery applications where moisture sensitivity dictates format selection command superior unit economics versus liquid equivalents.
- Agricultural byproduct valorization:Extraction from waste streams of the juicing and vegetable processing industries creates circular economy positioning and cost advantages.
Industry Challenges
- Heavy metal compliance talent gap:Supplier qualification now requires specialized analytical chemistry capabilities for mycotoxin and arsenic testing that exceed conventional food safety lab capacity.
- pH stabilization capex intensity:Shelf-stable incorporation against thermal degradation demands investment in microencapsulation and coating technologies.
- Novel food authorization timelines:EFSA regulatory uncertainty for emerging algal pigments extends commercial launch schedules beyond typical product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Food Color Additives Market |
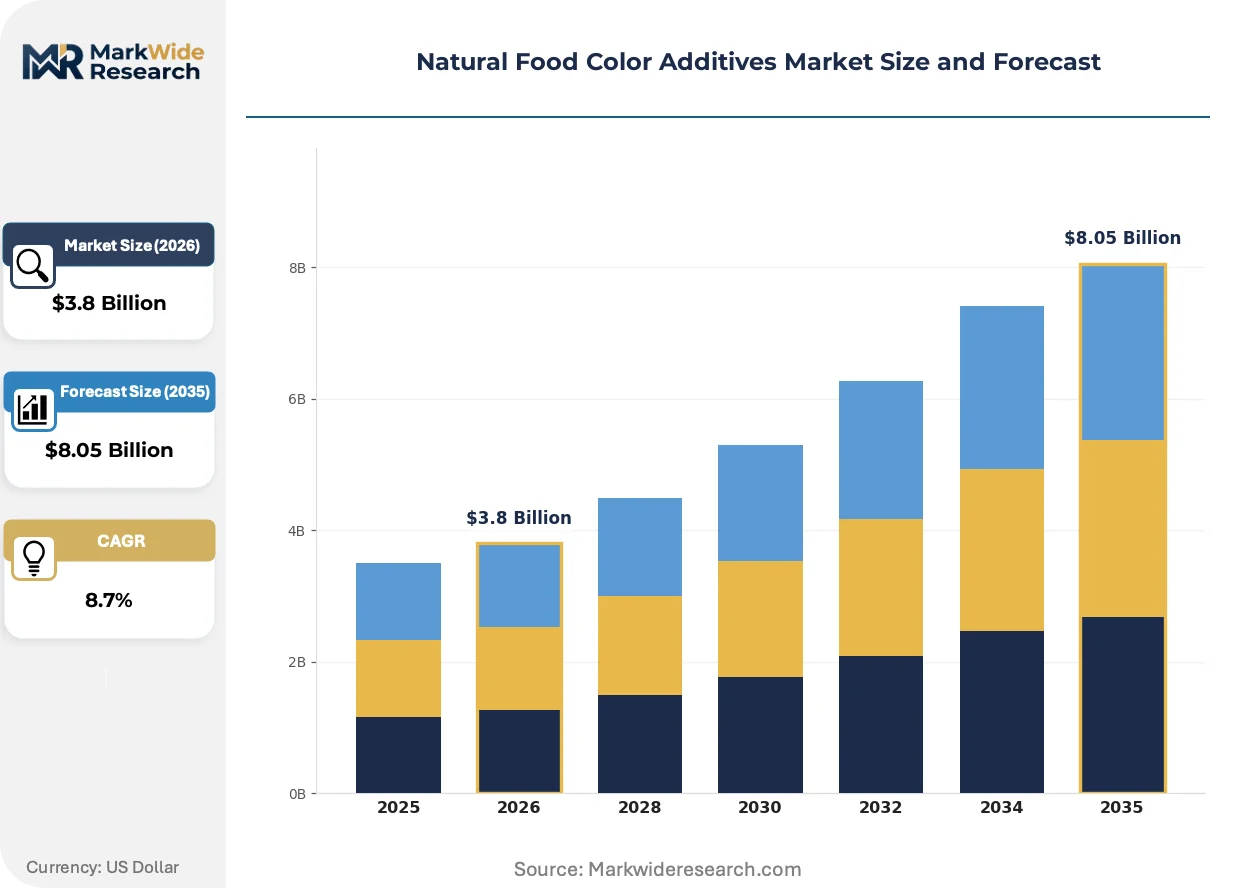
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
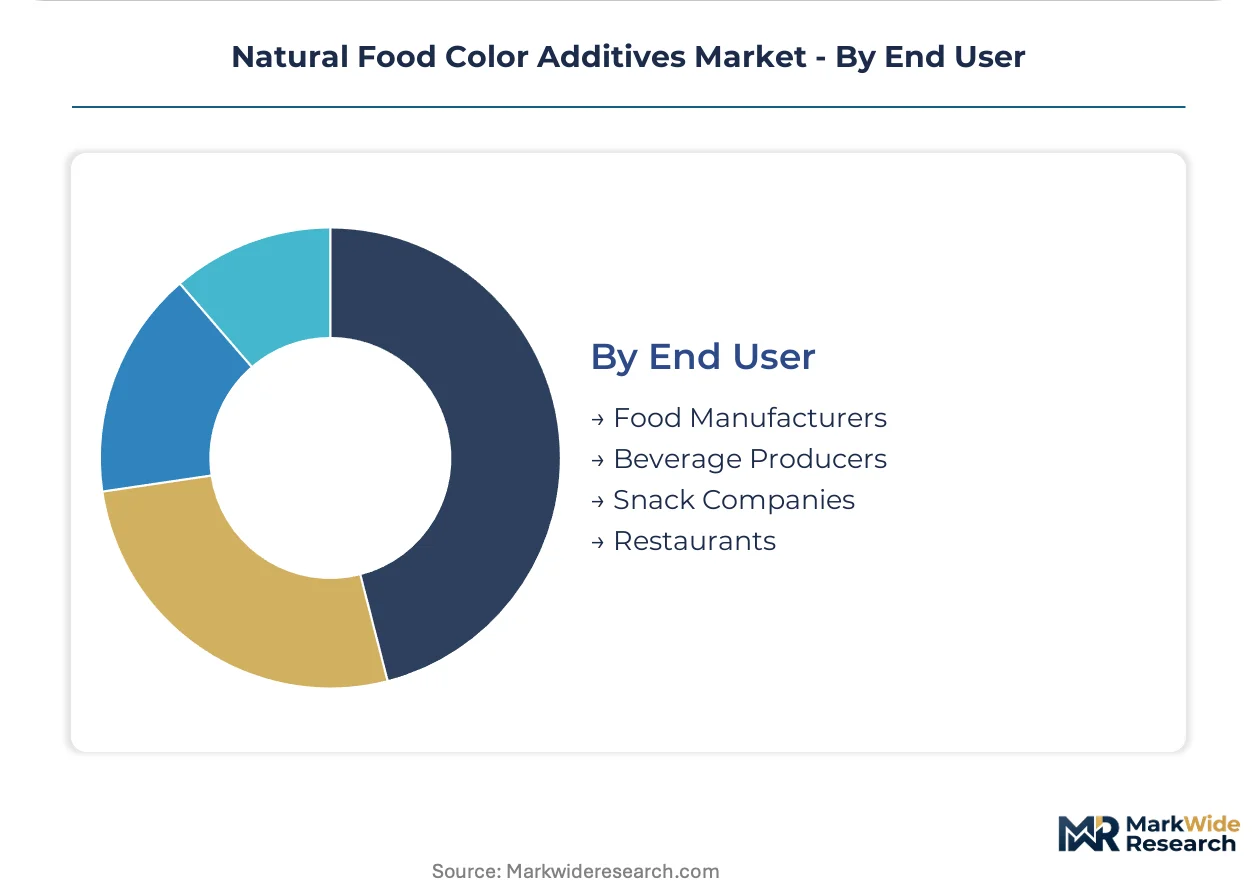
| Segmentation | Product Type: Beetroot Red, Caramel Color, Spirulina Extract, Annatto Application: Beverages, Bakery, Dairy, Confectionery Form: Liquid, Powder, Gel, Granule End User: Food Manufacturers, Beverage Producers, Snack Companies, Restaurants |
| Companies Covered | Döhler Group, Symrise AG, GNT Group, Givaudan, Kalsec Inc., Sensient Technologies Corporation, Archer Daniels Midland Company, DDW The Color House, Chr. Hansen Holding A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Food Color Additives Market Shifts & Advancements
Biotechnology extraction methods and precision fermentation are displacing conventional solvent-based processes, while regulatory harmonization efforts compress cross-border compliance costs for botanical suppliers.
Precision fermentation for phycocyanin and betalaine production is miniaturizing the capital footprint required for commercial-scale colorant manufacturing. Mid-sized ingredient suppliers in Denmark and the Netherlands are deploying modular bioreactor systems that achieve pharmaceutical-grade pigment consistency without agricultural acreage. This distributed production model is compressing geographic supply risk and enabling just-in-time contract manufacturing for regional beverage brands.
EFSA's systematic re-evaluation program for existing food colors is accelerating synthetic dye displacement across the European Union. The regulator's updated safety protocols for azo compounds have triggered reformulation deadlines that beverage manufacturers must meet to maintain distribution licenses. German clean-label producers are responding by locking multi-year procurement contracts with spirulina extractors to secure volume commitments ahead of competitor bidding.
Supermarket private-label procurement teams are consolidating supplier relationships around integrated botanical extractors capable of delivering certified organic colorant portfolios. Direct sourcing agreements are displacing traditional ingredient distributor intermediaries in Western European retail channels. This concentration is most visible in German and French hypermarket chains where front-of-pack plant-based declarations now determine shelf placement negotiations.
Natural Food Color Additives Market Segmentation
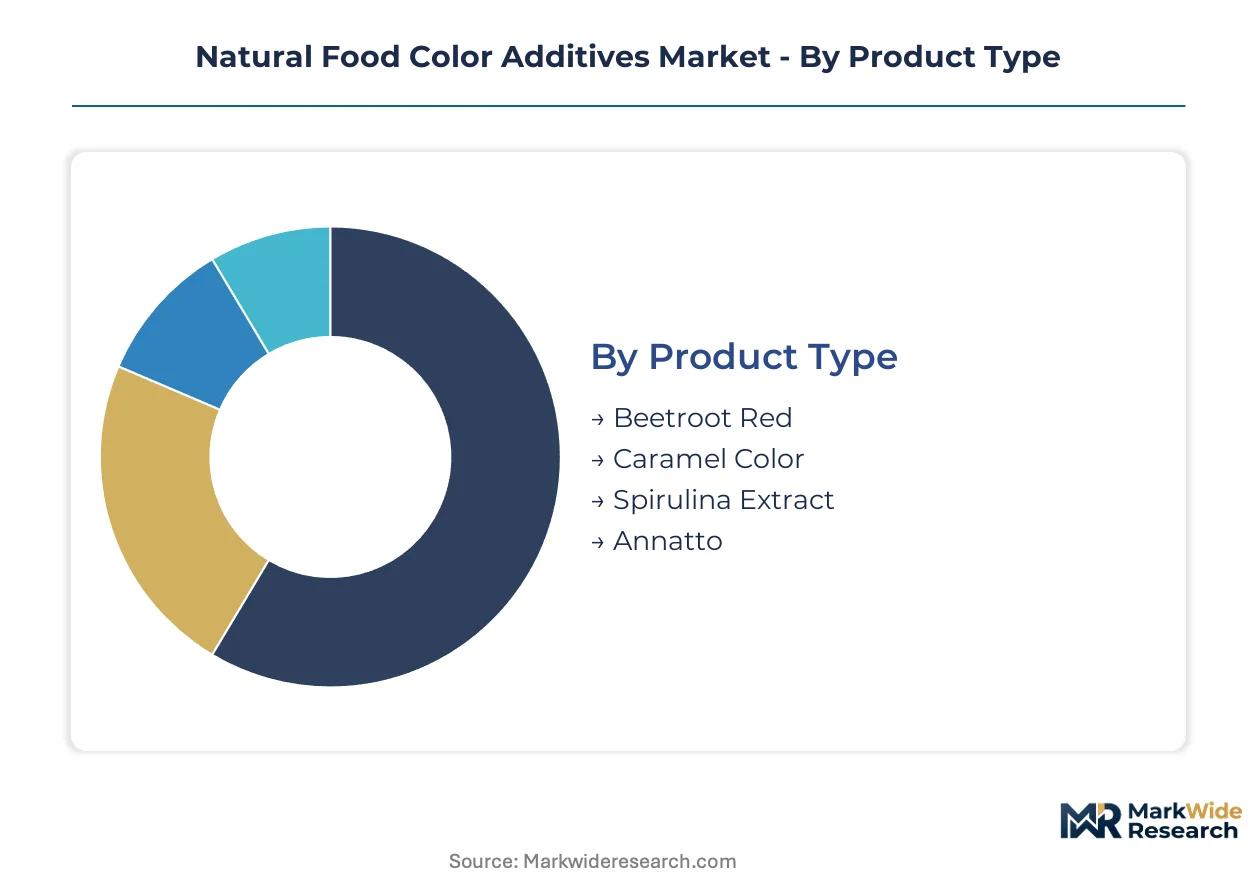
Natural food color procurement decisions hinge on format stability, regulatory approval breadth, and end-use processing conditions. Each segmentation dimension carries distinct compliance pathways and margin structures that determine supplier qualification and contract duration.
Product Type:
EFSA's azo dye re-evaluation has created divergent regulatory fates across botanical pigment categories, with approval status now determining commercial viability in European formulations.
- Caramel Color:Ammonium and sulfite-processed variants dominate beverage applications due to established FDA GRAS status and EFSA clearance across all pH ranges. German clean-label producers are accelerating procurement of Class I plain caramel for transparent ingredient declarations on front-of-pack labeling.
- Spirulina Extract:Phycocyanin-based blues and greens command premium positioning as the only EFSA-approved natural alternative to synthetic Brilliant Blue in beverage matrices. French and German manufacturers are locking multi-year supply agreements ahead of competitor bidding for limited biomass output.
- Annatto:Bixin and norbixin carotenoids from achiote seed provide stable yellow-orange hues for dairy and snack coatings with established Codex Alimentarius specifications.
- Beetroot Red:Betalaine pigments from Beta vulgaris deliver heat-sensitive pink-red tones primarily for frozen dessert and chilled beverage applications where thermal degradation is minimized.
Caramel color handles the majority of throughput; spirulina extract is expanding most quickly on share.
Application:
Moisture sensitivity and thermal processing intensity create divergent format requirements across end-use categories, with shelf-stable applications commanding powder premiums.
- Beverages:pH-stable anthocyanin and spirulina formulations dominate carbonated and still drink reformulations responding to EFSA synthetic dye deadlines. German private-label procurement teams now mandate plant-based colorant declarations as a shelf placement condition.
- Bakery:Dry-mix applications favor encapsulated powder formats that withstand oven temperatures without Maillard interference or moisture migration.
- Confectionery:Hard candy and panned coating processes require heat-stable carmine alternatives as EFSA scrutiny extends to insect-derived colorants.
- Dairy:Yogurt and cheese matrices demand oil-dispersible annatto and beta-carotene emulsions with standardized color intensity measured in absorbance units.
Beverages command the highest procurement urgency; confectionery is climbing the fastest on reformulation timelines.
Form:
Unit economics bifurcate sharply between moisture-resistant dry formats and convenience-oriented liquids, with stability specifications determining margin capture.
- Powder:Microencapsulated pigments with maltodextrin or gum arabic carriers achieve superior shelf stability in dry-mix bakery and instant beverage applications where moisture sensitivity dictates format selection.
- Liquid:Propylene glycol or glycerin-based solutions offer dosing convenience for high-volume beverage production lines but require cold chain logistics to prevent microbial degradation.
- Gel:Concentrated semi-solid formats suit artisanal and small-batch food manufacturers with limited metering equipment.
- Granule:Agglomerated powders disperse rapidly in aqueous systems without dust generation, addressing occupational safety requirements in large-scale manufacturing.
Powder commands the steepest price premium; liquid maintains volume dominance in beverage manufacturing.
End User:
Procurement sophistication varies dramatically by customer scale, with integrated botanical extractors displacing distributor intermediaries for the largest accounts.
- Food Manufacturers:Processed meat and sauce producers face EFSA deadlines for synthetic dye replacement while managing heat stability constraints in retort processing.
- Beverage Producers:Clean-label specialists in Germany and France are consolidating supplier relationships around certified organic portfolios with heavy metal testing documentation.
- Snack Companies:Seasoning and coating applications require oil-compatible colorants with standardized dispersibility for continuous extrusion lines.
- Restaurants:Foodservice distributors are expanding natural color SKUs in response to chain operator menu transparency commitments.
Food manufacturers generate the bulk of contract volume; beverage producers are gaining share fastest on procurement mandate intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spirulina cultivation clusters in southern Spain and the Netherlands dominate European phycocyanin supply, while Indian turmeric and annatto processing anchors Asian carotenoid output for export markets.
Germany
Clean-label beverage manufacturers in Bavaria and North Rhine-Westphalia are locking multi-year spirulina procurement contracts ahead of EFSA synthetic dye deadlines. The Federal Ministry of Food and Agriculture enforces strict heavy metal testing protocols under the German Food and Feed Code. Frankfurt's ingredient trading hub coordinates pan-European distribution for botanical colorant portfolios.
United States
FDA GRAS self-determination pathways accelerate commercialization timelines for fermentation-derived colorants in California and New Jersey formulation centers. The FDA's color additive batch certification requirements compress synthetic alternatives while creating compliance advantages for natural substitutes. Chicago's food manufacturing corridor concentrates demand for caramel color in carbonated beverage production.
India
Domestic processed food manufacturers in Maharashtra and Gujarat are substituting imported annatto and turmeric oleoresins under BIS-Codex harmonization. FSSAI maximum permissible levels for heavy metals in botanical raw materials determine supplier qualification criteria. Anand's dairy processing cluster drives regional demand for oil-dispersible carotenoid emulsions.
Netherlands
Vertical farming operations near Eindhoven sustain year-round chlorophyll and betalaine output regardless of seasonal crop variation. EFSA novel food authorization timelines for emerging algal pigments extend commercial launch schedules for Rotterdam-based extractors. Wageningen's agricultural research corridor anchors biotechnology fermentation platforms for phycocyanin production.
France
Supermarket private-label procurement teams in Paris and Lyon mandate plant-based colorant declarations as shelf placement conditions. ANSM enforces updated safety protocols for food additive contaminants under EU-wide harmonization. Brittany's seaweed harvesting cooperatives supply raw biomass for regional phycoerythrin extraction.
Natural Food Color Additives Market Competitive Landscape
Concentration sits with integrated botanical extractors capable of delivering certified organic portfolios with heavy metal testing documentation. The supplier base fragments between agricultural commodity processors and biotechnology fermentation specialists. Three archetypes dominate: vertically integrated farming-extraction operations, precision fermentation platforms, and distributed regional contract manufacturers. Competitive positioning hinges on multi-year supply agreement tenure and regulatory approval breadth across FDA, EFSA, and BIS jurisdictions.
Within the integrated extraction tier, Döhler Group and GNT Group exemplify European supply chain control through captive botanical raw material cultivation. Sensient Technologies Corporation occupies the biotechnology vector with fermentation-derived color platforms. Symrise AG represents the mid-cap specialist archetype leveraging regional formulation partnerships. Each anchors distinct competitive positioning around agricultural land dependency reduction versus year-round supply security.
| Leading Market Players |
|---|
| Döhler Group |
| Symrise AG |
| GNT Group |
| Givaudan |
| Kalsec Inc. |
| Sensient Technologies Corporation |
| Archer Daniels Midland Company |
| DDW The Color House |
| Chr. Hansen Holding A/S |
| Others |
Supply & Pricing Matrix
EFSA heavy metal testing protocols gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified extractors while enabling premium capture by integrated botanical operators with in-house analytical chemistry capabilities. Clean-label beverage manufacturers in Germany now mandate documentation of arsenic and mycotoxin screening as a contract precondition, bifurcating the supplier base into compliant premium tiers and excluded commodity players.
Pricing Analysis
EFSA azo dye re-evaluation dictates the pricing tier structure across European natural color procurement. Three-tier pricing stratifies across pharmaceutical-grade fermentation platforms, certified organic botanical extracts, and conventional agricultural commodity pigments. Price differentiation hinges on heavy metal certification depth and year-round supply security from vertical farming operations. Cost compression in conventional vegetable-derived tiers is intensifying because climate-induced harvest variability in Mediterranean growing regions. Snack seasoning manufacturers exhibit highest price sensitivity due to thin coating-application margins, while infant formula producers accept steepest premiums for batch-traceable spirulina phycocyanin.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for Indian turmeric oleoresins and Peruvian annatto shipments entering European formulation centers. Geographic supply concentration centers on Netherlands vertical farming operations, Spanish spirulina cultivation clusters, and Indian carotenoid processing facilities. Raw material dependencies draw from achiote seed harvests in Latin America, Beta vulgaris rootstock in Poland, and Arthrospira platensis biomass in controlled-environment photobioreactors. Single-source vulnerability pervades phycocyanin output where limited southern Spain cultivation sites supply German beverage reformulation deadlines. Distribution runs through Frankfurt ingredient trading hubs coordinating pan-European just-in-time delivery for private-label procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA regulatory deadlines fragment procurement demand across dozens of reformulation niches, each requiring distinct pH stability profiles and thermal degradation specifications. This fragmentation rewards specialized extractors capable of certified organic portfolios with heavy metal documentation.
For Market Incumbents: Compound defensible positioning through backward integration into captive spirulina cultivation and microencapsulation coating technologies. Lock multi-year supply agreements with German clean-label beverage producers ahead of competitor bidding for limited biomass output. Invest in fermentation-derived color platforms to reduce agricultural land dependency and stabilize year-round chlorophyll output against climate-induced harvest variability.
For New Entrants and Emerging Players: Differentiate on agricultural byproduct valorization from juicing and vegetable processing waste streams, delivering circular economy positioning and cost advantages beneath incumbent pricing floors. Target India's domestic annatto and turmeric oleoresin substitution opportunity under BIS-Codex harmonization. Pursue direct sourcing agreements with French supermarket private-label procurement teams seeking plant-based colorant declarations as shelf placement conditions.
For Investors and Strategic Acquirers: EFSA's systematic re-evaluation program for existing food colors reshapes the acquisition landscape toward integrated botanical extractors with pharmaceutical-grade fermentation capabilities and heavy metal testing infrastructure. Long-term viability favors precision fermentation platforms achieving pigment consistency without agricultural acreage constraints. Monitor EFSA novel food authorization timelines for emerging algal pigments as the inflection signal determining which biotechnology specialists achieve commercial scale before synthetic dye displacement deadlines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spirulina Cultivation | Captive biomass supply secures volume commitments from German beverage reformulation deadlines. |
| Fermentation-Derived Color Platform Deployment | Modular bioreactor systems achieve pharmaceutical-grade pigment consistency without Mediterranean climate exposure. |
| Heavy Metal Testing Infrastructure Investment | In-house analytical chemistry capabilities exceed conventional food safety lab capacity for EFSA compliance. |
| Agricultural Byproduct Valorization Partnership | Waste stream extraction from vegetable processing creates circular economy positioning against commodity competitors. |
| Direct Sourcing Agreement with Retail Chains | Supermarket private-label procurement consolidation displaces traditional ingredient distributor intermediaries. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA additive safety evaluations, FDA GRAS determinations, and BIS-Codex harmonization documentation. Primary interviews engaged botanical extraction plant managers, clean-label beverage procurement leads, supermarket private-label category buyers, and analytical chemistry laboratory directors across Germany, Netherlands, India, and France. Secondary validation incorporated customs trade data for annatto and turmeric oleoresins, FSSAI maximum permissible level notifications, and SEC filings from integrated ingredient suppliers. Bottom-up volume modeling triangulated against top-down market sizing from regulatory displacement timelines.
Segmentation dimensions modeled span pigment source category, formulation stability grade, end-use processing intensity, and geographic regulatory cluster across the projection horizon. CAGRs derived from synthetic dye displacement velocity under EFSA re-evaluation deadlines and clean-label procurement mandate penetration in Western European retail channels. Forecast inputs incorporated spirulina biomass yield projections from vertical farming operations and fermentation platform capacity expansion announcements.
The analysis sits within stated boundaries; outcomes outside EFSA regulatory timeline adherence, heavy metal specification enforcement, or climate-induced agricultural harvest patterns would require recalibration. Forecasts reflect documented assumptions regarding synthetic dye displacement rates and biotechnology fermentation scale-up trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
Africa Feed Additives Market
Food Additives and Ingredients
Food Grade Carrageenan Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
South America Anti Caking Market
Food Additives and Ingredients
France Food Acidulants Market
Food Additives and Ingredients
Asia-Pacific Malt Ingredient Market
Food Additives and Ingredients
Australia Food Acidulants Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market
Food Additives and Ingredients
South America Food Acidulants Market
Food Additives and Ingredients
Argentina Sodium Reduction Ingredient Market