
 Instant Dry Yeast Market | 2026-2036
Instant Dry Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Dry Yeast Market Outlook
Single-serve sachet bundling is pivoting toward bulk industrial formats as commercial bakers seek cost efficiency at scale. Lallemand Inc. leverages its North American manufacturing footprint to supply high-volume food manufacturers. Lesaffre anchors European demand through specialized strains for artisan bread applications. Angel Yeast dominates Asia-Pacific supply with integrated yeast extract and baking ingredient portfolios.
Instant dry yeast comprises Saccharomyces cerevisiae cells dried to below 8% moisture, vacuum-sealed for ambient stability, and rehydrated directly without proofing. The product accelerates fermentation in industrial baking by 15-30% versus active dry alternatives. Rapid-rise yeast commands premium positioning among home bakers seeking convenience. Commercial bakers generate the deepest margin pools through long-term supply contracts and technical service attachments. Granulated form leads volume share, though pellet formats gain traction in automated dispensing systems for large-scale facilities.
FDA food additive regulations and USDA organic certification standards govern strain approval and label claims in the United States. EU REACH compliance and EFSA novel food assessments shape strain introduction timelines across European markets. Stakeholders must monitor evolving clean-label demands and carbon-footprint disclosure requirements as procurement criteria harden across retail and foodservice channels.
Market Dynamics
Commercial baker procurement of single-serve sachets is collapsing in favor of bulk industrial formats, compressing packaging margins while amplifying strain development and technical service revenue pools. This volume-format pivot is restructuring competitive positioning around fermentation performance guarantees rather than commodity yeast supply.
Growth Catalysts
- EU F-Gas Regulation:Industrial bakeries across Germany, France, and Italy are retrofitting fermentation cooling systems, creating captive demand for thermotolerant yeast strains optimized for variable temperature profiles.
- Artisan bread segment:Munich and Stuttgart bakery clusters are specifying specialized Saccharomyces cerevisiae variants with extended fermentation tolerance, driving premium strain development.
- Pellet format automation:Large-scale facilities in the US Midwest are installing automated dispensing systems, displacing manual granulated yeast handling and reducing labor exposure.
Market Restraints
- Molasses input volatility:Beet and cane molasses prices fluctuate with agricultural commodity cycles, squeezing margin predictability for producers without backward integration into sugar processing.
- Strain approval timelines:EFSA novel food assessments and FDA GRAS determinations extend 18-36 months, freezing product pipeline velocity for innovative fermentation strains.
- Active dry yeast substitution:Price-sensitive foodservice operators in emerging markets retain legacy active dry formats, limiting instant dry yeast penetration in institutional baking channels.
Strategic Opportunities
- Clean-label certification tailwind:USDA organic and non-GMO Project Verified standards are hardening procurement criteria, creating margin premiums for certified strain portfolios.
- Yeast extract convergence:Integrated producers are capturing downstream value by supplying savory flavor enhancers to processed food manufacturers, diversifying beyond baking applications.
- Carbon disclosure mandates:EU CSRD and emerging Scope 3 reporting requirements are favoring suppliers with verified low-carbon fermentation processes, creating procurement preference in retail channels.
Industry Challenges
- Fermentation scientist scarcity:Industrial microbiology talent pools are contracting as academic programs pivot to pharmaceutical biotech, constraining strain optimization capabilities.
- Legacy equipment retrofit costs:Automated dispensing system installation requires six-figure capital outlays, freezing adoption timelines for mid-cap bakeries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Dry Yeast Market |
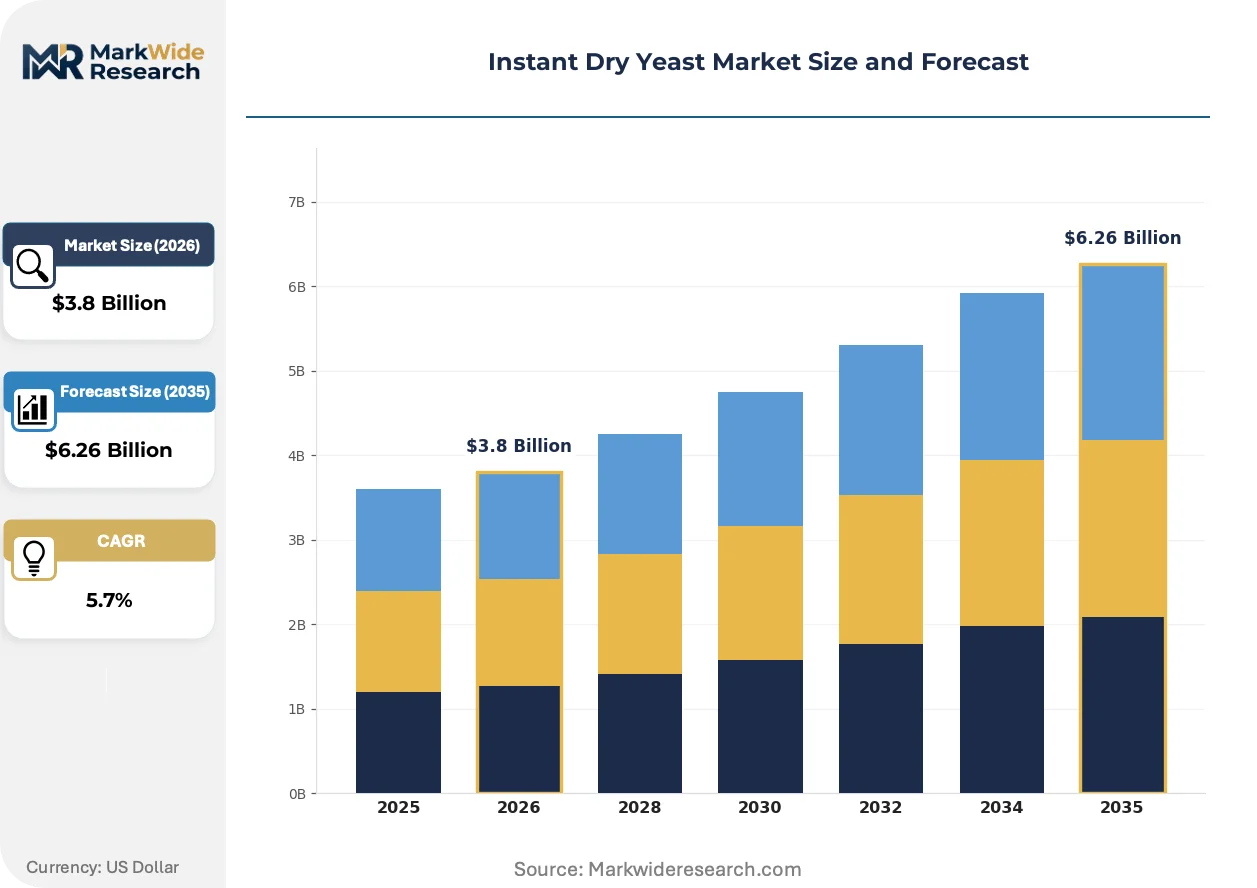
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Dry Yeast, Rapid-Rise Yeast, Instant Yeast, Bread Machine Yeast Application: Baking, Confectionery, Snacks, Brewing Form: Granulated, Instant, Pellets, Tablets End User: Commercial Bakers, Home Bakers, Food Manufacturers, Restaurants |
| Companies Covered | Lallemand Inc., Pakmaya, Lesaffre, DCL Yeast Ltd., Chr. Hansen Holding A/S, AB Mauri, Red Star Yeast, Imperial Yeast, Angel Yeast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Dry Yeast Market Strategic Shifts
Bioprocess engineering and regulatory disclosure requirements are compressing product development cycles while fragmenting buyer requirements across performance, sustainability, and convenience dimensions.
Pelletized instant dry yeast is converging with automated bulk handling systems in industrial bakeries. Large-scale facilities in Germany and the United States are adopting pneumatic conveying and precision dosing equipment. This convergence is compressing labor costs and contamination risk while demanding yeast formulations with enhanced flowability and moisture stability.
EU F-Gas Regulation phase-down schedules are forcing refrigeration-dependent fermentation operations to revalidate thermal performance envelopes. Industrial bakeries in France and Italy are installing variable-speed compressors and heat recovery systems. Strain suppliers are responding with expanded thermotolerant product lines and fermentation protocol consulting services.
Home baking channel consolidation is compressing brand loyalty cycles as private-label rapid-rise formats displace legacy names in supermarket baking aisles. Discounters in Germany and hypermarket chains in the United States are expanding own-brand instant dry yeast shelf space. This displacement is most visible in single-serve sachet segments where convenience positioning outweighs strain provenance claims.
Instant Dry Yeast Market Segmentation
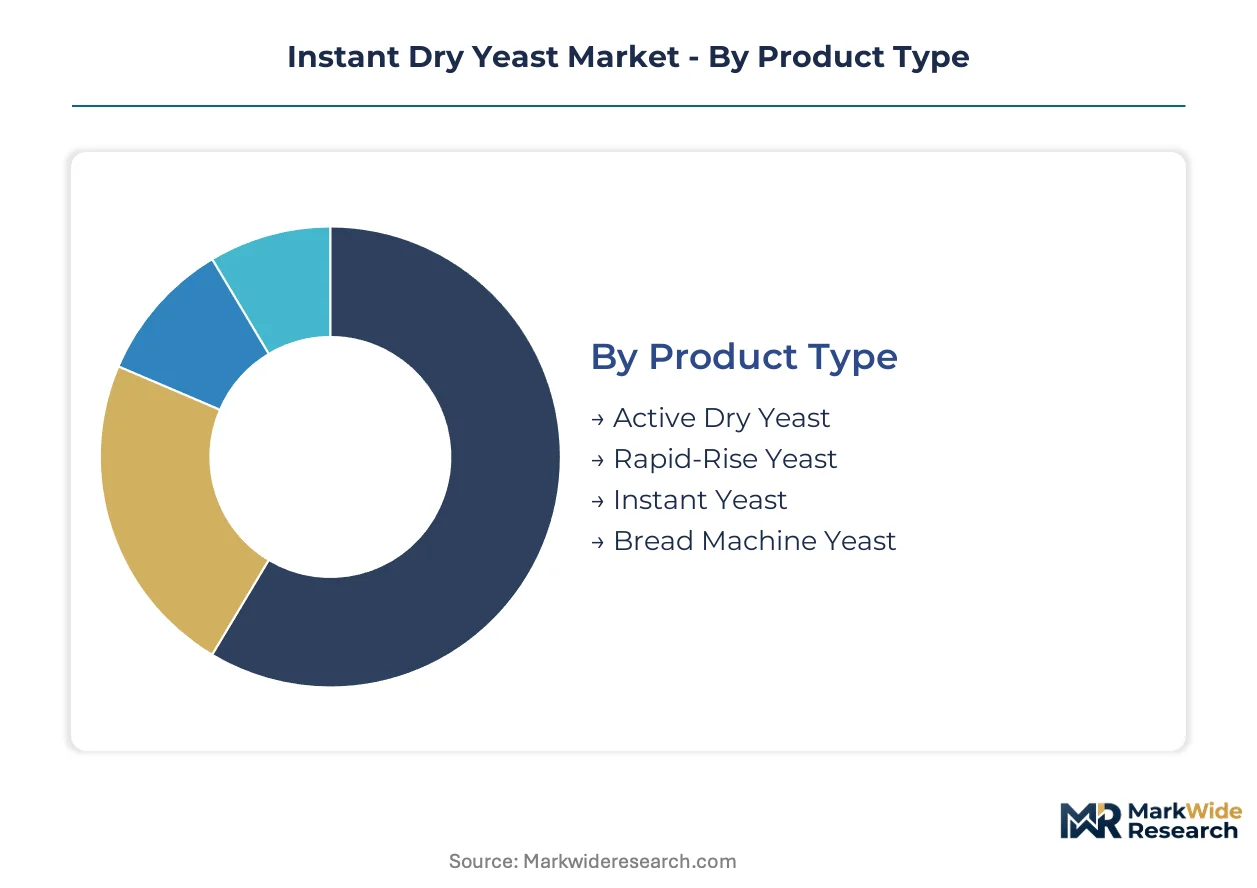
Instant dry yeast segmentation reveals how product specifications, usage contexts, and buyer economics fragment demand across distinct technical and commercial profiles. Strain development priorities, packaging formats, and distribution channels diverge sharply between home baking convenience seekers and industrial fermentation operators.
Product Type:
Integration depth varies dramatically: instant yeast functions as a standalone input requiring no proofing, while bread machine yeast embeds proprietary formulations optimized for specific appliance thermal profiles.
- Instant Yeast:Saccharomyces cerevisiae dried to sub-8% moisture with vacuum-sealed ambient stability. Commercial bakers in Germany's Munich-Stuttgart corridor specify this format for direct incorporation into high-throughput mixing systems without hydration protocols.
- Rapid-Rise Yeast:Accelerated fermentation strains with elevated ascorbic acid content and finer particle distribution. Home baking channels in US supermarket aisles concentrate demand here, though private-label displacement is compressing brand premiums.
- Active Dry Yeast:Legacy format requiring 100-110°F proofing activation retains price-sensitive foodservice penetration in emerging markets where equipment retrofit capital is scarce.
- Bread Machine Yeast:Appliance-specific strains calibrated for single-cycle thermal programs with extended shelf stability additives.
Volume placements concentrate in Instant Yeast; the faster expansion belongs to Rapid-Rise Yeast.
Application:
Cost tier stratification separates commodity baking inputs from premium confectionery strains where fermentation tolerance and flavor neutrality command technical service attachments.
- Baking:Artisan bread applications in France and Italy drive specialized Saccharomyces cerevisiae variants with extended cold fermentation tolerance and enhanced aromatic compound production during long proof cycles.
- Confectionery:Low-temperature fermentation strains with minimal residual sugar metabolism preserve delicate pastry structures. EU F-Gas Regulation compliance is forcing thermal profile revalidation in industrial facilities.
- Snacks:High-osmotic-tolerance strains for cracker and savory biscuit doughs with elevated salt and fat matrices.
- Brewing:Distinct fermentation kinetics with alcohol tolerance thresholds separate brewing strains from baking applications, though some integrated producers leverage shared manufacturing infrastructure.
Margin pools concentrate in Confectionery; the steepest volume trajectory belongs to Baking.
Form:
Automation compatibility distinguishes pellet and tablet formats designed for pneumatic conveying systems from legacy granulated handling.
- Granulated:Free-flowing particles with standardized 0.5-2.0mm sizing dominate current installed base. Manual handling protocols persist in mid-cap bakeries where automated dispensing capital outlays remain prohibitive.
- Pellets:Compressed spherical formats with enhanced flowability and reduced dust generation. Large-scale US Midwest facilities are installing precision dosing equipment calibrated for pellet geometry.
- Instant:Finely milled rapid-dissolution particles for direct dry incorporation without pre-hydration.
- Tablets:Unit-dosed compressed formats for small-batch artisan operations and home baking convenience segments.
Procurement gravity centers on Granulated; the fastest share gains belong to Pellets.
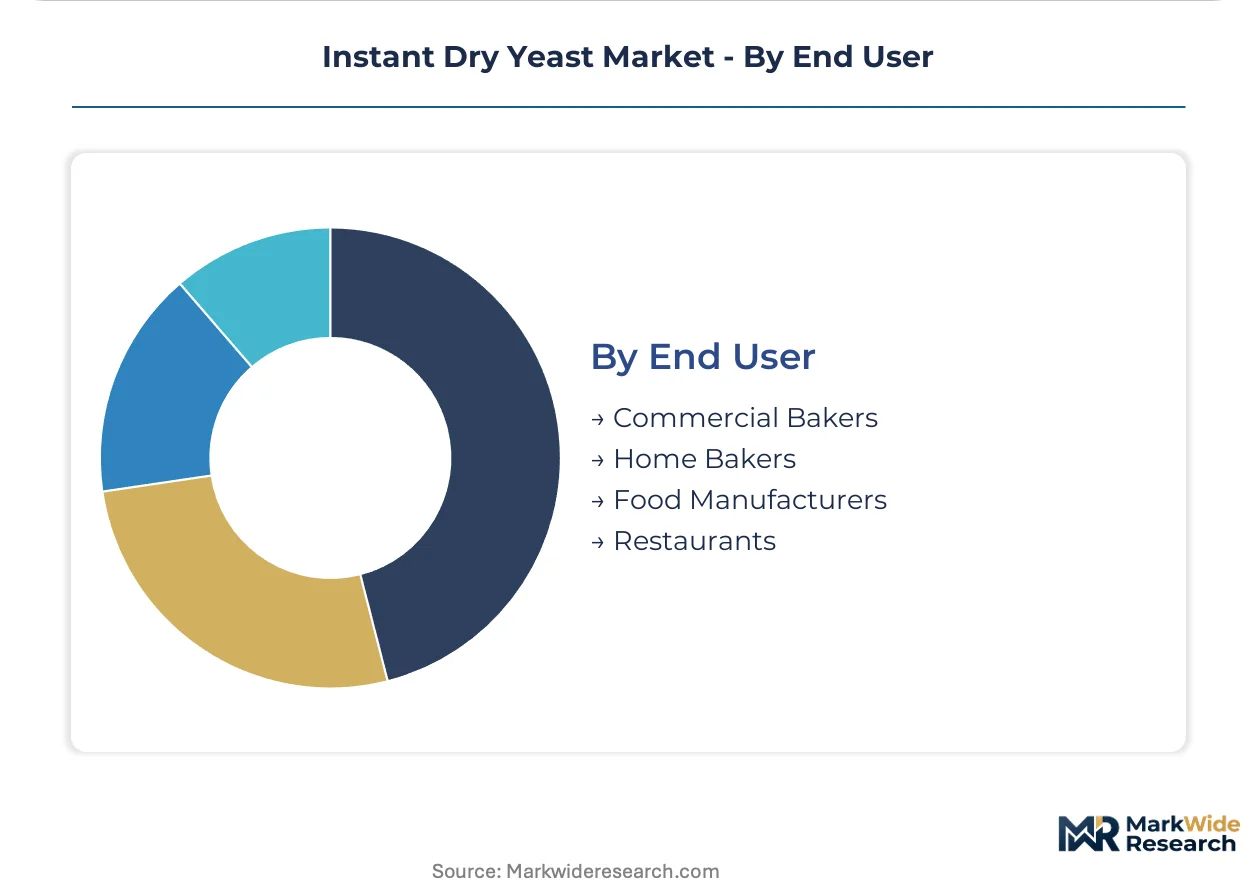
End User:
Customer type determines contract structure: long-term supply agreements with technical service bundles for commercial bakers versus transactional retail purchases by home bakers.
- Commercial Bakers:Industrial-scale operations in Germany's bakery clusters negotiate strain-specific supply contracts with fermentation performance guarantees and on-site technical consultation. This segment generates the deepest margin pools through volume commitments and captive technical service revenue.
- Food Manufacturers:Processed food producers integrate instant dry yeast into frozen dough and par-baked product lines, requiring thermotolerant strains for variable thermal processing environments.
- Home Bakers:Supermarket and discounter channel purchases concentrate in single-serve sachet formats where convenience positioning outweighs strain provenance.
- Restaurants:Foodservice operators with in-house baking programs represent fragmented demand with limited backward integration into strain specification.
Revenue concentration sits with Commercial Bakers; the expanding participation rate belongs to Food Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in yeast manufacturing clusters across Germany, China, and the United States, while consumption patterns diverge between artisan bread demand in Western Europe and industrial baking scale in Asia-Pacific. Supply chain configuration reflects this geographic split: European facilities emphasize strain specialization for premium applications, Chinese producers leverage integrated sugar-to-yeast processing for cost leadership, and North American operations balance bulk industrial supply with rapid-rise retail formats.
Germany
Artisan bread specifications from Munich and Stuttgart bakery clusters are driving specialized Saccharomyces cerevisiae strain development with extended cold fermentation tolerance. EU F-Gas Regulation compliance mandates are forcing industrial bakeries to retrofit refrigeration-dependent fermentation systems, creating captive demand for thermotolerant variants. The Baden-Württemberg region anchors continental European yeast manufacturing with integrated strain laboratories serving artisan and industrial channels simultaneously.
China
Integrated yeast extract and baking ingredient portfolios from domestic producers are capturing downstream value in processed food manufacturing. The country's national food safety regulator maintains stringent strain approval protocols that extend product introduction timelines. Yangtze River Delta manufacturing complexes combine beet molasses processing with fermentation capacity, achieving backward integration that insulates margin predictability from agricultural commodity cycles.
United States
FDA GRAS determinations and USDA organic certification standards govern strain commercialization pathways for domestic and export markets. Industrial bakeries across the Midwest are installing automated pellet dispensing systems, displacing legacy granulated yeast handling protocols. Chicago and Minneapolis-St. Paul corridor facilities represent the densest concentration of large-scale baking operations adopting pneumatic conveying infrastructure.
France
Confectionery applications requiring low-temperature fermentation strains with minimal residual sugar metabolism command technical service attachments and premium positioning. EFSA novel food assessment timelines extend 18-36 months, freezing pipeline velocity for innovative strain introductions. The Île-de-France region concentrates industrial baking demand alongside regulatory and technical consultation capabilities serving pan-European markets.
Italy
Premium pastry and traditional bread applications sustain demand for specialized fermentation strains with enhanced aromatic compound production. EU F-Gas Regulation phase-down schedules are accelerating variable-speed compressor and heat recovery system installations in industrial facilities. Emilia-Romagna bakery clusters specify strains optimized for long proof cycles characteristic of regional bread traditions.
Instant Dry Yeast Market Competitive Environment
The competitive structure tilts toward integrated multinational producers with captive sugar processing and strain development capabilities. Three archetypes dominate: continental European specialists with artisan bread technical service attachments, Asia-Pacific integrated producers leveraging yeast extract diversification, and North American bulk suppliers optimized for automated industrial dispensing. Capacity expansion and portfolio diversification into savory flavor enhancers represent the dominant competitive moves.
Within the integrated multinational tier, Lallemand Inc. and Lesaffre exemplify divergent geographic anchoring strategies, while Angel Yeast occupies a position bridging fermentation inputs and downstream extract applications. Lallemand's North American manufacturing footprint serves high-volume food manufacturers through bulk industrial formats. Lesaffre's European base supports specialized strain development for artisan bread specifications. Angel Yeast's Asia-Pacific dominance reflects integrated portfolios spanning yeast extract and baking ingredients.
| Leading Market Players |
|---|
| Lallemand Inc. |
| Pakmaya |
| Lesaffre |
| DCL Yeast Ltd. |
| Chr. Hansen Holding A/S |
| AB Mauri |
| Red Star Yeast |
| Imperial Yeast |
| Angel Yeast |
| Others |
Value Chain & Pricing Dynamics
Backward integration into captive molasses processing anchors both supply security and pricing power for leading producers, insulating margin predictability from beet and cane commodity cycles while compressing input cost exposure for integrated operators.
Pricing Analysis
Margin tightening in bulk industrial formats reflects the collapse of single-serve sachet procurement among commercial bakers. Three-tier pricing structure across premium certified strains, standard industrial grades, and economy active dry alternatives separates contract-based long-term offtake agreements from spot commodity purchases. Cost-down pressure on granulated formats accelerates because automated pellet dispensing systems demand reformulated flowability specifications. Foodservice operators in emerging markets retain the highest price sensitivity, while artisan bakery clusters in Germany absorb premiums for specialized cold-fermentation strains.
Supply Chain Analysis
USDA organic and non-GMO Project Verified certification gating is hardening procurement criteria across retail channels. Manufacturing gravity centers on Germany, China, and the United States, with Yangtze River Delta complexes achieving full backward integration from beet molasses through fermentation. Raw material dependencies draw from agricultural sugar processing, specialized strain laboratory capacity, and vacuum-sealing packaging infrastructure. Single-source vulnerability concentrates in thermotolerant strain development capabilities. Distribution runs through long-term supply contracts with technical service attachments for commercial bakers, supplemented by supermarket and discounter retail channels for home baking formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pellet format automation is displacing legacy granulated handling systems, creating a technology-transition phase where fermentation performance guarantees replace commodity supply relationships as the basis of competition.
For Market Incumbents: Lock in artisan bakery clusters through captive strain development partnerships and on-site fermentation consulting services. Deepen backward integration into regional molasses processing to defend margin predictability against agricultural commodity volatility. Prioritize thermotolerant strain portfolios to capture EU F-Gas Regulation retrofit demand across German, French, and Italian industrial facilities. For New Entrants and Emerging Players: Enter via private-label rapid-rise formats in supermarket discounter channels where brand loyalty cycles are compressing. Target home baking segments in Asia-Pacific markets where Angel Yeast's integrated extract portfolios have not fully penetrated retail baking aisles. Lead with clean-label certification as the primary go-to-market angle to bypass incumbent technical service bundling. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated multinational producers seeking regional manufacturing footprints or specialized strain libraries. Long-term viability favors operators with verified low-carbon fermentation processes and Scope 3 disclosure capabilities aligned with EU CSRD mandates. Watch carbon-footprint procurement criteria hardening in retail channels as the signal for margin premium inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Development Partnership | Captures artisan bakery demand through Munich-Stuttgart cluster technical attachments. |
| Backward Integration into Molasses Processing | Insulates margin predictability from beet and cane agricultural commodity cycles. |
| Pellet Format Manufacturing Scale-Up | Aligns with automated dispensing adoption across US Midwest industrial facilities. |
| Clean-Label Certification Program | Unlocks USDA organic and non-GMO Project Verified procurement premiums. |
| Yeast Extract Portfolio Diversification | Captures downstream savory flavor enhancer demand from processed food manufacturers. |
Study Parameters
Multi-period observation of strain approval timelines, molasses price indices, and automated dispensing system installations anchored the trend analysis, supplemented by interviews with fermentation scientists, commercial bakery procurement directors, and yeast extract product managers. Secondary validation drew from FDA GRAS determination filings, EFSA novel food assessment registers, EU F-Gas Regulation implementation reports, and customs trade data on molasses and dried yeast shipments. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, form, and end-user segments.
Segment-weighting applied differentiated growth assumptions by format automation penetration, certification adoption curves, and regional regulatory enforcement intensity. Modeled dimensions spanned instant, rapid-rise, active dry, and bread machine product types; baking, confectionery, snack, and brewing applications; granulated, pellet, instant, and tablet forms; and commercial baker, food manufacturer, home baker, and restaurant end users. CAGRs derived from fitted growth curves applied to base-year volume estimates, incorporating strain development pipeline velocity and EU refrigeration retrofit schedules as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA assessment timeline extensions or molasses supply disruptions from climate-affected harvests. Model outputs reflect assumptions on artisan bread demand persistence, automation capital expenditure cycles, and clean-label certification penetration rates. A model refresh is warranted upon material change in EU F-Gas Regulation phase-down schedules or USDA organic certification standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Pet Food Ingredients Market
Ingredients
France Sodium Reduction Ingredients Market
Ingredients
Xylooligosaccharide Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Commercial Flour Market
Ingredients
Chickpea Protein Ingredients Market
Ingredients
Dry Molasses Products Market
Ingredients
Jasmine Extract Market
Ingredients
Confectionery Ingredients Market
Ingredients
Flaxseed Derivatives Market
Ingredients
India Olive Oil Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Hydrogenated Starch Market
Ingredients
Yeast Autolysates Market
Ingredients
North America Cheese Powder Market