
 South America Lipid Market | 2026-2036
South America Lipid Market Size, Share, and Industry Trends Forecast 2026-2036
South America Lipid Market Analytics
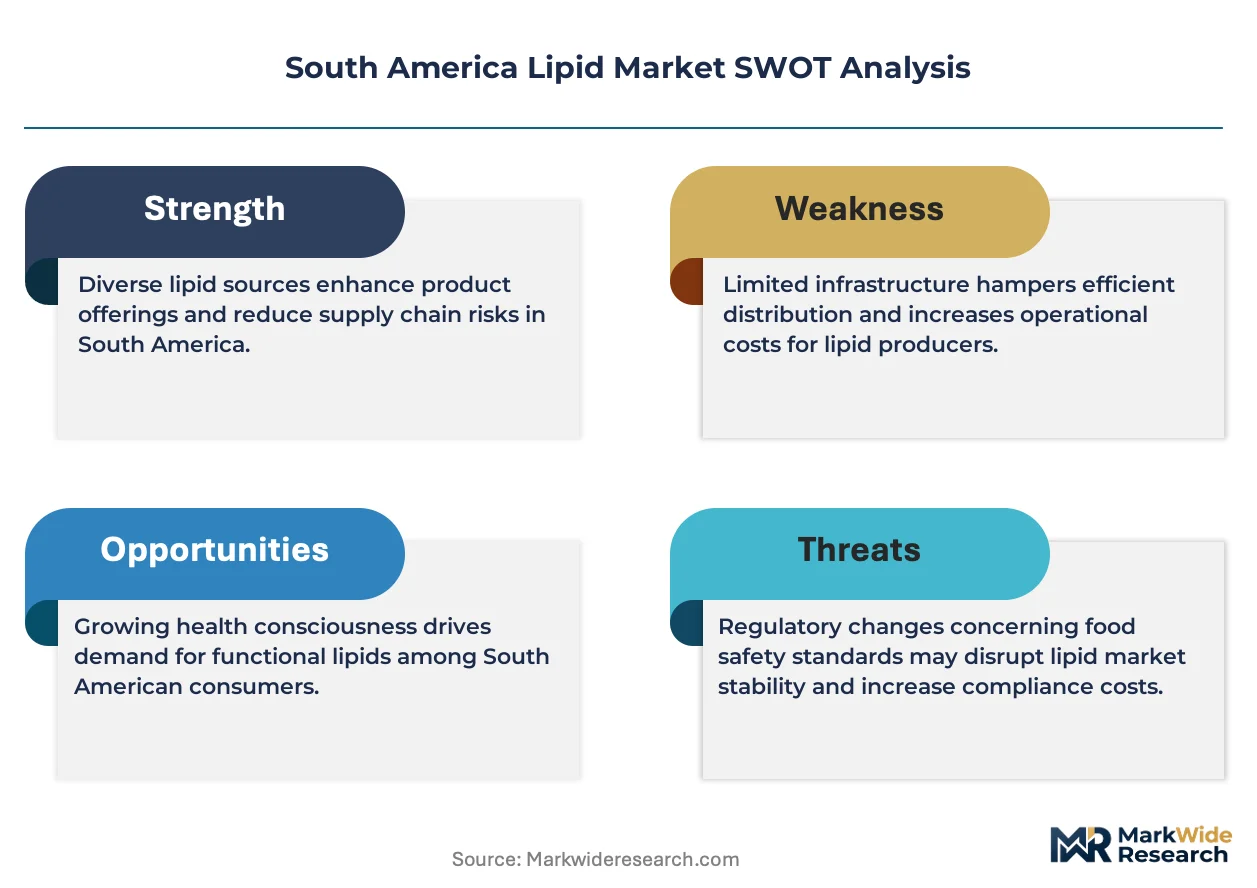
Ingredient procurement channels between Argentine soybean processors and Brazilian pharmaceutical formulators is reconfiguring as contract structures shift from spot trading to multi-year supply agreements. Cargill Incorporated anchors crushing capacity across the Paraná River basin with integrated oilseed processing infrastructure. Archer Daniels Midland Company leverages its Paraguayan logistics network to compete on delivered cost into São Paulo industrial zones. BASF SE differentiates through pharmaceutical-grade lipid excipient certification that commands premium positioning in regulated drug applications.
Lipids comprise a chemically diverse class of hydrophobic or amphiphilic organic compounds including triglycerides, phospholipids, and sterols, typically characterized by solubility in nonpolar solvents and structural roles in cellular membranes or energy storage. Industrial production employs solvent extraction, mechanical pressing, or enzymatic modification to achieve specified iodine values and fatty acid profiles for targeted functionality. The fats and oils product category dominates volume throughput given soybean and palm feedstock abundance across the continent, while phospholipids generate disproportionate margin contribution from pharmaceutical and nutraceutical end users. Nutraceutical applications are expanding fastest as Brazilian consumers seek omega-3 and phosphatidylserine supplements, though emulsifier demand in processed foods sustains the largest absolute consumption base.
ANVISA governs pharmaceutical lipid excipient registration through resolution-driven quality protocols that mandate traceability from raw material to finished dosage form. Brazil's Ministry of Agriculture (MAPA) enforces edible oil identity standards under Normative Instruction parameters that restrict adulteration and specify fatty acid composition thresholds for commercial classification. Argentina's National Food Commission (CONAL) aligns with Mercosur harmonized codes for lipid labeling and trans fat limits, creating cross-border compliance obligations for suppliers operating in both markets. Stakeholders must monitor pending Mercosur technical regulations on novel lipid ingredients and pre-position manufacturing documentation to avoid market access delays when standards crystallize.
Market Dynamics
ANVISA's tightening bioequivalence protocols for lipid-based drug delivery systems are forcing pharmaceutical formulators across Brazil to upgrade excipient traceability infrastructure, compressing supplier qualification timelines and redistributing procurement power toward certified manufacturers.
Growth Catalysts
- ANVISA Resolution-Driven Quality Mandates:Brazil's pharmaceutical regulator now requires end-to-end documentation for lipid excipients, pulling demand toward pre-qualified suppliers with established certification.
- Nutraceutical Omega-3 Supplementation:Brazilian consumers are expanding phosphatidylserine and omega-3 consumption, creating volume pull through retail pharmacy channels.
- Paraná River Basin Crushing Concentration:Integrated soybean processing infrastructure along this waterway secures feedstock access for specialty phospholipid production.
Market Restraints
- Soybean Oil Price Volatility:Argentine crop yields and currency instability transmit directly into input cost swings for regional processors.
- Pharmaceutical-Grade Certification Scarcity:Few South American facilities maintain the documentation depth required for ANVISA's evolving standards, concentrating viable supply.
- Palm Oil Substitution Pressure:Malaysian and Indonesian palm derivatives compete on cost in food emulsifier applications, pressuring regional soybean-derived alternatives.
Strategic Opportunities
- Buenos Aires Province Nutraceutical Cluster:Argentina's concentrated demand node for specialty phospholipids offers anchor tenancy for dedicated production facilities.
- Enzymatic Modification Technology:Precision biocatalysis enables custom fatty acid profiles for pharmaceutical liposome formulations, opening premium positioning.
- Multi-Year Supply Contracting:Brazilian formulators are abandoning spot markets for structured agreements, creating predictable offtake for processors willing to lock capacity.
Industry Challenges
- Cross-Border Mercosur Harmonization Delays:Pending technical regulations on novel lipid ingredients create documentation uncertainty for suppliers operating in both Brazilian and Argentine markets.
- Pharmaceutical Excipient Qualification Timelines:ANVISA's traceability mandates extend supplier onboarding cycles, straining working capital for mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Lipid Market |
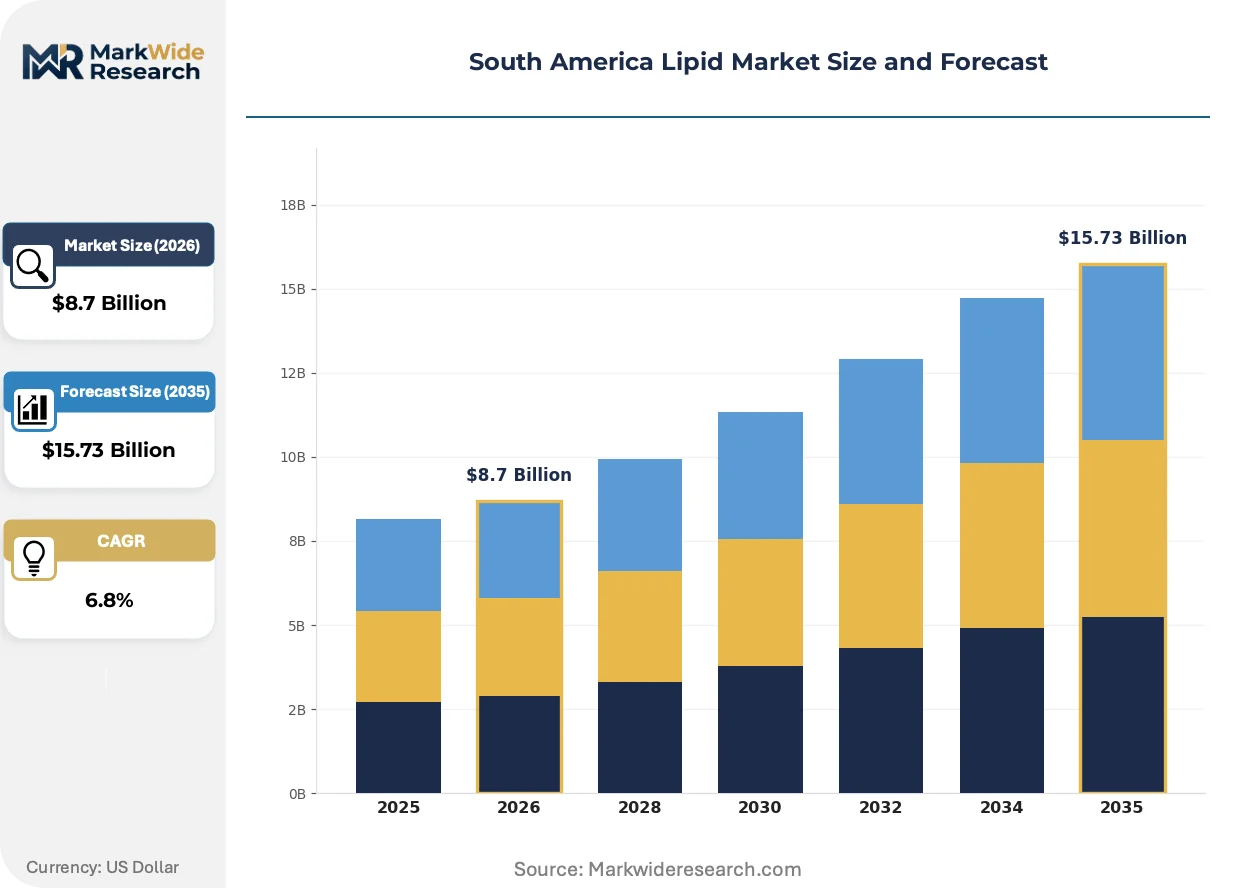
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fats, Oils, Phospholipids, Fatty Acids End User: Food Industry, Cosmetics, Pharmaceuticals, Nutraceuticals Application: Emulsifiers, Flavoring Agents, Nutritional Supplements, Skin Care Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, BASF SE, Croda International PLC, Clover Corporation Limited, Arista Industries, Ingredion Inc., Kerry Group plc, Tate and Lyle PLC, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Lipid Market Evolving Landscape
Digital traceability infrastructure and enzymatic processing advances are compressing the gap between commodity oilseed crushing and pharmaceutical-grade lipid production, while regulatory harmonization pressures are reshaping cross-border supply relationships.
Blockchain-enabled supply chain verification is digitizing documentation flows for lipid excipients moving from Argentine soybean processors to Brazilian pharmaceutical formulators. ANVISA's audit requirements are accelerating adoption among mid-scale suppliers seeking to reduce qualification friction. This technology is digitizing compliance cost structures, forcing technology laggards toward consolidation or exit.
MAPA's edible oil identity standards under Normative Instruction parameters are tightening fatty acid composition thresholds for commercial classification. The enforcement mechanism is pushing adulteration-prone suppliers toward laboratory investment or market withdrawal. Processed food manufacturers sourcing emulsifiers face reformulation costs as non-compliant batches face seizure risk.
Contract structures between oilseed crushers and pharmaceutical buyers are hardening from spot trading toward multi-year supply agreements with indexed pricing. Brazilian formulators in São Paulo industrial zones are locking capacity to secure ANVISA-ready documentation. This pattern is most visible in phospholipid procurement, where qualified supplier scarcity has inverted traditional buyer leverage.
South America Lipid Market Segmentation
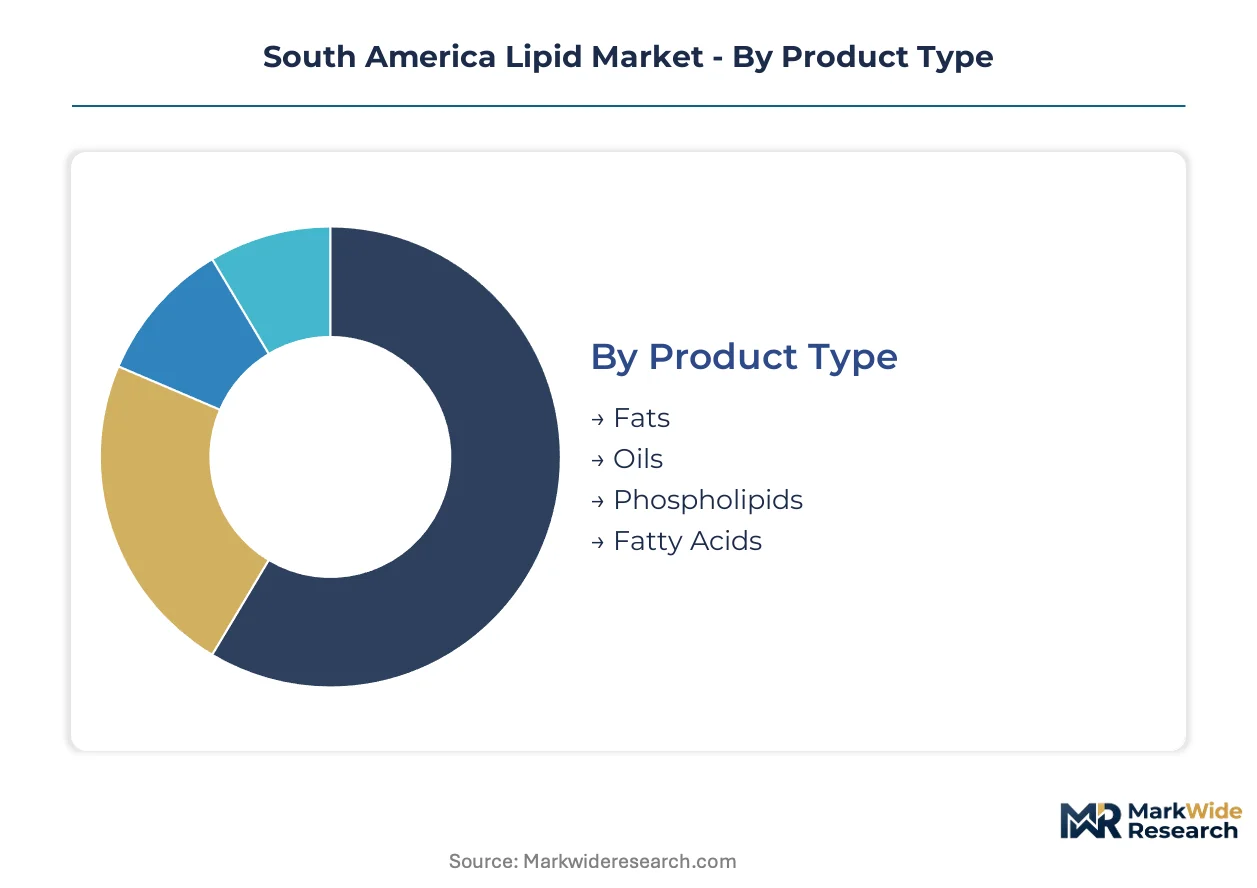
South American lipid procurement patterns diverge sharply across product grades and end-use specifications. ANVISA's pharmaceutical traceability mandates and MAPA's edible oil identity standards create tiered compliance obligations that reshape how buyers segment their supplier base.
Product Type:
Cost tier positioning separates commodity crushing outputs from certified excipient grades capable of commanding premium placement.
- Fats:Rendered animal and hydrogenated vegetable fats serve bakery and confectionery manufacturers across São Paulo industrial corridors. Argentine tallow processors face margin compression from Brazilian soy-based alternatives in shortening applications.
- Oils:Refined soybean and palm derivatives dominate volume throughput, with Paraná River basin crushers supplying bulk feedstock for both food and industrial applications. Currency volatility in Argentina transmits directly into pricing instability for regional buyers.
- Phospholipids:Concentrated demand from Buenos Aires province nutraceutical formulators.
- Fatty Acids:Fractionation outputs for surfactant and lubricant industries.
Fats and Oils hold installed capacity. Phospholipids is rotating up the share rankings.
End User:
Application maturity determines supplier qualification depth and contract structure rigidity.
- Food Industry:Processed meat, dairy, and baked goods manufacturers consume the largest absolute volumes. MAPA's Normative Instruction enforcement on fatty acid composition thresholds is forcing reformulation investments among emulsifier-dependent producers.
- Pharmaceuticals:Lipid-based drug delivery systems in Brazil require ANVISA-mandated end-to-end documentation. Excipient traceability infrastructure separates qualified suppliers from commodity crushers locked out of regulated channels.
- Nutraceuticals:Omega-3 and phosphatidylserine supplementation is climbing fastest among Brazilian retail pharmacy consumers.
- Cosmetics:Skin care formulators in Argentina source specialty lipids for emollient applications.
Food Industry holds installed capacity. Nutraceuticals is rotating up the share rankings.
Application:
Functional performance requirements stratify procurement between commodity specification and custom synthesis.
- Emulsifiers:Mono- and diglycerides stabilize processed food matrices across Mercosur trade corridors. Malaysian palm-derived competitors pressure regional soybean-based suppliers on delivered cost into Brazilian food manufacturing zones.
- Nutritional Supplements:Softgel encapsulation and powder formulations for omega-3 and phospholipid delivery. Buenos Aires province concentration creates geographic clustering of demand for high-purity grades.
- Flavoring Agents:Lipid carriers for fat-soluble flavor compounds.
- Skin Care:Emollient and occlusive functions in cosmetic formulations.
Emulsifiers hold installed capacity. Nutritional Supplements is rotating up the share rankings.
Distribution Channel:
Customer scale and documentation requirements determine channel selection and working capital intensity.
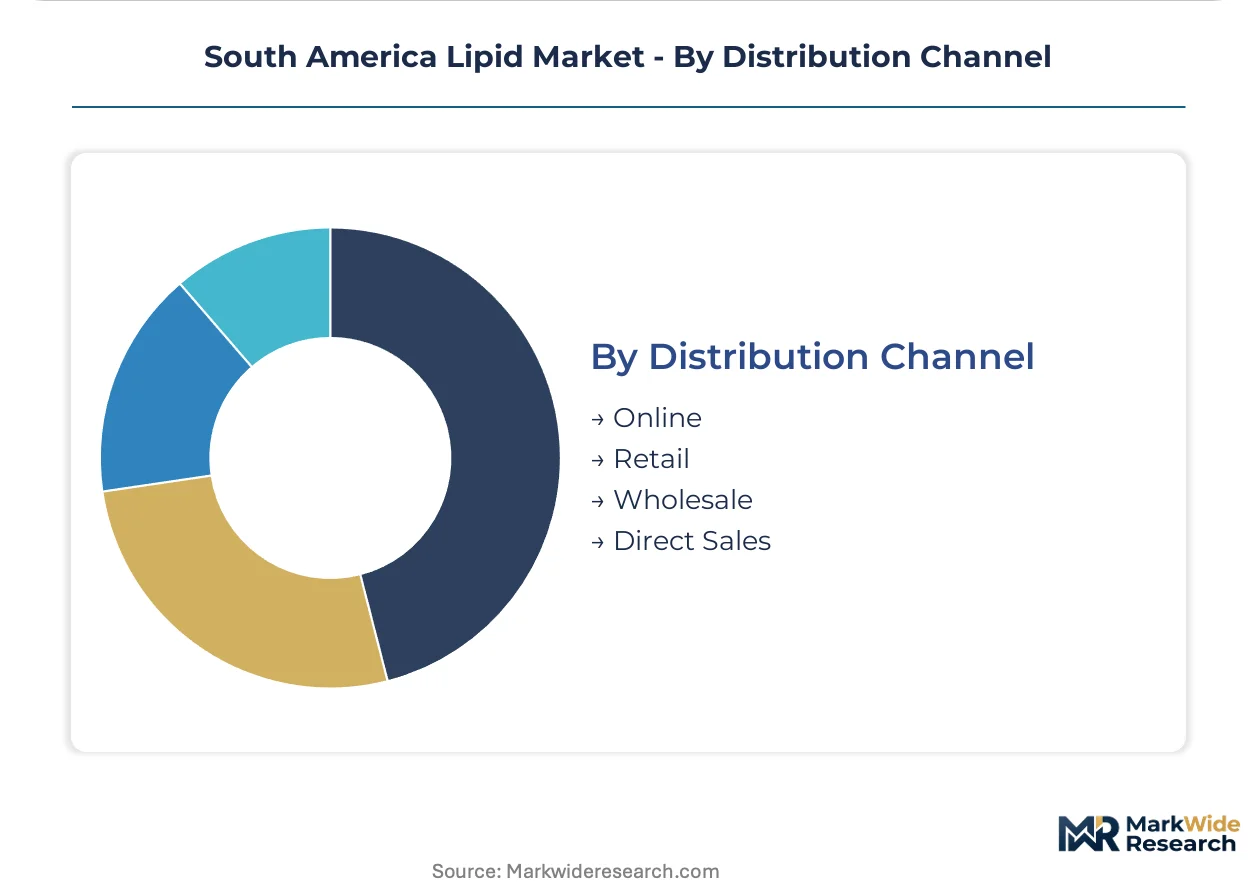
- Direct Sales:Pharmaceutical formulators in São Paulo industrial zones negotiate multi-year supply agreements with indexed pricing. ANVISA qualification timelines favor direct relationships over intermediated procurement.
- Wholesale:Food industry buyers leverage distributors for spot market flexibility on commodity grades. Argentine currency instability complicates cross-border wholesale arrangements.
- Retail:Nutraceutical finished products reach Brazilian consumers through pharmacy chains.
- Online:Emerging channel for specialty lipid ingredients to small-scale formulators.
Wholesale holds installed capacity. Direct Sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentine soybean processors extract margin premiums through Paraná River logistics, while Brazilian pharmaceutical formulators absorb compliance costs from ANVISA's tightening traceability mandates. This pricing-power asymmetry redistributes value capture upstream toward crushing infrastructure and downstream toward certified excipient channels.
Brazil
São Paulo industrial zones concentrate lipid demand from pharmaceutical formulators seeking ANVISA-qualified excipients. The regulator's bioequivalence resolution mandates end-to-end documentation, compressing supplier qualification timelines. Cargill's integrated crushing capacity along the Paraná River basin secures feedstock access for specialty phospholipid production serving regulated drug applications.
Argentina
Buenos Aires province anchors concentrated demand for nutraceutical-grade phospholipids, with local formulators driving volume through omega-3 and phosphatidylserine supplementation. CONAL aligns lipid labeling with Mercosur harmonized codes, creating cross-border compliance obligations. Soybean processors in the Pampas region leverage currency-adjusted export pricing to capture margin from Brazilian buyers.
Paraguay
Archer Daniels Midland's logistics network positions Paraguayan crushing capacity to compete on delivered cost into São Paulo industrial corridors. The country's central location enables transshipment arbitrage between Argentine feedstock and Brazilian demand. Integrated oilseed infrastructure along the Paraguay River supports bulk lipid exports with lower regulatory compliance burdens than pharmaceutical-grade channels.
Chile
Santiago-based nutraceutical distributors source specialty lipids for domestic omega-3 supplementation markets. The country's food safety agency enforces trans fat limits that exceed baseline Mercosur thresholds, creating a premium tier for compliant suppliers. Northern mining regions generate industrial fatty acid demand for surfactant applications in mineral processing.
Colombia
Bogotá pharmaceutical manufacturers import lipid excipients through direct sales channels to meet bioequivalence documentation requirements. The national food and drug surveillance institute maintains import registration protocols that favor pre-qualified suppliers with established traceability systems. Andean region cosmetic formulators drive modest demand for emollient-grade lipids in skin care applications.
South America Lipid Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying certified grades to regulated channels. The South American lipid market structures around three tiers: multinational agribusinesses with integrated crushing infrastructure, chemical conglomerates with pharmaceutical-grade certification, and regional processors competing on commodity volume. Competitive dynamics center on backward integration into feedstock sourcing and multi-year supply contracting to lock pharmaceutical offtake.
Among the integrated agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven platform players with Paraná River basin infrastructure. BASF SE occupies the specialty chemical position, differentiating through pharmaceutical-grade lipid excipient certification that commands premium placement. Croda International PLC represents the mid-tier specialist archetype, competing on custom fatty acid profiles for nutraceutical applications.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| BASF SE |
| Croda International PLC |
| Clover Corporation Limited |
| Arista Industries |
| Ingredion Inc. |
| Kerry Group plc |
| Tate and Lyle PLC |
| Others |
Value Network & Pricing Analysis
Undercapacity in Argentine pharmaceutical-grade phospholipid production drives aggressive capacity reservation behavior among Brazilian formulators, compressing spot market liquidity and forcing indexed pricing structures that tether contract values to soybean futures and currency baskets.
Pricing Analysis
The customization-premium spread between ANVISA-certified excipients and commodity-grade lipids has widened as traceability documentation becomes a priced attribute. Pharmaceutical formulators in São Paulo absorb premium-mid-economy pricing differentiation based on certification depth, with BASF SE and Croda International PLC commanding the top tier. Pricing pressure stems from Malaysian palm oil substitution in food emulsifier segments, eroding margins for regional soybean-derived alternatives. Food industry buyers exhibit highest price sensitivity, while pharmaceutical procurement teams prioritize documentation reliability over unit cost.
Supply Chain Analysis
Contract-manufacturing concentration in the Paraná River basin anchors regional supply, with Cargill Incorporated and Archer Daniels Midland Company holding integrated crushing and fractionation capacity. Argentina, Brazil, and Paraguay constitute the geographic core, drawing from Pampas-region soybean feedstock, Malaysian palm kernel imports, and domestic tallow rendering. Supply chain risk centers on Argentine currency volatility transmitting into input cost instability. Distribution runs through direct sales channels for pharmaceutical grades and wholesale networks for commodity food applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America lipid market sits at a platform-economics inflection where ANVISA's digital traceability mandates are creating interoperability standards that favor pre-qualified supplier networks over transactional procurement.
For Market Incumbents: Insulate qualified supplier positioning through captive phospholipid fractionation capacity in Buenos Aires province, defending against enzymatic modification specialists encroaching on custom fatty acid profiles. Deepen backward integration into Paraná River basin crushing infrastructure to secure feedstock preference during Argentine harvest volatility. Lock multi-year offtake agreements with São Paulo pharmaceutical formulators before competitor qualification cycles complete.
For New Entrants and Emerging Players: Pursue white-space opportunity in blockchain-enabled documentation services for mid-scale Argentine processors seeking ANVISA qualification friction reduction. Target nutraceutical omega-3 encapsulation in Chile and Colombia, where trans fat regulations exceed Mercosur baselines and create premium tier access. Deploy enzymatic biocatalysis capabilities as differentiation wedge against established solvent extraction players.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade lipid excipient production as qualification infrastructure and digital traceability systems become table stakes. Long-term viability favors platform integrators with crushing-to-certification pipeline control rather than standalone commodity processors. Monitor ANVISA resolution implementation velocity as signal for supplier consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Paraná River Crushing | Cargill's integrated infrastructure secures feedstock preference during Argentine currency volatility. |
| ANVISA Certification Investment | BASF SE's pharmaceutical-grade documentation commands premium positioning in São Paulo drug formulation. |
| Multi-Year Supply Agreement Lock | Brazilian formulators abandon spot markets to secure qualified phospholipid capacity ahead of competitor onboarding. |
| Enzymatic Modification Technology Deployment | Precision biocatalysis enables custom liposome profiles for differentiated nutraceutical applications. |
| Blockchain Traceability Implementation | Digital documentation reduces ANVISA qualification friction for mid-scale Argentine soybean processors. |
Research Methodology
Operator-level perspectives from phospholipid plant managers, pharmaceutical procurement leads at São Paulo formulators, ANVISA regulatory affairs specialists, and Buenos Aires nutraceutical R&D directors anchored the qualitative base. Secondary validation drew from ANVISA resolution texts, MAPA Normative Instruction parameters, Mercosur technical regulation drafts, Argentine customs export data, and Brazilian pharmaceutical import registrations. Bottom-up capacity modeling across Paraná River basin crushing facilities triangulated against top-down demand segmentation by end-use application.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product grade tier, end-use industry vertical, and regional regulatory cluster. CAGRs derived from feedstock cost trajectory modeling, pharmaceutical excipient demand elasticity, and nutraceutical consumption pattern analysis. Forecast inputs incorporated Argentine soybean yield volatility, Brazilian real currency band assumptions, and palm oil substitution elasticity in food emulsifier segments.
Sensitivities concentrate around ANVISA resolution implementation timing, Mercosur harmonization delays, and Argentine harvest shocks. Forecasts reflect documented assumptions on certification adoption curves and contract structure migration velocity. Quarterly review of ANVISA audit completion rates, Argentine crushing margin spreads, and multi-year contract announcement flow is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Oat Grass Powder Market
Ingredients
Demineralized Whey Powder Ingredient Market
Ingredients
Ben Oil Market
Ingredients
Corn Steep Liquor Market
Ingredients
Wheat Malt Market
Ingredients
Europe BBQ Charcoal Market
Ingredients
Milk Ingredients Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Corn-Based Ingredients Market
Ingredients
Egg Membrane Powder Market
Ingredients
North America Carrageenan Market
Ingredients
Europe Whey Protein Ingredients Market
Ingredients
Global Dietary Fibers Market
Ingredients
Asia-Pacific Soy Protein Concentrate Market
Ingredients
Kilned Malt Market
Ingredients
Sesame Seed Extract Market