
 Low-Fat and Low Protein Diet Market | 2026-2036
Low-Fat and Low Protein Diet Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat and Low Protein Diet Market Foresight
The gap between premium clinical-grade formulations and commodity shelf-stable products is expanding. General Mills Inc. leverages its cereal R&D infrastructure to develop reduced-protein grain platforms for metabolic condition management. Kerry Group PLC sustains ingredient innovation pipelines that supply flavor-masked, low-fat protein alternatives to therapeutic food manufacturers. Archer Daniels Midland Company anchors North American supply chains with plant-based lipid and carbohydrate systems designed for restricted-diet applications.
Low-fat and low protein diets restrict lipid intake to below thirty percent of total caloric consumption and limit protein to quantities compatible with impaired organ function, typically achieved through modified starch bases, specialized oils, and controlled amino acid profiles. These diets serve clinical populations managing chronic kidney disease, certain hepatic disorders, and inherited metabolic defects where standard macronutrient loads accelerate disease progression. Plant-Based diet types are capturing margin pools as flexitarian consumers cross over into clinically positioned products, while Ready-to-Eat Meals represent the fastest-growing product form as hospital discharge nutrition and home-based renal care converge. Seniors dominate the consumer age group segmentation, though pediatric metabolic clinics are emerging as a high-loyalty prescription channel.
The U.S. FDA governs health claims and nutrient content labeling for restricted-diet foods, while the EMA and national European regulators coordinate clinical nutrition frameworks that classify medical foods separately from supplements. In Asia-Pacific markets, national food safety agencies enforce protein declaration standards that determine whether products qualify for reimbursement under public health programs. Stakeholders must monitor evolving reimbursement codes for dietitian-prescribed therapeutic nutrition, as coverage decisions will determine whether clinical-grade products achieve household penetration or remain confined to institutional procurement channels.
Market Dynamics
The U.S. FDA's updated nutrition labeling requirements for protein content claims are compressing formulation cycles across therapeutic food manufacturers, forcing R&D departments to revalidate entire product lines against stricter substantiation thresholds before market release.
Growth Catalysts
- Renal Patient Volume Expansion:Hospital clinical nutrition departments are scaling specialized meal programs for chronic kidney disease populations, creating institutional procurement pull for controlled-protein formulations.
- REACH-Compliant Lipid Innovation:European ingredient suppliers are commercializing novel plant-based lipid systems that meet restricted-diet purity standards while maintaining sensory acceptability.
- Germany's Aging Demographics:Dietitian-prescribed therapeutic nutrition plans are penetrating household channels as reimbursement frameworks expand coverage for home-based renal care.
Market Restraints
- Specialized Oil Input Volatility:Modified lipid feedstocks for low-fat therapeutic formulations face supply concentration among North American and European specialty chemical producers.
- Medical Food Classification Friction:EMA and national European regulators maintain divergent frameworks for clinical nutrition reimbursement eligibility, fragmenting market access.
- Flavor-Masking Technical Ceiling:Current palatability technologies for reduced-protein grain platforms hit formulation limits above 40% protein reduction without unacceptable taste degradation.
Strategic Opportunities
- Pediatric Metabolic Clinic Channel:Inherited metabolic defect treatment centers represent an underpenetrated prescription channel with high caregiver loyalty and recurring revenue profiles.
- Asia-Pacific Protein Declaration Harmonization:National food safety agencies are converging on standardized amino acid profiling methods that would unlock public reimbursement for imported clinical nutrition products.
- Ready-to-Eat Hospital Discharge Integration:Home-based renal care providers are sourcing pre-portioned therapeutic meals through direct-to-patient subscription models bypassing traditional pharmacy distribution.
Industry Challenges
- Clinical Dietitian Talent Scarcity:Formulation science programs lack sufficient graduates trained in amino acid profiling for organ-specific dietary restrictions.
- Dual Certification Timeline Compression:Products seeking both FDA medical food designation and EMA clinical nutrition classification face sequential review processes extending commercialization by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat and Low Protein Diet Market |
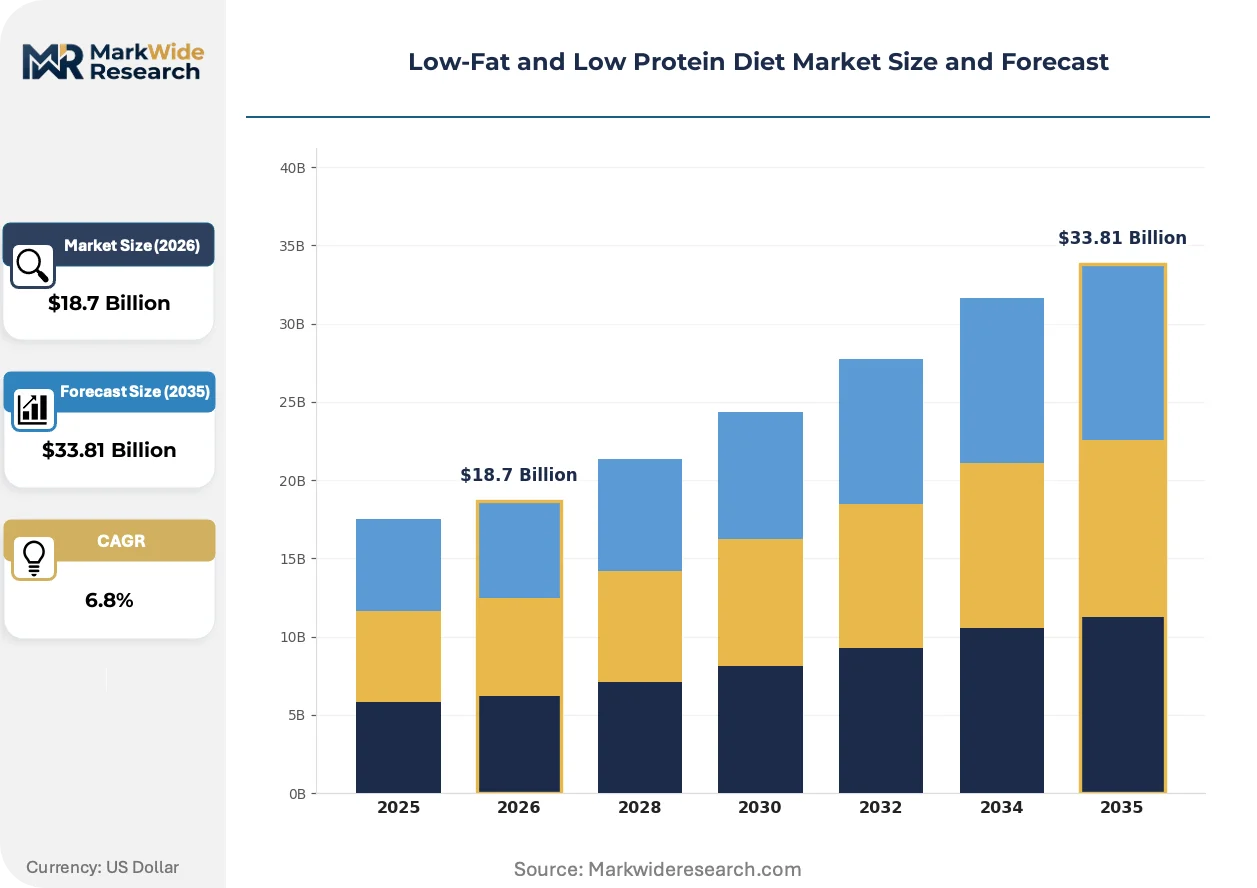
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Diet Type: Calorie Restriction, Ketogenic, Mediterranean, Plant-Based Consumer Age Group: Children, Young Adults, Middle-Aged, Seniors Product Form: Powders, Bars, Ready-to-Eat Meals, Supplements Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | General Mills Inc., Campbell Soup Company, Kerry Group PLC, Cargill, Kraft Foods Group Inc., Bel Brands, Sun-Maid, Archer Daniels Midland Company, Ingredion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat and Low Protein Diet Market Shifts & Advancements
Formulation science is converging with precision nutrition platforms to enable patient-specific macronutrient titration, while regulatory pressure on health claim substantiation is elevating clinical trial investment across the category.
Enzymatic protein hydrolysis is electrifying the development of controlled amino acid profiles for hepatic and renal applications. Metabolic condition management programs at major hospital systems are adopting these ingredient systems at accelerating procurement velocity. This technology is electrifying the shift from commodity shelf-stable products toward premium clinical-grade formulations with documented efficacy endpoints.
EMA's Medical Device Regulation framework is reclassifying certain enteral nutrition delivery systems as Class IIa devices, triggering quality management system audits for manufacturers previously operating under food-grade standards. This regulatory expansion is forcing reformulation of packaging and labeling claims across European therapeutic nutrition portfolios. German and French hospital procurement consortia are responding by consolidating supplier qualification requirements.
Hospital discharge planners are unbundling nutrition services from inpatient bundled payments, creating standalone reimbursement codes for 30-day post-acute therapeutic meal programs. Home health agencies are capturing these newly independent revenue streams by contracting directly with clinical food manufacturers. This channel disintermediation is most visible in U.S. Medicare Advantage networks and German statutory health insurance pilot regions.
Low-Fat and Low Protein Diet Market Segmentation
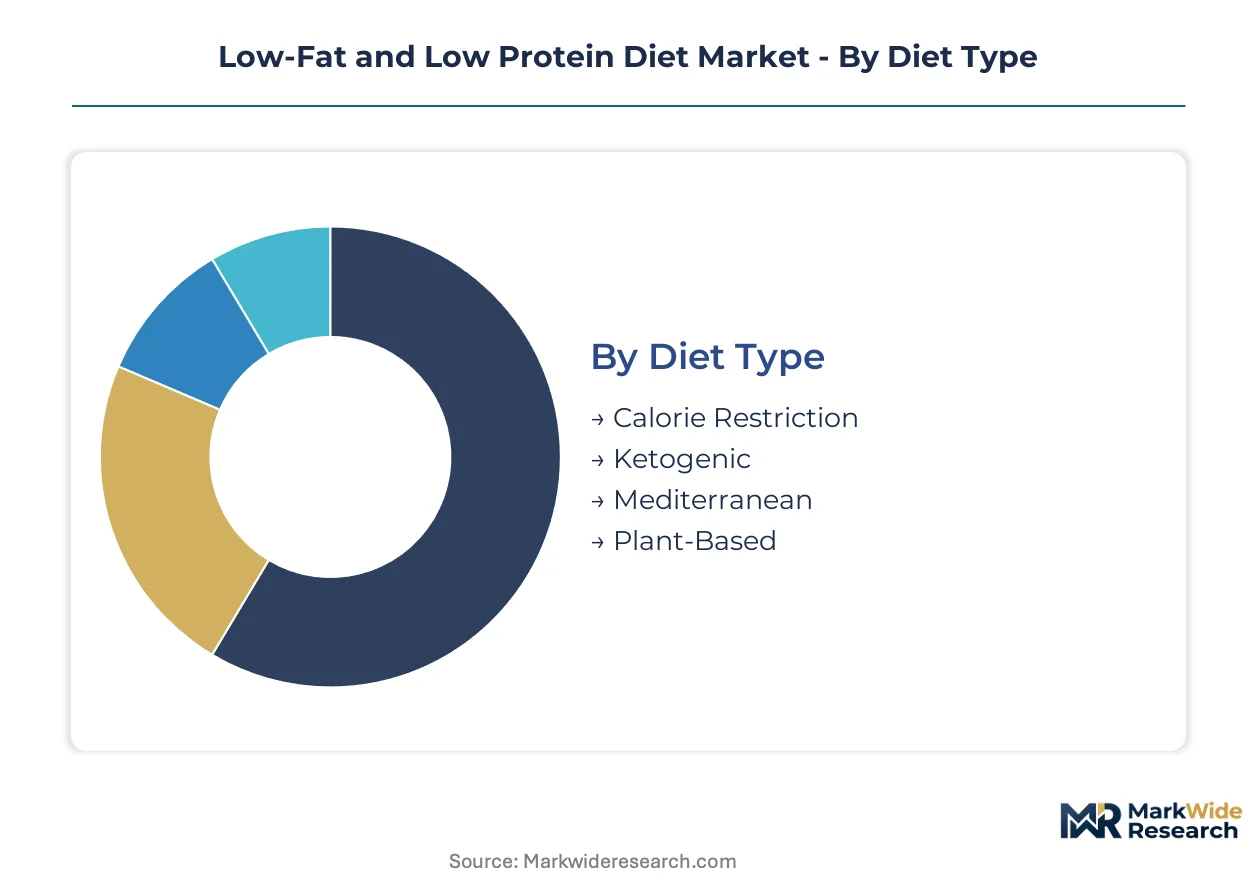
Segmentation in the low-fat and low protein diet market reveals divergent margin structures across therapeutic versus wellness-positioned products. Hospital procurement teams and retail buyers apply fundamentally different qualification criteria, fragmenting vendor strategies across institutional and consumer channels.
Diet Type:
Therapeutic efficacy claims determine reimbursement eligibility and shelf positioning across diet type segments.
- Plant-Based:Formulations leverage modified starch bases and specialized plant lipids to achieve protein restriction without animal-derived amino acids. Demand concentrates in Germany where aging demographics and statutory health insurance pilot programs for home-based renal care are expanding prescription coverage.
- Ketogenic:Severe carbohydrate restriction combined with controlled protein loads requires precision-formulated lipid systems to maintain ketosis without renal stress. Pediatric metabolic clinics in the United States are adopting these protocols for inherited metabolic defects, creating high-loyalty prescription channels with recurring revenue profiles.
- Calorie Restriction:Broad consumer wellness applications with limited clinical substantiation.
- Mediterranean:Heart-health positioning with moderate protein modification for general populations.
Volume sits with Plant-Based; growth tilts toward Ketogenic.
Consumer Age Group:
Organ function decline curves and metabolic condition prevalence shape age-based demand concentration.
- Seniors:Chronic kidney disease progression and hepatic function degradation drive institutional procurement of controlled-protein formulations. Hospital discharge planners in the United States are unbundling nutrition services from inpatient bundled payments, creating standalone reimbursement codes for post-acute therapeutic meal programs targeting this demographic.
- Children:Inherited metabolic defect treatment requires precise amino acid profiling from pediatric metabolic clinics. Caregiver loyalty and prescription adherence rates exceed adult populations, though addressable volumes remain constrained by rarity of qualifying conditions.
- Young Adults:Wellness-oriented flexitarian crossover with limited clinical positioning.
- Middle-Aged:Pre-clinical risk management with employer wellness program penetration.
Revenue concentrates with Seniors; prescription velocity climbs fastest in Children.
Product Form:
Supply chain configuration and palatability technology thresholds differentiate viable formats.
- Ready-to-Eat Meals:Pre-portioned therapeutic meals integrate controlled amino acid profiles with flavor-masked lipid systems for home-based renal care. Home health agencies in U.S. Medicare Advantage networks and German statutory health insurance regions are capturing newly independent revenue streams through direct-to-patient subscription models.
- Powders:Hospital clinical nutrition departments scale specialized meal programs through reconstituted formulations with documented efficacy endpoints. Procurement velocity accelerates as enzymatic protein hydrolysis enables more precise amino acid titration.
- Bars:Shelf-stable convenience formats face palatability ceilings above 40% protein reduction.
- Supplements:Adjunct positioning with limited standalone therapeutic claims.
Institutional procurement favors Powders; consumer channel expansion favors Ready-to-Eat Meals.
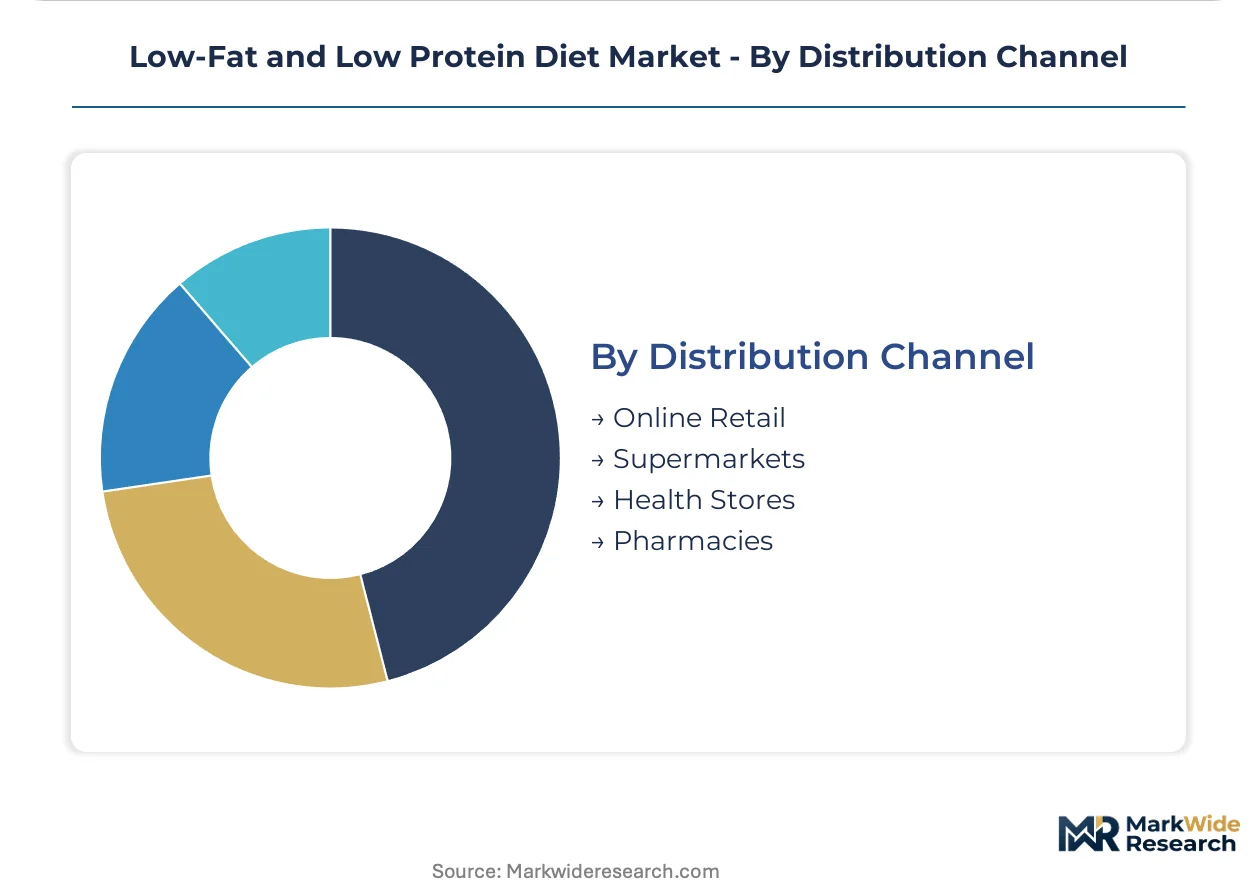
Distribution Channel:
Reimbursement pathway access determines channel viability for clinical-grade versus commodity products.
- Pharmacies:Dietitian-prescribed therapeutic nutrition plans flow through pharmacy benefit managers with established reimbursement codes. EMA and national European regulators maintain divergent medical food classification frameworks, fragmenting pharmacy channel access across member states.
- Online Retail:Direct-to-patient subscription models bypass traditional distribution for home-based renal care. U.S. FDA updated nutrition labeling requirements for protein content claims are compressing formulation cycles before digital channel launch.
- Supermarkets:Mass-market wellness positioning with limited therapeutic substantiation.
- Health Stores:Premium consumer segment with discretionary purchase patterns.
Prescription volume routes through Pharmacies; subscriber acquisition costs favor Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European therapeutic nutrition manufacturing, where statutory health insurance pilot programs for home-based renal care are expanding prescription coverage for controlled-protein formulations.
United States
Medicare Advantage networks are unbundling nutrition services from inpatient bundled payments, creating standalone reimbursement codes for post-acute therapeutic meal programs. FDA updated nutrition labeling requirements for protein content claims are compressing formulation cycles before market release. Hospital discharge planners in the Northeast Corridor are sourcing pre-portioned therapeutic meals through direct-to-patient subscription models.
Germany
Aging demographics and dietitian-prescribed therapeutic nutrition plans are driving category penetration in household channels. EMA clinical nutrition frameworks classify medical foods separately from supplements, fragmenting reimbursement eligibility across member states. The Cologne-Düsseldorf industrial corridor hosts ingredient suppliers commercializing novel plant-based lipid systems that meet restricted-diet purity standards.
Japan
Metropolitan Tokyo hospitals are scaling specialized meal programs for chronic kidney disease populations through reconstituted powder formulations. METI standards for functional food claims require clinical trial substantiation for therapeutic positioning. Osaka-based procurement consortia are consolidating supplier qualification requirements under stricter quality management protocols.
United Kingdom
NHS clinical commissioning groups are piloting direct-to-patient subscription models for home-based renal care in Greater London. Divergent EMA and national European regulatory frameworks for medical food classification create market access friction. The Cambridge-Oxford life sciences corridor is attracting precision nutrition platforms enabling patient-specific macronutrient titration.
Australia
TGA protein declaration standards determine whether products qualify for reimbursement under public health programs, shaping import eligibility for clinical nutrition manufacturers. Sydney and Melbourne hospital systems are adopting enzymatic protein hydrolysis ingredient systems at accelerating procurement velocity. Home health agencies in New South Wales are capturing newly independent revenue streams from unbundled post-acute nutrition services.
Low-Fat and Low Protein Diet Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and clinical substantiation depth. The market structures around three tiers: multinational food conglomerates with cereal R&D infrastructure, specialized ingredient suppliers with flavor-masked lipid innovation pipelines, and agribusiness operators anchoring North American supply chains with plant-based carbohydrate systems. Consolidation pressure concentrates among therapeutic food manufacturers seeking dual FDA medical food and EMA clinical nutrition certification. Strategic moves center on backward integration into specialized oil feedstocks and geographic expansion through direct-to-patient subscription channels.
Within the multinational food conglomerate tier, General Mills Inc. and Campbell Soup Company exemplify players leveraging existing R&D infrastructure to develop reduced-protein grain platforms for metabolic condition management. Kerry Group PLC represents the specialized ingredient supplier archetype, occupying a position within European supply chains for flavor-masked, low-fat protein alternatives. Archer Daniels Midland Company anchors the agribusiness operator segment, sitting within North American plant-based lipid and carbohydrate system distribution for restricted-diet applications.
| Leading Market Players |
|---|
| General Mills Inc. |
| Campbell Soup Company |
| Kerry Group PLC |
| Cargill |
| Kraft Foods Group Inc. |
| Bel Brands |
| Sun-Maid |
| Archer Daniels Midland Company |
| Ingredion |
| Others |
Supply & Pricing Matrix
REACH-compliant lipid innovation gates qualified supply for premium-tier therapeutic formulations, restricting market access to manufacturers with verified plant-based oil systems while elevating price floors for clinical-grade products above commodity alternatives. Buyers face tiered qualification costs where EMA clinical nutrition certification and FDA medical food designation create separate entry barriers that compound procurement complexity.
Pricing Analysis
Patient outcome metrics anchor value-based pricing for institutional procurement of controlled-protein formulations, with hospital systems paying premium rates for documented efficacy endpoints in renal and hepatic applications. Price differentiation stratifies across certification grade—dual FDA-EMA products command substantial premiums over single-jurisdiction alternatives—and volume scale, where direct-to-patient subscription models compress per-unit costs below pharmacy distribution. Pricing pressure stems from reimbursement code fragmentation across European member states, forcing manufacturers to absorb qualification redundancy. Pediatric metabolic clinics exhibit lowest price sensitivity due to caregiver loyalty and prescription adherence requirements, while employer wellness programs demonstrate highest sensitivity with discretionary purchase patterns.
Supply Chain Analysis
Cold-chain logistics costs for specialized oil feedstocks concentrate supply chain leverage among North American and European distributors with temperature-controlled infrastructure. Modified lipid systems draw from U.S. specialty chemical producers and German industrial corridors, with enzymatic protein hydrolysates sourced from Japanese and Irish ingredient innovators. Single-source vulnerability pervades pharmaceutical-grade amino acid profiling capacity, where qualified suppliers number below ten globally. Distribution runs through hospital procurement consortia and pharmacy benefit managers for institutional volumes, while direct-to-patient channels bypass traditional wholesale layers for home-based renal care.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market structures as a vertical-integration race where backward control over specialized oil feedstocks determines margin sustainability and supply security for therapeutic food manufacturers.
For Market Incumbents: To counter flavor-masking technical ceilings above 40% protein reduction, General Mills and Kerry Group should deepen captive supply of modified starch bases through acquisition of European specialty ingredient producers. Certification investment in simultaneous FDA-EMA review processes compresses commercialization timelines against fragmented regulatory arbitrage by smaller competitors.
For New Entrants and Emerging Players: Enter via pediatric metabolic clinic channels where inherited metabolic defect treatment centers remain underpenetrated and caregiver loyalty generates recurring revenue profiles. Asia-Pacific protein declaration harmonization presents the most penetrable geographic window, with go-to-market execution through direct-to-patient subscription models bypassing entrenched pharmacy distribution.
For Investors and Strategic Acquirers: German statutory health insurance pilot program expansions for home-based renal care are the leading indicator that prescription coverage will shift from institutional procurement toward household channels over the 5-10 year window. Acquisition targets should profile as mid-cap therapeutic food manufacturers with existing EMA clinical nutrition classification and scalable powder-to-ready-meal formulation capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialized Oil Feedstocks | Captive supply of REACH-compliant lipids secures margin sustainability against input volatility. |
| Dual Certification Investment | Simultaneous FDA medical food and EMA clinical nutrition review compresses 18-24 month sequential timelines. |
| Direct-to-Patient Subscription Launch | Bypasses pharmacy benefit managers to capture unbundled post-acute nutrition reimbursement codes. |
| Pediatric Metabolic Clinic Partnership | High-loyalty prescription channels for inherited metabolic defects generate recurring revenue profiles. |
| Precision Nutrition Platform Development | Patient-specific macronutrient titration differentiates premium clinical-grade from commodity formulations. |
Research Methodology
SEC 10-K filings, EMA clinical nutrition registration databases, and FDA medical food substantiation records formed the secondary backbone, cross-referenced with primary interviews involving hospital clinical nutrition directors, dietitian-prescribed therapeutic nutrition program managers, pharmaceutical procurement leads at GPOs, and specialized ingredient R&D directors at European suppliers. Bottom-up triangulation across patient volume data and top-down validation against reimbursement expenditure flows anchored market sizing.
Historical trendline analysis of institutional procurement velocity and home-based renal care adoption patterns informed projection modeling across the analysis window. Segmentation dimensions incorporated diet type, consumer age group, product form, and distribution channel, with CAGRs derived from elasticity-adjusted demand curves and reimbursement policy scenario weighting. Forecast inputs included enzymatic protein hydrolysis technology penetration rates and statutory health insurance pilot program expansion trajectories.
Revisions become necessary when EMA medical device reclassification extends to additional enteral nutrition delivery systems, when protein declaration harmonization stalls in Asia-Pacific markets, or when FDA nutrition labeling requirements tighten substantiation thresholds further. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Instant Protein Beverages Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Global Functional Drinks Market
Functional Food and Beverage
Middle East and Africa Functional Beverages Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Functional Water Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
South America Functional Beverages Market
Functional Food and Beverage
Fisetin Market
Functional Food and Beverage
Low Fat Smoothies Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Galacto Oligosaccharides (GOS) Market