
 Pea Starch Market | 2026-2036
Pea Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Pea Starch Market Intelligence
Market Context
Specialized protein-starch separation technicians is unwinding capacity constraints at major processing facilities across the pea value chain. Roquette Frères leverages its decades of pulse processing expertise to dominate European pharmaceutical and food-grade starch supply. Cosucra sustains a competitive position through integrated yellow pea fractionation in Belgium, yielding high-purity starch alongside protein and fiber streams. AGT Food and Ingredients anchors North American supply with prairie-origin yellow pea processing infrastructure spanning Saskatchewan and Manitoba.
Technical Definition and Segment Structure
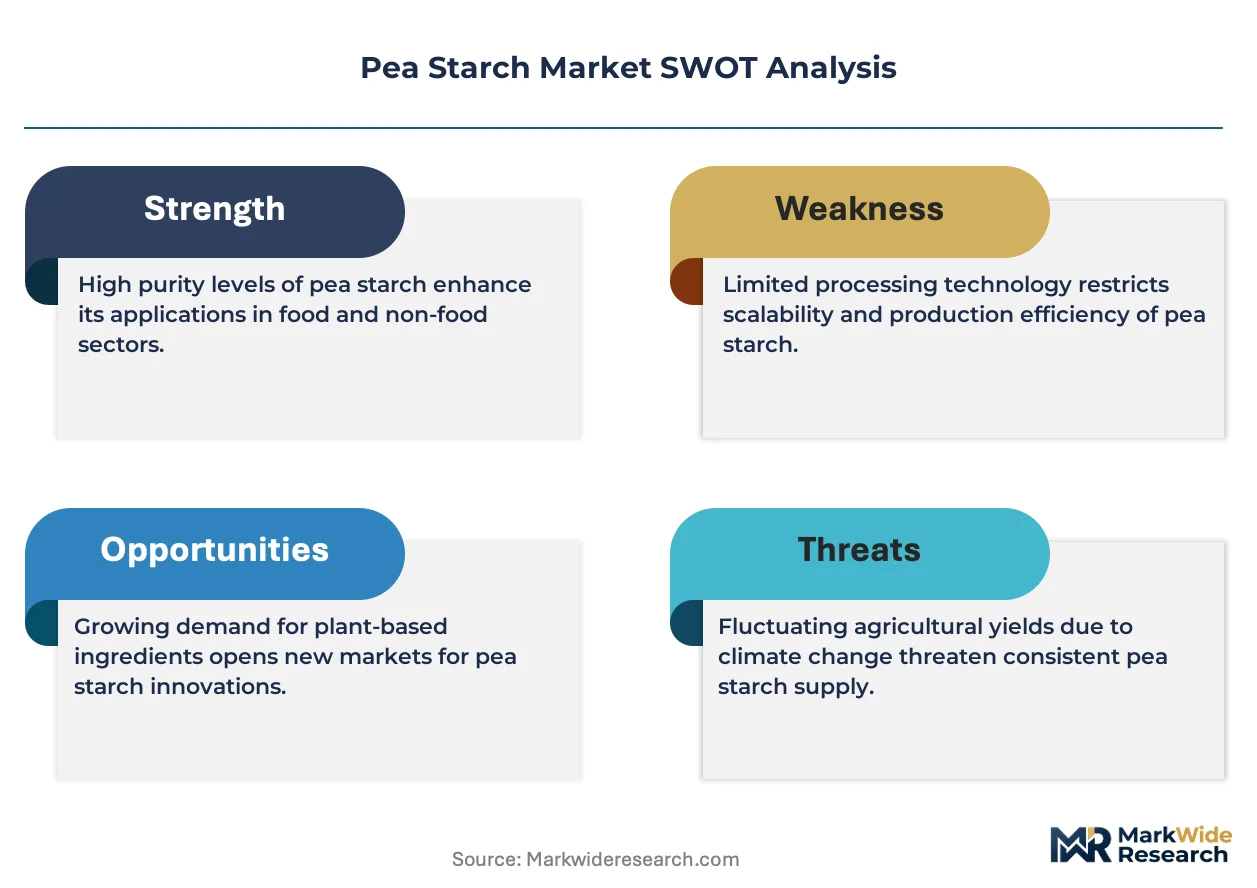
Pea starch is the carbohydrate fraction extracted from Pisum sativum seeds, typically comprising 35-50% amylose with gelatinization temperatures ranging from 55°C to 80°C depending on botanical variety and modification state. This composition delivers strong film-forming capacity and controlled viscosity profiles that serve as gelling agents, binders, and texture modifiers across food, paper, textile, and biopolymer applications. Native pea starch occupies the largest volume position due to straightforward processing and broad regulatory acceptance, while modified pea starch captures premium pricing through enhanced freeze-thaw stability and shear resistance demanded by ready-meal manufacturers. Bioplastics producers represent the fastest-growing end-user channel as hydrolyzed and cross-linked variants enable thermoplastic processing with competitive barrier properties against petroleum-derived films.
Regulatory Framework and Outlook
EMA food-contact guidelines and EU REACH compliance requirements govern starch migration limits and additive purity standards across European food and packaging applications. Health Canada and the FDA maintain parallel food additive regulations that facilitate cross-border trade for North American processors while imposing distinct labeling thresholds for modified starch declarations. Stakeholders must monitor evolving biodegradability certification standards from ISO and national regulators, as these frameworks will determine which pea starch derivatives qualify for preferential procurement in public-sector packaging contracts and corporate sustainability programs.
Market Dynamics
Clean-label procurement mandates from European retailers and North American foodservice chains are compressing demand timelines for native pea starch, forcing fractionation facilities to synchronize output with protein extraction cycles rather than standalone starch economics.
Growth Catalysts
- EU Green Deal bioplastics targets:Mandatory biodegradable packaging quotas under the EU F-Gas Regulation are redirecting industrial starch procurement from petrochemical films toward hydrolyzed pea starch derivatives for thermoplastic applications.
- Yellow pea fractionation infrastructure expansion:Protein-starch separation facilities in Saskatchewan and Manitoba are generating captive starch supply streams that lower unit costs for North American food manufacturers.
- Clean-label reformulation:Ready-meal manufacturers are substituting modified corn and potato starches with native pea starch to meet retailer ingredient transparency requirements.
Market Restraints
- Input cost volatility:Yellow pea commodity prices fluctuate with prairie drought cycles, compressing margin stability for processors lacking backward integration into crop origination.
- Supply concentration risk:European pharmaceutical-grade starch supply concentrates among a limited set of fractionation facilities with decades of pulse processing expertise, creating bottleneck vulnerability.
- Technical substitution threat:Cassava and rice starches offer comparable amylose content and gelatinization profiles at lower price points for non-premium food applications.
Strategic Opportunities
- Underpenetrated bioplastics channel:Cross-linked pea starch variants for thermoplastic starch blends remain underdeveloped in North American packaging markets relative to European adoption rates.
- Regulatory tailwind from biodegradability certification:ISO 17088 and national compostability standards are creating preferential procurement channels for certified starch derivatives in public-sector contracts.
- Technology convergence:Integration of enzymatic hydrolysis with reactive extrusion is enabling novel pea starch esters with enhanced barrier properties for edible film applications.
Industry Challenges
- Specialized technician scarcity:Protein-starch separation operations require skilled operators familiar with pulse-specific fractionation parameters, limiting facility ramp speed.
- Capex intensity for modification capacity:Cross-linking and acetylation equipment for modified starch production demands significant upfront investment with extended payback periods.
- Multi-jurisdiction compliance complexity:Simultaneous navigation of EMA food-contact guidelines, FDA food additive regulations, and evolving ISO biodegradability standards extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pea Starch Market |
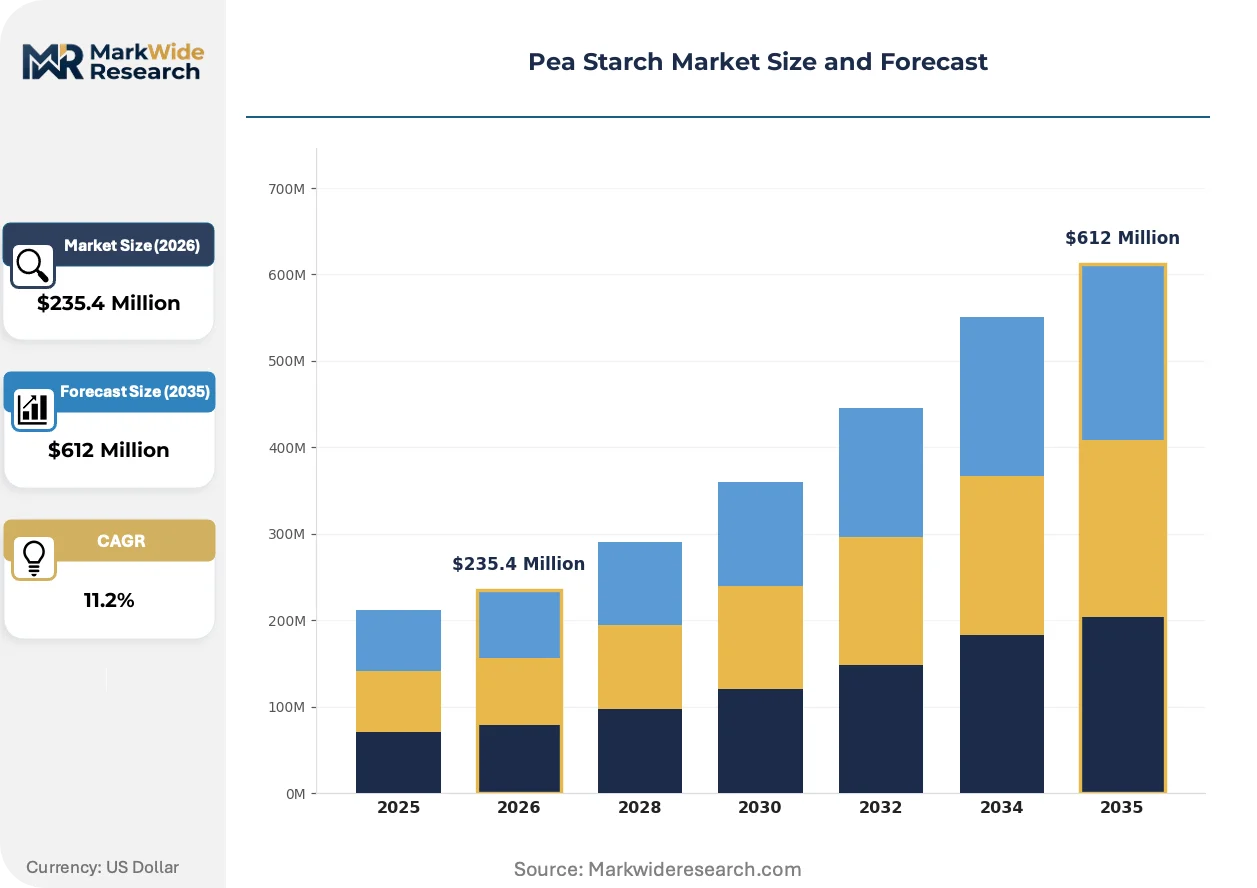
| Market Size in 2026 | $235.4 Million |
| Market Size in 2035 | $612 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Pea Starch, Modified Pea Starch, Hydrolyzed Pea Starch, Cross-linked Pea Starch Application: Food Additives, Textile Finishing, Paper Coating, Biodegradable Films, Adhesives End User: Food Processing Plants, Textile Manufacturers, Paper Mills, Bioplastics Producers Packaging Type: Bulk Bags, Paper Sacks, Plastic Bags, Fiber Drums |
| Companies Covered | Yantai Shuangta Food Co., Ltd, Cosucra, Ingredion, The Scoular Company, AGT Food and Ingredients, Roquette Frères, Emsland Group, Agridient, Puris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pea Starch Market Strategic Shifts & Innovations
Enzymatic modification platforms and extrusion-based reactive processing are compressing the performance gap between native and chemically modified starches, enabling cleaner-label alternatives without functional sacrifice.
Extrusion-assisted reactive processing is decomposing the traditional trade-off between clean-label positioning and freeze-thaw stability in frozen food applications. Ready-meal manufacturers in France and Canada are adopting these thermomechanically treated starches at accelerating rates. The technology is decomposing premium pricing power for chemically modified alternatives by delivering comparable shear resistance through physical rather than chemical intervention.
REACH authorization requirements for specific starch modification reagents are tightening purity thresholds for cross-linked variants entering European food-contact applications. Industrial consequence includes accelerated migration toward enzymatic and physical modification methods that circumvent chemical additive registration burdens. Modified starch producers serving EU pharmaceutical and packaging segments are responding by reconfiguring process trains to exclude restricted cross-linking agents.
Ingredient specification consolidation among North American retail private-label buyers is compressing approved supplier lists for native starch. Food manufacturers are consolidating procurement around fractionators with integrated protein-starch-fiber capabilities rather than standalone starch merchants. This concentration is most visible in contract manufacturing agreements for plant-based meat analogues, where single-source ingredient bundles reduce formulation complexity and audit burden.
Pea Starch Market Segmentation
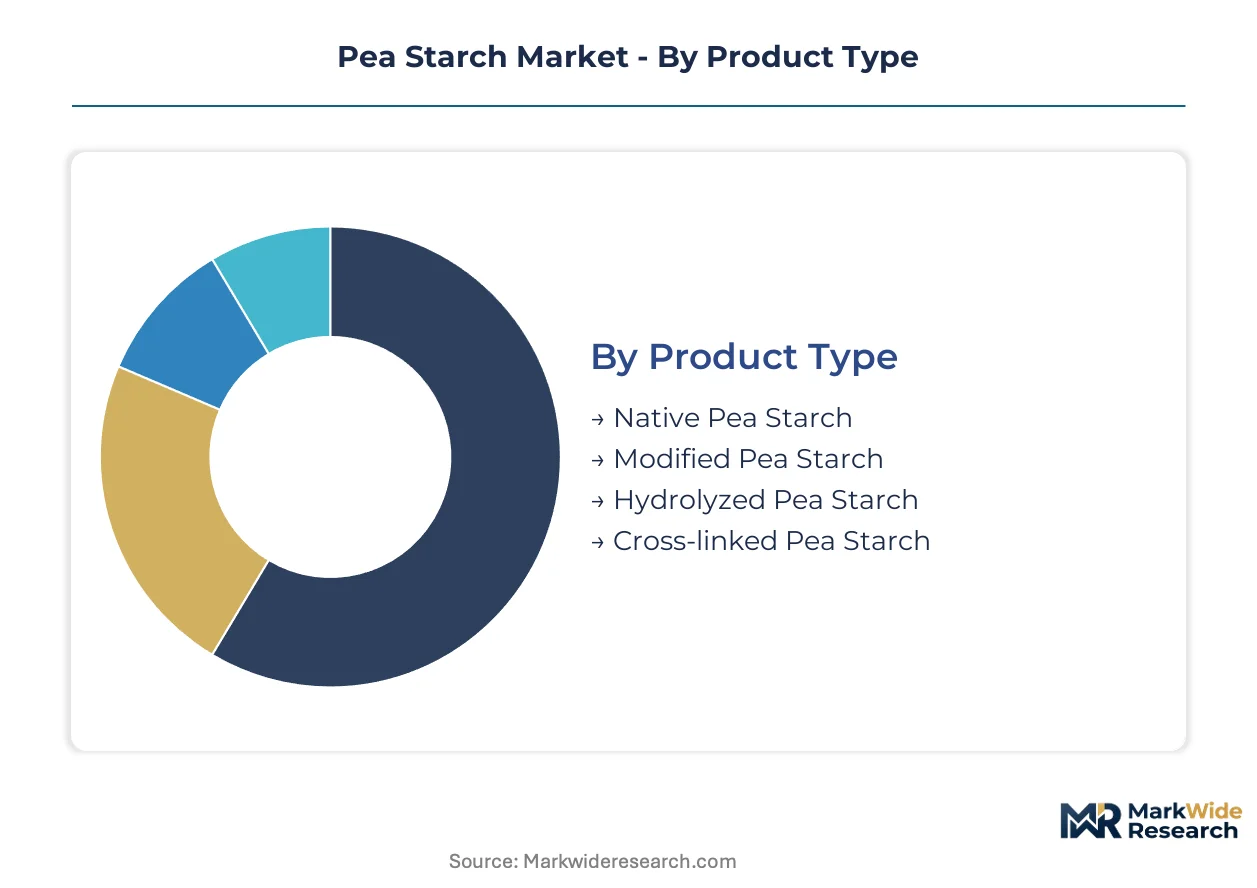
Pea starch procurement channels diverge sharply by modification state and purity grade, with food manufacturers favoring packaged retail formats while industrial bioplastics buyers source hydrolyzed variants in bulk. Channel economics force fractionators to align production schedules with protein extraction cycles rather than standalone starch demand patterns.
Product Type:
Native and modified variants flow through established food-ingredient distributors, while hydrolyzed and cross-linked grades move direct to industrial compounders and bioplastics processors.
- Native Pea Starch:This unmodified fraction retains 35-50% amylose content with gelatinization temperatures between 55°C and 80°C. European clean-label reformulators in France and Belgium are expanding procurement as replacement for modified corn starches under retailer transparency mandates.
- Modified Pea Starch:Chemical or physical alteration delivers enhanced freeze-thaw stability and shear resistance for ready-meal applications. North American frozen food manufacturers concentrate demand here despite REACH-driven regulatory pressure on certain cross-linking reagents.
- Hydrolyzed Pea Starch:Partial enzymatic breakdown reduces molecular weight for thermoplastic processing in biodegradable film extrusion.
- Cross-linked Pea Starch:Covalent bonding between starch chains creates viscosity stability under acid and heat stress for retort applications.
Native pea starch dominates installed base. Modified pea starch is where expansion concentrates.
Application:
Cost tier stratification separates commodity food additives from premium bioplastics channels, with textile and paper applications occupying mid-tier pricing bands.
- Food Additives:Gelling, binding, and texturizing functions in dairy alternatives and meat analogues drive volume. Canadian plant-based food manufacturers source native grades through integrated protein-starch fractionators in Saskatchewan.
- Biodegradable Films:Thermoplastic starch blends for packaging represent the steepest expansion trajectory as EU Green Deal quotas redirect procurement from petrochemical films.
- Textile Finishing:Warp sizing and fabric finishing utilize pea starch film-forming properties as cotton processing aid.
- Paper Coating:Surface sizing and binder applications compete with modified potato starches on cost-performance metrics.
- Adhesives:Corrugated board bonding and wood glue formulations leverage high amylose content for strong tack development.
Food additives anchor current volume. Biodegradable films are climbing the fastest.
End User:
Customer type determines specification stringency, with pharmaceutical and food-grade buyers imposing purity audits that bioplastics producers relax for industrial-grade supply.
- Food Processing Plants:Clean-label mandates from European retailers compress approved supplier lists to fractionators with integrated protein-starch-fiber capabilities.
- Bioplastics Producers:Compounders in France and Belgium scale thermoplastic starch production for EU packaging mandates.
- Textile Manufacturers:Warp sizing operations in India source lower-cost native grades for cotton yarn processing.
- Paper Mills:Surface coating applications favor modified starches with controlled viscosity profiles.
Food processing plants dominate specification requirements. Bioplastics producers are gaining share fastest.
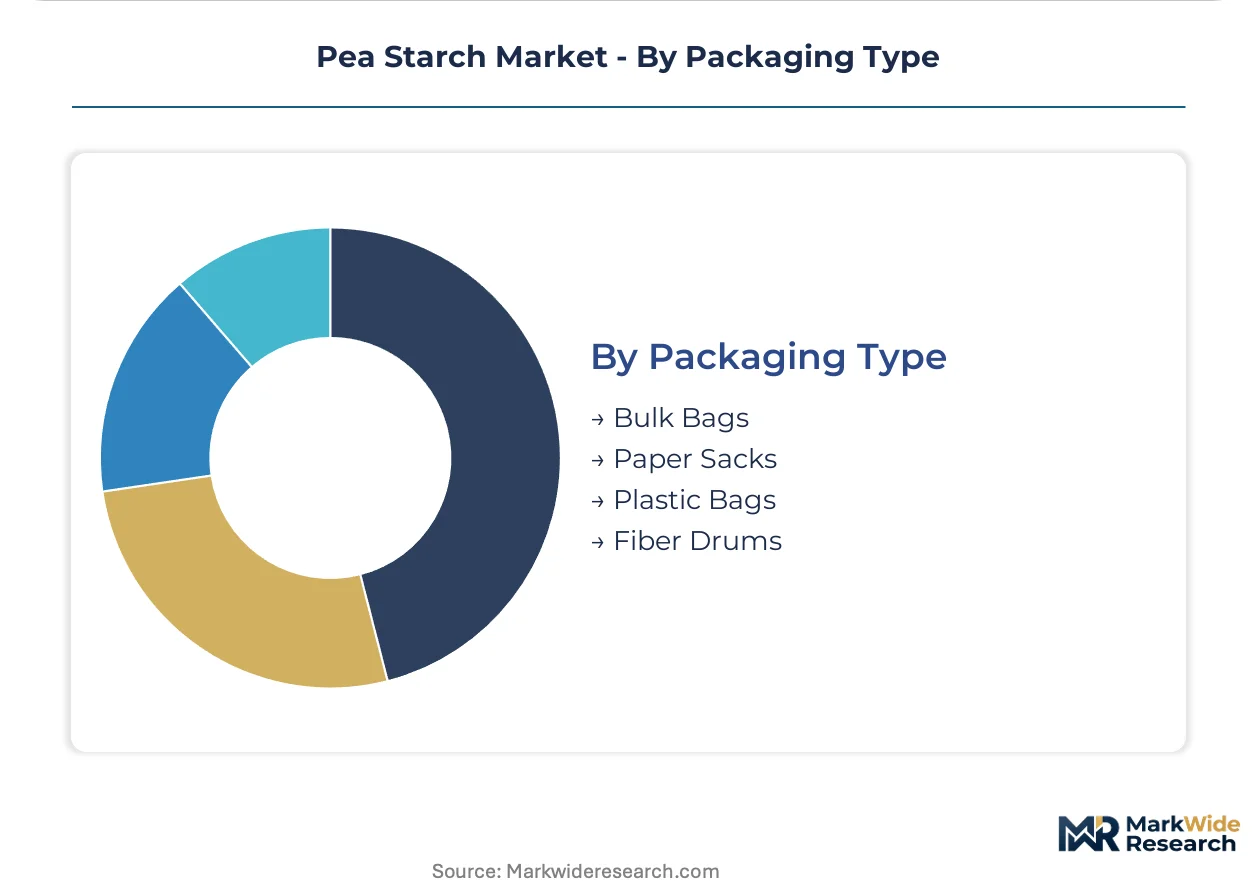
Packaging Type:
Volume scale dictates format selection, with bulk logistics favoring rail-served facilities while smaller food manufacturers require sack-packaged supply.
- Bulk Bags:One-tonne flexible intermediate bulk containers serve bioplastics compounders and paper mills with dedicated pneumatic handling systems.
- Paper Sacks:Multi-wall kraft packaging meets food-grade hygiene standards for ingredient distributors serving mid-size processors.
- Plastic Bags:Polyethylene liners provide moisture barrier for modified starch variants with sensitivity to humidity.
- Fiber Drums:Rigid containment suits pharmaceutical-grade shipments requiring lot traceability and tamper evidence.
Bulk bags dominate industrial procurement. Paper sacks are where food-channel expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA food-contact guidelines and EU Green Deal bioplastics mandates anchor European procurement patterns, while prairie fractionation infrastructure in Canada and protein-starch separation scale in China redirect supply chain gravity across three continents.
France
Roquette Frères operates decades-old pulse processing facilities in Lestrem, supplying pharmaceutical-grade starch to Paris-based drug formulators. The EU F-Gas Regulation accelerates biodegradable film demand from Lille bioplastics compounders. Hauts-de-France hosts the densest concentration of pea protein-starch fractionation capacity outside North America.
Canada
AGT Food and Ingredients anchors prairie supply through Saskatchewan and Manitoba yellow pea processing infrastructure. Health Canada maintains parallel food additive regulations with FDA that facilitate cross-border ingredient trade. Winnipeg and Regina corridor facilities generate captive starch streams synchronized with protein extraction cycles.
Belgium
Cosucra sustains integrated yellow pea fractionation in Warcoing, yielding high-purity starch alongside protein and fiber outputs. EMA migration limits govern starch purity thresholds for pharmaceutical applications serving Brussels and Antwerp formulators. Wallonia's bioplastics cluster sources hydrolyzed variants for thermoplastic starch blends.
China
Yantai Shuangta Food Co. leverages Shandong Province processing scale to supply native starch for domestic food manufacturers and export markets. SAMR food additive standards and evolving GB biodegradability certification frameworks shape product registration requirements. Yangtze River Delta food processors represent the fastest-growing import substitution channel for modified pea starch.
United States
Ingredion and Puris operate fractionation infrastructure serving Chicago and Minneapolis food manufacturing corridors. FDA food additive regulations and emerging state-level biodegradable packaging mandates in California and New York compress approved supplier lists. Pacific Northwest plant-based meat analogue producers consolidate procurement around integrated protein-starch-fiber suppliers.
Pea Starch Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with Roquette Frères and Cosucra anchoring pharmaceutical and food-grade supply through captive fractionation infrastructure. The mid-tier comprises regional starch merchants and bioplastics-focused compounders lacking backward integration into crop origination. Two strategic archetypes dominate: integrated pulse processors with protein-starch-fiber capabilities, and modification specialists with reactive extrusion equipment for cross-linked variants. Competitive moves concentrate on capacity expansion in prairie Canada and technology licensing for enzymatic modification platforms.
Among European integrated processors, Roquette Frères and Cosucra exemplify the fractionation-leader archetype through decades of pulse-specific expertise. Emsland Group occupies a position within the modification-specialist tier, while Yantai Shuangta Food Co., Ltd represents scale-driven Asian supply. AGT Food and Ingredients anchors North American prairie infrastructure, and Ingredion exemplifies the diversified ingredient conglomerate archetype with multi-source starch portfolios. Puris sits within the plant-based protein-native starch bundling segment serving meat analogue manufacturers.
| Leading Market Players |
|---|
| Yantai Shuangta Food Co., Ltd |
| Cosucra |
| Ingredion |
| The Scoular Company |
| AGT Food and Ingredients |
| Roquette Frères |
| Emsland Group |
| Agridient |
| Puris |
| Others |
Cost & Logistics Intelligence
Fractionation facility utilization rates across Saskatchewan and Manitoba determine price floors for North American food-grade supply, with protein-starch separation economics tethering starch output to higher-margin protein extraction cycles rather than standalone demand signals. Scale concentration among integrated pulse processors in France and Canada creates asymmetric bargaining power against fragmented ready-meal manufacturers and bioplastics startups.
Pricing Analysis
Price spreads between European pharmaceutical-grade and North American food-grade supply reflect EMA migration compliance costs and REACH authorization burdens for cross-linking reagents. Three-tier pricing structure across premium, standard, and economy levels separates certified pharmaceutical starch from food-grade native variants and industrial bioplastics feedstock. Cost compression in standard-tier supply is intensifying because prairie drought cycles inject yellow pea commodity volatility. Bioplastics compounders exhibit highest price sensitivity due to petroleum-derived film competition, while drug formulators accept premium positioning for batch traceability.
Supply Chain Analysis
Canada and France anchor global pea starch production through AGT Food and Ingredients' prairie infrastructure and Roquette Frères' Lestrem fractionation complex. Raw material flows draw from Saskatchewan yellow pea cultivation, Belgian protein-starch separation equipment, and Shandong Province processing scale. Single-source vulnerability concentrates in pharmaceutical-grade supply where decades of pulse-specific expertise limit qualified facility count. Distribution runs through integrated protein-starch-fiber suppliers for food manufacturers, while bioplastics compounders source hydrolyzed variants via direct bulk contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around EMA food-contact guidelines and REACH compliance creates high switching costs for pharmaceutical and clean-label food customers.
For Market Incumbents: Secure backward integration into prairie crop origination to buffer margin compression from yellow pea price volatility. Expand enzymatic modification capacity to circumvent REACH restrictions on chemical cross-linkers threatening modified starch revenue streams. For New Entrants and Emerging Players: Contract manufacturing services for plant-based meat analogues represent an underserved layer where incumbent bundling creates friction for mid-size food brands. Target North American bioplastics compounders lacking EU-market certification support as the most penetrable segment, deploying technical service partnerships as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated fractionators with captive protein-starch-fiber supply relationships locking multi-year procurement contracts. Long-term viability centers on facilities with demonstrated EMA and FDA dual compliance pathways. Watch ISO biodegradability certification adoption rates as the signal indicating bioplastics channel inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crop Origination | Prairie yellow pea sourcing buffers margin volatility from drought-driven commodity spikes. |
| Enzymatic Modification Platform Deployment | Clean-label processing circumvents REACH restrictions on chemical cross-linking reagents. |
| Pharmaceutical-Grade Certification Investment | EMA compliance opens high-margin drug formulation channels with multi-year supply contracts. |
| Bioplastics Channel Technical Partnership | ISO 17088 certification support accelerates thermoplastic starch adoption under EU Green Deal mandates. |
| Integrated Protein-Starch-Fiber Bundling | Single-source ingredient supply reduces audit burden for plant-based meat analogue contract manufacturers. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with fractionation plant managers, procurement leads at ready-meal manufacturers, bioplastics compounders, and pharmaceutical formulators; alongside secondary validation through EMA food-contact guideline databases, Health Canada additive registrations, FDA GRAS notifications, and SEC filings from listed ingredient suppliers. Bottom-up volume estimates from facility-level capacity utilization triangulated against top-down demand aggregation across food, pharmaceutical, and industrial end-use segments.
Across the analysis window, the forecasting framework modeled segmentation dimensions including modification state, purity grade, application channel, and end-user regulatory tier. CAGRs were derived from elasticity-adjusted demand projections incorporating EU F-Gas Regulation bioplastics quotas and clean-label procurement mandate diffusion rates. Industry-specific inputs included prairie crop yield variance patterns and REACH authorization timelines for starch modification reagents.
Material uncertainties — prairie drought frequency, REACH substance restriction expansion, and ISO biodegradability certification adoption curves — sit outside the modeled envelope. Forecasts reflect documented assumptions about protein-starch separation technology diffusion and regulatory harmonization progress. Recalibration cycles align with material shifts in EU packaging mandate enforcement and fractionation facility commissioning announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Mung Bean Starch Market
Ingredients
Glucose (Dextrose) Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Feed Ingredients Market
Ingredients
China Beer Adjuncts Market
Ingredients
Whey Permeate Market
Ingredients
North America Potato Starch Market
Ingredients
Modified Flour Market
Ingredients
Baobab Ingredient Market
Ingredients
Mexico Avocado Oil Market
Ingredients
Multi-Grain Premixes Market
Ingredients
Lime Seed Oils Market
Ingredients
PHO Oils Market
Ingredients
Olive Leaf Extract Market
Ingredients
Industrial Sugar Market
Ingredients
Grape Seed Extracts Market