
 Asia-Pacific Bakery Ingredients Market | 2026-2036
Asia-Pacific Bakery Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bakery Ingredients Market Outlook
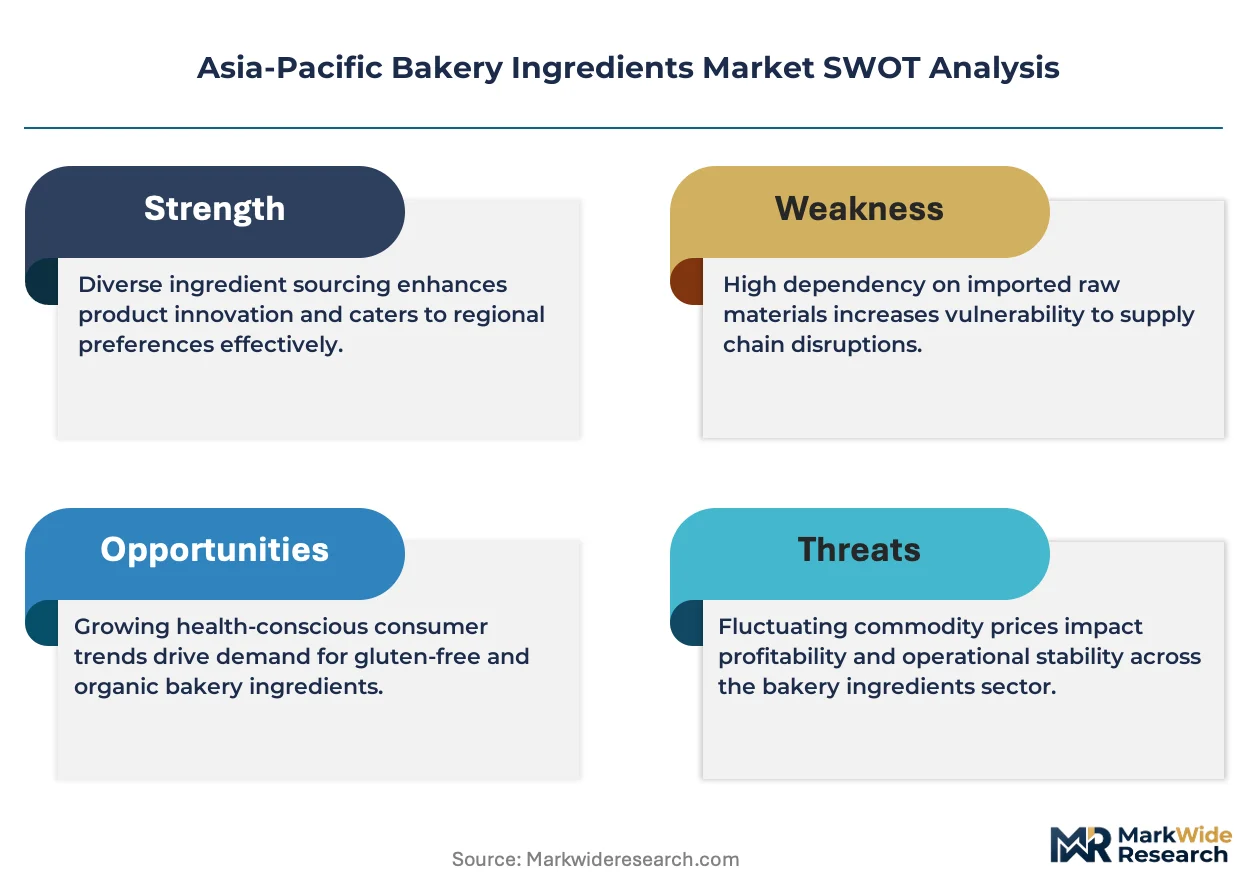
Artisan bread demand across Southeast Asian foodservice channels is broadening the addressable base for specialty flours and cultured yeast. Cargill Corporation leverages its regional grain sourcing infrastructure to secure cost-advantaged supply positions. Kerry Group PLC sustains formulation partnerships with quick-service restaurant chains seeking localized taste profiles. Associated British Foods PLC anchors its presence through dual distribution to industrial bakeries and premium retail channels.
Asia-Pacific bakery ingredients comprise functional additives, base materials, and conditioning agents formulated to control rheology, moisture retention, and shelf stability in wheat-based and alternative-flour systems; lecithin and DATEM emulsifiers typically constitute 0.5–2.5% of dough mass to optimize crumb structure and extend freshness in tropical climates. Emulsifiers command disproportionate attention from formulators managing high-humidity supply chains across Indonesia and Vietnam. Sweetener selection splits between cane-derived sucrose for cost-sensitive bread applications and specialty syrups for premium cakes and pastries. The foodservice end-user segment absorbs growing volumes of pre-mix concentrates as chain bakeries standardize output across multi-city footprints.
India's FSSAI mandates micronutrient fortification in mass-market flour, redirecting R&D spending toward premix integration. China's SAMR enforces stricter labeling for emulsifier and stabilizer content, compressing formulation flexibility for exporters. Japan's METI maintains JIS-aligned quality benchmarks that filter market access for imported enzyme preparations. Stakeholders must weigh regulatory compliance costs against the volume premiums available in fortified and clean-label product tiers.
Market Dynamics
India's FSSAI fortification mandates for staple flours are forcing ingredient suppliers to reconfigure premix portfolios and redirect R&D spending toward micronutrient integration capabilities. This regulatory pressure cascades through Southeast Asian supply chains as regional exporters adapt formulations to meet divergent national standards.
Growth Catalysts
- Artisan bread expansion:Southeast Asian foodservice channels are absorbing specialty flours and cultured yeast at accelerating rates as Western-style bakery formats penetrate tier-two cities.
- FSSAI fortification mandates:India's compulsory micronutrient addition to mass-market flour is creating dedicated demand streams for premix suppliers with integrated blending capabilities.
- High-humidity emulsifier demand:Indonesia and Vietnam's tropical supply chains require lecithin and DATEM formulations optimized for moisture retention, driving premium pricing for climate-adapted products.
Market Restraints
- Wheat price volatility:Australian and Black Sea grain supply fluctuations compress margins for flour-dependent ingredient systems across the region.
- Enzyme import dependency:Japan's METI-aligned JIS quality benchmarks restrict market access for non-compliant imported enzyme preparations, concentrating supply among certified suppliers.
- Clean-label substitution threat:Consumer preference for shortened ingredient lists is displacing synthetic emulsifiers in premium retail channels.
Strategic Opportunities
- Vietnam's underpenetrated tier-three cities:Quick-service bakery chains are standardizing output through pre-mix concentrates as they expand beyond Ho Chi Minh City and Hanoi.
- Dual-carbon formulation services:China's SAMR labeling requirements and carbon neutrality targets are creating advisory revenue streams for suppliers with lifecycle assessment capabilities.
- Alternative flour convergence:Rice, cassava, and coconut flour systems are converging with enzymatic modification technologies to serve gluten-free and low-glycemic applications.
Industry Challenges
- Multi-jurisdiction compliance timelines:Suppliers must synchronize FSSAI, SAMR, and METI certification cycles, extending product launch windows by 8-14 months.
- Legacy distribution integration:Industrial bakery customers in China resist cloud-based inventory management, forcing parallel analog-digital supply chain maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bakery Ingredients Market |
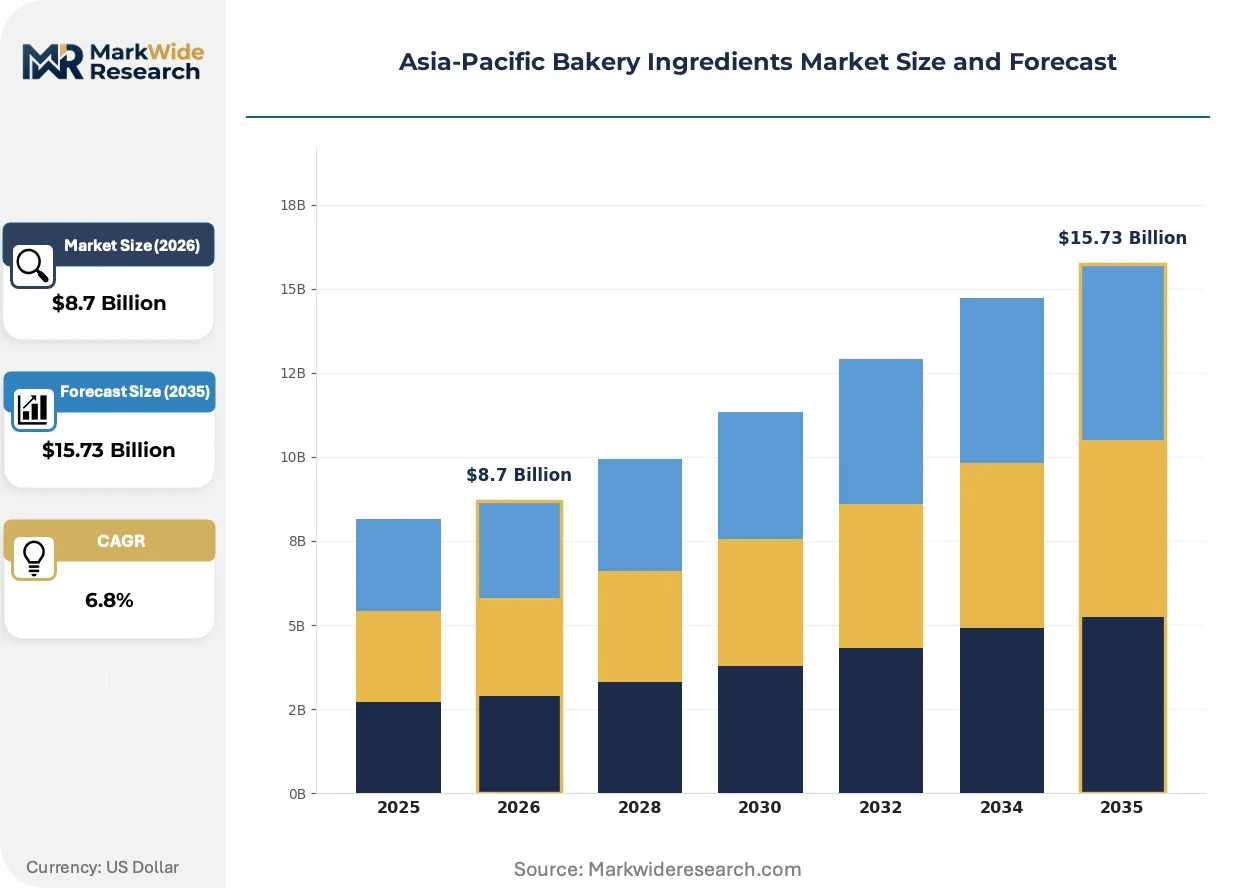
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Leavening Agents, Sweeteners, Stabilizers Application: Bread, Cakes, Pastries, Cookies End User: Bakeries, Foodservice, Retail, Home Baking Form: Powder, Liquid, Paste, Granules |
| Companies Covered | Associated British Foods PLC, Ingredion Incorporated, Archer Daniels Midland Company, Bakels Group, Dawn Food Products, Inc., Cargill Corporation, Koninklijke DSM N.V., Lallemand, Inc., Kerry Group PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bakery Ingredients Market Strategic Shifts
Formulation science and procurement patterns across Asia-Pacific are diverging as tropical climate adaptation, regulatory fragmentation, and channel consolidation reshape supplier priorities. Technology investments now concentrate on traceability and climate resilience rather than scale economies alone.
Enzymatic dough conditioners optimized for high-humidity environments are overtaking traditional chemical emulsifiers in Southeast Asian industrial bakeries. Indonesian and Vietnamese plant operators are adopting these bio-based alternatives to reduce tropical staling and extend distribution reach. The shift is compressing market share for synthetic additive portfolios while elevating suppliers with fermentation-derived ingredient pipelines.
China's SAMR has tightened disclosure requirements for emulsifier and stabilizer content on packaged bakery goods. The regulation is forcing reformulation cycles among exporters targeting Chinese retail channels, particularly for premium cake and pastry segments. Japanese and South Korean suppliers are responding fastest due to pre-existing clean-label capabilities developed under METI and MFDS guidance.
Centralized procurement by multi-city bakery chains is consolidating supplier relationships across the region. Quick-service operators in China's tier-one cities now mandate single-source pre-mix agreements to standardize output quality. The Philippines and Thailand exhibit the most visible concentration, where franchise networks are displacing independent ingredient distributors with direct manufacturer contracts.
Asia-Pacific Bakery Ingredients Market Segmentation
Ingredient specification varies sharply across Asia-Pacific bakery applications, with tropical climate conditions and divergent national regulations fragmenting demand patterns. Suppliers configure product portfolios around moisture retention requirements, fortification mandates, and channel-specific formulation constraints rather than pursuing uniform regional offerings.
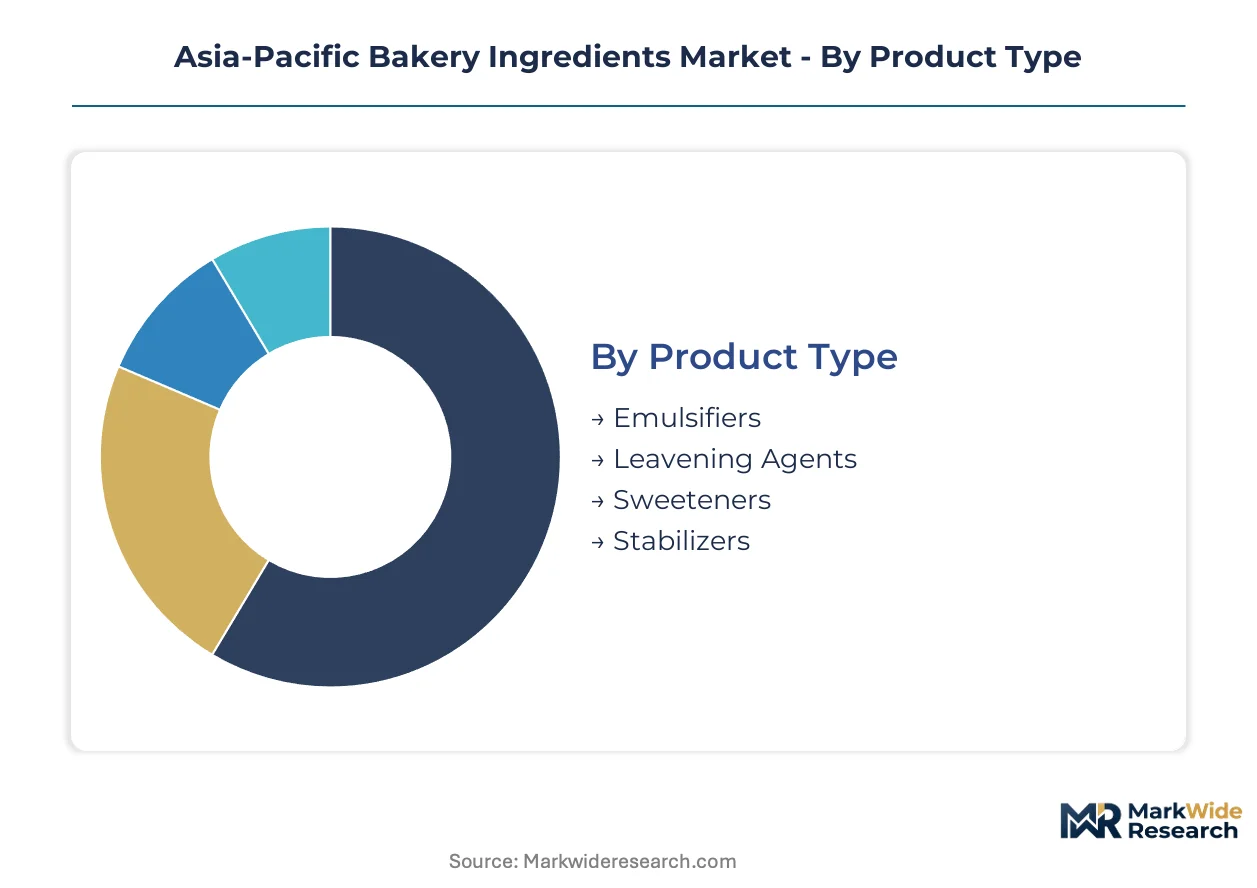
Product Type:
Functional chemistry determines shelf stability and processing tolerance across high-humidity supply chains from Jakarta to Ho Chi Minh City.
- Emulsifiers:Lecithin and DATEM formulations constitute 0.5–2.5% of dough mass to optimize crumb structure and extend freshness. Indonesia and Vietnam's tropical distribution networks command climate-adapted variants with enhanced moisture retention specifications. Clean-label substitution pressures are displacing synthetic emulsifiers in China's tier-one premium retail channels.
- Leavening Agents:Chemical and biological systems control gas production rates in wheat-based and alternative-flour matrices. Southeast Asian foodservice expansion into tier-two cities is accelerating cultured yeast demand for artisan bread applications. India's FSSAI fortification mandates require premix-compatible leavening systems with micronutrient stability.
- Sweeteners:Cane-derived sucrose serves cost-sensitive bread applications across mass-market channels.
- Stabilizers:Hydrocolloid systems manage water activity in extended distribution environments.
Emulsifiers lead on scale; leavening agents lead on momentum.
Application:
End-product characteristics dictate ingredient selection intensity, with premium segments demanding specialized functional systems.
- Bread:Staple applications absorb the highest ingredient volumes, with India's FSSAI-mandated flour fortification redirecting supplier R&D toward micronutrient integration. Industrial bakeries in China's tier-one cities are consolidating around single-source pre-mix agreements to standardize output quality across multi-city footprints.
- Cakes:Aeration and moisture retention requirements drive emulsifier and stabilizer specification. Japan's METI-aligned JIS quality benchmarks filter market access for imported enzyme preparations used in premium cake formulations.
- Pastries:Lamination performance depends on fat-emulsifier interaction optimization.
- Cookies:Extended shelf-life requirements concentrate demand for antioxidant and moisture-barrier systems.
Bread dominates volume absorption; cakes command premium formulation spend.
End User:
Procurement sophistication separates channel tiers, with chain consolidation favoring suppliers with integrated technical service capabilities.
- Bakeries:Industrial operators in China resist cloud-based inventory management, forcing parallel analog-digital supply chain maintenance from ingredient suppliers.
- Foodservice:Quick-service chains across the Philippines and Thailand are displacing independent distributors with direct manufacturer contracts as franchise networks consolidate procurement.
- Retail:Packaged goods face China's SAMR tightening on emulsifier disclosure requirements.
- Home Baking:Pre-mix concentrates serve convenience-oriented consumers in Vietnam's underpenetrated tier-three cities.
Foodservice channels are expanding most quickly; bakeries retain volume concentration.
Form:
Physical state determines handling economics and dissolution performance in varied processing environments.
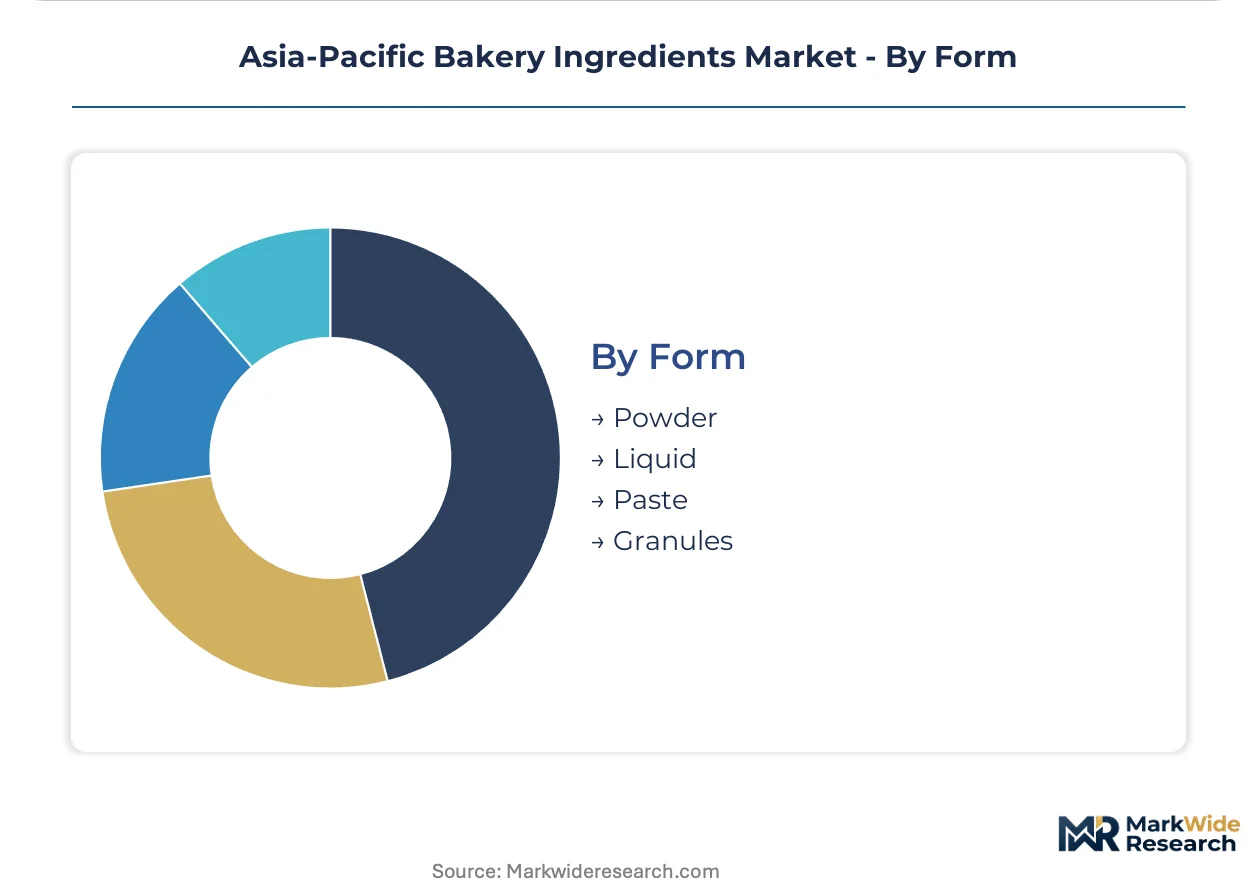
- Powder:Dominates industrial-scale applications with extended shelf stability and transport efficiency.
- Liquid:Enables precise dosing in automated continuous mixing systems.
- Paste:Concentrated formats reduce storage footprint for high-throughput operations.
- Granules:Flow properties suit pneumatic conveying systems in large bakery facilities.
Powder maintains scale leadership; liquid formats are gaining share fastest in automated facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors regional ingredient demand as Western-style bakery chains expand through Shanghai, Hangzhou, and Nanjing. SAMR labeling mandates and dual carbon targets are reshaping supplier compliance investments across tier-one procurement networks.
China
Industrial bakeries in Shanghai and Shenzhen are consolidating around single-source pre-mix agreements to standardize quality across multi-city footprints. SAMR enforces stricter emulsifier disclosure requirements, compressing formulation flexibility for exporters. The Pearl River Delta hosts the densest concentration of automated facilities adopting liquid-format dosing systems.
India
FSSAI fortification mandates for staple wheat flour are redirecting supplier R&D toward micronutrient premix integration capabilities. Maharashtra and Gujarat host the largest industrial bakery clusters adapting formulations to compulsory iron, folic acid, and vitamin B12 addition. Mumbai-based procurement networks are absorbing climate-adapted emulsifiers for extended tropical distribution.
Japan
Premium cake and pastry segments drive demand for METI-aligned JIS quality benchmarks that filter market access for imported enzyme preparations. The Kanto region around Tokyo concentrates formulation partnerships between ingredient suppliers and quick-service chains seeking localized taste profiles. Osaka-based industrial bakers maintain rigorous certification cycles that extend product launch timelines.
Vietnam
Quick-service bakery chains are standardizing output through pre-mix concentrates as they expand beyond Ho Chi Minh City and Hanoi into underpenetrated tier-three cities. Tropical humidity requirements are elevating demand for lecithin and DATEM formulations optimized for moisture retention. The Mekong Delta is emerging as a sourcing hub for rice flour systems serving gluten-free applications.
Indonesia
Jakarta's foodservice channels are absorbing specialty flours and cultured yeast at accelerating rates as Western-style bakery formats penetrate tier-two cities. High-humidity supply chains command premium pricing for climate-adapted emulsifiers that reduce tropical staling. Surabaya-based industrial operators are adopting enzymatic dough conditioners to extend distribution reach across archipelago logistics.
Asia-Pacific Bakery Ingredients Market Competitive Environment
Strategic partnerships dominate the current landscape as suppliers align with multi-city bakery chains seeking standardized output quality. The market structure concentrates around integrated multinationals with regional grain sourcing infrastructure, mid-scale specialists with fermentation-derived ingredient pipelines, and local distributors adapting to FSSAI and SAMR compliance requirements. Three archetypes define positioning: scale-driven premix suppliers, climate-specialized emulsifier formulators, and fortification-integrated premix blenders. Geographic expansion and portfolio diversification represent the dominant competitive vectors as players chase Vietnam's tier-three penetration and India's mandated micronutrient streams.
Among integrated multinationals, Cargill Corporation and Kerry Group PLC exemplify scale-driven archetypes with regional sourcing and formulation partnership capabilities. Associated British Foods PLC occupies a position bridging industrial bakery supply and premium retail channel access. These entities represent the compliance-heavy, multi-jurisdiction operational model required across FSSAI, SAMR, and METI regulatory environments.
| Leading Market Players |
|---|
| Associated British Foods PLC |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| Bakels Group |
| Dawn Food Products, Inc. |
| Cargill Corporation |
| Koninklijke DSM N.V. |
| Lallemand, Inc. |
| Kerry Group PLC |
| Others |
Value Chain & Pricing Dynamics
India's FSSAI fortification mandates for staple flours are compelling suppliers to absorb micronutrient premix costs while maintaining mass-market price points, compressing margins and forcing selective pass-through to industrial bakery customers. This regulatory-driven cost absorption is reshaping how suppliers configure tiered pricing across premium fortification-integrated and standard unfortified product lines.
Pricing Analysis
Input-cost pass-through from Australian and Black Sea wheat volatility is fragmenting pricing structures across the region. Three-tier pricing stratifies across premium climate-adapted emulsifiers, standard functional additives, and economy-grade base materials. Price differentiation hinges on fortification certification grade and volume scale, with FSSAI-compliant premixes commanding measurable premiums. Pricing pressure stems from wheat price instability and clean-label substitution threats in China's tier-one retail channels. Industrial bakeries in China's Yangtze River Delta exhibit lowest price sensitivity due to consolidated procurement power, while Vietnam's tier-three independent operators remain most exposed to spot-market fluctuations.
Supply Chain Analysis
Dual-sourcing requirements from multi-city bakery chains in China and the Philippines are mandating supplier qualification across at least two production geographies. Geographic supply concentration centers on Australia and Black Sea origins for wheat derivatives, with enzymatic preparations drawing from Japanese and South Korean certified facilities. Raw material dependencies include tropical climate-adapted lecithin, DATEM formulations, and fermentation-derived enzyme systems. Supply chain risk manifests through single-source vulnerability in JIS-aligned enzyme certifications. Distribution runs through direct manufacturer contracts with quick-service chains, displacing traditional independent distributor networks across Southeast Asian foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific bakery ingredients function as a geographic-arbitrage play where suppliers can capture margin spreads between India's cost-sensitive fortification-mandated volume and China's premium clean-label specification tiers. The regulatory divergence between FSSAI micronutrient requirements and SAMR disclosure mandates creates structural pricing discontinuities across adjacent markets.
For Market Incumbents: Cement fortification-integrated premix capabilities in India before competitors replicate FSSAI-compliant blending infrastructure. Anchor climate-adapted emulsifier production in Indonesia and Vietnam to defend against enzymatic substitution threats from fermentation-derived alternatives. Prioritize backward integration into regional grain sourcing to buffer Australian and Black Sea wheat price volatility. For New Entrants and Emerging Players: Begin with Vietnam's underpenetrated tier-three cities where quick-service bakery chains are standardizing output through pre-mix concentrates. Target gluten-free rice flour systems in the Mekong Delta as the most penetrable white-space segment. Pursue advisory-service positioning around China's SAMR labeling requirements and dual carbon targets as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specialists possessing fermentation-derived enzyme pipelines and existing JIS certification alignment. Long-term viability across the analysis window favors suppliers with multi-jurisdiction compliance capabilities spanning FSSAI, SAMR, and METI requirements. Watch for inflection signals in Vietnam's tier-three pre-mix adoption rates as the key demand validation indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Grain Sourcing | Cargill Corporation leverages Australian and Black Sea infrastructure to secure cost-advantaged wheat positions. |
| FSSAI-Compliant Premix Capacity Expansion | Maharashtra and Gujarat industrial clusters absorb compulsory iron, folic acid, and vitamin B12 integration capabilities. |
| Climate-Adapted Emulsifier Formulation Development | Indonesian and Vietnamese tropical supply chains demand lecithin and DATEM variants with enhanced moisture retention. |
| Direct Manufacturer Contracting with Quick-Service Chains | Philippines and Thailand franchise networks displace independent distributors with standardized procurement agreements. |
| JIS-Aligned Enzyme Certification Investment | Japanese METI quality benchmarks filter market access for imported dough conditioners in premium cake segments. |
Study Parameters
Multiple input streams — primary interviews with industrial bakery procurement managers, foodservice chain technical directors, and regional distribution partners; secondary validation through FSSAI regulatory filings, SAMR disclosure databases, and customs trade records — were reconciled through bottom-up and top-down triangulation. Stakeholder engagement spanned plant managers at Shanghai and Shenzhen automated facilities, category buyers at Philippine quick-service franchise networks, and R&D directors adapting formulations for tropical humidity specifications.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application intensity, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived through demand-side build-up and supply-side capacity assessment. Forecast inputs incorporated wheat price volatility indices, fortification mandate implementation timelines, and enzymatic substitution adoption curves in Southeast Asian industrial bakeries.
Several conditions sit outside the modeled scope, including abrupt regulatory reversals on fortification mandates, extreme climate events disrupting Australian grain harvests, and rapid clean-label displacement exceeding historical substitution rates. Forecasts reflect documented assumptions about chain bakery expansion trajectories and certification cycle durations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Chickpea Protein Ingredients Market
Ingredients
Cottonseed Oil Market
Ingredients
White Mulberry Leaves Extract Market
Ingredients
Freeze-Dried Vegetable Powder Market
Ingredients
Soy Peptones Market
Ingredients
Wheat Germ Oil Market
Ingredients
Mineral Premix Market
Ingredients
Bouillon Market
Ingredients
Stabilized Starch Market
Ingredients
Indonesia Edible Oil Market
Ingredients
Ice Cream Ingredients Market
Ingredients
Corn Oil Cake Market
Ingredients
Fats and Oils Market
Ingredients
Pine Needle Oil Market
Ingredients
Tuna and Algae Omega-3 Ingredient Market
Ingredients
Food Grade Hydrolyzed Casein Market