
 Medium-Chain Triglyceride (MCT) Fat Market | 2026-2036
Medium-Chain Triglyceride (MCT) Fat Market Size, Share, and Industry Trends Forecast 2026-2036
Medium-Chain Triglyceride (MCT) Fat Market Insights
Sports nutrition is consolidating its position as the dominant demand vertical for MCT fats, pulling volume away from traditional food-service channels. Croda International Plc leverages its lipid technology platform to supply pharmaceutical-grade MCT fractions across North American and European markets. Musim Mas Group anchors Southeast Asian supply through integrated palm kernel oil processing infrastructure. Wilmar International competes on oleochemical scale, drawing feedstock from its sprawling plantation-to-refinery network.
Medium-chain triglycerides are lipids composed predominantly of caprylic (C8) and capric (C10) fatty acids esterified to glycerol, typically manufactured via fractionation and esterification of coconut or palm kernel oils to achieve specific carbon-chain profiles. These compounds serve primarily as rapid-metabolizing energy substrates in clinical nutrition, sports formulations, and ketogenic applications. Liquid MCT commands the largest volume share due to its versatility in beverage and oil formulations, while powdered MCT represents the fastest-expanding format as brands seek shelf-stable, free-flowing ingredients for protein powders and meal replacements. MCT capsules occupy a premium margin niche targeting precise-dose consumers in the dietary supplements channel.
FDA oversight of dietary supplement Good Manufacturing Practices and FTC substantiation requirements for health claims directly constrain how MCT products are labeled and marketed in the United States. EFSA novel food evaluations and EU health claim authorization processes create parallel compliance thresholds for brands accessing European markets. ISO standards for lipid analysis and purity testing further shape supplier qualification protocols across jurisdictions. Stakeholders must monitor regulatory divergence between major markets while building formulation flexibility that satisfies multiple compliance regimes simultaneously.
Market Dynamics
The ketogenic diet wave and sports nutrition formulation surge are compressing traditional food-service channels while pulling MCT volume toward functional food and clinical nutrition applications.
Growth Catalysts
- Ketogenic diet proliferation:Consumer adherence to low-carbohydrate, high-fat regimens is pulling MCT oil into meal replacement powders and ready-to-drink beverages across United States retail channels.
- FDA dietary supplement GMP enforcement:Stricter manufacturing practice audits are filtering out substandard suppliers, creating qualification advantages for fractionation-capable producers.
- Fractionation technology maturation:Advanced molecular distillation is enabling precise C8/C10 ratio customization for pharmaceutical and neonatal nutrition specifications.
Market Restraints
- Coconut oil price volatility:Weather-driven supply fluctuations in Philippines and Indonesia feedstock regions compress margin predictability for esterification-dependent producers.
- Palm kernel oil concentration risk:Southeast Asian integrated plantation groups control upstream fractionation capacity, limiting independent processor bargaining power.
- EFSA novel food evaluation timelines:Extended safety assessment periods for new MCT delivery formats delay European market entry by 18-36 months.
Strategic Opportunities
- Pediatric metabolic disorder applications:Underpenetrated clinical nutrition segments in Germany and France present formulation partnerships with hospital feeding protocols.
- Microencapsulation-powder convergence:Spray-drying technology married to resistant starch carriers is opening shelf-stable inclusion in hot-beverage applications previously closed to liquid oils.
- Direct-to-consumer subscription channels:Ketogenic lifestyle brands are bypassing traditional supplement distributors through personalized dosing platforms.
Industry Challenges
- Lipid biochemistry talent scarcity:Formulation chemists with combined expertise in emulsion stability and clinical nutrition metabolism command premium compensation, constraining R&D expansion.
- Multi-jurisdiction certification complexity:Simultaneous pursuit of USP verification, NSF Certified for Sport, and Informed Sport accreditation stretches quality assurance timelines.
- Legacy oil processing equipment retrofit costs:Converting standard triglyceride infrastructure for MCT-specific fractionation requires capital outlays that mid-scale producers defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium-Chain Triglyceride (MCT) Fat Market |
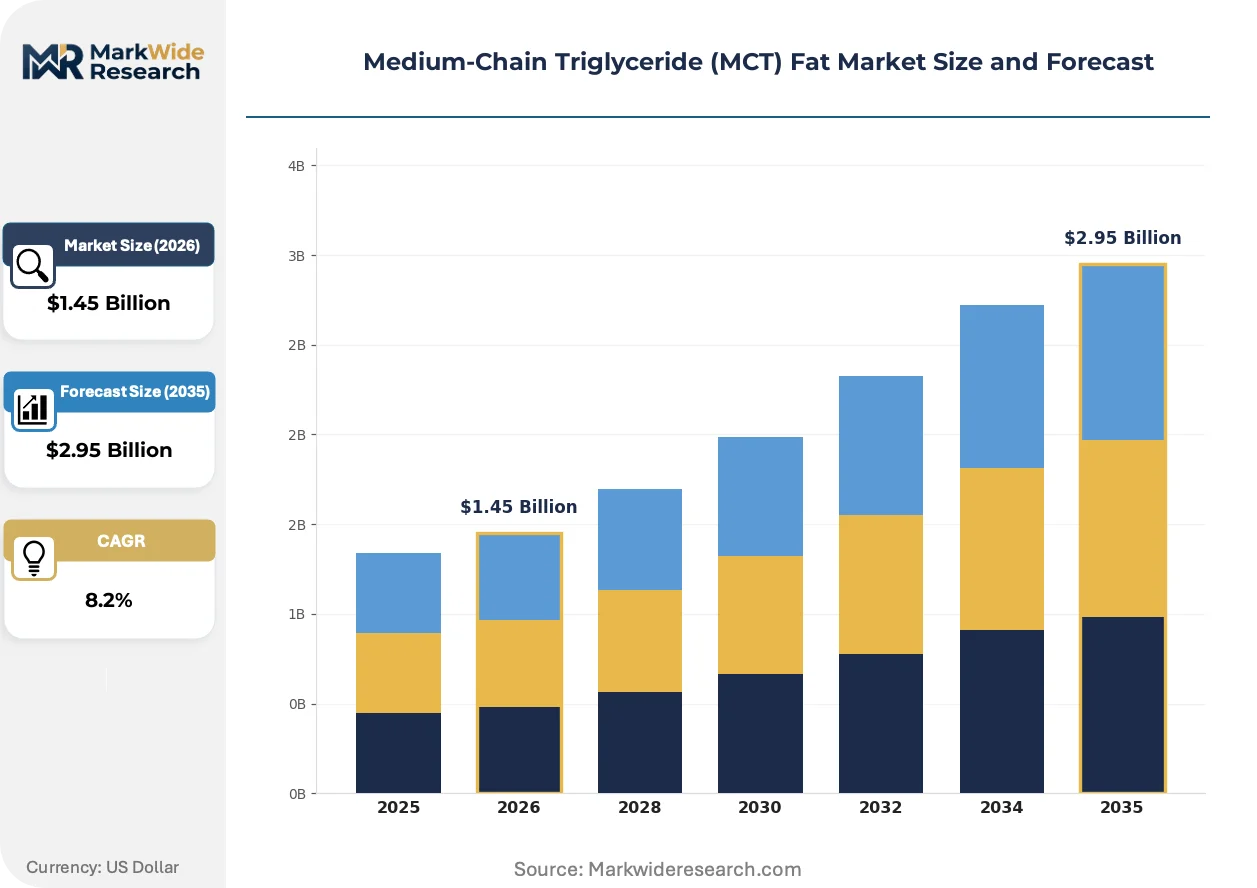
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.95 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid MCT, Powdered MCT, MCT Oil Blends, MCT Capsules Application: Food & Beverages, Pharmaceuticals, Dietary Supplements, Personal Care End User: Retail Consumers, Food Manufacturers, Healthcare Providers, Fitness Centers Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Stores |
| Companies Covered | Croda International Plc, Musim Mas Group, Wilmar International, Koninklijke DSM N.V., BASF SE, KLK Oleo, IOI Oleo GmbH, Lonza Group Ltd, Stepan Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium-Chain Triglyceride (MCT) Fat Market Trends and Innovations
Formulation science and regulatory transparency requirements are reshaping how MCT products are manufactured, labeled, and distributed across consumer and clinical channels.
Enzymatic interesterification is consolidating as the preferred manufacturing route for premium MCT grades. Specialty nutrition brands in the United States and Germany are specifying enzyme-catalyzed processes over chemical esterification for cleaner-label positioning. This shift is consolidating supplier tiers around bioprocessing-capable facilities while marginalizing legacy alkaline catalyst operations.
EFSA's evolving position on saturated fat health claims is forcing reformulation transparency across European functional food portfolios. Brands must now substantiate rapid-energy claims with clinical trial data rather than metabolic pathway theory. Sports nutrition SKUs targeting German and French markets are responding by commissioning glycemic response studies to support packaging assertions.
Hospital procurement departments are consolidating supplier lists around vertically integrated MCT sources with documented chain-of-custody documentation. Group purchasing organizations are replacing fragmented distributor networks with direct contracts covering neonatal and enteral nutrition applications. This concentration is most visible in United States academic medical centers and integrated delivery networks.
Medium-Chain Triglyceride (MCT) Fat Market Segmentation
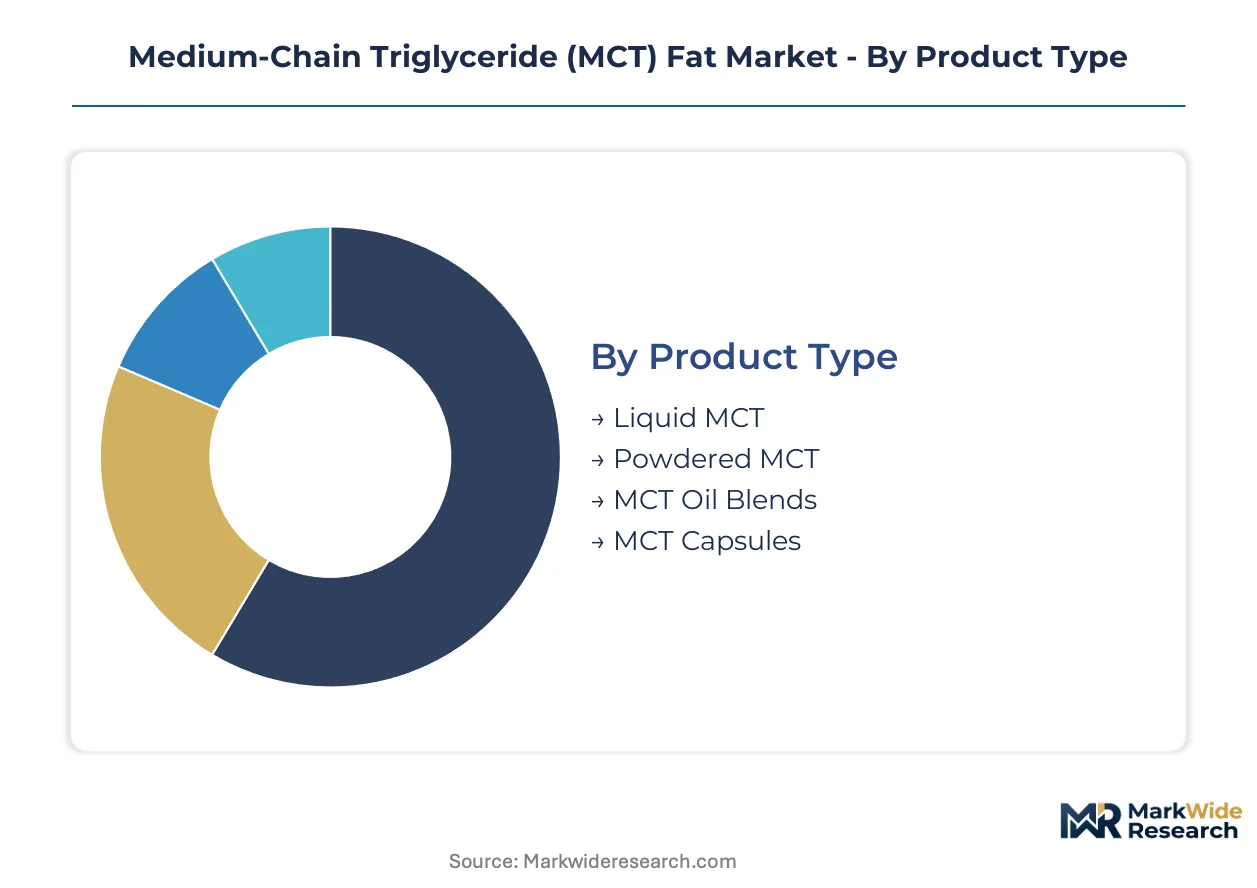
MCT fat segmentation reveals how capital deployment and technical capabilities concentrate around specific delivery formats and customer access channels. Understanding these divisions exposes where formulation investments yield margin protection versus commodity exposure.
Product Type:
Capital intensity varies sharply across MCT delivery formats, with fractionation infrastructure and powder processing equipment demanding the steepest upfront outlays.
- Liquid MCT:Predominantly C8/C10 fatty acid esters in oil form, manufactured through molecular distillation of coconut or palm kernel feedstocks. Food and beverage manufacturers in the United States absorb the largest volumes for ready-to-drink ketogenic beverages, though margin compression from coconut oil price swings constrains producer returns.
- Powdered MCT:Spray-dried MCT oil encapsulated in carbohydrate or protein matrices for shelf stability. Protein powder brands and meal replacement startups are pulling volume fastest as brands seek free-flowing ingredients that survive hot-beverage applications previously closed to liquid oils.
- MCT Oil Blends:Formulations combining MCT with other functional lipids or flavor systems for specific nutritional profiles. Sports nutrition contract manufacturers specify these for customized pre-workout and recovery products.
- MCT Capsules:Precise-dose gelatin or vegetable-based softgels targeting supplement channel consumers. Premium positioning in health stores and online subscription services supports higher unit economics despite smaller absolute volumes.
Liquid MCT absorbs the bulk of installed capacity; powdered MCT is expanding most quickly.
Application:
End-use diversification determines how MCT suppliers allocate technical service resources and regulatory compliance investments.
- Food & Beverages:Functional beverage startups and established dairy alternatives brands incorporate MCT for rapid energy positioning. FDA GRAS notifications and FTC substantiation requirements for metabolism claims concentrate compliance spending here.
- Pharmaceuticals:Neonatal nutrition and metabolic disorder therapeutics demand pharmaceutical-grade MCT with documented chain-of-custody. Hospital procurement consolidation around integrated suppliers is reshaping competitive access to academic medical centers.
- Dietary Supplements:Ketogenic diet adherence and sports performance positioning drive SKU proliferation. NSF Certified for Sport and Informed Sport accreditation requirements filter supplier qualification.
- Personal Care:Emollient and carrier oil applications in premium skincare formulations. Smaller volume but insulation from commodity feedstock volatility through value-added positioning.
Food and beverages command the largest application share; pharmaceuticals present the steepest regulatory barriers to entry.
End User:
Customer type shapes pricing architecture and relationship management intensity across the MCT value chain.
- Retail Consumers:Direct purchasers through e-commerce platforms and health stores, often seeking ketogenic lifestyle products. Subscription-based dosing platforms are bypassing traditional supplement distributors.
- Food Manufacturers:Industrial buyers integrating MCT into formulated products. Volume commitments and long-term supply agreements dominate procurement patterns.
- Healthcare Providers:Hospital feeding protocols and clinical nutrition departments. Group purchasing organization consolidation is replacing fragmented distributor networks with direct supplier contracts.
- Fitness Centers:Gyms and wellness facilities retailing MCT products to member bases. Private-label arrangements with regional supplement brands predominate.
Food manufacturers anchor procurement volumes; healthcare providers are consolidating supplier relationships fastest.
Distribution Channel:
Channel selection determines margin capture and customer data access for MCT brands navigating channel conflict.
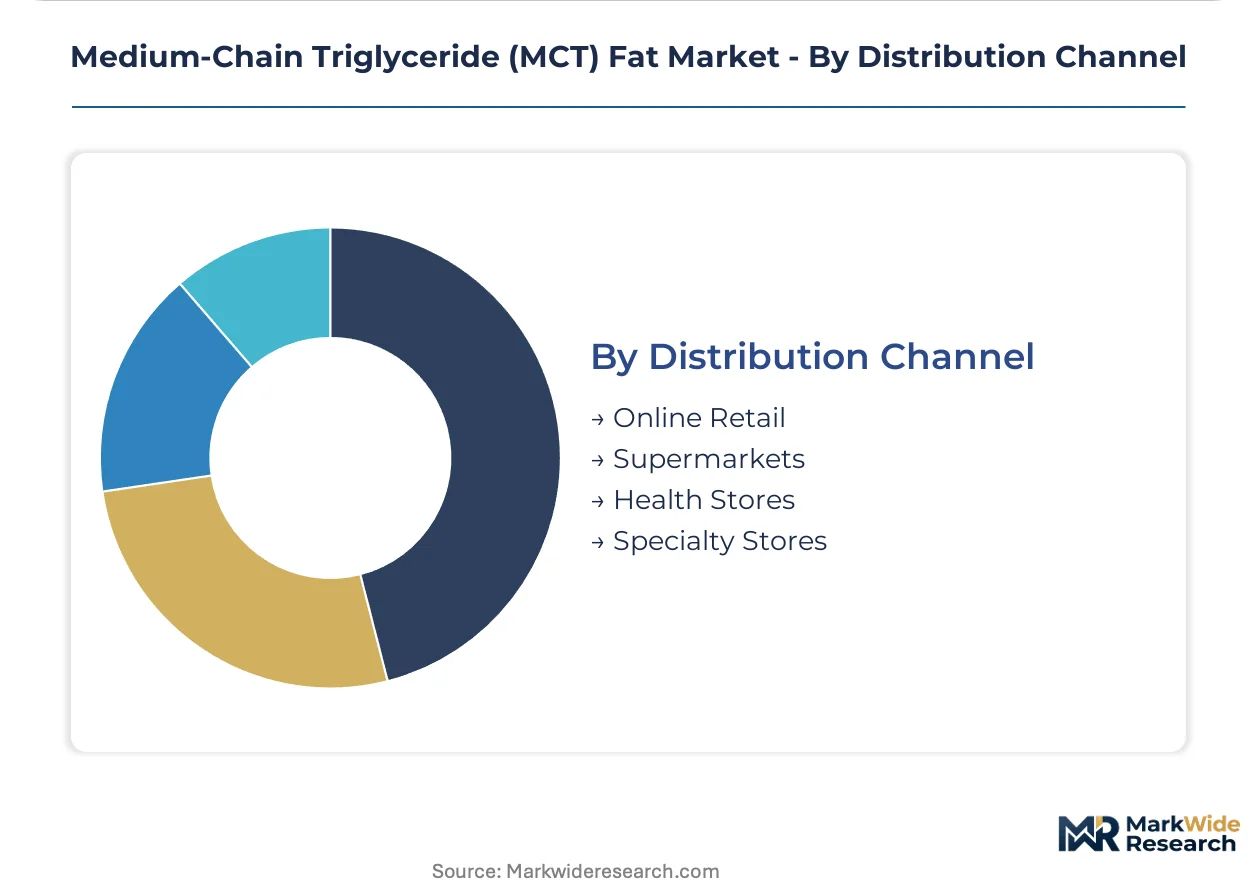
- Online Retail:Direct-to-consumer platforms and marketplace presence. Ketogenic lifestyle brands leverage personalized dosing algorithms and subscription mechanics to build recurring revenue.
- Supermarkets:Mass retail placement for MCT oil and blended products. Slotting fees and promotional spending requirements compress margins for emerging brands.
- Health Stores:Specialty retail with trained staff and educated consumer base. Premium positioning supports higher price points for pharmaceutical-grade and certified products.
- Specialty Stores:Fitness equipment retailers, wellness boutiques, and alternative medicine practitioners. Localized demand concentration limits scale but supports community-based brand building.
Online retail captures the fastest expansion trajectory; supermarkets maintain the largest absolute throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Singapore and Jebel Ali anchor MCT oil transshipment and fractionation investment. Tax incentives in these hubs concentrate pharmaceutical-grade processing capacity. Regional demand patterns diverge sharply between ketogenic lifestyle markets and clinical nutrition procurement systems.
United States
Ketogenic beverage startups and sports nutrition contract manufacturers drive MCT oil absorption. FDA dietary supplement GMP enforcement filters supplier qualification, favoring fractionation-capable producers. Greater Los Angeles and Miami clusters host formulation labs blending MCT into ready-to-drink products.
Germany
Neonatal nutrition protocols and metabolic disorder therapeutics pull pharmaceutical-grade MCT volumes. EFSA novel food evaluation timelines delay new delivery format approvals by 18-36 months. Frankfurt-Rhine-Main corridor houses hospital group purchasing organizations consolidating supplier contracts.
China
Functional food brands and infant formula manufacturers expand MCT inclusion for rapid-energy positioning. SAMR oversight of novel food ingredients shapes import registration requirements. Yangtze River Delta processing zones upgrade molecular distillation capacity for C8/C10 ratio customization.
Indonesia
Integrated palm kernel oil processors anchor upstream fractionation supply. Weather-driven coconut oil volatility in Philippine feedstock regions shifts procurement patterns. Riau Islands industrial estates control esterification infrastructure serving Southeast Asian oleochemical demand.
Netherlands
Specialty lipid distributors and pharmaceutical excipient suppliers cluster around Rotterdam port access. REACH compliance for lipid derivatives shapes supplier documentation burdens. Eindhoven-Helmond corridor hosts spray-drying operations converting liquid MCT into powder formats.
Medium-Chain Triglyceride (MCT) Fat Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade supply, while regional oleochemical groups control upstream feedstock. The vendor base stratifies between fractionation-technology specialists and plantation-integrated processors. Three archetypes dominate: lipid technology platforms, integrated palm kernel processors, and pharmaceutical-grade fractionators. Capacity expansion and enzymatic process licensing constitute the primary competitive vectors reshaping supplier tiers.
Within the lipid technology platform tier, Croda International Plc exemplifies pharmaceutical-grade positioning across North American and European markets. Plantation-integrated processors include Musim Mas Group, representing Southeast Asian upstream concentration through palm kernel oil infrastructure. Wilmar International occupies a position at the scale-driven end, drawing feedstock from plantation-to-refinery networks. These three entities anchor distinct competitive vectors: technology licensing, upstream integration, and oleochemical scale.
| Leading Market Players |
|---|
| Croda International Plc |
| Musim Mas Group |
| Wilmar International |
| Koninklijke DSM N.V. |
| BASF SE |
| KLK Oleo |
| IOI Oleo GmbH |
| Lonza Group Ltd |
| Stepan Company |
| Others |
Pricing and Supply Chain Analysis
Integrated plantation-to-refinery groups backed by Southeast Asian sovereign wealth and family conglomerates anchor upstream MCT fractionation capacity, translating captive palm kernel oil supply into pricing discipline that resists coconut oil volatility. This ownership pattern compresses spot-market liquidity while rewarding long-term offtake commitments with preferential C8/C10 ratio customization.
Pricing Analysis
Short lead-time premiums of 15-25% above contract baselines reward pharmaceutical-grade MCT buyers facing neonatal nutrition stockout risks. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certifications separates hospital procurement from sports nutrition contract manufacturing. Cost compression in food-grade liquid MCT is intensifying because Indonesian integrated processors are expanding fractionation capacity ahead of demand absorption. Hospital group purchasing organizations exhibit lowest price sensitivity due to patient-safety compliance mandates, while functional beverage startups face acute margin pressure from coconut oil feedstock swings.
Supply Chain Analysis
Direct-to-hospital channels handle pharmaceutical-grade volumes through group purchasing organization contracts, bypassing traditional distributor markups. Upstream concentration centers on Indonesia, Malaysia, and the Philippines, where integrated palm kernel oil processors control molecular distillation infrastructure. Esterification operations draw from coconut oil, palm kernel oil, and refined glycerol feedstocks. Single-source vulnerability in Philippine coconut supply exposes producers to typhoon-driven crop losses. Distribution runs through Rotterdam and Singapore free-trade zones for European and Asia-Pacific pharmaceutical customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MCT fat supply is consolidating around fractionation-capable integrated processors, with FDA GMP enforcement and EFSA novel food timelines filtering subscale competitors from hospital and European functional food channels.
For Market Incumbents: Deploy enzymatic interesterification licensing to capture premium positioning as German and United States brands specify cleaner-label manufacturing routes. Secure backward integration into palm kernel crushing capacity in Riau Islands or Sabah to insulate margin structures from coconut oil volatility. Counter threat from Chinese molecular distillation upgrades by locking multi-year hospital GPO contracts with documented chain-of-custody protocols. For New Entrants and Emerging Players: The 40-60% price spread between pharmaceutical-grade and standard food-grade MCT creates entry space for mid-tier certified producers targeting sports nutrition contract manufacturers. Pediatric metabolic disorder applications in France and Germany represent the most penetrable clinical segment, with formulation partnerships replacing fragmented distributor relationships. Commission glycemic response studies to support rapid-energy claims for European market access. For Investors and Strategic Acquirers: Distressed-cycle entries favor Southeast Asian fractionation assets with uncommitted capacity and existing FDA establishment registrations. Five-to-ten-year viability hinges on feedstock flexibility between coconut and palm kernel oils. Watch for EFSA novel food approval acceleration as signal that European powder-format demand is structurally unlocking.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Licensing | Cleaner-label positioning captures premium tier demand from German and United States brands. |
| Backward Integration into Crushing | Captive palm kernel supply insulates margin structures from Philippine coconut volatility. |
| Powder Format Capacity Expansion | Spray-drying infrastructure addresses fastest-growing protein powder and meal replacement demand. |
| Hospital GPO Contract Consolidation | Direct supplier relationships replace fragmented distributors in United States academic medical centers. |
| EFSA Novel Food Submission | European regulatory approval unlocks 18-36 month delayed powder format market entry. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fractionation plant managers, sports nutrition brand formulators, hospital procurement directors, and oleochemical distribution channel partners. FDA GRAS notifications, EFSA novel food registers, and Indonesian trade statistics provided supply-side validation. Bottom-up capacity assessments and top-down demand modeling were triangulated against import-export flows.
Data-stream reconciliation across molecular distillation capacity surveys, neonatal nutrition protocol adoption rates, and ketogenic product SKU proliferation informed the analytical framework over the projection horizon. Segmentation dimensions modeled include delivery format, application vertical, end-user type, and geographic regulatory cluster. CAGRs were derived from fitted trend extrapolation with cross-validation against feedstock price elasticity estimates and hospital procurement cycle timing.
Inputs from United States hospital GPO contract databases and Indonesian plantation production reports were available through the study window; gaps in real-time Chinese molecular distillation capacity additions introduce uncertainty bands around Asia-Pacific supply forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Protein Ingredients Market
Ingredients
Bread Flour Market
Ingredients
Lime Seed Oils Market
Ingredients
Plant Based Ingredients Market
Ingredients
Mung Bean Starch Market
Ingredients
Potato Fiber Market
Ingredients
Dried Fruit Ingredients Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Torula Yeast Market
Ingredients
Europe Phytosterols Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Edible Oils and Fats Market
Ingredients
Europe Malt Ingredient Market
Ingredients
Europe Feed Yeast Market
Ingredients
Sodium Caseinate Market
Ingredients
Textured Soy Flour Market