
 Phytogenic Market | 2026-2036
Phytogenic Market Size, Share, and Industry Trends Forecast 2026-2036
Phytogenic Market Analysis
Brazilian essential oil distillers is broadening output for feed-grade applications. Cargill leverages backward integration into botanical sourcing to secure supply continuity. DSM-Firmenich sustains R&D intensity across standardized plant extract portfolios. Delacon Biotechnik specializes in species-specific phytogenic blends for monogastric and ruminant nutrition.
Phytogenics comprise bioactive compounds derived from herbs, spices, and essential oils containing terpenoids, phenolics, and alkaloids that modulate gut microbiota and enhance nutrient absorption in production animals. These substances undergo steam distillation, solvent extraction, or cold pressing to concentrate active principles for industrial dosing at parts-per-million inclusion rates. Essential oils command the largest revenue pool within product type segments due to standardized potency and longer shelf stability. Animal feed represents the fastest-expanding application channel as livestock producers substitute synthetic growth promoters with botanical alternatives. Powder formulations dominate volume shipments because of easier blending into compound feeds and premixes.
FDA guidelines on veterinary feed directives and EFSA evaluations of botanical safety in animal nutrition shape product registration pathways and label claims across North America and Europe. India's FSSAI and CDSCO monitor parallel tracks for human-grade phytogenic extracts entering nutraceutical channels. China's NMPA and Ministry of Agriculture enforce pesticide residue thresholds on imported herbal raw materials. Stakeholders must track evolving maximum residue limits and novel food approval queues to time market entry and formulation investments.
Market Dynamics
Antibiotic growth promoter bans across major livestock-producing jurisdictions are forcing feed compounders to reformulate rations around botanical bioactives, restructuring procurement relationships and technical service requirements throughout the value chain.
Growth Catalysts
- EFSA botanical safety evaluations:Clarified approval pathways for terpenoid-rich extracts in poultry and swine diets accelerate product registration timelines across EU member states.
- Steam distillation yield improvements:Continuous processing equipment retrofits at Brazilian and German essential oil facilities compress unit production costs for feed-grade formulations.
- Monogastric nutrition protocols:Standardized inclusion rates for oregano and thyme oil blends in broiler starter feeds drive repeat purchasing from integrated poultry operators.
Market Restraints
- Raw material geographic concentration:Seventy percent of pharmaceutical-grade thyme biomass originates from Mediterranean basin smallholder networks, exposing processors to climate-induced harvest volatility.
- Pesticide residue threshold enforcement:China's NMPA and Ministry of Agriculture screening protocols reject imported herbal inputs exceeding maximum residue limits, triggering batch destruction costs.
- Synthetic phytochemical substitution:Laboratory-synthesized cinnamaldehyde and eugenol analogues offer price stability and purity consistency that challenge botanical extraction economics.
Strategic Opportunities
- India FSSAI nutraceutical crossover approvals:Dual-use extract registrations for human digestive health supplements open parallel revenue streams beyond animal feed channels.
- Precision fermentation convergence:Microbial production of rare terpenoids enables biosynthesis of heat-sensitive compounds impractical to isolate from plant matrices.
- Aquaculture application white space:Species-specific phytogenic protocols for shrimp and salmonid gut health remain underdeveloped relative to terrestrial livestock segments.
Industry Challenges
- Standardized potency certification timelines:Third-party validation of terpenoid concentration and oxidative stability extends product launch cycles by eight to fourteen months.
- Extraction chemist talent scarcity:Specialized expertise in supercritical CO2 and subcritical water extraction techniques concentrates among German, Swiss, and Japanese technical institutes.
- Legacy premix integration complexity:Microencapsulation requirements for heat-stable essential oil delivery conflict with existing pelleting equipment specifications at mid-scale feed mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phytogenic Market |
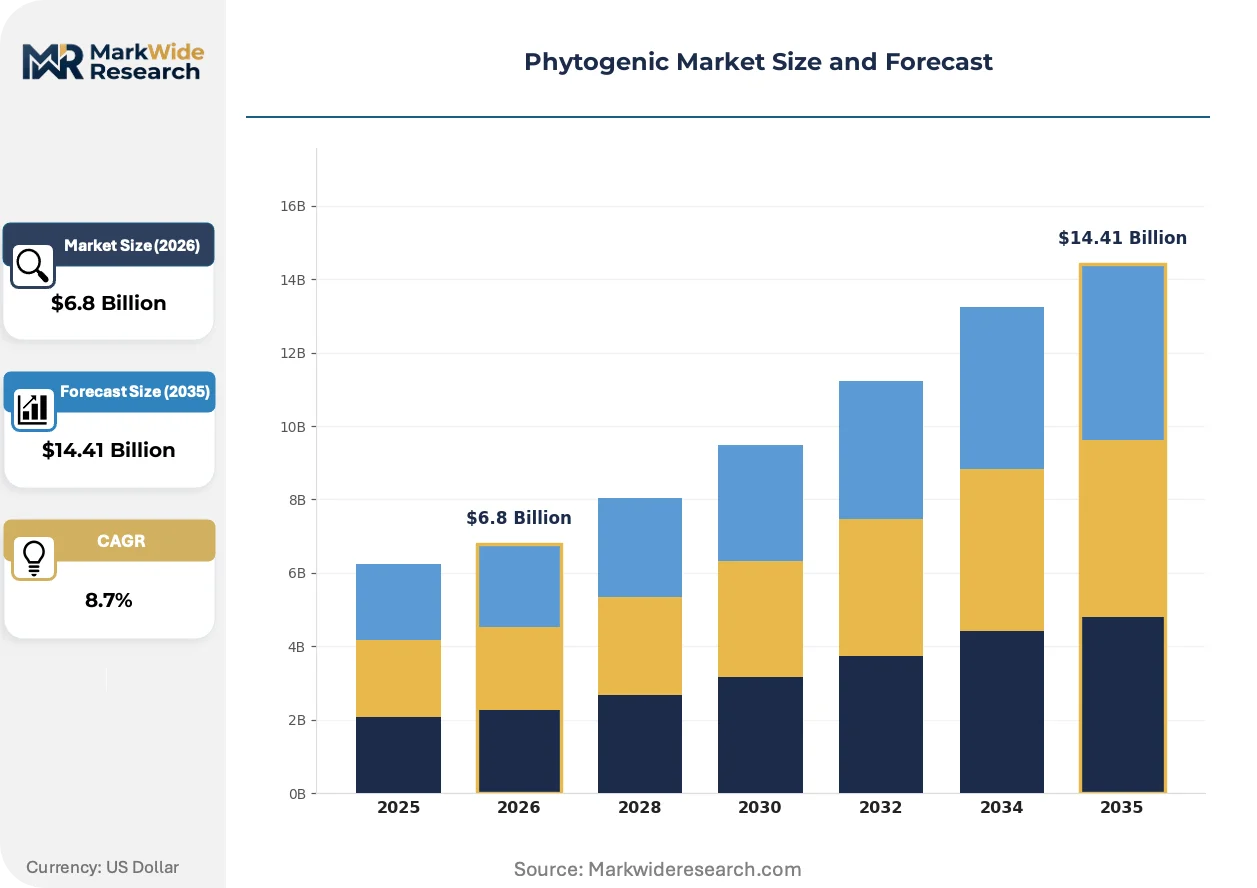
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Herbs, Spices, Plant Extracts Application: Animal Feed, Food & Beverages, Pharmaceuticals, Nutraceuticals Form: Liquid, Powder, Granules, Capsule End User: Agriculture, Food Industry, Healthcare, Animal Husbandry |
| Companies Covered | Cargill, DSM-Firmenich, ADM, Delacon Biotechnik, Kemin Industries, DuPont, Nutreco, Adisseo, EW Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phytogenic Market Emerging Trajectories
Formulation science and process engineering advances are compressing the performance gap between botanical and synthetic feed additives while regulatory harmonization efforts reshape competitive access rules.
Microencapsulation via fluidized bed coating and complex coacervation is electrifying essential oil stability in high-temperature pelleting operations. Major broiler integrators in the southeastern United States now specify coated thymol formulations for grower-finisher diets. This thermal protection capability is electrifying contract manufacturing demand for toll-processing services at specialized encapsulation facilities.
EU Green Deal Farm-to-Fork targets mandate twenty-five percent reduction in agricultural antibiotic use by decade's end, accelerating botanical additive approvals. EFSA's 2023 updated guidance on botanical safety assessment streamlines dossier requirements for dried herb preparations. Poultry feed compounders in Poland and Spain are expanding technical teams to manage novel feed additive registration queues.
Direct procurement relationships between livestock cooperatives and essential oil distillers are shortening traditional distribution hierarchies. French and Dutch pig producer associations now contract quarterly volumes with Croatian rosemary and Hungarian oregano processors. This disintermediation pattern concentrates price negotiation leverage among volume buyers and pressures legacy feed additive distributors to add formulation technical services.
Phytogenic Market Segmentation
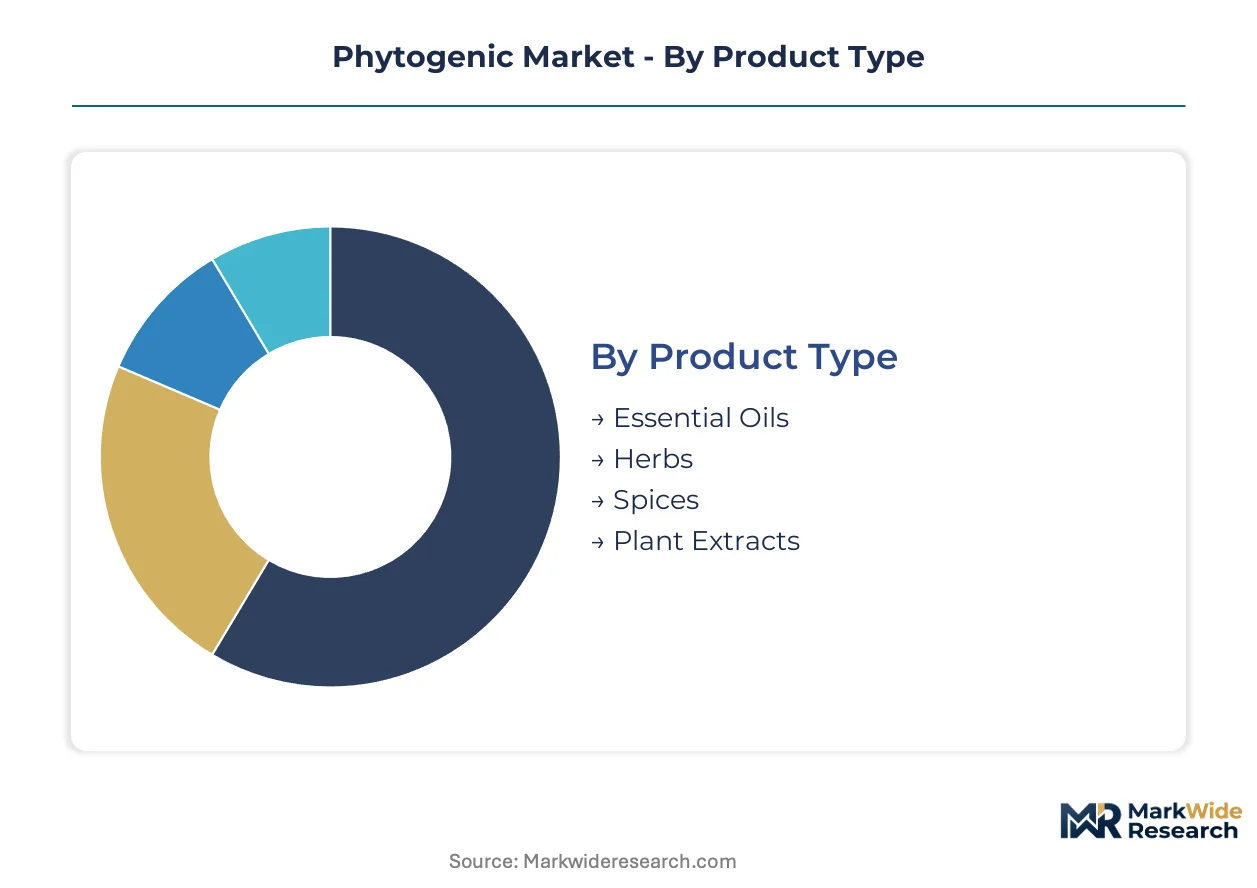
Phytogenic suppliers configure production assets around specific bioactive profiles and formulation requirements. Segmentation discipline determines extraction technology investments, regulatory dossier priorities, and distribution partnerships across disparate end-use specifications.
Product Type:
Supply concentration for terpenoid-rich biomass shapes competitive positioning within each product category, with Mediterranean and Brazilian sourcing networks commanding disproportionate leverage.
- Essential Oils:Steam-distilled concentrates of terpenoids, phenolics, and aldehydes achieve standardized potency for industrial dosing. German and Brazilian distillation facilities absorb the majority of feed-grade procurement contracts as antibiotic growth promoter bans tighten across EU member states and North America.
- Herbs:Dried and milled botanical matter retains fiber matrices and heat-labile compounds unsuitable for distillation. Polish and Spanish poultry feed compounders drive repeat purchasing for oregano and thyme leaf preparations following EFSA's streamlined botanical safety guidance.
- Spices:Pungent bioactive matrices from cinnamon, clove, and capsicum deliver cinnamaldehyde and capsaicinoids for gut health modulation.
- Plant Extracts:Solvent-extracted or supercritical CO2 concentrates isolate specific compound classes for pharmaceutical and nutraceutical purity requirements.
Essential oils absorb the bulk of installed capacity; plant extracts are expanding most quickly.
Application:
Cost tier differentiation separates commodity feed additives from premium pharmaceutical-grade extracts, with certification requirements and residue testing protocols determining margin structures.
- Animal Feed:Broiler integrators in the southeastern United States and pig producer associations in France and the Netherlands specify microencapsulated thymol and coated essential oil formulations for thermal stability during pelleting. This channel concentrates volume demand as livestock producers substitute botanical bioactives for synthetic growth promoters.
- Food & Beverages:Flavoring and preservation applications leverage GRAS-status botanicals for clean-label positioning in processed foods and functional beverages.
- Pharmaceuticals:Standardized marker compound content and batch-level analytical verification support drug development pipelines targeting anti-inflammatory and antimicrobial indications.
- Nutraceuticals:India's FSSAI dual-use approval pathways enable crossover registrations from animal feed extracts into human digestive health supplements.
Animal feed dominates volume throughput; nutraceuticals gain share fastest.
Form:
Customer type requirements dictate delivery system engineering, with integrated livestock operators demanding thermal protection that conflicts with legacy premix equipment at mid-scale feed mills.
- Liquid:Bulk tanker deliveries of standardized essential oil blends suit large-scale feed manufacturing with automated dosing systems. Brazilian and German toll processors supply liquid thymol-carvacrol formulations to major broiler integrators.
- Powder:Spray-dried or adsorbed preparations blend uniformly into compound feeds and premixes, commanding the majority of volume shipments due to handling convenience.
- Granules:Extruded delivery systems protect volatile compounds during transport and storage, addressing oxidative stability concerns in extended distribution chains.
- Capsule:Unit-dose presentations serve nutraceutical and pharmaceutical channels requiring precise consumer-level dosing.
Powder forms absorb the bulk of volume shipments; granules are expanding most quickly.
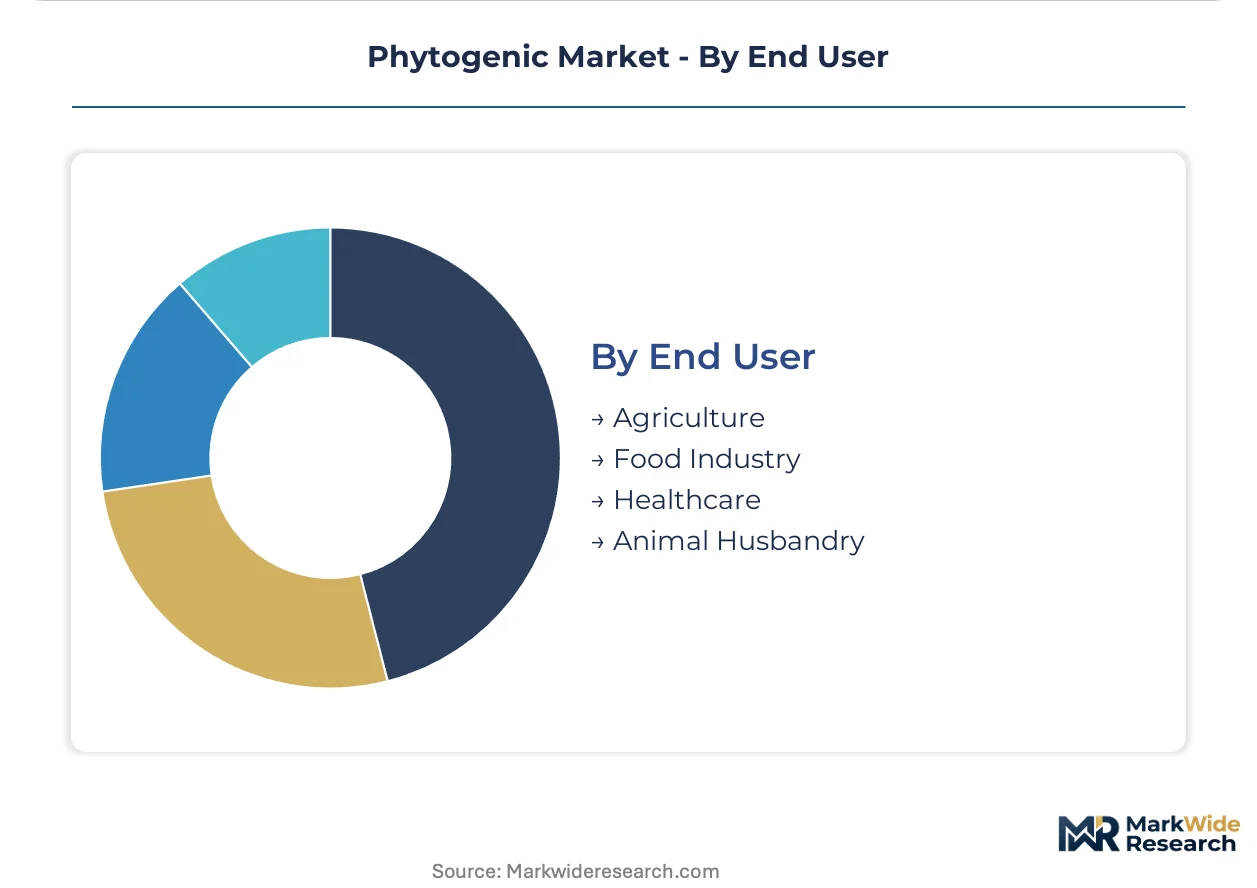
End User:
Geographic clustering of processing infrastructure concentrates supply relationships, with Croatian rosemary and Hungarian oregano processors establishing direct procurement contracts with Dutch and French livestock cooperatives.
- Agriculture:Crop protection and soil amendment applications utilize botanical extracts for nematicidal and fungicidal properties in organic production systems.
- Food Industry:Clean-label preservation and flavor enhancement drive formulation demand from processed meat and beverage manufacturers.
- Healthcare:Pharmaceutical manufacturers source standardized plant extracts for active pharmaceutical ingredient development and traditional medicine formulations.
- Animal Husbandry:Monogastric and ruminant nutrition protocols specify species-specific phytogenic inclusion rates, with Delacon Biotechnik and DSM-Firmenich sustaining R&D intensity across standardized portfolios.
Animal husbandry absorbs the bulk of demand concentration; healthcare channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mediterranean thyme and oregano harvests anchor European phytogenic supply chains, while Brazilian eucalyptus and German chamomile operations concentrate distillation capacity for feed-grade essential oils.
United States
Southeastern broiler integrators specify microencapsulated thymol formulations for thermal stability during pelleting operations. FDA veterinary feed directive enforcement tightens documentation requirements for botanical growth promoter substitutions. Georgia and Alabama processing clusters absorb the majority of domestic essential oil procurement contracts.
Germany
Steam distillation yield improvements at Bavarian and Saxon facilities compress unit production costs for standardized terpenoid concentrates. EFSA botanical safety evaluations streamline dossier requirements for dried herb preparations entering EU member state markets. Hamburg and Frankfurt logistics hubs coordinate toll-processing services for specialized encapsulation operations.
Brazil
Feed additive makers in São Paulo and Minas Gerais states drive uptake as antibiotic growth promoter bans tighten across Mercosur jurisdictions. ANVISA pesticide residue screening protocols shape import documentation for Mediterranean herbal raw materials. Campinas and Ribeirão Preto essential oil distillers expand backward integration into captive eucalyptus and citrus biomass plantations.
China
NMPA and Ministry of Agriculture enforce maximum residue limits on imported herbal inputs, triggering batch destruction costs for non-compliant shipments. Yangtze River Delta feed compounders reformulate rations around botanical bioactives as domestic antibiotic reduction targets tighten. Shanghai and Nanjing processing facilities invest in supercritical CO2 extraction capacity for pharmaceutical-grade plant extracts.
India
FSSAI dual-use approval pathways enable crossover registrations from animal feed extracts into human digestive health supplements. CDSCO monitoring of nutraceutical channels creates parallel revenue streams beyond livestock applications. Gujarat and Maharashtra spice processing clusters concentrate solvent extraction capacity for standardized alkaloid concentrates.
Phytogenic Market Vendor Landscape
Global majors compete with regional champions across formulation technology and botanical sourcing networks, producing a tiered structure where integrated agribusiness conglomerates occupy premium positions while specialized biotechnology firms anchor mid-market segments. Three archetypes dominate: diversified nutrition conglomerates with captive supply chains, dedicated phytogenic blenders with species-specific protocols, and toll processors with encapsulation expertise. Competitive moves concentrate on backward integration into biomass procurement and capacity expansion at continuous distillation facilities.
Among diversified nutrition conglomerates, Cargill and DSM-Firmenich exemplify the integrated archetype through captive botanical sourcing and standardized extract portfolios. Delacon Biotechnik occupies a specialist position within the species-specific formulation tier, representing dedicated phytogenic blenders focused on monogastric and ruminant nutrition protocols. These three entities anchor the competitive spectrum from commodity-scale feed additive supply to precision-formulated botanical bioactives.
| Leading Market Players |
|---|
| Cargill |
| DSM-Firmenich |
| ADM |
| Delacon Biotechnik |
| Kemin Industries |
| DuPont |
| Nutreco |
| Adisseo |
| EW Nutrition |
| Others |
Supply Flow & Price Mechanics
Broiler integrators in the southeastern United States specifying microencapsulated thymol formulations are forcing Brazilian and German distillers to retrofit continuous processing equipment, compressing unit economics and redistributing margin capture toward buyers with volume leverage.
Pricing Analysis
Technical service bundling separates feed-grade essential oil quotations into unbundled commodity concentrates versus fully supported formulation packages with stability certification and species-specific dosing protocols. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA botanical safety dossier completeness, with pharmaceutical-grade terpenoid concentrates commanding sustained premiums while feed-grade thymol-carvacrol blends face cost compression from synthetic cinnamaldehyde substitution. Price differentiation hinges on third-party terpenoid concentration validation and oxidative stability guarantees. Mid-scale feed mills without pelleting equipment retrofits exhibit highest price sensitivity; integrated poultry operators with captive formulation teams demonstrate lowest.
Supply Chain Analysis
Specialized extraction chemist scarcity concentrates among Bavarian, Swiss, and Japanese technical institutes, constraining supercritical CO2 capacity expansion despite pharmaceutical-grade demand growth. Mediterranean smallholder networks supply seventy percent of pharmaceutical-grade thyme biomass, while Brazilian eucalyptus and German chamomile plantations anchor feed-grade distillation. Raw material dependencies center on climate-vulnerable oregano and rosemary harvests, laboratory-synthesized terpenoid analogues, and pesticide-compliant herbal imports. Single-source vulnerability from Croatian rosemary and Hungarian oregano processors exposes Dutch and French livestock cooperatives to harvest volatility. Distribution runs through toll-processing facilities at Hamburg and Frankfurt logistics hubs coordinating encapsulation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibiotic growth promoter bans across major livestock-producing jurisdictions are forcing consolidation as capital-intensive backward integration into biomass procurement eliminates formulation-only competitors lacking captive supply.
For Market Incumbents: Extend backward integration into Mediterranean thyme and oregano smallholder networks to secure climate-resilient biomass procurement against harvest volatility. Expand continuous steam distillation capacity at Brazilian and German facilities to capture cost compression from yield improvements. Synthetic phytochemical substitution threatens botanical extraction economics; EFSA botanical safety dossier investment preserves premium positioning against unvalidated competitors. For New Entrants and Emerging Players: Precision fermentation capabilities for heat-sensitive terpenoid biosynthesis offer unprotected white space against established botanical extractors. Aquaculture gut health protocols for shrimp and salmonid species remain underdeveloped relative to terrestrial livestock penetration. India's FSSAI dual-use nutraceutical crossover approvals provide the most penetrable regulatory pathway for human digestive health supplement positioning. Target toll-processing partnerships with Croatian rosemary and Hungarian oregano processors to bypass capital-intensive distillation infrastructure. For Investors and Strategic Acquirers: The window for entry favors species-specific phytogenic blenders with validated monogastric and ruminant protocols before EFSA registration queues lengthen. Long-term viability centers on integrated models combining captive biomass with formulation science capabilities. Watch EFSA botanical safety evaluation throughput as inflection indicator; processing delays signal margin compression for undifferentiated commodity suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biomass Procurement | Cargill's captive botanical sourcing secures supply continuity against Mediterranean climate volatility. |
| Microencapsulation Capacity Expansion | Coated thymol formulations meet southeastern US broiler integrator thermal stability specifications. |
| EFSA Botanical Safety Dossier Investment | Streamlined approval pathways accelerate product registration timelines across EU member states. |
| Precision Fermentation Technology Adoption | Microbial terpenoid production enables biosynthesis of compounds impractical to isolate from plant matrices. |
| India FSSAI Dual-Use Registration | Crossover approvals from animal feed extracts into human digestive health supplements open parallel revenue streams. |
Methodological Framework
Independent corroboration across essential oil distiller production records, feed compounder procurement contracts, and EFSA botanical safety evaluation databases underwrites the qualitative findings. Primary interviews with extraction technology directors at German and Brazilian facilities, regulatory affairs leads navigating FDA veterinary feed directives, livestock cooperative procurement managers in France and the Netherlands, and species-specific nutrition protocol specialists at dedicated phytogenic blenders combined with secondary validation. Secondary sources include customs and trade data on Mediterranean herbal raw material flows, ANVISA pesticide residue screening protocols, SEC filings from diversified nutrition conglomerates, and FSSAI dual-use approval track records. Bottom-up volume modeling from installed distillation capacity and top-down value triangulation from procurement contract values cross-validate segment estimates.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects. Segmentation dimensions modeled include product type, application channel, formulation specification, and end-user industry vertical. CAGRs derive from fitted trend extrapolation against regulatory inflection points and technology substitution curves. Industry-specific forecast inputs center on EFSA botanical safety evaluation throughput rates and antibiotic growth promoter ban implementation schedules across Mercosur and North American jurisdictions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under climate-induced Mediterranean harvest failure or accelerated synthetic phytochemical cost reduction. Forecasts reflect documented assumptions on regulatory harmonization progress and extraction yield improvement trajectories. Material deviation in EFSA evaluation timelines or precision fermentation unit cost curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Lipids Market
Ingredients
Europe Agar Market
Ingredients
United States Wheat Protein Market
Ingredients
Global Dietary Fibers Market
Ingredients
Microparticulated Egg White Protein Market
Ingredients
Hen Egg White Protein Market
Ingredients
South America Vegetable Oil Market
Ingredients
Europe Alcohol Ingredients Market
Ingredients
Edible Oils and Fats Market
Ingredients
North America Alcohol Ingredients Market
Ingredients
Sea Buckthorn Berry Extract Market
Ingredients
Milk Mineral Concentrate Market
Ingredients
Apple Extract Market
Ingredients
Europe Pea Starch Market
Ingredients
North America Gelatin Market
Ingredients
Fig Ingredient Market