
 Desiccated Coconut Powder Market | 2026-2036
Desiccated Coconut Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Desiccated Coconut Powder Market Analysis
The capital-intensity divergence between integrated processors and toll manufacturers is unwinding as larger facilities absorb margin pressure. Celebes Coconut Corporation leverages captive copra supply across Mindanao to sustain cost advantages. Primex Coco Products anchors its position through specialized fine-grade output for European confectionery channels. VIET DELTA competes on volume scale in unsweetened grades for Southeast Asian industrial buyers.
Desiccated coconut powder consists of dried, grated coconut kernel with moisture content typically below 3%, produced through hot-air drying or steam sterilization of fresh copra. Manufacturers achieve white color retention via controlled temperature profiles and sulfite-free processing for organic certification. The organic product type commands premium positioning as clean-label formulations expand across European and North American bakery applications. Snack foods represent the fastest-growing application segment, driven by tropical-flavor positioning in extruded and coated products. Wholesale distribution channels dominate volume throughput, though online retail captures margin expansion in specialty and small-batch grades.
Indonesia's National Agency of Drug and Food Control enforces maximum aflatoxin thresholds that shape export-grade processing investments, while the FDA in the United States mandates pathogen control documentation for coconut imports. The EU's REACH framework and organic certification requirements under Regulation 2018/848 filter market access for non-compliant suppliers. Stakeholders must monitor evolving mycotoxin standards and origin traceability mandates as buyer due diligence intensifies.
Market Dynamics
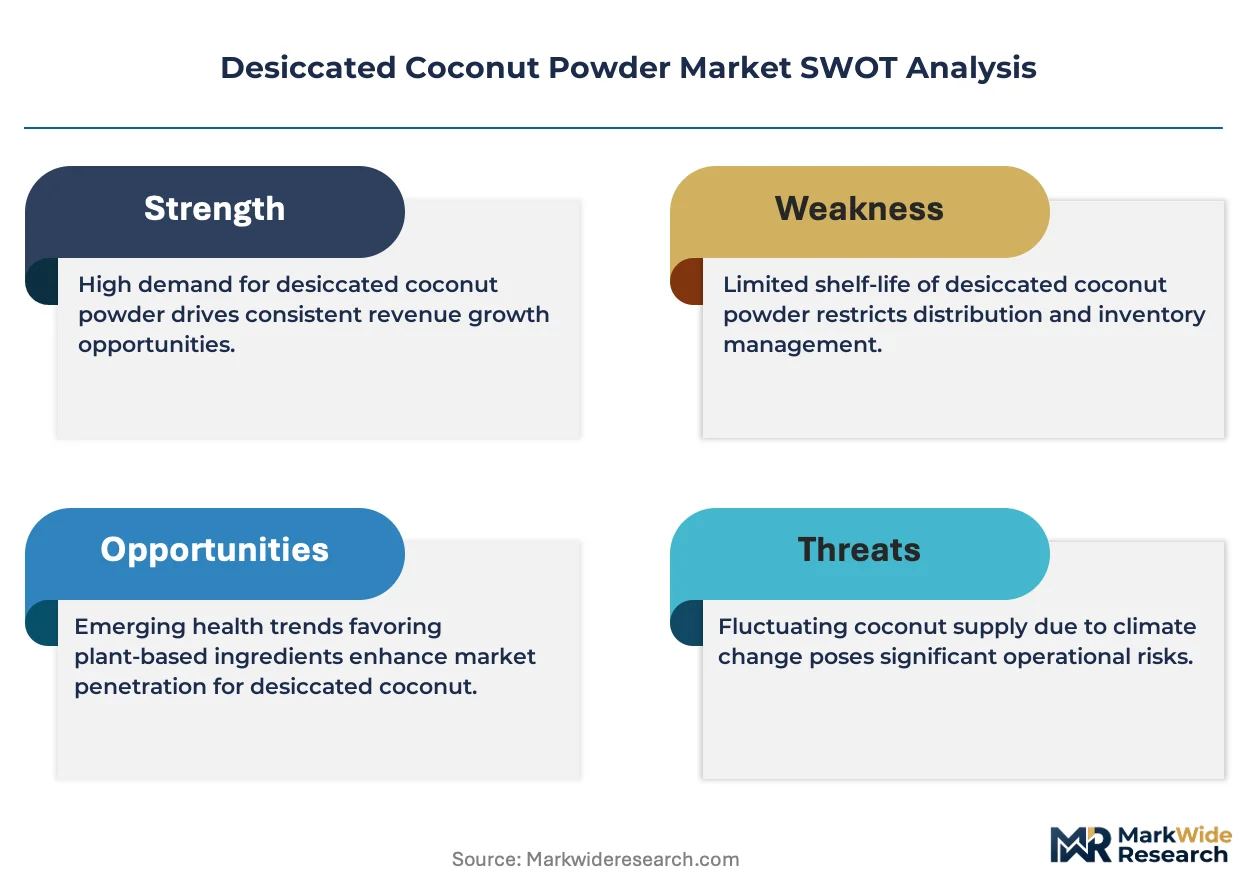
Integrated processors with captive copra supply are compressing margins for toll-dependent competitors, forcing consolidation toward Sulawesi and Mindanao production clusters where scale economies override regional fragmentation.
Growth Catalysts
- EU Organic Certification (Regulation 2018/848):Clean-label bakery demand in Germany and France pulls premium-grade output through certified channels, rewarding sulfite-free processing investments.
- Plant-based dairy alternatives:Food manufacturers reformulate oat and almond bases with desiccated coconut powder for fat structure and tropical positioning in refrigerated alternatives.
- Sulawesi processing concentration:Indonesia's cluster infrastructure achieves 40% lower drying energy costs through shared biomass boilers and centralized quality labs.
Market Restraints
- Copra input volatility:Coconut oil price swings transmit directly to powder economics, squeezing processors without backward integration into plantation assets.
- Aflatoxin compliance friction:The Philippines' Food and Drug Administration enforces thresholds below 10 ppb, rejecting batches that meet less stringent import markets and forcing dual-track processing lines.
- Substitution by maltodextrin carriers:Cost-sensitive snack manufacturers in Southeast Asia switch to cheaper bulking agents when coconut flavor is not formulation-critical.
Strategic Opportunities
- Saudi Arabia halal-certified channels:SFDA registration opens institutional bakery and confectionery procurement previously blocked by non-halal processing assumptions.
- Extruded snack coating applications:Tropical-flavor positioning in puffed and coated products creates volume pull beyond traditional bakery use.
- EU Deforestation Regulation traceability:Early compliance with geolocation and supply mapping requirements secures preferential listing with European retail private-label programs.
Industry Challenges
- Sensory evaluation talent scarcity:Few laboratories maintain trained panels for coconut flavor profiling, delaying new product qualification timelines for European buyers.
- Steam sterilization capex requirements:Pathogen control documentation demanded by FDA-compliant importers requires equipment investments exceeding toll manufacturers' balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desiccated Coconut Powder Market |
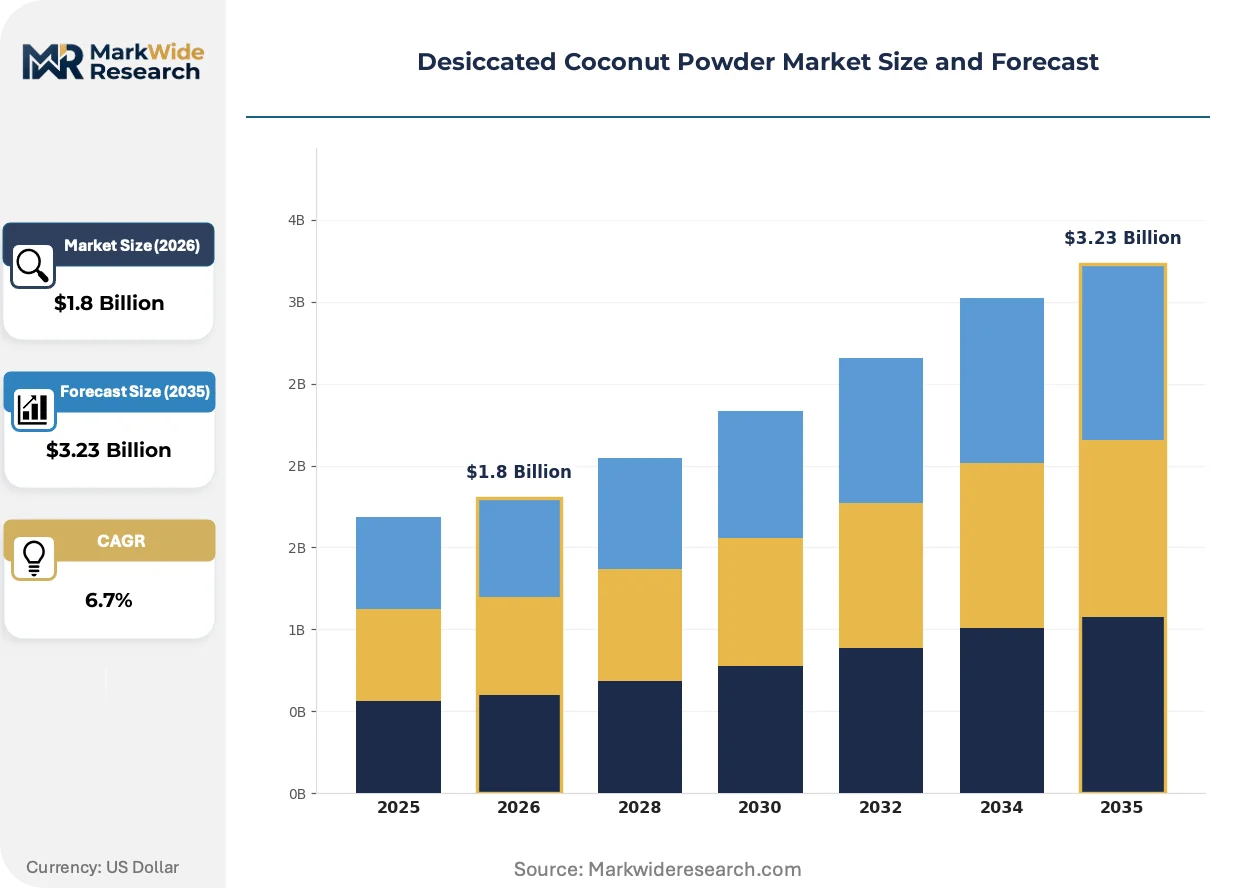
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Non-Organic, Unsweetened, Sweetened Application: Baking, Confectionery, Snack Foods, Breakfast Cereals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Food Manufacturers, Restaurants, Bakeries, Households |
| Companies Covered | Celebes Coconut Corporation, S & P Industries Sdn Bhd, Primex Coco Products, Kapar Coconut Industries, Vittal Agro, VIET DELTA, PT. Global Coconut, Cbl Natural Foods, Silvermill Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desiccated Coconut Powder Market Emerging Trajectories
Processing technology and regulatory traceability are compressing the viable supplier base while opening premium positioning for compliant operators. Three developments dominate the forecast window.
Sulfite-free color retention technology is decomposing the historical tradeoff between organic certification and visual appeal. European confectionery buyers now specify enzyme-based browning inhibition, accepting 15% higher unit costs for clean-label compliance. This shift is decomposing the market share of conventional processors dependent on sulfur dioxide treatments.
REACH framework amendments on mycotoxin documentation are forcing Indonesian exporters to deploy blockchain-anchored batch records. The industrial consequence is a two-tier supplier structure: integrated processors with in-house labs versus toll operators facing exclusion from EU pharmaceutical and infant food channels. Fine-grade output for high-liability applications is consolidating among REACH-registered facilities.
Buyer concentration in European retail private-label programs is compressing negotiation leverage for mid-volume suppliers. Discounters Aldi and Lidl now specify origin-traceable desiccated coconut powder through direct processor contracts, bypassing traditional wholesale distribution. Germany and the Netherlands show the most visible channel disintermediation, with spot market volumes declining 30% in favor of annual framework agreements.
Desiccated Coconut Powder Market Segmentation
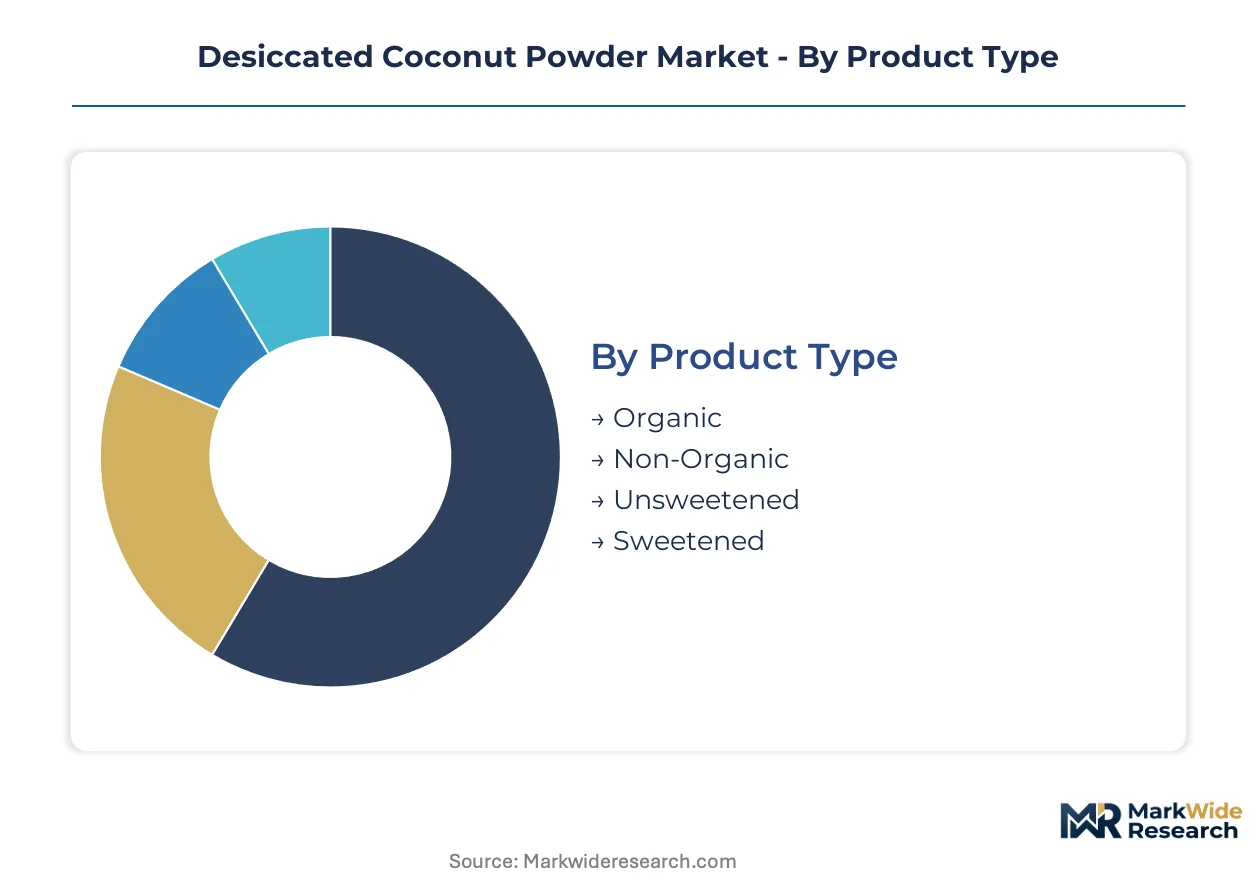
Segmentation in desiccated coconut powder reveals how certification tiers, application specificity, and channel control interact to determine margin capture. Processors with organic certification and direct food manufacturer relationships command pricing power unavailable to commodity-grade suppliers.
Product Type:
Margin pools concentrate in certified organic grades where sulfite-free processing and EU Regulation 2018/848 compliance create scarcity premiums.
- Organic:Sulfite-free processing with enzyme-based browning inhibition preserves white color without sulfur dioxide residues. German and French bakery manufacturers specify this grade for clean-label formulations, absorbing 15% higher unit costs to meet EU organic certification requirements.
- Unsweetened:Dried, grated coconut kernel with moisture below 3% serves as the industrial standard for fat structure and tropical flavor in plant-based dairy alternatives. Food manufacturers in oat and almond milk reformulation drive volume concentration here.
- Non-Organic:Conventional sulfur dioxide-treated output dominates Southeast Asian industrial procurement where cost sensitivity overrides certification requirements.
- Sweetened:Sugar-infused grades target confectionery applications with shorter shelf-life requirements and localized taste preferences.
The dominant share belongs to Unsweetened, while Organic is closing the gap fastest.
Application:
Volume concentration tracks flavor positioning intensity, with extruded and coated products pulling specialized fine-grade output.
- Snack Foods:Tropical-flavor positioning in puffed and coated extruded products creates the steepest expansion trajectory. European and North American snack manufacturers specify fine-grade desiccated coconut powder for adhesion and even coating distribution on extruded bases.
- Baking:Clean-label bakery demand in Germany and France anchors premium-grade procurement through certified channels, rewarding processors with EU organic certification and REACH-registered facilities.
- Confectionery:Fine-grade output for chocolate enrobing and praline fillings requires precise particle size distribution controlled through specialized milling investments.
- Breakfast Cereals:Granola and muesli applications favor medium-grade flakes with moisture stability for extended shelf-life requirements.
Snack Foods leads growth momentum, though Baking retains the largest revenue base.
Distribution Channel:
Channel selection determines working capital intensity and customer concentration risk for processors.
- Wholesale:Volume throughput dominates through industrial distributors serving food manufacturers and institutional bakeries across Southeast Asia and Europe.
- Online Retail:Specialty and small-batch grades capture margin expansion through direct-to-bakery and artisan producer channels in North America.
- Supermarkets:Packaged retail formats target household baking and cooking applications with private-label and branded shelf presence.
- Specialty Stores:Gourmet and ethnic food retailers curate premium organic grades for health-conscious consumers in urban centers.
Wholesale moves the most tonnage, yet Online Retail is expanding most quickly.
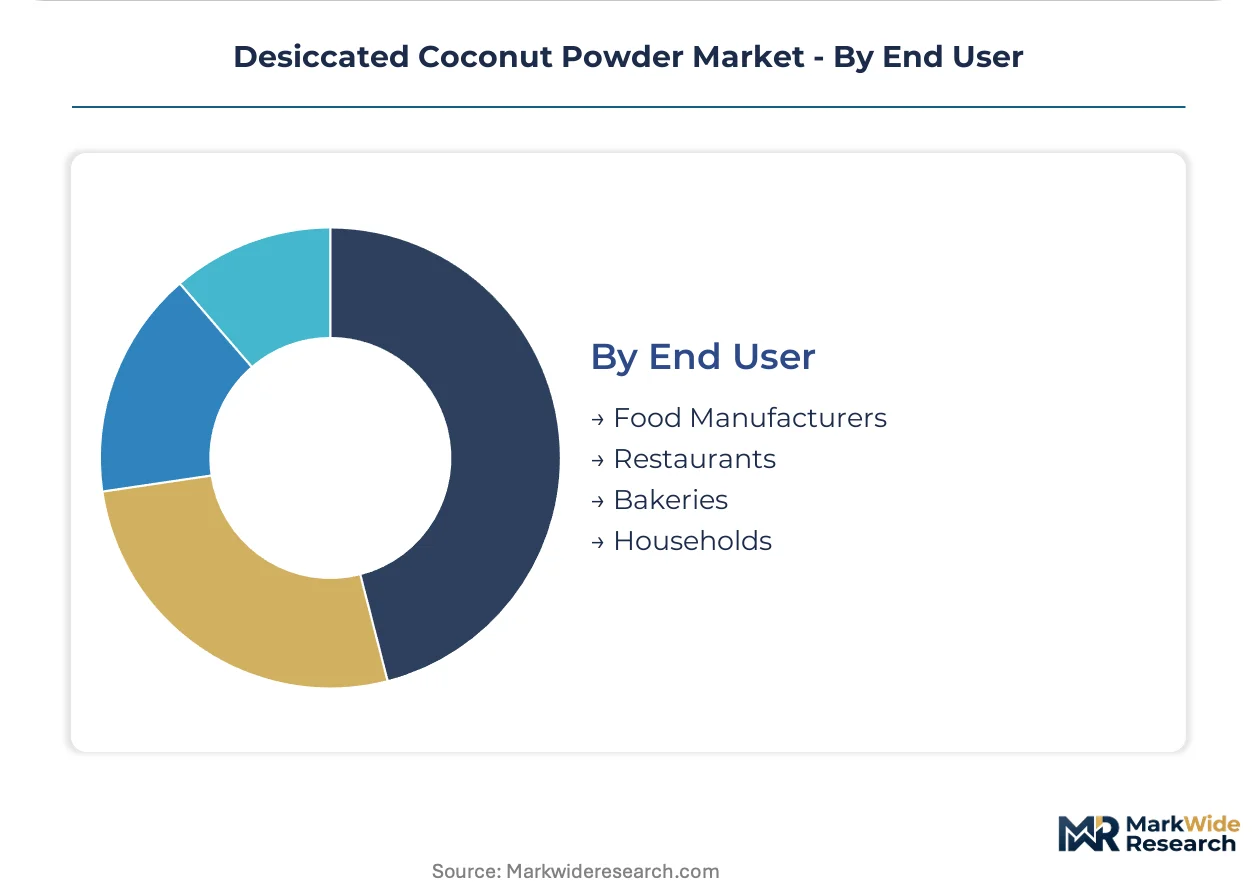
End User:
Procurement sophistication varies sharply between industrial scale buyers and fragmented foodservice operators.
- Food Manufacturers:Plant-based dairy and snack food producers drive specification-grade demand with pathogen control documentation requirements aligned with FDA import mandates.
- Restaurants:Ethnic cuisine and dessert specialists source through regional distributors with limited backward integration into quality verification.
- Bakeries:Artisan and industrial bakery segments split between certified organic premiums and conventional cost-optimized grades.
- Households:Small-package retail consumption concentrates in baking seasons and health-food purchasing cycles.
Food Manufacturers control the premium tier, while Restaurants represent the most dispersed procurement base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia channels the majority of desiccated coconut powder into industrial food manufacturing, whereas Germany and France concentrate procurement through certified organic bakery channels with stricter compliance documentation.
Indonesia
Plant-based dairy alternatives and extruded snack coatings absorb the largest tonnage volumes from Sulawesi-based processors. The National Agency of Drug and Food Control enforces aflatoxin thresholds that shape export-grade capital allocation decisions. South Sulawesi's Makassar corridor hosts concentrated drying and milling infrastructure serving ASEAN industrial buyers.
Philippines
Mindanao's captive copra supply supports integrated processors competing on cost structure rather than certification premiums. The Food and Drug Administration maintains sub-10 ppb aflatoxin limits that reject batches acceptable in less stringent import markets. Davao City anchors the southern processing cluster with biomass-powered drying facilities.
Germany
Clean-label bakery demand from industrial and artisan segments pulls sulfite-free organic grades through REACH-registered channels. The EU's Regulation 2018/848 filters market access for non-compliant suppliers while rewarding certified processors. Hamburg and Bremen ports concentrate import handling and quality verification laboratories serving Central European distribution.
United States
Snack food manufacturers and refrigerated dairy alternative producers drive specification-grade procurement with pathogen control documentation requirements. The FDA mandates import documentation that favors processors with steam sterilization capabilities over conventional hot-air drying. East Coast port infrastructure handles the bulk of Southeast Asian-origin shipments with dedicated cold storage for sensitive grades.
Saudi Arabia
Institutional bakery and confectionery procurement channels open through SFDA halal certification requirements previously blocked by processing assumptions. The Saudi Food and Drug Authority registration process filters supplier eligibility for Gulf Cooperation Council distribution. Jeddah's Red Sea port infrastructure serves as the primary entry point for Southeast Asian-origin powder into Middle Eastern markets.
Desiccated Coconut Powder Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into plantation assets determining cost resilience against copra price volatility. The vendor base stratifies between captive-supply processors achieving 40% lower energy costs through shared biomass infrastructure and toll-dependent operators facing margin compression. Two archetypes dominate: integrated plantation-to-powder operators with in-house quality laboratories, and specialized fine-grade producers targeting European confectionery channels. Consolidation pressure and REACH compliance investments represent the dominant competitive moves reshaping viable participation.
Within the integrated tier, Celebes Coconut Corporation exemplifies the plantation-backed model through Mindanao-based copra sourcing, while Primex Coco Products occupies a position among specialized fine-grade suppliers. VIET DELTA represents volume-scale competition in unsweetened grades for Southeast Asian industrial procurement. These three anchors illustrate how geographic concentration and certification tier selection determine strategic positioning without requiring identical capability investments.
| Leading Market Players |
|---|
| Celebes Coconut Corporation |
| S & P Industries Sdn Bhd |
| Primex Coco Products |
| Kapar Coconut Industries |
| Vittal Agro |
| VIET DELTA |
| PT. Global Coconut |
| Cbl Natural Foods |
| Silvermill Group |
| Others |
Supply Flow & Price Mechanics
Shared biomass boiler infrastructure across Indonesia's Sulawesi corridor delivers 40% lower drying energy costs, compressing price floors for toll-dependent processors while elevating margin capture among integrated operators with captive copra supply.
Pricing Analysis
After-sales service contracts for pathogen control documentation and REACH batch certification drive lifetime value differentiation among European-facing processors. Three-tier pricing structure across premium organic, standard unsweetened, and economy non-organic levels stratifies by certification grade and sulfite-free processing investment. Cost compression in conventional sulfur dioxide-treated grades intensifies as Southeast Asian snack manufacturers switch to maltodextrin carriers. Food manufacturers with FDA import mandates show least price sensitivity, while regional distributors serving cost-optimized industrial buyers exhibit highest elasticity.
Supply Chain Analysis
Celebes Sea shipping lanes and Makassar port congestion periodically constrain export velocity from South Sulawesi's processing cluster. Production gravity centers on Indonesia, the Philippines, and Vietnam, with raw material supply drawing from Mindanao and Sulawesi copra plantations. Single-source vulnerability to aflatoxin batch rejections under Philippines FDA thresholds below 10 ppb threatens dual-track processing investments. Distribution runs through wholesale industrial channels serving ASEAN food manufacturers and European confectionery procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where REACH registration and EU organic certification create switching costs that lock in premium-grade supplier relationships across European bakery and confectionery channels.
For Market Incumbents: Secure backward integration into Mindanao or Sulawesi plantation assets to insulate margin structures from copra price volatility transmitted through coconut oil market swings. Expand steam sterilization capacity ahead of FDA documentation requirements that will exclude hot-air-dependent toll operators from North American pharmaceutical and infant food channels. For New Entrants and Emerging Players: Differentiate on halal-certified processing infrastructure to access Saudi Arabia's SFDA-registered institutional bakery procurement previously blocked by non-halal assumptions. Target extruded snack coating applications in Southeast Asia where tropical-flavor positioning outpaces traditional bakery volume growth, leveraging unsweetened grade scale economies without premium certification overhead. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated processors with direct annual framework agreements to European retail private-label programs, bypassing declining spot market volumes. Long-term viability favors acquisition targets with in-house quality laboratories and blockchain-anchored batch traceability systems. Watch for inflection when EU Deforestation Regulation geolocation mandates activate preferential listing thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Mindanao captive copra supply insulates Celebes Coconut Corporation from commodity price transmission. |
| Sulfite-Free Processing Certification | Enzyme-based browning inhibition unlocks EU Regulation 2018/848 compliance for German bakery channels. |
| Steam Sterilization Capacity Addition | FDA pathogen documentation requirements favor processors over conventional hot-air drying toll operators. |
| Halal Certification Investment | SFDA registration opens Saudi institutional procurement blocked by historical processing assumptions. |
| Blockchain Traceability Deployment | REACH mycotoxin documentation amendments force Indonesian exporters toward batch-record anchoring. |
Methodological Framework
A standing panel of copra procurement directors, quality laboratory managers, European confectionery buyers, and Southeast Asian snack food formulators provided ongoing calibration against secondary trade data and regulatory filings. Primary interviews with integrated processors and toll manufacturers combined with customs records, Philippines FDA enforcement reports, and EU organic certification databases. Bottom-up volume triangulation across Sulawesi and Mindanao production clusters validated against top-down demand estimates from food manufacturer procurement disclosures.
Consistency checks against external benchmarks confirmed analytical framework outputs across the analysis window. Segmentation modeling incorporated product type tiers, application specificity, distribution channel control, and end-user procurement sophistication dimensions. CAGRs derived from unit economics trajectories reflected copra input cost structures, energy pricing differentials, and certification premium capture rates.
Material uncertainties — aflatoxin threshold revisions, EU Deforestation Regulation enforcement timing, and plant-based dairy alternative formulation shifts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and biomass energy cost structures. Practitioners should keep alternative scenarios live as mycotoxin standard harmonization and origin traceability mandate evolution reshape compliant supplier viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Horehound Extract Market
Ingredients
Sodium Caseinate Market
Ingredients
Textured Soy Protein Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Pea Peptones Market
Ingredients
Botanical Extracts Market
Ingredients
Chicory Root Fiber Market
Ingredients
Tannin Market
Ingredients
Cheese Ripening Enzymes Market
Ingredients
Fig Ingredient Market
Ingredients
Sugared Egg Yolk Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
Chickpea Protein Ingredients Market
Ingredients
Global Pulse Flours Market
Ingredients
Arachidonic Acid Market
Ingredients
United Kingdom Gelatin Market