
 Europe Corn Glucose Market | 2026-2036
Europe Corn Glucose Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Corn Glucose Market Intelligence
The EU Green Deal is realigning procurement priorities across European corn glucose buyers toward lower-carbon supply chains. Roquette Freres leverages its plant-based ingredient expertise to anchor clean-label glucose positioning for food manufacturers. Cargill Inc. competes through backward integration into European maize sourcing, securing supply stability amid volatile grain markets. Tate & Lyle PLC differentiates via specialty dextrose formulations targeting pharmaceutical-grade applications.
Corn glucose comprises purified starch hydrolysates derived from maize enzymatic conversion, typically exhibiting dextrose equivalents between twenty and ninety-five depending on intended viscosity and sweetness profiles. The substance functions primarily as a bulk sweetener, humectant, and crystallization inhibitor across processed food systems. Liquid glucose dominates volume flows into European confectionery and bakery operations where moisture retention properties command premium formulation slots. Dextrose segments sustain higher margin structures in pharmaceutical applications requiring compendial-grade purity certifications. Powder and granular forms occupy niche positions in dry-mix beverages and sports nutrition products where handling efficiency outweighs liquid convenience.
EMA pharmaceutical standards and EU Green Deal industrial decarbonization frameworks jointly constrain processing methodologies while opening certified-sustainable product premiums. REACH chemical registration requirements govern modified glucose derivatives entering cosmetic and personal care verticals, filtering non-compliant imports from extra-European suppliers. EFSA food additive evaluations periodically recalibrate acceptable daily intake thresholds, directly reformulating end-product recipes across Food & Beverage verticals. Stakeholders must monitor evolving F-Gas Regulation amendments affecting starch facility refrigeration systems and their pass-through cost impacts on glucose refining economics.
Market Dynamics
The EU Green Deal's industrial decarbonization mandates are restructuring corn glucose procurement priorities across European food and beverage manufacturers, forcing energy-intensive starch processors to retrofit enzymatic conversion facilities or surrender volume to certified-low-carbon competitors.
Growth Catalysts
- Clean-label formulation mandates:EFSA additive evaluations are reformulating confectionery and bakery recipes toward simpler ingredient decks, elevating corn glucose as a recognizable alternative to synthetic sweeteners.
- Pharmaceutical-grade dextrose certification:EMA compendial standards are opening premium revenue tiers for producers achieving injectable-grade purity, redirecting capital toward specialized refining lines.
- Germany's food processing belt concentration:Large-scale bakery clusters in Bavaria and Baden-Württemberg are consolidating liquid glucose procurement through direct supplier partnerships, anchoring regional demand stability.
Market Restraints
- Maize input cost volatility:Ukrainian grain supply disruptions and weather-driven yield fluctuations in Romania and Hungary are compressing margin predictability for starch processors lacking backward integration into sourcing.
- F-Gas Regulation compliance burdens:Facility refrigeration system retrofits required under evolving EU F-Gas amendments are imposing capital intensity on mid-scale glucose refiners without captive engineering resources.
- Isomaltulose substitution pressure:Low-glycemic alternative sweeteners are capturing formulation slots in sports nutrition and diabetic-friendly confectionery, eroding dextrose share in health-positioned product lines.
Strategic Opportunities
- Poland's underpenetrated pharmaceutical vertical:Generic drug manufacturing expansion around Warsaw and Łódź is creating demand for compendial-grade glucose excipients currently sourced from Western European suppliers.
- Bioplastics feedstock pivot:Polylactic acid producers in the Netherlands and Belgium are qualifying corn glucose as a fermentation substrate, opening industrial demand beyond traditional food applications.
- CSRD-driven carbon accounting premiums:The EU Corporate Sustainability Reporting Directive is enabling price differentiation for glucose lots with verified lifecycle emissions documentation, rewarding early certifiers.
Industry Challenges
- Specialized enzyme engineering talent scarcity:Starch conversion facilities require biochemists capable of optimizing glucoamylase performance under variable substrate conditions, with recruitment competition from biopharma sectors intensifying.
- Legacy ERP integration with carbon tracking systems:Processors must reconcile decades-old production databases with new EU Green Deal reporting protocols, creating data architecture friction during compliance transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Corn Glucose Market |
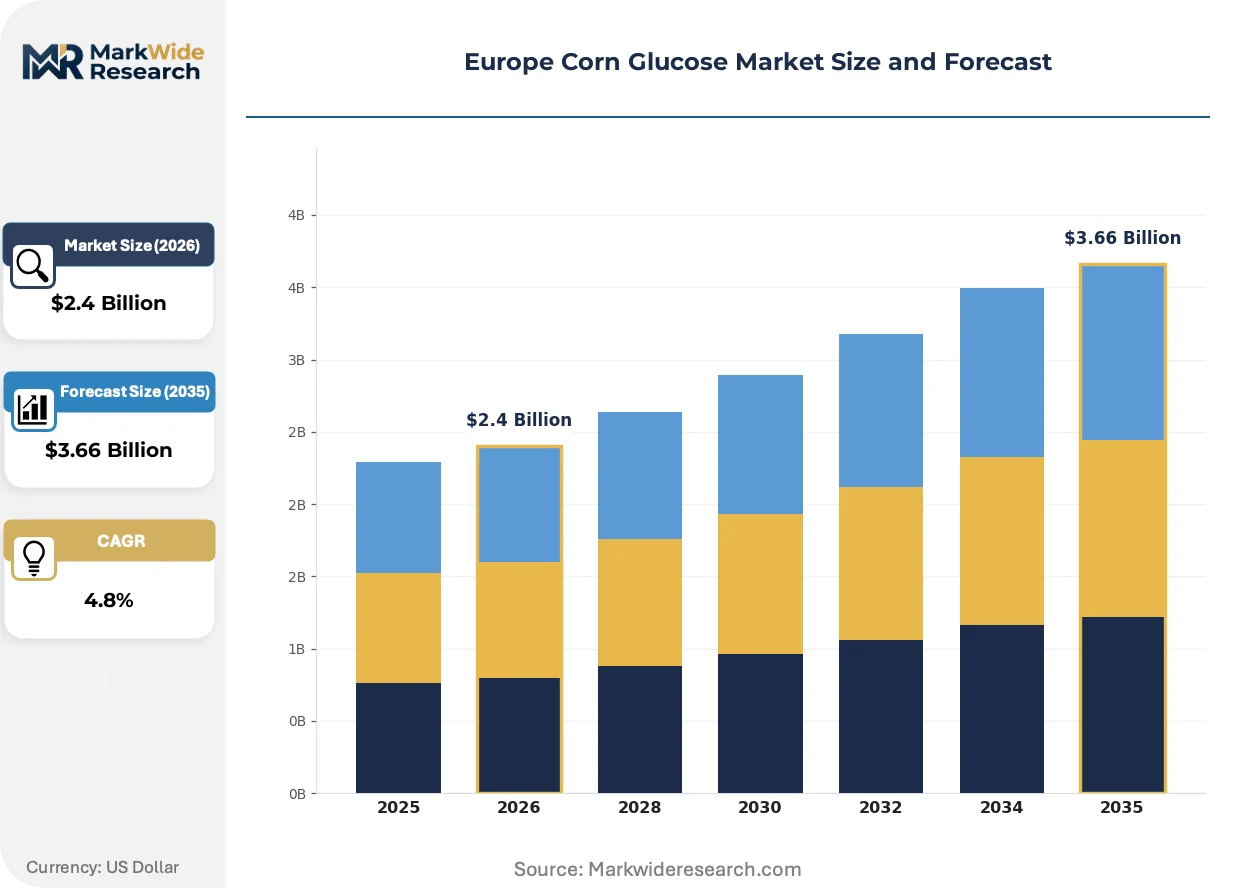
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Fructose Corn Syrup, Cornstarch, Liquid Glucose, Dextrose Industry Vertical: Food & Beverage, Pharmaceuticals, Personal Care, Animal Feed Form: Liquid, Powder, Granular, Syrup End User: Manufacturers, Retailers, Food Service, Exporters |
| Companies Covered | Roquette Freres, Cargill Inc., Archer Daniels Midland Company, Ingredion Inc., Tate & Lyle PLC, AGRANA Beteiligungs-AG, Dr. August Oetker KG, BENEO GmbH (Südzucker AG), Royal Avebe U.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Corn Glucose Market Strategic Shifts & Innovations
Continuous enzymatic conversion systems are displacing batch processing across European starch facilities, while regulatory carbon accounting and shifting buyer procurement models are compressing traditional supply relationships into direct partnerships.
Membrane filtration technology is overtaking conventional vacuum evaporation in glucose refining operations. German and Dutch processors are retrofitting ceramic and polymeric membrane systems to reduce steam energy consumption by half. This technology is overtaking legacy thermal methods because it enables simultaneous purification and concentration, collapsing capital requirements for facility expansion.
The EU F-Gas Regulation's phasedown schedule for hydrofluorocarbon refrigerants is forcing starch facility operators to adopt ammonia-based or transcritical CO2 cooling systems. Industrial refrigeration contractors report order backlogs extending eighteen months for compliant equipment. Bakery and confectionery clusters in Northern France are prioritizing suppliers with verified low-leakage refrigeration infrastructure in their vendor scorecards.
Direct mill-to-manufacturer contracting is fragmenting traditional glucose distribution channels. Large German bakery cooperatives are establishing toll-processing agreements with Romanian maize mills, bypassing established traders. This pattern is most visible in the liquid glucose segment serving industrial confectionery, where handling efficiency and carbon traceability now outweigh the convenience of distributor-stocked inventory.
Europe Corn Glucose Market Segmentation
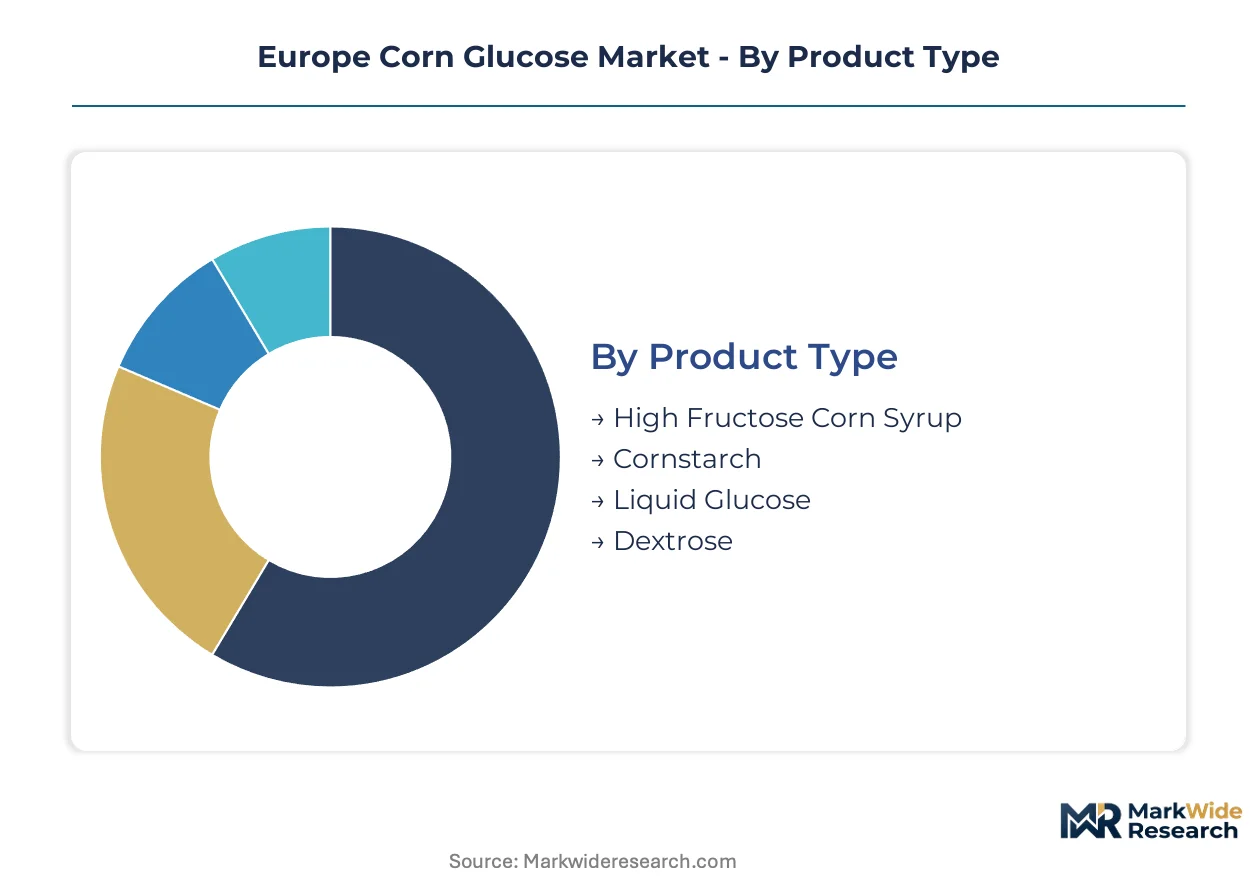
Segmentation in the European corn glucose market reveals how formulation requirements, regulatory compliance burdens, and supply chain configurations split demand across distinct product specifications and buyer categories. Understanding these divisions exposes where margin concentrates and where procurement power shifts between suppliers and end-users.
Product Type:
Buyers differentiate primarily by functional sweetness, viscosity requirements, and enzymatic conversion depth needed for their formulations.
- Liquid Glucose:Partially hydrolyzed starch syrup with dextrose equivalents typically between 20 and 48, prized for moisture retention and crystallization inhibition. Bavarian and Baden-Württemberg bakery clusters source this grade in bulk tanker volumes, with EFSA clean-label evaluations pushing synthetic sweetener substitution toward recognizable glucose-based alternatives.
- Dextrose:Highly refined monosaccharide achieving dextrose equivalents above 95 through complete enzymatic conversion and crystallization. Injectable-grade dextrose commands premium positioning in pharmaceutical applications around Frankfurt and Basel, where EMA compendial certification gates supplier qualification.
- High Fructose Corn Syrup:Isomerized glucose-fructose blend with elevated relative sweetness versus unmodified syrups. Reformulation trends in continental confectionery have compressed demand as manufacturers retreat from fructose-heavy recipes amid nutritional scrutiny.
- Cornstarch:Native or modified granular starch preceding hydrolysis, serving as feedstock for captive glucose production or direct food thickening. Romanian and Hungarian grain processors dominate upstream supply into Western European refiners.
Liquid glucose leads volumes today; dextrose is gaining share fastest.
Industry Vertical:
End-use concentration determines purity specifications, certification requirements, and contract structures across buyer segments.
- Food & Beverage:Confectionery, bakery, and beverage manufacturers constitute the volume anchor, with clean-label mandates from EFSA driving synthetic sweetener displacement. German cooperatives increasingly contract directly with Romanian mills for liquid glucose toll processing.
- Pharmaceuticals:Compendial-grade dextrose for parenteral nutrition and tablet excipients demands injectable purity certification under EMA standards. Warsaw and Łódź generic drug manufacturing expansion is creating new demand nodes previously served from Western Europe.
- Personal Care:REACH-registered glucose derivatives enter cosmetic formulations as humectants and fermentation substrates. Modified glucose esters face tighter ECHA evaluation thresholds than food-grade equivalents.
- Animal Feed:Lower-purity glucose syrups supplement caloric density in compound feed production. This segment tracks grain price volatility more closely than formulation-driven verticals.
Food and Beverage dominates volume absorption; Pharmaceuticals is expanding most quickly.
Form:
Physical state selection hinges on handling infrastructure, moisture sensitivity of end products, and transportation economics.
- Liquid:Dominant format for industrial-scale confectionery and bakery operations, delivered in bulk tankers with temperature-controlled logistics. Northern French clusters now scorecard suppliers on refrigeration infrastructure compliance with F-Gas Regulation amendments.
- Powder:Spray-dried glucose for dry-mix beverages and instant formulations where moisture control is critical. Sports nutrition manufacturers in the Netherlands favor this format for blending efficiency.
- Granular:Crystalline dextrose with defined particle size distribution for direct compression tableting and controlled dissolution applications. Pharmaceutical-grade granular commands specification premiums over standard crystalline.
- Syrup:Intermediate viscosity products between liquid glucose and fully refined dextrose, often customized to specific DE ranges for individual customer formulations.
Liquid form anchors current procurement; Powder is climbing the fastest.
End User:
Scale and integration depth separate how different buyer types structure supplier relationships and inventory positions.
- Manufacturers:Integrated food, pharmaceutical, and chemical processors with captive formulation expertise and tank farm infrastructure. Direct mill partnerships are fragmenting traditional distribution channels for this cohort.
- Food Service:Restaurants, catering operations, and institutional kitchens sourcing smaller-format glucose for recipe execution. This segment shows price sensitivity and limited backward integration.
- Retailers:Private-label confectionery and baking ingredient brands packaging glucose for consumer purchase. Clean-label positioning drives premium tiering in this channel.
- Exporters:Traders and redistributors qualifying glucose lots for extra-European destinations with divergent regulatory standards. Brexit-related customs friction has reconfigured UK-bound flows through dedicated certification tracks.
Manufacturers command the largest volume share; Food Service is advancing quickest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial starch processing took root in Germany's Rhineland during the late nineteenth century, spreading through the Netherlands and Belgium as enzymatic conversion technologies matured. Today's European corn glucose map reflects this inherited infrastructure, with modern demand clustering around food manufacturing belts and pharmaceutical corridors that have absorbed successive waves of processing innovation.
Germany
Bavarian and Baden-Württemberg bakery cooperatives anchor continental liquid glucose consumption, sourcing bulk tanker volumes for industrial confectionery production. The EU Green Deal's industrial decarbonization mandates are forcing Baden-Württemberg processors to retrofit enzymatic facilities with membrane filtration systems. Frankfurt's pharmaceutical corridor sustains premium dextrose demand for parenteral nutrition formulations.
France
Northern French confectionery clusters around Lille and Roubaix are prioritizing suppliers with F-Gas Regulation-compliant refrigeration infrastructure in procurement scorecards. EFSA clean-label evaluations are reformulating traditional patisserie recipes toward glucose-based sweeteners. The Hauts-de-France region hosts specialized refining capacity serving both food and pharmaceutical verticals.
Netherlands
Polylactic acid producers in the Rotterdam-Antwerp port corridor are qualifying corn glucose as fermentation feedstock for bioplastics manufacturing. Dutch membrane technology suppliers are retrofitting German and Belgian starch facilities with energy-efficient ceramic filtration systems. CSRD carbon accounting requirements are enabling price premiums for glucose lots with verified lifecycle emissions documentation.
Italy
Emilia-Romagna's pasta and confectionery manufacturers are expanding glucose procurement for clean-label reformulations of traditional products. REACH registration requirements govern modified glucose derivatives entering cosmetic formulations from Lombardy-based personal care producers. Milan's pharmaceutical packaging cluster creates downstream demand for compendial-grade excipients.
Poland
Generic drug manufacturing expansion around Warsaw and Łódź is generating demand for pharmaceutical-grade glucose excipients previously sourced from Western European refiners. Polish maize processors are developing toll-processing capabilities to serve German bakery cooperatives seeking supply diversification. The country's starch industry is upgrading enzymatic conversion capacity to meet EMA purity standards.
Europe Corn Glucose Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-grade and carbon-accounting dimensions, with injectable-grade dextrose and CSRD-verified low-emission glucose commanding structural price premiums over standard food-grade syrups. The vendor base organizes into three archetypes: integrated agribusiness conglomerates with captive maize sourcing, specialized starch processors with deep enzymatic engineering capabilities, and regional toll processors serving specific industrial clusters. Dominant competitive moves include backward integration into Romanian and Hungarian grain origination, and facility retrofit partnerships with membrane technology vendors.
Within the specialized starch processing tier, Roquette Freres and Tate & Lyle PLC exemplify divergent strategic positioning around application-specific purity grades, while Cargill Inc. occupies a position reflecting integrated agricultural supply chain control. These three anchors represent how European corn glucose competition stratifies across clean-label food positioning, pharmaceutical-grade certification, and upstream sourcing security rather than converging on a single performance vector.
| Leading Market Players |
|---|
| Roquette Freres |
| Cargill Inc. |
| Archer Daniels Midland Company |
| Ingredion Inc. |
| Tate & Lyle PLC |
| AGRANA Beteiligungs-AG |
| Dr. August Oetker KG |
| BENEO GmbH (Südzucker AG) |
| Royal Avebe U.A. |
| Others |
Cost & Logistics Intelligence
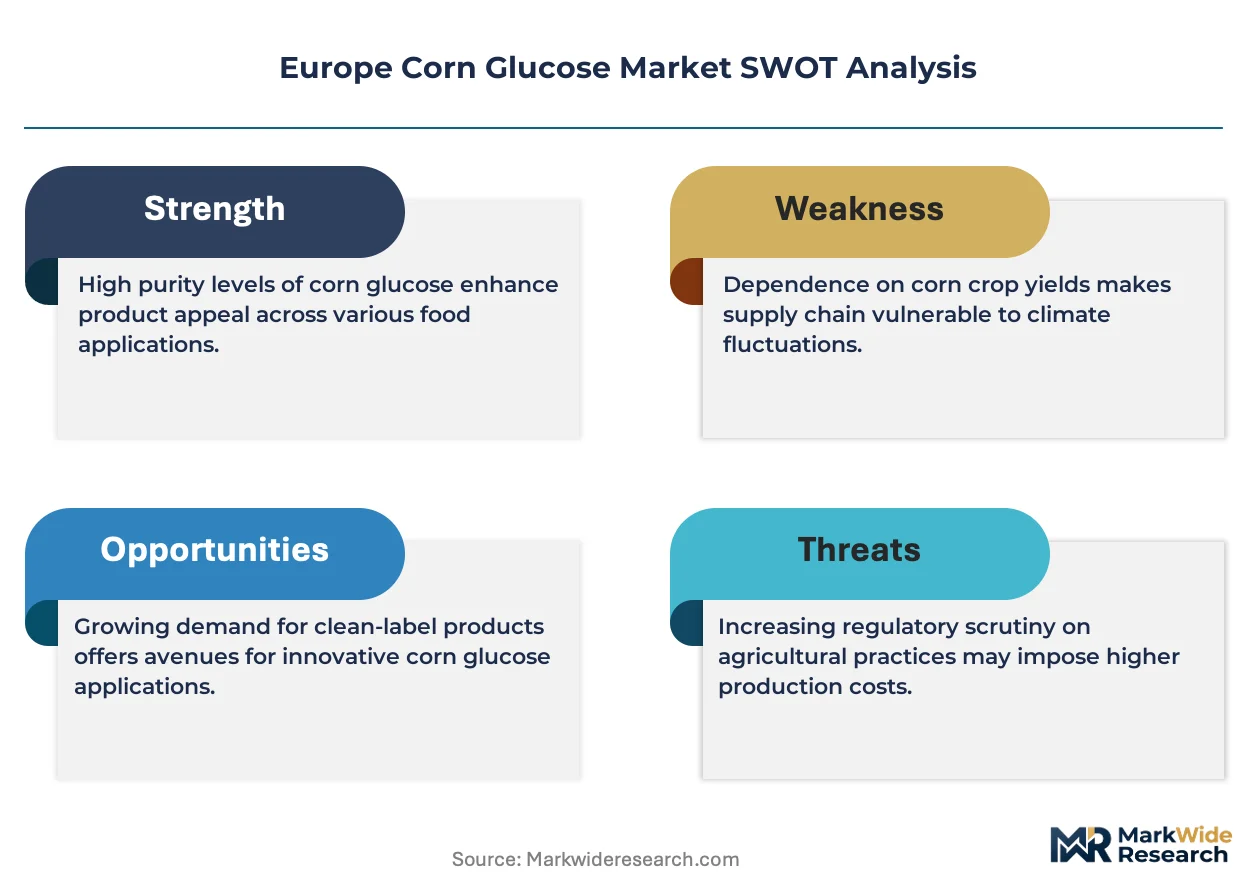
Injectable-grade certification premiums against standard food-grade commodity glucose bifurcate the European corn glucose market, with this divergence manifesting in both contract structures and supply chain configurations. EMA compendial standards gate pharmaceutical access while F-Gas Regulation compliance costs concentrate procurement power among capital-rich processors capable of retrofitting refrigeration infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs European corn glucose transactions, with certification grade and volume scale as the primary differentiation drivers. Pharmaceutical-grade dextrose commands substantial premiums over liquid glucose for confectionery applications. Pricing pressure stems from Ukrainian grain supply disruptions compressing margin predictability for non-integrated processors. Large German bakery cooperatives exhibit lowest price sensitivity due to direct toll-processing arrangements, while food service distributors remain most exposed to spot market volatility.
Supply Chain Analysis
EMA pharmaceutical certification and EU Green Deal carbon accounting requirements gate supplier qualification, filtering non-compliant extra-European imports from downstream procurement scorecards. Supply concentrates in Germany, Romania, and Hungary, with enzymatic conversion facilities drawing from maize inputs and specialized glucoamylase enzyme supplies. Single-source vulnerability runs through Ukrainian grain corridors disrupted by geopolitical conflict. Distribution runs through direct mill-to-manufacturer contracting that fragments traditional trader channels, particularly for liquid glucose serving Northern French and Bavarian industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European corn glucose has entered late-cycle quality differentiation, with EFSA clean-label mandates and EMA pharmaceutical standards redirecting procurement toward certified-low-carbon and compendial-grade specifications. This demand shift rewards processors with verified lifecycle emissions documentation and specialized refining capabilities.
For Market Incumbents: Anticipate isomaltulose substitution pressure in sports nutrition and diabetic-friendly segments by accelerating membrane filtration retrofits that halve steam energy consumption. Secure backward integration into Romanian and Hungarian grain origination to defend margin predictability against Ukrainian supply disruptions. Prioritize CSRD carbon accounting certification to capture price premiums from sustainability-scorecard buyers.
For New Entrants and Emerging Players: EU Green Deal industrial decarbonization mandates in Germany and France open a window for specialized toll processors offering F-Gas Regulation-compliant refrigeration infrastructure. Target Poland's underpenetrated pharmaceutical vertical around Warsaw and Łódź, where generic drug manufacturing expansion outpaces local compendial-grade glucose supply. Establish direct partnerships with Dutch bioplastics producers qualifying fermentation feedstock as a differentiated entry angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale refiners lack capital for F-Gas compliance and membrane technology retrofitting. Long-term viability favors processors with captive enzyme engineering capabilities and verified low-carbon supply chains. Watch for inflection signals in German bakery cooperative procurement patterns shifting toward carbon-accounted glucose lots.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | Reduces steam energy consumption by half, aligning with EU Green Deal decarbonization mandates for starch facilities. |
| Backward Integration into Maize Sourcing | Secures supply stability against Romanian and Hungarian yield volatility and Ukrainian corridor disruptions. |
| Pharmaceutical-Grade Certification Investment | Opens premium revenue tiers under EMA compendial standards for parenteral nutrition and tablet excipient applications. |
| CSRD Carbon Accounting Documentation | Enables price differentiation for glucose lots with verified lifecycle emissions under Corporate Sustainability Reporting Directive. |
| Direct Mill-to-Manufacturer Contracting | Bypasses trader intermediaries for Bavarian bakery clusters seeking handling efficiency and supply traceability. |
Research Approach
Bottom-up food and beverage manufacturer modeling reconciled against top-down starch processing capacity tracking forms the analytical core of this study. Primary interviews with plant managers at enzymatic conversion facilities, procurement leads at German bakery cooperatives, pharmaceutical excipient buyers, and Dutch bioplastics fermentation specialists combined with secondary validation from EFSA additive evaluations, EMA compendial standards documentation, EU customs trade data, and SEC filings of listed agribusiness conglomerates.
Historical trendline analysis of enzymetric conversion capacity deployment and clean-label reformulation adoption patterns informed projection frameworks across the analysis window. Segmentation modeling incorporated product type, industry vertical, physical form, and end-user integration depth dimensions. CAGRs derived from volume-weighted capacity expansion schedules and end-use demand elasticity coefficients, with maize input cost volatility and F-Gas Regulation compliance timelines as key forecast inputs.
Revisions become necessary when Ukrainian grain corridor stability, EFSA acceptable daily intake threshold adjustments, or F-Gas Regulation amendment enforcement timelines materialize differently than modeled assumptions anticipate. Forecasts reflect documented assumptions about enzymatic conversion technology diffusion and bakery cluster procurement centralization. A model refresh is warranted upon material change in EU Green Deal industrial decarbonization mandate implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Agave Inulin Market
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market
Ingredients
Sesame Oil Market
Ingredients
India Bakery Ingredients Market
Ingredients
Interesterified CBE Market
Ingredients
Sweet Almond Oil Market
Ingredients
Textured Milk Protein Market
Ingredients
Egg Phosphatidylcholine Market
Ingredients
Stabilized Starch Market
Ingredients
Fish Feed Ingredients Market
Ingredients
Hibiscus Extract Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Rapid-Set Gelatin Market
Ingredients
North America Fats and Oils Market
Ingredients
Potato Fiber Market
Ingredients
Smoked Yeast Market