
 Industrial Networking Solutions Market | 2026-2036
Industrial Networking Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Networking Solutions Market Intelligence
Germany's industrial corridor is fragmenting into competing technology ecosystems as domestic automation vendors and global networking suppliers vie for plant-floor dominance. Cisco Systems leverages its enterprise security stack to anchor industrial edge deployments across European manufacturing. Siemens sustains deep vertical integration from programmable logic controllers through managed Ethernet switches, controlling entire automation architectures. Rockwell Automation specializes in North American factory automation channels, dominating brownfield retrofit opportunities with its Stratix switch portfolio.
Industrial networking solutions encompass hardened communication infrastructure purpose-built for factory floors, process plants, and critical infrastructure, operating across temperature extremes from minus forty to plus seventy-five degrees Celsius with sub-millisecond latency guarantees. Ethernet switches and Time-Sensitive Networking technology together constitute the structural core, with TSN-enabled segments capturing disproportionate engineering attention as deterministic timing becomes essential for motion control and robotics coordination. Wireless access points and 5G industrial radio units represent the fastest-growing technology layer, though margin pools remain thinner due to interoperability certification burdens and site-specific spectrum licensing complexity.
FCC Part 15 rules govern unlicensed industrial radio deployments in the United States, while the EU's Radio Equipment Directive and IEC 62443 cybersecurity standards jointly shape product certification requirements for European market access. Germany's Federal Network Agency enforces additional spectrum coordination protocols for private 5G campus networks, directly influencing vendor product roadmaps and customer procurement specifications. Stakeholders must monitor whether TSN standardization momentum consolidates around IEEE 802.1AS timing profiles or fragments into vendor-specific implementations that lock buyers into single-supplier ecosystems.
Market Dynamics
Time-Sensitive Networking standards are forcing deterministic Ethernet infrastructure into legacy industrial sites, compressing equipment refresh cycles as manufacturers pursue sub-millisecond latency guarantees for motion control applications.
Growth Catalysts
- IEC 62443 cybersecurity frameworks:European manufacturers face mandatory compliance timelines that accelerate replacement of unhardened legacy switches. Automotive OEMs in Germany are retrofitting entire production lines to meet certification requirements.
- Factory automation systems:Real-time operational visibility demands are pulling hardened Ethernet switches into brownfield process plants. Machinery OEMs specify TSN-enabled segments for robotics coordination.
- Private 5G campus networks:Germany's Federal Network Agency spectrum coordination protocols are unlocking wireless access point deployments in automotive assembly halls. Industrial radio units capture engineering attention for mobile asset tracking.
Market Restraints
- Interoperability certification burdens:Wireless technology layers face margin compression from site-specific spectrum licensing complexity. 5G industrial radio units require vendor-specific testing protocols that extend deployment timelines.
- Input cost volatility:Hardened switch manufacturing depends on specialized industrial-grade semiconductors with concentrated foundry capacity. Temperature-rated components for minus forty to plus seventy-five Celsius operation face supply constraints.
- Technical limitation of legacy integration:Deterministic Ethernet deployment encounters proprietary fieldbus protocols in installed base. Brownfield retrofit projects require protocol gateway investments that dilute TSN return calculations.
Strategic Opportunities
- Underpenetrated process industries:Chemical and pharmaceutical plants in Germany lag discrete manufacturing in TSN adoption. Batch process applications present deterministic timing requirements that Ethernet infrastructure can address.
- Technology convergence:Edge computing platforms are merging with managed switch architectures to enable localized analytics. This convergence creates white space for infrastructure vendors offering integrated compute-networking stacks.
- EU Green Deal industrial transition:Energy efficiency mandates are retrofitting plant-floor communication infrastructure as part of broader sustainability investments. TSN-enabled power management features align with carbon reduction targets.
Industry Challenges
- Skill gap in converged IT-OT environments:Plant engineering teams lack expertise in enterprise security stack configuration. Cisco-trained network administrators rarely possess PLC programming experience.
- Capex intensity of infrastructure refresh:Full-scale TSN deployment requires simultaneous switch replacement, cabling verification, and controller firmware updates. Automotive OEMs face multi-year capital allocation cycles.
- Standardization timeline uncertainty:IEEE 802.1AS timing profiles risk fragmentation into vendor-specific implementations. Buyers fear single-supplier ecosystem lock-in from premature technology commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Networking Solutions Market |
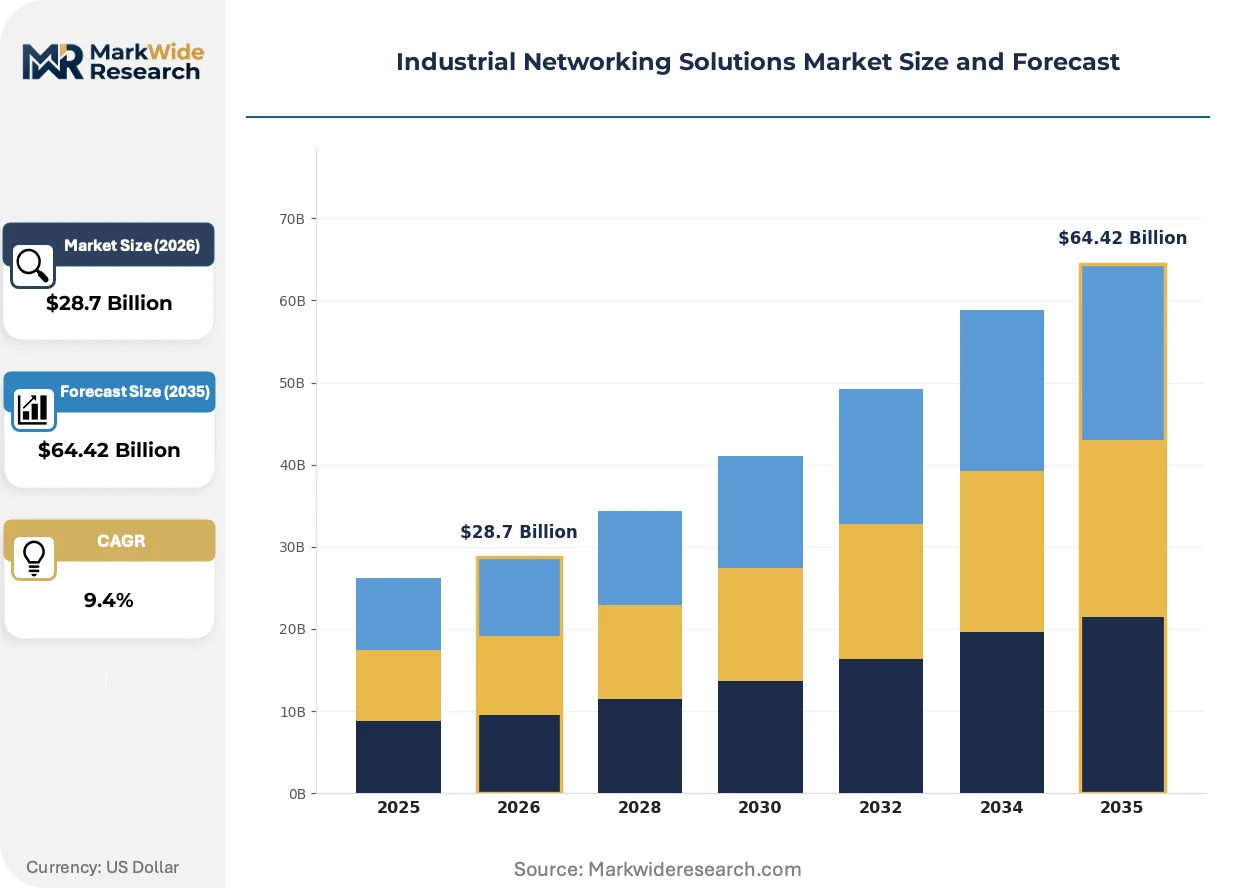
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $64.42 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethernet Switches, Wireless Access Points, Gateways, Media Converters, Network Interface Cards, Network Management Software Technology: Ethernet, Wi-Fi, Bluetooth, Zigbee, 5G, Time-Sensitive Networking Application: Factory Automation, Process Control, Smart Metering, Asset Monitoring, Energy Management, Building Automation End User Industry: Manufacturing Plants, Utilities, Transportation Systems, Oil Refining Facilities, Semiconductor Fabrication, Food Processing Units |
| Companies Covered | Rockwell Automation, Dell Technologies, Cisco Systems, Schneider Electric, Belden, Siemens, Moxa, Huawei Technologies, Juniper Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Networking Solutions Market Strategic Shifts & Innovations
Industrial networking architecture is migrating from hierarchical fieldbus topologies toward flat Ethernet fabrics, compressing the traditional automation pyramid and redistributing intelligence toward the edge.
Ethernet-based motion control is migrating from proprietary drive networks toward TSN-enabled deterministic timing. Automotive assembly robot OEMs specify IEEE 802.1AS profiles for coordinated multi-axis positioning. This migration is compressing the traditional separation between information technology infrastructure and operational technology control layers.
The EU's Radio Equipment Directive is tightening electromagnetic compatibility requirements for industrial wireless equipment. Private 5G campus network deployments face extended certification timelines that delay production line commissioning. German machinery OEMs are pre-certifying radio units to accelerate customer procurement cycles.
Buyers are consolidating vendor relationships around full-stack automation suppliers rather than best-of-breed networking specialists. Procurement teams favor Siemens and Rockwell Automation for integrated PLC-switch-controller bundles. This concentration is most visible in North American automotive tier-one supplier facilities where single-source accountability reduces integration risk.
Industrial Networking Solutions Market Segmentation
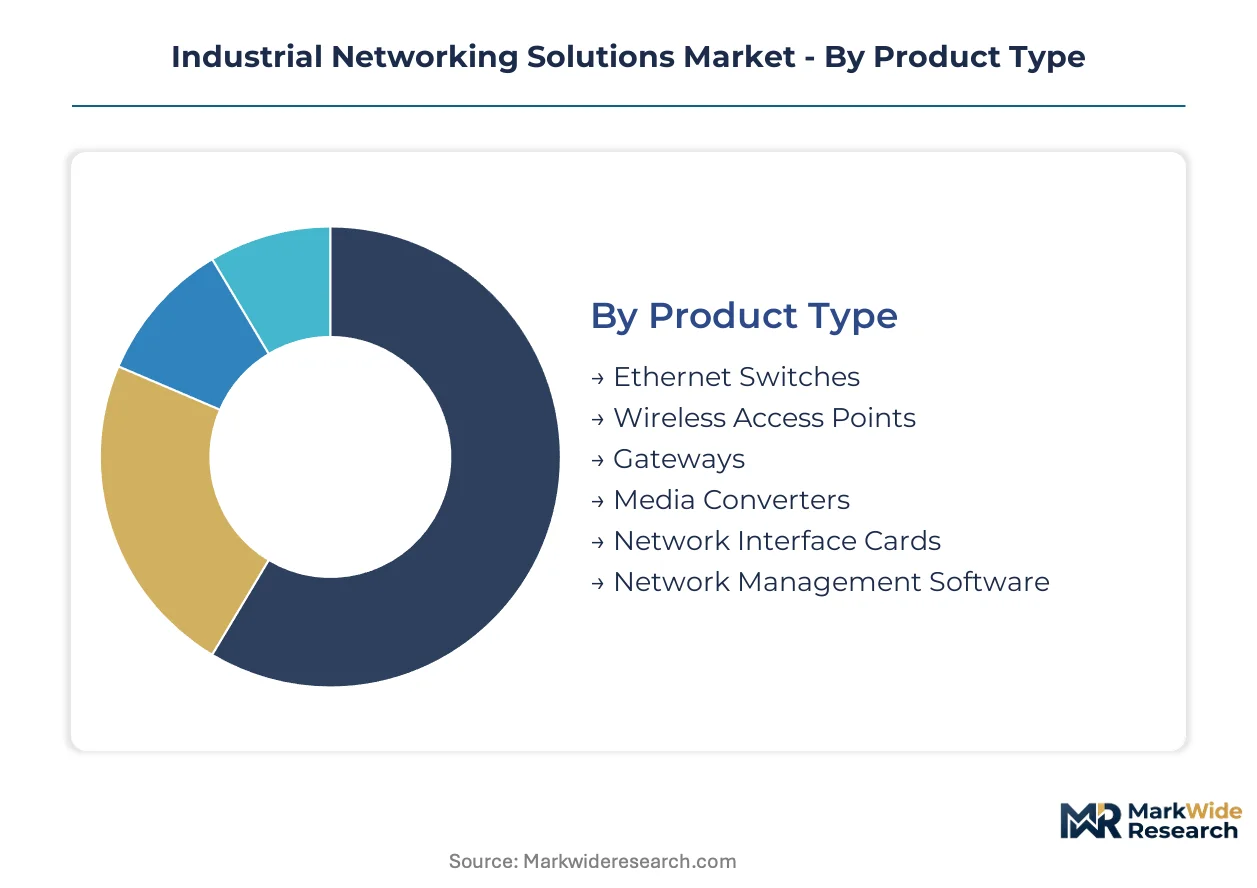
Industrial networking solutions fragment across multiple technical and commercial dimensions, with product architecture and connectivity standards determining deployment economics. Segmentation clarity matters because buyers face incompatible technology stacks and divergent certification requirements across use cases.
Product Type:
Mature switch hardware dominates installed value, while emerging software-defined layers are capturing incremental margin.
- Ethernet Switches:Hardened Layer 2 and Layer 3 devices with industrial temperature ratings from minus forty to plus seventy-five degrees Celsius form the backbone of plant-floor infrastructure. German automotive OEMs specify managed variants with TSN support for robotics coordination, driving premium tier specification.
- Wireless Access Points:Industrial-grade Wi-Fi 6 and Wi-Fi 6E units with IP67 enclosures address mobile asset tracking and AGV fleet management. FCC Part 15 rules in the United States and Germany's Federal Network Agency spectrum protocols create divergent certification burdens that compress margins.
- Gateways:Protocol translation devices bridge deterministic Ethernet to legacy fieldbus networks.
- Media Converters:Fiber-to-copper interfaces extend physical layer reach in electrically noisy environments.
- Network Interface Cards:Embedded communication modules for PLC and controller integration.
- Network Management Software:Centralized configuration and monitoring platforms for multi-site deployments.
Ethernet Switches handle the majority of throughput; Wireless Access Points is the fastest mover on share.
Technology:
Cost tiers separate standardized Ethernet infrastructure from specialized deterministic and wireless alternatives with premium pricing.
- Ethernet:Standard IEEE 802.3 wired connectivity with industrial-grade shielding and M12 connectors constitutes the baseline for factory automation. Manufacturing Plants in Germany retrofit entire production lines with gigabit-capable variants to support edge computing convergence.
- Time-Sensitive Networking:IEEE 802.1AS timing profiles and traffic shaping extensions deliver sub-millisecond latency guarantees for motion control. Machinery OEMs specify TSN-enabled segments for coordinated multi-axis robotics, though standardization fragmentation risks vendor lock-in.
- Wi-Fi:Unlicensed spectrum wireless for non-critical monitoring applications.
- Bluetooth:Short-range connectivity for sensor networks and maintenance tool pairing.
- Zigbee:Low-power mesh networking for battery-operated field devices.
- 5G:Private campus networks with ultra-reliable low-latency communication for mobile equipment.
Ethernet commands the largest installed base; Time-Sensitive Networking is climbing the fastest as deterministic timing becomes essential.
Application:
Volume concentrates in continuous manufacturing environments, while margin pools favor mission-critical control applications with certification requirements.
- Factory Automation:Discrete manufacturing lines with PLC-coordinated material handling and robotic assembly represent the primary demand center. Automotive OEMs in Germany are retrofitting brownfield sites with TSN infrastructure to achieve real-time operational visibility.
- Process Control:Continuous operations in chemical and pharmaceutical plants with batch sequencing and safety instrumented systems. Underpenetrated relative to discrete manufacturing, these applications present deterministic timing requirements that Ethernet infrastructure can address.
- Smart Metering:Utility-scale data collection for grid optimization and demand response.
- Asset Monitoring:Condition-based maintenance sensors for rotating equipment and critical infrastructure.
- Energy Management:Power consumption tracking aligned with EU Green Deal carbon reduction targets.
- Building Automation:HVAC and lighting control integration with industrial facility management systems.
Factory Automation generates the highest absolute volume; Process Control is expanding most quickly as chemical plants modernize.
End User Industry:
Customer type stratification separates capital-intensive continuous processors from discrete manufacturers with shorter replacement cycles.
- Manufacturing Plants:Automotive, machinery, and electronics assembly facilities with high-volume production requirements. German OEMs specify integrated PLC-switch-controller bundles from full-stack automation suppliers to reduce integration risk.
- Semiconductor Fabrication:Cleanroom environments with extreme electromagnetic compatibility and contamination control standards. EU Radio Equipment Directive tightening extends wireless certification timelines, favoring pre-certified vendor relationships.
- Utilities:Electric power generation and distribution with SCADA integration requirements.
- Transportation Systems:Rail signaling and port automation with hardened environmental specifications.
- Oil Refining Facilities:Hazardous area classifications with explosion-proof enclosure requirements.
- Food Processing Units:Washdown-rated equipment with sanitary design compliance.
Manufacturing Plants account for the dominant share of procurement; Semiconductor Fabrication is gaining share fastest on precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardened switch manufacturing clusters in Germany, the United States, and China supply three-quarters of global industrial Ethernet infrastructure. Temperature-rated semiconductor foundries in Taiwan and South Korea feed component demand. Regulatory divergence between FCC Part 15 rules and EU Radio Equipment Directive shapes regional deployment timelines.
Germany
Automotive OEMs in Stuttgart and Munich are retrofitting entire production lines with TSN-enabled infrastructure to achieve real-time operational visibility. The Federal Network Agency enforces spectrum coordination protocols for private 5G campus networks that directly influence vendor product roadmaps. Bavarian machinery OEMs specify integrated PLC-switch-controller bundles from full-stack automation suppliers to reduce integration risk.
United States
Brownfield process plants in Texas and Louisiana are pulling hardened Ethernet switches into legacy facilities for real-time operational visibility. FCC Part 15 rules govern unlicensed industrial radio deployments, creating a regulatory environment distinct from European certification requirements. Detroit automotive tier-one suppliers favor single-source accountability from integrated automation vendors to compress commissioning timelines.
China
Discrete manufacturing corridors in the Yangtze River Delta are deploying gigabit-capable Ethernet variants to support edge computing convergence. MIIT standards and GB certification requirements shape product roadmaps for domestic and export markets. Shenzhen-based electronics assemblers are consolidating vendor relationships around full-stack suppliers to reduce procurement complexity.
Japan
Precision machinery OEMs in Nagoya and Osaka specify TSN-enabled segments for coordinated multi-axis robotics in cleanroom environments. METI industrial policy supports deterministic Ethernet adoption through standardization alignment with IEEE 802.1AS profiles. Kanto region semiconductor fabricators face extended wireless certification timelines under tightening electromagnetic compatibility requirements.
South Korea
Memory chip foundries in Gyeonggi Province are retrofitting plant-floor communication infrastructure to meet energy efficiency mandates aligned with carbon reduction targets. MFDS and KTL certification protocols govern industrial equipment market access with timelines that influence procurement cycles. Busan-Ulsan petrochemical complexes present underpenetrated opportunities for deterministic timing applications in batch process control.
Industrial Networking Solutions Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower scope but targeted expertise. The vendor base separates into three tiers: full-stack automation suppliers controlling entire architectures, enterprise networking incumbents anchoring security-centric edge deployments, and industrial connectivity pure-plays dominating temperature-rated switch hardware. Strategic moves concentrate on backward integration into semiconductor sourcing and geographic expansion through localized certification partnerships.
Within the full-stack automation tier, Rockwell Automation and Siemens exemplify integrated platform positioning, with the former representing North American brownfield retrofit specialization and the latter anchoring European vertical control from programmable logic controllers through managed Ethernet infrastructure. Cisco Systems occupies a distinct position as an enterprise security stack incumbent extending into industrial edge deployments. Among industrial connectivity specialists, Belden and Moxa represent hardened hardware archetypes with concentrated expertise in temperature-extreme operating environments.
| Leading Market Players |
|---|
| Rockwell Automation |
| Dell Technologies |
| Cisco Systems |
| Schneider Electric |
| Belden |
| Siemens |
| Moxa |
| Huawei Technologies |
| Juniper Networks |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Taiwan-based foundries for temperature-rated industrial semiconductors compresses margin flexibility at both premium and economy tiers while forcing buyers into extended order queues. This concentration vector simultaneously widens pricing spreads between TSN-certified managed switches and unmanaged baseline units and locks procurement teams into qualification cycles that span multiple fiscal periods.
Pricing Analysis
IEC 62443 cybersecurity certification dictates the pricing tier structure across European procurement channels, separating pre-certified premium switches from uncertified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects compliance grade, thermal operating range, and after-sales service bundling. Cost compression in the economy tier is intensifying because foundry allocation favors automotive-grade chip volumes. Automotive OEMs in Germany exhibit lowest price sensitivity due to line-stoppage risk, while small machinery builders face acute budget constraints.
Supply Chain Analysis
Extended payment terms from German automotive OEMs cascade through tier-one switch suppliers into semiconductor procurement cycles. Manufacturing concentrates in Germany, the United States, and China for final assembly, with Taiwan and South Korea feeding critical foundry inputs. Hardened switch production draws from specialized industrial-grade FPGAs, M12 copper connectors, and fiber optic transceivers. Single-source vulnerability in temperature-extreme semiconductor packaging creates exposure to foundry allocation shifts. Distribution runs through authorized industrial automation distributors with regional stocking depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial networking solutions are entering a cyclical recovery phase as deferred TSN infrastructure investments from the prior capital allocation freeze release into active procurement. Automotive production resumption in Germany provides the cyclical anchor.
For Market Incumbents: Pre-empt standardization fragmentation by anchoring IEEE 802.1AS profile implementations before vendor-specific lock-in solidifies. Deepen backward integration into industrial-grade semiconductor sourcing to defend margin position against foundry allocation volatility. Prioritize certification pre-qualification with Germany's Federal Network Agency to compress customer deployment timelines.
For New Entrants and Emerging Players: Build out underpenetrated process control applications in German chemical and pharmaceutical plants where TSN adoption lags discrete manufacturing. Target batch process deterministic timing requirements with Ethernet-native solutions that displace legacy fieldbus infrastructure. Pursue channel partnerships with specialized industrial automation distributors rather than direct OEM engagement.
For Investors and Strategic Acquirers: IEC 62443 mandatory compliance timelines reshape the acquisition landscape toward cybersecurity-certified asset bases. Position for five-to-ten year infrastructure refresh duration by targeting industrial connectivity pure-plays with concentrated temperature-rated hardware expertise. Monitor IEEE 802.1AS implementation convergence as the signal for ecosystem consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| TSN Certification Pre-Qualification | Accelerates German automotive OEM procurement cycles by compressing site acceptance testing duration. |
| Backward Integration into Semiconductors | Captures margin pool from Taiwan foundry allocation volatility affecting temperature-rated component supply. |
| Process Industry Application Development | Addresses underpenetrated German chemical plant segment with deterministic Ethernet for batch control. |
| Private 5G Campus Network Partnerships | Aligns with Federal Network Agency spectrum protocols unlocking wireless deployment in automotive assembly. |
| Edge Computing Platform Convergence | Creates white space for integrated compute-networking stacks serving localized analytics demand. |
Research Approach
A spread of perspectives from plant engineering directors, industrial OEM procurement teams, automation system integrators, and hardened switch manufacturing executives converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, EU Radio Equipment Directive certification databases, and customs trade data for industrial networking equipment. Bottom-up demand modeling from end-use application volumes triangulated against top-down market sizing from supplier revenue aggregation.
Demand-supply balance dynamics across product type, technology standard, and end-user industry segmentation anchored the analytical framework over the projection horizon. Modeled dimensions included connectivity protocol, environmental rating tier, and regional regulatory cluster. CAGRs were derived from segment-level volume trajectories and value-per-unit expansion patterns. Forecast inputs incorporated foundry capacity allocation schedules for industrial-grade semiconductors and automotive OEM capital expenditure disclosure trends.
Stress conditions across foundry allocation shocks, IEC 62443 compliance timeline acceleration, and TSN standardization fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding capital availability and regulatory enforcement intensity. Macroeconomic contraction, cybersecurity framework delay, or wireless spectrum policy reversal would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Modular Automation and Services Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
India Warehouse Automation Market
Industrial Automation
Global Smart Warehousing Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
Safety Programmable Controller Market
Industrial Automation
Factory Automation in Japan Market
Industrial Automation
Factory Automation Platform As a Service Market
Industrial Automation
Warehouse Automation Solutions Market
Industrial Automation
Europe ICS Market
Industrial Automation
Japan Factory Automation and Industrial Controls Market
Industrial Automation
SCADA Alarm Management Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Industrial Multiprotocol Gateways Market
Industrial Automation
Palletizing Systems Market
Industrial Automation
Sortation Systems Market