
 Global Smart Warehousing Market | 2026-2036
Global Smart Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Warehousing Market Foresight
The EU Green Deal is consolidating demand for electrified intralogistics and carbon-accountable warehouse operations across European distribution networks. Daifuku leverages its deep manufacturing scale in automated storage and retrieval systems to anchor high-throughput fulfillment contracts in Asia. Honeywell International competes through vertical control over sensors, software, and safety systems that integrate warehouse execution with building management.
Smart warehousing denotes the application of networked sensors, autonomous mobile platforms, and algorithmic orchestration software to coordinate inventory movement, storage density, and labor deployment within distribution and production facilities. Systems typically operate on sub-second response loops where AI-driven warehouse management software directs robotic pickers and conveyor networks to optimize cube utilization and order cycle times. IoT and Artificial Intelligence segments command the deepest margin pools because sensor fusion and predictive analytics command premium pricing and create switching costs. Cloud-Based deployment is expanding fastest among mid-market third-party logistics providers seeking to avoid capital-intensive on-premise infrastructure.
FDA traceability mandates for pharmaceutical distribution, EU F-Gas Regulation limits on warehouse refrigeration systems, and OSHA powered industrial truck standards collectively shape equipment specifications and software validation requirements in regulated storage environments. The EU AI Act adds conformity assessment burdens for automated decision systems that allocate labor or prioritize shipments. Stakeholders must weigh regulatory compliance costs against automation labor savings when evaluating warehouse retrofit timelines.
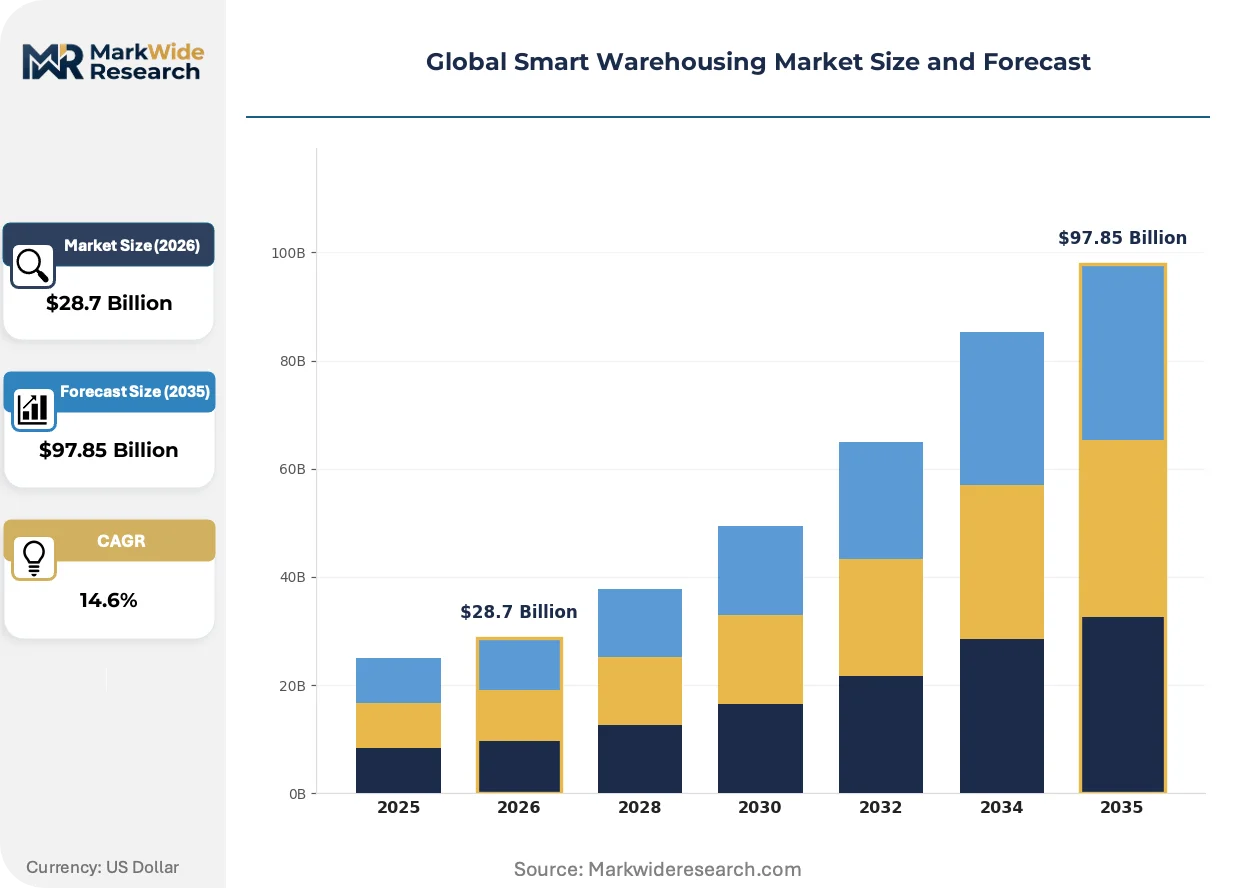
Market Dynamics
E-commerce fulfillment networks are compressing order cycle times from hours to minutes, forcing warehouse operators to retrofit legacy distribution centers with AI-driven orchestration layers that coordinate robotic pickers and autonomous mobile robots in sub-second response loops.
Growth Catalysts
- EU F-Gas Regulation:Mandates to phase down hydrofluorocarbon refrigerants in cold-chain warehouses are accelerating electrification of material handling equipment and driving replacement demand for compliant refrigeration systems across European distribution networks.
- Same-day delivery commitments:Major retailers are contracting automated storage and retrieval systems to compress last-mile staging times, pulling capital into high-throughput fulfillment centers in urban peripheries.
- Pharmaceutical traceability mandates:FDA serialization requirements for drug distribution are forcing warehouse operators to deploy sensor networks and blockchain-enabled track-and-trace systems to maintain compliance.
Market Restraints
- Lithium-ion battery supply concentration:Dependence on East Asian cell manufacturers for electrified forklift fleets creates input cost volatility and geopolitical exposure for European and North American operators.
- EU AI Act conformity assessments:Automated decision systems that allocate labor or prioritize shipments face extended validation timelines, delaying deployment of algorithmic warehouse management software.
- Legacy WMS integration friction:Proprietary data formats in incumbent warehouse management systems obstruct API connectivity with modern orchestration platforms, extending retrofit timelines.
Strategic Opportunities
- India's PLI scheme for logistics:Production-linked incentives for automated material handling equipment create localized manufacturing capacity to serve underpenetrated South Asian fulfillment markets.
- Convergence of digital twin and predictive maintenance:Real-time simulation of warehouse operations combined with sensor-based failure prediction opens subscription revenue models for system integrators.
- OSHA powered industrial truck standards:Updated safety certification requirements for autonomous forklifts create consultancy and retrofit service demand for compliance advisory firms.
Industry Challenges
- Mechatronics talent scarcity:Shortage of technicians qualified to maintain integrated robotic and conveyor systems extends mean time to repair and inflates service contract costs.
- Multi-vendor sensor fusion complexity:Warehouses deploying equipment from competing automation suppliers face interoperability failures that degrade orchestration software performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Warehousing Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $97.85 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, Automated Guided Vehicles, Robotics, Artificial Intelligence End User: E-Commerce, Retail, Manufacturing, Logistics Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution: Warehouse Management System, Inventory Optimization, Order Fulfillment, Data Analytics |
| Companies Covered | Dematic, Daifuku, SSI Schaefer, Körber, Blue Yonder, Honeywell International, IBM, Oracle, Manhattan Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Warehousing Market Shifts & Advancements
Algorithmic orchestration is displacing rule-based warehouse management as the dominant control paradigm, compressing the gap between sensor data and robotic actuation to milliseconds while enabling dynamic reconfiguration of storage density and pick paths.
Swarm robotics for collaborative picking is rewriting fulfillment economics in high-SKU environments. Mid-market third-party logistics providers in Germany and the Netherlands are piloting decentralized robot fleets that self-coordinate through local communication protocols. The technology is compressing labor cost per pick by eliminating centralized traffic management overhead.
The EU AI Act's risk classification framework is forcing warehouse operators to document algorithmic decision logic for labor allocation systems. Automated shift scheduling and performance scoring algorithms now face conformity assessment burdens in France and Germany. Cold-chain pharmaceutical distributors are responding by segregating AI-driven and human-supervised workflows to limit regulatory exposure.
Subscription-based robotics procurement is displacing capital purchase models among North American e-commerce fulfillment networks. Third-party logistics providers in California and Texas are contracting autonomous mobile robot fleets through per-pick pricing arrangements rather than owning equipment. The shift transfers obsolescence risk to OEMs while aligning vendor incentives with throughput outcomes.
Global Smart Warehousing Market Segmentation
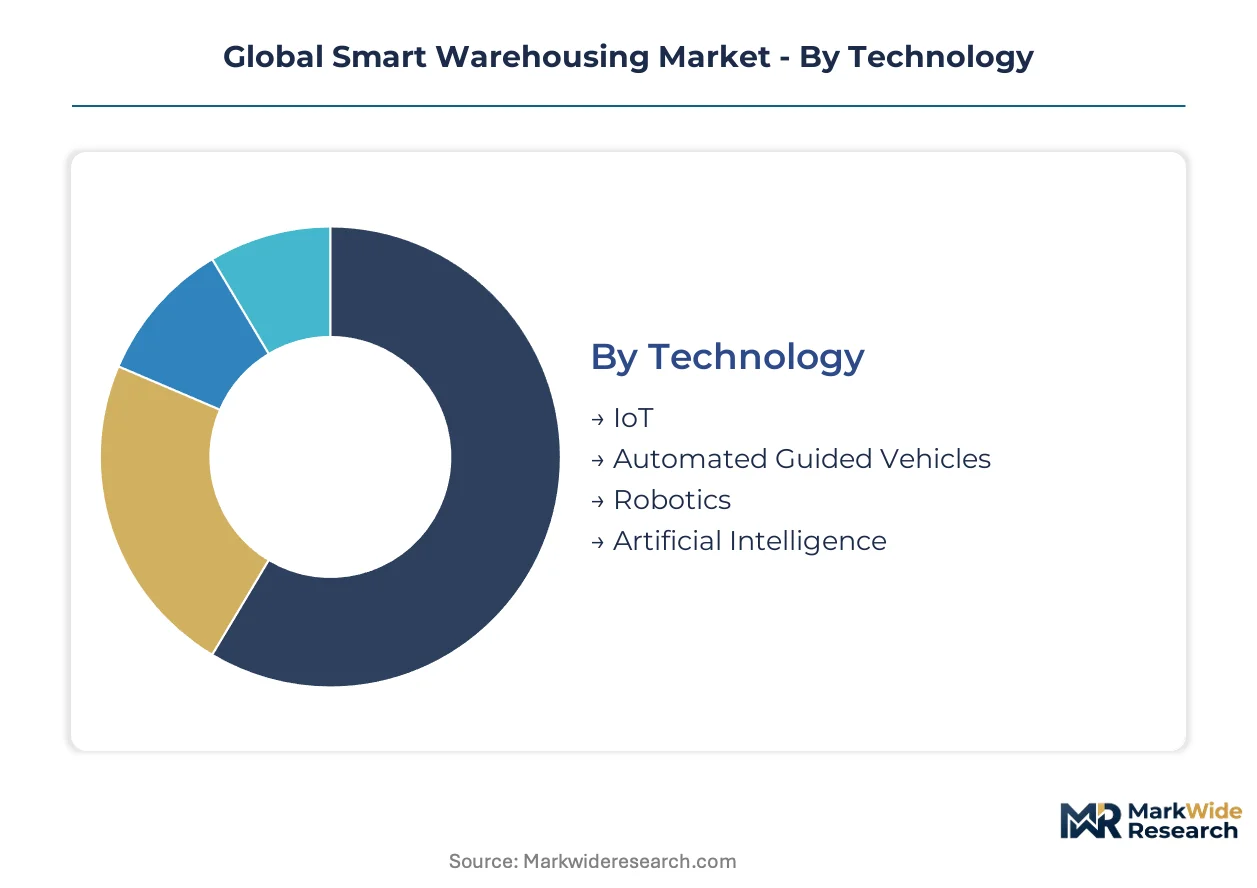
Smart warehousing technology stacks fragment across control layers, physical automation, and decision intelligence. Procurement patterns diverge sharply between capital-intensive on-premise deployments favored by large retailers and subscription-based cloud models gaining traction among third-party logistics providers.
Technology:
IoT and Artificial Intelligence command premium pricing and create switching costs, while Automated Guided Vehicles and Robotics compete on throughput economics.
- IoT:Sensor networks fuse temperature, vibration, and location data into unified telemetry streams. Cold-chain pharmaceutical distributors in Germany and the Netherlands deploy dense IoT mesh layers to satisfy EMA traceability mandates and EU F-Gas refrigeration compliance.
- Artificial Intelligence:Machine learning models optimize pick-paths, predict demand spikes, and dynamically rebalance labor across zones. The EU AI Act's conformity assessment requirements are extending validation timelines for algorithmic warehouse management software in France and Germany.
- Automated Guided Vehicles:Wire-guided and laser-navigated transport platforms move pallet loads along fixed routes. Manufacturing clusters around Stuttgart retrofit legacy facilities with AGV lanes to reduce forklift traffic congestion.
- Robotics:Articulated arms and collaborative cobots execute piece-picking in high-SKU environments. E-commerce fulfillment centers in California and Texas pilot swarm-based decentralized fleets to eliminate centralized traffic management overhead.
Today's leader: IoT. Tomorrow's challenger: Artificial Intelligence.
End User:
E-Commerce drives volume deployment, while Retail and Manufacturing concentrate spending on retrofit integration with legacy enterprise resource planning systems.
- E-Commerce:Same-day delivery commitments compress order cycle times from hours to minutes, forcing investment in automated storage and retrieval systems. Urban periphery fulfillment centers in Hamburg and Dallas anchor high-throughput contract wins.
- Retail:Omnichannel inventory unification requires real-time visibility across store networks and distribution nodes. European retailers face EU Green Deal pressure to electrify material handling fleets and cut warehouse carbon intensity.
- Manufacturing:Just-in-sequence parts delivery to assembly lines demands sub-minute retrieval precision. Automotive suppliers around Stuttgart deploy AI-driven orchestration layers to coordinate robotic pickers with production schedules.
- Logistics:Third-party providers seek flexible automation that scales with seasonal volume swings. India's PLI scheme for logistics equipment creates localized manufacturing capacity to serve underpenetrated South Asian markets.
E-Commerce dominates current procurement volumes. Manufacturing presents the steepest expansion trajectory as reshoring accelerates.
Deployment:
Cloud-Based models expand fastest among mid-market operators avoiding capital-intensive infrastructure, while Edge Computing addresses latency-critical robotics coordination.
- Cloud-Based:Warehouse management software delivered via subscription eliminates on-premise server maintenance. North American third-party logistics providers in Texas and California lead migration away from owned infrastructure.
- Edge Computing:Localized processing enables millisecond-response robot coordination without cloud latency. Swarm robotics pilots in the Netherlands rely on edge nodes for decentralized fleet communication.
- On-Premise:Dedicated hardware stacks retain sensitive pharmaceutical and defense inventory data within facility perimeters. FDA serialization requirements drive on-premise blockchain track-and-trace deployments for drug distributors.
- Hybrid:Split architectures run core warehouse management in-cloud while reserving edge nodes for robotics control. German industrial clusters favor hybrid models to balance EU GDPR data residency rules with real-time automation needs.
Cloud-Based deployment is gaining share fastest. Edge Computing emerges as the critical enabler for next-generation swarm robotics.
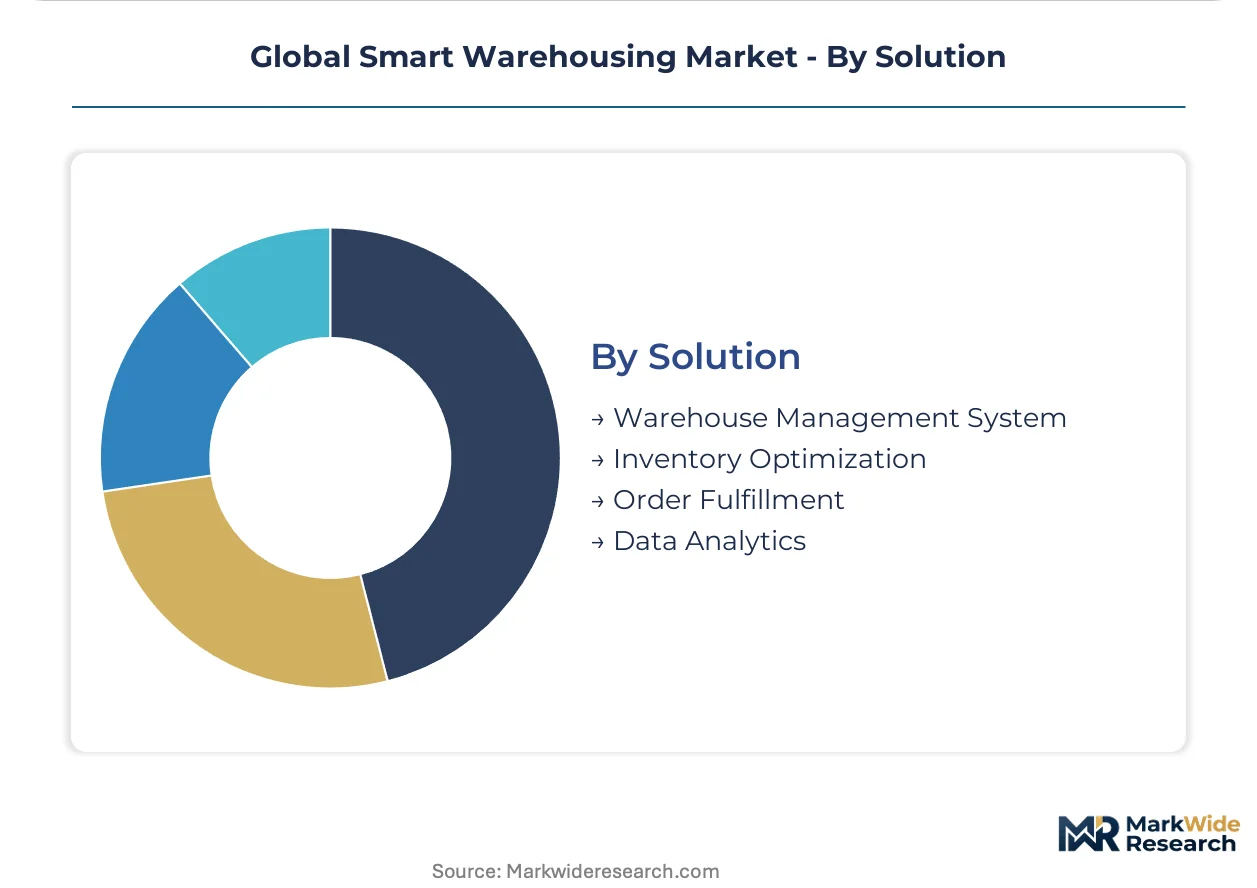
Solution:
Warehouse Management System anchors software spending, while Data Analytics commands expanding share as predictive maintenance and digital twin simulations mature.
- Warehouse Management System:Core software orchestrates inventory location, labor allocation, and order wave planning. Legacy WMS integration friction with modern API-first platforms extends retrofit timelines for European distribution networks.
- Data Analytics:Predictive models forecast equipment failure, optimize storage density, and simulate operational scenarios. The convergence of digital twin and predictive maintenance opens subscription revenue models for system integrators.
- Inventory Optimization:Algorithms balance stock levels against service-level commitments and carrying costs. Pharmaceutical distributors deploy sensor-fusion analytics to maintain FDA traceability compliance across cold-chain nodes.
- Order Fulfillment:Execution modules coordinate picking, packing, and shipping workflows. Same-day delivery promises from major retailers pull capital into last-mile staging automation in urban peripheries.
Warehouse Management System holds current revenue concentration. Data Analytics represents the fastest-climbing margin pool as outcome-based contracting spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized mechatronics technicians and automation engineers cluster in Germany's industrial heartland, California's technology corridors, and China's manufacturing zones, anchoring smart warehousing deployment capacity across three continents.
Germany
Automotive suppliers and pharmaceutical distributors drive retrofit demand around Stuttgart and Hamburg. The EU F-Gas Regulation accelerates electrification of material handling fleets and compliant refrigeration system replacements. Industrial clusters in Baden-Württemberg deploy AI-driven orchestration layers to coordinate robotic pickers with just-in-sequence production schedules.
United States
E-commerce fulfillment networks compress order cycle times from hours to minutes across Texas and California distribution hubs. OSHA powered industrial truck standards shape safety certification requirements for autonomous forklift deployments. Third-party logistics providers in Dallas and Los Angeles pilot subscription-based robotics procurement through per-pick pricing arrangements.
China
Domestic e-commerce platforms and cross-border fulfillment operators expand automated storage and retrieval system capacity in the Yangtze River Delta. Dual carbon goals pressure warehouse operators to electrify intralogistics equipment and reduce facility emissions. Manufacturing clusters around Shanghai retrofit legacy distribution centers with sensor networks and algorithmic warehouse management software.
India
Third-party logistics providers and e-commerce platforms seek scalable automation solutions across Maharashtra and Karnataka. The PLI scheme for logistics equipment creates localized manufacturing capacity for automated material handling systems. Industrial corridors around Mumbai and Bengaluru attract system integrators establishing regional service networks for underpenetrated South Asian fulfillment markets.
Netherlands
Cold-chain pharmaceutical distributors and omnichannel retailers deploy dense IoT mesh layers to satisfy EMA traceability mandates. EU AI Act conformity assessment requirements extend validation timelines for algorithmic labor allocation systems. Logistics hubs around Rotterdam pilot swarm robotics fleets that self-coordinate through decentralized edge computing protocols.
Global Smart Warehousing Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the smart warehousing technology stack. The vendor base separates between integrated automation hardware fabricators and software-centric orchestration platform developers. Three archetypes dominate: full-stack system integrators controlling physical and digital layers, pure-play software vendors licensing warehouse management platforms, and component specialists supplying sensors or robotic subsystems. Competitive positioning sharpens through strategic partnerships bridging hardware-software gaps and geographic expansion into underpenetrated fulfillment markets.
Within the full-stack integration tier, Dematic and Daifuku represent capital-intensive automation fabricators with deep manufacturing scale in automated storage and retrieval systems. SSI Schaefer anchors European system integration capability. Among software-centric vendors, Blue Yonder occupies a position exemplifying cloud-native warehouse management platforms, while Manhattan Associates sits within the tier of execution software specialists. Honeywell International exemplifies industrial conglomerates leveraging vertical control over sensors, safety systems, and building management integration. Körber represents European-based automation specialists competing through modular system architectures.
| Leading Market Players |
|---|
| Dematic |
| Daifuku |
| SSI Schaefer |
| Körber |
| Blue Yonder |
| Honeywell International |
| IBM |
| Oracle |
| Manhattan Associates |
| Others |
Supply & Pricing Matrix
Third-party logistics providers concentrated in Texas and California anchor demand for subscription-based robotics procurement, compressing capital expenditure into per-pick operating models that transfer obsolescence risk to OEMs.
Pricing Analysis
Per-pick subscription pricing dominates high-throughput fulfillment contracts, separating premium-tier AI-orchestrated systems from standard AGV lanes and economy-grade conveyor retrofits. Price differentiation rests on sensor density and EU AI Act compliance certification levels. Margins are tightening due to lithium-ion battery supply concentration in East Asian cell manufacturers. Mid-market third-party logistics providers exhibit highest price sensitivity, while pharmaceutical distributors prioritize traceability compliance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for automated storage and retrieval systems, while system integrators serve retrofit markets through modular component sourcing. Manufacturing concentrates in Germany, China, and Japan for precision mechatronics and control systems. Supply chains draw from East Asian lithium-ion cell production, German sensor fabrication, and Chinese steel framing. Single-source vulnerability in battery chemistry feedstocks creates geopolitical exposure for European and North American operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart warehousing margins are expanding through software-defined orchestration layers that capture recurring revenue while hardware commoditizes, with AI-driven warehouse management systems commanding premium pricing against capital-intensive automation.
For Market Incumbents: Extend software-centric revenue models through outcome-based contracting that aligns vendor incentives with throughput outcomes. Deepen backward integration into sensor hardware to defend margin position against pure-play orchestration platforms. Invest in EU AI Act conformity assessment capabilities ahead of extended validation timelines in France and Germany. For New Entrants and Emerging Players: Enter via India's PLI scheme for logistics equipment to establish localized manufacturing capacity serving underpenetrated South Asian fulfillment markets. Target mid-market third-party logistics providers in Maharashtra and Karnataka with cloud-native warehouse management platforms that eliminate on-premise infrastructure burdens. Lead with swarm robotics pilots demonstrating decentralized fleet coordination without centralized traffic management overhead. For Investors and Strategic Acquirers: Industrial conglomerates with vertical control over sensors and safety systems are the most active acquirer in this space, consolidating orchestration software capabilities to bridge hardware-software gaps. Long-term viability favors platform vendors with switching-cost moats in AI-driven labor allocation and predictive maintenance analytics. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for electrified material handling equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Hardware | Captures margin pools in IoT telemetry layers demanded by FDA pharmaceutical traceability mandates. |
| Cloud-Native Platform Launch | Eliminates on-premise infrastructure barriers for mid-market third-party logistics providers in Texas and California. |
| EU AI Act Conformity Investment | Accelerates deployment timelines for algorithmic labor allocation systems in German industrial clusters. |
| Swarm Robotics Fleet Pilot | Demonstrates decentralized coordination eliminating centralized traffic management overhead in Netherlands logistics hubs. |
| India PLI Manufacturing Scale-Up | Creates localized capacity to serve underpenetrated South Asian fulfillment markets around Mumbai and Bengaluru. |
Research Methodology
Multiple input streams — executive interviews with warehouse operations directors, procurement leads at third-party logistics providers, system integrator technical directors, and automation OEM product managers — were reconciled against secondary sources including SEC filings, customs trade records, and EU regulatory compliance databases. Bottom-up equipment shipment tallies and top-down fulfillment center capex disclosures were triangulated to anchor market sizing.
Data-stream reconciliation across technology deployment models, end-use verticals, and geographic adoption patterns structured the analytical framework over the projection horizon. Segmentation dimensions modeled include physical automation tier, software control layer, deployment architecture, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and fulfillment center buildout pipelines, with specific inputs from e-commerce same-day delivery commitment timelines and pharmaceutical serialization mandate compliance deadlines.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time warehouse automation deployment data introduce uncertainty bands around short-term adoption velocity. Forecasts reflect assumptions regarding lithium-ion battery supply stability and EU AI Act enforcement consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Europe Intralogistics Automation Market
Industrial Automation
Industrial Data Loggers Market
Industrial Automation
North America Industrial Automation Market
Industrial Automation
Robot Gearboxes Market
Industrial Automation
Europe Industrial Automation Software Market
Industrial Automation
Industrial Automation Spares Market
Industrial Automation
Asia-Pacific Smart Manufacturing Market
Industrial Automation
Global Intelligent Completion Market
Industrial Automation
Asia Pacific Warehouse Automation Market
Industrial Automation
Asia Pacific Sortation Systems Market
Industrial Automation
Global Operational Technology Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
Intralogistics Market
Industrial Automation
SCADA Alarm Management Market
Industrial Automation
Hardware in the Loop Market