
 Global Blasting Automation Services Market | 2026-2036
Global Blasting Automation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blasting Automation Services Market Intelligence
Software-as-a-Service (SaaS) models for process optimization and remote monitoring are realigning how blasting automation services are procured and delivered. This shift favors technology providers like ABB, which leverages its extensive industrial automation portfolio. Rockwell Automation competes through its integrated control systems and software platforms. Meanwhile, Epiroc specializes in equipment and services tailored for mining and infrastructure applications.
Blasting automation services involve the deployment of robotic arms and automated systems to propel abrasive media for surface treatment. These services provide precise control over parameters like nozzle pressure, standoff distance, and abrasive flow rate, ensuring repeatable quality. Robotic blasting represents the fastest-growing service type, displacing manual methods in high-value applications. Within end-user segments, aerospace assemblers and defense contractors command premium pricing for services focused on surface preparation and paint stripping.
Worker safety regulations, including permissible exposure limits for airborne particulates set by bodies like the US Occupational Safety and Health Administration (OSHA), drive adoption of contained, automated systems. In Europe, equipment must comply with CE marking provisions under the Machinery Directive, which governs the safety of automated industrial machinery. A key strategic decision for end-users will be choosing between capital investment in in-house automated cells versus outsourcing through contract-based service models.
Market Dynamics
The convergence of industrial robotics with AI-powered machine vision is the central force shaping the blasting automation services market. This integration moves the industry beyond simple repetitive automation toward intelligent systems capable of real-time process optimization and quality control.
Growth Catalysts
- Precision in Aerospace Manufacturing:Demand from aerospace assemblers for flawless surface preparation prior to bonding and coating drives adoption of robotic systems. AI-powered vision guidance ensures consistent standoff distances and angles, which is critical for components used in aircraft.
- Worker Safety Regulations:Mandates from bodies like the US Occupational Safety and Health Administration (OSHA) concerning permissible exposure limits for airborne particulates, such as crystalline silica, compel firms to adopt contained automated blasting cells, reducing human exposure.
- Advanced Manufacturing Requirements:Industrial clusters in Germany and the United States require the repeatable quality and process documentation that automated systems provide. This is especially true for high-value sectors like medical device manufacturing and automotive component production.
Market Restraints
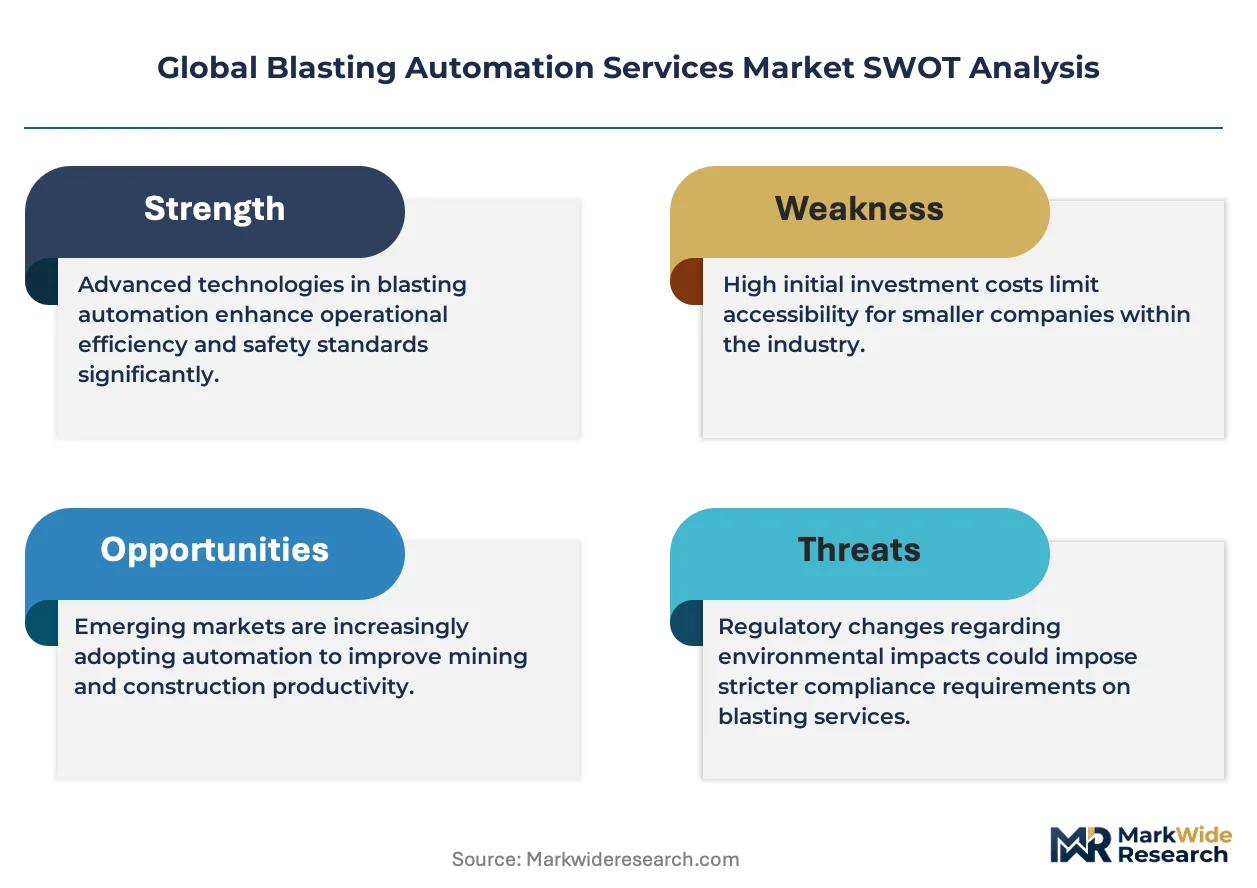
- High Initial Capital Outlay:The significant upfront investment required for robotic arms, customized blasting enclosures, and sophisticated control systems presents a substantial barrier to entry for small and medium-sized enterprises.
- Programming for Complex Geometries:Automated systems face limitations when dealing with highly irregular, non-repeating parts. The complex programming and calibration required for such tasks can negate the efficiency gains over skilled manual blasting.
- Specialized Integrator Dependency:The market relies on a concentrated group of system integrators with expertise in both robotics and abrasive blasting physics. This dependency can lead to long lead times and limited service provider options for end-users.
Strategic Opportunities
- Digital Twin Integration:Combining digital twin technology with blasting automation allows for virtual simulation and optimization of blasting parameters. This approach can drastically reduce physical trial-and-error, saving time and expensive abrasive media.
- Services for Renewable Energy:The maintenance of large-scale infrastructure, such as preparing wind turbine blades for recoating, offers a significant new application area for mobile and containerized automated blasting services.
- Remote Monitoring via SaaS:Offering Software-as-a-Service platforms for remote monitoring, diagnostics, and process optimization creates a recurring revenue stream and lowers the adoption barrier for customers hesitant about managing complex software.
Industry Challenges
- Skilled Technician Scarcity:A persistent shortage of technicians who possess dual expertise in robotics programming and the nuances of surface preparation science creates an operational bottleneck for service providers and end-users alike.
- Legacy System Integration:Integrating modern automated blasting cells with older, pre-existing factory floor enterprise resource planning (ERP) and material handling systems is a significant technical and financial challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blasting Automation Services Market |
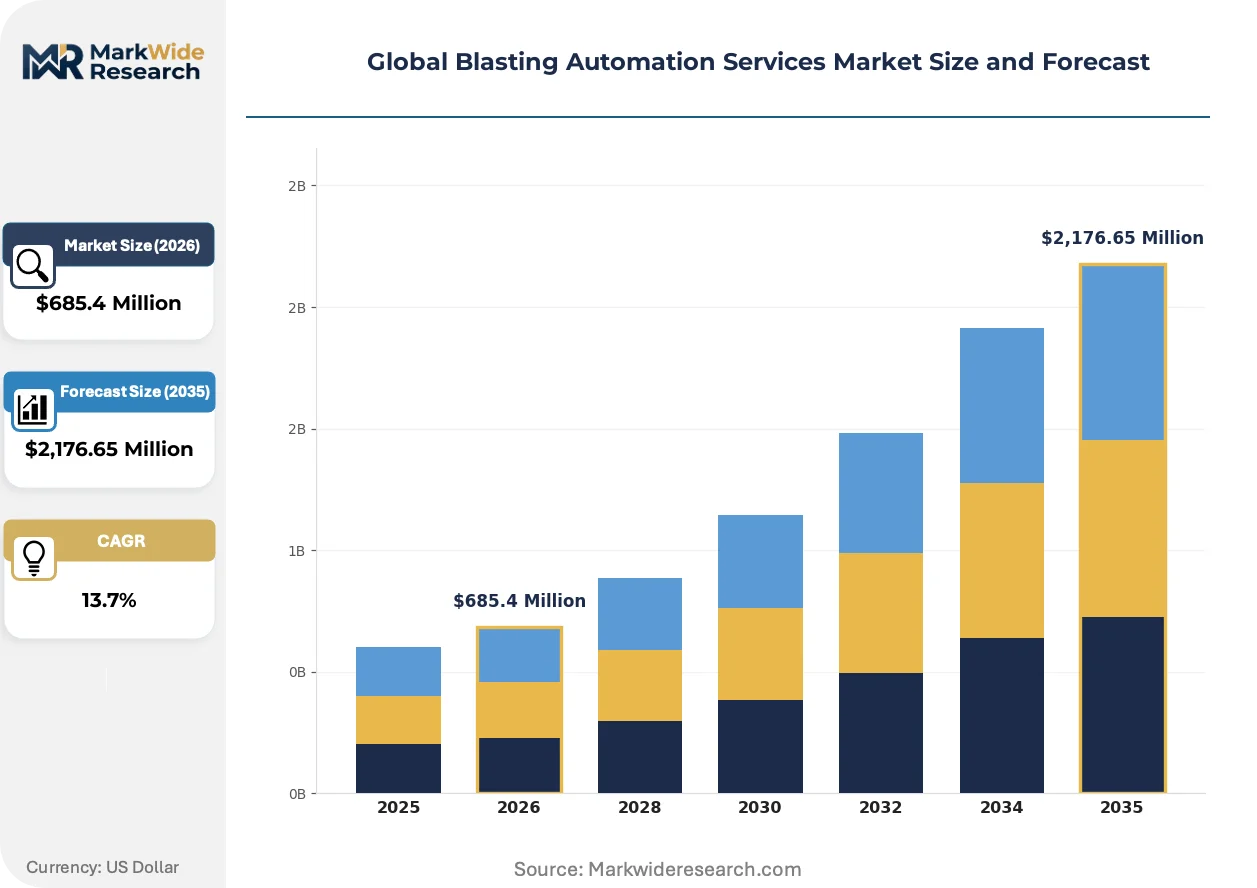
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,176.65 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Robotic Blasting, Abrasive Blasting, Vapor Blasting, Wheel Blasting, Shot Blasting, Dust-free Blasting Application: Surface Preparation, Corrosion Removal, Paint Stripping, Deburring, Cleaning, Polishing End User: Shipbuilding, Aerospace Assemblers, Metal Fabricators, Construction Firms, Machinery Manufacturers, Defense Contractors Deployment Model: On-site Services, Remote Monitoring, Integrated Automation, Mobile Units, Fixed Plant Installation, Contract-based |
| Companies Covered | iRing Inc., Komatsu, ABB, Autonomous Solutions Inc., Rockwell Automation, Dyno Nobel, Orica Limited, Modular Mining Systems, Epiroc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blasting Automation Services Market Strategic Shifts & Innovations
Intelligent automation is transforming service delivery from a labor-replacement function into a data-driven process control discipline. The focus is shifting toward systems that not only execute tasks but also sense, adapt, and document the entire surface treatment workflow for quality assurance.
Closed-loop control systems use integrated sensors to provide real-time feedback on process variables like surface roughness or coating removal. Aerospace and defense contractors are primary adopters, using this capability to meet stringent military and FAA specifications. This sensor-driven automation is expanding into adjacent quality control functions, creating a fully documented and validated surface treatment cycle within a single work cell.
The European Union's Machinery Directive imposes rigorous safety, design, and risk assessment standards, requiring CE marking for automated equipment. This regulation compels system integrators to build in comprehensive safety features such as light curtains, interlocked access doors, and robust dust collection systems. Compliance is particularly critical for service providers targeting Germany's advanced automotive and machine tool industries.
A shift from capital equipment purchases to contract-based service models is gaining momentum among industrial end-users. This approach allows companies to leverage advanced automation for surface treatment without incurring the large upfront investment and maintenance overhead of owning the equipment. The trend is most visible within the contract manufacturing sector in the United States, where operational flexibility is paramount.
Global Blasting Automation Services Market Segmentation
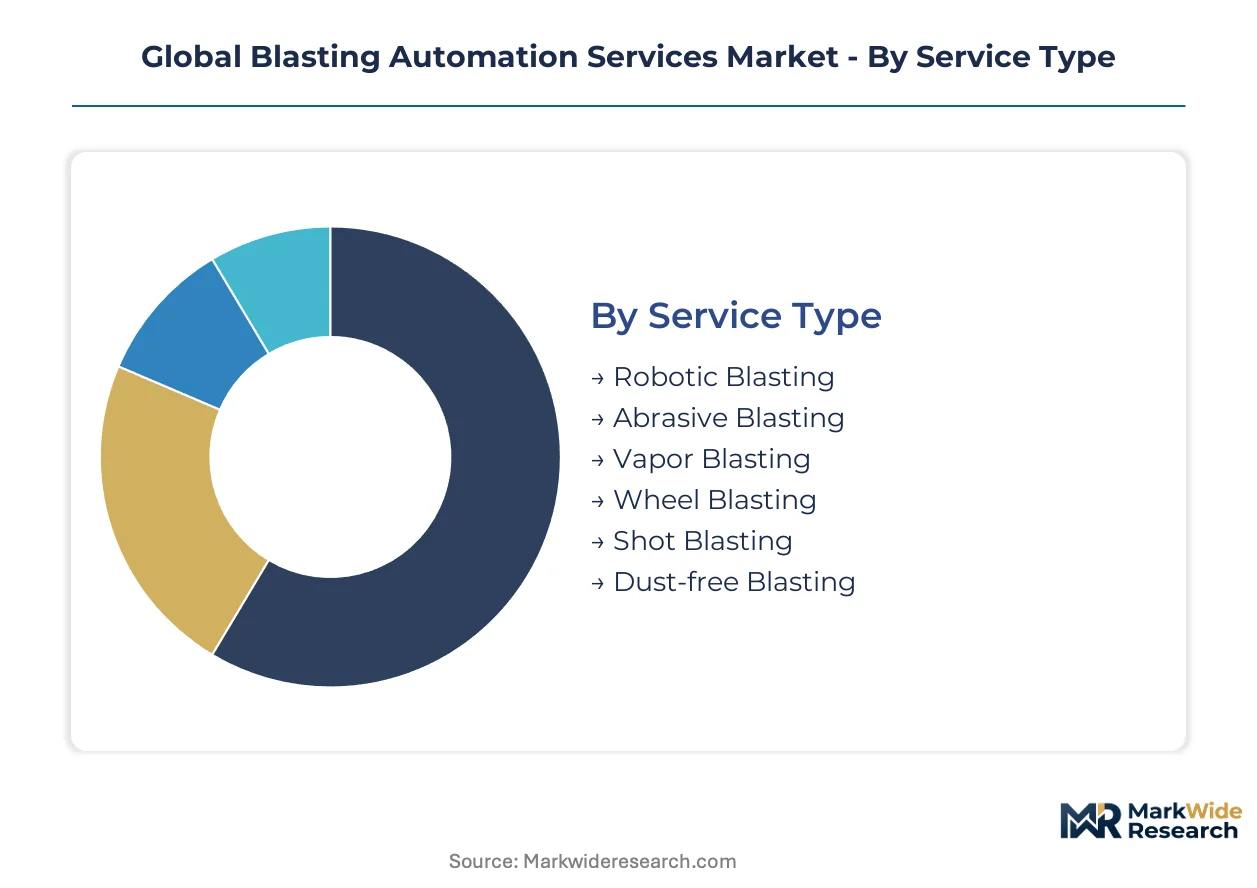
The Global Blasting Automation Services Market segmentation reveals distinct operational preferences and technological requirements across various industrial applications. Understanding these categories is critical for service providers to tailor offerings, address specific pain points, and optimize resource allocation within a diverse customer base.
Service Type:
Buyers in this category differentiate based on the abrasive media used and the method of propulsion, directly impacting surface finish and material removal rates.
- Robotic Blasting:This service type utilizes automated robotic arms to precisely control abrasive media delivery, ensuring consistent standoff distances and angles. Demand from aerospace assemblers in the United States drives its adoption for critical surface preparation tasks.
- Abrasive Blasting:This foundational method employs various abrasive media propelled by compressed air or centrifugal force for surface cleaning and preparation. Industrial clusters in Germany heavily utilize abrasive blasting for general metal fabrication.
- Vapor Blasting:Combining abrasive media with water, this technique reduces dust and heat generation, making it suitable for delicate surfaces. Automotive component manufacturers in Japan employ vapor blasting for precision cleaning.
- Wheel Blasting:This high-volume method uses a rotating wheel to centrifugally propel abrasive media, commonly found in large-scale foundries. Heavy machinery producers in China use wheel blasting for component descaling.
- Shot Blasting:Utilizing spherical metallic shot, this process imparts compressive stress to surfaces, enhancing fatigue life and strength. Shipbuilding yards in South Korea rely on shot blasting for hull preparation.
- Dust-free Blasting:These contained systems minimize airborne particulates, meeting stringent worker safety regulations set by OSHA in the United States. Medical device manufacturers adopt dust-free solutions for cleanroom environments.
Volume sits with Abrasive Blasting; growth tilts toward Robotic Blasting.
Application:
Customer requirements for finished product quality determine the selection within this category, influencing process parameters and abrasive media choice.
- Surface Preparation:This application involves cleaning, roughening, or profiling a surface to improve adhesion for coatings or bonding. Aerospace assemblers demand precise surface preparation for aircraft components in France.
- Corrosion Removal:Blasting services effectively strip away rust, scale, and other corrosive layers from metal substrates to restore integrity. Infrastructure maintenance firms in Canada utilize corrosion removal for bridge structures.
- Paint Stripping:This process removes old paint or coatings without damaging the underlying material, often required for refurbishment or repainting. Defense contractors in the United Kingdom employ paint stripping for military vehicles.
- Deburring:Blasting removes sharp edges or burrs left after manufacturing processes, improving part safety and functionality. Medical device manufacturers in Switzerland use deburring for surgical instruments.
- Cleaning:This application focuses on removing dirt, grime, and contaminants from various surfaces, often as a pre-treatment step. Automotive factories in Mexico use cleaning services for engine blocks.
- Polishing:Fine abrasive media are used to achieve a smooth, reflective finish on components, enhancing aesthetic appeal or reducing friction. Luxury goods producers in Italy employ polishing for metal parts.
Demand for Surface Preparation drives market expansion, while Paint Stripping shows significant potential.
End User:
The operational scale and regulatory environment of end-users dictate their service type preferences, often influencing the level of automation required.
- Shipbuilding:Large-scale surface treatment of hulls and components for new construction and maintenance defines this segment. Shipbuilding companies in Japan use automated blasting for vessel preparation.
- Aerospace Assemblers:This segment requires extremely high precision and repeatability for surface preparation of critical aircraft parts. Aerospace assemblers in the United States command premium services for bonding surfaces.
- Metal Fabricators:General metalworking operations, including cleaning, deburring, and surface finishing, characterize this broad segment. Metal fabricators in Germany integrate blasting services for component finishing.
- Construction Firms:Surface treatment for concrete, steel structures, and equipment maintenance falls under this segment. Construction firms in Australia utilize mobile blasting units for site work.
- Machinery Manufacturers:Preparation of machine components for painting, coating, or assembly is crucial for this segment. Machinery manufacturers in Sweden adopt automated blasting for quality control.
- Defense Contractors:Stringent specifications for surface integrity and paint removal on military equipment define this segment. Defense contractors in Israel require specialized blasting for vehicle refurbishment.
High-value applications characterize Aerospace Assemblers, with Defense Contractors expanding their share.
Deployment Model:
Strategic decisions regarding capital investment versus operational expenditure shape choices in this category, impacting flexibility and long-term cost structures.
- On-site Services:Service providers deploy equipment and personnel directly at the customer's facility, offering convenience for large or immovable assets. Construction firms in the United Kingdom frequently use on-site blasting services.
- Remote Monitoring:This model involves real-time data collection and analysis from automated blasting systems, enabling off-site oversight and process optimization. Technology providers like ABB offer remote monitoring for industrial clients.
- Integrated Automation:Blasting cells are fully integrated into a broader manufacturing line, often with AI-powered vision systems for seamless operation. Advanced manufacturing facilities in Germany prioritize integrated automation.
- Mobile Units:Containerized or trailer-mounted blasting systems offer portability for various locations or temporary projects. Infrastructure maintenance companies in Canada deploy mobile units for remote sites.
- Fixed Plant Installation:Dedicated blasting facilities are permanently installed at a customer's location for consistent, high-volume operations. Large metal fabricators in the United States often invest in fixed plant installations.
- Contract-based:Customers outsource blasting needs to service providers, paying for outcomes rather than owning equipment. Contract manufacturers in Mexico increasingly opt for contract-based blasting services.
Flexibility and reduced upfront costs define the appeal of Contract-based services, while Integrated Automation offers advanced process control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global blasting automation services market exhibits a clear divide, with certain regions driving consumption due to advanced manufacturing needs while others focus on service provision. This dynamic shapes investment and technological adoption patterns worldwide. Regional nuances in regulatory environments and industrial concentration further influence market development.
United States
Demand from aerospace assemblers for critical surface preparation and defense contractors for military equipment refurbishment drives service adoption. Worker safety regulations from the US Occupational Safety and Health Administration (OSHA) compel firms to invest in automated, contained blasting systems. Industrial clusters in states like Washington and California see high utilization of robotic blasting for precision components.
Germany
Advanced manufacturing requirements in the automotive and machine tool industries necessitate repeatable quality and process documentation. Equipment must comply with CE marking provisions under the European Union's Machinery Directive, ensuring safety for automated industrial machinery. Industrial regions like Bavaria and North Rhine-Westphalia integrate automated blasting into sophisticated production lines.
China
Heavy machinery producers and large-scale foundries utilize blasting services for component descaling and surface preparation. Stringent GB standards for industrial equipment safety and environmental protection are becoming more influential. Major industrial hubs, including the Yangtze River Delta, increasingly adopt wheel blasting for high-volume applications.
France
Aerospace assemblers demand precise surface preparation for aircraft components, requiring advanced blasting automation. National policies supporting industrial modernization and safety standards for manufacturing processes encourage investment in automated solutions. The Toulouse region, a major aerospace hub, concentrates demand for high-precision surface treatment services.
Australia
Construction firms and mining operations utilize mobile and containerized blasting units for infrastructure maintenance and equipment preparation. National safety standards and environmental regulations, particularly concerning dust control, influence service delivery. Western Australia's mining sector frequently employs on-site blasting services for heavy equipment refurbishment.
Global Blasting Automation Services Market Key Industry Players
Top-tier vendors anchor the integrated automation segment, while specialized equipment providers and regional service integrators cater to niche applications. The market structure is moderately fragmented, reflecting a blend of large industrial conglomerates and focused technology firms. Strategic archetypes include industrial automation specialists, blasting equipment manufacturers, and contract service providers. Portfolio diversification and strategic partnerships represent dominant competitive moves among market participants.
Industrial automation specialists like ABB and Rockwell Automation exemplify the trend towards integrated control systems and remote monitoring solutions within the market. These companies leverage their extensive industrial automation portfolios to offer comprehensive service packages. Epiroc, a Swedish-based company, occupies a specialized position, focusing on equipment and services tailored for mining and infrastructure applications, particularly in regions with significant extractive industries.
| Leading Market Players |
|---|
| iRing Inc. |
| Komatsu |
| ABB |
| Autonomous Solutions Inc. |
| Rockwell Automation |
| Dyno Nobel |
| Orica Limited |
| Modular Mining Systems |
| Epiroc |
| Others |
Cost & Logistics Intelligence
The integration of AI-powered vision systems with robotic blasting arms fundamentally reshapes cost economics by reducing labor and abrasive waste, simultaneously concentrating specialized service provision among technology-driven integrators. This technological advancement also influences supply chain dynamics for advanced components.
Pricing Analysis
Margin tightening in traditional abrasive blasting services reflects intensified competition from automated solutions. The dominant pricing model favors contract-based services and project-based engagements, offering customers operational expenditure flexibility. Price differentiation stems from the level of automation integration and the required surface finish certification. Aerospace assemblers are least price-sensitive for critical applications, while general metal fabricators exhibit higher sensitivity.
Supply Chain Analysis
Logistics costs for specialized robotic components and abrasive media influence service delivery pricing. Geographic supply concentration for advanced robotics is centered in Germany and the United States, while specialized abrasives often source from China and India. A structural risk involves single-source vulnerability for proprietary control software. Distribution runs through a network of specialized system integrators and equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a consolidation play, as the significant capital outlay for advanced robotic systems forces smaller, less capitalized service providers out. Technological sophistication and compliance requirements drive this trend.
For Market Incumbents:
Deepen vertical integration into specialized software development to counter threats from pure-play tech firms. Incumbents should invest in AI-powered vision systems and closed-loop control to meet stringent FAA and CE marking specifications. Expanding service contracts for remote monitoring provides a crucial lever against margin pressure from commoditized manual blasting services.
For New Entrants and Emerging Players:
Enter via niche applications requiring specialized material handling or unique surface finishes, such as medical device manufacturing in Switzerland. Focus on contract-based service models in regions with lower capital expenditure capacity, like Mexico's automotive sector. A strong go-to-market angle involves offering mobile, containerized units for infrastructure maintenance in underserved rural areas.
For Investors and Strategic Acquirers:
Exit pathways concentrate in industrial automation specialists with strong software and robotics portfolios. The long-term viability favors firms integrating AI and digital twin capabilities for process optimization. Acquisition targets should be mid-cap system integrators possessing proprietary vision system algorithms and a skilled technician base. A signal to watch is the increasing adoption rate of SaaS models for blasting process control.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-powered Vision Systems | Enhances precision for aerospace components, meeting stringent quality specifications for aircraft manufacturers. |
| Develop SaaS for Remote Monitoring | Creates recurring revenue streams and lowers adoption barriers for industrial clients hesitant about complex software management. |
| Expand Mobile Blasting Unit Deployment | Addresses demand from construction firms for on-site infrastructure maintenance and equipment preparation in Australia. |
| Strategic Partnerships with Robotics OEMs | Secures access to cutting-edge robotic arms, critical for maintaining technological leadership in automated surface treatment. |
| Acquire Specialized System Integrators | Consolidates expertise in complex programming for irregular geometries, reducing specialized integrator dependency for end-users. |
Research Approach
Document review covered technical specifications, industry white papers, and regulatory filings from OSHA and the EU Machinery Directive, complemented by interviews with key stakeholders. Primary interviews included robotics engineers, plant operations managers, and aerospace quality assurance specialists. This approach involved bottom-up data collection from market participants and top-down validation against published industry statistics.
Historical market data was cross-referenced against expert panel input to project volume and value across the analysis window. Segmentation dimensions modeled included service type, application, end-user, and deployment model. Compound annual growth rates were derived from a multi-variable regression model, informed by capital expenditure trends in advanced manufacturing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid technological disruption or unforeseen regulatory shifts. Forecasts reflect assumptions regarding economic stability and continued industrial automation investment. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Global SCADA Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market
Industrial Automation
North America Factory Automation and Industrial Controls Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
SCADA Alarm Management Market
Industrial Automation
China Factory Automation and Industrial Controls Market
Industrial Automation
Digital Transformation in Manufacturing Market
Industrial Automation
Global Intelligent Process Automation Market
Industrial Automation
Global Intelligent Completion Market
Industrial Automation
Middle East and Africa Industrial Automation Market
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
Motion Control Drive Market
Industrial Automation
Pick and Place Machines Market
Industrial Automation
Global Electric Gripper Market