
 India Data Center Rack Market | 2026-2036
India Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
India Data Center Rack Market Insights
Asset-light leasing and build-to-suit project finance is reshaping competitive entry in India's data center rack landscape. Schneider Electric SE leverages its integrated power and cooling portfolio to anchor large-scale deployments. Rittal GmbH & Co KG differentiates through precision thermal engineering for high-density configurations. Vertiv Group Corp competes aggressively on channel control, sustaining direct relationships with colocation operators across Noida and Chennai.
A data center rack is a standardized metal framework designed to house servers, networking equipment, and power distribution units, typically conforming to 19-inch EIA-310-D specifications with load ratings between 1,000 and 3,000 pounds. Its primary purpose is to enable organized cable management, optimized airflow, and scalable density in climate-controlled facilities. Enclosed cabinet racks command premium positioning due to integrated security and containment features demanded by financial services and government clients. Liquid cooling racks represent the fastest-expanding category as thermal loads from AI training clusters exceed traditional air-conditioning thresholds. Steel remains the dominant material segment, though aluminum gains share in edge deployments where weight constraints matter.
BIS certification requirements and CEA electrical safety mandates govern rack manufacturing standards for equipment deployed within Indian territory. MeitY's data center localization directives and state-level IT policies in Maharashtra and Telangana directly shape procurement localization and domestic assembly obligations. Stakeholders must monitor evolving BIS testing protocols and state incentive structures to align capacity planning with compliance timelines.
Market Dynamics
Liquid cooling infrastructure is collapsing thermal density ceilings across Indian hyperscale facilities, forcing rack manufacturers to reengineer load-bearing and containment architectures for GPU-intensive AI clusters.
Growth Catalysts
- MeitY Localization Directives:Data center equipment procurement mandates under India's Ministry of Electronics and Information Technology are accelerating domestic assembly lines and BIS certification pathways for rack manufacturers.
- AI Training Clusters:Thermal loads exceeding 50kW per rack from NVIDIA H100 deployments are rendering air-cooled designs obsolete and driving precision liquid cooling rack procurement.
- Maharashtra IT Policy:State-level infrastructure incentives in Mumbai-Pune corridor have concentrated hyperscale investments, creating sustained demand for high-density enclosed cabinet configurations.
Market Restraints
- Steel Price Volatility:Cold-rolled steel input costs fluctuate with global commodity cycles, compressing margin predictability for domestic rack fabricators serving price-sensitive colocation operators.
- BIS Certification Timelines:Bureau of Indian Standards testing protocols for electrical safety and structural load ratings extend product qualification cycles, delaying contract fulfillment for urgent hyperscale deployments.
- Aluminum Substitution Limits:Edge computing weight constraints favor aluminum rack materials, but structural rigidity requirements above 1,500-pound load ratings restrict substitution in core data center applications.
Strategic Opportunities
- Telangana Data Center Policy:Hyderabad's emerging hyperscale cluster offers first-mover positioning for rack suppliers establishing dedicated regional manufacturing and service infrastructure.
- CEA Electrical Safety Mandates:Central Electricity Authority compliance requirements for power distribution integration within rack enclosures create premium pricing potential for certified integrated solutions.
- Edge Computing Convergence:5G base station co-location with micro data centers is opening modular rack demand across tier-2 Indian cities where standardized 19-inch EIA-310-D configurations remain underpenetrated.
Industry Challenges
- Thermal Engineering Talent Scarcity:Liquid cooling system integration requires specialized fluid dynamics expertise that Indian vocational pipelines have not yet scaled to match deployment velocity.
- Legacy Air-Cooled Infrastructure Stranding:Existing data center investments in traditional HVAC architectures create retrofit friction for high-density rack upgrades, slowing adoption cycles in brownfield facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Data Center Rack Market |
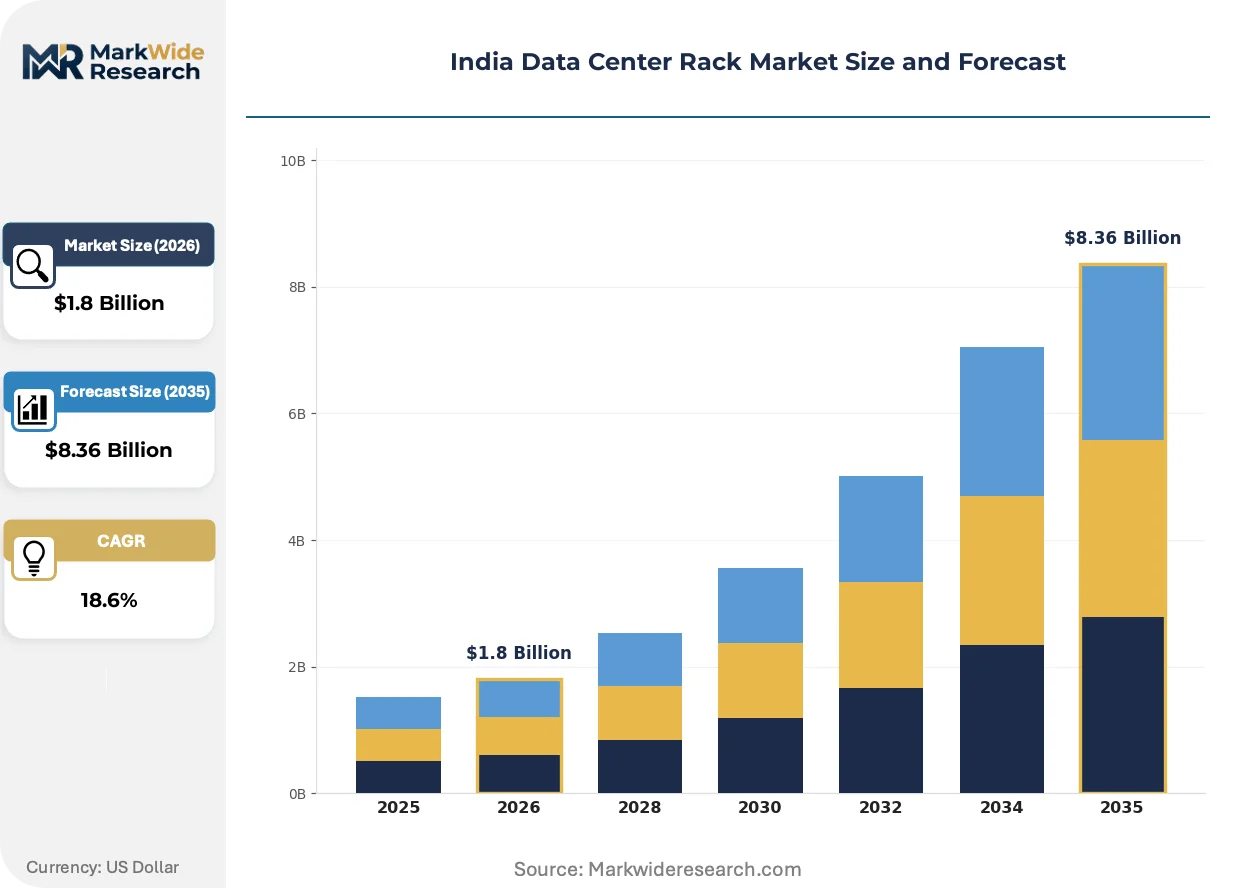
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Rack Type: Open Frame, Enclosed Cabinet, Wall-Mount, Cooling Rack Material: Steel, Aluminum, Plastic, Composite End User: Telecommunications, Cloud Service Providers, Enterprises, Colocation Providers Cooling Solution: Air Conditioning, Liquid Cooling, Free Cooling, Evaporative Cooling |
| Companies Covered | Rittal GmbH & Co KG, Hewlett Packard Enterprise, Schneider Electric SE, Legrand SA, Fujitsu Corporation, Vertiv Group Corp, Black Box Corporation, nVent Electric PLC, Eaton Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Data Center Rack Market Trends and Innovations
Rack architecture is undergoing fundamental redesign as thermal physics and localization policy converge, compressing legacy product lifecycles and rewarding manufacturers with integrated power-thermal-cooling portfolios.
Direct-to-chip liquid cooling is collapsing the boundary between rack infrastructure and thermal management systems. Cold plate and immersion designs integrate pumping manifolds directly into rack frames, eliminating separate CRAH dependencies. Hyperscale operators in Bangalore and Hyderabad are specifying these configurations for 100kW-plus AI training pods. The structural consequence is collapsing margins for standalone air-cooling specialists unable to pivot to fluid-integrated rack engineering.
BIS certification protocols are tightening electrical safety and electromagnetic compatibility requirements for rack-mounted power distribution units. The Bureau of Indian Standards has accelerated testing frequency for equipment deployed in financial services and government facilities. Domestic manufacturers with in-house testing laboratories are compressing qualification timelines while import-dependent competitors face extended customs hold risks.
Build-to-suit project finance is displacing traditional equipment purchase models across Indian colocation markets. Operators in Noida and Chennai are securing rack infrastructure through leasing structures that bundle installation, maintenance, and upgrade pathways. This shift concentrates procurement authority with integrated solution providers capable of underwriting long-term service contracts rather than discrete hardware vendors.
India Data Center Rack Market Segmentation
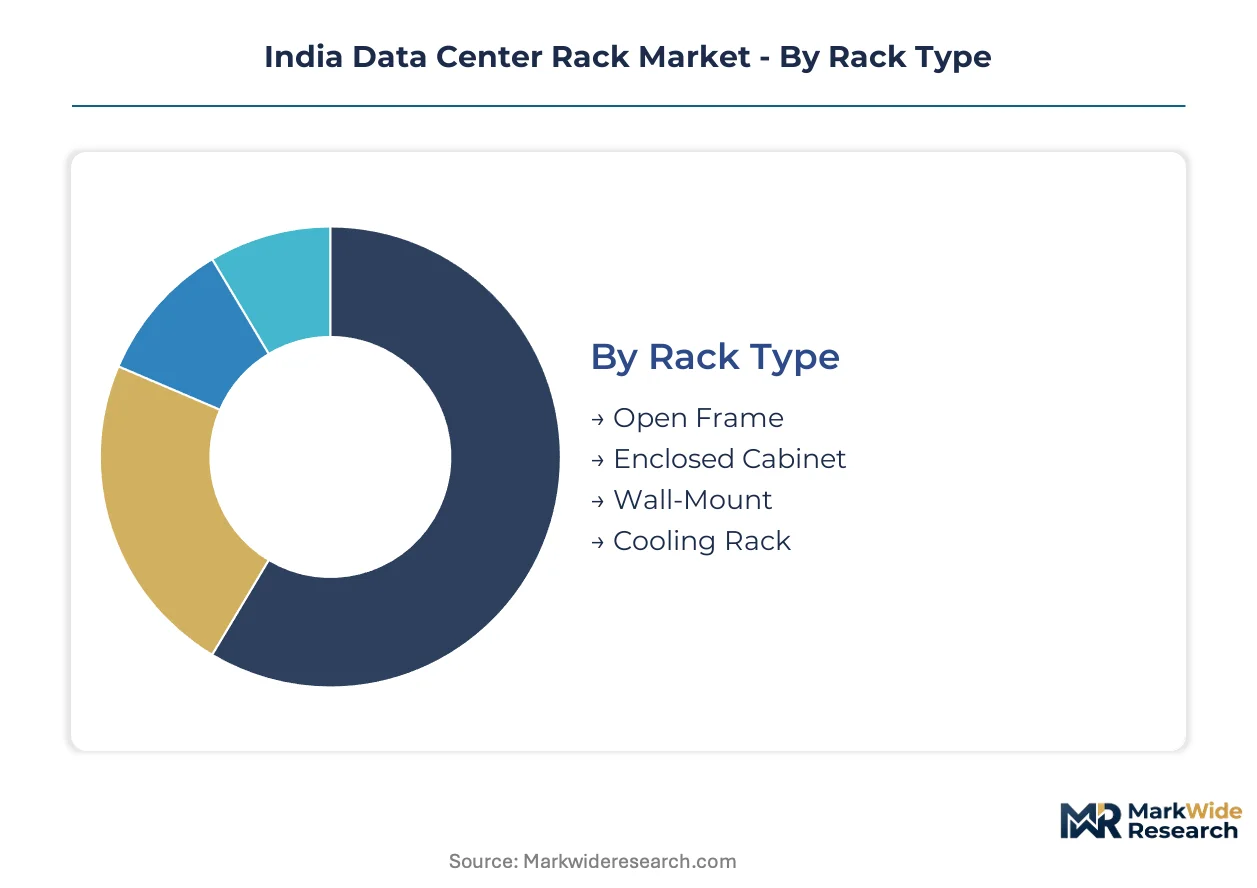
Segmentation in India's data center rack market exposes divergent procurement logics across thermal architectures, material specifications, and customer scale. Each dimension carries distinct compliance obligations and margin structures that manufacturers must navigate.
Rack Type:
Physical enclosure architecture determines security tiering, thermal containment capability, and compliance eligibility for regulated workloads.
- Enclosed Cabinet:Fully enclosed steel housings with integrated locking mechanisms and side panels satisfy BIS electrical safety mandates for financial services and government deployments. Demand concentrates in Mumbai and Hyderabad hyperscale facilities where physical security certifications gate contract eligibility.
- Cooling Rack:Purpose-built frames with integrated liquid distribution manifolds and cold plate mounting rails support 100kW-plus GPU clusters. Telangana's emerging AI training corridor is driving specification requests for direct-to-chip configurations that eliminate separate CRAH dependencies.
- Open Frame:Four-post structures without side panels optimize airflow in legacy air-cooled facilities with existing perimeter cooling infrastructure.
- Wall-Mount:Compact two-post designs serve edge computing and 5G base station co-location deployments in tier-2 Indian cities with constrained floor space.
Enclosed Cabinet commands the established base. The steepest expansion runs through Cooling Rack.
Material:
Structural composition trades load-bearing capacity against weight, corrosion resistance, and fabrication cost in India's price-sensitive procurement environment.
- Steel:Cold-rolled carbon steel dominates core data center specifications with 1,500-3,000 pound load ratings required for dense server stacking. Maharashtra's hyperscale operators specify steel frames for main halls despite commodity price volatility compressing fabricator margins.
- Aluminum:Lightweight extrusions enable single-person installation in edge micro data centers where ceiling loading limits apply. Bangalore's 5G edge rollout is accelerating aluminum procurement for rooftop and cellular base station deployments.
- Composite:Fiber-reinforced polymer blends offer electromagnetic interference shielding for defense and research computing applications with specialized signal integrity requirements.
- Plastic:Injection-molded housings serve low-density networking closets and temporary installations where structural load requirements remain minimal.
Steel anchors volume procurement. Aluminum is climbing the fastest as edge infrastructure proliferates.
End User:
Customer category shapes specification complexity, contract duration, and service bundling expectations across India's data center value chain.
- Cloud Service Providers:Hyperscale operators in Noida and Chennai drive standardization toward 19-inch EIA-310-D configurations with hot-aisle containment and integrated busbar power distribution. Build-to-suit leasing structures concentrate procurement authority with integrated solution providers capable of underwriting decade-long service contracts.
- Colocation Providers:Multi-tenant facility operators in Mumbai-Pune corridor specify enclosed cabinets with biometric access controls and segmented power monitoring to satisfy diverse tenant compliance requirements.
- Enterprises:Banking and manufacturing captive data centers prioritize BIS-certified integrated power-thermal solutions over discrete component sourcing.
- Telecommunications:Reliance Jio and Bharti Airtel edge deployments favor wall-mount and open-frame configurations for 5G infrastructure with rapid deployment timelines.
Cloud Service Providers dominate contract value. Colocation Providers are gaining share fastest as asset-light leasing models expand.
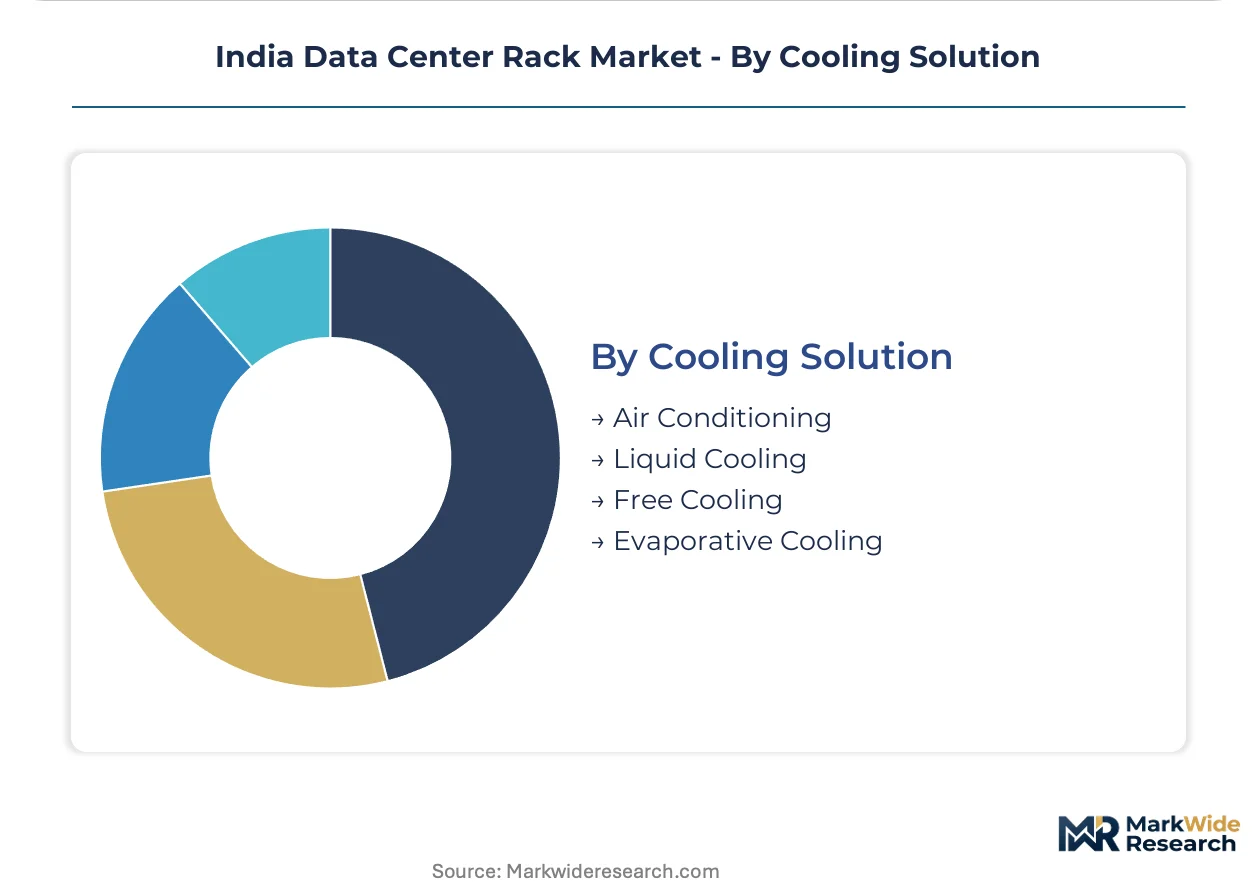
Cooling Solution:
Thermal management architecture now determines rack structural design rather than operating as a separate facility-level decision.
- Liquid Cooling:Direct-to-chip and immersion systems integrate pumping infrastructure into rack frames, collapsing the boundary between mechanical and structural engineering. NVIDIA H100 deployments in Bangalore and Hyderabad are rendering air-cooled designs obsolete for AI training workloads exceeding 50kW per rack.
- Air Conditioning:Conventional raised-floor perimeter cooling persists in brownfield facilities where retrofit economics delay high-density upgrades.
- Free Cooling:Economizer-based systems leverage Pune and Bengaluru ambient temperature profiles to reduce mechanical refrigeration duty cycles.
- Evaporative Cooling:Adiabatic designs suit Hyderabad's dry climate with lower water consumption than traditional chilled water systems.
Air Conditioning retains installed base dominance. Liquid Cooling exhibits the steepest expansion trajectory as AI cluster densities escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level IT policies and hyperscale clustering incentives are redistributing data center rack procurement across India's major economic corridors, concentrating manufacturing obligations and thermal engineering requirements in specific sub-regional markets.
Maharashtra
Mumbai-Pune corridor hosts India's densest hyperscale concentration, with cloud service providers driving demand for enclosed cabinet racks meeting BIS electrical safety mandates. The state's IT infrastructure incentives have attracted multi-gigawatt capacity commitments. Fabricators in Navi Mumbai and Pimpri-Chinchwad industrial zones are scaling steel frame production for 1,500-3,000 pound load-rated configurations.
Telangana
Hyderabad's emerging AI training cluster is generating specification requests for liquid cooling racks supporting 100kW-plus GPU deployments. The Telangana Data Center Policy offers power tariff subsidies and land allocation preferences for rack suppliers establishing regional assembly. Hardware Park and Genome Valley industrial areas are attracting integrated power-thermal-cooling solution providers.
Karnataka
Bangalore's 5G edge rollout is accelerating aluminum rack procurement for rooftop micro data centers where ceiling loading limits constrain steel deployment. Karnataka's Electronics System Design and Manufacturing policy extends PLI scheme benefits to domestic rack fabricators. Whitefield and Electronic City industrial corridors are concentrating modular wall-mount and open-frame manufacturing for telecommunications infrastructure.
Tamil Nadu
Chennai's colocation market is shifting toward build-to-suit leasing structures that bundle rack infrastructure with long-term service contracts. The state's Electronics Manufacturing Policy provides capital subsidies for testing laboratories compressing BIS certification timelines. Sriperumbudur and Oragadam industrial belts are hosting integrated solution providers capable of underwriting decade-long maintenance agreements.
Delhi-NCR
Noida's hyperscale facilities are standardizing on 19-inch EIA-310-D configurations with hot-aisle containment and integrated busbar power distribution. Uttar Pradesh's Data Center Policy offers stamp duty exemptions and subsidized electricity tariffs for rack manufacturers. Greater Noida industrial zone is attracting channel-controlled suppliers maintaining direct relationships with colocation operators.
India Data Center Rack Market Competitive Landscape
On the supply side, the industry is consolidating around integrated power-thermal-cooling portfolios rather than discrete hardware vendors, with procurement authority shifting toward solution providers capable of underwriting long-term service contracts. Three strategic archetypes dominate: European engineering conglomerates with precision thermal capabilities, diversified electrical infrastructure multinationals leveraging power distribution integration, and channel-focused specialists sustaining direct operator relationships. Competitive moves center on regional manufacturing localization to satisfy MeitY directives and liquid cooling engineering acquisitions to address AI cluster thermal densities.
Among European-based engineering specialists, Rittal GmbH & Co KG and Schneider Electric SE exemplify the integrated portfolio archetype, occupying positions that bundle structural, power, and thermal engineering under single procurement relationships. Vertiv Group Corp represents the channel-control model, anchoring competitive positioning through sustained direct engagement with colocation operators across Noida and Chennai rather than intermediary distribution. These three entities collectively illustrate how compliance with BIS certification pathways and CEA electrical safety mandates has become inseparable from market access in India's localization-driven procurement environment.
| Leading Market Players |
|---|
| Rittal GmbH & Co KG |
| Hewlett Packard Enterprise |
| Schneider Electric SE |
| Legrand SA |
| Fujitsu Corporation |
| Vertiv Group Corp |
| Black Box Corporation |
| nVent Electric PLC |
| Eaton Corporation |
| Others |
Pricing and Supply Chain Analysis
Navi Mumbai's steel fabrication cluster anchors domestic rack manufacturing capacity, concentrating supply-side leverage among integrated power-thermal providers and compressing margin structures for discrete component vendors serving price-sensitive colocation operators.
Pricing Analysis
Certification level (BIS/CEA-grade) creates the primary spread between rack tiers, with BIS-certified integrated power-thermal-cooling solutions commanding substantial premiums over uncertified air-cooled frames. Three-tier pricing structure across premium liquid-cooled, standard enclosed cabinet, and economy open-frame configurations reflects thermal density capabilities and compliance bundling. Cost compression in the economy tier is intensifying because cold-rolled steel input volatility and extended BIS testing timelines squeeze fabricator margins. Cloud service providers exhibit the lowest price sensitivity due to decade-long build-to-suit leasing structures, while tier-2 telecommunications operators drive aggressive procurement negotiations.
Supply Chain Analysis
Tariff exposure between India and China dominates supply chain risk calculations for rack manufacturers dependent on precision cooling components and high-grade aluminum extrusions. Domestic production draws from cold-rolled steel mills in Maharashtra and Jharkhand, copper busbar suppliers in Tamil Nadu, and imported cold plates and pumping manifolds from Taiwan and South Korea. Single-source vulnerability concentrates in liquid cooling subsystems where Taiwanese fluid dynamics engineering remains unmatched. Distribution runs through direct manufacturer relationships with hyperscale operators in Mumbai and Chennai, supplemented by regional distributors serving edge computing deployments in tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid cooling engineering talent scarcity constrains deployment velocity for AI training clusters, creating asymmetric returns for manufacturers that internalize fluid dynamics capabilities ahead of competitor catch-up cycles.
For Market Incumbents: Build regulatory certification moats by accelerating in-house BIS testing laboratory investments and CEA electrical safety mandate pre-qualification programs. Compress qualification timelines for urgent hyperscale deployments while import-dependent competitors face customs hold risks. Deepen backward integration into precision thermal component manufacturing to capture margins collapsing for standalone air-cooling specialists. For New Entrants and Emerging Players: Tier-2 edge computing markets in Uttar Pradesh and Madhya Pradesh offer underpenetrated white-space for aluminum wall-mount and open-frame configurations serving 5G base station co-location. Target telecommunications infrastructure procurement with rapid-deployment modular designs that bypass the certification complexity gating financial services contracts. Establish regional service partnerships rather than competing on integrated solution bundling. For Investors and Strategic Acquirers: Long-term, this sits as a localization-policy arbitrage play because MeitY directives and state-level IT incentives are structurally advantaging domestic assembly over import-dependent competitors. Acquisition candidates with captive BIS certification pathways and Telangana or Maharashtra manufacturing presence offer the cleanest exposure. Monitor liquid cooling engineering hiring velocity at hyperscale operators as the inflection signal for thermal architecture transition speed.| Strategic Initiative | Industry Significance |
|---|---|
| In-House BIS Testing Laboratory Investment | Compresses qualification timelines while competitors face extended customs hold risks at Indian ports. |
| Liquid Cooling Engineering Acquisition | Internalizes fluid dynamics capabilities that vocational pipelines have not scaled to match deployment velocity. |
| Telangana Regional Manufacturing Footprint | Captures power tariff subsidies and land allocation preferences under state data center policy incentives. |
| Direct Hyperscale Operator Relationship | Secures procurement authority as build-to-suit leasing displaces traditional equipment purchase models. |
| Integrated Power-Thermal-Cooling Portfolio | Aligns with procurement concentration toward solution providers underwriting long-term service contracts. |
Research Methodology
A spread of perspectives from data center infrastructure executives, thermal engineering specialists, colocation procurement managers, and state IT policy officials converged on the working assumptions. Primary field engagement with rack fabricators in Navi Mumbai and Hyderabad supplemented secondary validation through BIS certification records, CEA electrical safety filings, MeitY policy circulars, and hyperscaler capex disclosures. Customs trade data and state industrial development corporation land allocation records anchored supply-side triangulation. Bottom-up unit economics and top-down policy impact assessment were cross-referenced for convergence.
Demand-supply balance dynamics across rack type, material specification, cooling architecture, and end-user category shaped the analytical framework over the projection horizon. Segmentation modeling incorporated thermal density tiers, certification grade differentials, and regional manufacturing obligation clusters. CAGRs were derived from installed base replacement cycles and AI training cluster deployment pipelines. Hyperscale operator specification trends and state incentive program uptake rates served as primary forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in cold-rolled steel commodity cycles, rupee-dollar exchange volatility, or BIS testing protocol acceleration would shift the trajectory. Forecasts reflect documented assumptions regarding localization policy enforcement intensity and liquid cooling technology maturation curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
South America Data Center Server Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
Los Angeles Data Center Market
Data Center Infrastructure
Taiwan Data Center Rack Market
Data Center Infrastructure
Smart Data Center Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
Singapore Data Center Power Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Canada Data Center Power Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
Israel Data Center Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
Sweden Data Center Construction Market
Data Center Infrastructure
Data Center Containment Solution Market