
 Modular Automation and Services Market | 2026-2036
Modular Automation and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Automation and Services Market Outlook
German system integrators and Japanese precision equipment makers is pivoting toward plug-and-play automation architectures that slash reconfiguration downtime for batch manufacturers. ABB leverages its robotics portfolio to dominate high-mix automotive body shops across Europe. Siemens anchors digital twin integration within its SIMATIC ecosystem, competing on software-hardware convergence. Bosch Rexroth AG specializes in linear motion modules that sustain margin pools in battery assembly applications.
Modular automation and services denotes factory systems built from standardized, interchangeable hardware and software blocks that communicate via open protocols and can be reconfigured without custom engineering. These architectures typically employ IP67-rated I/O modules, EtherCAT or PROFINET buses, and containerized control code to enable line changes in hours rather than weeks. Control Systems and Industrial Robots represent the most mature revenue pools, while IoT-enabled sensor networks and cloud-based predictive maintenance services capture the fastest expansion in margin contribution. Machine Learning applications within quality inspection and adaptive process control are displacing fixed-parameter systems in pharmaceutical packaging and food processing lines.
The EU Machinery Directive and IEC 61508 functional safety standards mandate validated software architectures and documented failure modes for reprogrammable safety systems, raising barriers for uncertified entrants. OSHA lockout-tagout rules and FDA 21 CFR Part 11 electronic records requirements in the United States further shape validation protocols for pharmaceutical and food processing deployments. Stakeholders must weigh the capital efficiency of modular retrofits against the stranded asset risk of legacy fixed automation as product lifecycles compress across consumer electronics and electric vehicle manufacturing.
Market Dynamics
Automotive OEMs in Germany and Japan are compressing model lifecycles below 24 months, forcing assembly line reconfiguration cycles that legacy fixed automation cannot sustain. This demand velocity is restructuring supplier relationships around interchangeable hardware blocks and containerized control software.
Growth Catalysts
- EU Machinery Directive certification mandates:Reprogrammable safety systems require validated software architectures under IEC 61508, creating pull for certified modular platforms that reduce compliance overhead for batch manufacturers.
- China's Yangtze River Delta electronics clustering:EV battery and consumer electronics suppliers concentrate manufacturing footprint in this corridor, demanding rapid line changeover capabilities that modular architectures uniquely deliver.
- EtherCAT and PROFINET protocol standardization:Open industrial Ethernet buses enable plug-and-play interoperability between heterogeneous equipment vendors, collapsing integration timelines from weeks to hours.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium for servo motors concentrate in Chinese processing facilities, exposing linear motion module costs to geopolitical supply disruptions.
- IEC 61508 SIL certification timelines:Functional safety validation for reprogrammable systems requires 18-24 month documentation cycles, freezing smaller integrators from bidding on pharmaceutical and automotive safety-critical applications.
- Fixed automation stranded asset risk:Legacy hardwired control systems in mature European automotive plants carry depreciation schedules misaligned with product lifecycle compression, deterring incremental modular investment.
Strategic Opportunities
- India's PLI scheme for advanced manufacturing:Production-linked incentives for electronics and automotive component makers create first-mover advantage for modular automation vendors establishing local integration capabilities.
- Machine Learning convergence with edge computing:Adaptive process control algorithms deployed on IP67-rated edge devices enable real-time quality inspection without cloud latency, opening pharmaceutical packaging applications.
- Outcome-based maintenance contracts:Cloud-based predictive analytics bundled with hardware subscriptions shift revenue from capital equipment to recurring service streams in food processing verticals.
Industry Challenges
- Multi-protocol integration complexity:Brownfield deployments must bridge legacy fieldbus systems with modern EtherCAT networks, requiring scarce systems engineering talent conversant in both generations.
- IP67-rated enclosure lead times:Supply chain constraints on sealed I/O modules extend project delivery schedules, compressing integrator margins on fixed-price contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Automation and Services Market |
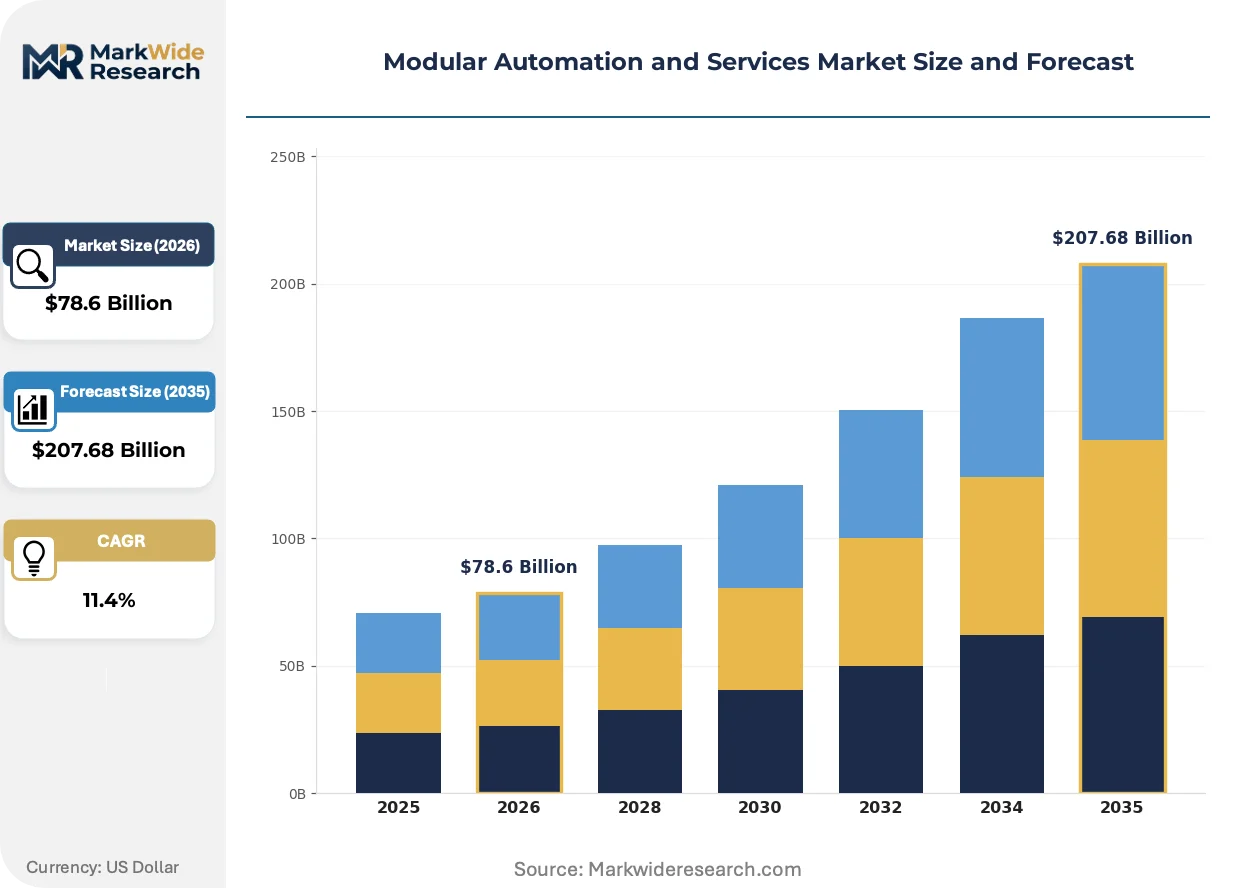
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $207.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Control Systems, HMI, Sensors Technology: Machine Learning, Robotics, IoT, Cloud Computing End User: Manufacturing, Automotive, Food Processing, Pharmaceuticals Service Type: Consulting, Maintenance, Installation, Support |
| Companies Covered | ABB, Siemens, Festo Inc., Bosch Rexroth AG, Yokogawa Electric Corporation, HIMA, Rockwell Automation, Schneider Electric, Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Automation and Services Market Strategic Shifts
Containerized control code and digital twin simulation are collapsing the boundary between hardware commissioning and software deployment. These shifts are redefining competitive advantage around software-hardware convergence rather than mechanical precision alone.
Digital twin platforms are rewriting how automotive body shops validate line configurations before physical installation. German OEMs deploy Siemens SIMATIC virtual commissioning to simulate robot interference zones and cycle times, compressing startup schedules by eliminating on-site debugging. This capability is shifting procurement criteria toward vendors with integrated simulation environments rather than standalone hardware specifications.
Japan's METI has accelerated JIS B 8433 collaborative robot safety standards revision to address force-limiting requirements in human-robot workcells. The updated framework mandates validated collision detection algorithms and documented risk assessments for reprogrammable systems. Pharmaceutical packaging lines in Osaka and Nagoya industrial zones are retrofitting existing installations to meet these protocols ahead of enforcement deadlines.
Chinese EV battery manufacturers are unbundling after-sales service from initial equipment procurement, demanding predictive maintenance subscriptions tied to cell yield performance. CATL and BYD suppliers in the Yangtze River Delta now specify uptime guarantees rather than spare parts availability in vendor selection criteria. This contractual shift is forcing European robotics vendors to build local service footprints or cede margin to domestic integrators.
Modular Automation and Services Market Segmentation
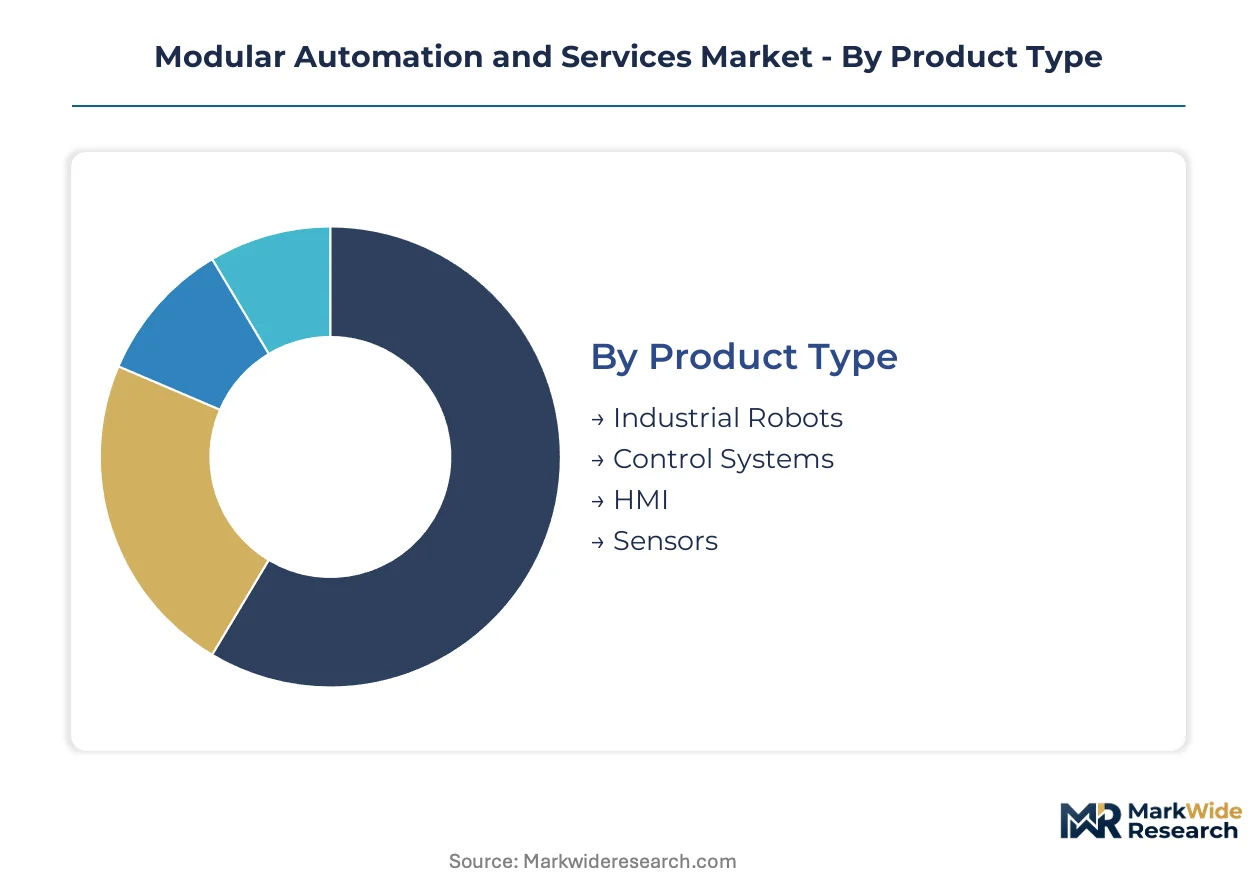
Modular automation architectures fragment across hardware, software, and service layers that buyers combine based on reconfiguration velocity needs. Segmentation reveals where capital concentrates versus where margin pools are forming fastest.
Product Type:
Buyers differentiate by the mechanical complexity they can deploy without custom engineering.
- Industrial Robots:Six-axis articulated arms and SCARA configurations dominate automotive body shops where ABB and KUKA systems execute tool changes in under 10 minutes. German OEMs in Stuttgart and Wolfsburg specify these for model-cycle compression below 24 months.
- Control Systems:PLCs with containerized runtime environments host reprogrammable logic for batch manufacturers. Siemens SIMATIC units anchor digital twin integration in EU-certified safety architectures.
- HMI:Industrial touch panels with IP67 sealing enable operator interaction in washdown food processing environments.
- Sensors:EtherCAT-enabled I/O blocks feed real-time data to edge controllers for adaptive process monitoring.
Volume sits with Control Systems; growth tilts toward Industrial Robots.
Technology:
Adoption patterns split between proven industrial protocols and emerging intelligence layers.
- Machine Learning:Vision-based defect detection algorithms deploy on IP67-rated edge devices for pharmaceutical packaging lines in Osaka and Nagoya. METI's revised JIS B 8433 standards mandate validated collision detection for these adaptive systems.
- Robotics:Force-limiting collaborative systems penetrate human-robot workcells where reprogramming frequency exceeds weekly cycles.
- IoT:Sensor networks with predictive analytics capabilities capture the steepest expansion trajectory as CATL and BYD suppliers in China's Yangtze River Delta specify uptime guarantees over spare parts.
- Cloud Computing:Containerized control code enables remote commissioning and over-the-air updates for distributed manufacturing footprints.
Deployment maturity favors Robotics; margin expansion concentrates in IoT-enabled predictive maintenance.
End User:
Vertical applications diverge by regulatory burden and reconfiguration frequency.
- Manufacturing:Electronics and EV battery suppliers in the Yangtze River Delta demand rapid line changeover capabilities that modular architectures uniquely deliver.
- Automotive:German and Japanese OEMs compress model lifecycles below 24 months, forcing assembly line reconfiguration cycles that legacy fixed automation cannot sustain.
- Food Processing:FDA 21 CFR Part 11 electronic records requirements shape validation protocols for reprogrammable safety systems in washdown environments.
- Pharmaceuticals:IEC 61508 SIL certification mandates validated software architectures, freezing smaller integrators from bidding on safety-critical packaging applications.
Revenue concentration rests with Automotive; contract structure innovation is climbing fastest in Pharmaceuticals.
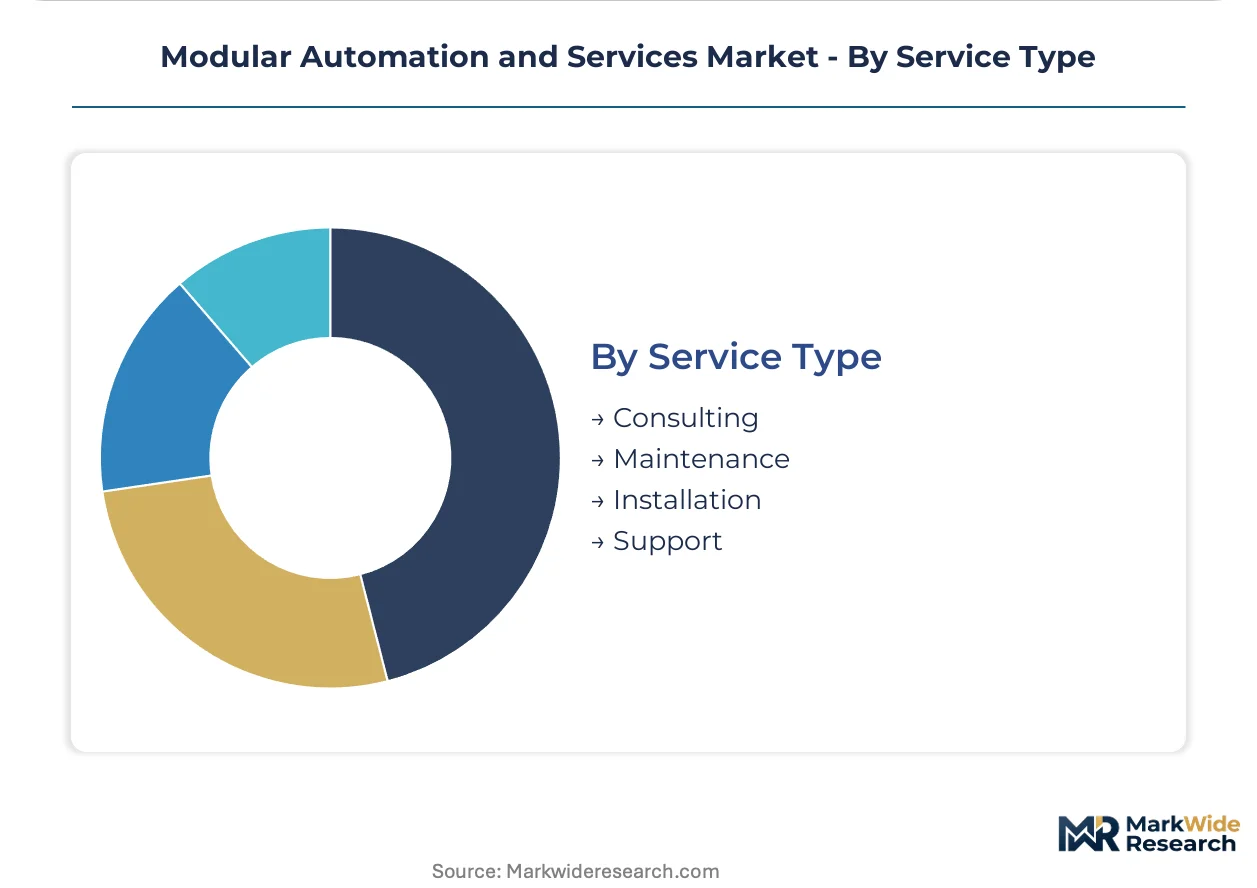
Service Type:
Procurement patterns shift from capital purchase toward performance-linked recurring models.
- Consulting:Systems engineering talent bridges legacy fieldbus with modern EtherCAT networks in brownfield European automotive plants.
- Maintenance:Outcome-based contracts tied to cell yield performance are unbundling from initial equipment procurement by Chinese EV battery manufacturers.
- Installation:Virtual commissioning via digital twin platforms compresses startup schedules by eliminating on-site debugging.
- Support:Cloud-based predictive analytics subscriptions shift revenue streams from hardware to recurring service in food processing verticals.
Contract value aggregates in Maintenance; pricing power is expanding most quickly in Support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet processing facilities in China anchor supply-side exposure for servo motor costs, while demand velocity concentrates in manufacturing corridors where electronics and automotive OEMs compress model lifecycles below 24 months.
Germany
Automotive OEMs in Stuttgart and Wolfsburg compress model lifecycles below 24 months, forcing assembly line reconfigurations that legacy fixed automation cannot sustain. KBA vehicle certification requirements and EU Machinery Directive mandates shape procurement criteria for reprogrammable safety systems. The Baden-Württemberg industrial corridor hosts system integrators pivoting toward plug-and-play architectures that slash reconfiguration downtime.
China
EV battery and consumer electronics suppliers in the Yangtze River Delta demand rapid line changeover capabilities that modular architectures uniquely deliver. MIIT industrial policy and GB standards for collaborative robotics accelerate domestic certification timelines for reprogrammable systems. CATL and BYD suppliers in Suzhou and Ningbo now specify uptime guarantees rather than spare parts availability in vendor selection criteria.
Japan
Precision equipment makers pivot toward force-limiting collaborative systems for human-robot workcells where reprogramming frequency exceeds weekly cycles. METI accelerated JIS B 8433 safety standards revision to address collision detection requirements. Pharmaceutical packaging lines in Osaka and Nagoya industrial zones retrofit existing installations to meet these protocols ahead of enforcement deadlines.
United States
FDA 21 CFR Part 11 electronic records requirements and OSHA lockout-tagout rules shape validation protocols for pharmaceutical and food processing deployments of reprogrammable systems. The Midwest automotive belt and Southeast electronics manufacturing zones drive demand for containerized control code that enables remote commissioning. Brownfield deployments bridge legacy fieldbus systems with modern EtherCAT networks, requiring scarce systems engineering talent.
India
Production-linked incentives for electronics and automotive component makers create first-mover advantage for modular automation vendors establishing local integration capabilities. BIS certification requirements and the PLI scheme for advanced manufacturing accelerate domestic assembly of battery and electronics components. Tamil Nadu and Karnataka industrial corridors concentrate contract manufacturing for global OEMs seeking to diversify supply chains beyond China.
Modular Automation and Services Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue software-hardware convergence and predictive maintenance subscriptions. The vendor base clusters around three archetypes: diversified industrial conglomerates with robotics portfolios, precision motion specialists with linear module expertise, and automation pure-plays betting on digital twin integration. Competitive moves center on strategic partnerships for protocol interoperability and geographic expansion into China's Yangtze River Delta manufacturing corridor.
Within the diversified industrial tier, ABB and Siemens occupy positions exemplifying robotics-to-software convergence strategies. Bosch Rexroth AG anchors the precision motion specialist archetype with German engineering heritage. These three represent distinct competitive vectors: ABB exemplifies high-mix automotive body shop dominance, Siemens anchors digital twin integration within control ecosystems, and Bosch Rexroth AG sustains margin pools in battery assembly applications through linear motion module specialization.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Festo Inc. |
| Bosch Rexroth AG |
| Yokogawa Electric Corporation |
| HIMA |
| Rockwell Automation |
| Schneider Electric |
| Emerson Electric Co. |
| Others |
Value Chain & Pricing Dynamics
Containerized control code deployment simultaneously collapses commissioning costs and concentrates procurement leverage among system integrators capable of virtual validation. This dual compression reshapes margin pools across hardware manufacturers and software providers as buyers unbundle after-sales service from initial capital outlays.
Pricing Analysis
Warranty and predictive maintenance bundling now separates premium-tier vendors from standard hardware suppliers in vendor selection criteria. Three-tier pricing structure across premium, standard, and economy levels reflects IEC 61508 SIL certification grade and digital twin integration depth. Pricing pressure stems from Chinese EV battery manufacturers demanding uptime guarantees rather than spare parts availability. Tier 1 automotive OEMs exhibit lowest price sensitivity; mid-sized batch manufacturers face acute margin compression.
Supply Chain Analysis
Rare earth magnet supply for servo motors rests on Chinese neodymium and dysprosium processing facilities, with secondary concentration in Japanese magnet fabrication. Linear motion modules draw from German precision engineering and Chinese aluminum extrusion capacity. Single-source vulnerability in rare earth processing exposes module costs to geopolitical disruption. Distribution runs through authorized system integrator networks rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
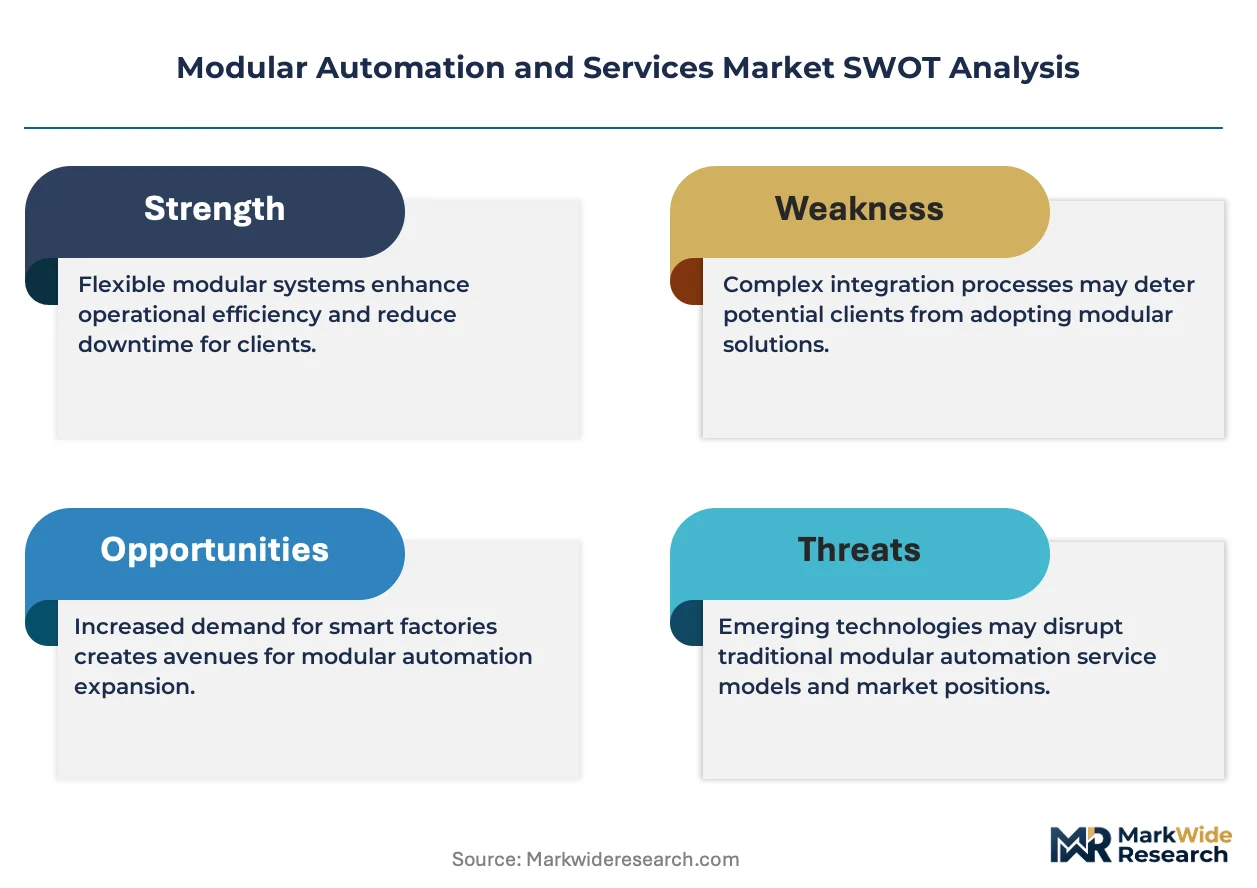
Supply-side scarcity in IEC 61508-certified safety architectures props pricing power for validated platform vendors, constraining capacity expansion by uncertified competitors.
For Market Incumbents: Deploy digital twin integration as the primary defensive lever against emerging software-native entrants. Deepen backward integration into IP67-rated I/O module production to compress lead times and defend margin pools. Accelerate certification investment under revised JIS B 8433 standards ahead of enforcement deadlines to freeze smaller competitors from pharmaceutical packaging bids. For New Entrants and Emerging Players: Capture India's PLI scheme corridor in Tamil Nadu and Karnataka before incumbent service footprints solidify. Target outcome-based maintenance contracts in food processing verticals where legacy vendors lack cloud analytics capabilities. Pursue direct partnerships with Yangtze River Delta battery suppliers seeking uptime guarantees over equipment procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking robotics-to-software convergence. Long-term viability favors automation pure-plays with validated safety architectures and recurring revenue streams above 40 percent of total. Watch for IEC 61508 certification timeline compression as the inflection signal for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Siemens SIMATIC virtual commissioning compresses automotive body shop startup schedules by eliminating on-site debugging cycles. |
| Backward Integration into IP67 Modules | Bosch Rexroth AG's captive production of sealed I/O blocks insulates margin pools from supply chain lead time volatility. |
| Outcome-Based Maintenance Contracts | CATL and BYD suppliers in the Yangtze River Delta now specify cell yield performance guarantees over spare parts availability. |
| IEC 61508 SIL Certification Investment | Validated software architectures raise compliance barriers that freeze uncertified integrators from pharmaceutical safety-critical applications. |
| Geographic Expansion into India PLI Corridors | Tamil Nadu and Karnataka production-linked incentives create first-mover advantage for modular automation vendors establishing local integration capabilities. |
Study Parameters
Independent corroboration across plant engineers at German automotive OEMs, system integrators in the Baden-Württemberg corridor, and procurement leads at Yangtze River Delta battery suppliers underwrites the qualitative findings. Secondary validation draws from MIIT industrial policy disclosures, KBA vehicle certification databases, and SEC filings by diversified industrial conglomerates. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Comparable-period anchoring to historical reconfiguration cycle data and safety standard revision timelines structures the projection horizon. The analytical framework models revenue across hardware, software, and service layers segmented by end-use vertical, reconfiguration velocity requirement, and certification tier. CAGRs derive from regression analysis against capital expenditure patterns and regulatory compliance cost trajectories. Forecast inputs incorporate EtherCAT protocol adoption curves and JIS B 8433 enforcement schedule assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth supply disruptions and IEC 61508 certification timeline extensions. Forecasts reflect documented assumptions regarding model lifecycle compression rates and cloud analytics penetration in food processing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Pick and Place Machines Market
Industrial Automation
Europe Retail Automation Market
Industrial Automation
North America Smart Factory Market
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
Refining Industry Automation and Software Market
Industrial Automation
HMI Market
Industrial Automation
Industrial Data Loggers Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Grippers Market
Industrial Automation
Smart Manufacturing Devices Market
Industrial Automation
North America Human Machine Interface Market
Industrial Automation
Warehousing Automation Equipment Market
Industrial Automation
Conveyor-Free Sortation Modules Market
Industrial Automation
Palletizing Systems Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
China Factory Automation and Industrial Controls Market