
 Factory Automation Platform As a Service Market | 2026-2036
Factory Automation Platform As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Factory Automation Platform As a Service Market Analysis
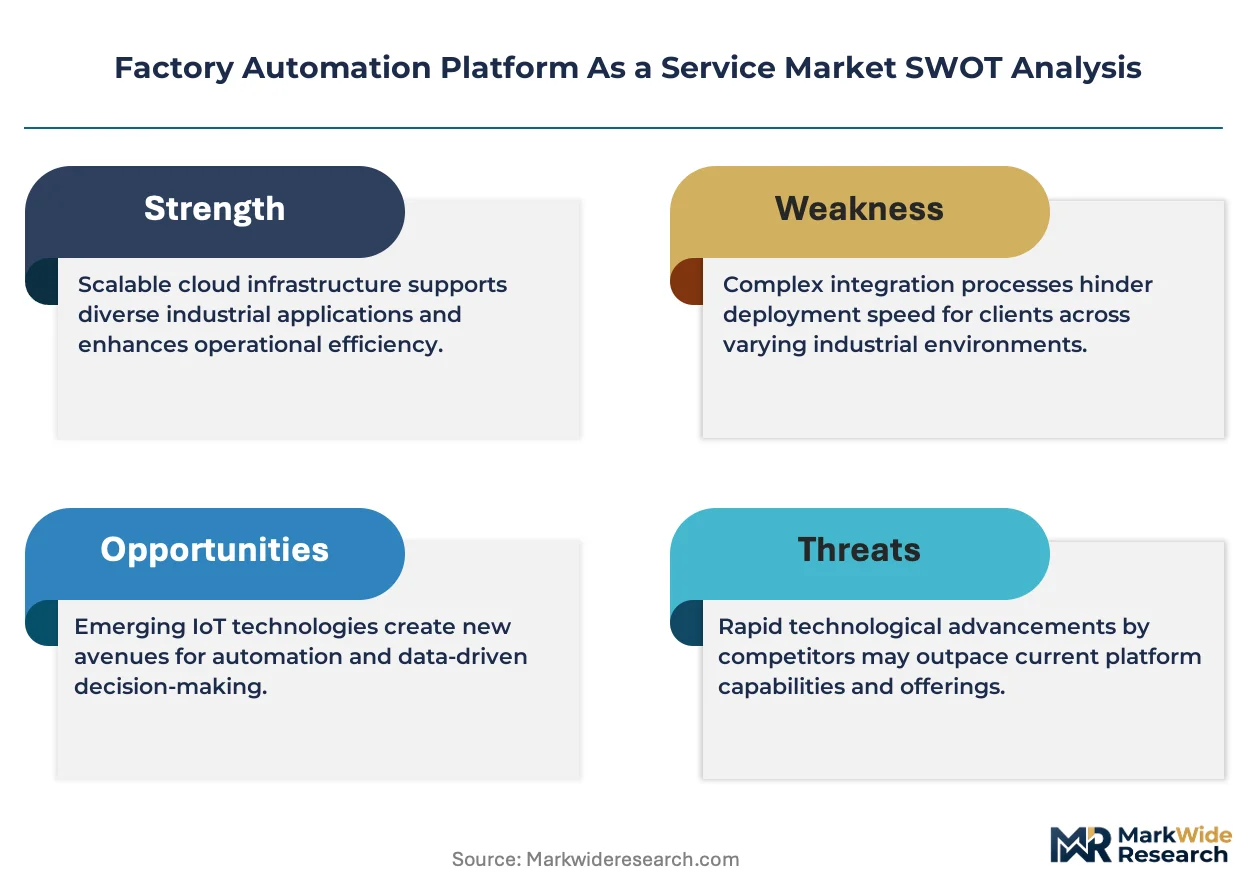
REACH compliance is pivoting vendor investment toward traceability modules and audit-ready data architectures. Siemens AG leverages its digital twin portfolio to anchor premium positioning in European process automation. Rockwell Automation Inc. competes through its FactoryTalk platform specialization in discrete manufacturing verticals. Microsoft Corporation extends cloud infrastructure dominance by embedding Azure IoT capabilities into partner automation stacks.
Factory Automation Platform As a Service delivers cloud-native industrial control environments where subscribers access SCADA, MES, and analytics functions via API-connected infrastructure rather than perpetual on-site licenses. These platforms typically operate on sub-100 millisecond latency thresholds for real-time process control while maintaining ISO 27001-certified data segregation between tenant environments. Deployment model selection reveals structural divergence: hybrid cloud configurations capture the largest revenue share as manufacturers retain critical control loops on-premises while pushing analytics workloads to public infrastructure. Service type segmentation shows process automation modules generating the steadiest recurring revenue, though data analytics subscriptions are expanding fastest as predictive maintenance use cases mature.
The EU AI Act and FDA software validation requirements for pharmaceutical manufacturing are tightening algorithmic transparency mandates across regulated verticals. Germany's KBA and Japan's METI are advancing functional safety certifications for cloud-connected control systems, creating compliance moats for certified platform providers. Stakeholders must weigh sovereignty requirements against scalability gains as national data residency rules fragment deployment architectures.
Market Dynamics
Cloud-native control architectures are compressing the traditional automation vendor stack, forcing incumbents to restructure licensing models around recurring platform subscriptions rather than perpetual hardware sales.
Growth Catalysts
- EU AI Act compliance mandates:Regulated manufacturers in automotive and pharmaceutical verticals must deploy auditable algorithmic systems, accelerating replacement of legacy black-box controllers with transparent platform architectures.
- German automotive OEM consolidation:Volkswagen, BMW, and Mercedes-Benz are standardizing on shared automation platforms across multi-site production networks to reduce integration overhead.
- Edge-to-cloud orchestration protocols:OPC UA over TSN is enabling deterministic control loop migration to hybrid infrastructures without sacrificing sub-50 millisecond response thresholds.
Market Restraints
- Semiconductor supply concentration:Industrial-grade FPGA and ASIC sourcing remains concentrated among Taiwanese and South Korean foundries, creating input bottlenecks for platform hardware gateways.
- Functional safety certification friction:IEC 61508 and ISO 13849 compliance timelines for cloud-connected safety systems extend 18-24 months, delaying go-live dates for safety-critical applications.
- On-premises control retention:Chemical and nuclear facilities maintain hard air-gapped requirements for primary control loops, capping addressable market share for fully cloud-native deployments.
Strategic Opportunities
- India PLI scheme alignment:Electronics and automotive manufacturing incentives are attracting greenfield facilities with native cloud automation architectures, bypassing legacy migration costs.
- Predictive maintenance module expansion:Vibration analysis and thermal imaging AI services are penetrating food and beverage processing, a vertical previously underserved by industrial IoT platforms.
- Digital twin convergence with sustainability reporting:CSRD-mandated Scope 3 emissions tracking is creating demand for integrated energy modeling within automation platforms.
Industry Challenges
- OT-IT cybersecurity skill scarcity:Manufacturing enterprises face acute shortages of engineers cross-trained in industrial protocols and cloud security frameworks.
- Multi-generational system integration:Brownfield facilities operate 20-30 year-old proprietary bus systems requiring costly protocol translation layers for platform connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Factory Automation Platform As a Service Market |
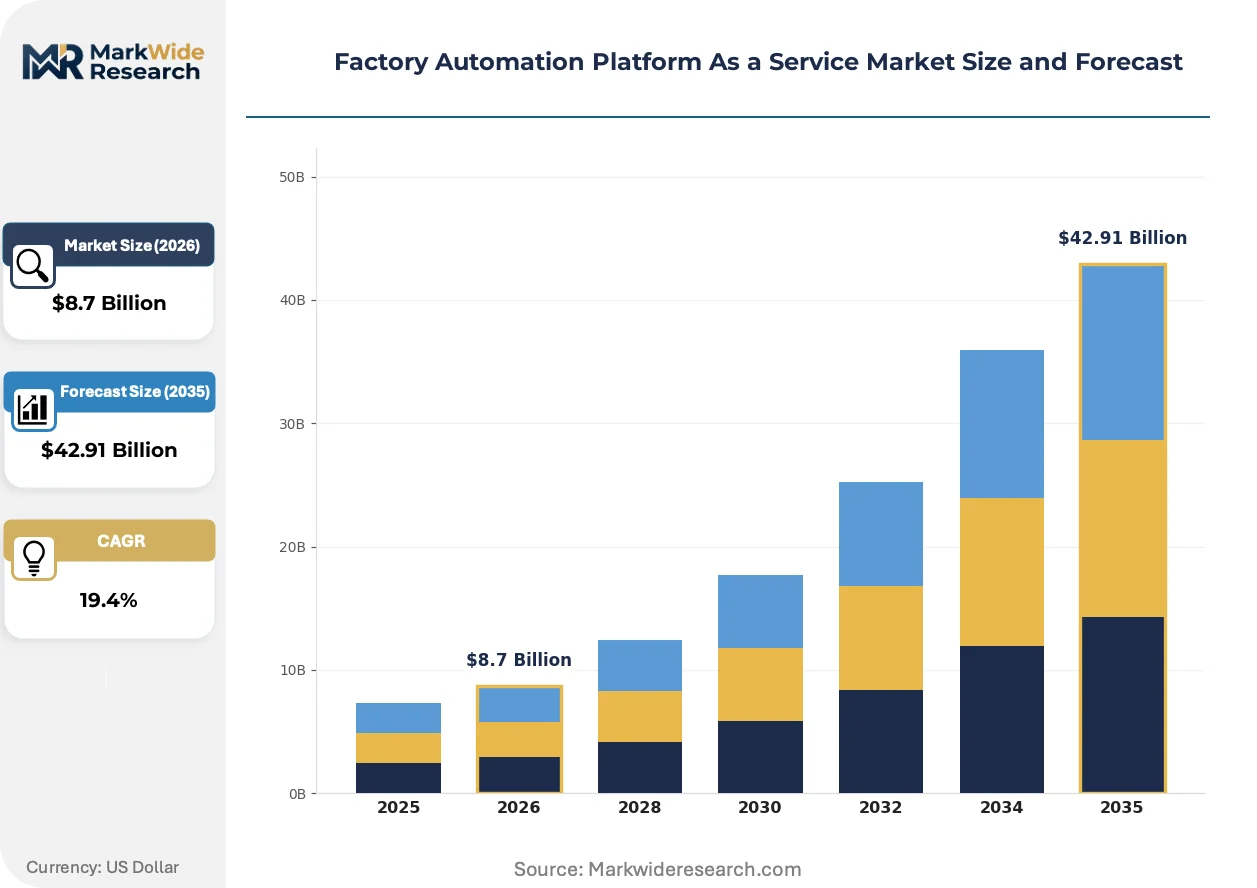
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Process Automation, Data Analytics, Workflow Management, Monitoring Services Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Manufacturers, System Integrators, OEMs, Maintenance Providers Industry Vertical: Automotive, Electronics, Food & Beverage, Pharmaceuticals |
| Companies Covered | Rockwell Automation Inc., Schneider Electric SE, Siemens AG, Hitachi Ltd., Honeywell International Inc., Microsoft Corporation, ABB Ltd., Mitsubishi Electric Corporation, PTC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Factory Automation Platform As a Service Market Emerging Trajectories
Deterministic cloud control is collapsing the boundary between operational technology and enterprise IT, rewriting procurement criteria and vendor evaluation frameworks across process and discrete manufacturing alike.
Microservice-based SCADA architectures are modularizing traditional monolithic control systems into interoperable function blocks. Automotive tier-one suppliers are piloting these decompositions at 40% of new greenfield lines. The shift is modularizing vendor lock-in patterns and enabling mix-and-match sourcing from specialized subsystem providers.
REACH substance restrictions on industrial lubricants and thermal fluids are forcing reformulation of physical plant equipment specifications. Platform providers must now embed chemical compliance tracking into asset management modules. German machinery builders are absorbing these requirements fastest, integrating ECHA database APIs directly into maintenance workflows.
Subscription-based control licensing is displacing capital-intensive automation procurement. Mid-sized discrete manufacturers are compressing equipment financing from 7-year depreciation cycles to 3-year operational expenditure models. This behavioral pivot is most pronounced in Japan, where METI's smart factory subsidies explicitly favor recurring platform contracts over traditional CAPEX grants.
Factory Automation Platform As a Service Market Segmentation
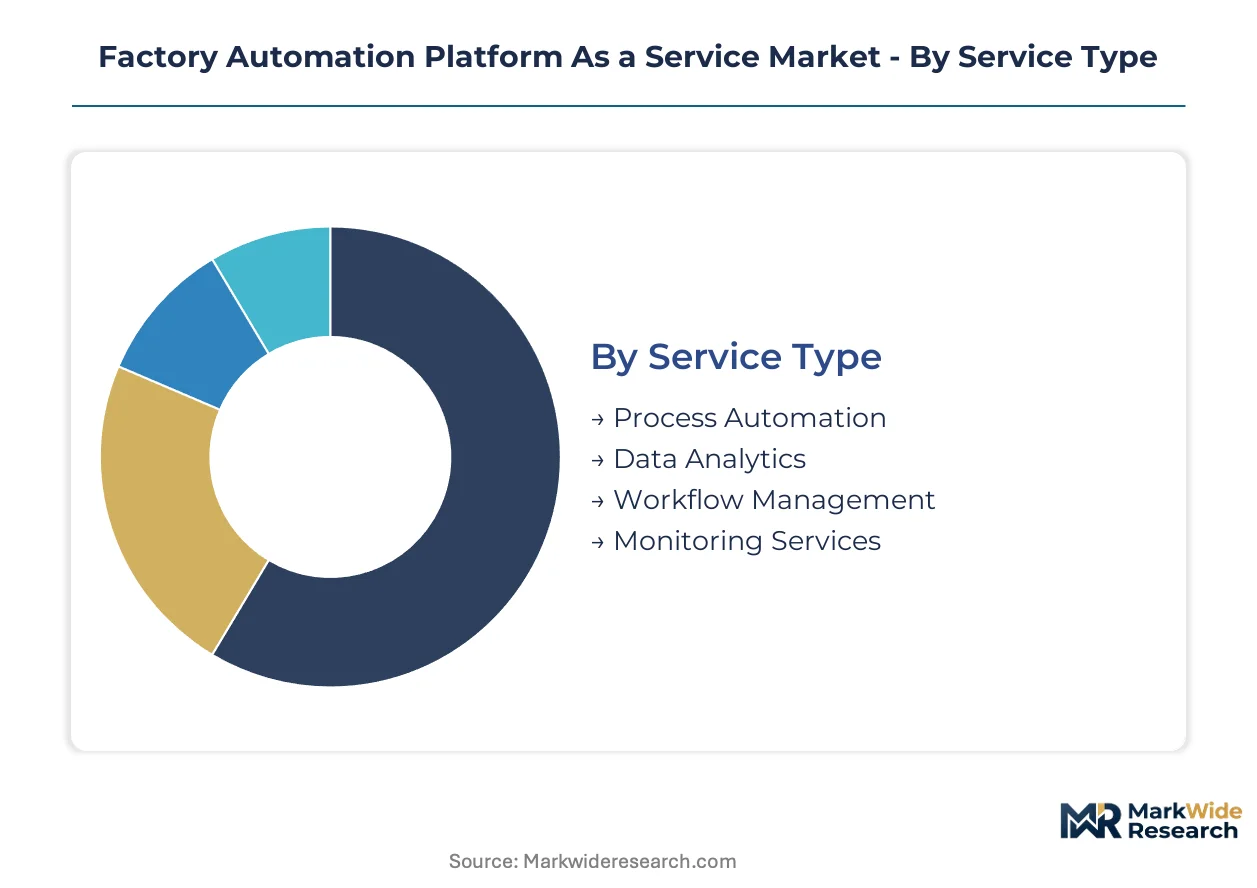
Factory Automation Platform As a Service procurement decisions hinge on latency requirements, data sovereignty constraints, and legacy system integration burdens. Segmentation reveals how these technical trade-offs split demand across deployment architectures and service tiers.
Service Type:
Buyers prioritize modules based on operational criticality and recurring value capture potential.
- Process Automation:Cloud-native SCADA and MES functions delivered via API with sub-100 millisecond response guarantees. German automotive OEMs anchor demand here, driven by KBA certification requirements for traceable production control.
- Data Analytics:Predictive maintenance and energy optimization algorithms operating on historical and real-time telemetry streams. Food and beverage processors in Japan are expanding subscriptions fastest under METI smart factory incentives.
- Workflow Management:Digital work instruction and quality checklist orchestration for shop-floor personnel.
- Monitoring Services:Uptime assurance and anomaly detection dashboards with tiered SLA commitments.
Volume sits with Process Automation; growth tilts toward Data Analytics.
Deployment Model:
Latency thresholds and regulatory jurisdiction dictate infrastructure placement across the stack.
- Hybrid Cloud:Critical control loops remain on-premises while analytics workloads shift to public infrastructure. This configuration captures the largest revenue share as manufacturers reconcile real-time determinism with cloud scalability.
- Public Cloud:Fully offloaded platform instances with ISO 27001-certified tenant segregation. Electronics manufacturers in India favor this model for greenfield PLI-funded facilities lacking legacy equipment.
- Private Cloud:Dedicated single-tenant deployments for pharmaceutical manufacturers facing FDA software validation requirements.
- On-Premises:Air-gapped installations for nuclear and chemical facilities with hard operational technology isolation mandates.
Revenue concentrates in Hybrid Cloud; Public Cloud climbs the fastest among new facility deployments.
End User:
Technical sophistication and integration risk tolerance segment the buyer base.
- Manufacturers:Direct platform subscribers seeking to compress automation procurement from capital-intensive hardware cycles to operational expenditure models.
- System Integrators:Intermediaries bundling platform subscriptions with custom engineering services for brownfield retrofit projects.
- OEMs:Machinery builders embedding platform connectivity as standard equipment features, particularly German automotive tier-one suppliers standardizing multi-site architectures.
- Maintenance Providers:Third-party service firms leveraging predictive analytics modules to transform break-fix contracts into outcome-based availability agreements.
Subscription volume flows through Manufacturers; System Integrators are expanding platform reach fastest into legacy facilities.
Industry Vertical:
Regulatory intensity and production velocity shape vertical adoption patterns.
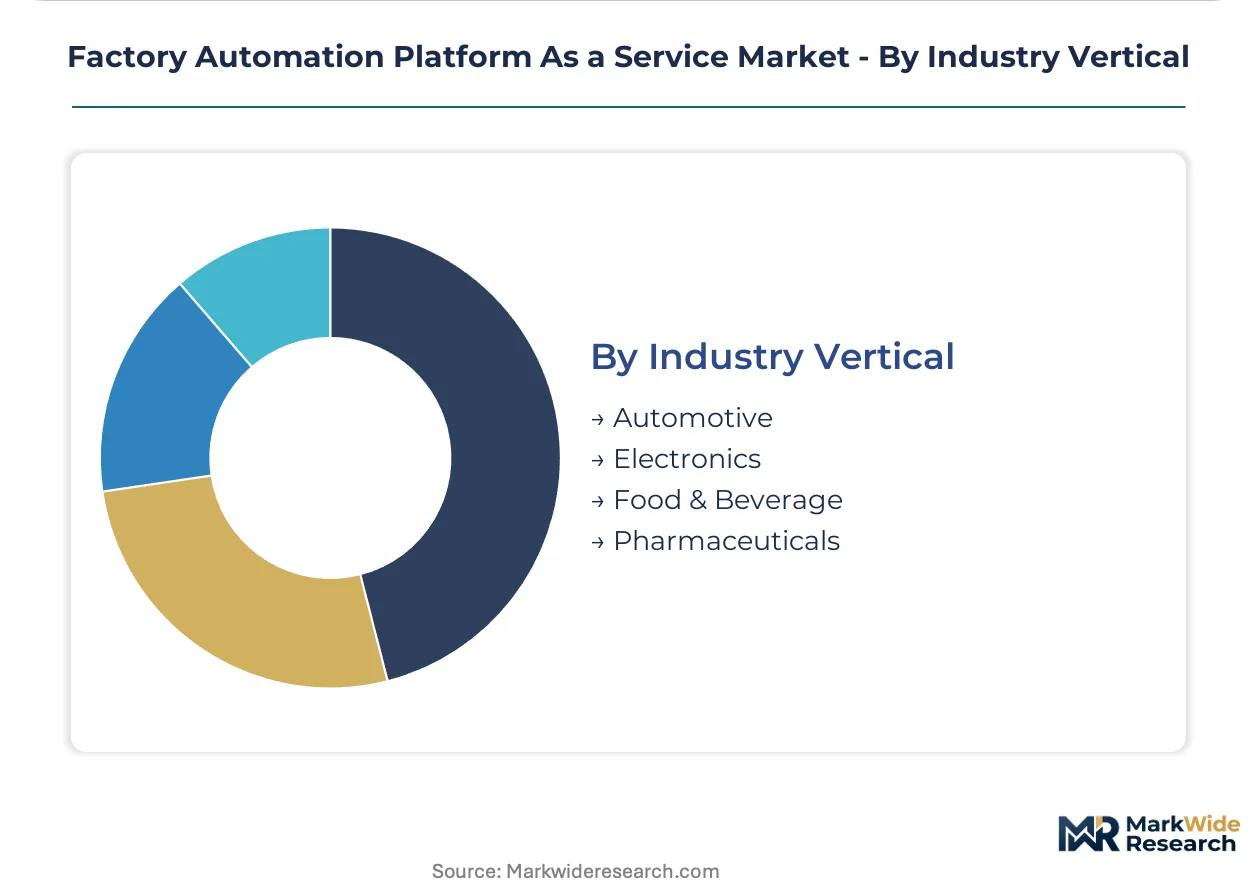
- Automotive:High-volume discrete manufacturing with synchronized multi-site production networks. Volkswagen, BMW, and Mercedes-Benz standardization initiatives are consolidating platform selection authority at the OEM level.
- Pharmaceuticals:Batch process environments with FDA software validation and EU AI Act algorithmic transparency mandates. Compliance documentation requirements favor auditable platform architectures over legacy black-box controllers.
- Electronics:Rapid product cycle manufacturing with cleanroom and precision assembly requirements.
- Food & Beverage:Hygienic processing with emerging predictive maintenance penetration through vibration analysis and thermal imaging AI services.
Automotive commands the largest vertical share; Pharmaceuticals show the steepest expansion trajectory as regulatory deadlines tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform subscription volume concentrates in Germany, where automotive OEM consolidation and KBA certification requirements are compressing procurement cycles. Japan and India follow as distinct growth vectors shaped by METI smart factory subsidies and PLI scheme greenfield investments respectively.
Germany
Volkswagen, BMW, and Mercedes-Benz are standardizing shared automation architectures across multi-site production networks. The KBA mandates traceable algorithmic systems for safety-critical manufacturing controls. Stuttgart and Munich machinery clusters are embedding ECHA database APIs directly into maintenance workflows to satisfy REACH substance tracking requirements.
United States
Discrete manufacturers in automotive and electronics verticals are migrating from 7-year capital depreciation to 3-year operational expenditure models. FDA software validation requirements for pharmaceutical producers favor auditable platform architectures over legacy black-box controllers. Detroit-area automotive tier-one suppliers are piloting microservice-based SCADA decompositions at new greenfield lines.
Japan
METI smart factory subsidies explicitly favor recurring platform contracts over traditional CAPEX grants, accelerating behavioral pivots among mid-sized manufacturers. JIS standards for functional safety certification create compliance moats for certified providers. Osaka and Nagoya industrial corridors are expanding predictive maintenance subscriptions fastest among food and beverage processors.
India
Electronics and automotive manufacturing incentives under the PLI scheme are attracting greenfield facilities with native cloud automation architectures. BIS certification requirements for industrial equipment are aligning with international ISO frameworks. Karnataka and Tamil Nadu industrial zones are favoring public cloud deployments lacking legacy equipment integration burdens.
South Korea
Semiconductor and display panel manufacturers are driving demand for sub-50 millisecond deterministic control via OPC UA over TSN protocols. MFDS pharmaceutical manufacturing regulations are tightening algorithmic transparency mandates for batch process environments. Seoul Capital Area and Busan-Ulsan production clusters are standardizing on hybrid cloud configurations retaining critical control loops on-premises.
Factory Automation Platform As a Service Market Vendor Landscape
German producers anchor the premium-tier positioning through digital twin and process automation portfolios; US specialists hold cloud infrastructure and discrete manufacturing verticals. The vendor structure compresses into three strategic archetypes: diversified industrial conglomerates with automation divisions, pure-play cloud platform providers, and embedded software specialists. Competitive moves center on restructuring perpetual hardware licensing into recurring platform subscriptions and securing functional safety certifications for cloud-connected control systems.
Within the diversified industrial tier, Siemens AG and ABB Ltd. exemplify European conglomerate positioning anchored in process automation heritage and certification depth. Rockwell Automation Inc. occupies the discrete manufacturing specialist position with FactoryTalk platform specialization. Microsoft Corporation represents the cloud-native archetype extending infrastructure dominance through Azure IoT capability embedding.
| Leading Market Players |
|---|
| Rockwell Automation Inc. |
| Schneider Electric SE |
| Siemens AG |
| Hitachi Ltd. |
| Honeywell International Inc. |
| Microsoft Corporation |
| ABB Ltd. |
| Mitsubishi Electric Corporation |
| PTC Inc. |
| Others |
Supply Flow & Price Mechanics
German automotive OEM procurement consolidation at Volkswagen, BMW, and Mercedes-Benz anchors subscription pricing power for Factory Automation Platform As a Service vendors, compressing negotiation leverage toward multi-site enterprise licensing rather than per-facility transactional models.
Pricing Analysis
Short lead-time premiums for IEC 61508-certified safety modules command substantial markups over standard process automation tiers. Three-tier pricing structure across premium-certified, standard-compliant, and economy-unbundled levels differentiates by functional safety grade and API integration depth. Cost compression in economy tiers is intensifying because Indian PLI-funded greenfield facilities favor public cloud spot deployments without legacy migration overhead. Mid-sized discrete manufacturers in Japan exhibit highest price sensitivity under METI subsidy constraints, while pharmaceutical OEMs in Germany show lowest sensitivity due to EU AI Act compliance mandates.
Supply Chain Analysis
Workforce scarcity for OT-IT cross-trained engineers in Taiwan, South Korea, and Germany constrains gateway hardware production scaling for platform providers. Industrial-grade FPGA and ASIC sourcing draws from Taiwanese and South Korean foundries, with embedded software development concentrated in German automation clusters and US cloud infrastructure hubs. Single-source vulnerability in semiconductor fabrication creates supply chain risk for deterministic control hardware. Distribution runs through system integrator intermediaries for brownfield retrofit projects, while direct platform subscriptions dominate greenfield deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory Automation Platform As a Service competition is becoming a vertical-integration race, with cloud infrastructure providers pursuing backward integration into edge hardware and industrial conglomerates embedding proprietary silicon.
For Market Incumbents: Acquire edge hardware gateway capabilities to secure supply chain autonomy against semiconductor foundry concentration. Siemens AG and Rockwell Automation Inc. must accelerate functional safety certification timelines for cloud-connected control systems to defend against pure-play cloud entrants. Certification depth in IEC 61508 and ISO 13849 compliance creates defensive moats as EU AI Act deadlines tighten. For New Entrants and Emerging Players: Capture predictive maintenance module white space in food and beverage processing, a vertical previously underserved by industrial IoT platforms. Indian PLI-funded electronics manufacturing clusters offer the most penetrable geography for native cloud architectures without legacy equipment integration burdens. Partner with system integrators for brownfield retrofit channel access rather than direct manufacturer sales. For Investors and Strategic Acquirers: The window for entry favors pure-play cloud platform providers with embedded AI capabilities over diversified industrial hardware incumbents. Long-term viability hinges on functional safety certification depth and multi-tenant infrastructure scale. Watch OPC UA over TSN protocol adoption rates as the inflection signal for deterministic cloud control market readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Investment | IEC 61508 compliance for cloud-connected systems creates regulatory moats in EU automotive verticals. |
| Edge Hardware Gateway Acquisition | Backward integration into FPGA sourcing mitigates Taiwanese foundry concentration risk. |
| Predictive Maintenance Module Launch | Vibration analysis AI services penetrate food and beverage processing under METI incentives. |
| Hybrid Cloud Infrastructure Expansion | Sub-50 millisecond latency guarantees via OPC UA over TSN capture German automotive demand. |
| System Integrator Channel Partnership | Brownfield retrofit access accelerates platform penetration in 20-30 year-old facilities. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Factory Automation Platform As a Service analysis. Primary interviews with automation platform engineers, plant maintenance directors, OEM procurement teams, and system integrator technical leads combined with bottom-up and top-down triangulation. Secondary validation drew from KBA certification databases, ECHA REACH substance registries, METI smart factory subsidy disclosures, and BIS industrial equipment standards.
Data-stream reconciliation across deployment model adoption rates, service type subscription volumes, and vertical penetration patterns informed the analytical framework. Segmentation dimensions modeled include service type, deployment architecture, end-user category, and industry vertical across the projection horizon. CAGRs were derived from curve-fitting historical platform subscription growth against regulatory deadline acceleration and greenfield facility investment cycles. OPC UA over TSN protocol deployment rates and EU AI Act compliance timeline adherence served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply chain disruptions and functional safety certification timeline extensions. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and cloud infrastructure latency improvement trajectories. Material deviation in IEC 61508 certification approval rates or Taiwan foundry capacity allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
Industrial Automation Services Market
Industrial Automation
Pick and Place Machines Market
Industrial Automation
North America Automated Storage and Retrieval System Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Global Warehouse Automation Market
Industrial Automation
South East Asia Warehouse Automation Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
Industrial Automation Motion Control System Software Market
Industrial Automation
North America Factory Automation and Industrial Controls Market
Industrial Automation
Mining Automation Solutions Market
Industrial Automation
India Warehouse Automation Market
Industrial Automation
Smart Manufacturing Devices Market