
 Warehouse Automation Solutions Market | 2026-2036
Warehouse Automation Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Warehouse Automation Solutions Market Analytics
Steel-reinforced aluminum framing is restructuring conveyor system economics by cutting weight without sacrificing load capacity. Daifuku leverages its captive manufacturing of precision drive components to protect margin pools in high-throughput sortation. SSI Schaefer anchors European retrofit demand through modular rack designs that integrate with legacy warehouse layouts. KNAPP competes on software-hardware convergence, embedding machine learning directly into pick-and-place robotics.
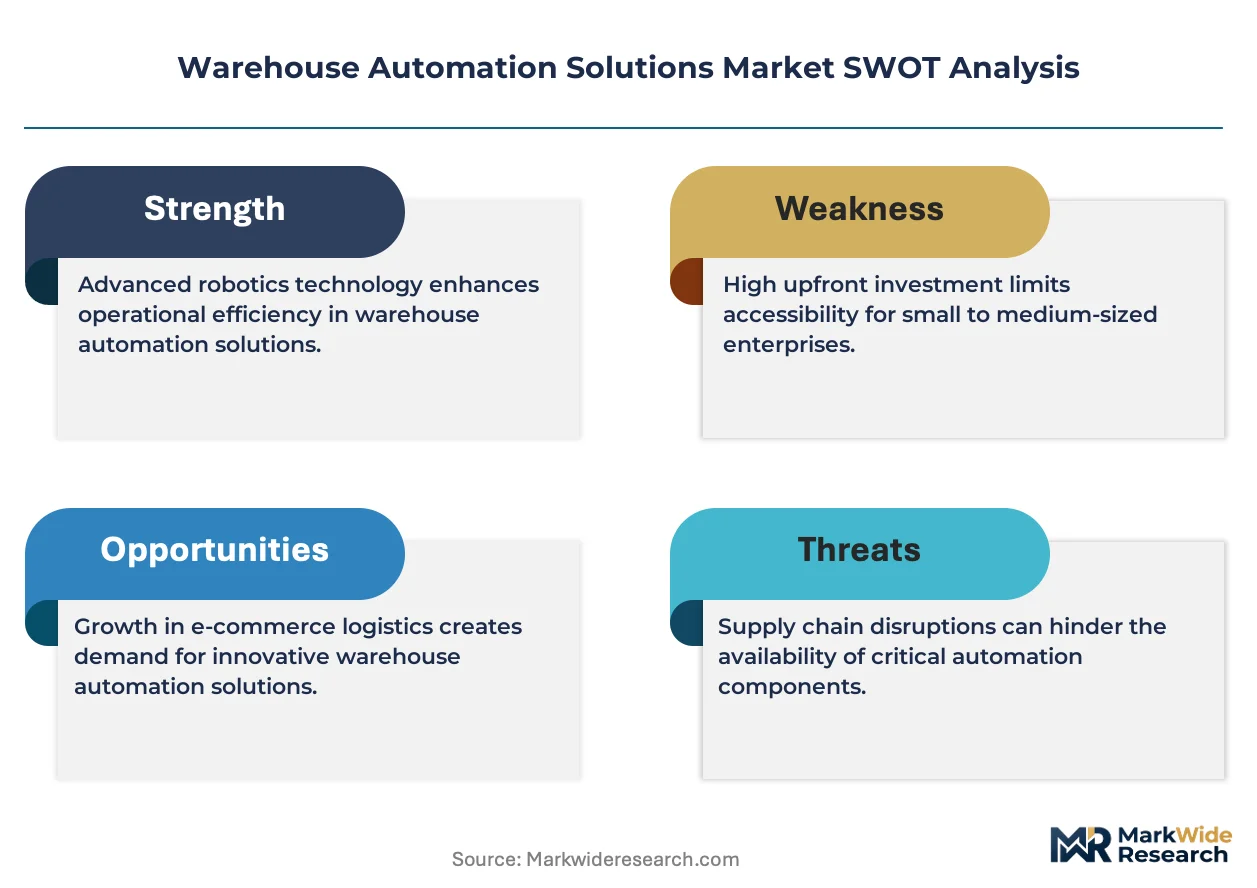
Warehouse automation solutions encompass electromechanical systems, control software, and sensor networks that execute storage, retrieval, sorting, and transport functions with minimal human intervention, typically operating at throughput rates exceeding 1,000 picks per hour in dense configurations. Their primary purpose is to compress order cycle times and eliminate picking errors in facilities where labor availability constrains volume scaling. Robots and automated guided vehicles capture the dominant share of product-type value, though sorting systems yield higher per-unit margins in parcel-heavy e-commerce operations. Machine learning and IoT technologies are expanding fastest as operators demand predictive maintenance and real-time inventory visibility, while cloud computing remains concentrated among mid-tier buyers seeking lower capital barriers.
FDA workplace ergonomics guidelines, OSHA material handling standards, and EU Machinery Directive safety certifications shape system design requirements and market access conditions for equipment deployed in food, pharmaceutical, and general logistics environments. Compliance with these frameworks adds engineering cost but creates preference windows for vendors with pre-certified platform architectures. Stakeholders must weigh retrofit compatibility against greenfield optimization as facility age profiles diverge across regional warehouse stocks.
Market Dynamics
Robotic picking systems are compressing order cycle times in e-commerce fulfillment centers, forcing incumbent conveyor manufacturers to defend throughput benchmarks through software-hardware convergence rather than mechanical refinement alone.
Growth Catalysts
- OSHA material handling standards:Stricter workplace safety mandates in US distribution facilities are accelerating replacement of manual palletizing workflows with automated guided vehicles and collaborative robot arms.
- Pharmaceutical logistics clusters:Temperature-sensitive cold chain requirements in Germany's Rhine-Ruhr corridor are driving integrated system deployments that combine automated storage with real-time environmental monitoring.
- Machine learning:Predictive maintenance algorithms embedded in sortation controllers are reducing unplanned downtime in high-volume parcel hubs, converting capital expenditure into operational reliability metrics.
Market Restraints
- Steel and rare-earth magnet costs:Volatility in neodymium pricing and structural steel tariffs are compressing margins for robotic actuator and conveyor frame producers.
- EU Machinery Directive certification timelines:Multi-month safety validation protocols for autonomous mobile robots are extending sales cycles and freezing budget allocations in European retrofit projects.
- Manual picking labor pools:Persistent availability of low-cost warehouse labor in Eastern European markets is delaying automation adoption among mid-tier third-party logistics operators.
Strategic Opportunities
- India's PLI scheme for advanced manufacturing:Production-linked incentives for electronics and automotive sectors are creating greenfield warehouse demand in Pune and Chennai industrial corridors.
- Cloud-native warehouse management platforms:Subscription-based control software is lowering capital barriers for mid-market 3PLs previously excluded from integrated automation.
- FDA workplace ergonomics guidelines:Compliance-driven retrofit mandates in US food and beverage distribution are opening replacement cycles for aging material handling infrastructure.
Industry Challenges
- Mechatronics engineering talent scarcity:Shortages of technicians capable of integrating PLCs, vision systems, and servo drives are extending commissioning timelines and inflating implementation costs.
- Legacy WMS interoperability:Proprietary data protocols in decade-old warehouse management systems are forcing costly middleware development for brownfield automation deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warehouse Automation Solutions Market |
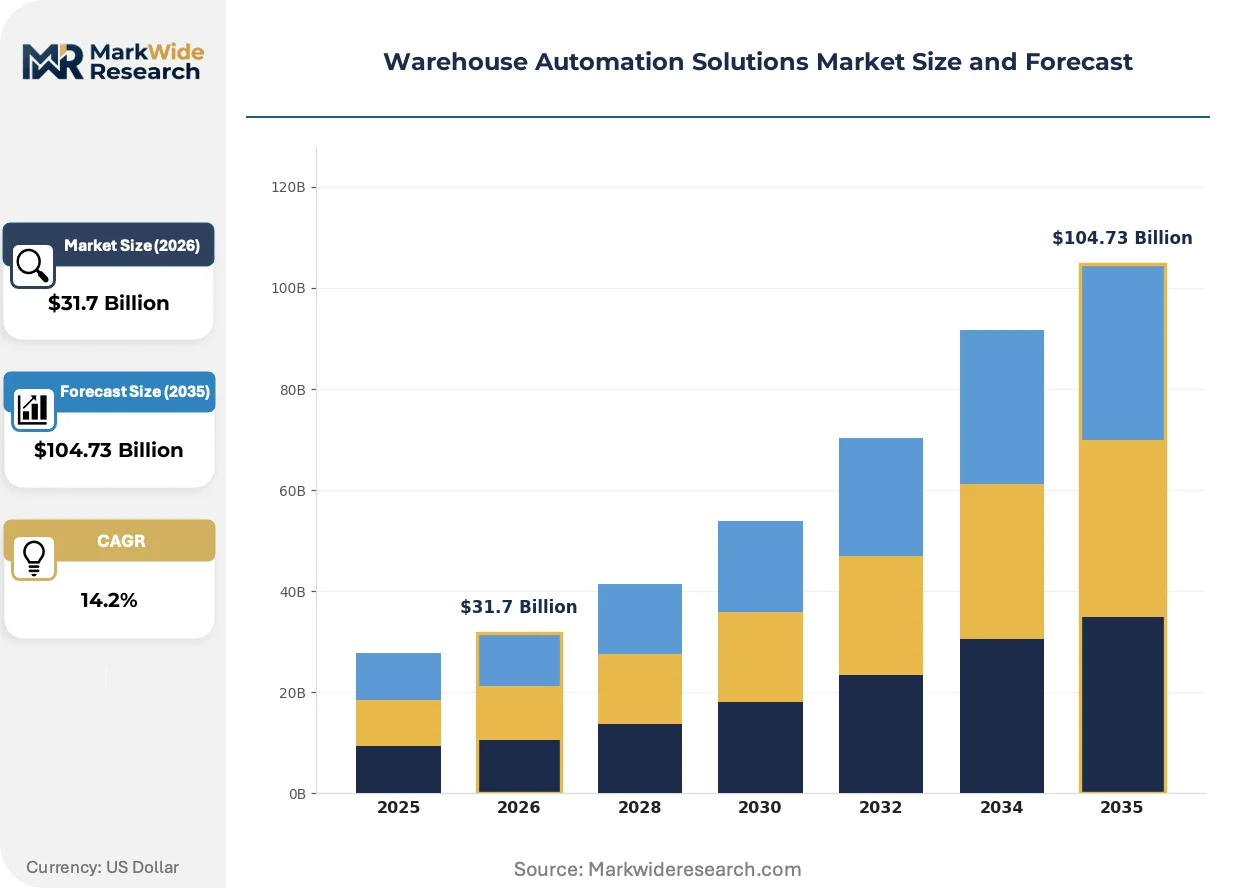
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $104.73 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robots, Automated Guided Vehicles, Sorting Systems, Conveyors Technology: Machine Learning, IoT, Cloud Computing, RFID End User: E-Commerce, Retail, Manufacturing, Logistics Installation: New Build, Retrofit, Integrated Systems, Standalone |
| Companies Covered | Dematic, Daifuku, SSI Schaefer, KNAPP, Honeywell Intelligrated, Swisslog, AutoStore, Murata Machinery, TGW Logistics Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warehouse Automation Solutions Market Evolving Landscape
Electrification of drive systems and convergence of edge computing with robotic controllers are redefining throughput economics, shifting competitive advantage from mechanical engineering to software-defined orchestration.
Autonomous mobile robots equipped with lithium-ion battery packs and regenerative braking are electrifying material transport workflows in multi-zone fulfillment facilities. Grocery and apparel e-commerce operators are deploying these systems at 300-unit-plus fleet scales to eliminate fixed conveyor infrastructure. The technology is electrifying capital allocation patterns, converting permanent installations into reconfigurable mobile assets that follow demand volatility rather than predicting it.
REACH restrictions on perfluorinated compounds are forcing conveyor belt manufacturers to reformulate friction coatings and release agents used in high-speed sortation. Industrial consequence includes accelerated qualification of bio-based polymer alternatives and supply chain requalification costs for European OEMs. Pharmaceutical and food-grade conveyor deployments in Germany and the Netherlands are most affected, with buyers demanding pre-certified material passports to avoid downstream compliance liability.
After-sales service unbundling is fragmenting traditional automation vendor relationships in North American parcel networks. Large e-commerce operators are insourcing preventive maintenance and predictive analytics while purchasing hardware on capital-only terms, displacing bundled service contracts. This pattern is most visible in California and Texas fulfillment corridors where dedicated reliability engineering teams have achieved scale sufficient to self-perform.
Warehouse Automation Solutions Market Segmentation
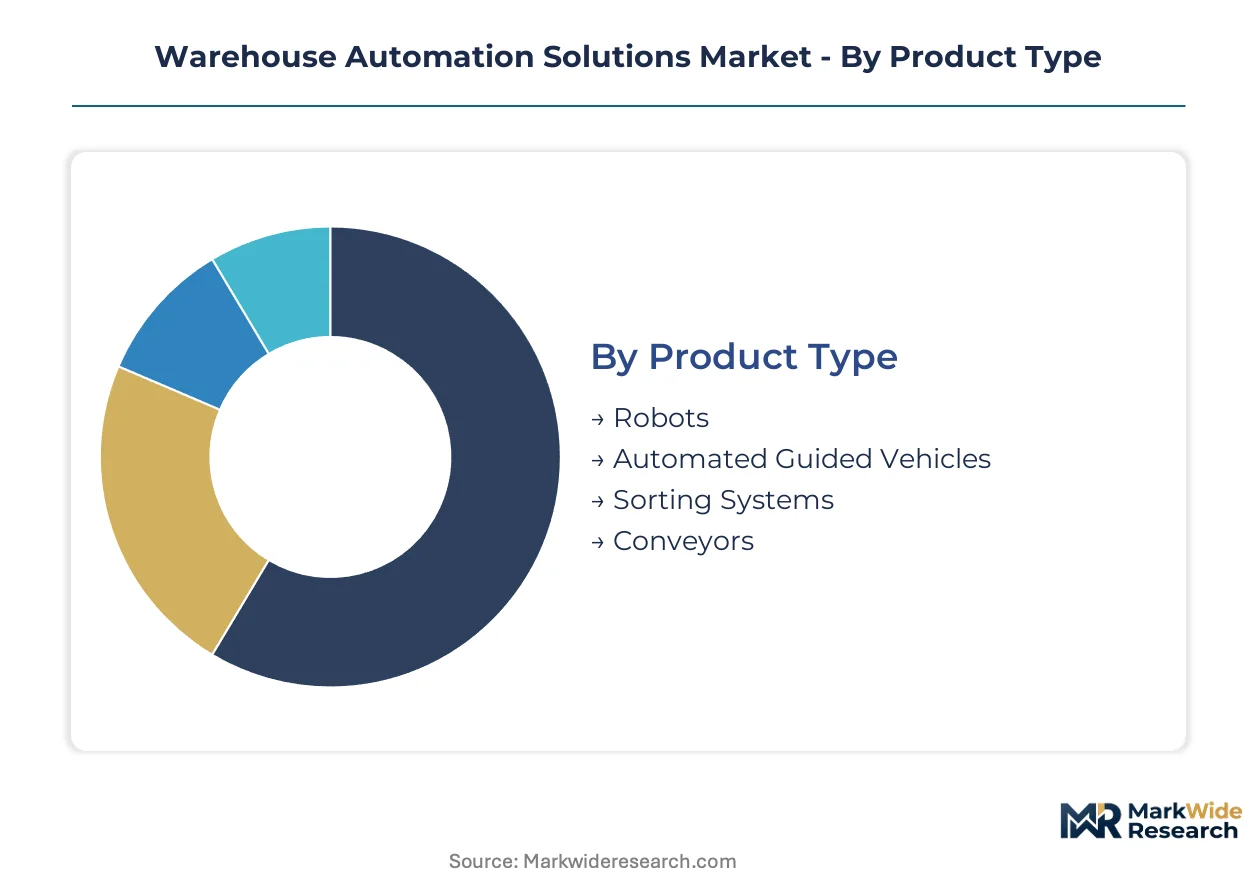
Warehouse automation solutions fragment across four dimensions that determine procurement patterns and vendor selection criteria. Product type and technology choices dictate capital intensity and compliance burden, while end-user verticals and installation modes shape implementation timelines and integration complexity.
Product Type:
Certification requirements diverge sharply across this category, with EU Machinery Directive safety validation mandatory for autonomous mobile robots and collaborative arms deployed in European facilities, while conveyor and sortation systems face lighter conformity assessment procedures.
- Robots:Articulated and SCARA configurations execute pick-and-place operations at sustained rates exceeding human throughput benchmarks. Demand concentrates in German pharmaceutical logistics clusters where FDA workplace ergonomics guidelines and EU Machinery Directive certifications create dual compliance overhead for cold-chain deployments.
- Automated Guided Vehicles:Lithium-ion powered mobile platforms transport palletized loads across multi-zone fulfillment facilities without fixed infrastructure. California and Texas e-commerce corridors are scaling fleet deployments beyond 300 units per site, converting capital expenditure into reconfigurable operational assets that track demand volatility.
- Sorting Systems:High-speed tilt-tray and cross-belt configurations handle parcel throughput in express delivery hubs.
- Conveyors:Steel-reinforced aluminum frame designs predominate in greenfield installations seeking weight reduction without load capacity sacrifice.
Leading the category by volume: Automated Guided Vehicles. Expanding most quickly: Robots.
Technology:
Cost tiers separate this category, with cloud-native platforms offering subscription-based entry points for mid-market buyers while edge-deployed machine learning and IoT architectures command premium pricing for predictive maintenance capabilities.
- Machine Learning:Embedded algorithms in sortation controllers and robotic vision systems enable real-time anomaly detection and adaptive path planning. E-commerce fulfillment operators in North America are prioritizing these capabilities to compress order cycle times and eliminate picking errors at scale.
- IoT:Sensor networks deliver real-time inventory visibility and environmental monitoring across distributed warehouse estates. Germany's automotive and pharmaceutical logistics clusters drive integrated system deployments combining automated storage with temperature-sensitive cold chain oversight.
- Cloud Computing:Subscription-based control software lowers capital barriers for mid-tier 3PLs previously excluded from integrated automation.
- RFID:Item-level tracking infrastructure supports high-accuracy inventory reconciliation in apparel and electronics fulfillment.
Machine Learning commands premium pricing tiers. Cloud Computing is climbing the fastest among cost-conscious buyers.
End User:
Application context determines performance specifications and regulatory exposure across this category, with pharmaceutical and food-grade deployments facing stricter material certification and traceability mandates than general merchandise operations.
- E-Commerce:Fulfillment centers demand robotic picking systems capable of handling heterogeneous SKU profiles at throughput rates exceeding 1,000 picks per hour. North American and European operators are accelerating adoption as labor shortages and OSHA material handling standards pressure distribution workflows toward automation.
- Retail:Omnichannel distribution networks require flexible automation that accommodates seasonal demand swings and store replenishment alongside direct-to-consumer fulfillment.
- Manufacturing:Just-in-time production lines depend on automated storage and retrieval for component sequencing and work-in-process buffering.
- Logistics:Third-party operators balance retrofit compatibility against greenfield optimization as facility age profiles diverge across regional warehouse stocks.
E-Commerce dominates absolute deployment value. Logistics represents the steepest expansion trajectory as 3PLs modernize aging infrastructure.
Installation:
Customer type and facility vintage split this category, with established operators prioritizing brownfield integration to preserve existing warehouse management system investments while new entrants pursue optimized greenfield configurations.
- New Build:Purpose-designed automation architectures maximize throughput density and minimize commissioning timelines in facilities constructed without legacy constraints. India's PLI scheme for advanced manufacturing is generating greenfield warehouse demand in Pune and Chennai industrial corridors.
- Retrofit:Modular rack designs and middleware solutions enable automation integration with decade-old warehouse layouts. SSI Schaefer anchors European retrofit demand through designs that accommodate proprietary data protocols in legacy WMS environments.
- Integrated Systems:Combined hardware-software deployments from single vendors reduce interoperability risk.
- Standalone:Point solutions address specific bottlenecks without enterprise-wide automation commitment.
New Build leads capital allocation. Retrofit is gaining share fastest as facility modernization cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's automotive and pharmaceutical logistics clusters, with the Rhine-Ruhr corridor driving integrated system deployments that combine automated storage with real-time environmental monitoring.
United States
California and Texas e-commerce corridors are scaling autonomous mobile robot fleets beyond 300 units per site, converting capital expenditure into reconfigurable operational assets. OSHA material handling standards are accelerating replacement of manual palletizing workflows with automated guided vehicles. The FDA workplace ergonomics guidelines are opening replacement cycles for aging material handling infrastructure in food and beverage distribution centers across the Midwest.
Germany
Temperature-sensitive cold chain requirements in the Rhine-Ruhr pharmaceutical logistics corridor are driving integrated system deployments. EU Machinery Directive safety validation protocols are extending sales cycles for autonomous mobile robots while creating preference windows for pre-certified platform architectures. Automotive and pharmaceutical clusters in Baden-Württemberg and Bavaria are deploying large-scale integrated systems at throughput rates exceeding 1,000 picks per hour.
India
The PLI scheme for advanced manufacturing is generating greenfield warehouse demand in Pune and Chennai industrial corridors. Electronics and automotive sector incentives are attracting integrated automation vendors to establish local commissioning capabilities. Maharashtra and Tamil Nadu are emerging as concentration points for subscription-based control software adoption among mid-market 3PLs.
Japan
Just-in-time production lines in the Chubu and Kansai regions depend on automated storage and retrieval for component sequencing and work-in-process buffering. METI industrial efficiency standards are pressuring distribution operators to replace manual workflows with automated material handling. The Kanto region around Tokyo hosts dense concentrations of robotics-integrated fulfillment centers serving domestic e-commerce demand.
United Kingdom
Omnichannel retail distribution networks in the Midlands and Southeast require flexible automation accommodating seasonal demand swings. REACH restrictions on perfluorinated compounds are forcing conveyor belt manufacturers to reformulate friction coatings for pharmaceutical and food-grade deployments. London-area parcel hubs are prioritizing predictive maintenance algorithms to reduce unplanned downtime in high-volume sortation operations.
Warehouse Automation Solutions Market Competitive Landscape
Software-hardware convergence dominates the current landscape as incumbent conveyor manufacturers defend throughput benchmarks against robotic picking systems. The vendor base stratifies across three tiers: diversified industrial conglomerates with captive component manufacturing, specialized automation integrators with modular platform architectures, and emerging cloud-native software vendors. Strategic archetypes include full-stack system providers, point-solution robotics specialists, and aftermarket service unbundlers. M&A activity and technology licensing agreements represent the dominant competitive moves as players seek predictive maintenance capabilities and edge-computing competencies.
Among diversified industrial conglomerates, Daifuku and Murata Machinery exemplify the captive manufacturing archetype, leveraging in-house production of precision drive components to protect margin pools in high-throughput sortation. SSI Schaefer occupies a position within the European retrofit specialist tier, anchoring demand through modular rack designs that integrate with legacy warehouse layouts. KNAPP sits within the software-hardware convergence vector, embedding machine learning directly into pick-and-place robotics to compress order cycle times in e-commerce fulfillment centers.
| Leading Market Players |
|---|
| Dematic |
| Daifuku |
| SSI Schaefer |
| KNAPP |
| Honeywell Intelligrated |
| Swisslog |
| AutoStore |
| Murata Machinery |
| TGW Logistics Group |
| Others |
Value Network & Pricing Analysis
REACH restrictions on perfluorinated compounds gate qualified supply for conveyor belt manufacturers serving European pharmaceutical and food-grade deployments, creating tiered access where pre-certified material passports command premium pricing while uncertified alternatives face buyer exclusion.
Pricing Analysis
Volume leadership sits with automated guided vehicles while robotic systems capture margin premiums through embedded machine learning capabilities. Three-tier pricing structure across premium, standard, and economy levels separates EU Machinery Directive-certified platforms from uncertified alternatives and basic conveyor configurations. Cost compression in standard-tier robotic actuators is intensifying because neodymium price volatility and structural steel tariffs squeeze component producers. Mid-market third-party logistics operators in Eastern Europe exhibit highest price sensitivity, whereas German automotive clusters prioritize throughput density over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from large e-commerce operators in California and Texas are forcing conveyor frame and precision drive component suppliers to qualify secondary manufacturing locations. Component production concentrates in Germany, Japan, and China, with steel-reinforced aluminum framing and lithium-ion battery packs as critical inputs. Single-source vulnerability in rare-earth magnet supply creates exposure to export restriction shocks. Distribution runs through captive manufacturing networks for diversified conglomerates and specialized automation integrators serving regional warehouse clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around software-hardware convergence capabilities, with mechatronics engineering talent scarcity forcing weaker mechanical-only vendors toward exit or acquisition.
For Market Incumbents: Cement defensive positions through captive manufacturing of precision drive components and embedded machine learning in pick-and-place robotics. Cloud-native software vendors threaten traditional hardware margins by unbundling after-sales service contracts. Backward integration into sensor networks and edge computing architectures protects margin pools against software-centric entrants. For New Entrants and Emerging Players: Enter via India's PLI scheme corridors in Pune and Chennai, where greenfield warehouse demand lacks established automation relationships. Subscription-based control software for mid-tier third-party logistics operators represents the most penetrable segment. Partner with local commissioning capabilities to overcome mechatronics talent scarcity in rapid deployment scenarios. For Investors and Strategic Acquirers: After-sales service unbundling announcements by major North American e-commerce operators is the leading indicator that hardware-only valuations are compressing while predictive analytics capabilities command acquisition premiums. Five-to-ten year viability favors vendors with integrated software-hardware platforms over point-solution mechanical specialists. Watch for EU Machinery Directive certification backlog clearance rates as the signal of European retrofit demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Hardware Convergence | KNAPP embeds machine learning directly into robotic controllers to compress order cycle times. |
| Captive Component Manufacturing | Daifuku protects margin pools through in-house production of precision drive systems. |
| Modular Retrofit Platform | SSI Schaefer anchors European demand through rack designs integrating with legacy WMS layouts. |
| Cloud-Native Control Software | Subscription platforms lower capital barriers for mid-market third-party logistics operators. |
| Predictive Maintenance Capability | Embedded algorithms in sortation controllers reduce unplanned downtime in parcel hubs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this warehouse automation solutions analysis, combined with primary interviews across warehouse operations directors, OEM procurement teams, mechatronics engineering leads, and aftermarket service heads. Secondary sources included OSHA enforcement databases, EU Machinery Directive certification registries, FDA workplace ergonomics guideline documentation, and SEC filings from diversified industrial conglomerates. Bottom-up installation data triangulated against top-down capital expenditure surveys across e-commerce fulfillment and pharmaceutical logistics verticals.
Data-stream reconciliation across product type, technology tier, end-user vertical, and installation mode segmentation drove analytical framework construction across the projection horizon. Modeled dimensions included robotic system configurations, automated guided vehicle fleet scales, machine learning deployment architectures, and brownfield versus greenfield implementation patterns. CAGRs derived from trajectory fitting against historical capital expenditure cycles and regulatory compliance deadline clustering. Forecast inputs incorporated PLI scheme incentive trajectories in India and REACH restriction phase-in timelines affecting conveyor belt formulations.
Revisions become necessary when rare-earth export restrictions, EU Machinery Directive certification timeline extensions, or labor pool availability shifts in Eastern European logistics markets materialize. Deviation in neodymium pricing volatility or steel tariff structures would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Europe SCADA Market
Industrial Automation
US Smart Manufacturing Market
Industrial Automation
Supervisory Control and Data Acquisition (SCADA) Market
Industrial Automation
Global Industrial Wireless Automation Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
Smart Manufacturing Devices Market
Industrial Automation
Linear Motion System Market
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Latin America Laboratory Automation Market
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market
Industrial Automation
Material Handling Robotics Market
Industrial Automation
China Factory Automation and Industrial Controls Market
Industrial Automation
Middle East Programmable Logic Controller (PLC) Market
Industrial Automation
Global Electric Gripper Market
Industrial Automation
Refining Industry Automation and Software Market
Industrial Automation
Intelligent Conveyor System Market