
 SCADA Alarm Management Market | 2026-2036
SCADA Alarm Management Market Size, Share, and Industry Trends Forecast 2026-2036
SCADA Alarm Management Market Analytics
North American industrial software vendors is consolidating around platforms that unify SCADA alarm data with enterprise asset management. Schneider Electric leverages its EcoStruxure architecture to bridge edge analytics with centralized alarm lifecycle tools. Siemens anchors its position through deep integration between WinCC and process safety systems. ABB competes by extending Ability Genix into predictive alarm correlation for power generation clients.
SCADA alarm management encompasses the systematic design, prioritization, suppression, and response coordination of abnormal situation notifications within supervisory control architectures. The discipline employs alarm rationalization methodologies, dynamic suppression algorithms, and operator response tracking to maintain situational awareness across distributed industrial processes. Cloud-based system types are gaining traction fastest as utilities seek elastic compute for alarm flood analysis without capital-intensive infrastructure. On-premises deployment models still dominate manufacturing environments where air-gapped security policies prevail and latency constraints preclude external connectivity. The oil and gas application segment commands premium pricing due to explosion-proof hardware requirements and SIL-rated safety system integration.
The US Environmental Protection Agency enforces leak detection and repair mandates that compel pipeline operators to maintain auditable alarm records with timestamp integrity. IEC 62682 and ISA-18.2 standards define alarm performance metrics including annunciation rates, operator workload limits, and shelving duration protocols that shape procurement specifications. OSHA process safety management rules in the United States require documented management of change procedures for alarm setpoint modifications. Stakeholders must weigh the trade-off between cloud-native scalability and deterministic latency guarantees when selecting next-generation alarm management platforms.
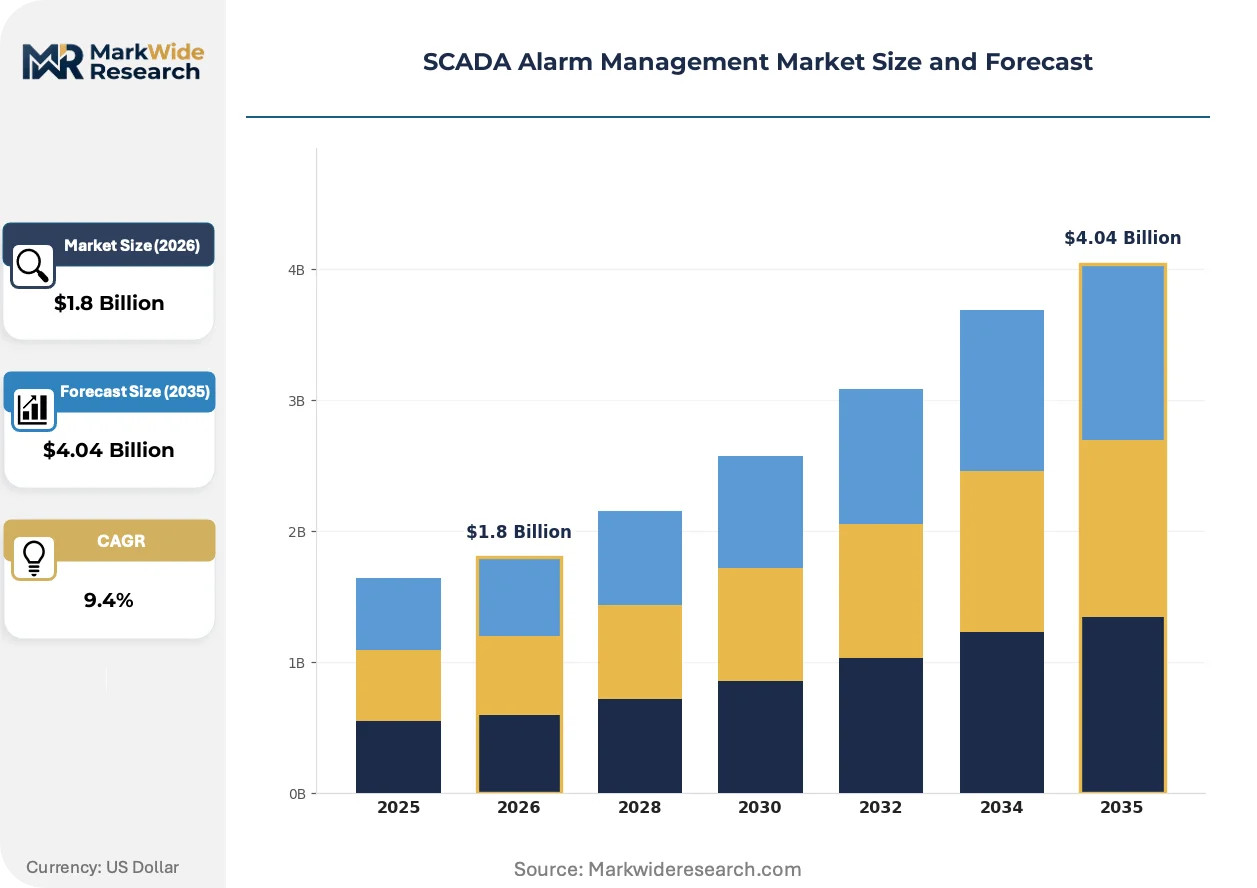
Market Dynamics
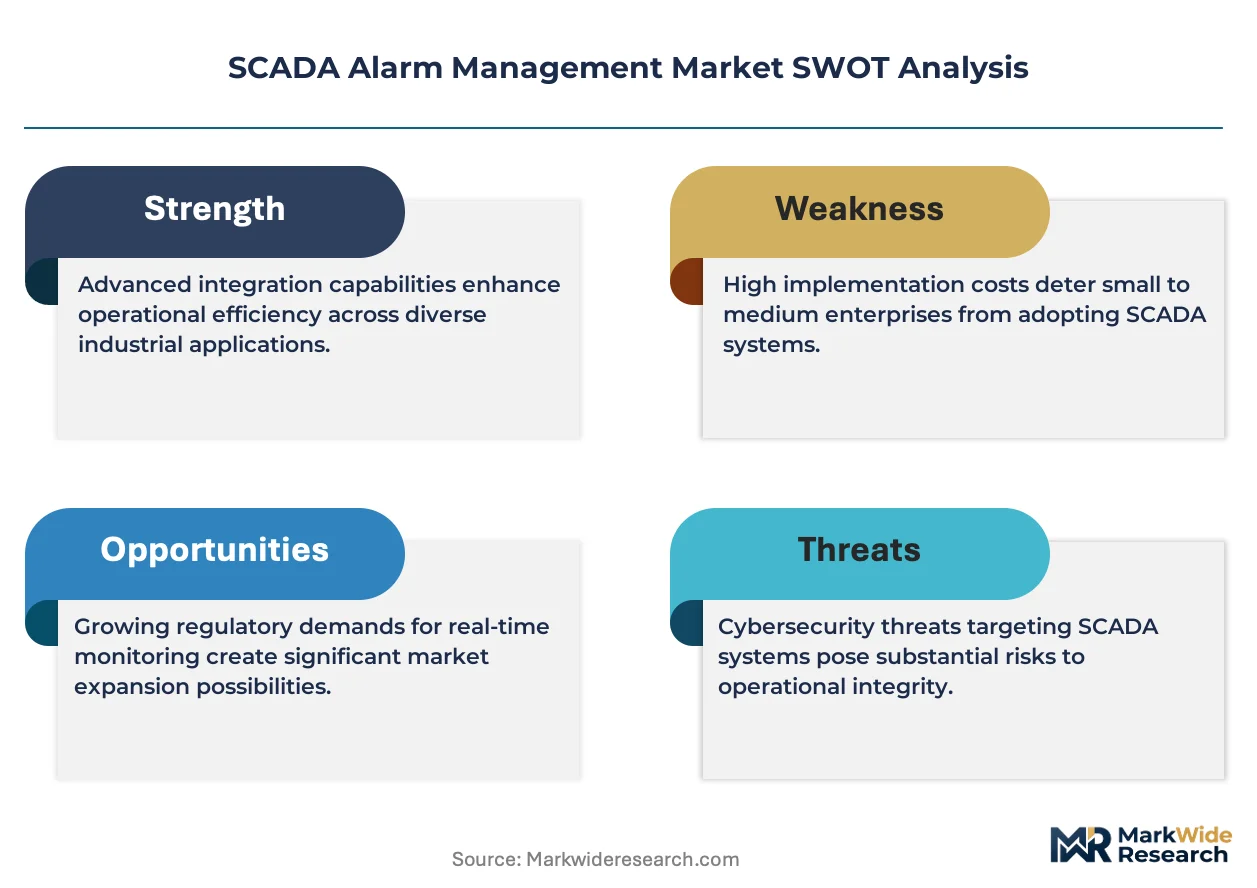
The SCADA alarm management sector faces acute pressure from IEC 62682 and ISA-18.2 compliance deadlines, which force asset operators to retire legacy alarm configurations and adopt dynamic suppression architectures that reduce operator cognitive load.
Growth Catalysts
- Pipeline leak detection mandates:EPA enforcement actions against midstream operators create immediate procurement urgency for auditable alarm lifecycle platforms with timestamp integrity guarantees.
- Power grid modernization:United States utilities facing NERC CIP reliability standards are rationalizing thousands of stale alarms to meet operator workload limits.
- Edge analytics maturation:Distributed computing architectures now enable real-time alarm flood analysis at substations and well pads without centralized latency.
Market Restraints
- SIL-rated integration costs:Oil and gas safety instrumented systems require explosion-proof hardware that multiplies deployment capital versus standard industrial automation.
- Air-gapped security policies:Defense and nuclear facilities in the United States prohibit external connectivity, blocking cloud-native alarm correlation tools.
- Legacy protocol fragmentation:Proprietary fieldbus implementations from the 1990s resist seamless migration to unified alarm management platforms.
Strategic Opportunities
- Predictive alarm correlation:Machine learning models trained on historical alarm sequences can identify precursor patterns to equipment failure before threshold breaches.
- Renewable generation integration:Wind and solar farms in Texas and California need new alarm hierarchies for inverter-based resources with fundamentally different fault signatures.
- Subscription-based deployment:Software-as-a-service models lower entry barriers for municipal water utilities with constrained capital budgets.
Industry Challenges
- Alarm rationalization expertise shortage:Few engineers possess combined domain knowledge of process safety, human factors psychology, and IEC 62682 documentation requirements.
- Management of change protocols:OSHA process safety management rules require exhaustive documentation for every setpoint modification, slowing operational adjustments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SCADA Alarm Management Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Network-based, Standalone, Cloud-based, Hybrid Application: Utilities, Manufacturing, Transportation, Oil & Gas Deployment Model: On-premises, Cloud, Managed Services, SaaS End User: Industrial, Energy, Healthcare, Water Treatment |
| Companies Covered | Schneider Electric, Rockwell Automation, ABB, Trihedral, Yokogawa, Siemens, Emerson, Inductive Automation, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SCADA Alarm Management Market Evolving Landscape
Alarm management technology is pivoting from static configuration toward adaptive systems that learn from operator response patterns. This shift redefines how industrial facilities balance safety integrity with operational agility.
Dynamic alarm suppression algorithms are converging with edge-deployed analytics to filter nuisance notifications before they reach control room operators. Water treatment utilities in the Great Lakes region are piloting these systems to reduce alarm floods during storm events. The technology is converging with mobile operator interfaces, enabling field technicians to acknowledge and investigate alarms without returning to central control rooms.
OSHA process safety management rules are tightening documentation requirements for alarm setpoint modifications across chemical processing facilities. The regulation now mandates electronic audit trails with version control for every rationalization decision. Refineries along the Gulf Coast are responding by embedding compliance workflows directly into alarm management software rather than maintaining separate documentation systems.
Utility procurement departments are unbundling alarm management software from bundled SCADA contracts to evaluate specialized vendors independently. This pattern disrupts traditional channel structures where automation integrators controlled specification authority. The shift is most visible among electric cooperatives in the Midwest seeking modular platforms that interoperate with existing DCS investments.
SCADA Alarm Management Market Segmentation
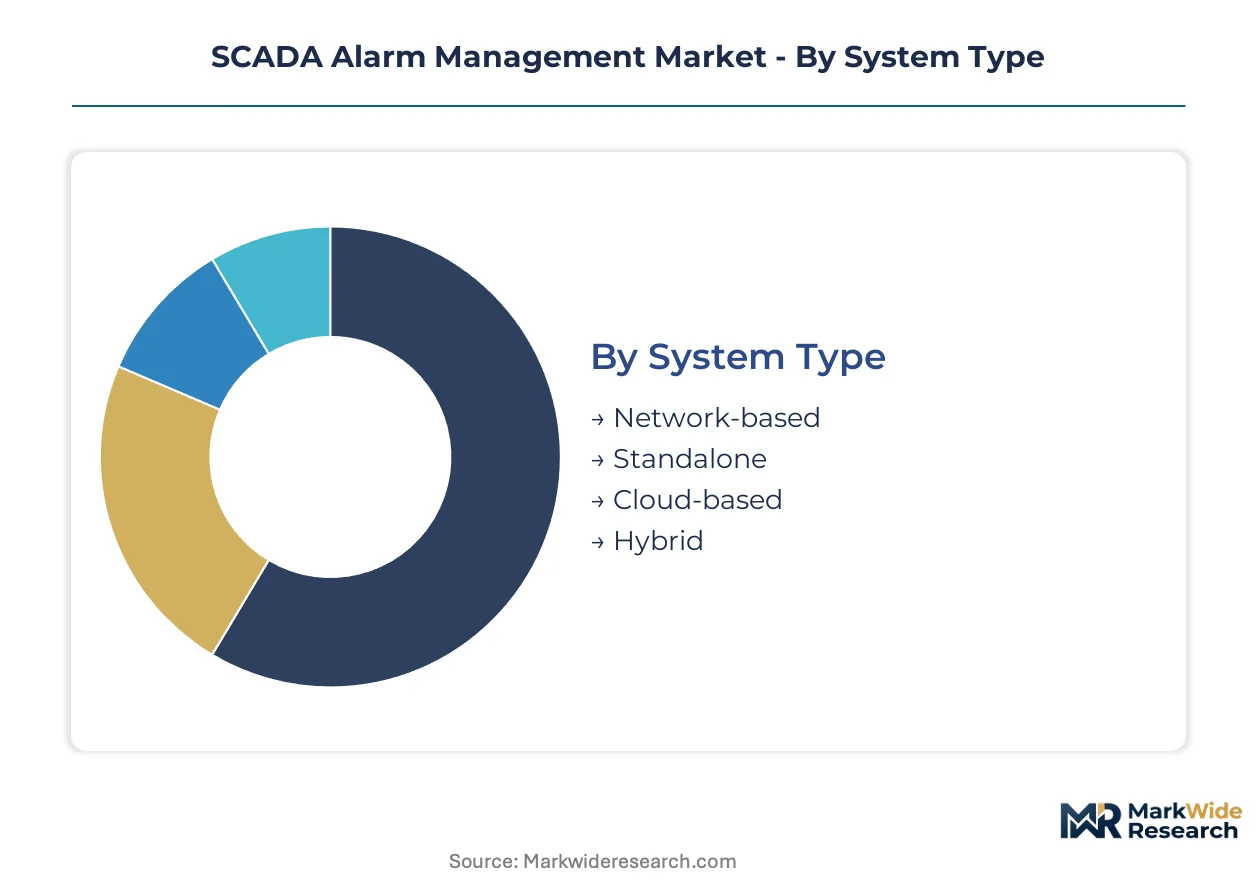
SCADA alarm management procurement varies sharply by infrastructure architecture, regulatory exposure, and operational criticality. Technology choices here determine compliance posture, latency tolerance, and integration complexity across industrial verticals.
System Type:
Architectural decisions hinge on connectivity constraints, compute distribution, and the balance between centralized oversight and edge autonomy.
- Cloud-based:Elastic compute resources enable alarm flood analysis without capital-intensive infrastructure builds. United States utilities facing NERC CIP workload mandates are migrating here fastest to rationalize alarm volumes during peak demand events.
- Hybrid:Combines air-gapped edge processing with cloud-based analytics for facilities with mixed security zones. Gulf Coast refineries deploy this architecture to satisfy OSHA process safety documentation requirements while enabling remote engineering access.
- Network-based:Distributed alarm servers across LAN segments serve manufacturing plants with legacy DCS investments.
- Standalone:Self-contained systems persist in nuclear and defense facilities where external connectivity is prohibited.
Cloud-based systems lead on momentum; hybrid architectures lead on strategic positioning for regulated environments.
Application:
End-use verticals impose distinct certification requirements, explosion-proofing standards, and integration protocols with safety instrumented systems.
- Oil & Gas:SIL-rated safety system integration and explosion-proof hardware multiply deployment complexity. Pipeline operators across Texas, North Dakota, and Alaska face EPA leak detection mandates that demand auditable alarm lifecycle records with timestamp integrity.
- Utilities:Electric power and water treatment operators rationalize thousands of stale alarms to meet operator workload limits. Midwest electric cooperatives are unbundling alarm software from bundled SCADA contracts to evaluate specialized vendors independently.
- Manufacturing:Discrete and process manufacturers prioritize deterministic latency over cloud elasticity, favoring on-premises architectures.
- Transportation:Rail signaling and port automation systems require fail-safe alarm hierarchies with millisecond response guarantees.
Oil & Gas commands premium pricing; Utilities represents the steepest expansion trajectory as grid modernization accelerates.
Deployment Model:
Commercial structures reflect capital availability, IT staffing levels, and the urgency of compliance deadlines.
- On-premises:Perpetual licensing with dedicated infrastructure dominates manufacturing and nuclear facilities where air-gapped security policies preclude external connectivity. Latency-sensitive applications in power generation require deterministic local processing.
- SaaS:Subscription models lower entry barriers for municipal water utilities with constrained capital budgets. Great Lakes water treatment operators pilot dynamic suppression algorithms through these platforms to reduce storm-event alarm floods.
- Cloud:Public cloud deployments concentrate among utilities seeking elastic compute for alarm analytics without infrastructure ownership.
- Managed Services:Outsourced alarm rationalization and lifecycle management appeals to midstream operators lacking in-house IEC 62682 expertise.
On-premises retains scale dominance; SaaS gains share fastest among capital-constrained municipal operators.
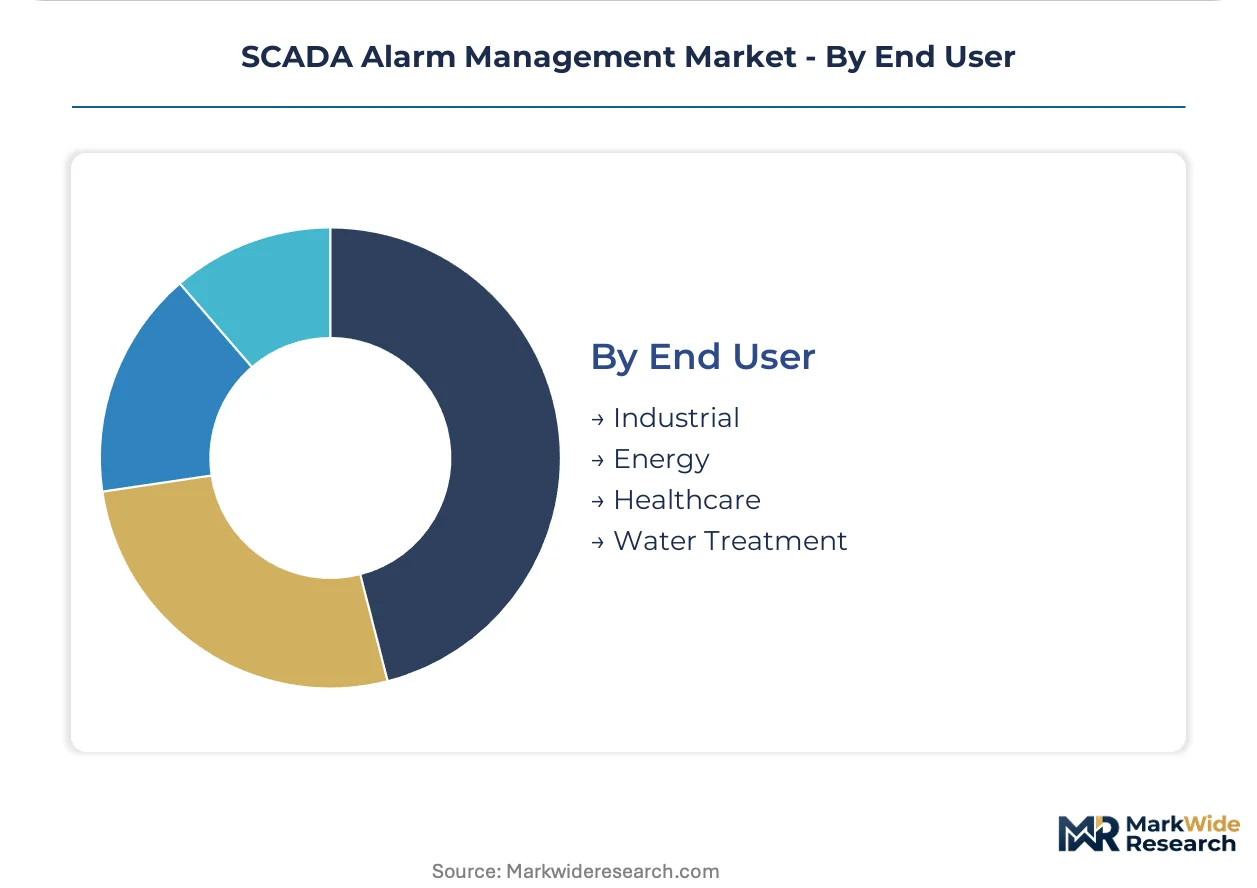
End User:
Operational environments shape alarm prioritization hierarchies, mobile workforce integration, and integration depth with enterprise asset management.
- Energy:Power generation and T&D operators face NERC CIP reliability standards requiring documented alarm performance metrics. Wind and solar farms in Texas and California need new hierarchies for inverter-based resources with fundamentally different fault signatures.
- Industrial:Chemical processing and heavy manufacturing facilities embed OSHA process safety management workflows directly into alarm software to satisfy electronic audit trail mandates.
- Water Treatment:Storm-driven alarm floods drive demand for dynamic suppression and mobile operator interfaces enabling field acknowledgment without control room return.
- Healthcare:Hospital campuses and medical device manufacturing apply alarm management to building automation and critical equipment monitoring with Joint Commission patient safety overlays.
Energy leads on revenue concentration; Water Treatment climbs fastest as infrastructure resilience investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping procurement patterns as operators migrate toward jurisdictions with clearer compliance pathways and enforceable standards. The cost-of-compliance gap between mature regulatory environments and emerging enforcement regimes drives concentration in markets where IEC 62682 and ISA-18.2 adoption carries both legal weight and operational credibility.
United States
Pipeline operators across Texas, North Dakota, and Alaska face EPA leak detection mandates that demand auditable alarm lifecycle records with timestamp integrity. OSHA process safety management rules require documented management of change procedures for every setpoint modification. Gulf Coast refineries embed compliance workflows directly into alarm software to satisfy electronic audit trail requirements.
Germany
Industrial conglomerates in the Ruhr Valley and Bavaria prioritize deterministic latency guarantees for manufacturing environments where air-gapped security policies prevail. The country's national industrial regulator enforces functional safety standards that align with IEC 62682 performance metrics. Chemical processing clusters along the Rhine River rationalize alarm hierarchies to meet operator workload limits.
China
State-owned power utilities in the Yangtze River Delta and Pearl River Delta modernize grid infrastructure under national dual carbon goals that mandate operational efficiency improvements. The Ministry of Ecology and Environment tightens emissions monitoring requirements that cascade into alarm system procurement specifications. Wind and solar farms in Inner Mongolia deploy new alarm hierarchies for inverter-based resources.
Japan
Precision manufacturers in the Chubu region around Nagoya demand millisecond-response alarm hierarchies for discrete automation systems. METI industrial standards emphasize human factors engineering in control room design that shapes alarm rationalization methodologies. Nuclear facilities in Fukushima and Niigata prefectures maintain standalone systems where external connectivity remains prohibited.
India
Municipal water utilities in Maharashtra and Gujarat pilot subscription-based alarm management platforms to overcome capital budget constraints. The Central Electricity Authority mandates reliability standards for grid operators that drive alarm rationalization programs. Petrochemical complexes in Gujarat's Dahej belt integrate SIL-rated safety systems with explosion-proof hardware requirements.
SCADA Alarm Management Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native architectures and predictive analytics capabilities. The vendor landscape concentrates around industrial automation incumbents with deep SCADA integration heritage and specialized software firms with modular interoperability. Three archetypes dominate: diversified automation conglomerates with bundled ecosystem plays, pure-play alarm management specialists with IEC 62682 expertise, and edge analytics vendors with distributed computing architectures. Competitive moves center on unbundling alarm software from bundled SCADA contracts and embedding compliance workflows directly into platform architectures.
Within the diversified automation tier, Schneider Electric and Siemens exemplify ecosystem-centric positioning through unified architecture plays that bridge edge analytics with centralized lifecycle tools. ABB occupies a position among predictive correlation specialists extending industrial data platforms into alarm flood analysis. Rockwell Automation and Honeywell sit within the North American incumbent archetype, anchoring positions through deep integration between control systems and process safety infrastructure. Emerson and Yokogawa represent the process industries specialist tier with heritage in SIL-rated safety system integration. Among modular software entrants, Inductive Automation and Trihedral exemplify interoperability-focused positioning that appeals to utilities unbundling procurement from legacy DCS investments.
| Leading Market Players |
|---|
| Schneider Electric |
| Rockwell Automation |
| ABB |
| Trihedral |
| Yokogawa |
| Siemens |
| Emerson |
| Inductive Automation |
| Honeywell |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up alarm management specialists have consolidated fragmented regional integrators across the United States and Germany, concentrating procurement leverage over SIL-rated hardware suppliers while enforcing pricing discipline through standardized SaaS-tiered offerings. This ownership pattern compresses distributor margins for legacy on-premises deployments while redirecting margin capture toward recurring subscription revenue streams.
Pricing Analysis
Distributor margins on bundled SCADA-alarm software contracts have compressed from traditional automation channels as utilities unbundle procurement to evaluate specialized vendors independently. Pricing stratifies across enterprise-grade platforms with full IEC 62682 compliance documentation, mid-tier solutions for municipal water operators, and economy configurations serving discrete manufacturing. Cost compression in the mid-tier is intensifying because SaaS entrants from cloud-native backgrounds undercut perpetual-license incumbents on total cost of ownership. Municipal water utilities in capital-constrained districts exhibit highest price sensitivity; Gulf Coast refineries facing OSHA electronic audit-trail mandates show lowest sensitivity due to compliance-driven procurement urgency.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and the United States Buy American provisions are reshaping sourcing patterns for explosion-proof enclosures and safety-rated processors. Manufacturing concentration centers on Germany for precision automation hardware, the United States for NERC CIP-certified edge computing modules, and Taiwan for industrial-grade semiconductors. Component dependencies rest on advanced FPGA chips for deterministic alarm processing, specialized analog-to-digital converters for field sensor integration, and hardened memory modules for timestamp integrity. Single-source vulnerability runs through Taiwan-based foundry capacity for safety-rated silicon. Distribution runs through automation integrators with certified IEC 62682 implementation expertise, though direct OEM relationships are gaining share among large utility accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SCADA alarm management market functions as a geographic-arbitrage play where operators migrate procurement toward United States jurisdictions with enforceable EPA leak-detection mandates and OSHA electronic audit-trail requirements, capturing compliance-premium pricing unavailable in enforcement-lagging regions.
For Market Incumbents: Cement market position by acquiring specialized IEC 62682 documentation consultancies to embed compliance workflows directly into platform architectures, countering the threat of modular software entrants unbundling alarm management from bundled SCADA contracts. Prioritize backward integration into edge analytics silicon to secure deterministic latency guarantees for power-utility substation deployments. For New Entrants and Emerging Players: Enter via subscription-based SaaS platforms targeting municipal water utilities in the Great Lakes region, where capital constraints and storm-driven alarm floods create immediate demand for dynamic suppression without infrastructure ownership. White-space concentration sits with renewable generation operators in Texas and California needing new alarm hierarchies for inverter-based resources with unfamiliar fault signatures. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play alarm management specialists with deep IEC 62682 expertise but limited geographic footprint, offering rollup potential into diversified automation platforms. Long-term viability hinges on regulatory enforcement trajectories across industrial jurisdictions. The signal to watch is EPA enforcement action intensity against midstream pipeline operators, which directly correlates with procurement urgency for auditable alarm lifecycle platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies edge analytics with centralized alarm lifecycle tools for NERC CIP compliance. |
| Acquisition of Specialist Firm | Absorbs IEC 62682 documentation expertise to embed compliance workflows directly. |
| Geographic Expansion | Targets municipal water utilities in India and the United States with SaaS entry points. |
| Product Launch | Introduces predictive alarm correlation trained on historical equipment failure sequences. |
| Strategic Partnership | Aligns with renewable developers in Texas for inverter-based resource alarm hierarchies. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with control room operators, SCADA integration specialists, utility procurement officers, and process safety engineers with secondary validation. Secondary sources drew from EPA enforcement databases, NERC CIP reliability filings, IEC 62682 documentation repositories, and industrial automation trade registers. Bottom-up segment sizing triangulated against top-down regulatory mandate tracking.
Rate-of-change decomposition separated baseline alarm system replacement demand from incremental compliance-driven procurement across the projection horizon. Segmentation dimensions modeled include system architecture, deployment model, application vertical, and end-user operational environment, with regulatory enforcement intensity treated as a cross-cutting sensitivity input. CAGRs were derived from elasticity-adjusted replacement cycles and mandate-compliance deadlines mapped to operator workload limits.
Inputs from EPA enforcement actions and utility capital expenditure disclosures were available through the study window; gaps in real-time alarm response telemetry from air-gapped nuclear facilities introduce uncertainty bands around edge-deployment share estimates. Forecasts reflect assumptions about IEC 62682 adoption trajectories and OSHA documentation rule enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Industrial Data Loggers Market
Industrial Automation
Internet of Things Enabled Industrial Wearables Market
Industrial Automation
Operational Predictive Maintenance Market
Industrial Automation
Latin America Process Automation Market
Industrial Automation
Port Equipment Automation Market
Industrial Automation
Latin America Factory Automation and Industrial Controls Market
Industrial Automation
Smart Elevator Market
Industrial Automation
Mini-Load Systems Market
Industrial Automation
South Korea Factory Automation and Industrial Controls Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
Smart and Connected Elevators and Elevators Control Systems Market
Industrial Automation
Human Machine Interface (HMI) Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
South Korea Automation and Industrial Control Market
Industrial Automation
Asia Pacific Sortation Systems Market