
 Sortation Systems Market | 2026-2036
Sortation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Sortation Systems Market Outlook
High-throughput specification tiers is collapsing the distinction between parcel hubs and e-commerce fulfillment centers, forcing infrastructure buyers to recalibrate capacity planning. Vanderlande leverages its baggage-handling heritage to dominate airport-to-warehouse technology transfers. Daifuku Co. Ltd anchors its position through captive manufacturing of drive units and control software. Honeywell Intelligrated competes by extending its Intelligrated software stack into predictive maintenance modules.
Sortation systems are electromechanical assemblies that receive mixed product flows, identify individual items through barcode, RFID, or machine vision, and divert each to predetermined destinations using pusher arms, cross-belt carriages, or sliding shoe mechanisms; throughput rates typically range from 2,000 to 40,000 items per hour depending on mechanism and item characteristics. Their primary purpose is to replace manual pick-and-sort labor in high-volume distribution environments where accuracy and speed determine operational economics. Automated sorters and cross-belt sorters lead the product type dimension, with the former capturing standard parcel flows and the latter commanding premium positioning in fragile-goods handling where gentle discharge prevents damage. AI-based sorting within the technology dimension represents the fastest-expanding margin pool, though barcode scanning sustains the largest installed base due to legacy compatibility and lower capital thresholds.
The EU Machinery Directive, CE marking requirements, and OSHA workplace safety standards in the United States collectively shape product design by mandating emergency stop architectures, guard interlocks, and noise emission limits that add engineering cost but also create compliance barriers for non-certified entrants. REACH substance restrictions in Europe further constrain material choices for belt compounds and electronic housings, pushing suppliers toward halogen-free formulations. Stakeholders must monitor how the EU AI Act's risk-classification framework applies to autonomous sortation decisions, as this will determine whether vision-system vendors must pursue third-party conformity assessment or self-certification pathways.
Market Dynamics
E-commerce fulfillment centers are compressing sortation infrastructure upgrade cycles from seven-year replacement schedules to three-to-four-year refresh timelines, forcing capital allocation toward modular systems that accommodate throughput scaling without facility reconstruction.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for emergency stop architectures and guard interlocks are accelerating replacement of legacy sorter installations across German, Dutch, and Belgian distribution hubs.
- Cross-belt carriage mechanism adoption:Fragile-goods handlers in pharmaceutical and electronics fulfillment are specifying gentle-discharge sorters to reduce damage rates in high-value parcel flows.
- Rhine-Ruhr logistics corridor concentration:Warehouse automation investments in Düsseldorf-Cologne-Dortmund axis are generating clustered demand for high-throughput parcel sortation infrastructure.
Market Restraints
- Steel and aluminum input volatility:Belt frame and carriage fabrication costs fluctuate with commodity pricing, compressing margin predictability for system integrators on fixed-price contracts.
- Drive unit supply concentration:Captive manufacturing of precision motors and gearboxes by Japanese and German industrial conglomerates limits second-source availability for mid-tier sorter builders.
- REACH substance restrictions:Halogen-free belt compound formulations required under ECHA guidelines increase material costs and reduce supplier pool for European installations.
Strategic Opportunities
- AI Act conformity assessment pathways:Early positioning for third-party certification of autonomous vision-based sortation decisions creates differentiation before mandatory frameworks solidify.
- Airport-to-warehouse technology transfer:Baggage-handling system architectures adapted for e-commerce parcel flows unlock new application segments with proven reliability records.
- Predictive maintenance module integration:Software stack extensions that forecast mechanical failure before throughput degradation command premium pricing in 24/7 fulfillment operations.
Industry Challenges
- Mechatronics technician scarcity:Cross-functional maintenance staffing that combines PLC programming, mechanical adjustment, and machine vision calibration remains difficult to source in regional labor markets.
- Legacy WMS integration friction:Brownfield warehouse management system interfaces require custom middleware development, extending deployment timelines and inflating project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sortation Systems Market |
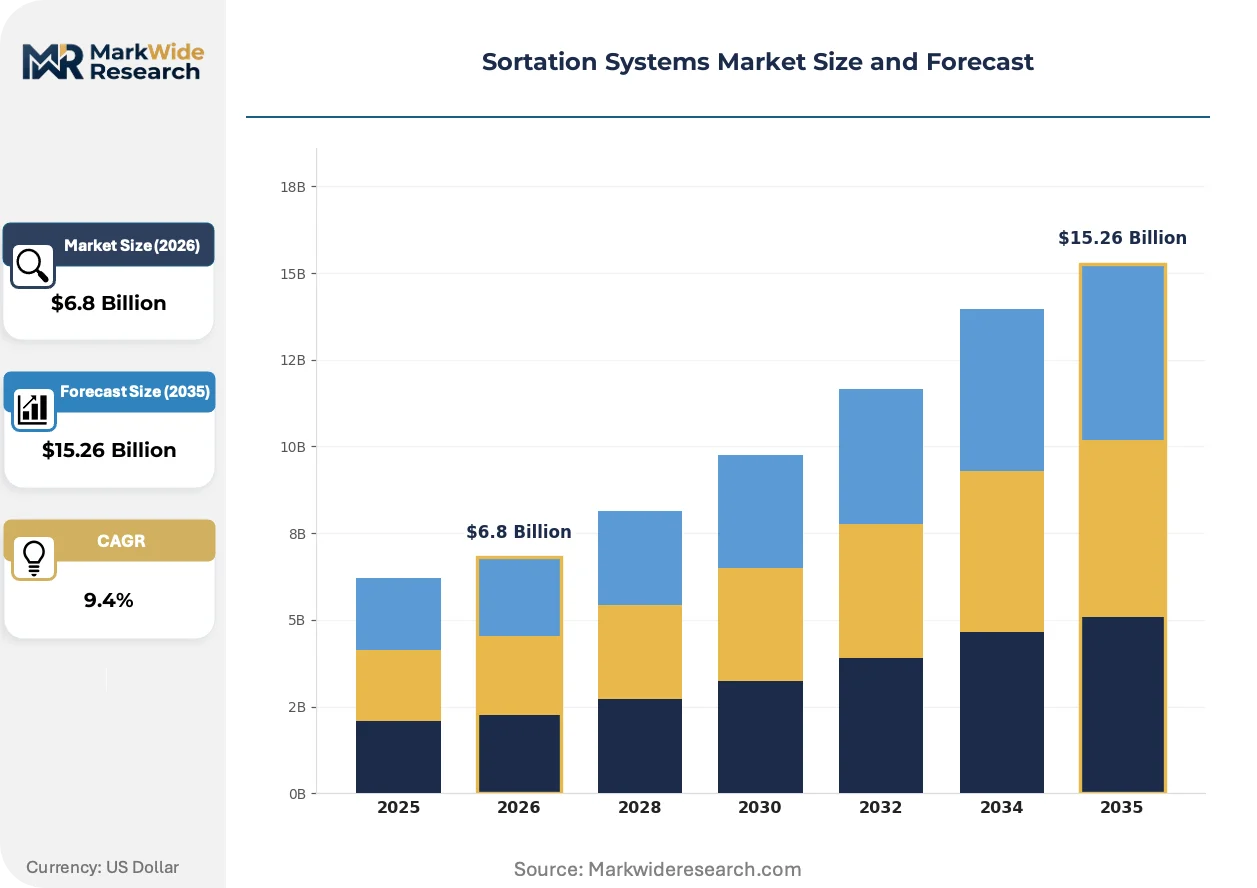
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Sorters, Conveyor Sorters, Sliding Shoe Sorters, Cross-belt Sorters End User: E-commerce, Retail, Food & Beverage, Pharmaceuticals Technology: Barcode Scanning, RFID Tracking, Optical Recognition, AI-based Sorting Application: Warehouse Management, Parcel Distribution, Inventory Control, Order Fulfillment |
| Companies Covered | Vanderlande, Honeywell Intelligrated, Daifuku Co. Ltd, Beumer Group, Dematic Corp., Bastian Solutions, Interroll Holding AG, KNAPP AG, Fives, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sortation Systems Market Strategic Shifts
Machine vision architectures are displacing fixed-position barcode scanning as the primary item-identification layer, enabling sortation of unlabeled or damaged parcels while compressing the physical footprint required for induction stations.
Convolutional neural networks paired with high-speed line-scan cameras are decomposing the traditional separation between identification and sortation subsystems. Pharmaceutical distributors in Switzerland and medical device fulfillment centers in the Netherlands are deploying these integrated vision-sorter combinations to handle variable packaging formats without manual presorting. The technology is decomposing the historical distinction between parcel hubs and e-commerce fulfillment centers by enabling identical hardware configurations to serve both standard and fragile-goods flows through software-parameterized discharge profiles.
REACH substance restrictions and RoHS compliance deadlines are constraining material choices for belt compounds and electronic housings in European installations. Suppliers are reformulating halogen-free polyurethane belt materials and migrating to lead-free solder formulations for control board assemblies. German system builders face the tightest compliance timelines, with Bavarian manufacturing clusters reporting accelerated qualification cycles for replacement materials.
Outcome-based service contracts are displacing traditional break-fix maintenance arrangements in large fulfillment operations. Retailers operating multi-site networks in France and the United Kingdom are specifying guaranteed uptime percentages with penalty clauses, transferring operational risk to sorter vendors. This procurement evolution concentrates service revenue with manufacturers possessing captive spare parts logistics and remote diagnostics capabilities.
Sortation Systems Market Segmentation
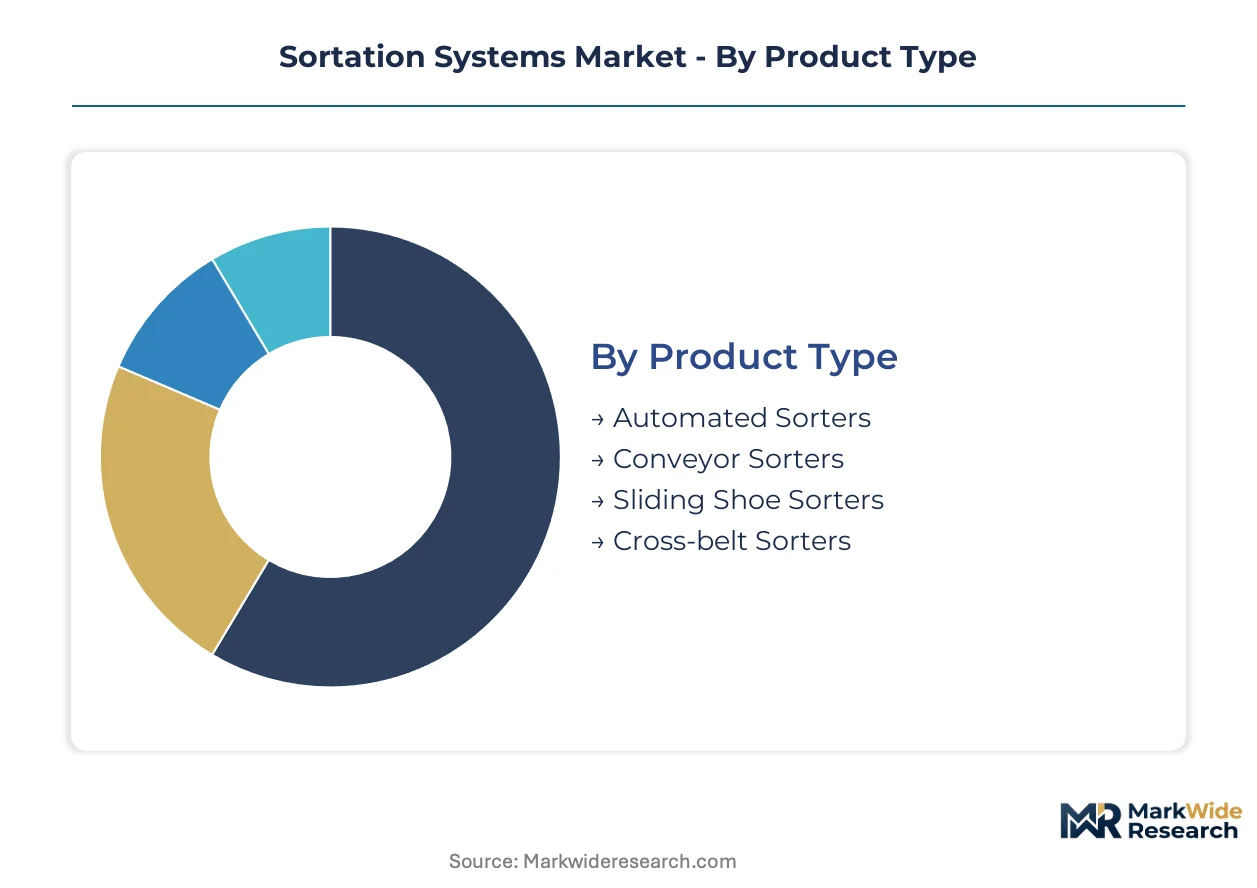
Sortation systems serve divergent operational economics across fulfillment archetypes. Equipment specification varies sharply between high-velocity parcel hubs and fragile-goods handling environments. Technology selection determines capital intensity and integration complexity.
Product Type:
Domestic demand in Germany and the Netherlands concentrates on modular configurations for brownfield retrofit. Export-led growth flows from Japanese and Korean manufacturers supplying cross-belt systems to pharmaceutical handlers in Switzerland and medical device distributors in Belgium.
- Automated Sorters:Electromechanical assemblies deploy pusher arms or pop-up wheels to divert parcels at rates up to 20,000 items per hour. E-commerce fulfillment centers in the Rhine-Ruhr corridor specify these for standard parcel flows where capital efficiency outweighs gentle handling requirements.
- Cross-belt Sorters:Individual carriages with perpendicular belt segments enable bi-directional discharge without item rotation. Pharmaceutical distributors in Basel and electronics fulfillment operators in Eindhoven command premium positioning here to prevent damage to high-value, fragile shipments.
- Conveyor Sorters:Gravity or powered roller configurations provide entry-level automation for mid-tier retail distribution.
- Sliding Shoe Sorters:Positive-discharge mechanisms using aluminum shoes sliding across a slat bed handle irregularly shaped items in mixed-carton environments.
Automated sorters command the established base. The steepest expansion runs through cross-belt sorters.
End User:
Cost tier segmentation separates capital-intensive 24/7 operations from seasonal or lower-velocity deployments. Premium procurement specifications cluster in pharmaceutical and medical device handling where compliance documentation and audit trails justify higher equipment spend.
- E-commerce:Multi-shift fulfillment centers processing 50,000+ daily orders drive modular system architecture with throughput scaling capabilities. Warehouse automation investments across Bavaria and Baden-Württemberg prioritize rapid deployment timelines over customization depth.
- Pharmaceuticals:Temperature-controlled environments and serialization compliance requirements demand stainless steel construction, washdown capability, and integration with track-and-trace databases. Swissmedic-regulated facilities in Geneva and Basel specify validation documentation packages that extend procurement cycles.
- Retail:Department store and fashion distribution networks balance seasonal volume spikes against year-round baseline capacity.
- Food & Beverage:Hygienic design priorities and allergen segregation protocols constrain mechanism selection in European chilled distribution.
E-commerce captures the volume concentration. Pharmaceuticals generate the highest margin per installed base unit.
Technology:
Application context determines identification layer selection. High-speed parcel hubs prioritize read-rate reliability over handling flexibility. Variable-format fulfillment centers sacrifice maximum velocity for adaptability to unlabeled or damaged items.
- AI-based Sorting:Convolutional neural networks processing line-scan camera inputs enable sortation without barcode dependency. Medical device fulfillment centers in the Netherlands deploy these systems to handle supplier-agnostic packaging formats without manual presorting intervention.
- Barcode Scanning:Fixed-position laser or camera arrays deliver 99.9%+ read rates on labeled parcels at lowest capital threshold. Legacy warehouse management system integration in German retail distribution sustains this technology's installed base dominance.
- RFID Tracking:UHF tag interrogation enables bulk reading and item-level traceability in closed-loop apparel and pharmaceutical logistics.
- Optical Recognition:Character recognition and dimensioning systems supplement primary identification methods in mixed-flow environments.
Barcode scanning anchors current deployment volumes. AI-based sorting climbs the fastest as vision system costs decline and EU AI Act conformity pathways clarify.
Application:
Customer type segmentation separates asset owners from third-party logistics operators with divergent payback period requirements. Parcel carriers prioritize throughput density per square meter. Retailers emphasize order accuracy metrics and returns processing flexibility.
- Parcel Distribution:Hub-and-spoke networks in Cologne, Leipzig, and Frankfurt operate tilt-tray and cross-belt systems at 30,000+ items per hour. Deutsche Post DHL and regional carriers specify mean-time-between-failure metrics above 10,000 hours for 24/7 operations.
- Order Fulfillment:E-commerce picking operations integrate sorters with automated storage and retrieval systems for same-day delivery commitments. Belgian and Dutch fulfillment clusters serving Benelux consumer markets lead European deployment density here.
- Warehouse Management:General material handling applications in manufacturing and wholesale distribution.
- Inventory Control:Cycle counting and put-away optimization in high-SKU environments.
Parcel distribution holds the largest equipment base. Order fulfillment gains share fastest as delivery speed commitments compress warehouse automation upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sortation system supply concentrates among German and Japanese industrial conglomerates with captive drive manufacturing, while demand clusters in logistics corridors where e-commerce fulfillment density justifies automation capital deployment.
Germany
Deutsche Post DHL and regional parcel carriers are compressing sortation refresh cycles to three-to-four years across Rhine-Ruhr distribution hubs. CE marking requirements under the EU Machinery Directive are accelerating replacement of legacy installations lacking emergency stop architectures and guard interlocks. Bavarian manufacturing clusters around Munich and Nuremberg are reporting accelerated qualification cycles for halogen-free belt materials to meet REACH substance restrictions.
United States
OSHA workplace safety standards are mandating noise emission limits and guard interlocks that add engineering cost but create compliance barriers for non-certified equipment entrants. E-commerce fulfillment operators in the Midwest and Southeast are specifying modular systems for throughput scaling without facility reconstruction. Retail distribution networks in Texas and Georgia are driving demand for predictive maintenance modules with guaranteed uptime percentages.
Japan
METI industrial automation incentives are supporting technology transfers from baggage-handling heritage into e-commerce parcel applications. Captive manufacturing of precision motors and gearboxes by industrial conglomerates limits second-source availability for mid-tier sorter builders. The Kansai and Chubu industrial corridors host concentrated system integration expertise for pharmaceutical and electronics fulfillment exports.
Netherlands
Belgian and Dutch fulfillment clusters serving Benelux consumer markets lead European deployment density for order-fulfillment-integrated sorters. ECHA REACH compliance deadlines are constraining material choices for belt compounds and electronic housings. The Eindhoven-Rotterdam logistics axis is generating clustered demand for high-throughput parcel sortation infrastructure with rapid deployment timelines.
Switzerland
Swissmedic-regulated pharmaceutical facilities in Geneva and Basel specify validation documentation packages that extend procurement cycles for stainless steel, washdown-capable sorters. Temperature-controlled environments and serialization compliance requirements demand integration with track-and-trace databases. Medical device fulfillment centers are deploying AI-based vision systems to handle supplier-agnostic packaging formats.
Sortation Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with baggage-handling heritage companies dominating high-reliability segments while modular specialists capture brownfield retrofit demand. The vendor base separates into three strategic tiers: integrated conglomerates with captive component manufacturing, mid-tier system integrators dependent on third-party drive units, and software-focused challengers extending predictive maintenance capabilities. Consolidation pressure is accelerating as outcome-based service contracts transfer operational risk to manufacturers with spare parts logistics and remote diagnostics capabilities. Geographic expansion and technology licensing represent the dominant competitive moves for accessing pharmaceutical and food-grade handling segments.
Within the integrated conglomerate tier, Vanderlande and Daifuku Co. Ltd exemplify archetypes combining captive drive manufacturing with control software development. Honeywell Intelligrated occupies a position representing software-stack extension strategies into predictive maintenance modules. These three companies anchor the competitive structure by demonstrating how heritage in adjacent automation domains translates into sortation market positioning.
| Leading Market Players |
|---|
| Vanderlande |
| Honeywell Intelligrated |
| Daifuku Co. Ltd |
| Beumer Group |
| Dematic Corp. |
| Bastian Solutions |
| Interroll Holding AG |
| KNAPP AG |
| Fives |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Japanese and German drive-unit manufacturers lock in supply access and price visibility for system integrators facing volatile steel and aluminum input markets. These arrangements transfer commodity risk upstream while securing allocation priority during supply crunches, particularly for CE-marked installations serving Rhine-Ruhr logistics corridors.
Pricing Analysis
CE marking requirements under the EU Machinery Directive dictate the pricing tier structure across European installations, separating validated emergency-stop architectures from non-compliant legacy systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling, with pharmaceutical handlers in Basel and Geneva showing lowest price sensitivity due to Swissmedic validation requirements. Cost compression in mid-tier automated sorters is intensifying because captive drive manufacturing by Japanese conglomerates limits second-source competition. E-commerce fulfillment operators in the Benelux region exhibit highest price sensitivity, prioritizing modular throughput scaling over premium gentle-handling specifications.
Supply Chain Analysis
Precision motor and gearbox fabrication concentrates in Japan and Germany as the critical chokepoint constraining mid-tier sorter builder expansion. Belt frame assemblies draw from German and Italian steel fabrication clusters, while halogen-free polyurethane belt compounds source from specialized European chemical processors under REACH compliance timelines. Single-source vulnerability runs through captive manufacturing of control software and drive units by integrated conglomerates. Distribution runs through direct OEM relationships for large fulfillment deployments and regional system integrators for brownfield retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sortation systems market represents a high-growth disruption as EU AI Act conformity pathways for autonomous vision-based decisions reshape competitive differentiation before mandatory frameworks solidify.
For Market Incumbents: Consolidate spare parts logistics networks and remote diagnostics capabilities to capture outcome-based service contracts transferring operational risk from multi-site retailers. Deepen backward integration into precision motor manufacturing to reduce exposure to Japanese supply concentration. Pursue third-party certification for AI-based sorting decisions ahead of EU AI Act enforcement timelines. For New Entrants and Emerging Players: Lead with AI-based vision systems targeting pharmaceutical and medical device fulfillment centers in Switzerland and the Netherlands, where supplier-agnostic packaging handling commands premium positioning. Exploit white-space in brownfield warehouse management system middleware development, where legacy integration friction extends deployment timelines for established vendors. Position around rapid deployment capabilities for Bavarian e-commerce clusters prioritizing speed over customization depth. For Investors and Strategic Acquirers: Capital is best deployed toward software-focused challengers with predictive maintenance module capabilities and established pharmaceutical validation documentation packages. Long-term viability centers on vendors combining captive component manufacturing with outcome-based service revenue streams. Monitor EU AI Act risk-classification finalization as the signal indicating whether vision-system vendors must pursue third-party conformity assessment or self-certification pathways.| Strategic Initiative | Industry Significance |
|---|---|
| AI Act Conformity Certification | Third-party assessment of autonomous vision-based sortation decisions creates compliance differentiation before mandatory frameworks solidify. |
| Backward Integration into Drive Manufacturing | In-house production of precision motors and gearboxes reduces supply concentration risk from Japanese and German conglomerates. |
| Predictive Maintenance Module Development | Software stack extensions forecasting mechanical failure command premium pricing in 24/7 Rhine-Ruhr fulfillment operations. |
| Airport-to-Warehouse Technology Transfer | Baggage-handling system architectures adapted for e-commerce parcel flows unlock proven reliability records in new segments. |
| Halogen-Free Material Qualification | Accelerated validation cycles for REACH-compliant belt compounds secure European installation access against restricted supplier pools. |
Study Parameters
Desk research of regulatory filings, customs trade databases, and industry association technical specifications preceded structured interviews with warehouse automation directors, mechatronics procurement leads, system integration engineers, and aftermarket service heads. Primary fieldwork across German, Dutch, and Belgian logistics corridors validated secondary estimates of refresh cycle compression and modular system adoption. Bottom-up equipment shipment analysis triangulated against top-down e-commerce fulfillment capital expenditure disclosures.
Variance decomposition across product type, end-use sector, technology layer, and application context anchored the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market scaling. Modeled inputs included E-commerce order volume trajectories, EU Machinery Directive compliance deadlines, and REACH substance restriction implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce fulfillment investment levels or accelerated EU AI Act enforcement would require recalibration. Forecasts reflect documented assumptions regarding steel and aluminum input stability and mechatronics technician labor availability. Practitioners should keep alternative scenarios live as EU AI Act risk-classification frameworks and REACH compliance deadlines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Material Handling Robotics Market
Industrial Automation
Europe Process Automation Market
Industrial Automation
Smart Elevator Automation System Market
Industrial Automation
Pick and Place Machines Market
Industrial Automation
United Kingdom Factory Automation and Industrial Control Systems Market
Industrial Automation
Model Based Manufacturing Technologies Market
Industrial Automation
Global Warehouse Automation Market
Industrial Automation
North America Automated Storage and Retrieval System Market
Industrial Automation
North America Automated Rotary Indexing Table Market
Industrial Automation
Asia Pacific Process Automation Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Middle East and Africa Process Automation Market
Industrial Automation
Global Assembly Line Solutions Market
Industrial Automation
Europe Retail Automation Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Cold Storage AGV Market