
 Industrial Robotics Market | 2026-2036
Industrial Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Robotics Market Intelligence
Japanese servo motor and reducer producers is realigning global supply chains toward regional assembly hubs. Fanuc Corporation leverages its captive CNC and servo technology stack to dominate high-precision automotive lines. ABB Ltd anchors European demand through its integrated RobotStudio software and hardware bundles. KUKA AG competes aggressively in Chinese automotive joint ventures through localized production.
Industrial robotics comprises programmable multi-axis manipulators with payload capacities from sub-kilogram precision units to over one-ton heavy-lift systems, typically employing harmonic drives, RV reducers, and servo motors to achieve repeatability within 0.02 millimeters for welding, assembly, and material transport operations. Articulated robots occupy the largest installed base across automotive body shops where six-axis flexibility commands premium positioning. Collaborative robots represent the fastest-expanding technology segment as force-limited designs with ISO/TS 15066 certification enable fenceless human-robot workstations. Material handling applications generate the most consistent replacement demand across electronics and consumer goods end users.
The EU Machinery Directive and ISO 10218-1/2 safety standards mandate risk assessments and protective measures for all industrial robot installations, directly shaping product design and integration service margins. China's MIIT publishes GB national standards for industrial robot performance testing that govern domestic procurement and export certification pathways. Stakeholders must monitor how evolving AI-enabled motion planning regulations in multiple jurisdictions reshape software validation requirements and liability frameworks for autonomous robot operations.
Market Dynamics
The transition from caged industrial robots to fenceless collaborative workstations is compressing integration timelines and reshaping facility layouts across automotive and electronics manufacturing. Force-limited cobot designs certified to ISO/TS 15066 are displacing traditional safety enclosures, altering capital allocation toward software-driven motion planning rather than physical guarding infrastructure.
Growth Catalysts
- EU Machinery Directive amendments:Tightened risk assessment requirements for human-robot collaboration are accelerating replacement cycles of legacy guarded installations across German and Italian automotive plants.
- Electric vehicle battery assembly:Precision welding and stacking operations for lithium-ion cell modules are pulling six-axis articulated systems into new gigafactory constructions in Hungary and the United States.
- China's Yangtze River Delta:Concentrated electronics contract manufacturing is generating sustained replacement demand for SCARA robots in semiconductor packaging and smartphone final assembly.
Market Restraints
- Harmonic drive supply concentration:Japanese precision gear producers control critical reducer supply, exposing European and North American integrators to extended lead times and input cost volatility.
- RV reducer technical limitations:Backlash and wear characteristics in heavy-payload applications above 500 kilograms restrict articulation accuracy for aerospace component handling.
- ISO 10218-1/2 compliance friction:Mandatory protective measure documentation and third-party validation extend project commissioning timelines by four to eight weeks in regulated European jurisdictions.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for automotive and electronics sectors are creating first-mover advantage for robot integrators establishing local service capabilities.
- AI-enabled predictive maintenance:Convergence of edge computing and vibration sensing is opening subscription-based service revenue streams independent of hardware replacement cycles.
- Food and beverage handling:IP69K-rated collaborative units for washdown environments represent underpenetrated application white space beyond traditional industrial end-uses.
Industry Challenges
- Mechatronics technician scarcity:Shortage of professionals skilled in servo tuning and kinematic calibration is extending commissioning timelines and inflating integration labor rates.
- Legacy PLC integration complexity:Retrofitting decades-old programmable logic controller architectures with modern Ethernet-based robot controllers demands custom gateway development and extended debugging phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Robotics Market |
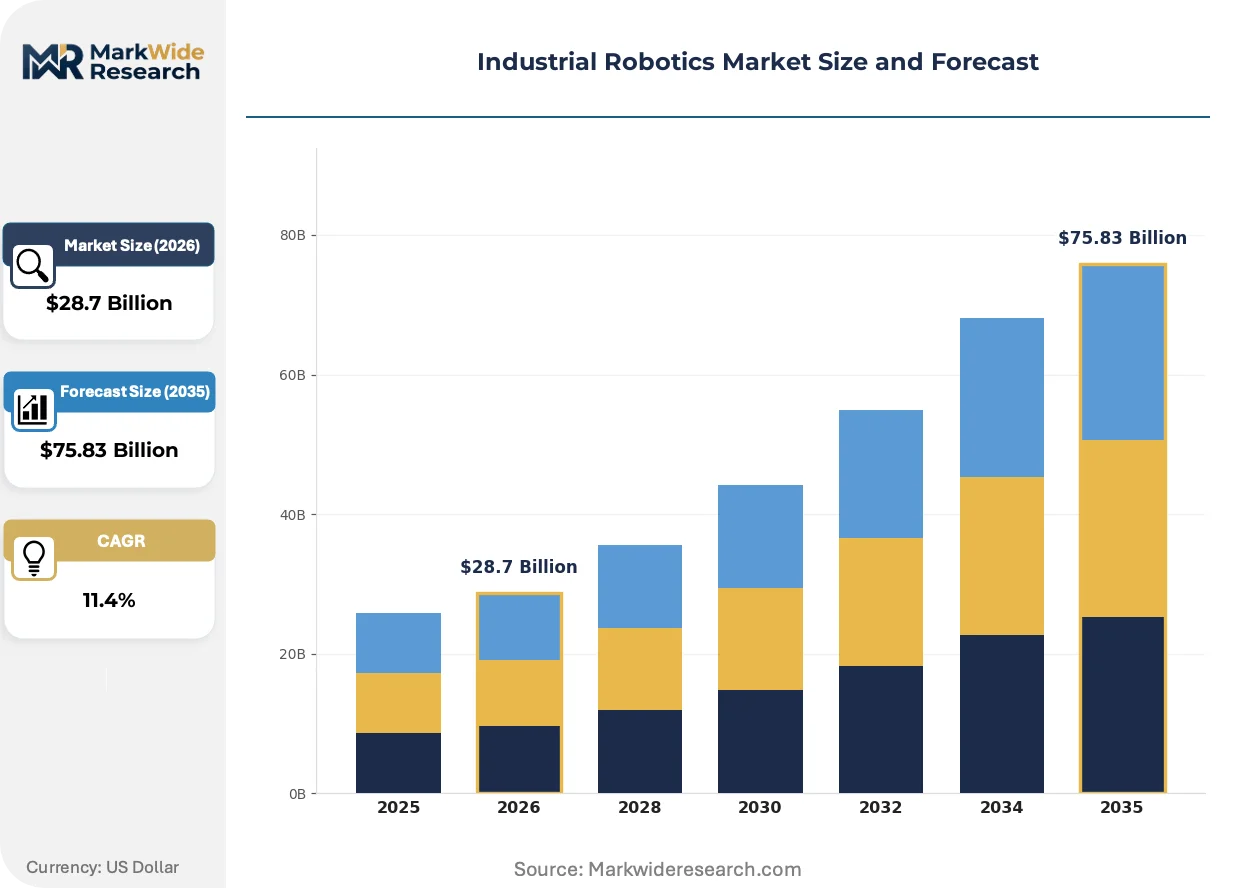
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $75.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Articulated Robots, SCARA Robots, Collaborative Robots, Cartesian Robots Application: Welding, Painting, Assembly, Material Handling End User: Automotive, Electronics, Consumer Goods, Aerospace Solution: Hardware, Software, Integrated Systems, Maintenance |
| Companies Covered | ABB Ltd, Fanuc Corporation, Yaskawa Electric Corporation, KUKA AG, Epson, Kawasaki Heavy Industries, Denso Corporation, Mitsubishi Electric Corporation, Nachi-Fujikoshi Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Robotics Market Strategic Shifts & Innovations
Software-defined motion control and sensor fusion are displacing fixed automation sequences, enabling robots to adapt to variable part geometries without mechanical retooling. This shift elevates programming environment capabilities above hardware specifications in procurement evaluations.
Digital twin simulation platforms are expanding into offline programming workflows, allowing automotive manufacturers to validate welding paths and cycle times before physical installation. BMW and Hyundai Motor Group facilities in Germany and South Korea are deploying these virtual commissioning tools to compress ramp-up phases. The technology is expanding into small-batch electronics producers previously priced out of simulation software licenses.
The EU AI Act's risk classification framework for autonomous robotic systems is mandating conformity assessments for AI-enabled motion planning algorithms. Industrial robot OEMs must now document training data provenance and algorithmic transparency for high-risk installations in collaborative environments. German automotive suppliers are responding by segregating AI-driven adaptive control features into separately certifiable software modules.
Buying committees are consolidating vendor relationships around integrated hardware-software bundles rather than sourcing manipulators and controllers from separate suppliers. Electronics manufacturers in China's Pearl River Delta are favoring single-source procurement for robot, vision system, and programming environment to reduce interface debugging burden. This pattern is most visible in contract manufacturers serving Apple and Samsung supply chains where line changeover frequency demands rapid technical support response.
Industrial Robotics Market Segmentation
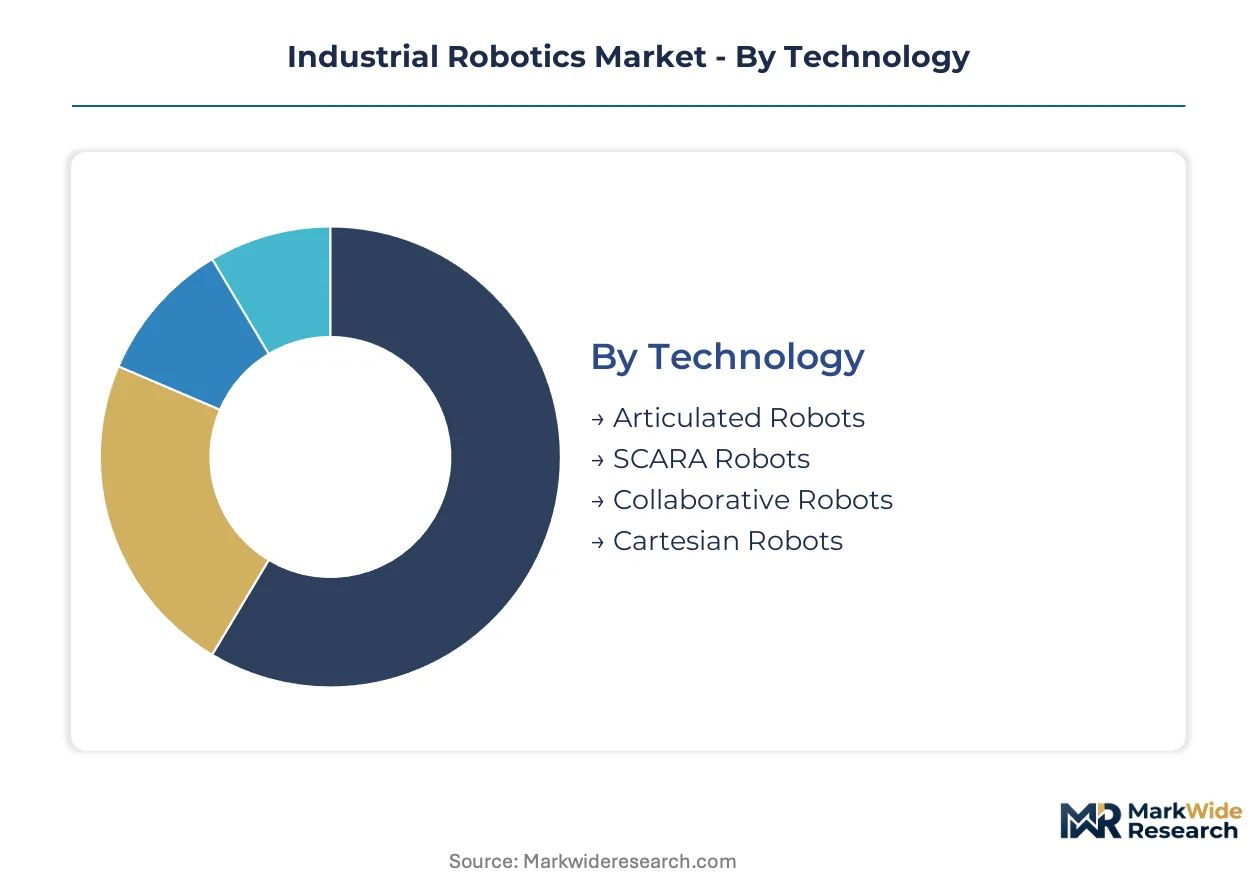
Technology choices in industrial robotics determine capital recovery timelines and facility reconfiguration costs. Procurement committees evaluate upgrade pathways against existing automation footprints when selecting between articulated, collaborative, and fixed-axis systems.
Technology:
Replacement cycles accelerate where force-limited designs displace legacy caged installations, compressing payback periods through reduced guarding infrastructure.
- Articulated Robots:Six-axis manipulators employing harmonic drives and RV reducers achieve sub-0.02mm repeatability for automotive body-in-white welding. German and Japanese OEMs dominate installed base in high-volume paint shops where multi-joint flexibility commands positioning premiums.
- Collaborative Robots:Force-torque sensing and power-limited actuation enable fenceless human-robot workstations certified to ISO/TS 15066. Electronics manufacturers in China's Yangtze River Delta deploy these for smartphone final assembly where line changeover frequency demands rapid redeployment.
- SCARA Robots:Selective Compliance Assembly Robot Arm designs optimize planar precision with vertical rigidity for semiconductor packaging.
- Cartesian Robots:Gantry configurations deliver linear motion for pick-and-place and dispensing across consumer goods production.
Volume placements concentrate in Articulated Robots; the faster expansion belongs to Collaborative Robots.
Application:
Process automation intensity varies by task physics—thermal processes demand higher precision than transport operations, affecting controller specification and integration labor.
- Welding:Arc and spot welding operations require seam tracking and adaptive current control for battery module assembly in electric vehicle gigafactories. Hungarian and United States facilities are pulling six-axis systems into new constructions for lithium-ion cell stacking precision.
- Material Handling:Palletizing, machine tending, and bin picking generate consistent replacement demand across contract electronics manufacturing. SCARA and Cartesian configurations dominate where payload-to-precision ratios favor fixed-axis economics over articulated flexibility.
- Painting:Explosion-proof manipulators with ATEX certification apply coatings in automotive finish shops.
- Assembly:Precision fastening and component insertion operations populate consumer goods lines.
Revenue concentration sits with Welding; Material Handling claims the steepest replacement velocity.
End User:
Capital allocation discipline differs sharply between cyclical automotive investment and electronics contract manufacturing's sustained refresh rates.
- Automotive:Body shop and powertrain automation commands the largest project values, with German manufacturers expanding robot deployment for electric vehicle battery assembly lines. Tier-1 suppliers face EU Machinery Directive compliance pressure accelerating legacy system replacement.
- Electronics:Semiconductor packaging and smartphone assembly sustain SCARA and collaborative robot demand in China's Yangtze River Delta manufacturing corridor. Contract manufacturers serving Apple and Samsung supply chains favor integrated hardware-software bundles to reduce debugging burden.
- Consumer Goods:High-volume packaging and palletizing operations populate food and beverage handling.
- Aerospace:Heavy-payload applications above 500 kilograms encounter RV reducer backlash limitations restricting articulation accuracy for component handling.
Automotive anchors capital deployment; Electronics demonstrates the most resilient recurring demand.
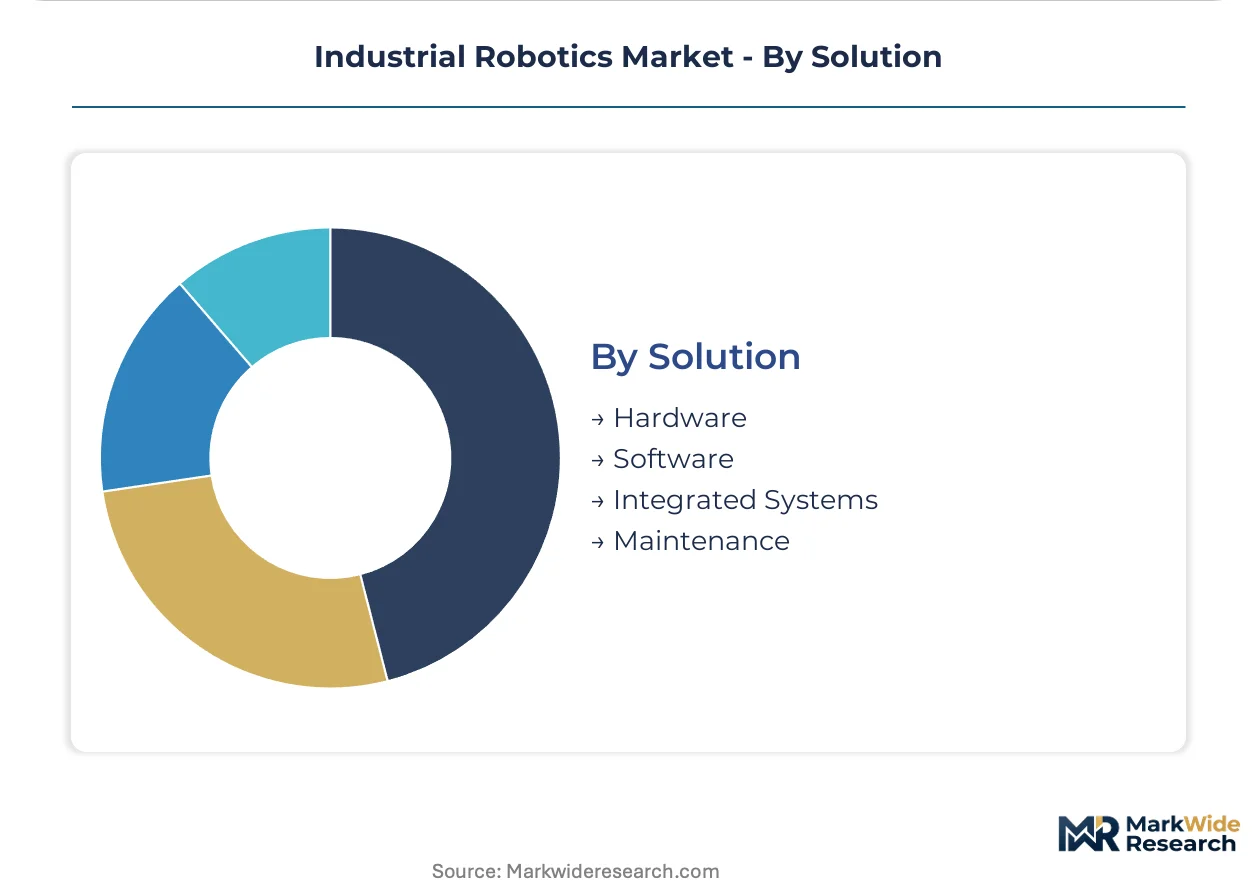
Solution:
Margin capture is shifting from hardware shipment toward software licensing and predictive service contracts, altering vendor business models.
- Hardware:Manipulator, controller, and end-effector shipments face margin pressure as buyers consolidate around integrated bundles. Japanese servo motor and reducer producers control critical supply, exposing European integrators to lead time volatility.
- Software:Offline programming, digital twin simulation, and AI-enabled motion planning command expanding procurement evaluation weight. BMW and Hyundai Motor Group facilities deploy virtual commissioning tools to compress ramp-up phases.
- Integrated Systems:Single-source procurement of robot, vision, and programming environment reduces interface debugging for Pearl River Delta contract manufacturers.
- Maintenance:Vibration sensing and edge computing convergence opens subscription-based service revenue independent of replacement cycles.
Hardware retains volume dominance; Software and Maintenance together claim the fastest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese harmonic drive and RV reducer manufacturing clusters supply precision gearing that anchors robot articulation accuracy standards worldwide. Germany and China concentrate final assembly capacity for automotive and electronics applications. Regulatory frameworks in multiple jurisdictions reshape certification pathways and deployment timelines.
China
MIIT's GB national standards for industrial robot performance testing govern domestic procurement and export certification pathways. The Yangtze River Delta manufacturing corridor generates sustained replacement demand for SCARA robots in semiconductor packaging and smartphone final assembly. Shanghai and Suzhou host concentrated electronics contract manufacturing serving Apple and Samsung supply chains.
Germany
Automotive OEMs expand robot deployment for electric vehicle battery assembly lines across Bavarian and Baden-Württemberg facilities. EU Machinery Directive amendments tighten risk assessment requirements for human-robot collaboration, accelerating replacement cycles of legacy guarded installations. Stuttgart anchors high-volume paint shop automation where multi-joint flexibility commands positioning premiums.
Japan
Servo motor and reducer producers realign global supply chains toward regional assembly hubs to mitigate lead time volatility. METI oversees JIS standards coordination with ISO frameworks for collaborative robot safety certification. Nagoya and Osaka prefectures concentrate precision gear manufacturing that supplies European and North American integrators.
United States
Electric vehicle battery assembly operations pull six-axis articulated systems into new gigafactory constructions across the Midwest and Southeast. OSHA workplace safety regulations intersect with ISO 10218-1/2 compliance requirements for collaborative installations. Michigan and Tennessee automotive corridors drive welding and material handling robot procurement.
South Korea
Hyundai Motor Group facilities deploy digital twin simulation platforms to compress ramp-up phases for welding path validation. MFDS-equivalent industrial safety frameworks align with ISO/TS 15066 for fenceless human-robot workstations. The Seoul Capital Area and Busan-Ulsan corridor concentrate electronics and automotive automation demand.
Industrial Robotics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue collaborative and AI-enabled motion planning segments. The vendor base organizes around three tiers: integrated hardware-software bundlers, precision component specialists, and regional system integrators. Dominant competitive moves include strategic partnerships for digital twin platform access and geographic expansion through localized production joint ventures.
Among Japan-based precision automation producers, Fanuc Corporation and Yaskawa Electric Corporation exemplify the integrated technology stack archetype. ABB Ltd anchors European demand through bundled RobotStudio software and hardware offerings. KUKA AG occupies a position within the German automotive supplier ecosystem, competing through China-focused localized production strategies.
| Leading Market Players |
|---|
| ABB Ltd |
| Fanuc Corporation |
| Yaskawa Electric Corporation |
| KUKA AG |
| Epson |
| Kawasaki Heavy Industries |
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Nachi-Fujikoshi Corp |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between ISO 10218-compliant guarded systems and fenceless ISO/TS 15066 collaborative units splits pricing power along safety architecture lines, with premium bundling of predictive maintenance software commanding three-year service contracts while commodity articulated hardware faces margin compression from Chinese integrators.
Pricing Analysis
Warranty and service-bundling unbundling separates premium Japanese OEM offerings from emerging Chinese suppliers, with Fanuc and Yaskawa embedding five-year predictive maintenance subscriptions while domestic Chinese brands compete on bare-hardware transactional pricing. Price differentiation hinges on ISO/TS 15066 certification tier and servo-reducer integration depth. Pricing pressure intensifies in SCARA segments where Yangtze River Delta contract manufacturers drive cost compression through volume aggregation. Electronics contract manufacturers exhibit highest price sensitivity; automotive OEMs prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Mechatronics technician scarcity in Nagoya, Stuttgart, and Shanghai precision manufacturing clusters constrains final assembly throughput regardless of component availability. Supply chains draw from Japanese harmonic drive producers, German servo controller specialists, and Chinese aluminum casting foundries. Raw material dependencies span rare-earth magnets for servo motors, high-grade steel for RV reducers, and copper windings for actuators. Single-source vulnerability concentrates in Japanese precision gearing. Distribution runs through authorized integrator networks with direct OEM relationships for automotive tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as EU Machinery Directive compliance costs and AI-enabled motion planning R&D requirements force sub-scale integrators toward acquisition or exit. Marginal players lacking captive servo technology or software-defined control stacks face structural disadvantage.
For Market Incumbents: Deploy predictive maintenance subscription bundling to capture recurring revenue independent of hardware replacement cycles. Integrate digital twin simulation capabilities through partnership or acquisition to defend against software-first entrants. Accelerate backward integration into servo motor production to reduce exposure to Japanese supply concentration. For New Entrants and Emerging Players: Enter via IP69K-rated collaborative units for food and beverage washdown environments, the most underpenetrated application white space beyond traditional industrial end-uses. Target India's PLI scheme beneficiaries with localized service capabilities before established players anchor relationships. Lead with AI-enabled motion planning as the primary go-to-market differentiator against legacy PLC-dependent incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier integrators possessing ISO 10218 certification expertise and established automotive relationships given accelerating replacement cycle demand from EU regulatory amendments. Long-term viability favors vendors with software-defined control architectures over hardware-centric legacy positions. Monitor AI Act conformity assessment documentation requirements as the inflection signal for competitive sorting between compliant and non-compliant software modules.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | Captive supply of precision actuators insulates margins from Japanese lead time volatility. |
| Digital Twin Platform Partnership | Virtual commissioning tools compress automotive ramp-up phases for BMW and Hyundai suppliers. |
| ISO/TS 15066 Certification Investment | Fenceless collaborative deployment opens electronics manufacturing demand in Yangtze River Delta. |
| AI-Enabled Motion Planning Module Development | Separately certifiable software architectures satisfy EU AI Act risk classification requirements. |
| India Localized Production Joint Venture | PLI scheme automotive and electronics incentives reward first-mover integrator establishment. |
Research Approach
Trade association filings, customs import records, and OEM procurement disclosures formed the secondary backbone, supplemented by primary interviews with plant engineers, aftermarket service heads, OEM procurement teams, and robotics integration specialists. Bottom-up unit shipment estimates triangulated against top-down capital expenditure analysis across automotive and electronics manufacturing verticals.
Bottom-up modeling aggregated segment-level volume and value trajectories across the projection horizon, with technology, application, end user, and solution dimensions informing granularity. CAGRs derived from regression analysis against industrial automation capex cycles and electric vehicle battery assembly facility announcements. Forecast inputs incorporated MIIT GB standard adoption timelines and EU Machinery Directive amendment implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff escalation scenarios affecting Japanese precision component flows. Automotive demand volatility and AI regulatory fragmentation present material revision triggers. Significant deviation in electric vehicle gigafactory construction pace or collaborative robot safety certification harmonization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robot Controller, Integrator and Software Market
Robotics and Automation
Global Programmable Robots Market
Robotics and Automation
Global Machine Vision and Vision Guided Robotics Market
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
Europe Data Center Robotics Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
Human-Robot Collaborative Picking Optimization Platforms Market
Robotics and Automation
Virtual 3D Nanorobots Market
Robotics and Automation
Robotics-Ready Fulfillment Center Design and Integration Services Market
Robotics and Automation
Latin America Autonomous Mobile Robot Market
Robotics and Automation
Asia-Pacific Medical Robots Market
Robotics and Automation
Asia-Pacific Cloud Robotics Market
Robotics and Automation
Global All Terrain Robots Market
Robotics and Automation
Assistive Robotics Market